
 Global Closed Molding Composites Market | 2026-2036
Global Closed Molding Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Global Closed Molding Composites Market Intelligence
The capital-intensity divergence between large-scale resin compounders and specialized molders is bifurcating competitive dynamics in closed molding composites. BASF leverages its backward integration into epoxy and polyurethane chemistry to control raw material costs across European automotive programs. Toray Industries anchors its position through captive carbon fiber supply that feeds directly into aerospace-grade compression molding lines. Gurit Holding specializes in marine and wind energy preform kits, competing on tailored fiber architectures rather than commodity resin volumes.
Closed molding composites enclose fiber reinforcements within matched molds where resin infusion occurs under controlled vacuum or pressure, typically achieving fiber volume fractions of 50-60% with void content below 1% for primary structural duty. Compression molding dominates automotive serial production where cycle times under five minutes justify steel tool investments, while vacuum assisted resin transfer molding leads aerospace and marine applications demanding complex geometries with minimal scrap. Epoxy resins command premium positioning in structural components for aircraft primary frames, whereas polyester retains volume leadership in construction and marine aesthetic panels where cost sensitivity overrides thermal performance requirements.
REACH in Europe and EPA regulations in the United States restrict styrene emissions from open molding alternatives, directly accelerating closed process conversion in marine and construction sectors. China's MEE enforces volatile organic compound limits that push coastal manufacturers toward resin transfer molding systems with sealed injection circuits. Stakeholders must monitor evolving carbon border adjustment mechanisms and bio-based resin certification pathways that will reshape material qualification protocols and supplier eligibility across major procurement programs.
Market Dynamics
Automotive OEMs in Germany and Japan are consolidating vacuum assisted resin transfer molding specifications for primary structural components, compressing supplier qualification timelines and forcing molders to choose between steel tool investments at scale or specialized preform kit partnerships.
Growth Catalysts
- EU Green Deal emissions mandates:REACH compliance requirements for styrene reduction are accelerating closed process conversion in European marine and construction sectors where open molding previously dominated.
- Wind turbine blade clusters:Production concentration in China's Jiangsu province around Shanghai is driving resin transfer molding system deployments with sealed injection circuits meeting MEE volatile organic compound limits.
- Compression molding cycle time gains:Sub-five-minute automotive serial production cycles are justifying steel tool investments and displacing thermoplastic alternatives in German OEM structural programs.
Market Restraints
- Carbon fiber supply concentration:Aerospace-grade fiber availability remains captive to Japanese and US producers, constraining European molders' cost positions and qualification access.
- Steel tooling capex intensity:Matched mold fabrication for compression molding requires capital commitments that exclude mid-volume entrants from automotive serial contracts.
- Epoxy resin price volatility:Petrochemical feedstock exposure in bisphenol-A and amine hardener supply chains compresses margin predictability for structural component specialists.
Strategic Opportunities
- India automotive lightweighting:PLI scheme incentives for electric vehicle manufacturing are creating first-mover openings for vacuum infusion specialists in Tamil Nadu and Maharashtra component clusters.
- Bio-based resin certification:EU Green Deal carbon border adjustment mechanisms are reshaping material qualification protocols and creating supplier eligibility advantages for certified bio-epoxy compounders.
- Marine preform kit integration:Tailored fiber architecture partnerships between European molders and Scandinavian yacht builders are displacing in-house lamination shops with outsourced closed molding modules.
Industry Challenges
- Process technician scarcity:Vacuum infusion expertise and mold flow simulation competency gaps are extending commissioning timelines for new resin transfer molding installations in expanding Chinese coastal facilities.
- Multi-material certification complexity:Aerospace OEM qualification protocols for hybrid carbon-glass preforms are creating eighteen-to-twenty-four-month approval cycles that freeze supplier switching.
- Legacy open molding asset stranding:Marine and construction fabricators with existing spray-up infrastructure face write-down pressure as EPA and MEE enforcement tightens emissions compliance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Closed Molding Composites Market |
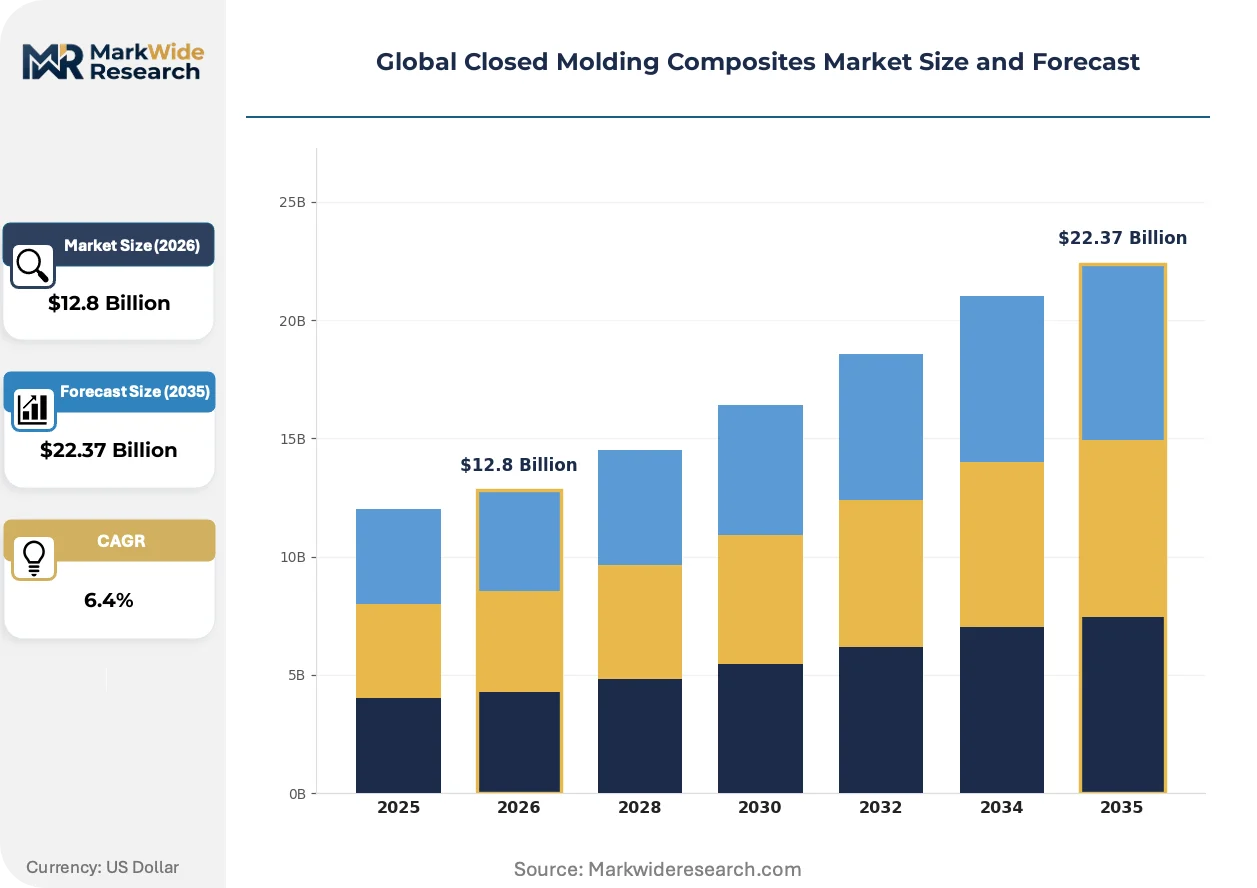
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resin Transfer Molding, Vacuum Assisted Resin Transfer Molding, Compression Molding, Others Material: Polyester, Epoxy, Vinyl Ester, Phenolic End User: Aerospace, Automotive, Marine, Construction Application: Structural Components, Aesthetic Components, Electrical Insulation, Sporting Goods |
| Companies Covered | Mitsubishi Chemical Group, BASF, Toray Industries, Owens Corning, Teijin Limited, Hexcel Corporation, Gurit Holding, Huntsman Corporation, SGL Carbon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Closed Molding Composites Market Strategic Shifts & Innovations
Process automation and digital twin integration are compressing development cycles for complex geometries while regulatory emissions frameworks are redrawing competitive boundaries between open and closed molding alternatives.
Out-of-autoclave prepreg systems are bifurcating aerospace component sourcing between traditional autoclave-dependent suppliers and emerging vacuum-only qualified molders. Tier-2 aerostructures contractors in Italy and Spain are adopting these systems to bypass autoclave capacity constraints at prime OEMs. The technology is bifurcating supply base eligibility and compressing qualification timelines from thirty-six to eighteen months for secondary structural applications.
REACH authorization requirements for diisocyanates in polyurethane chemistry are forcing reformulation investments across European automotive seating and interior component programs. Compounders with backward integration into aliphatic isocyanate alternatives are capturing specification wins in German premium OEM contracts. Marine applications in Nordic countries are accelerating waterborne epoxy and UV-curable resin adoption to preempt comparable regulatory extensions.
Consolidated procurement through tier-1 system integrators is displacing direct OEM relationships for specialized molders in wind energy blade manufacturing. Vestas and Siemens Gamesa are centralizing preform kit sourcing through qualified supply agreements that bundle fiber architecture, resin chemistry, and logistics into single-source contracts. This concentration is most visible in Denmark and northern Germany where blade engineering centers are co-located with molder qualification facilities.
Global Closed Molding Composites Market Segmentation
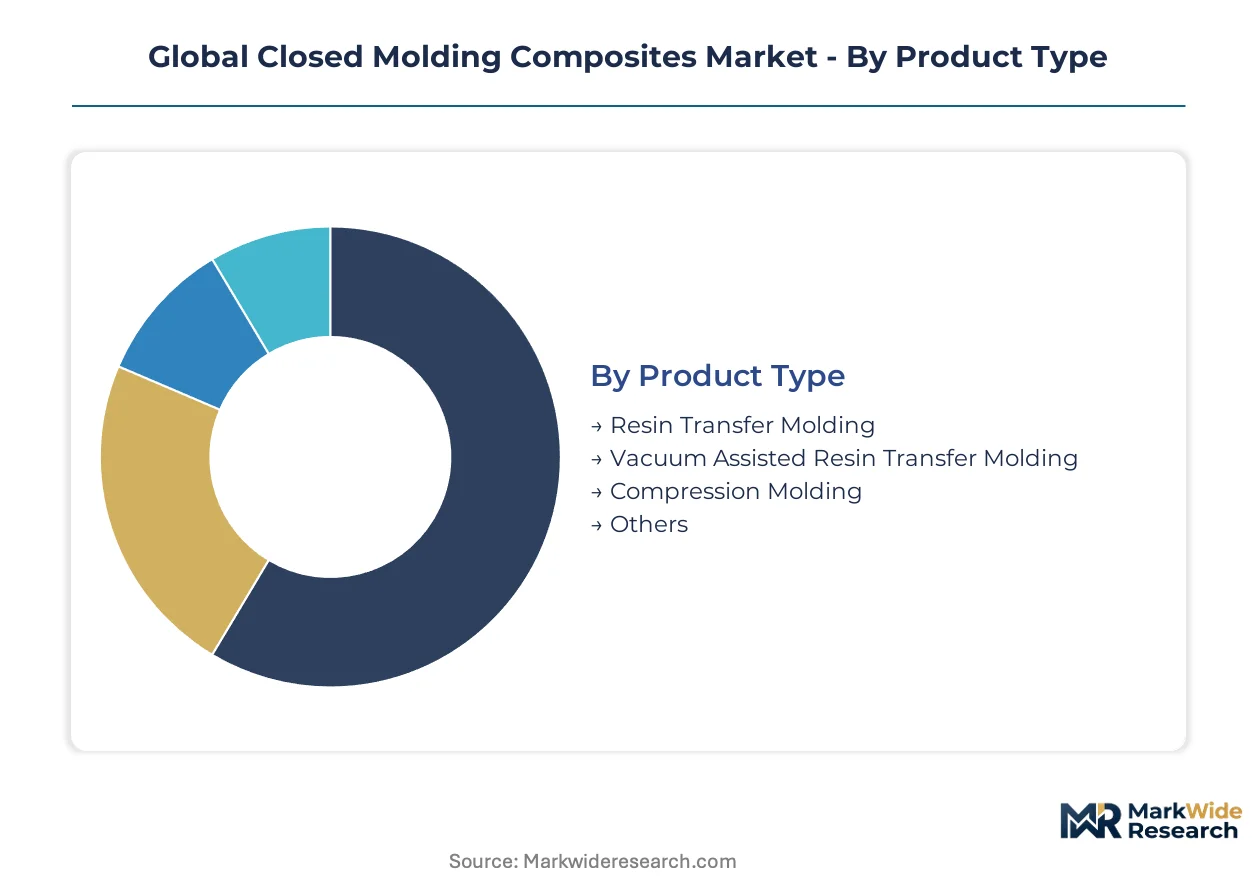
Segmentation in closed molding composites reveals how process economics, material specifications, and end-use certification requirements fragment competitive positioning across distinct value pools. Understanding these divides clarifies where capital deployment and technical specialization generate sustainable returns.
Product Type:
Highest margin capture sits with processes enabling complex geometries at aerospace-grade fiber volume fractions, where tooling amortization spreads across long production runs.
- Vacuum Assisted Resin Transfer Molding:Resin infusion under controlled vacuum achieves 50-60% fiber volume fractions with sub-1% void content for primary structural duty. Demand concentrates in Germany and Japan where automotive OEMs specify this process for lightweight chassis components under tightening emissions mandates.
- Compression Molding:Matched steel molds deliver sub-five-minute cycle times justifying capital intensity in serial automotive production. German OEM structural programs favor this method for displacing thermoplastic alternatives where throughput economics dominate.
- Resin Transfer Molding:Sealed injection circuits meet MEE volatile organic compound limits in China's Jiangsu province wind blade clusters.
- Others:Emerging hybrid processes target niche geometries in marine preform kit integration.
The dominant share belongs to Compression Molding, while Vacuum Assisted Resin Transfer Molding is gaining share fastest as aerospace and automotive qualification timelines compress.
Material:
Cost tier stratification separates commodity construction grades from certified structural chemistries commanding qualification premiums.
- Epoxy:Bisphenol-A and amine hardener formulations deliver thermal performance and mechanical properties required for aircraft primary frames. REACH authorization pressures on diisocyanates are accelerating reformulation investments across European automotive programs.
- Polyester:Styrene-based formulations retain volume leadership in construction and marine aesthetic panels where cost sensitivity overrides thermal requirements. EPA and MEE enforcement on open molding emissions directly accelerates closed process conversion in these sectors.
- Vinyl Ester:Corrosion resistance specifications dominate chemical processing and marine infrastructure applications.
- Phenolic:Fire-retardant grades serve rail and building code compliance in European construction.
Polyester holds the installed base advantage, though Epoxy climbs fastest as carbon fiber compatibility expands beyond aerospace into premium automotive.
End User:
Application maturity varies sharply, with aerospace qualification protocols creating eighteen-to-twenty-four-month approval cycles that freeze supplier relationships.
- Automotive:Serial production economics drive compression molding adoption in German and Japanese OEM lightweighting programs. PLI scheme incentives in India's Tamil Nadu and Maharashtra are creating first-mover openings for vacuum infusion specialists.
- Aerospace:Out-of-autoclave prepreg systems bifurcate sourcing between traditional autoclave-dependent suppliers and emerging vacuum-only qualified molders in Italy and Spain.
- Marine:Preform kit outsourcing displaces in-house lamination shops among Scandinavian yacht builders.
- Construction:REACH styrene reduction mandates accelerate closed process conversion from legacy spray-up infrastructure.
Automotive commands the largest revenue pool, while Marine demonstrates the steepest expansion trajectory as regulatory emissions enforcement tightens.
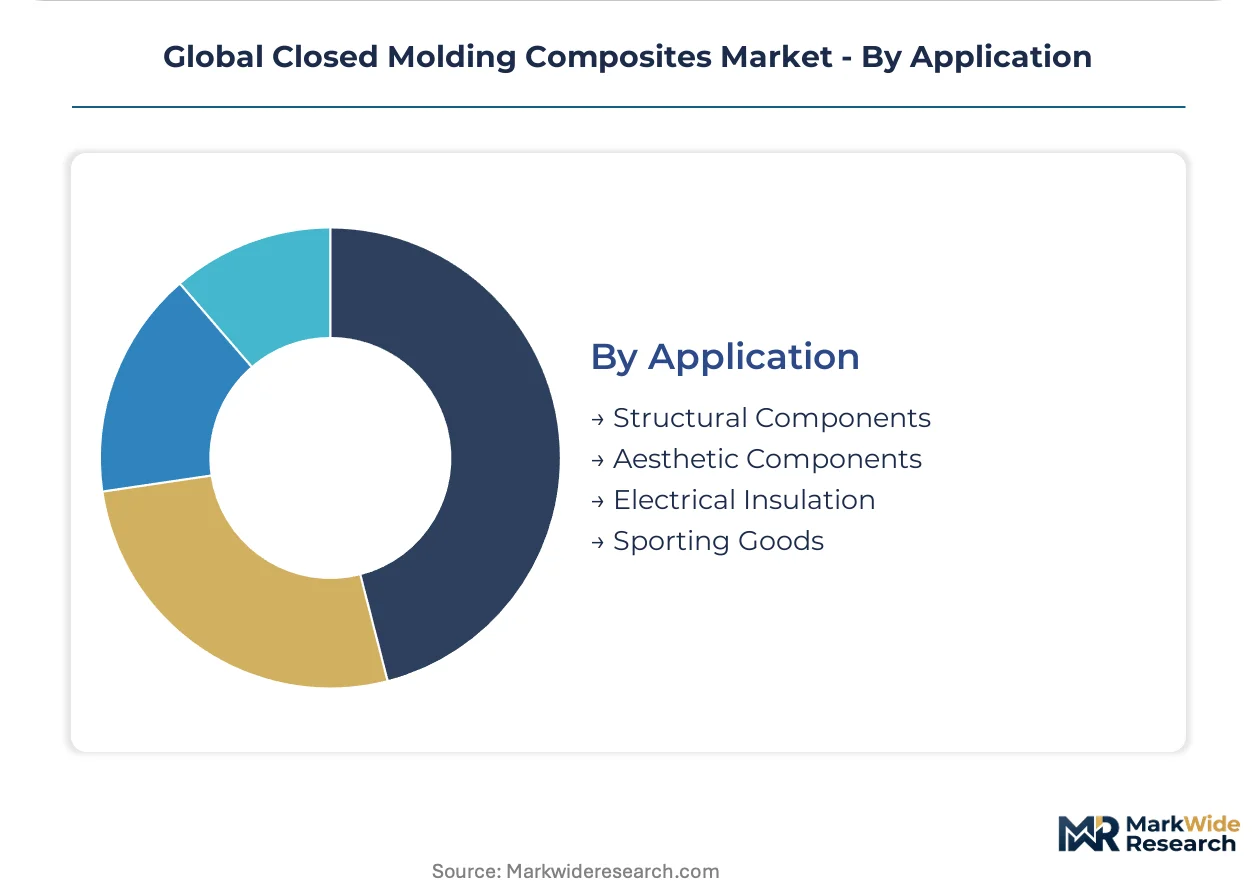
Application:
Performance requirements dictate material-process pairing, with structural duty commanding premium positioning over aesthetic or functional grades.
- Structural Components:Primary load-bearing applications mandate aerospace-grade fiber volume fractions and void content specifications. Vestas and Siemens Gamesa centralize preform kit sourcing through bundled supply agreements in Denmark and northern Germany.
- Aesthetic Components:Surface finish requirements in marine and construction panels prioritize cost-efficient polyester formulations where emissions compliance has become the binding constraint.
- Electrical Insulation:Phenolic and epoxy grades serve transformer and switchgear specifications.
- Sporting Goods:Carbon fiber preform kits target high-performance equipment with compressed development cycles.
Structural Components dominate procurement volumes, yet Aesthetic Components expand most quickly as regulatory conversion accelerates across European marine and construction sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's Jiangsu province and Germany's automotive belt show the least price elasticity for qualified preform kits, while marine fabricators in Southern Europe and construction contractors across India's secondary cities remain acutely sensitive to resin cost swings. This demand-elasticity contrast shapes regional investment patterns and supplier qualification timelines.
Germany
BMW and Mercedes-Benz compression molding programs for electric vehicle chassis components drive specification consolidation. REACH diisocyanate authorization pressures force polyurethane reformulation investments across Baden-Württemberg seating suppliers. Stuttgart-area molders are consolidating vacuum assisted resin transfer molding capacity to serve premium OEM lightweighting contracts.
China
Wind turbine blade production in Jiangsu province around Shanghai anchors resin transfer molding system deployments. MEE volatile organic compound enforcement pushes coastal manufacturers toward sealed injection circuits. The Yangtze River Delta cluster is absorbing the majority of domestic carbon fiber preform kit investments.
Japan
Toray Industries' captive aerospace fiber supply feeds directly into Nagoya-area compression molding lines for aircraft structural components. METI carbon neutrality roadmaps accelerate out-of-autoclave process adoption. The Chubu region hosts the densest concentration of qualified vacuum infusion specialists serving Boeing and Airbus tier-1 contracts.
United States
EPA styrene emission limits accelerate closed process conversion in Florida and California marine fabrication. Huntsman Corporation's Texas epoxy operations supply wind blade molders expanding Gulf Coast capacity. The Southeast automotive corridor is attracting compression molding investments to serve BMW Spartanburg and Mercedes-Benz Tuscaloosa programs.
India
PLI scheme incentives for electric vehicle manufacturing create first-mover openings for vacuum infusion specialists. BIS certification requirements for automotive composites extend supplier qualification timelines. Tamil Nadu and Maharashtra component clusters are consolidating preform kit partnerships with European technology licensors.
Global Closed Molding Composites Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with chemical compounders controlling resin chemistry and specialized molders commanding fiber architecture expertise. The market structures around three tiers: integrated resin-to-composite suppliers, captive fiber producers with downstream molding operations, and independent preform kit specialists. Strategic moves concentrate on backward integration into raw material supply and geographic expansion through qualified joint ventures in high-growth automotive and wind energy clusters.
Within the integrated chemical compounder tier, BASF and Huntsman Corporation exemplify backward integration strategies that capture margin across epoxy and polyurethane value chains. Toray Industries and Mitsubishi Chemical Group anchor the captive fiber producer segment, leveraging in-house carbon fiber supply to secure aerospace and automotive qualification positions. Gurit Holding occupies a specialist niche competing on tailored fiber architectures rather than commodity resin volumes.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group |
| BASF |
| Toray Industries |
| Owens Corning |
| Teijin Limited |
| Hexcel Corporation |
| Gurit Holding |
| Huntsman Corporation |
| SGL Carbon |
| Others |
Cost & Logistics Intelligence
Carbon fiber substitution for glass fiber in automotive structural programs simultaneously concentrates procurement around Japanese and German fiber suppliers while compressing margin pools for molders without captive supply. This material shift reconfigures supply geography toward Nagoya and Stuttgart while amplifying price volatility exposure for independent compounders.
Pricing Analysis
After-sales service contracts for mold maintenance and resin replenishment drive lifetime value capture across qualified supplier relationships. Three-tier pricing structure across aerospace-grade, automotive-certified, and industrial-commodity levels separates Toray's carbon fiber prepreg premiums from polyester bulk volumes. Pricing pressure stems from bisphenol-A feedstock volatility squeezing epoxy compounders. Tier-1 automotive OEMs in Germany show least price sensitivity for qualified preform kits, while Indian construction contractors remain acutely reactive to resin cost swings.
Supply Chain Analysis
Inventory cycles for aerospace-grade carbon fiber extend twelve to eighteen months, locking working capital into preform kit producers. Raw material supply concentrates in Japan, Germany, and China, with epoxy chemistry anchored in BASF's Ludwigshafen complex and carbon fiber production centered on Toray's Nagoya facilities. Single-source vulnerability runs through Japanese aerospace fiber suppliers. Distribution runs through tier-1 system integrators bundling fiber architecture, resin chemistry, and logistics into consolidated procurement agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
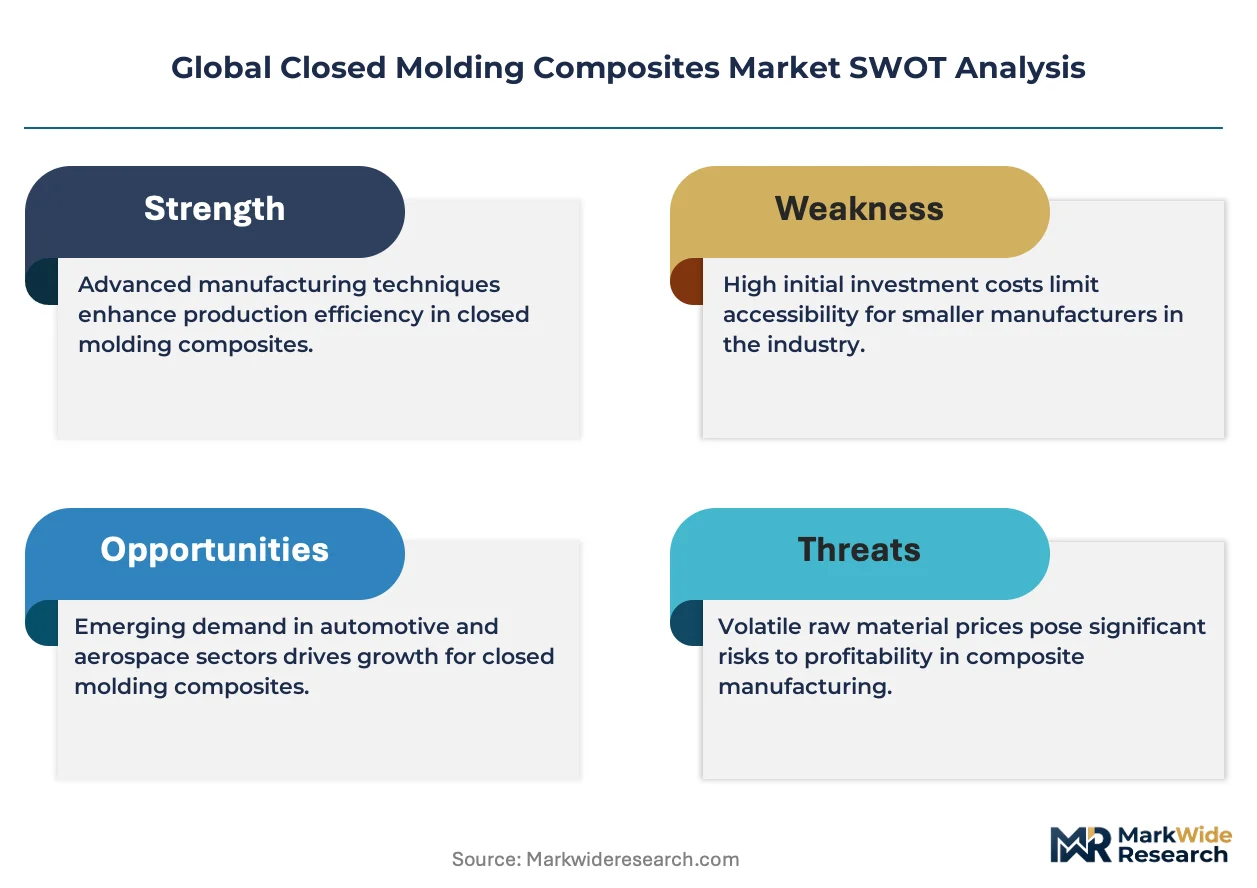
Thermoplastic composite substitution threatens epoxy-based closed molding incumbents in automotive lightweighting programs, forcing defensive repositioning around qualification moats and process differentiation.
For Market Incumbents: Fortify backward integration into resin chemistry to offset feedstock volatility, while accelerating out-of-autoclave qualification investments to defend against emerging vacuum-only molders in Italy and Spain. Captive carbon fiber supply and steel tool amortization at scale remain the priority defensive levers against mid-volume entrants. For New Entrants and Emerging Players: Preform kit outsourcing gaps among Scandinavian yacht builders and Indian automotive component clusters offer white-space penetration paths. Target Tamil Nadu and Maharashtra vacuum infusion partnerships under PLI scheme incentives, positioning through European technology licensing rather than greenfield chemistry development. For Investors and Strategic Acquirers: EU Green Deal carbon border adjustment mechanisms reshape the acquisition landscape toward certified bio-epoxy compounders with REACH-compliant formulations. Long-term viability centers on qualification-enabled pricing power rather than commodity volume scale. Monitor diisocyanate authorization enforcement as the signal for polyurethane reformulation investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Chemistry | BASF's Ludwigshafen complex captures margin across European automotive programs by controlling bisphenol-A supply. |
| Out-of-Autoclave Qualification Investment | Italian and Spanish tier-2 aerostructures contractors bypass prime OEM capacity constraints through vacuum-only certification. |
| Preform Kit Partnership Expansion | Gurit Holding displaces in-house lamination shops among Scandinavian yacht builders through tailored fiber architecture outsourcing. |
| Steel Tool Capacity Addition in Germany | Stuttgart-area molders consolidate vacuum assisted resin transfer molding capacity to serve BMW and Mercedes-Benz lightweighting contracts. |
| Bio-Based Resin Certification Program | EU Green Deal carbon border adjustments create supplier eligibility advantages for certified bio-epoxy compounders in wind energy procurement. |
Research Approach
A spread of perspectives from resin compounder procurement directors, automotive OEM platform engineers, wind blade manufacturing heads, and marine fabrication operators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs trade data, ECHA REACH authorization filings, SEC 10-K disclosures from listed compounders, and MEE environmental enforcement records. Bottom-up segment sizing triangulated against top-down demand modeling from end-use production forecasts.
Segmentation dimensions modeled include process technology, resin chemistry grade, fiber reinforcement type, end-use industry, and regional regulatory cluster across the analysis window. CAGRs derived from production volume trajectories, content-per-unit assumptions, and price evolution curves. Industry-specific forecast inputs incorporated wind turbine blade length trends and automotive electric vehicle platform lightweighting targets.
Forecasts assume regulatory continuity in EU REACH, EPA emissions enforcement, and China MEE volatile organic compound limits; material policy shifts would require re-modeling qualification timelines and substitution elasticities. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Green Composites Market
Composite Materials
Composite Material for Passenger Car Market
Composite Materials
High Temperature Composite Resin Market
Composite Materials
Case Material Market
Composite Materials
Light Curable Flowable Composite Market
Composite Materials
FRP Grating Market
Composite Materials
Composites Distributor Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
Lightweight Materials Market
Composite Materials
Global Molded FRP Grating Market
Composite Materials
Structural Composites Market
Composite Materials
Global FRP Sheets and Panels Market
Composite Materials
Global Carbon Fiber Reinforced Polymer Market
Composite Materials
Composites Testing Market
Composite Materials
Global Lightweight Construction Material Market
Composite Materials
LAMEA Composite Process Material Kits Market