
 Chemistry 4.0 Market | 2026-2036
Chemistry 4.0 Market Size, Share, and Industry Trends Forecast 2026-2036
Chemistry 4.0 Market Analysis
Multi-sourced digital infrastructure procurement is repositioning how chemical producers deploy IoT sensors and AI-driven process optimizers. BASF leverages its Ludwigshafen Verbund site to anchor captive data analytics capabilities across integrated production networks. Dow competes through specialized automation platforms for polymer batch consistency. Sinopec dominates domestic smart refinery deployments, extending its control over Asia's largest ethylene complexes.
Chemistry 4.0 denotes the convergence of artificial intelligence, industrial internet-of-things, and advanced data analytics with chemical manufacturing operations, typically involving real-time sensor arrays sampling temperature, pressure, and compositional variables at sub-second intervals to enable predictive process control and autonomous recipe adjustment. Its primary purpose is to yield efficiency gains, reduce waste generation, and accelerate product development cycles across commodity and specialty chemical production. Chemicals and polymers command the dominant product-type revenue pool, while catalysts represent the fastest-growing segment as precision dosing algorithms improve selectivity and throughput. Artificial intelligence applications are displacing conventional statistical process control in coatings formulation, where machine learning models now predict viscosity and adhesion properties from molecular descriptors.
The EPA enforces emissions monitoring mandates that compel U.S. chemical facilities to install continuous digital reporting systems, while REACH and the EU Green Deal impose substance traceability requirements that drive blockchain-anchored supply chain platforms. China's MEE enforces dual carbon goals that restrict energy-intensive batch processes, redirecting capital toward continuous-flow technologies with embedded automation. Stakeholders must evaluate whether backward integration into sensor hardware or partnership with specialized analytics vendors offers superior returns as regulatory granularity intensifies.
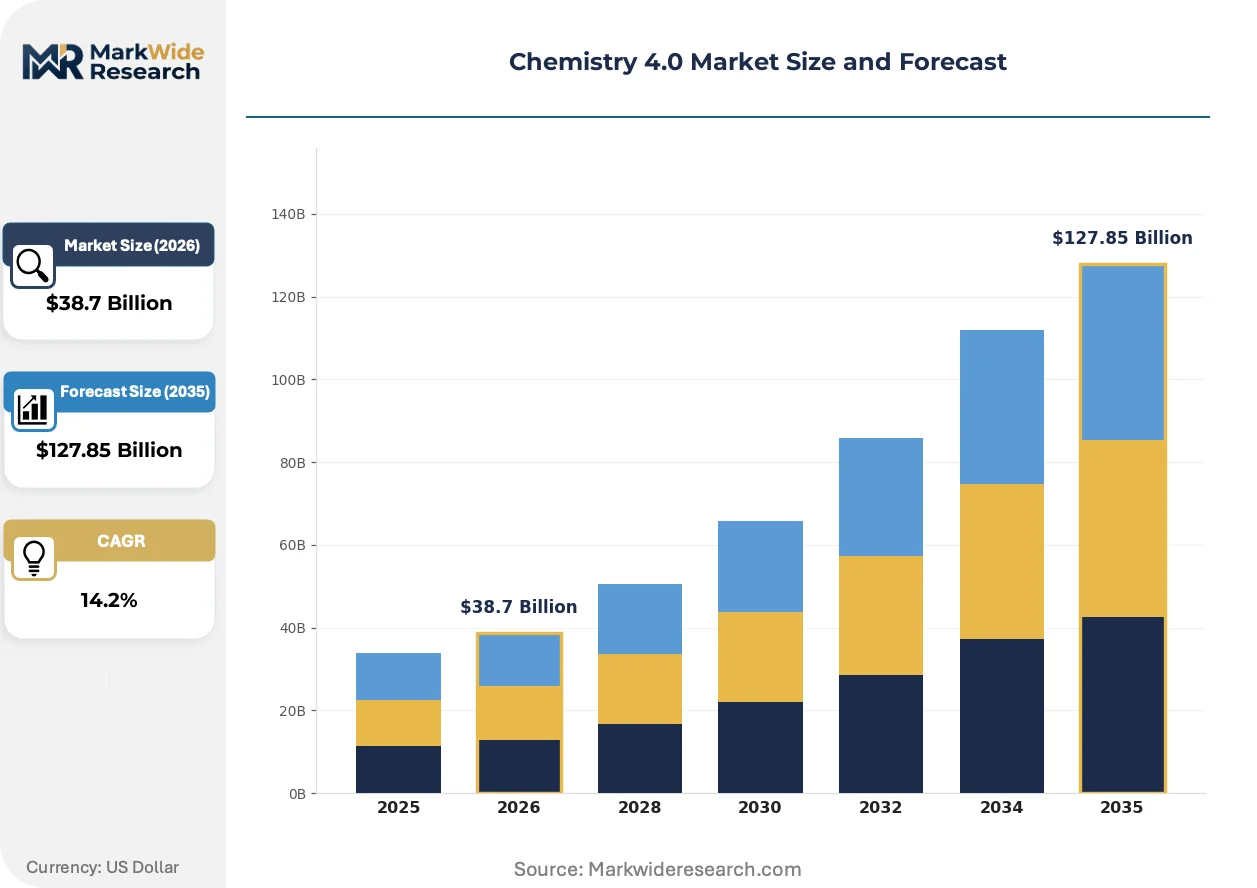
Market Dynamics
The EU Green Deal's emissions trading framework is tightening compliance requirements for chemical producers, forcing capital reallocation toward sensor-embedded continuous-flow systems and predictive maintenance infrastructure.
Growth Catalysts
- REACH substance traceability mandates:European chemical manufacturers deploy blockchain-anchored supply chain platforms to satisfy granular documentation requirements, accelerating digital infrastructure procurement.
- Polymer batch consistency demands:Specialty chemical buyers insist on real-time viscosity prediction through machine learning models, pulling AI adoption into coatings formulation.
- Germany's Rhine corridor concentration:Integrated smart manufacturing clusters at Ludwigshafen and Leverkusen generate network effects that lower per-unit digital deployment costs for neighboring producers.
Market Restraints
- Sensor hardware cost volatility:Rare earth price swings in Chinese export markets compress margins for facilities undertaking full-stack IoT retrofits of legacy batch reactors.
- MEE dual carbon enforcement:China's Ministry of Ecology and Environment restricts energy-intensive processes, stranding capital in conventional production assets before automation payback periods complete.
- Interoperability limitations:Proprietary data protocols from competing automation vendors fragment plant-wide analytics integration, delaying autonomous recipe adjustment deployment.
Strategic Opportunities
- India's PLI scheme for advanced manufacturing:Domestic chemical producers qualify for production-linked incentives when embedding Industry 4.0 compliance into greenfield specialty chemical plants.
- Predictive catalyst dosing convergence:Precision algorithms combining quantum chemistry simulation with real-time spectroscopy open throughput gains in polyethylene and polypropylene lines.
- EPA continuous emissions monitoring mandates:U.S. facilities face compulsory digital reporting installation, creating captive demand for integrated sensor-to-cloud platforms that vendors can bundle with optimization software.
Industry Challenges
- Process control engineer scarcity:Chemical plants compete with technology firms for talent capable of bridging statistical process control with neural network architecture.
- Legacy DCS integration friction:Decades-old distributed control systems at commodity chemical sites resist API connectivity, forcing expensive middleware development or full replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemistry 4.0 Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemicals, Polymers, Additives, Catalysts Application: Pharmaceuticals, Petrochemicals, Agrochemicals, Coatings Technology: Automation, Data Analytics, IoT, Artificial Intelligence End Use Industry: Manufacturing, Healthcare, Food & Beverage, Environmental |
| Companies Covered | BASF, Dow, Sinopec, Sabic, Ineos, Formosa Plastics, ExxonMobil Chemical, LyondellBasell Industries, Mitsubishi Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemistry 4.0 Market Emerging Trajectories
Artificial intelligence architectures are compressing product development cycles while regulatory granularity forces data infrastructure standardization. Three developments dominate the current transformation.
Edge computing platforms are decentralizing process analytics by relocating inference workloads from centralized cloud servers to on-premise industrial gateways. Polymer producers at Sinopec's Zhenhai complex deploy these architectures to achieve sub-50-millisecond latency for safety-critical pressure adjustments. This topology is decentralizing vendor influence away from hyperscale cloud providers toward specialized industrial software firms with hardened hardware portfolios.
REACH authorization requirements for Substances of Very High Concern are compelling full molecular genealogy documentation from raw material through formulation. European coatings manufacturers now embed digital substance passports at the batch level, with ECHA audit trails extending to downstream automotive OEMs. Specialty chemical segments with complex multi-step syntheses bear the heaviest compliance burden and are consolidating supplier relationships to reduce documentation fragmentation.
Buyers in pharmaceutical manufacturing are unbundling after-sales service contracts from automation hardware procurement, demanding API-accessible performance guarantees instead of fixed maintenance schedules. This restructures vendor revenue toward outcome-contingent pricing models. German fine chemical producers have pioneered this shift, with Merck KGaA and Evonik negotiating throughput-based fees for AI-driven yield optimization platforms rather than capital-intensive licensing arrangements.
Chemistry 4.0 Market Segmentation
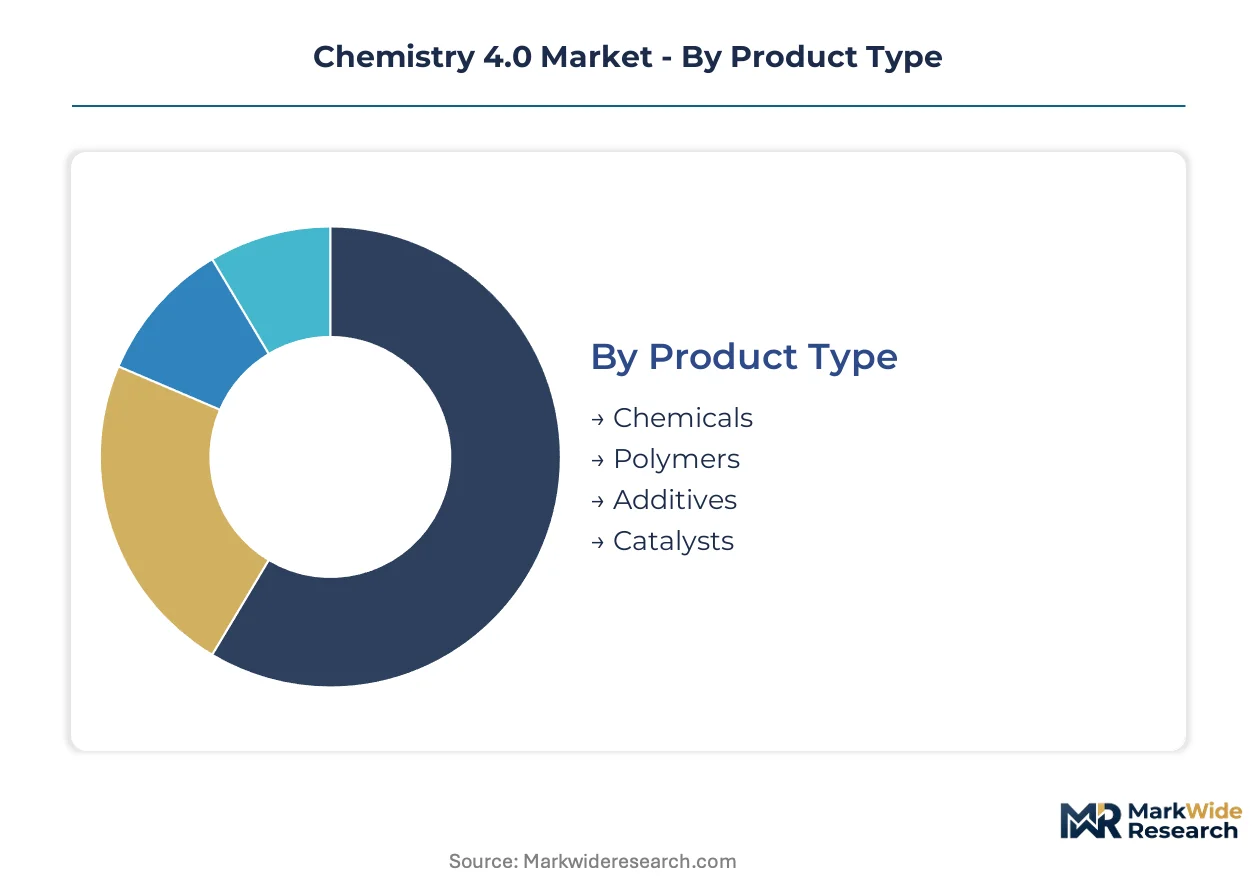
Chemistry 4.0 deployment patterns diverge sharply across product categories and industrial applications. Segment-specific digital maturity determines where AI-driven process control yields immediate returns versus where legacy retrofit costs delay adoption.
Product Type:
Supply concentration in commodity chemicals creates divergent digital investment profiles across molecular categories.
- Chemicals:Bulk inorganics and commodity organics deploy sensor arrays for continuous-flow reactor optimization. Demand clusters in Germany's Ludwigshafen corridor where BASF's Verbund integration enables shared predictive maintenance infrastructure.
- Polymers:Polyethylene and polypropylene lines require real-time melt index prediction through machine learning models. Specialty buyers in automotive and packaging enforce batch consistency standards that pull AI adoption from statistical process control.
- Additives:Functional additives for lubricants and plastics incorporate digital formulation databases to accelerate regulatory compliance documentation.
- Catalysts:Precision dosing algorithms improve selectivity in fluid catalytic cracking and polymerization units.
Chemicals absorb the bulk of installed capacity; catalysts are expanding most quickly.
Application:
Margin compression in downstream processing creates tiered digital investment thresholds across chemical value chains.
- Pharmaceuticals:FDA-enforced process analytical technology mandates drive continuous manufacturing adoption. Real-time release testing replaces end-point quality control, compressing batch release cycles from weeks to hours.
- Petrochemicals:Integrated refinery-petrochemical complexes at Sinopec's Zhenhai and ExxonMobil's Baytown deploy digital twins for furnace yield optimization. Steam cracker energy intensity monitoring satisfies MEE dual carbon enforcement.
- Agrochemicals:Formulation consistency requirements for pesticide active ingredients deploy spectroscopic PAT sensors.
- Coatings:Viscosity and adhesion prediction from molecular descriptors displaces empirical testing protocols.
Petrochemicals absorb the bulk of installed capacity; pharmaceuticals is climbing the fastest.
Technology:
Interoperability limitations between vendor platforms fragment procurement patterns for chemical producers.
- Automation:Distributed control system retrofits face API connectivity friction at decades-old batch reactor sites. Greenfield specialty chemical plants embed Industry 4.0 compliance from commissioning.
- Data Analytics:Edge computing architectures relocate inference workloads to on-premise industrial gateways, achieving sub-50-millisecond latency for safety-critical pressure adjustments.
- IoT:Rare earth price volatility in Chinese export markets compresses margins for full-stack sensor retrofits of legacy assets.
- Artificial Intelligence:Neural network architectures for yield optimization compete with technology firms for process control engineering talent.
Automation absorbs the bulk of installed capacity; artificial intelligence is gaining share fastest.
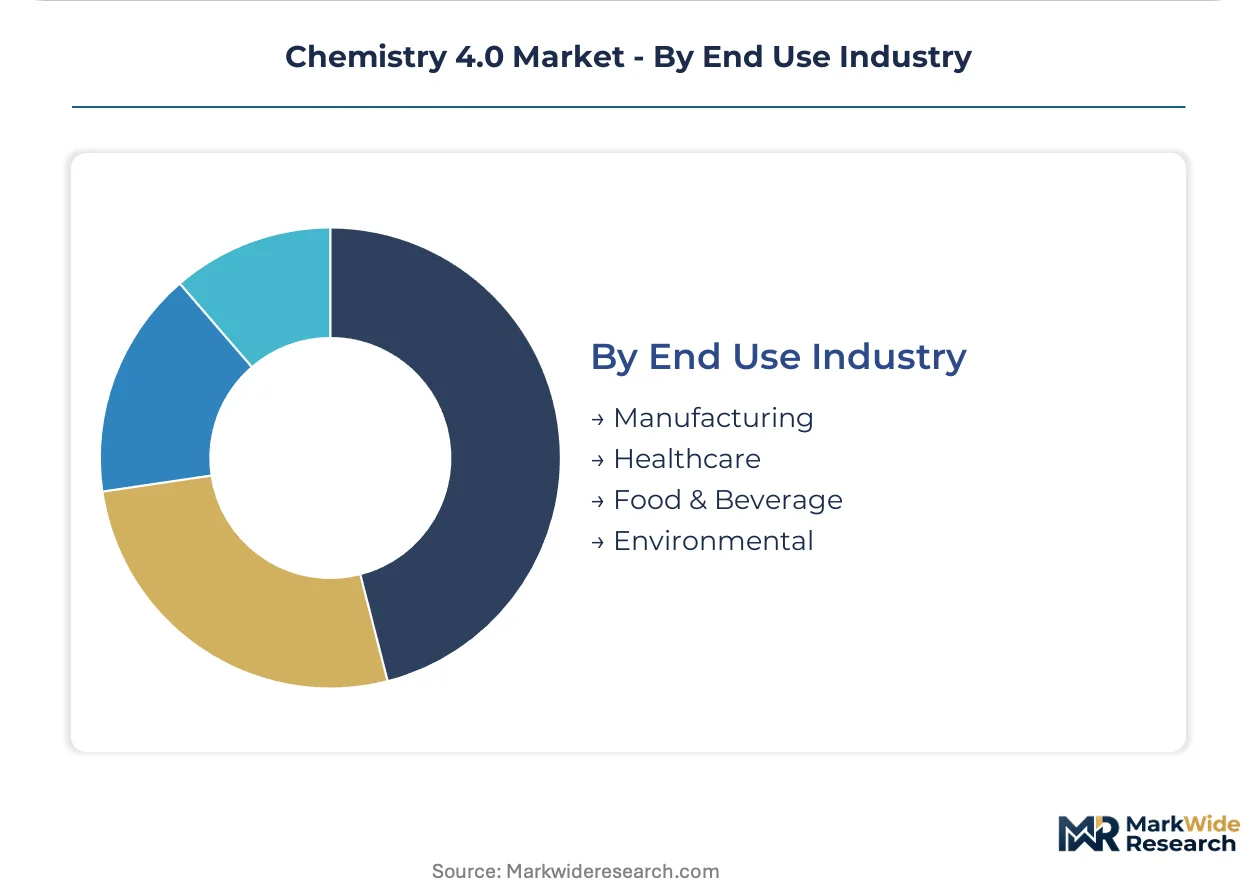
End Use Industry:
Regulatory granularity varies dramatically across downstream sectors, shaping digital infrastructure procurement urgency.
- Manufacturing:Automotive OEMs enforce digital substance passports from coatings suppliers, extending ECHA audit trail requirements through multi-tier supply chains.
- Healthcare:Continuous bioprocessing adoption in monoclonal antibody production deploys real-time titer prediction and automated harvest scheduling.
- Food & Beverage:Flavor and fragrance molecular genealogy documentation satisfies REACH authorization requirements for Substances of Very High Concern.
- Environmental:EPA continuous emissions monitoring mandates create captive demand for integrated sensor-to-cloud platforms bundled with optimization software.
Manufacturing absorbs the bulk of installed capacity; environmental is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rhine River petrochemical corridors and Gulf Coast ethylene complexes anchor Chemistry 4.0 deployment density, with regulatory pressure and integrated manufacturing clusters pulling automation investment toward specific industrial zones.
United States
EPA continuous emissions monitoring mandates force Gulf Coast refineries to install sensor-to-cloud reporting infrastructure. The Inflation Reduction Act channels tax credits toward carbon capture retrofits with embedded digital control systems. Houston-Baytown petrochemical complexes deploy digital twins for furnace yield optimization.
Germany
Ludwigshafen Verbund integration enables shared predictive maintenance infrastructure across contiguous production networks. EU Green Deal emissions trading tightens compliance thresholds for Rhine corridor chemical producers. Leverkusen smart manufacturing clusters generate network effects lowering per-unit digital deployment costs.
China
MEE dual carbon enforcement restricts energy-intensive batch processes at Zhenhai and Ningbo complexes. Dual carbon goals redirect capital toward continuous-flow technologies with embedded automation. Yangtze River Delta ethylene producers deploy edge computing architectures for sub-50-millisecond safety-critical pressure adjustments.
Saudi Arabia
Jubail industrial city concentration pulls AI-driven process control into integrated refinery-petrochemical complexes. SAMR standards alignment accelerates digital infrastructure procurement for export-oriented producers. Eastern Province producers leverage captive feedstock integration to anchor predictive catalyst dosing platforms.
Japan
Chubu region chemical producers face METI pressure to reduce energy intensity through real-time process optimization. JIS standards for industrial automation create procurement clarity for sensor hardware vendors. Osaka-Kobe manufacturing belt concentrates specialty chemical digital maturity.
Chemistry 4.0 Market Vendor Landscape
Strategic partnerships dominate the current landscape as chemical producers seek to bridge legacy distributed control systems with neural network architectures. The vendor base organizes around three tiers: integrated multinational conglomerates with captive digital capabilities, specialized industrial software firms with hardened edge hardware portfolios, and regional automation integrators serving single-site retrofits. Competitive positioning crystallizes through M&A activity targeting predictive analytics startups and technology licensing arrangements for proprietary dosing algorithms.
Within the integrated multinational tier, BASF, Dow, and Sinopec exemplify divergent strategic postures. BASF occupies a position anchored by Verbund site integration, leveraging contiguous production networks to amortize digital infrastructure across multiple product lines. Dow sits within the specialized automation vector, competing through platforms targeting polymer batch consistency. Sinopec represents the state-backed scale archetype, dominating domestic smart refinery deployments across Asia's largest ethylene complexes.
| Leading Market Players |
|---|
| BASF |
| Dow |
| Sinopec |
| Sabic |
| Ineos |
| Formosa Plastics |
| ExxonMobil Chemical |
| LyondellBasell Industries |
| Mitsubishi Chemical |
| Others |
Supply Flow & Price Mechanics
Rare earth oxide price indices from Chinese export markets cascade through sensor hardware procurement into three-tier pricing structures separating premium AI-enabled platforms from standard automation bundles and economy retrofit kits. Pharmaceutical manufacturers unbundling after-sales service contracts compress margins for vendors still bundling fixed maintenance schedules.
Pricing Analysis
Service-bundling unbundling by German fine chemical buyers is compressing vendor margins across the installed base. Pricing stratifies across premium AI-yield platforms, standard DCS retrofits, and economy sensor-only deployments. Cost compression in the economy tier is intensifying because rare earth price volatility squeezes full-stack IoT retrofit margins. Specialty chemical producers prove least price-sensitive, accepting throughput-based fees for autonomous recipe adjustment; commodity chemical sites exhibit highest sensitivity, delaying payback-critical automation investments.
Supply Chain Analysis
ISO 27001 and IEC 62443 certification gating restricts vendor qualification for critical infrastructure deployments across European and North American chemical facilities. Sensor hardware supply concentrates in China, Germany, and Japan. Production draws from rare earth concentrates, silicon photonics components, and hardened industrial processors. Single-source vulnerability runs through Chinese rare earth export quotas. Distribution feeds through system integrators and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
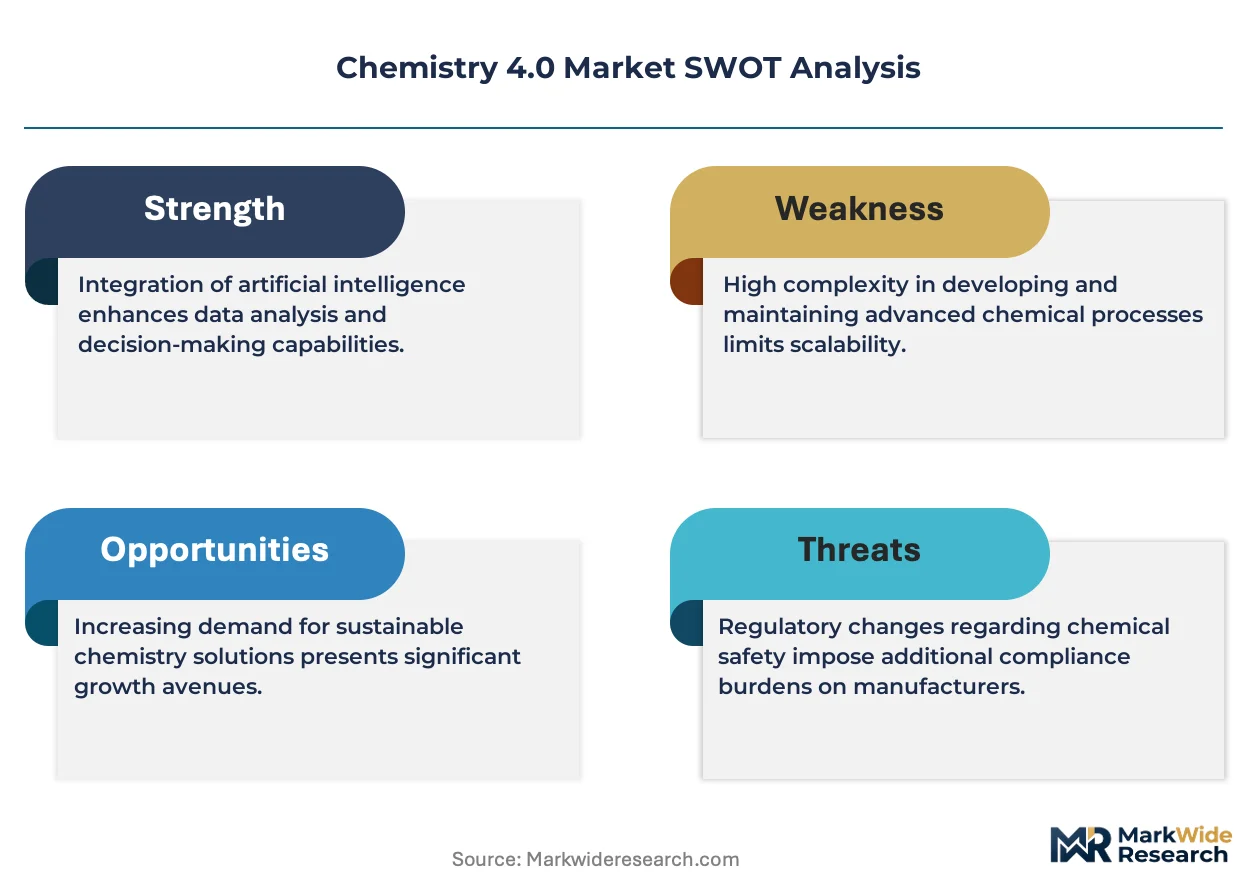
Analyst Recommendations
Chemistry 4.0 competitive dynamics are accelerating into a vertical-integration race as producers pursue captive control over edge computing hardware to escape hyperscale cloud dependency.
For Market Incumbents: To counter proprietary data protocol fragmentation from competing automation vendors, BASF-class producers should anchor open API standards across Verbund networks while acquiring specialized edge hardware firms to harden on-premise inference capabilities. For New Entrants and Emerging Players: Mid-size Indian specialty chemical producers under PLI scheme qualification thresholds represent the most penetrable buyer archetype. White-space exists in continuous-flow retrofit packages for stranded batch assets and blockchain-anchored supply chain documentation for REACH-pressured European coatings suppliers. Go-to-market should leverage outcome-contingent pricing tied to yield improvement guarantees. For Investors and Strategic Acquirers: Distressed-cycle entries favor predictive analytics startups with pharmaceutical PAT compliance credentials in Germany's Rhine corridor. Long-term viability hinges on neural network architectures bridging statistical process control legacy. The signal to watch is FDA real-time release testing mandate expansion beyond biologics into small-molecule continuous manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Edge Hardware | Captive production of industrial gateways reduces hyperscale cloud dependency for Sinopec-class producers. |
| Green Manufacturing Transition | Continuous-flow reactor conversion satisfies MEE dual carbon enforcement while embedding automation from commissioning. |
| Long-term Supply Agreement | Rare earth offtake contracts with Australian miners insulate sensor vendors from Chinese export quota volatility. |
| Joint Venture | Automation vendors partnering with BASF leverage Ludwigshafen network effects to amortize R&D across contiguous production. |
| Acquisition of Specialist Firm | Quantum chemistry simulation startups enable precision catalyst dosing algorithms for polyethylene throughput gains. |
Methodological Framework
Independent corroboration across plant manager interviews, procurement leads at downstream automotive OEMs, and distribution channel partners underwrites the qualitative findings. Secondary validation draws from ACC and Cefic trade association reports, customs and trade flow databases, and SEC 10-K automation vendor disclosures. Bottom-up segment sizing triangulates against top-down macro chemical production capacity estimates.
Comparable-period anchoring to historical digital adoption curves in adjacent process industries shapes the projection horizon. Segmentation modeling spans product type, application, technology deployment, and regional production hub characteristics. CAGRs derive from fitted growth curves calibrated to disclosed automation vendor bookings and regulatory compliance deadline clustering. Industry-specific inputs include EPA emissions monitoring mandate implementation timelines and EU ETS carbon price trajectory assumptions.
Revisions become necessary when rare earth export restriction severity, REACH authorization list expansion, or neural network talent migration patterns materialize outside modeled bounds. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology substitution elasticities. A model refresh is warranted upon material change in FDA continuous manufacturing guidance or MEE dual carbon enforcement stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
North America Next Generation Anode Materials Market
Advanced Materials
Europe Blanket Aerogel Market
Advanced Materials
High-Purity Amorphous Boron Market
Advanced Materials
Europe Aerogel Market
Advanced Materials
Carbon Graphite Market
Advanced Materials
Global Electrostrictive Material Market
Advanced Materials
Advanced Functional Materials Market
Advanced Materials
North America Plasma Powder Market
Advanced Materials
Natural Single Crystal Diamond Market
Advanced Materials
Borophene Market
Advanced Materials
Advanced Sports Materials Market
Advanced Materials
Nomex Honeycomb Market
Advanced Materials
Magnetic Shielding Sheets Market
Advanced Materials
Long-Range Ordered Porous Carbon (LOPC) Market
Advanced Materials
Flexible Bio-Foams Market
Advanced Materials
Global Glass Filled Nylon Market