
 Durability Testing Systems Market | 2026-2036
Durability Testing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Durability Testing Systems Market Foresight
Equipment leasing and performance-based service contracts are fragmenting capital deployment across the durability testing landscape. MTS Systems Corporation leverages its hydraulic actuator installed base to lock in long-term service revenue. Bureau Veritas anchors its competitiveness through integrated certification and testing workflows that reduce client vendor counts. Kistler Holding AG specializes in piezoelectric force measurement chains that command premium positioning in automotive crash labs.
Durability testing systems subject materials, components, and assemblies to repeated mechanical, thermal, or environmental stress to predict service life and failure modes; electromechanical frames apply sinusoidal or random waveforms up to thousands of hertz while hydraulic rigs generate multi-axis loads exceeding meganewtons for full-vehicle structural validation. Dynamic testing rigs capture the fastest expansion as EV battery packs and electric drivetrains require vibration and shock qualification beyond traditional internal-combustion architectures. Environmental testing chambers concentrate margin pools where combined temperature-humidity-vibration protocols meet aerospace and medical device qualification standards.
NHTSA mandates FMVSS crashworthiness compliance that drives automotive OEMs toward multi-axis durability rigs, while the EU Green Deal's embodied-carbon tracking requirements push manufacturers to validate recycled-material performance across longer test cycles. ISO 17025 accreditation frames market access for third-party labs serving medical device and aerospace supply chains. Stakeholders must weigh captive versus outsourced testing capacity as regulatory scope widens and equipment utilization economics shift.
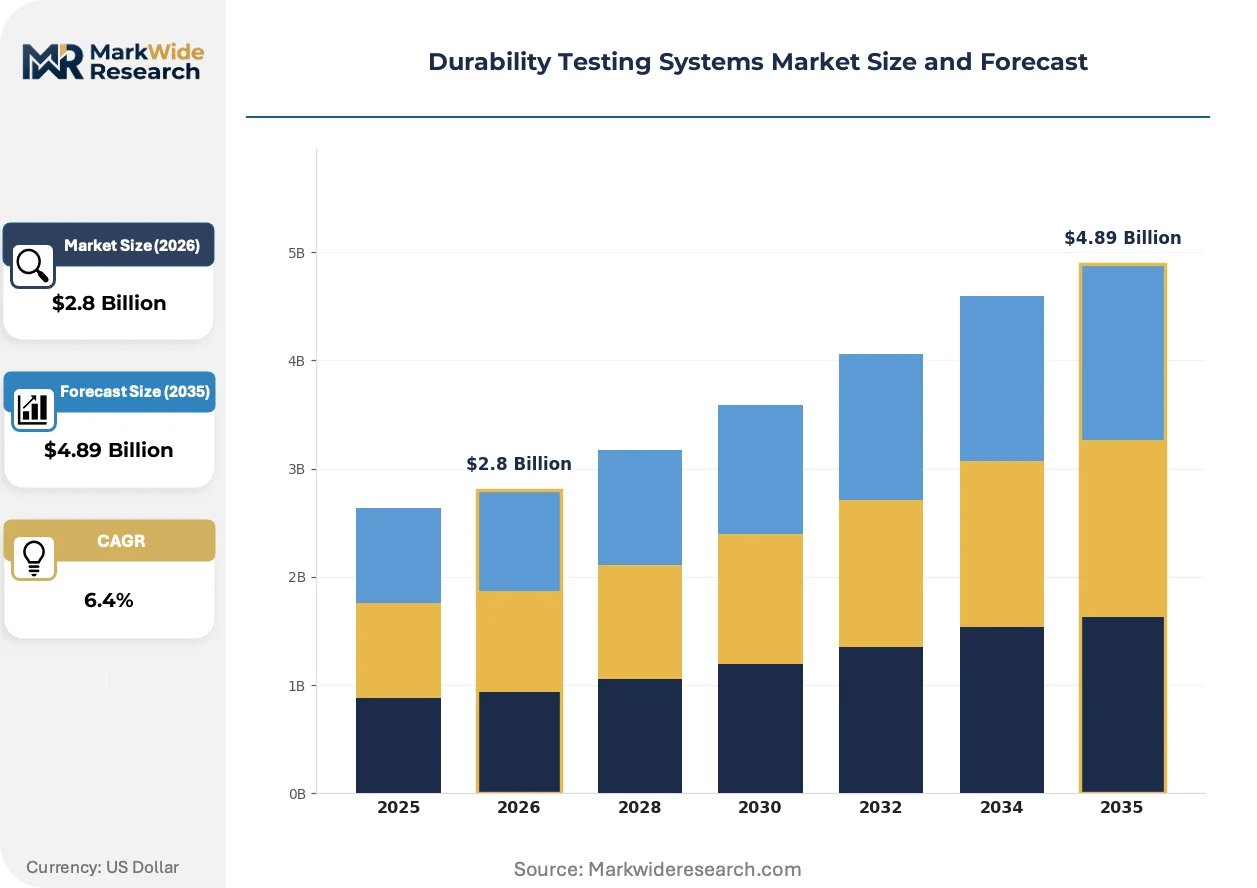
Market Dynamics
Automotive electrification is forcing a wholesale retooling of validation protocols as battery packs and electric drivetrains demand vibration frequencies and thermal cycling regimes that exceed legacy internal-combustion test matrices.
Growth Catalysts
- EU Green Deal embodied-carbon mandates:Manufacturers must validate recycled aluminum and composite performance across extended fatigue cycles, driving replacement of obsolete single-axis rigs with multi-channel environmental chambers.
- China's NEV platform proliferation:Domestic OEMs and battery cell producers are commissioning combined temperature-humidity-vibration systems at scale to qualify pack-level durability under MIIT homologation timelines.
- Solid-state battery commercialization:Next-generation cell architectures require novel mechanical abuse testing and pressure-cycling protocols that obsolete conventional lithium-ion qualification equipment.
Market Restraints
- High-purity hydraulic fluid cost volatility:Specialized synthetic formulations for multi-axis servo-hydraulic rigs have experienced input cost swings that compress service contract margins for equipment lessors.
- Sensor supply concentration in Germany and Japan:Piezoelectric force transducer production clusters around Kistler and Kyowa manufacturing footprints, creating single-source vulnerability for crash lab operators.
- ISO 17025 accreditation timelines:Third-party test houses face 12-18 month certification windows that delay revenue recognition on new environmental chamber installations.
Strategic Opportunities
- India's PLI scheme for automotive component testing:Domestic suppliers are building captive durability capacity to serve export markets, creating demand for electromechanical frames with localized service support.
- Medical device wearable qualification:Biocompatibility and sweat-corrosion testing for continuous glucose monitors and hearing aids opens specialized chamber applications beyond traditional industrial markets.
- Digital twin integration with physical rigs:Convergence of real-time sensor telemetry and finite-element simulation enables predictive maintenance contracts that extend equipment lifecycle value.
Industry Challenges
- Multi-physics simulation expertise scarcity:Test engineers capable of correlating thermal-mechanical-electrical degradation models command premium compensation that strains mid-size lab operating budgets.
- Legacy data format incompatibility:Decades of proprietary file structures from MTS, Instron, and Zwick systems obstruct unified analytics platforms and cloud-based reporting architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Durability Testing Systems Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Testing, Dynamic Testing, Fatigue Testing, Environmental Testing Industry Vertical: Aerospace, Automotive Parts, Consumer Electronics, Medical Devices Technology: Electromechanical, Hydraulic, Pneumatic, Thermal End User: Manufacturers, Research Institutions, Quality Control Labs, Automotive OEMs |
| Companies Covered | Horiba Mira, MTS Systems Corporation, Intertek Group Plc, SGS SA, TÜV SÜD, Bureau Veritas, AVL, Kistler Holding AG, Instron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Durability Testing Systems Market Shifts & Advancements
Real-time data streaming and edge computing architectures are compressing test cycle feedback loops while enabling predictive failure modeling that shifts validation from reactive pass-fail to proactive design optimization.
Embedded fiber-optic strain sensing is digitizing structural health monitoring during fatigue testing by replacing bonded foil gauges with distributed measurement chains. Automotive OEMs in Germany and the United States are retrofitting existing hydraulic rigs with photonic interrogators to capture full-field deformation maps. This digitizing of load path visualization enables root-cause analysis in hours rather than weeks, compressing platform development timelines for EV skateboard architectures.
NHTSA's updated FMVSS side-impact and roof-crush protocols are mandating higher load-rate fidelity and post-test data retention periods. Test houses must upgrade data acquisition systems to 500 kHz sampling rates and implement blockchain-anchored test records for litigation defense. Full-vehicle structural labs in Michigan and California face the steepest compliance investments as they validate pickup truck and SUV platforms under the revised standards.
Leasing structures with utilization-linked payment terms are displacing traditional capital purchase models for environmental chambers. Tier-2 automotive suppliers in Mexico and Eastern Europe prefer per-test-hour contracts that transfer obsolescence risk to equipment vendors. This preference concentrates in regions where OEMs impose shorter model-cycle commitments and demand flexible capacity scaling without balance-sheet expansion.
Durability Testing Systems Market Segmentation
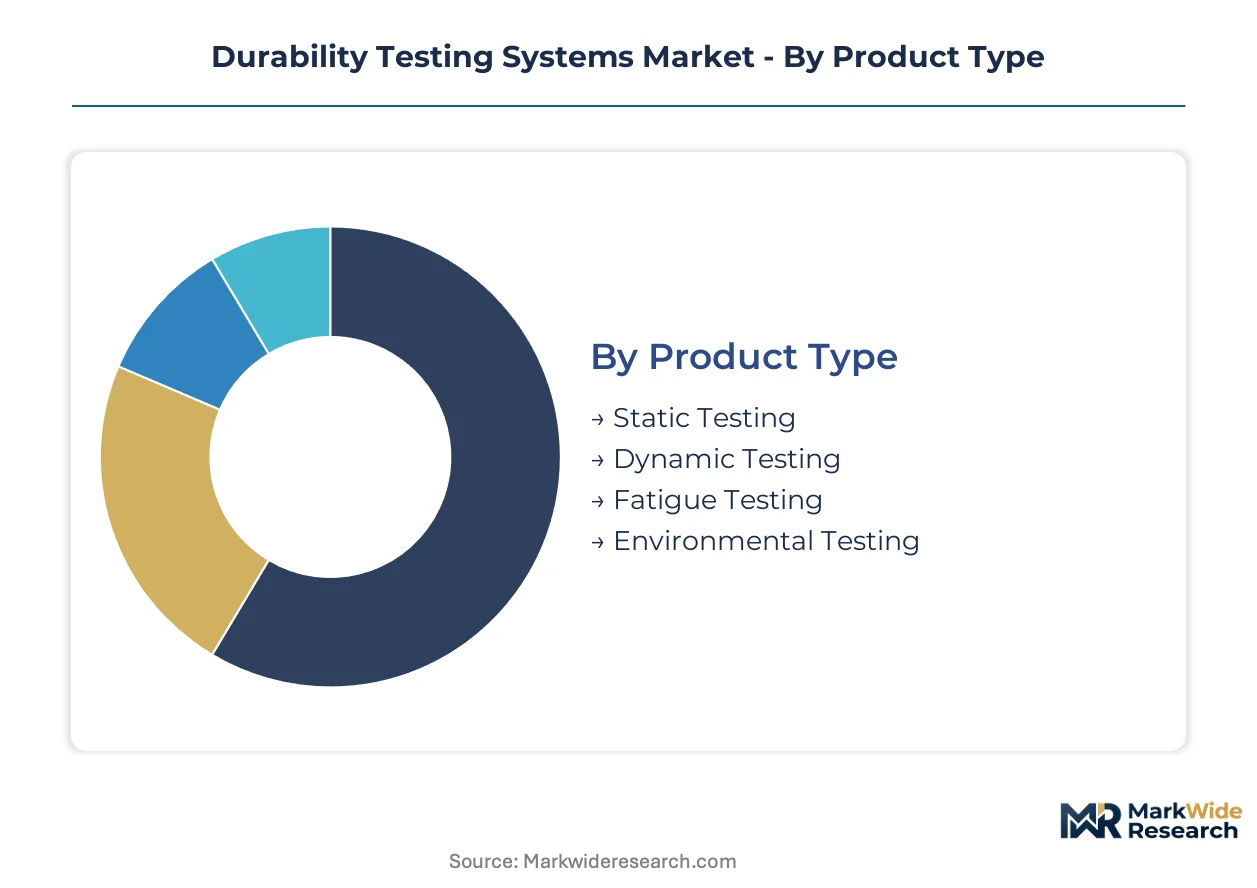
Segmentation in durability testing systems reveals how equipment specifications, validation protocols, and procurement models diverge across end-use requirements. Each dimension—product architecture, industry application, actuation technology, and buyer type—carries distinct margin profiles and competitive dynamics that reshape vendor positioning.
Product Type:
Application severity and test cycle complexity separate these equipment categories, with automotive and aerospace qualification protocols driving divergence in load capacity and environmental simulation requirements.
- Static Testing:Uniaxial and multi-axial frames apply sustained loads to characterize creep deformation and ultimate tensile strength. German automotive tier suppliers deploy these systems for chassis bracket validation under KBA homologation requirements.
- Dynamic Testing:Servo-hydraulic and electromechanical rigs generate oscillating loads from millihertz to kilohertz frequencies. EV battery pack manufacturers in China commission these systems for vibration qualification under MIIT safety mandates, with demand concentrating at combined temperature-vibration facilities.
- Fatigue Testing:High-cycle and low-cycle regimes predict crack initiation and propagation in metallic and composite structures. Aerospace fastener producers utilize these rigs for airframe joint validation.
- Environmental Testing:Chambers integrate thermal cycling, humidity control, and corrosive atmosphere exposure. Medical device manufacturers in Switzerland and the United States qualify implantable electronics under ISO 17025 protocols.
Static testing holds installed capacity. Dynamic testing is rotating up the share rankings.
Industry Vertical:
Margin concentration varies sharply by vertical, with certification burden and liability exposure determining willingness to pay for precision and traceability.
- Aerospace:Structural integrity validation for airframes, engines, and landing gear demands multi-axis fatigue rigs with full-scale specimen capacity. US and European prime contractors specify NADCAP-accredited testing for supply chain qualification.
- Automotive Parts:Suspension components, powertrain mounts, and structural adhesives undergo durability cycles simulating 150,000-mile service life. Mexican suppliers serving Detroit OEMs are expanding captive testing capacity under USMCA localization pressures.
- Consumer Electronics:Drop testing, hinge fatigue, and thermal shock protocols validate smartphones, laptops, and wearables. Shenzhen contract manufacturers drive volume demand for compact electromechanical frames.
- Medical Devices:Biocompatibility, sterilization cycling, and fatigue testing for implants and surgical instruments require ISO 14155 traceability. German and Swiss orthopedic device producers anchor premium chamber demand.
Aerospace commands premium pricing tiers. Automotive parts is gaining share fastest as EV platform proliferation extends validation requirements.
Technology:
Actuation method determines force range, frequency response, and energy efficiency trade-offs that lock buyers into specific service ecosystems.
- Electromechanical:Ball-screw and linear motor drives deliver precise displacement control with lower energy consumption and minimal hydraulic infrastructure. Consumer electronics and medical device labs in Japan and South Korea favor these systems for cleanroom compatibility.
- Hydraulic:Servo-valve controlled fluid power generates meganewton forces for full-vehicle structural and aerospace component testing. US and German automotive OEMs maintain extensive installed bases despite higher maintenance burden.
- Pneumatic:Compressed air systems address lower-force applications with rapid cycling capability. Packaging and furniture manufacturers utilize these for cost-sensitive repetitive load testing.
- Thermal:Heating and cooling subsystems enable temperature cycling independent of mechanical loading. Battery cell producers require these for thermal runaway characterization.
Hydraulic technology holds installed capacity. Electromechanical is rotating up the share rankings.
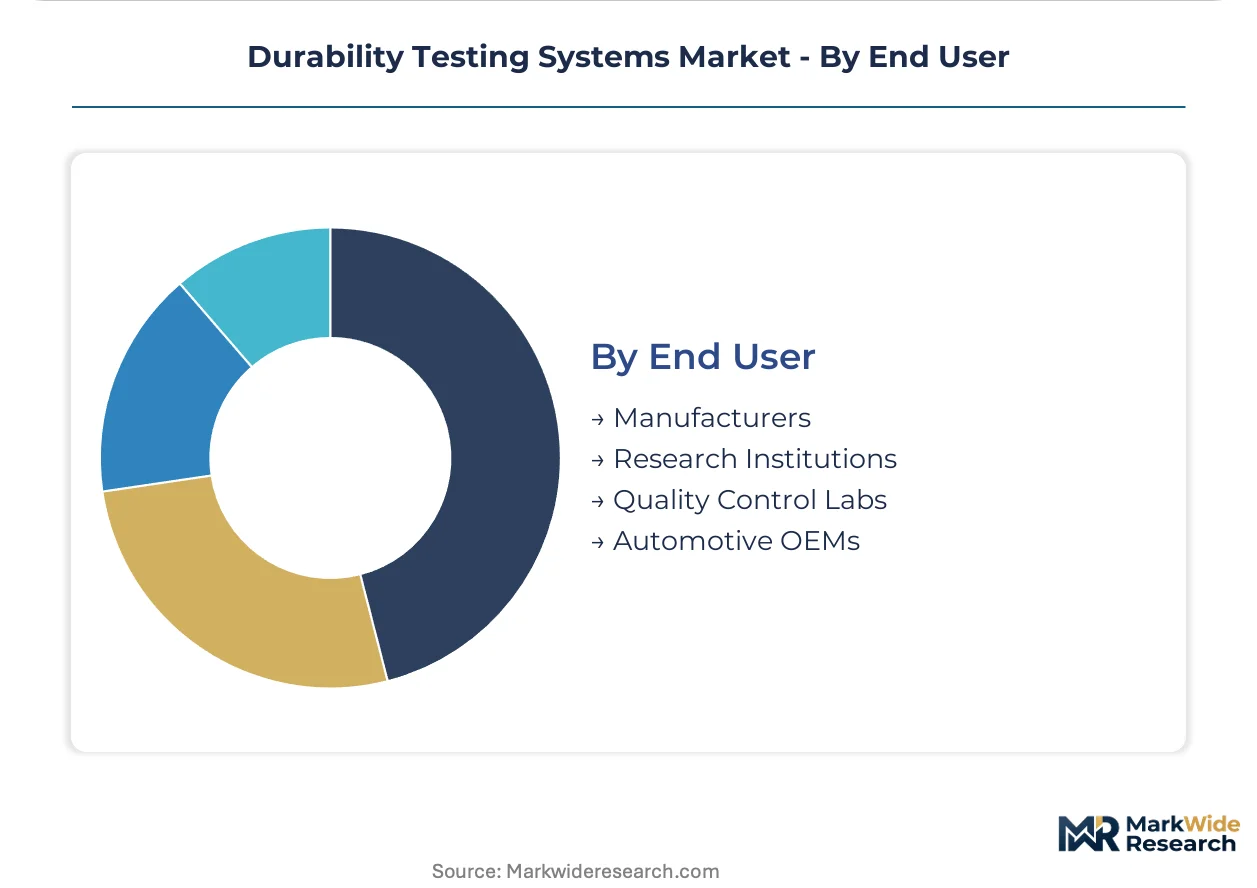
End User:
Procurement sophistication and utilization economics separate captive from outsourced testing capacity, with accreditation requirements filtering vendor selection.
- Manufacturers:In-house durability labs at tier-1 automotive and aerospace suppliers prioritize throughput and integration with design engineering workflows. India's PLI scheme beneficiaries are building captive capacity for export market access.
- Research Institutions:University and government laboratories pursue fundamental materials characterization with emphasis on publication-grade data fidelity. German Fraunhofer institutes and US national laboratories anchor demand for multi-physics testing platforms.
- Quality Control Labs:Third-party test houses serving multiple clients require ISO 17025 accreditation and flexible capacity scaling. Bureau Veritas and SGS operate global networks with regional chamber installations.
- Automotive OEMs:Vehicle manufacturers maintain proprietary validation facilities for platform development and regulatory submission. NHTSA FMVSS compliance drives upgrade cycles at Michigan and California structural labs.
Automotive OEMs hold installed capacity. Quality control labs is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented automotive manufacturing clusters drive equipment procurement patterns across major economies, with regulatory divergence creating specialized demand pockets for compliance-grade testing infrastructure. Import dependency for high-precision sensor components concentrates in German and Japanese supply chains, shaping regional vendor strategies.
United States
NHTSA FMVSS crashworthiness mandates and EPA emissions protocols force automotive OEMs to upgrade multi-axis structural rigs at Michigan and California validation centers. The Inflation Reduction Act's domestic content requirements accelerate captive testing capacity buildouts for EV battery qualification. Detroit-area tier-1 suppliers expand fatigue testing footprints to serve USMCA-compliant export programs.
Germany
KBA homologation standards and EU Green Deal embodied-carbon tracking push manufacturers toward extended-cycle environmental chambers for recycled-material validation. Fraunhofer research institutes anchor demand for multi-physics characterization platforms. Bavarian automotive clusters commission combined temperature-humidity-vibration systems for next-generation drivetrain development.
China
MIIT new energy vehicle safety mandates and dual carbon goals drive battery cell producers to install thermal runaway characterization equipment at scale. Domestic OEMs in the Yangtze River Delta region build combined testing facilities to accelerate NEV platform homologation. Shanghai and Shenzhen testing hubs concentrate procurement of electromechanical frames for consumer electronics durability validation.
India
PLI scheme incentives for automotive component manufacturing spur captive durability lab investments among export-focused suppliers. BIS certification requirements and CDSCO medical device regulations create dual demand streams for electromechanical and environmental testing systems. Tamil Nadu and Maharashtra industrial corridors attract chamber installations serving pharmaceutical and automotive export markets.
Japan
METI carbon neutrality roadmaps and JIS standards for automotive lightweighting push manufacturers to validate composite performance across accelerated fatigue regimes. Precision equipment manufacturers in the Nagoya and Osaka industrial zones maintain demand for piezoelectric force measurement chains. Medical device producers in the Kanto region invest in ISO 17025-accredited environmental chambers for implantable electronics qualification.
Durability Testing Systems Market Competitive Landscape
On the supply side, the industry is consolidating around integrated testing service providers while specialized equipment manufacturers defend niche technology positions. Hydraulic actuator and electromechanical frame producers operate in distinct procurement ecosystems with limited customer overlap. Strategic archetypes include full-service validation houses, precision sensor specialists, and regional certification networks. Competitive moves center on long-term service contract lock-ins and cross-border accreditation expansion to capture multinational OEM procurement.
Within the integrated validation tier, Bureau Veritas and SGS SA exemplify global certification networks that bundle testing workflows with regulatory submission support. MTS Systems Corporation anchors the equipment-centric segment through hydraulic actuator installed bases that generate recurring service revenue. Kistler Holding AG occupies a premium positioning archetype focused on piezoelectric force measurement chains for automotive crash laboratories.
| Leading Market Players |
|---|
| Horiba Mira |
| MTS Systems Corporation |
| Intertek Group Plc |
| SGS SA |
| TÜV SÜD |
| Bureau Veritas |
| AVL |
| Kistler Holding AG |
| Instron |
| Others |
Supply & Pricing Matrix
Bavarian automotive clusters anchor European supply capacity for multi-axis servo-hydraulic rigs, and their equipment utilization rates directly transmit into downstream pricing power for third-party validation services across the continent.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers attach to ISO 17025-accredited chambers with full calibration traceability, while economy tiers serve uncertified captive labs with stripped service contracts. Cost compression in the hydraulic fluid supply tier is intensifying because synthetic formulation input costs have swung unpredictably. Tier-2 automotive suppliers in Mexico exhibit the highest price sensitivity, whereas aerospace prime contractors in the United States demonstrate the least.
Supply Chain Analysis
Export-control restrictions on high-precision piezoelectric sensor technology limit flows from German and Japanese manufacturing footprints. Production concentrates in Germany, Japan, and the United States for force transducer assemblies. The supply chain draws from specialty steel forgings, high-purity hydraulic fluids, and fiber-optic sensing components. Single-source vulnerability around Kistler and Kyowa production creates structural risk. Distribution runs through authorized service networks with long-term maintenance bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering talent capable of correlating thermal-mechanical-electrical degradation models commands compensation premiums that strain mid-size lab operating budgets, creating a persistent capability gap that shapes competitive outcomes.
For Market Incumbents: Harden installed-base lock-in through predictive maintenance contracts that extend equipment lifecycle value and capture telemetry data for design feedback loops. Deepen backward integration into sensor calibration services to offset margin pressure from hydraulic fluid cost volatility. Defend against emerging digital-twin specialists by anchoring physical rig superiority with real-time simulation convergence. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme beneficiary tier, where domestic automotive component suppliers are building captive durability capacity without legacy vendor relationships. Target medical device wearable qualification as the most penetrable application, where biocompatibility and sweat-corrosion testing protocols remain undersupplied. Lead with localized service support and rapid ISO 17025 accreditation assistance as the go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors equipment-as-a-service platforms with recurring revenue streams over pure hardware manufacturers. Long-term viability rests on vendors that bridge physical testing rigs with digital-twin integration capabilities. Target acquisition archetypes include piezoelectric sensor specialists with automotive crash-lab relationships and regional certification networks with cross-border accreditation expansion. Watch for inflection when NHTSA mandates blockchain-anchored test records as standard compliance.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Convergence of real-time sensor telemetry with finite-element simulation enables predictive maintenance contracts that extend equipment lifecycle value for MTS Systems Corporation installed bases. |
| ISO 17025 Accreditation Expansion | Cross-border certification investments allow Bureau Veritas to capture multinational OEM procurement across EU Green Deal and NHTSA compliance workflows. |
| Localized Service Network Buildout | Regional chamber installations with per-test-hour contracts transfer obsolescence risk to equipment vendors in Mexico and Eastern Europe. |
| Piezoelectric Sensor Specialization | Premium positioning in automotive crash labs commands pricing power for Kistler Holding AG amid single-source supply concentration. |
| Backward Integration into Calibration | In-house production of sensor calibration services offsets hydraulic fluid cost volatility and protects service contract margins. |
Research Methodology
Initial hypotheses were tested against primary input from validation lab directors, automotive OEM platform engineers, tier-1 supplier procurement leads, and aftermarket service heads, and refined through secondary validation against SEC 10-K filings, customs and trade data, NHTSA FMVSS submission records, and ISO accreditation registries. Bottom-up equipment shipment analysis was triangulated with top-down spending estimates from automotive and aerospace R&D budgets.
Demand-supply balance dynamics across the analysis window were modeled through segmentation across product architecture, actuation technology, industry vertical, and end-user procurement model, with specific attention to EV battery pack qualification intensity and medical device wearable testing expansion. CAGRs were derived from installed base replacement cycles and new capacity buildouts. Forecast inputs incorporated MIIT homologation timelines and EU Green Deal embodied-carbon tracking requirements.
Macroeconomic conditions sit as an overlay; deviation in capital expenditure cycles at automotive OEMs or export credit availability for emerging market labs would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology substitution rates. Material shifts in solid-state battery commercialization timelines or NHTSA data retention mandate implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
High-Temperature Corrosion and Creep Testing Equipment for Process Industries Market
Testing Equipment
Chromatography Data Systems Market
Testing Equipment
Next-Generation Titrators Market
Testing Equipment
Rheometer Market
Testing Equipment
Chloride Reagents Kits Market
Testing Equipment
Benchtop Density Meter for Solids Market
Testing Equipment
Chemical Detector Market
Testing Equipment
Continuous Flow Analyzer Market
Testing Equipment
Salt Spray Chamber Market
Testing Equipment
U-Tube Viscometer Market
Testing Equipment
PFAS Ultra-Trace Water Analysis Test Instruments Market
Testing Equipment
Global Distillate Oil Testing Service Market
Testing Equipment
Liquid Analytical Instrument Market
Testing Equipment
Global Chromatography Columns Market
Testing Equipment
Dynamic Vapor Sorption Analyzer Market
Testing Equipment
Electrical Testing Equipment Market