
 Europe Aerogel Market | 2026-2036
Europe Aerogel Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aerogel Market Foresight
CE marking under the EU Construction Products Regulation is reorganizing competitive access for aerogel insulation suppliers across member states. Aspen Aerogels Inc. anchors its European position through dedicated manufacturing capacity and thermal insulation specialization. BASF SE leverages its polymer chemistry heritage to compete in polymer aerogel formulations. Svenska Aerogel AB differentiates through cost-efficient silica aerogel production methods developed in Sweden.
Aerogel denotes a synthetic porous ultralight material derived from a gel, where the liquid component has been replaced with gas, yielding densities as low as 0.003 g/cm³ and thermal conductivities reaching 0.012 W/m·K at ambient pressure. Silica aerogel dominates commercial supply due to decades of process maturation and established supply chains serving oil and gas pipeline insulation. Carbon aerogel occupies emerging niches in energy storage electrodes where electrical conductivity complements porosity. Polymer aerogel represents the fastest-expanding structural category, driven by mechanical flexibility requirements in automotive and aerospace weight-reduction programs.
EMA and ECHA frameworks govern chemical safety and environmental release thresholds for aerogel precursors, while the EU Green Deal and F-Gas Regulation directly shape insulation procurement by penalizing high-global-warming-potential alternatives. Member state building codes transposing the Energy Performance of Buildings Directive create fragmented but binding demand pull for superinsulating materials. Stakeholders must monitor revision cycles of the EU Taxonomy for sustainable activities, which determines green financing eligibility for construction projects specifying aerogel systems.
Market Dynamics
Binding efficiency mandates under the EU Energy Performance of Buildings Directive are compressing payback periods for superinsulating retrofits, pulling silica aerogel into mainstream construction specifications across Germany and France.
Growth Catalysts
- F-Gas Regulation:The EU framework penalizes hydrofluorocarbon-based insulating foams, creating procurement pull for lower-emission aerogel alternatives in commercial building envelopes.
- Energy-intensive manufacturing:Germany's industrial corridor faces binding efficiency mandates that accelerate thermal insulation upgrades in process equipment and facility envelopes.
- Silica aerogel maturation:Decades of process refinement have collapsed production costs, enabling specification in mid-market construction projects previously served by conventional mineral wool.
Market Restraints
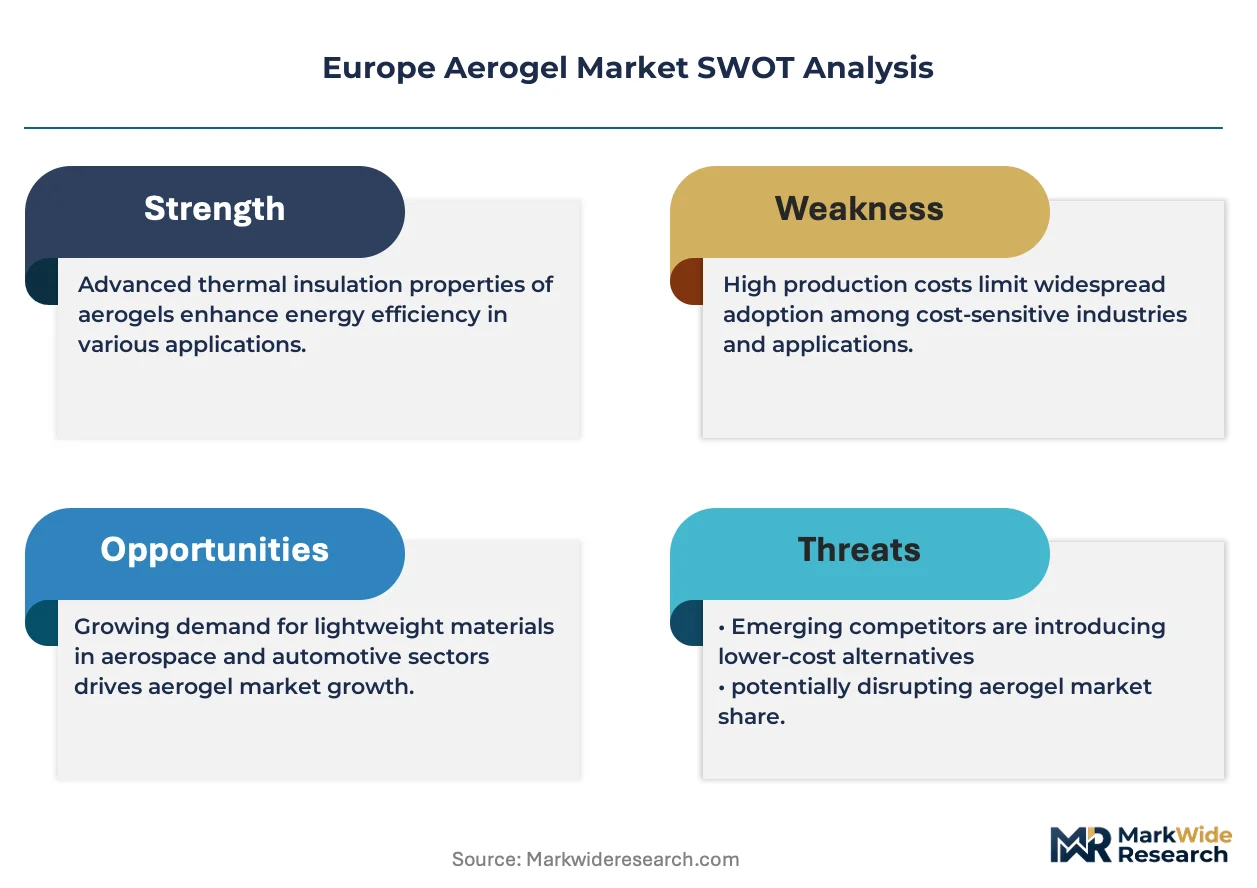
- Precursor cost volatility:Tetramethyl orthosilicate and other organosilicon feedstocks tie aerogel economics to petrochemical pricing cycles, compressing margins during upstream spikes.
- Production concentration:Commercial silica aerogel capacity clusters in Sweden and Germany, creating geographic supply risk for southern European projects.
- Mechanical brittleness:Silica aerogel's friability limits monolithic panel sizes and requires protective encapsulation, adding fabrication steps that conventional insulations avoid.
Strategic Opportunities
- France's building renovation wave:The national strategy for low-carbon renovation targets residential stock built before 1975, opening volume demand for aerogel-based internal wall insulation systems.
- Polymer aerogel convergence:Mechanical flexibility from polyimide and polyurethane formulations is unlocking automotive battery pack thermal barriers and aerospace cabin insulation.
- EU Taxonomy alignment:Green financing eligibility for construction projects specifying certified low-carbon insulation creates a specification wedge against incumbent materials.
Industry Challenges
- Installation certification gaps:CE marking under the Construction Products Regulation requires member-state-specific technical approvals, fragmenting go-to-market timelines across borders.
- Solvent recovery capex:Supercritical drying infrastructure demands seven-figure capital commitments, constraining capacity expansion to well-capitalized producers.
- Silica dust exposure protocols:ECHA workplace exposure limits for respirable crystalline silica impose handling procedures that elevate contractor training costs and liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aerogel Market |
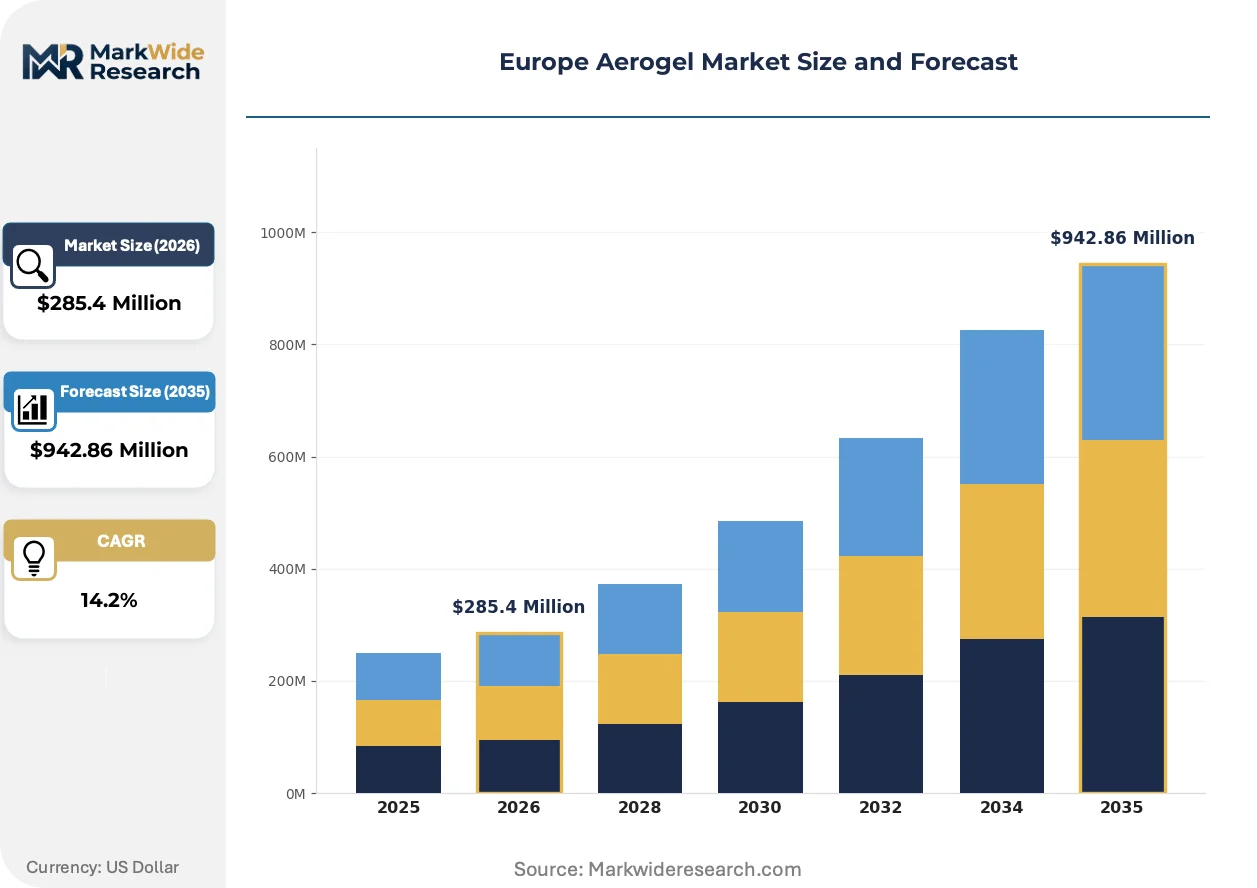
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $942.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica Aerogel, Carbon Aerogel, Polymer Aerogel, Metal Oxide Aerogel Application: Thermal Insulation, Oil & Gas, Aerospace, Automotive End User: Construction, Energy, Transportation, Electronics Form: Granules, Blocks, Powder, Coatings |
| Companies Covered | BASF SE, Cabot Corporation, Aspen Aerogels Inc., Svenska Aerogel AB, Green Earth Aerogel Technologies, Enersens, Aerogel Technologies, Aerogel-it GmbH, Armacell International S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aerogel Market Shifts & Advancements
Ambient pressure drying routes are collapsing the capital barrier to aerogel production, enabling mid-scale European entrants to challenge incumbent supercritical-drying specialists on cost and lead time.
Silica aerogel composite blankets are fragmenting the thermal insulation category by combining superinsulating performance with textile-like handling. Automotive battery pack engineers at Volvo and BMW are specifying these materials for inter-cell thermal barriers. The technology is fragmenting procurement patterns by displacing both mica sheets and intumescent coatings in electric vehicle architectures.
The EU F-Gas Regulation's phasedown schedule is compressing specification windows for high-GWP blowing agents in polyurethane foams. Building envelope consultants in the Netherlands and Belgium are rewriting thermal bridge details around aerogel strips. The policy is forcing insulation distributors to retrain sales teams on superinsulating alternatives ahead of 2030 phase-out milestones.
Buyer concentration among European building retrofit consortia is consolidating purchasing power. France's Effilogis and Germany's KfW-funded renovation aggregators are negotiating frame contracts directly with aerogel manufacturers, bypassing traditional merchant distribution. The behavior is most visible in multi-family residential retrofits where standardized envelope packages reduce engineering overhead per project.
Europe Aerogel Market Segmentation
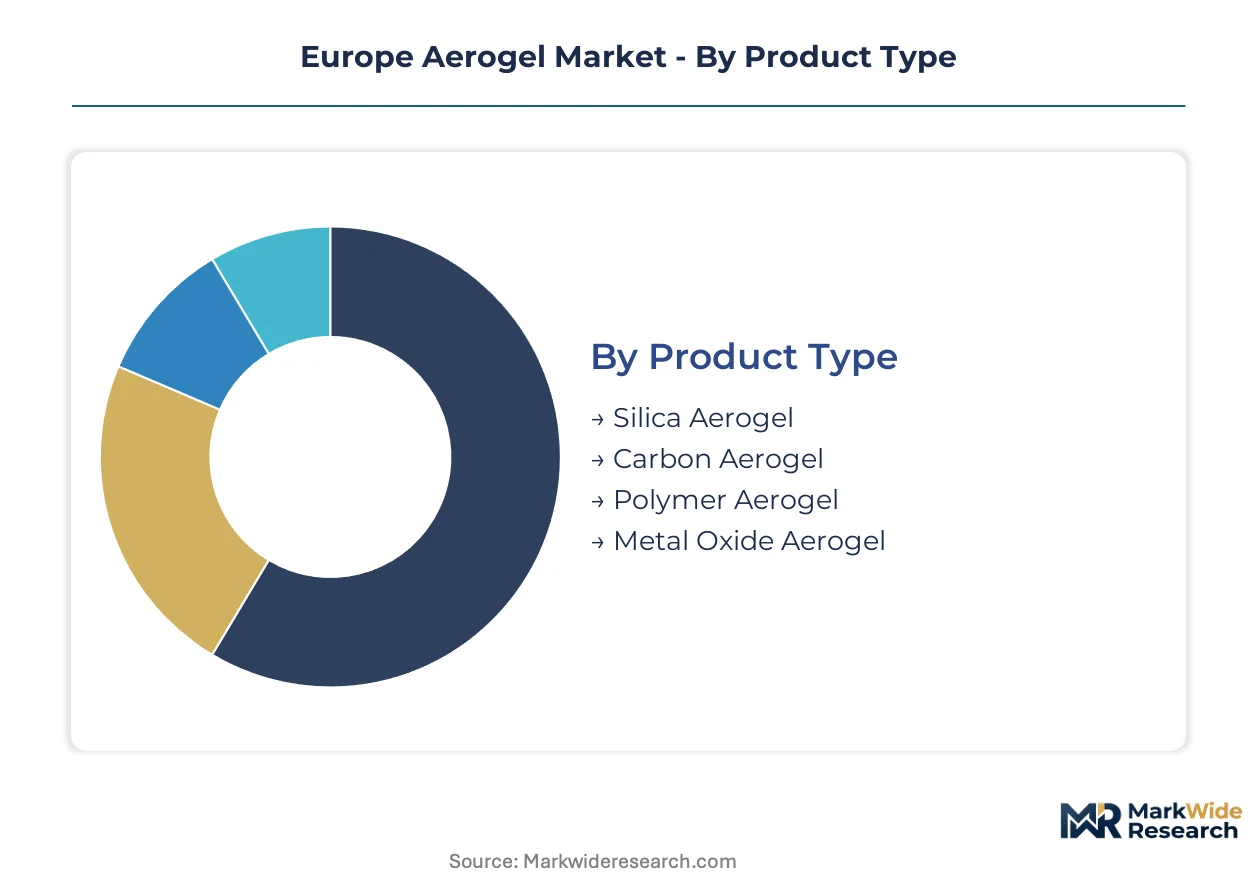
Segmentation reveals where aerogel substitutes displace incumbent materials across Europe's regulated construction and industrial markets. Product chemistry and application requirements determine specification patterns, while form factor choices reflect installation constraints in retrofit versus new-build contexts.
Product Type:
Silica formulations face intensifying substitution pressure from polymer alternatives in mechanical-flexibility applications, while carbon aerogel competes with activated carbon in electrode markets.
- Silica Aerogel:Derived from tetramethyl orthosilicate gelation followed by supercritical or ambient-pressure drying, achieving thermal conductivities of 0.012-0.020 W/m·K. German building retrofit consortia specify silica aerogel blankets for internal wall insulation under Energy Performance of Buildings Directive mandates, though mechanical brittleness requires protective encapsulation that polymer alternatives avoid.
- Polymer Aerogel:Polyimide and polyurethane variants deliver compressive resilience exceeding 10 MPa with densities below 0.150 g/cm³. BMW and Volvo engineers specify polymer aerogel for electric vehicle battery pack thermal barriers, where vibration tolerance and thin-profile installation displace mica sheets and intumescent coatings.
- Carbon Aerogel:Pyrolyzed organic aerogels with electrical conductivities of 10-100 S/m and surface areas exceeding 500 m²/g. Swedish energy storage developers test carbon aerogel electrodes for supercapacitor applications, competing with activated carbon in grid-scale buffering systems.
- Metal Oxide Aerogel:Alumina and titania formulations offering catalytic surface activity and high-temperature stability above 800°C. French chemical processors evaluate metal oxide aerogels for refinery catalyst supports, though precursor costs limit commercial scale.
Silica aerogel anchors the volume base while polymer aerogel gains share at the steepest rate.
Application:
Application concentration follows regulatory enforcement intensity, with thermal insulation procurement pulled by binding efficiency mandates while oil and gas demand softens on pipeline construction cycles.
- Thermal Insulation:Superinsulating performance in 5-10 mm profiles enables compliance with France's low-carbon renovation targets for pre-1975 residential stock. CE marking under the Construction Products Regulation fragments technical approval timelines across member states, slowing specification velocity in southern European markets.
- Oil & Gas:Subsea pipeline insulation and LNG carrier cargo containment represent mature demand centers. North Sea decommissioning schedules compress new installation volumes, redirecting supplier attention toward Middle East and African project exports.
- Aerospace:Cabin insulation and radome applications exploit polymer aerogel's acoustic damping and dielectric properties. Airbus procurement teams evaluate weight-reduction potential against qualification timelines that stretch 5-7 years for new material systems.
- Automotive:Electric vehicle thermal management specifications climb fastest, with battery pack inter-cell barriers and firewall insulation absorbing production scale. ECHA workplace exposure limits for respirable silica elevate contractor training costs, favoring encapsulated blanket formats over loose-fill alternatives.
Thermal insulation commands the revenue base while automotive applications expand most quickly.
End User:
End-user concentration reflects construction sector procurement consolidation, with energy and transportation buyers fragmenting across specialized engineering specifications.
- Construction:France's Effilogis and Germany's KfW-funded renovation aggregators negotiate frame contracts directly with manufacturers, bypassing traditional distribution. Multi-family residential retrofits standardize envelope packages that reduce engineering overhead per project.
- Energy:Power generation and grid infrastructure specifications concentrate in German industrial corridors where process equipment efficiency mandates accelerate thermal insulation upgrades. District heating network expansions in Denmark and Sweden create seasonal demand pulses for pre-insulated piping systems.
- Transportation:Automotive and aerospace procurement teams specify collaboratively, with Volvo and BMW thermal engineers driving polymer aerogel qualification programs. Rail OEMs in Spain and Italy test aerogel floor insulation for weight-critical high-speed trainsets.
- Electronics:Thermal interface materials and semiconductor packaging represent emerging demand pockets. Dutch electronics assemblers evaluate aerogel gap fillers for 5G base station thermal management, competing with phase-change materials on cost-performance.
Construction anchors installed volume while transportation specifications climb fastest.
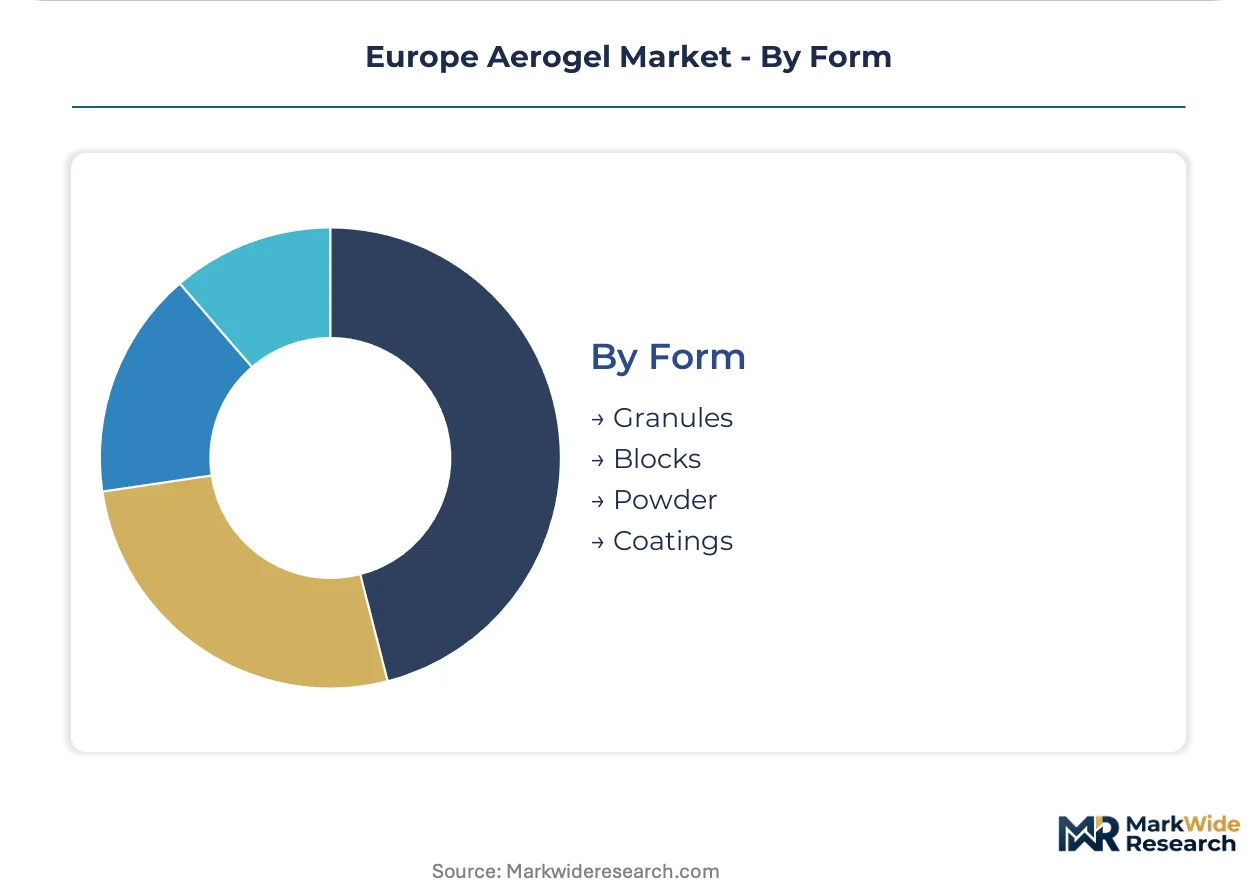
Form:
Form selection tracks installation economics, with blanket and panel formats displacing loose granular systems in labor-constrained European construction markets.
- Granules:Loose-fill cavity wall insulation and industrial tank base applications exploit pour-in-place economics. Dust exposure protocols under ECHA guidelines elevate contractor liability insurance and training costs, compressing specification share.
- Blocks:Monolithic panels for façade and roof insulation deliver R-values exceeding 10 per inch. Mechanical fragility limits maximum panel dimensions and requires protective facings that add fabrication steps.
- Powder:Additive incorporation into coatings and composites enables thin-film superinsulation. Belgian and Dutch building envelope consultants specify powder-enhanced renders for thermal bridge remediation in heritage structures.
- Coatings:Direct-deposition aerogel layers on metal substrates target industrial equipment insulation. Spray-applied formats reduce installation labor but require specialized contractor certification that fragments market access.
Granules retain legacy volume while coatings gain specification share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and F-Gas Regulation are channeling retrofit investment toward superinsulating materials across member states, with national building codes transposing the Energy Performance of Buildings Directive into binding procurement mandates.
Germany
KfW-funded renovation aggregators negotiate frame contracts directly with aerogel manufacturers, bypassing traditional distribution channels. The Federal Ministry for Economic Affairs enforces efficiency mandates on energy-intensive manufacturers in the industrial corridor. The Rhine-Ruhr metropolitan region hosts process equipment upgrades where thermal insulation specifications are accelerating.
France
Effilogis and other building retrofit consortia consolidate purchasing power for multi-family residential envelope packages. The national strategy for low-carbon renovation targets pre-1975 residential stock with binding thermal performance thresholds. The Paris metropolitan area drives specification of internal wall insulation systems in heritage structures.
Sweden
District heating network expansions create seasonal demand pulses for pre-insulated piping systems. The Swedish Energy Agency supports superinsulating material procurement through building code enforcement. Stockholm and Gothenburg anchor commercial silica aerogel production capacity serving northern European projects.
Netherlands
Building envelope consultants rewrite thermal bridge details around aerogel strips ahead of F-Gas phase-out milestones. The Ministry of the Interior mandates low-emission insulation alternatives in public construction procurement. The Randstad conurbation concentrates retrofit engineering expertise and distributor retraining programs.
Belgium
Flemish and Walloon building codes fragment technical approval timelines for CE-marked insulation products. The Federal Public Service Health enforces ECHA workplace exposure protocols for respirable silica. Antwerp and Brussels host contractor certification programs for spray-applied aerogel formats.
Europe Aerogel Market Competitive Landscape
Player mix skews toward chemical conglomerates and specialized aerogel fabricators competing on production scale and formulation expertise. Market structure concentrates around supercritical drying specialists with seven-figure capital commitments and emerging ambient-pressure entrants challenging on cost. Two strategic archetypes dominate: diversified chemical majors leveraging polymer chemistry heritage, and pure-play aerogel specialists defending thermal insulation specialization. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure precursor supply and distribution access.
Among Germany-based chemical majors, BASF SE exemplifies the diversified archetype with polymer aerogel formulation capabilities. Aspen Aerogels Inc. and Svenska Aerogel AB occupy positions as specialized fabricators, with the former representing North American thermal insulation expertise and the latter anchoring cost-efficient silica production methods developed in Sweden. These three companies represent the competitive spectrum from integrated chemical platforms to focused aerogel technology developers.
| Leading Market Players |
|---|
| BASF SE |
| Cabot Corporation |
| Aspen Aerogels Inc. |
| Svenska Aerogel AB |
| Green Earth Aerogel Technologies |
| Enersens |
| Aerogel Technologies |
| Aerogel-it GmbH |
| Armacell International S.A. |
| Others |
Supply & Pricing Matrix
Polymer aerogel's displacement of silica formulations in automotive battery pack applications simultaneously redraws supply geography toward Germany's polymer chemistry corridor and compresses pricing premiums for mechanical-flexibility grades. The shift pulls tetramethyl orthosilicate demand toward specialty chemical hubs while redirecting investment into polyimide precursor capacity near OEM engineering centers.
Pricing Analysis
Certification level under CE marking and member-state technical approvals creates the primary spread between premium and standard tiers, with France's Effilogis and Germany's KfW aggregators commanding volume discounts through frame contract structures. Pricing stratifies across certified low-carbon insulation eligible for EU Taxonomy green financing, conventional CE-marked products, and uncertified imports facing installation liability barriers. Cost compression in silica aerogel blankets intensifies as ambient-pressure drying entrants challenge supercritical-drying incumbents on capital efficiency. Residential retrofit consortia exhibit highest price sensitivity, while aerospace qualification programs absorb premium pricing for polymer formulations with minimal negotiation leverage.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for tetramethyl orthosilicate shipments from Asian petrochemical hubs, compressing margins on just-in-time precursor deliveries. Commercial silica aerogel capacity clusters in Sweden and Germany, with polymer aerogel feedstock production anchored in the Rhine-Ruhr industrial corridor. Raw material dependencies rest on organosilicon precursors, polyimide resins, and supercritical CO2 for drying infrastructure. Single-source vulnerability concentrates in supercritical drying equipment suppliers, where seven-figure capital commitments constrain capacity scaling. Distribution runs through building retrofit consortia bypassing traditional merchant channels, with direct manufacturer contracting consolidating procurement power in multi-family residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe aerogel market functions as a defensive-moat structure where regulatory entrenchment through CE marking and member-state technical approvals erects switching costs that protect incumbent positions against price-based challengers.
For Market Incumbents: Consolidate certification coverage across fragmented member-state approval timelines to preempt emerging ambient-pressure drying entrants from achieving pan-European specification eligibility. Secure backward integration into tetramethyl orthosilicate supply through long-term offtake agreements with German and Swedish petrochemical producers, insulating margin structures from upstream volatility. The priority defensive lever centers on channel control through direct frame contracts with France's Effilogis and Germany's KfW renovation aggregators, locking out mid-scale competitors from volume procurement pathways. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Belgium and the Netherlands offers the most penetrable regulatory pathway for southern European market access. Target Spain and Italy's rail OEM thermal insulation specifications, where polymer aerogel qualification programs remain underdeveloped and engineering relationships are less entrenched than automotive battery pack applications. The optimal go-to-market angle deploys spray-applied coating formats requiring specialized contractor certification, creating service-layer differentiation against incumbent blanket suppliers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed polymer chemistry platforms seeking aerogel technology bolt-ons to complete insulation portfolio coverage. Long-term viability over the coming decade hinges on EU Taxonomy alignment and F-Gas Regulation enforcement intensity sustaining specification pull for lower-emission alternatives. The acquisition target archetype encompasses ambient-pressure drying specialists with scalable production economics and pending CE marking approvals. The critical inflection signal to monitor is revision cycles of the EU Taxonomy for sustainable activities, which determine green financing eligibility flows toward certified insulation systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive tetramethyl orthosilicate access insulates BASF and Svenska Aerogel from petrochemical price cycles. |
| CE Marking Expansion Across Member States | Pan-European technical approval unlocks specification eligibility in France's low-carbon renovation wave. |
| Polymer Aerogel Capacity Buildout | Polyimide formulation scale-up serves BMW and Volvo battery pack thermal barrier procurement. |
| Direct Frame Contracting with Retrofit Consortia | Bypassing merchant distribution captures margin from Germany's KfW-funded renovation aggregators. |
| Ambient Pressure Drying Technology Licensing | Capital-efficient production routes challenge supercritical-drying incumbents on mid-market project economics. |
Research Methodology
A standing panel of building retrofit consortium procurement directors, chemical plant managers at precursor facilities, automotive thermal engineers at European OEMs, and building envelope consultants provided ongoing calibration across the research cycle. Primary interviews with these stakeholders combined with secondary validation against ECHA regulatory filings, EU Construction Products Regulation technical documentation, customs trade data for organosilicon imports, and SEC disclosures from listed aerogel specialists. Bottom-up project pipeline tracking across France's Effilogis and Germany's KfW programs triangulated against top-down macroeconomic scenario modeling.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product chemistry, application requirements, end-user procurement consolidation, and form factor installation economics. CAGRs derived from installed base penetration curves and substitution elasticity estimates for conventional insulation materials. Industry-specific forecast inputs incorporated F-Gas Regulation phasedown schedules and Energy Performance of Buildings Directive transposition timelines across member states.
Underlying assumptions cover regulatory enforcement continuity, precursor supply stability, and certification pathway timelines, with deviation risk concentrated in EU Taxonomy revision cycles and ECHA workplace exposure limit modifications. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Europe Advanced Building Materials Market
Advanced Materials
Natural Single Crystal Diamond Market
Advanced Materials
Solar Encapsulation Materials Market
Advanced Materials
Curable Materials Market
Advanced Materials
North America Plasma Powder Market
Advanced Materials
2D Materials Market
Advanced Materials
Europe Blanket Aerogel Market
Advanced Materials
Transparent Wood Market
Advanced Materials
Global Core Materials Market
Advanced Materials
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market
Advanced Materials
Anisotropic Conductive Films (ACF) Market
Advanced Materials
Advanced Nanomaterials Market
Advanced Materials
High-Purity Amorphous Boron Market
Advanced Materials
Extracellular Matrix Proteins Market
Advanced Materials
Global Graphene Market
Advanced Materials
Thermal Conductive Material Market