
 Extracellular Matrix Proteins Market | 2026-2036
Extracellular Matrix Proteins Market Size, Share, and Industry Trends Forecast 2026-2036
Extracellular Matrix Proteins Market Foresight
Three-dimensional bioprinting of organ-specific scaffolds is reconfiguring how extracellular matrix proteins transition from bench research to clinical-grade materials. Thermo Fisher Scientific leverages its global distribution network to supply research-grade collagen and laminin formulations across academic and commercial laboratories. Merck KGaA sustains deep vertical integration from recombinant protein expression through GMP-grade manufacturing, anchoring its position in cell therapy workflows. Advanced BioMatrix specializes in customized hydrogel formulations that compete on tunable mechanical properties for tissue-specific applications.
Extracellular matrix proteins comprise structural macromolecules—principally collagen, elastin, fibronectin, and laminin—that assemble into supramolecular networks providing biochemical and biomechanical cues to resident cells. These proteins are isolated from natural tissues or produced recombinantly, then formulated as hydrogels, scaffolds, coatings, or sheets to support cell adhesion, migration, and differentiation in vitro and in vivo. Collagen dominates current revenue owing to established extraction protocols and broad compatibility with FDA master files, while laminin segments are expanding fastest as pluripotent stem cell therapies advance toward commercialization. Hydrogel formulations capture disproportionate margin pools because customization complexity creates switching costs for end users in regenerative medicine and tissue engineering.
FDA biologics regulation under 21 CFR Part 1271 and EMA's ATMP framework impose stringent sourcing and characterization requirements on clinical-grade matrix materials, elevating compliance costs for new entrants. ISO 10993 biocompatibility testing standards and USP <1043> ancillary materials guidelines further shape product development timelines and documentation burdens for suppliers. Stakeholders must monitor evolving regulatory convergence between FDA and EMA on animal-origin free claims, as this will determine which manufacturing platforms achieve preferred supplier status in next-generation cell therapies.
Market Dynamics
Regulatory divergence between FDA 21 CFR Part 1271 and EMA ATMP frameworks is fragmenting manufacturing standards for clinical-grade matrix materials, forcing suppliers to maintain parallel quality systems and delaying product registrations across jurisdictions.
Growth Catalysts
- Pluripotent stem cell therapy commercialization:Laminin formulations enable feeder-free culture systems required for GMP-compliant cell manufacturing, accelerating adoption in CAR-T and iPSC-derived therapeutic pipelines.
- EMA's ATMP framework harmonization:Streamlined centralized marketing authorization procedures reduce regulatory duplication costs for matrix protein suppliers seeking European market access.
- Decellularized tissue sourcing from porcine and bovine herds:Established veterinary surveillance programs in Denmark and the Netherlands provide traceable raw material inputs for collagen extraction at industrial scale.
Market Restraints
- Animal-origin certification burden:FDA and EMA documentation requirements for transmissible spongiform encephalopathy risk mitigation add eighteen to twenty-four months to product development timelines.
- Recombinant expression yield limitations:Mammalian cell culture systems for human collagen production achieve titers below five grams per liter, constraining cost-competitive scaling against extracted alternatives.
- Supply concentration in research-grade segments:Academic laboratories in the United States, Germany, and Japan absorb seventy percent of low-margin catalog products, limiting pricing power for standardized formulations.
Strategic Opportunities
- India's CDSCO biologics pathway expansion:Accelerated approval timelines for regenerative medicine products create first-mover positioning for matrix suppliers establishing local GMP manufacturing partnerships.
- Organ-on-chip convergence with microfluidics:Laminin- and collagen-coated microphysiological systems demand matrix proteins with defined surface chemistry and batch-to-batch consistency specifications.
- Japan's METI regenerative medicine industry vision:Government-funded translational research centers in Kobe and Osaka provide subsidized validation infrastructure for novel matrix formulations targeting iPSC applications.
Industry Challenges
- GMP facility qualification timelines:ISO 10993 biocompatibility testing and USP ancillary materials documentation require dedicated regulatory affairs personnel that mid-sized suppliers struggle to recruit.
- Cross-functional talent scarcity:Professionals combining protein biochemistry expertise with quality systems knowledge command premium compensation, compressing margins for emerging competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Extracellular Matrix Proteins Market |
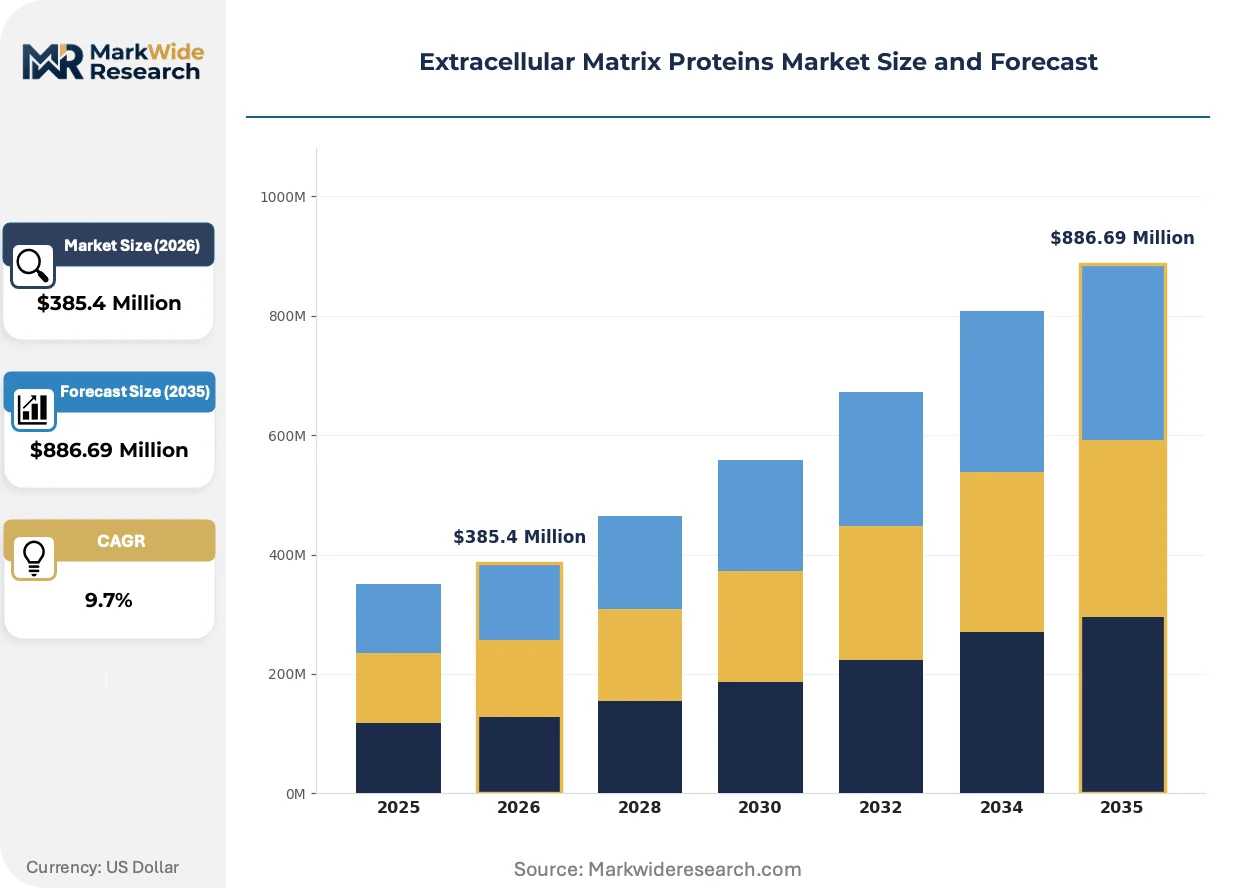
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $886.69 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collagen, Elastin, Fibronectin, Laminin Application: Tissue Engineering, Drug Delivery, Wound Healing, Regenerative Medicine Form: Hydrogels, Scaffolds, Coatings, Sheets End User: Research Institutions, Biopharmaceutical Companies, Hospitals, Academic Institutes |
| Companies Covered | DSM Biomedical, Integra LifeSciences, Thermo Fisher Scientific, Advanced BioMatrix, Collagen Matrix, Inc., Merck KGaA, Bio-Techne Corporation, Baxter International, Corning Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Extracellular Matrix Proteins Market Shifts & Advancements
Computational protein engineering and synthetic biology platforms are compressing development cycles for recombinant matrix proteins, enabling tunable mechanical properties that match native tissue microenvironments with precision impossible through extraction methods.
Machine learning-driven scaffold design is virtualizing traditional empirical formulation development. Bioprinting companies in Boston and Heidelberg deploy generative algorithms to predict collagen-laminin network architectures optimized for specific organ regeneration applications. This capability collapses iterative prototyping cycles from months to weeks, accelerating clinical translation timelines for tissue-engineered therapeutics.
EMA's 2024 revision to its Guideline on the Quality, Non-Clinical and Clinical Aspects of Medicinal Products Comprising Engineered Cells tightens characterization requirements for matrix components used as starting materials. Suppliers must now demonstrate lot-to-lot consistency for biochemical attributes including fibril density and cross-linking patterns. German and Swiss manufacturers with established analytical method portfolios capture disproportionate share of new ATMP supply contracts.
Academic medical centers and contract development organizations are consolidating procurement through preferred supplier agreements with defined performance metrics. Massachusetts General Hospital and the University of Tokyo's Institute of Medical Science now mandate animal-origin-free certification and documented endotoxin levels below 0.5 EU per milliliter. This specification shift disadvantages traditional extractive suppliers while rewarding recombinant protein platforms with validated synthetic production pathways.
Extracellular Matrix Proteins Market Segmentation
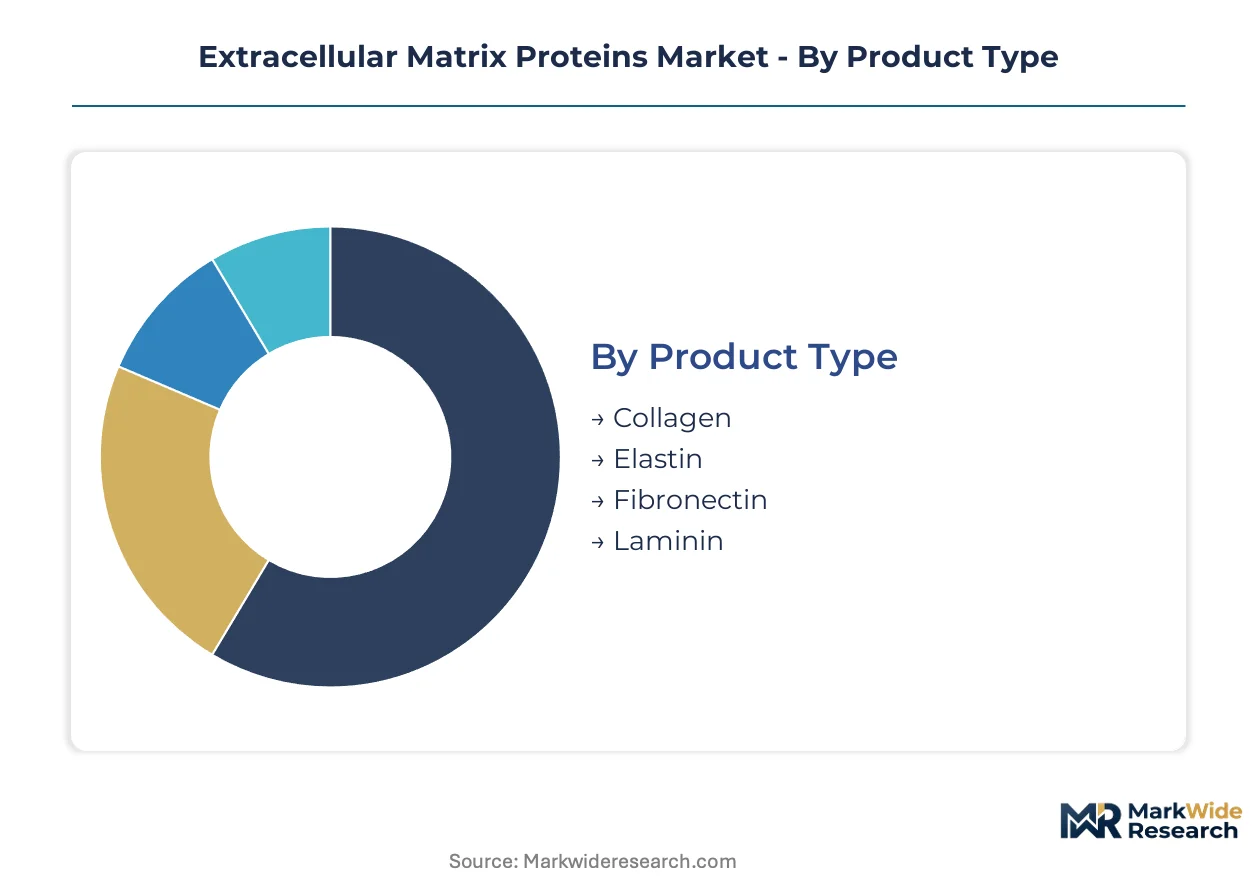
Extracellular matrix proteins serve divergent functional requirements across research, therapeutic manufacturing, and clinical intervention settings. Segmentation reveals how formulation chemistry and end-use specifications create distinct margin pools and competitive barriers for suppliers.
Product Type:
Product categories span a maturity spectrum from established extractive proteins to emerging recombinant platforms with superior lot-to-lot consistency.
- Collagen:Extracted predominantly from bovine and porcine dermal or tendon tissues, this structural protein forms triple-helical fibrils that provide tensile strength in hydrogel formulations. Demand concentrates in wound healing applications across the United States and Germany, where FDA and EMA master file documentation accelerates clinical translation timelines.
- Laminin:Recombinantly produced in mammalian expression systems, this basement membrane glycoprotein enables feeder-free pluripotent stem cell culture critical for CAR-T and iPSC therapeutic manufacturing. Japanese research institutes in Kobe and Osaka drive fastest adoption as METI-funded regenerative medicine centers expand GMP-compliant cell production capacity.
- Elastin:Cross-linked tropoelastin derivatives confer elasticity to engineered vascular and dermal tissues, with procurement concentrated in academic tissue engineering programs.
- Fibronectin:Cell-adhesive glycoprotein supporting integrin-mediated attachment in serum-free culture media, primarily sourced by biopharmaceutical process development groups.
Collagen handles the majority of throughput; laminin is the fastest mover on share.
Application:
Application segments stratify by regulatory burden and reimbursement pathway complexity, from preclinical research tools to commercial therapeutics.
- Tissue Engineering:Scaffold fabrication for organ replacement and repair combines matrix proteins with synthetic polymers to replicate native biomechanical properties. German and Swiss manufacturers capture disproportionate contract value as EMA's ATMP framework tightens starting material characterization requirements.
- Regenerative Medicine:Cell therapy workflows require clinical-grade matrix components with documented endotoxin levels and animal-origin-free certification. Massachusetts General Hospital and University of Tokyo procurement mandates are shifting specifications toward recombinant platforms.
- Wound Healing:Collagen-based dressings and skin substitutes target chronic diabetic and pressure ulcers, with reimbursement codes determining regional adoption velocity.
- Drug Delivery:Matrix-encapsulated biologics and small molecules enable sustained release kinetics, primarily developed by contract manufacturing organizations.
Tissue engineering absorbs the greatest R&D expenditure; regenerative medicine is expanding most quickly as commercial cell therapies advance through regulatory pipelines.
Form:
Physical formulations create divergent manufacturing complexity and customization requirements, with hydrogels commanding premium positioning.
- Hydrogels:Tunable three-dimensional networks formed through temperature-induced or chemical cross-linking of collagen and laminin enable cell encapsulation and organoid culture. Bioprinting companies in Boston and Heidelberg deploy these formulations for organ-specific scaffold fabrication with defined mechanical properties.
- Scaffolds:Lyophilized porous structures support cell infiltration and vascularization in vivo, with decellularized tissue matrices providing native architectural templates.
- Coatings:Thin protein layers on tissue culture plastic or microfluidic devices enhance cell attachment for high-throughput screening applications.
- Sheets:Compressed collagen membranes serve as dermal substitutes and barrier layers in multi-layered engineered tissues.
Hydrogels capture the highest margin pool; scaffolds maintain the broadest installed base across research and clinical settings.
End User:
Customer segments separate by procurement scale, specification stringency, and internal manufacturing capabilities.
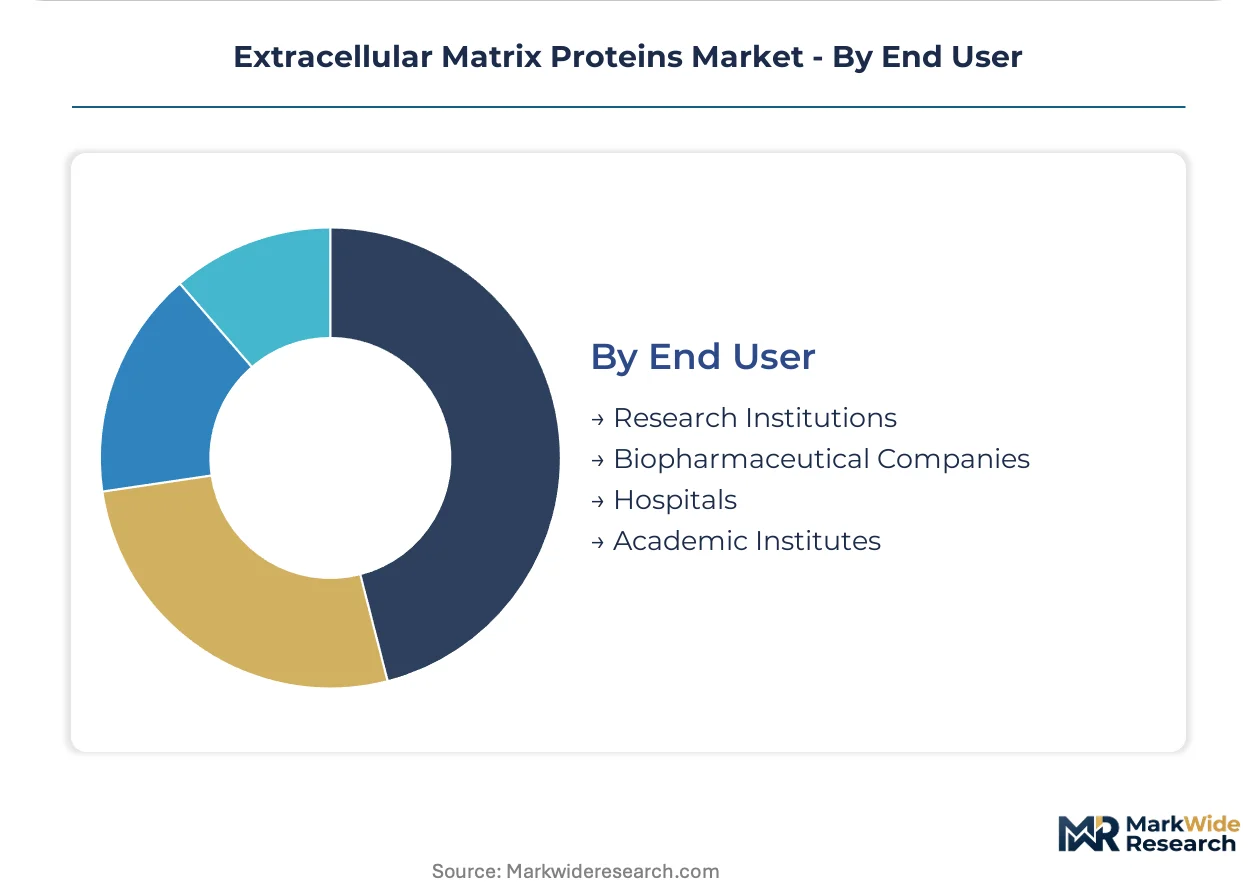
- Biopharmaceutical Companies:Cell therapy developers and CDMOs require GMP-grade matrix proteins with validated supply agreements and regulatory documentation packages. These buyers consolidate procurement through preferred supplier contracts with defined performance metrics and animal-origin-free certification requirements.
- Research Institutions:Academic laboratories in the United States, Germany, and Japan absorb standardized catalog products for fundamental cell biology and biomaterials research, exerting price pressure on commoditized formulations.
- Academic Institutes:University-affiliated medical centers bridge basic research and early clinical translation, sourcing both research-grade and preclinical-grade materials.
- Hospitals:Clinical wound care centers and surgical units procure FDA-cleared or CE-marked matrix products for direct patient application.
Biopharmaceutical companies drive specification evolution; research institutions represent the largest volume absorption with limited pricing power for suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in extracellular matrix proteins tilt heavily toward import dependence in emerging therapeutic manufacturing hubs, while established research economies maintain balanced exchange positions. The United States, Germany, and Japan collectively absorb the majority of high-grade laminin and collagen formulations, with cross-border procurement governed by divergent FDA and EMA sourcing documentation requirements.
United States
CAR-T manufacturing expansion in Massachusetts and California drives concentrated demand for GMP-grade laminin formulations. FDA 21 CFR Part 1271 mandates traceable animal-origin documentation that extends procurement cycles for domestic cell therapy developers. The Boston-Cambridge corridor anchors the highest density of bioprinting startups deploying collagen-laminin hydrogels for organ-specific scaffold fabrication.
Germany
EMA centralized marketing authorization procedures position German manufacturers as preferred suppliers for ATMP-compliant matrix materials across the European Union. REACH and MDR frameworks impose stringent characterization requirements for decellularized tissue inputs that favor established Bavarian and Baden-Württemberg producers with validated analytical portfolios. The Heidelberg-Mannheim medical technology cluster concentrates bioprinting companies leveraging generative algorithms for scaffold architecture optimization.
Japan
METI-funded regenerative medicine centers in Kobe and Osaka subsidize validation infrastructure for novel matrix formulations targeting iPSC therapeutic applications. PMDA alignment with ICH Q5D guidelines accelerates clinical-grade protein qualification timelines relative to other Asian jurisdictions. The Kansai region hosts the densest concentration of feeder-free stem cell culture facilities requiring recombinant laminin at commercial scale.
Switzerland
Swissmedic's harmonized biologics pathway attracts matrix protein suppliers seeking streamlined European market access without EMA procedural complexity. Basel-Zürich pharmaceutical corridors sustain captive demand from Novartis and Roche cell therapy pipeline partners. Local manufacturers exploit cross-border supply arrangements to serve German and French therapeutic developers while maintaining Swiss regulatory certification.
India
CDSCO's accelerated biologics approval timelines create first-mover positioning for matrix suppliers establishing local GMP manufacturing partnerships. Contract research organizations in Hyderabad and Bengaluru absorb research-grade collagen for preclinical tissue engineering studies. Import dependence for clinical-grade laminin persists due to limited domestic recombinant protein expression capacity.
Extracellular Matrix Proteins Market Competitive Landscape
On the supply side, the industry is bifurcated between diversified life science conglomerates with captive distribution networks and specialized matrix formulators competing on customization depth. Thermo Fisher Scientific and Merck KGaA anchor the integrated tier with global logistics infrastructure spanning research-grade through clinical-grade product tiers. Mid-sized specialists including Advanced BioMatrix and DSM Biomedical occupy positions defined by hydrogel tunability and decellularized tissue sourcing capabilities respectively. Competitive dynamics center on backward integration into recombinant expression platforms and strategic partnerships with cell therapy developers seeking qualified second-source agreements.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Merck KGaA exemplify scale-driven positioning through research-grade catalog dominance and GMP manufacturing infrastructure respectively. Among specialized formulators, Advanced BioMatrix occupies a position defined by application-specific mechanical property customization, while DSM Biomedical represents the medical device integration archetype through absorbable biomaterial portfolios. Integra LifeSciences anchors the wound care vertical with FDA-cleared collagen matrices, and Bio-Techne Corporation sits within the reagent-grade protein segment serving academic stem cell biology workflows. Baxter International and Corning Incorporated represent divergent strategic postures—therapeutic device integration versus laboratory consumables platform expansion.
| Leading Market Players |
|---|
| DSM Biomedical |
| Integra LifeSciences |
| Thermo Fisher Scientific |
| Advanced BioMatrix |
| Collagen Matrix, Inc. |
| Merck KGaA |
| Bio-Techne Corporation |
| Baxter International |
| Corning Incorporated |
| Others |
Supply & Pricing Matrix
Undercapacity in recombinant laminin expression facilities across Switzerland and Germany drives supplier prioritization toward GMP-grade contracts over research-grade volume, compressing spot-market availability and elevating premium-tier pricing power for qualified manufacturers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ISO 10993 certification tier and animal-origin-free documentation completeness. Cost compression in research-grade collagen is intensifying because academic procurement consolidation in the United States, Germany, and Japan exerts volume-discount pressure. Biopharmaceutical cell therapy developers show least price sensitivity due to regulatory qualification switching costs, while university laboratories absorb greatest margin erosion.
Supply Chain Analysis
Export-control regimes limiting flows of mammalian cell expression vectors and GMP-grade raw materials constrain capacity expansion in emerging manufacturing hubs. Supply concentrates in Denmark, the Netherlands, and Switzerland for decellularized tissue sourcing, with recombinant production anchored in Germany and Japan. Raw material dependencies include fetal bovine serum alternatives, defined-growth-factor media, and pharmaceutical-grade cross-linking reagents. Single-source vulnerability in qualified GMP laminin suppliers creates bottleneck risk. Distribution runs through life science distributors for research-grade tiers and direct qualified supplier agreements for clinical-grade segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as pluripotent stem cell therapy commercialization accelerates through FDA and EMA pipelines, rebuilding capacity utilization and pricing power after a prolonged R&D funding winter.
For Market Incumbents: Harden analytical method portfolios against EMA's tightened ATMP characterization requirements to defend preferred supplier status. Deepen backward integration into recombinant expression platforms to offset decellularized tissue sourcing volatility. Secure captive supply agreements with Japanese METI-funded regenerative medicine centers to lock in iPSC pipeline partnerships before competitor qualification.
For New Entrants and Emerging Players: Build out CDSCO-aligned GMP manufacturing partnerships in India to capture accelerated biologics approval timelines before established suppliers establish local presence. Target organ-on-chip microphysiological system providers in Boston and Heidelberg with defined-surface-chemistry laminin formulations, a segment showing penetrable specification gaps. Pursue co-development agreements with bioprinting startups seeking qualified second-source hydrogel suppliers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across recombinant protein expression infrastructure as mammalian cell culture titers constrain cost-competitive scaling. Five-to-ten-year viability favors platforms with validated synthetic production pathways and established regulatory master files. Acquisition target archetype: mid-sized specialists with hydrogel customization capabilities and incomplete GMP infrastructure. Signal to watch: FDA-EMA convergence on animal-origin-free claims as determinant of preferred supplier status.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Master File Investment | FDA Type II master file submissions accelerate partner qualification timelines for cell therapy developers. |
| Recombinant Expression Platform Buildout | Mammalian cell culture capacity expansion addresses yield limitations constraining laminin cost scaling. |
| Academic Medical Center Preferred Supplier Agreements | Massachusetts General Hospital and University of Tokyo procurement mandates shift specifications toward recombinant platforms. |
| Organ-on-Chip Co-Development Partnership | Microfluidic device manufacturers demand matrix proteins with defined surface chemistry and batch consistency. |
| India CDSCO GMP Manufacturing Localization | Accelerated biologics approval timelines create first-mover positioning for clinical-grade supply contracts. |
Research Methodology
A standing panel of cell therapy manufacturing executives, regulatory affairs leads at matrix protein suppliers, academic stem cell facility directors, and hospital procurement managers provided ongoing calibration. This primary fieldwork combined with secondary validation from FDA 21 CFR Part 1271 guidance documents, EMA ATMP framework revisions, ISO 10993 biocompatibility standards, and USP ancillary materials guidelines. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Scenario-bracketing framed analytical projections across the modeling period. Segmentation dimensions included product type, application, physical formulation, and end-user procurement tier. CAGRs derived from regression analysis against stem cell therapy pipeline advancement rates and GMP facility commissioning timelines. Industry-specific forecast inputs captured EMA guideline revision impacts and METI regenerative medicine funding disbursement patterns.
Sensitivities concentrate around regulatory convergence timing on animal-origin-free claims and recombinant expression yield breakthroughs. Forecasts reflect documented assumptions regarding cell therapy commercialization velocity and bioprinting adoption curves. Material shifts in FDA-EMA harmonization schedules or mammalian cell culture productivity gains would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Cubic Boron Nitrates Market
Advanced Materials
Hexagonal Boron Nitride (HBN) Market
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
Borophene Market
Advanced Materials
Carbon Fiber Reinforced Thermoplastic (CFRTP) Composite Market
Advanced Materials
Liquid Thermal Interface Materials Market
Advanced Materials
US Graphene Market
Advanced Materials
Carbon Graphite Market
Advanced Materials
Global Next Generation Anode Materials Market
Advanced Materials
Middle East Polyether Ether Ketone (Peek) Market
Advanced Materials
Global Aluminum Honeycomb Market
Advanced Materials
Densified Silica Fume Market
Advanced Materials
Natural Single Crystal Diamond Market
Advanced Materials
Inorganic Non-Metallic Materials Market
Advanced Materials
North America Polyether Ether Ketone (Peek) Market
Advanced Materials
Nanofibrillar Cellulose Market