
 Europe MDI-Based PU Technical Insulation Market | 2026-2036
Europe MDI-Based PU Technical Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe MDI-Based PU Technical Insulation Market Intelligence
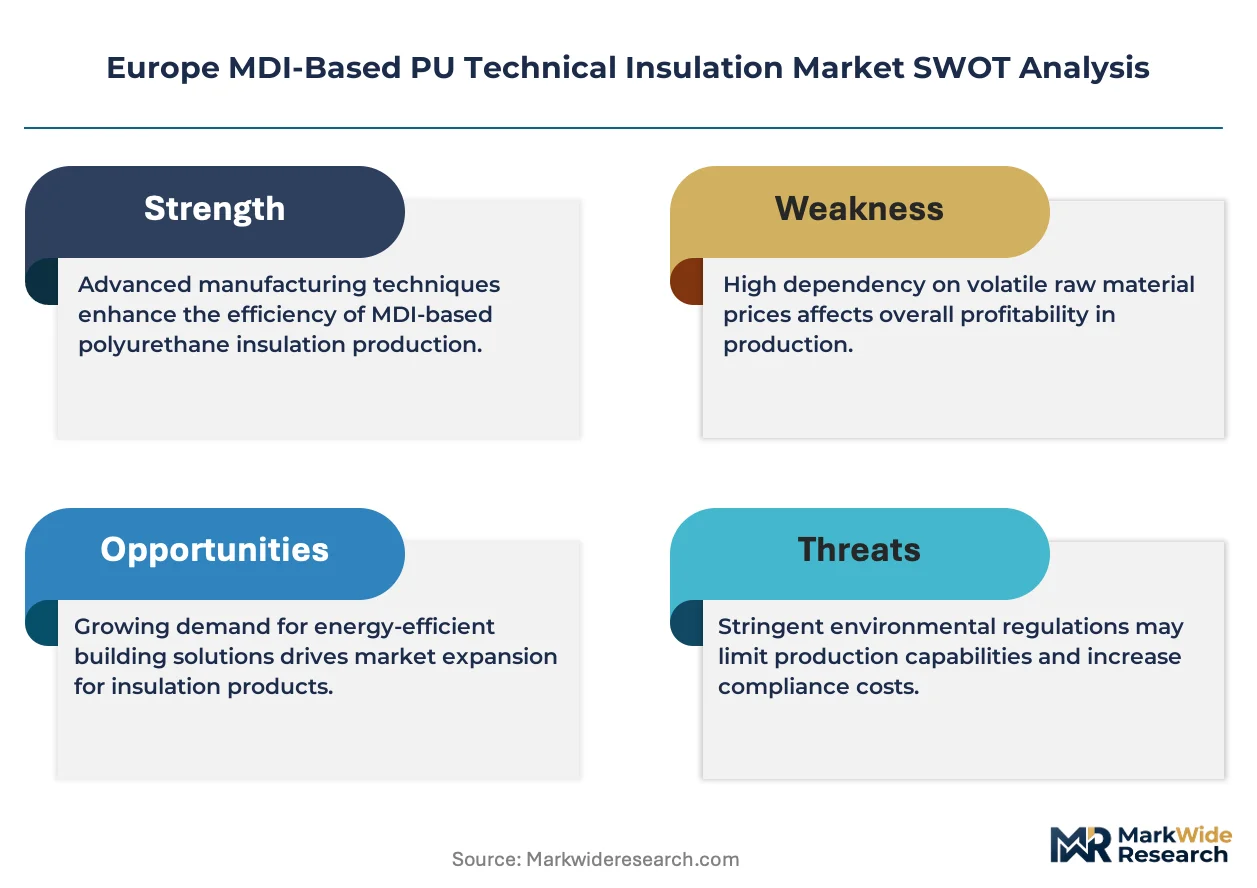
Mineral wool is hardening its cost position against MDI-based polyurethane in mid-temperature HVAC applications across Southern Europe. Huntsman International LLC leverages its upstream MDI manufacturing network to secure feedstock continuity for technical insulation grades. Covestro AG anchors its European position through rigid foam specialization for industrial pipe and equipment applications. BASF SE differentiates via integrated polyol-MDI systems tailored to construction and refrigeration end users.
Europe MDI-based PU technical insulation comprises rigid and flexible polyurethane foam systems formulated with methylene diphenyl diisocyanate, typically achieving closed-cell densities of 35–50 kg/m³ and thermal conductivity values near 0.022 W/m·K, engineered to reduce energy transfer in industrial equipment, building envelopes, and cold chain infrastructure. Pipe insulation leads application value capture due to concentrated demand from oil and gas retrofit programs and district heating network expansions across Scandinavia and Central Europe. Roof insulation competes aggressively in commercial construction, where fast-cure spray polyurethane foam systems reduce labor hours and weather dependency during installation cycles.
The EU F-Gas Regulation and ECHA REACH framework jointly constrain blowing agent selection and chemical substance authorization, compelling reformulation investments and tightening market access for non-compliant imports. CE marking under the Construction Products Regulation mandates declared thermal performance and fire reaction classifications, creating compliance thresholds that favor established European manufacturers with testing infrastructure. Stakeholders must monitor the interplay between Ecodesign requirements for building energy performance and evolving EN standards for reaction-to-fire behavior, as these will determine which foam formulations retain specification eligibility in public and commercial tenders.
Market Dynamics
The EU F-Gas Regulation is compressing formulation windows for MDI-based polyurethane technical insulation, forcing converters to retire hydrofluorocarbon blowing agents ahead of phase-down deadlines while racing to qualify low-GWP alternatives.
Growth Catalysts
- Cold chain infrastructure:Refrigerated warehouse expansions across Germany and France are pulling rigid foam volumes for temperature-controlled storage envelopes. Logistics operators specify high-performance thermal barriers to meet energy efficiency mandates.
- REACH framework compliance:Chemical substance authorization requirements under ECHA are filtering out non-compliant imports, tightening specification eligibility for established European manufacturers with testing infrastructure.
- LNG terminal construction:Industrial pipe insulation demand concentrates in Germany's chemical processing corridor and Scandinavian district heating networks, where cryogenic and high-temperature applications require specialized MDI formulations.
Market Restraints
- MDI feedstock concentration:European supply hinges on a narrow base of upstream isocyanate producers, exposing converters to allocation risk during planned maintenance or force majeure events.
- Mineral wool substitution:Stone wool and glass wool producers are hardening cost positions in mid-temperature HVAC segments across Southern Europe, compressing polyurethane's addressable market in commercial building envelopes.
- CE marking complexity:Construction Products Regulation mandates for declared thermal performance and fire reaction classifications extend certification timelines, delaying market access for reformulated low-GWP systems.
Strategic Opportunities
- Eastern European industrialization:Poland and Czechia are expanding manufacturing footprints, creating demand for equipment insulation in automotive and electronics production facilities.
- Refrigerant transition alignment:The EU Green Deal's building renovation wave is accelerating retrofit specifications that pair low-GWP blowing agents with high-performance thermal barriers in existing commercial stock.
- Spray polyurethane foam systems:Fast-cure application technology is reducing weather dependency and labor hours in commercial roofing, opening specification pathways in Nordic climates with compressed construction seasons.
Industry Challenges
- Formulation chemistry expertise:The shift from HFC to hydrofluoroolefin and hydrocarbon blowing agents demands specialized knowledge in nucleation, cell structure control, and dimensional stability that existing technical workforces lack.
- Reaction-to-fire testing backlog:EN standard updates for fire behavior classification are creating queue congestion at notified bodies, delaying product launches and tender participation for reformulated systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe MDI-Based PU Technical Insulation Market |
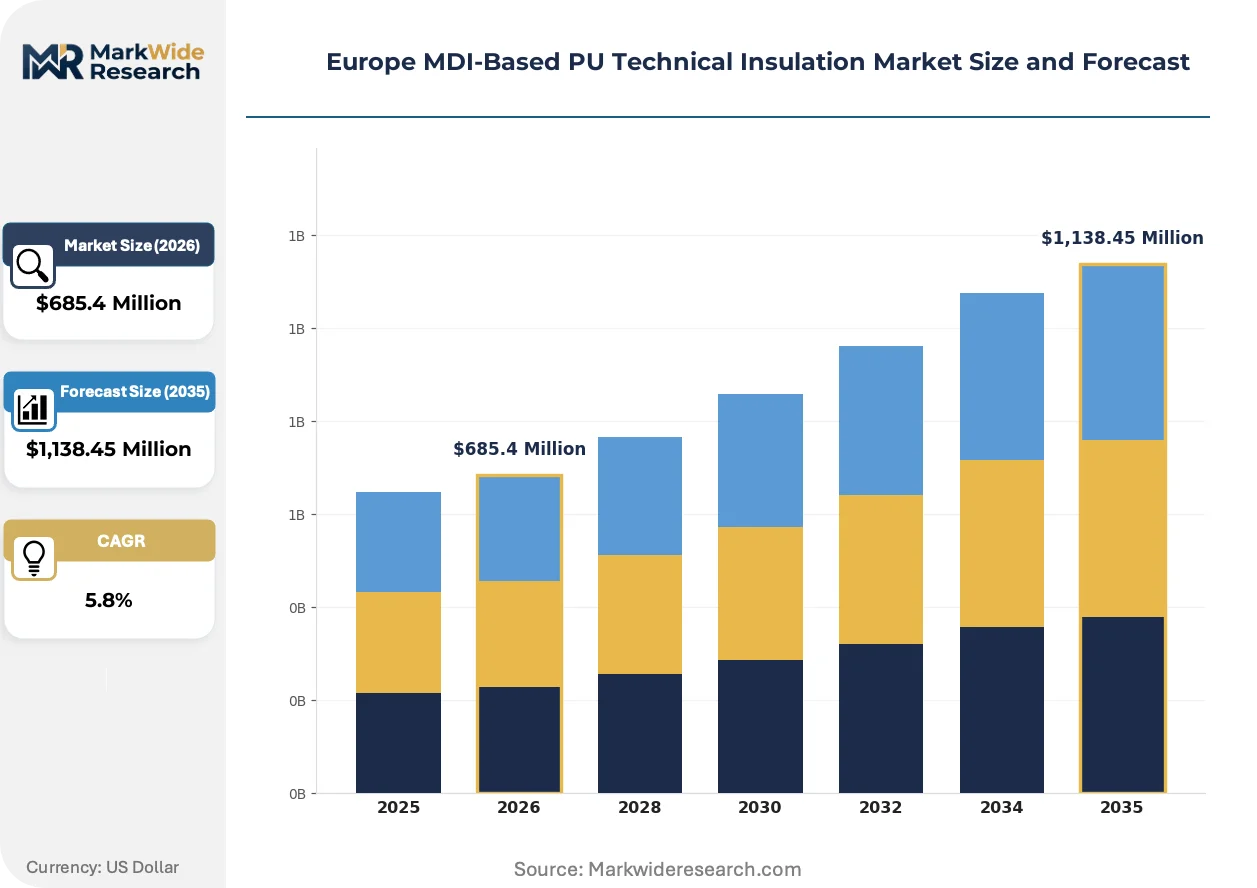
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Foam, Flexible Foam, Coatings, Adhesives End User: Construction, Automotive, Refrigeration, HVAC Application: Wall Insulation, Roof Insulation, Pipe Insulation, Floor Insulation Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Rockwool Insulation A/S, Owens Corning, Huntsman International LLC, Compagnie de Saint-Gobain S.A., Knauf Insulation, Kingspan Group, Recticel Group, Covestro AG, BASF SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe MDI-Based PU Technical Insulation Market Strategic Shifts & Innovations
Formulation chemistry and application technology are converging to address the tension between thermal performance targets and regulatory constraints on blowing agent selection. Three developments are reshaping competitive positioning.
Water-blown and hydrocarbon-blown rigid foam systems are consolidating technical specification share in industrial pipe and equipment applications. Oil and gas retrofit programs across Scandinavia specify these formulations for their compatibility with existing installation protocols and reduced GWP profiles. The consolidation is compressing demand for legacy HFC-based systems ahead of regulatory deadlines.
CE marking requirements under the Construction Products Regulation are tightening fire reaction classification thresholds for building envelope applications. Manufacturers must retest reformulated low-GWP systems against updated EN standards to maintain specification eligibility. The Nordic and German markets are responding fastest, with public tenders already requiring declared performance data for reaction-to-fire behavior.
Buyer specification patterns are rotating toward bundled thermal-performance guarantees. District heating operators in Denmark and Sweden now contract for energy-loss outcomes rather than material volumes, forcing insulation contractors to assume performance risk. This shift is compressing margins for distributors while rewarding manufacturers with in-house engineering capabilities and long-term warranty infrastructure.
Europe MDI-Based PU Technical Insulation Market Segmentation
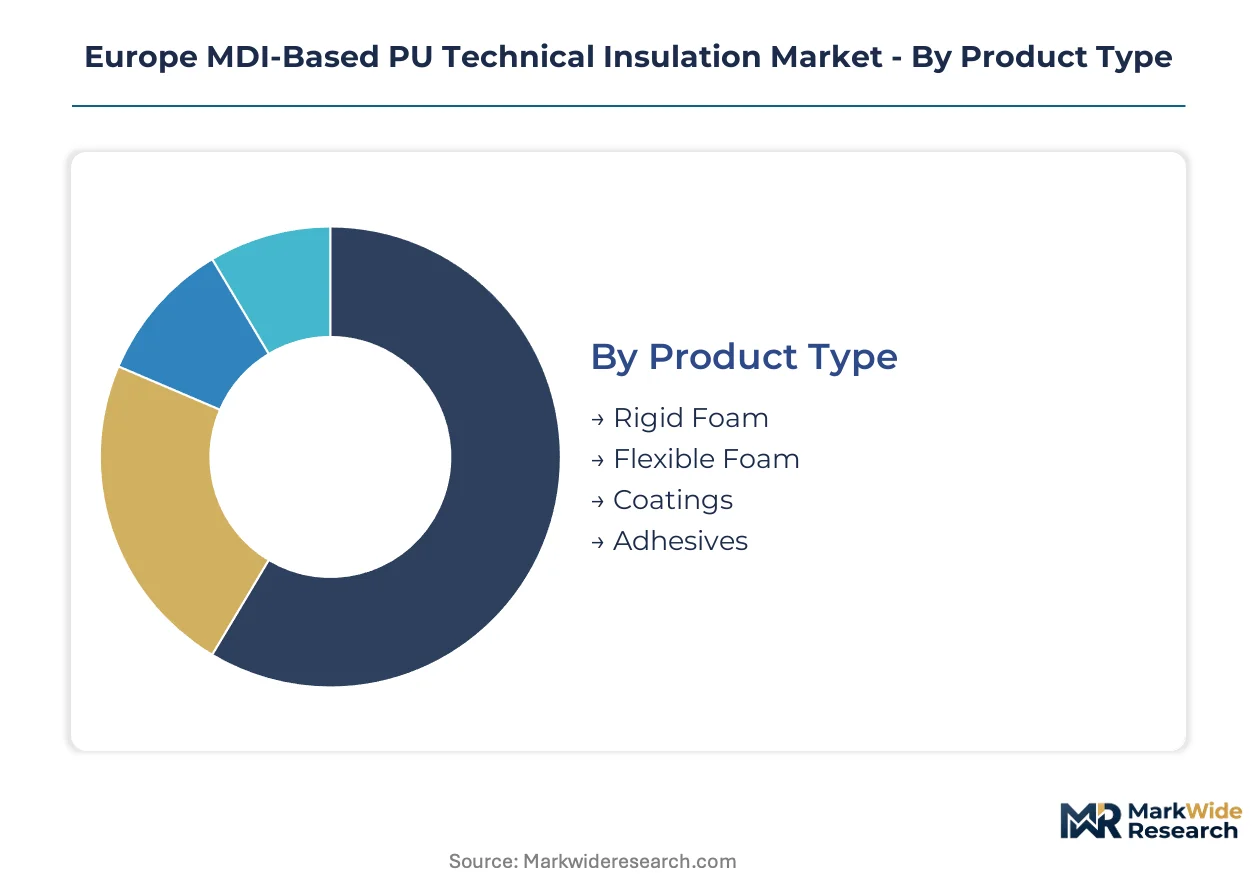
Segmentation reveals how capital deployment, regulatory exposure, and technical requirements vary across product forms and end-use environments. Understanding these fault lines helps suppliers align formulation investments with specification pathways that resist substitution.
Product Type:
Capital intensity escalates sharply with density and cell-structure control requirements, separating commodity converters from specialized systems houses.
- Rigid Foam:Closed-cell systems achieving 35–50 kg/m³ density dominate industrial pipe and equipment specifications across Germany's chemical corridor. LNG terminal construction and cryogenic transport infrastructure pull volumes requiring dimensional stability under thermal cycling.
- Flexible Foam:Open-cell formulations with lower compressive strength serve vibration-dampening and gap-filling applications in automotive assembly. Czechia and Poland's expanding electronics manufacturing footprints are generating specification demand for conformable insulation layers.
- Coatings:Spray-applied barrier systems protect substrates in aggressive chemical environments. Scandinavian offshore platforms specify these for corrosion-under-insulation mitigation.
- Adhesives:Bonding agents laminate facings to foam cores in prefabricated panel production. Southern European HVAC duct manufacturers source these for assembly-line integration.
Most installed capacity flows through Rigid Foam. Expansion is steepest in Coatings.
End User:
Customer technical sophistication and procurement scale fragment the addressable market into specification-driven and price-sensitive pools.
- Construction:Commercial building envelopes across Nordic markets specify fast-cure spray systems to compress installation cycles. CE marking under the Construction Products Regulation mandates declared thermal performance and fire reaction classifications that filter out non-compliant imports.
- Refrigeration:Cold chain operators in France and Germany contract for temperature-controlled storage envelopes meeting energy efficiency mandates. Refrigerated warehouse expansions are pulling rigid foam volumes for large-format envelope applications.
- Automotive:Lightweight thermal management layers integrate into electric vehicle battery enclosures. Poland's manufacturing footprint expansion is creating demand for equipment insulation in production facilities.
- HVAC:Mid-temperature duct and equipment insulation faces substitution pressure from mineral wool across Southern Europe. Stone wool producers have hardened cost positions in commercial building segments.
Construction absorbs the largest share of qualified production. Refrigeration is climbing the fastest as logistics infrastructure expands.
Application:
Installation method and exposure severity determine formulation complexity and warranty risk allocation.
- Pipe Insulation:Preformed shells and spray-applied systems protect industrial process lines and district heating networks across Scandinavia and Central Europe. Oil and gas retrofit programs specify water-blown and hydrocarbon-blown formulations for reduced GWP profiles.
- Roof Insulation:Fast-cure spray polyurethane foam systems reduce labor hours and weather dependency during commercial roofing installation. Nordic climates with compressed construction seasons favor these application technologies.
- Wall Insulation:Cavity-fill and external thermal insulation composite systems compete with mineral wool in mid-rise commercial construction. Fire reaction classification thresholds under updated EN standards are retesting reformulated low-GWP systems.
- Floor Insulation:Load-bearing rigid foam layers provide thermal breaks in cold storage foundations. German refrigerated warehouse specifications prioritize compressive strength under point loading.
Pipe Insulation channels the majority of specialized formulation output. Roof Insulation is gaining share fastest through spray technology adoption.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic coverage needs.
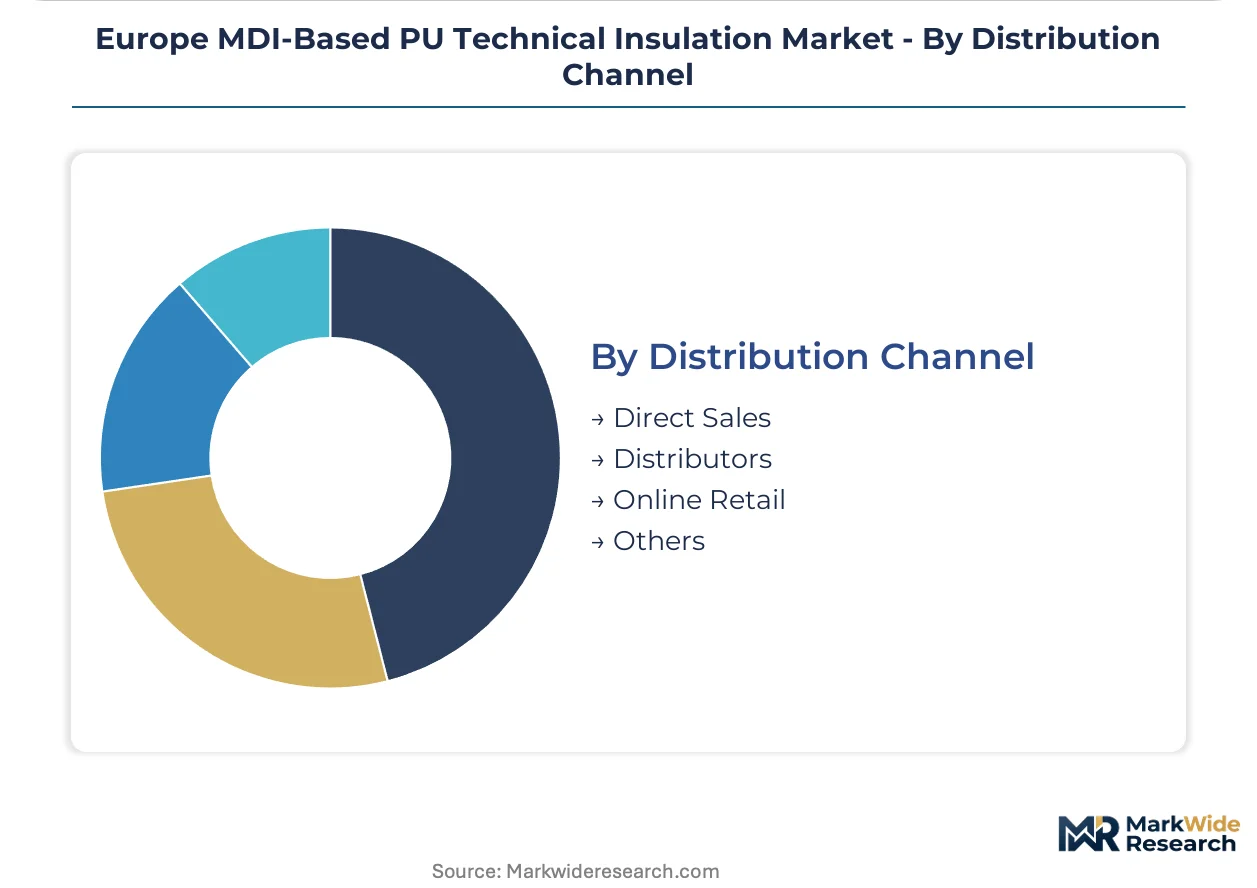
- Direct Sales:Systems houses supply formulated components to large insulation contractors with in-house metering equipment. District heating operators in Denmark and Sweden contract directly for energy-loss outcome guarantees rather than material volumes.
- Distributors:Regional stockists serve mid-tier contractors requiring just-in-time delivery across fragmented construction schedules. German industrial corridor demand concentrates through established distribution networks.
- Online Retail:Small-format kits and accessory products reach maintenance contractors and facility managers. Limited penetration in technical grades due to application expertise requirements.
- Others:Cooperative purchasing arrangements and specification house direct sourcing serve niche segments. Public tender frameworks in France route volumes through appointed intermediaries.
Direct Sales handles the largest contract values. Distributors are expanding coverage fastest into Eastern European industrializing regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor commands the largest share of MDI-based PU technical insulation demand, with chemical processing clusters and LNG infrastructure projects driving specification volumes. National regulations and energy efficiency mandates are reshaping procurement patterns across four additional European markets.
Germany
Cold chain logistics operators are expanding refrigerated warehouse footprints across the Rhine-Ruhr and Bavarian industrial zones. The EU F-Gas Regulation accelerates phase-down timelines for hydrofluorocarbon blowing agents, compelling converters toward low-GWP MDI formulations. Hamburg's port infrastructure and chemical processing corridors concentrate demand for cryogenic pipe insulation in LNG terminal construction.
France
Refrigerated warehouse construction in the Île-de-France logistics belt is pulling rigid foam volumes for temperature-controlled storage envelopes. CE marking under the Construction Products Regulation mandates declared thermal performance and fire reaction classifications. Lyon and Marseille industrial zones specify high-performance thermal barriers for district heating network expansions.
Scandinavia
District heating operators in Denmark and Sweden are contracting for energy-loss outcome guarantees rather than material volumes. ECHA REACH framework compliance requirements filter non-compliant imports from specification eligibility. Oslo and Stockholm metropolitan construction markets favor fast-cure spray polyurethane foam systems to compress installation cycles in compressed construction seasons.
Poland
Automotive and electronics manufacturing facility expansions in the Silesian and Greater Poland voivodeships are generating equipment insulation demand. The EU Green Deal's building renovation wave accelerates retrofit specifications pairing low-GWP blowing agents with thermal barriers. Warsaw logistics corridors are emerging as cold chain infrastructure investment targets for regional distribution networks.
Italy
Mid-temperature HVAC applications across Southern Europe face intensifying substitution pressure from mineral wool producers hardening cost positions. EN standard updates for reaction-to-fire behavior create testing backlogs at notified bodies. Milan and Turin industrial clusters concentrate demand for automotive thermal management layers in electric vehicle battery enclosure integration.
Europe MDI-Based PU Technical Insulation Market Key Industry Players
Capacity expansion dominates the current landscape as established manufacturers retrofit lines for low-GWP blowing agent compatibility ahead of regulatory deadlines. The vendor base separates into three tiers: integrated chemical producers controlling upstream MDI supply, specialized systems houses with formulation expertise, and regional converters serving price-sensitive installation contractors. Strategic archetypes include upstream-integrated material suppliers, application-technology specialists, and distribution-focused service providers. M&A activity and geographic expansion into Eastern European industrializing regions represent the dominant competitive vectors.
Among upstream-integrated chemical producers, Huntsman International LLC and Covestro AG exemplify archetypes with captive isocyanate manufacturing networks. BASF SE occupies a position representing integrated polyol-MDI system suppliers. These three anchors demonstrate how feedstock continuity and formulation specialization create specification stickiness in industrial pipe and cold chain infrastructure tenders.
| Leading Market Players |
|---|
| Rockwool Insulation A/S |
| Owens Corning |
| Huntsman International LLC |
| Compagnie de Saint-Gobain S.A. |
| Knauf Insulation |
| Kingspan Group |
| Recticel Group |
| Covestro AG |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap converters across Germany and Belgium anchor supply continuity through long-term offtake agreements with upstream isocyanate producers, compressing working capital flexibility but insulating formulated systems from spot MDI volatility that erodes margins at non-integrated competitors.
Pricing Analysis
Input-cost pass-through from benzene and aniline derivatives governs rigid foam pricing cycles, with three-month lag contracts dominating industrial pipe insulation procurement. Premium-mid-economy pricing differentiation separates CE-marked systems with declared fire reaction classifications from commodity grades lacking notified body certification. Pricing pressure stems from mineral wool substitution in Southern European HVAC segments, where stone wool producers have hardened cost positions. Small-format distributors serving maintenance contractors exhibit highest price sensitivity, while district heating operators contracting for energy-loss outcomes prioritize thermal performance guarantees over unit economics.
Supply Chain Analysis
Workforce availability constraints in the German chemical corridor and Dutch Rotterdam port complex limit expansion velocity for formulated systems houses requiring skilled nucleation technicians. Supply concentrates in Germany, Belgium, and the Netherlands, with feedstock draws from integrated MDI producers BASF, Covestro, and Huntsman. Raw material dependencies rest on aniline, formaldehyde, and polyol feedstocks, with hydrocarbon blowing agent sourcing tightening under EU F-Gas Regulation phase-down timelines. Single-source vulnerability concentrates in upstream isocyanate allocation, where planned maintenance at Antwerp or Ludwigshafen facilities triggers converter rationing. Distribution runs through direct sales to large insulation contractors and regional distributors serving mid-tier installation firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in low-GWP formulation premiums and outcome-based contracting models that shift performance risk from buyers to suppliers with engineering capabilities.
For Market Incumbents: Extend warranty infrastructure to capture district heating energy-loss outcome contracts before competitors replicate long-term thermal performance guarantees. Deepen backward integration into captive polyol blending to defend formulation margins against integrated chemical producers. Mineral wool substitution in Southern European HVAC represents the primary volume threat requiring fire-reaction-classification investment to maintain specification eligibility. For New Entrants and Emerging Players: Eastern European automotive equipment insulation contractors represent an underserved buyer archetype with fragmented supplier relationships and limited technical service coverage. Poland and Czechia manufacturing facility expansions offer the most penetrable geography, with spray polyurethane foam application technology providing differentiation against rigid panel incumbents. Partner with regional distributors holding existing construction channel relationships to bypass direct sales infrastructure requirements. For Investors and Strategic Acquirers: Integrated chemical producers with captive MDI supply are the most active acquirers in this space, targeting formulated systems houses with ECHA REACH compliance infrastructure and CE marking capabilities. Long-term viability hinges on successful HFC-to-hydrocarbon formulation transitions completed ahead of regulatory deadlines. Watch for reaction-to-fire testing backlog resolution at notified bodies as the signal indicating which reformulated systems will retain tender eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Blending | Captive polyol supply insulates margin compression from integrated chemical producers. |
| Low-GWP Formulation Certification | ECHA REACH compliance and CE marking maintain specification eligibility under F-Gas Regulation. |
| Outcome-Based Contracting Infrastructure | Energy-loss guarantees capture district heating operators shifting from material volumes. |
| Spray Application Technology Expansion | Fast-cure systems reduce weather dependency in Nordic climates with compressed construction seasons. |
| Eastern European Distribution Partnerships | Regional stockist relationships accelerate coverage into Poland and Czechia industrializing zones. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at formulated systems houses, procurement leads at district heating operators, distribution channel partners in Germany and Poland, and technical R&D directors at insulation contractors. Secondary validation drew from customs and trade data, Cefic chemical industry reports, SEC 10-K filings of listed chemical producers, and EN standard updates from notified bodies. Bottom-up volume estimates from application segments triangulated against top-down chemical producer disclosure patterns.
Segment-weighting across product type, end user, application, and distribution channel dimensions drove forecast construction across the projection horizon. Rigid foam, flexible foam, coatings, and adhesives each carried distinct growth assumptions based on capital intensity and regulatory exposure. CAGRs derived from elasticity modeling against industrial construction indices, cold chain investment flows, and automotive production forecasts. Formulation chemistry transition timelines and reaction-to-fire testing queue dynamics served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; pipe insulation and refrigeration applications carry tighter precision than emerging coatings categories with limited historical data. Forecasts reflect assumptions around EU F-Gas Regulation enforcement consistency, REACH authorization timelines, and district heating operator procurement pattern stability. Material deviation in MDI feedstock allocation events or EN standard update schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Impact Sound Insulation Acoustic Mat Market
Insulation Materials
Industrial Pipe Insulation Market
Insulation Materials
Global EMI Shielding Materials Market
Insulation Materials
Thermal Insulation Material Market
Insulation Materials
Pipe Insulation Products Market
Insulation Materials
Beryllium Oxide Market
Insulation Materials
Syntactic Foam Market
Insulation Materials
Low Temperature Insulation Materials Market
Insulation Materials
US Industrial Insulation Market
Insulation Materials
Thin Insulation Market
Insulation Materials
Europe Phase Change Material Market
Insulation Materials
Flexible Insulation Market
Insulation Materials
Fiberglass Duct Wrap Insulation Market
Insulation Materials
Fire Resistant Cable Materials Market
Insulation Materials
Thermal Conductive Polymer Materials Market
Insulation Materials
North America Industrial Insulation Market