
 Lithium Hydride Market | 2026-2036
Lithium Hydride Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Hydride Market Analysis
Battery-grade purity specifications is reorganizing procurement standards across the lithium hydride value chain. Albemarle Corporation leverages its integrated brine-to-chemical operations to sustain cost advantages in high-purity output. Ganfeng Lithium Co., Ltd anchors its position through captive lithium sourcing and expanding hydride conversion capacity in Asia.
Lithium hydride is an inorganic compound with the formula LiH, produced by direct combination of lithium metal with hydrogen gas at elevated temperatures, serving primarily as a dense hydrogen source and strong reducing agent in industrial chemistry. High purity lithium hydride commands premium positioning in aerospace and defense applications where trace contamination tolerance sits at parts-per-million thresholds. Technical grade lithium hydride occupies volume leadership in chemical synthesis and metallurgy, though hydrogen storage applications in research laboratories represent the fastest-expanding margin pool as clean energy R&D accelerates.
China's MIIT sets domestic purity benchmarks for hydride exports, while REACH in Europe governs chemical registration and hazard classification for importers. The EPA in the United States regulates hydrogen storage system safety standards, directly shaping product certification requirements for defense and aerospace contractors. Stakeholders must monitor how diverging transatlantic chemical safety frameworks reshape cross-border qualification timelines and supplier eligibility.
Market Dynamics
The lithium hydride market is undergoing structural recalibration as aerospace hydrogen storage specifications tighten and dual carbon mandates in China redirect feedstock procurement toward verified low-carbon lithium sources.
Growth Catalysts
- EU Green Deal emissions frameworks:The tightening carbon border adjustment mechanism is redirecting European chemical procurement toward hydride suppliers with documented supply chain decarbonization, accelerating demand for certified low-carbon lithium hydride in Germany's research corridor.
- Hydrogen storage in aerospace:Defense contractors and satellite manufacturers are specifying lithium hydride for compact hydrogen reservoirs, driven by weight constraints in orbital payload systems and hypersonic propulsion research.
- Metallurgical reducing agent substitution:Specialty steel producers are displacing conventional reductants with lithium hydride in vacuum induction processes, drawn by superior deoxidation kinetics and reduced slag generation.
Market Restraints
- Lithium metal feedstock volatility:Spodumene concentrate and brine-derived lithium carbonate price swings transmit directly into lithium hydride production economics, compressing margin stability for non-integrated converters.
- Technical limitation in moisture sensitivity:Lithium hydride's extreme reactivity with atmospheric moisture necessitates hermetic packaging and inert atmosphere handling, elevating logistics costs and limiting distribution network expansion.
- REACH registration friction:ECHA's hazard classification requirements for lithium hydride imports impose extended qualification timelines for non-European suppliers, constraining supply elasticity in European specialty chemical markets.
Strategic Opportunities
- India's PLI scheme for advanced chemistry:Production-linked incentives for battery materials and hydrogen storage technologies are attracting hydride conversion capacity investments to Gujarat and Tamil Nadu chemical clusters.
- Research laboratory channel expansion:Direct-to-laboratory distribution models bypassing traditional chemical distributors are capturing margin in academic and national laboratory procurement, particularly in fusion energy research programs.
- Convergence of solid-state hydrogen storage with fuel cell systems:Integration of lithium hydride reservoirs with proton exchange membrane fuel cells is opening stationary backup power applications previously served by compressed gas systems.
Industry Challenges
- Pyrophoric handling certification gaps:The scarcity of technicians qualified for lithium hydride synthesis and packaging under inert atmosphere protocols is constraining capacity expansion timelines for new market entrants.
- Dual-use export control complexity:Lithium hydride's classification under missile technology control regimes creates licensing uncertainty for aerospace and defense shipments, elongating order fulfillment cycles.
- Legacy quality system integration:Specialty chemical producers adopting aerospace-grade purity standards face AS9100 certification timelines that delay qualification for defense contractor supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Hydride Market |
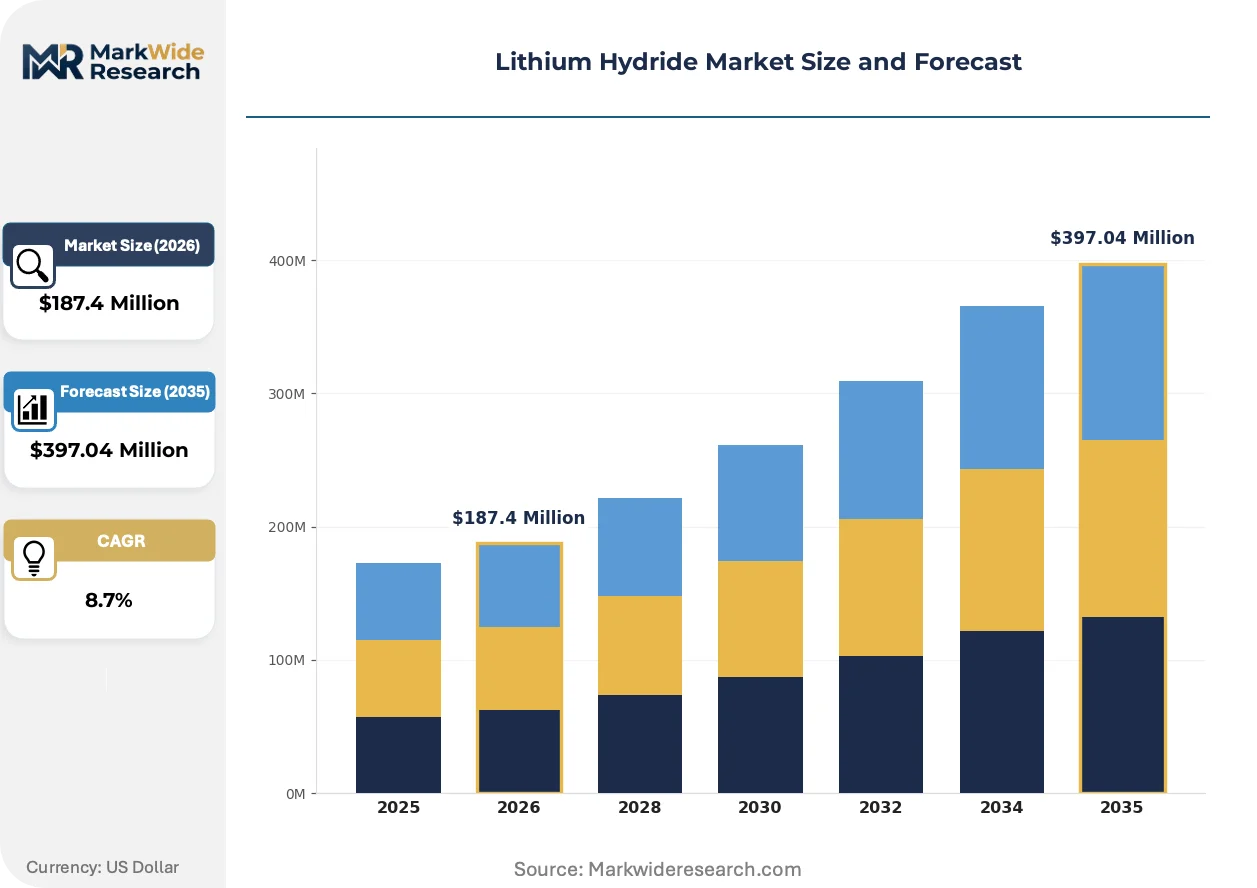
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity Lithium Hydride, Technical Grade Lithium Hydride, Lithium Hydride Powder, Lithium Hydride Pellets Application: Hydrogen Storage, Rocket Propulsion, Chemical Synthesis, Metallurgy End User: Aerospace, Defense, Chemical Manufacturing, Research Laboratories Distribution Channel: Direct Sales, Online Retail, Distributors, Export |
| Companies Covered | Merck KGaA, Albemarle Corporation, Ganfeng Lithium Co., Ltd, American Elements, Santa Cruz Biotechnology, Inc., Tianjin Daofu Chemical New Technology Development Co., Ltd., Parad Corporation Pvt Ltd., ESPI Metals Co, Ltd., Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Hydride Market Emerging Trajectories
Active reformulation of lithium hydride production protocols is compressing impurity thresholds while novel hydrogen release mechanisms expand addressable applications beyond conventional chemical reduction.
Ball-milled lithium hydride-graphite nanocomposites are decomposing at lower thermal activation temperatures than conventional powder forms. Satellite propulsion system designers at national space agencies are specifying these composites for cold-start hydrogen generation. The technology is decomposing the traditional trade-off between hydrogen storage density and release kinetics, enabling single-use reservoir designs previously precluded by thermal management constraints.
China's MIIT purity benchmarks for hydride exports are mandating parts-per-million certification for alkali metal contaminants. Domestic producers are retrofitting synthesis reactors with in-situ spectroscopic monitoring to maintain continuous compliance. Battery-grade lithium hydride shipments to European cathode manufacturers face the most stringent enforcement, with rejected lots triggering supply chain requalification costs.
Defense procurement offices are consolidating supplier lists around vertically integrated lithium-to-hydride producers with captive brine or spodumene assets. Long-term offtake agreements with fixed purity escalators are displacing spot market purchasing for strategic hydrogen storage applications. The concentration is most visible in US Department of Energy national laboratory supply chains, where sole-source justifications now favor domestic conversion capacity over cost-optimized import alternatives.
Lithium Hydride Market Segmentation
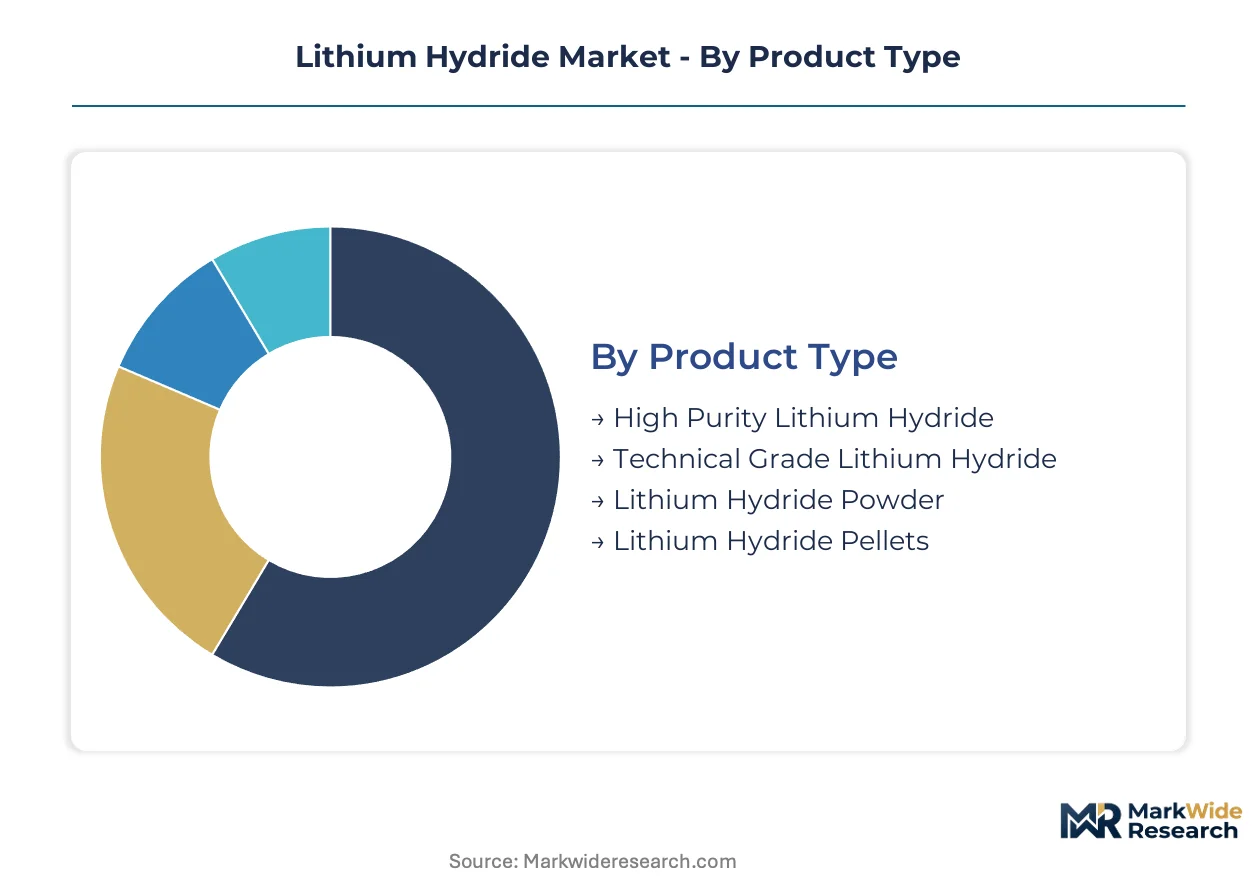
Segmentation in lithium hydride markets separates aerospace-grade specifications from industrial volumes, with purity thresholds and handling protocols determining supplier eligibility across defense procurement channels and chemical manufacturing corridors.
Product Type:
Domestic production in China and the United States concentrates on high-purity grades for strategic reserves, while technical grades flow through export channels serving European chemical synthesis clusters.
- High Purity Lithium Hydride:Synthesized under inert atmosphere protocols with alkali metal contamination held below parts-per-million thresholds. Demand concentrates in US Department of Energy national laboratories and satellite propulsion contractors, driven by REACH registration requirements that disqualify lower-grade imports for European aerospace applications.
- Technical Grade Lithium Hydride:Manufactured to broader specification bands suitable for chemical reduction and metallurgical deoxidation. German specialty steel producers in the Ruhr industrial basin absorb significant volumes, constrained by moisture sensitivity logistics that limit viable supplier radius.
- Lithium Hydride Powder:Fine particulate form with elevated surface area for rapid hydrogen release kinetics. Fusion energy research programs at Princeton Plasma Physics Laboratory specify this morphology.
- Lithium Hydride Pellets:Compressed cylindrical form reducing atmospheric exposure during handling. India's Bhabha Atomic Research Centre procurement favors pelletized delivery for reactor shielding applications.
Technical grade commands the established base. The steepest expansion runs through high purity lithium hydride.
Application:
Cost tier differentiation separates military-specification hydrogen storage from commodity chemical synthesis, with propulsion applications commanding five-fold price multiples over metallurgical reducing agent volumes.
- Hydrogen Storage:Dense solid-state hydrogen reservoir for aerospace weight constraints and backup power systems. China's MIIT purity benchmarks and US EPA safety certification create dual compliance burdens for suppliers targeting both markets.
- Rocket Propulsion:Thermal decomposition hydrogen generation for orbital maneuvering and upper-stage propulsion. JAXA and ISRO development programs in Japan and India are specifying lithium hydride for microsatellite cold-start sequences.
- Chemical Synthesis:Strong reducing agent in organometallic and pharmaceutical intermediate production. Basel-area pharmaceutical corridors in Switzerland utilize technical grades for Grignard-type reactions.
- Metallurgy:Vacuum induction deoxidation in specialty alloy production. ThyssenKrupp operations in Duisburg displace calcium-based reductants with lithium hydride for titanium alloy refining.
Hydrogen storage commands the established base. The steepest expansion runs through rocket propulsion.
End User:
Customer type stratification isolates defense procurement offices with multi-year offtake agreements from spot-market research laboratory purchasing, with payment terms and certification requirements diverging sharply.
- Aerospace:Satellite manufacturers and launch vehicle designers specifying AS9100-certified supply chains. NASA Glenn Research Center maintains qualified supplier lists with domestic conversion capacity requirements.
- Defense:National security hydrogen storage applications under missile technology control regimes. US Department of Defense procurement faces International Traffic in Arms Regulations licensing delays elongating fulfillment cycles.
- Chemical Manufacturing:Industrial-scale consumers integrating lithium hydride into continuous reduction processes. Lanxess operations in Antwerp manage technical grade inventories for polymer precursor synthesis.
- Research Laboratories:Academic and national laboratory procurement with small-batch, high-frequency ordering patterns. Max Planck Institute fusion research programs in Garching source directly through specialized chemical distributors.
Chemical manufacturing commands the established base. The steepest expansion runs through research laboratories.
Distribution Channel:
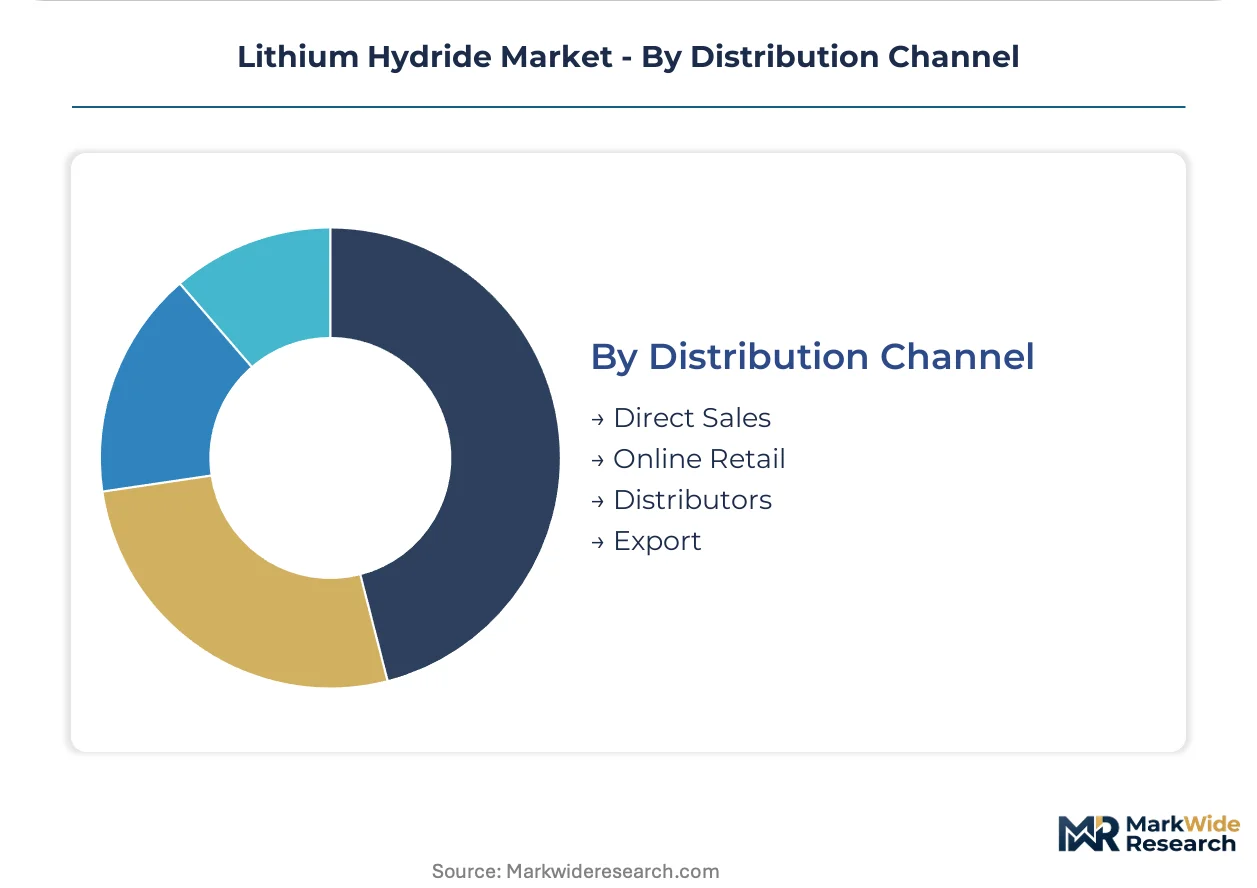
Volume concentration determines channel selection, with direct sales capturing aerospace bulk contracts and distributor networks penetrating fragmented research laboratory demand.
- Direct Sales:Long-term supply agreements between producers and aerospace-defense primes. Lockheed Martin Space Systems negotiates multi-year lithium hydride contracts with fixed purity escalators.
- Online Retail:E-procurement platforms serving small-volume research customers. Sigma-Aldrich digital channels capture academic laboratory demand for gram-scale quantities.
- Distributors:Regional chemical distributors with inert atmosphere warehousing capabilities. VWR International maintains European distribution hubs with argon-purged storage for lithium hydride inventories.
- Export:Cross-border shipments subject to dual-use export controls and REACH registration. Ganfeng Lithium exports from Jiangxi province face extended ECHA qualification timelines for battery-grade hydride.
Direct sales commands the established base. The steepest expansion runs through online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in lithium hydride concentrate in established chemical manufacturing corridors, with domestic production capacity in China and the United States absorbing strategic demand while European procurement relies on qualified imports subject to REACH registration timelines.
China
MIIT purity benchmarks for hydride exports are tightening contamination thresholds for alkali metals to parts-per-million levels. Domestic producers in Jiangxi province are retrofitting synthesis reactors with in-situ spectroscopic monitoring to maintain continuous compliance for battery-grade shipments to European cathode manufacturers.
United States
Defense procurement offices are consolidating supplier lists around vertically integrated producers with captive brine or spodumene assets. EPA hydrogen storage system safety standards directly shape product certification requirements for aerospace contractors at NASA Glenn Research Center and Department of Energy national laboratories.
Germany
Specialty hydride consumption for research laboratories and defense contractors continues to deepen in the Ruhr industrial basin and chemical corridor. ECHA hazard classification requirements for lithium hydride imports impose extended qualification timelines, constraining supply elasticity in European specialty chemical markets.
India
PLI scheme production-linked incentives for battery materials and hydrogen storage technologies are attracting hydride conversion capacity investments to Gujarat and Tamil Nadu chemical clusters. Bhabha Atomic Research Centre procurement favors pelletized lithium hydride delivery for reactor shielding applications.
Japan
JAXA development programs are specifying lithium hydride for microsatellite cold-start sequences in orbital maneuvering systems. METI industrial policy is supporting domestic hydrogen storage R&D, though specialty chemical synthesis demand continues to flow through established import channels.
Lithium Hydride Market Vendor Landscape
Listed leaders compete with private specialists across purity-grade positioning and captive feedstock access. The vendor base separates into three tiers: integrated lithium-to-hydride producers with mining assets, regional conversion specialists serving technical-grade industrial demand, and research-chemical distributors handling gram-scale laboratory procurement. Strategic moves center on backward integration into lithium carbonate supply and AS9100 certification for defense contractor qualification.
Among diversified chemical conglomerates, Merck KGaA and Thermo Fisher Scientific occupy positions spanning laboratory distribution and high-purity specialty chemicals. Ganfeng Lithium Co., Ltd exemplifies the integrated archetype with apparent captive sourcing advantages. Albemarle Corporation represents listed leaders with established brine-to-chemical operations. These three anchors illustrate how competitive positioning separates around feedstock control, distribution channel reach, and certification depth rather than product differentiation alone.
| Leading Market Players |
|---|
| Merck KGaA |
| Albemarle Corporation |
| Ganfeng Lithium Co., Ltd |
| American Elements |
| Santa Cruz Biotechnology, Inc. |
| Tianjin Daofu Chemical New Technology Development Co., Ltd. |
| Parad Corporation Pvt Ltd. |
| ESPI Metals Co, Ltd. |
| Thermo Fisher Scientific |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Jiangxi province synthesis reactors shapes both supply concentration and price floors for lithium hydride, with scale economies at integrated brine-to-hydride operations compressing unit costs below what regional converters can match. This dynamic concentrates pricing power among captive-lithium producers while elevating logistics premiums for moisture-sensitive handling that smaller entrants cannot absorb.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across aerospace-grade certification, technical-grade volume, and research-laboratory spot tiers. Price differentiation hinges on AS9100 certification depth and REACH registration status, with defense procurement offices showing minimal sensitivity while chemical manufacturers face acute pressure from lithium carbonate feedstock volatility. Cost compression in technical-grade volumes is intensifying because non-integrated converters lack captive spodumene supply.
Supply Chain Analysis
Shanghai port customs clearance underwrites export velocity for Chinese hydride shipments, yet ECHA qualification timelines create chokepoints for battery-grade lots entering European aerospace channels. Supply concentrates in China, the United States, and Germany, with raw material dependencies on spodumene concentrate from Australia, brine-derived lithium carbonate from Chile, and hydrogen feedstock from industrial gas suppliers. Single-source vulnerability runs through qualified argon-purged warehousing for moisture-sensitive inventories. Distribution feeds from producer-direct sales for aerospace bulk contracts through specialized chemical distributors serving fragmented research laboratory demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lithium hydride sits in early-cycle expansion as solid-state hydrogen storage penetrates aerospace propulsion systems and fusion energy research programs, with clean energy R&D tailwinds accelerating specification adoption beyond traditional chemical reduction applications.
For Market Incumbents: Compound AS9100 certification depth with captive lithium sourcing to lock out non-integrated rivals. Expand inert atmosphere packaging capacity in Texas and Jiangxi to capture defense procurement consolidation. The priority lever rests on backward integration into spodumene assets rather than toll conversion relationships. For New Entrants and Emerging Players: Lead with direct-to-laboratory distribution models bypassing traditional chemical distributors, targeting gram-scale fusion energy research procurement at Princeton Plasma Physics Laboratory and Max Planck Institute Garching. India's PLI scheme subsidies in Gujarat chemical clusters offer the most penetrable geography for greenfield conversion capacity. For Investors and Strategic Acquirers: Regional conversion specialists with established REACH registrations and argon-purged warehousing infrastructure represent the most defensible acquisition archetype. Long-term viability hinges on hydrogen storage specification adoption in stationary backup power. Watch for MIIT purity benchmark enforcement tightening as the inflection signal for supply chain requalification waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Feedstock | Captive spodumene or brine supply insulates margin from carbonate price volatility at Jiangxi operations. |
| AS9100 Certification Investment | Defense contractor qualification opens multi-year offtake agreements with NASA Glenn Research Center. |
| Direct-to-Laboratory Distribution Launch | Bypassing VWR International and Sigma-Aldrich captures margin in academic fusion research procurement. |
| Inert Atmosphere Packaging Scale-Up | Hermetic pellet and powder formats reduce moisture sensitivity losses in transit to Bhabha Atomic Research Centre. |
| Long-Term Supply Agreement with Aerospace Primes | Fixed purity escalators with Lockheed Martin Space Systems stabilize revenue against spot market lithium volatility. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the lithium hydride value chain, including plant managers at Jiangxi conversion facilities, procurement leads at German specialty steel producers, distribution channel partners with argon-purged warehousing capabilities, and technical R&D directors at national space agencies. Secondary validation drew from customs and trade data, SEC 10-K filings of listed lithium producers, ECHA registration databases, and MIIT export certification records. Bottom-up volume modeling triangulated against top-down market sizing from identified end-use applications.
Across the analysis window, the forecast framework modeled segmentation by purity grade tier, end-use application, packaging morphology, and regional production hub. CAGRs were derived from elasticity-adjusted demand projections for hydrogen storage adoption in aerospace and defense channels, with inputs from lithium carbonate price trajectory assumptions and REACH registration timeline scenarios.
The analysis sits within stated boundaries; outcomes outside sustained clean energy R&D funding levels or relaxed dual-use export licensing would require recalibration. Forecasts reflect documented assumptions on MIIT enforcement intensity and ECHA qualification throughput. Practitioners should keep alternative scenarios live as aerospace procurement consolidation patterns and lithium feedstock sourcing economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Bioactive Glass Market
Advanced Materials
Global Advanced Phase Change Materials Market
Advanced Materials
Extracellular Matrix Proteins Market
Advanced Materials
Superconducting Materials Market
Advanced Materials
North America Next Generation Anode Materials Market
Advanced Materials
Rigid Foam Market
Advanced Materials
Lab-Grown Rough Diamond Market
Advanced Materials
Vacuum Insulation Panels Market
Advanced Materials
Synthetic Graphite Market
Advanced Materials
Global Electrostrictive Material Market
Advanced Materials
Si-C Anode Material Market
Advanced Materials
North America Polyether Ether Ketone (Peek) Market
Advanced Materials
Global Core Materials Market
Advanced Materials
Organic Aerogel Market
Advanced Materials
Europe Blanket Aerogel Market
Advanced Materials
Carbon Graphite Market