
 Global Aluminum Honeycomb Market | 2026-2036
Global Aluminum Honeycomb Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aluminum Honeycomb Market Foresight
Aftermarket panel refurbishment is reconfiguring margin distribution across the value chain. Hexcel Corporation leverages captive resin formulation and core bonding expertise to sustain aerospace tier-one relationships. Plascore, Inc. anchors industrial volume through automated cell expansion lines serving rail and marine customers. 3A Composites GmbH differentiates via European certification density and proximity to German OEM engineering centers.
Aluminum honeycomb consists of expanded hexagonal-cell aluminum foil structures bonded into sandwich panels with face sheets, typically manufactured through adhesive node bonding or brazing processes to achieve specific shear and compression properties for load-bearing applications. The product type dimension shows aluminum-magnesium alloy cores gaining traction in marine vessels due to saltwater corrosion resistance, while standard aluminum grades dominate mature aerospace procurement where legacy specifications govern material selection. Application segmentation reveals aerospace absorbing the largest value share, though construction panels represent the fastest-expanding demand pool as curtain wall fire-rating requirements elevate engineered core specifications.
FAA airworthiness directives and EASA CS-25 certification frameworks mandate flammability and smoke-toxicity thresholds that shape core adhesive chemistry and node-bonding process validation. REACH chemical restrictions and EU Green Deal embodied-carbon tracking are forcing European suppliers to document lifecycle emissions across aluminum smelting, foil rolling, and cell expansion stages. Stakeholders must monitor evolving MEE emissions standards in China and their potential to reshape export-competitive positioning for Asian honeycomb fabricators serving Western OEM qualification programs.
Market Dynamics
Fuel-efficiency mandates from FAA and EASA are compressing aircraft design cycles, forcing aerospace OEMs to qualify lightweight sandwich structures faster than legacy timelines permit. This regulatory pressure is redistributing procurement power toward certified honeycomb fabricators with proven node-bonding process validation.
Growth Catalysts
- EU Green Deal embodied-carbon tracking:Lifecycle documentation requirements are creating competitive moats for European suppliers with smelting-to-expansion traceability systems.
- Curtain wall fire-rating mandates:Construction codes in Germany and Singapore are elevating engineered core specifications for high-rise facade panels.
- Aluminum-magnesium alloy cores:Saltwater corrosion resistance properties are opening marine vessel applications previously served by heavier metallic structures.
Market Restraints
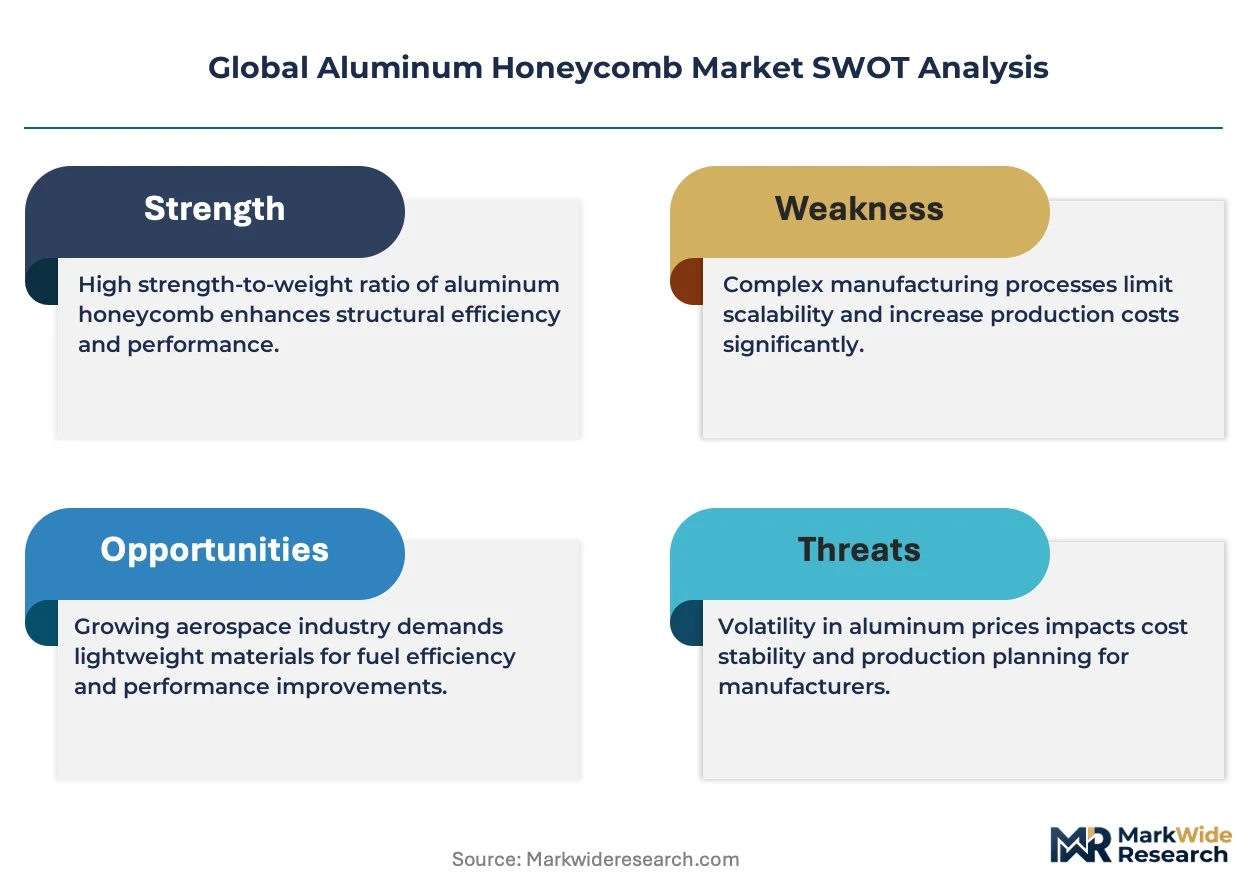
- Primary aluminum price volatility:LME aluminum fluctuations transmit directly to foil rolling costs, compressing margins for non-integrated expanders.
- Bavarian supplier concentration:Airbus supply chain localization creates single-region dependency risk for tier-two fabricators without multi-site qualification.
- Aramid and thermoplastic substitution:Nomex and PEI cores are displacing aluminum in interior panels where flammability thresholds favor non-metallic chemistry.
Strategic Opportunities
- India rail infrastructure expansion:Metro and high-speed rail programs are generating demand for lightweight floor and ceiling panels with fire-certified cores.
- MEE emissions standards compliance:Chinese fabricators investing in low-carbon smelting partnerships can regain Western OEM qualification access.
- Automated cell expansion + robotic bonding convergence:Capital-light modular production systems are enabling mid-scale entrants to serve industrial volume segments.
Industry Challenges
- Adhesive formulation chemist scarcity:REACH-compliant core bonding expertise concentrates among aging specialists in German and Swiss research clusters.
- CS-25 certification timeline compression:FAA and EASA parallel qualification tracks demand redundant testing budgets without guaranteed program wins.
- Legacy MRP integration:Honeycomb expanders face ERP incompatibility when aerospace OEMs mandate real-time production data feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aluminum Honeycomb Market |
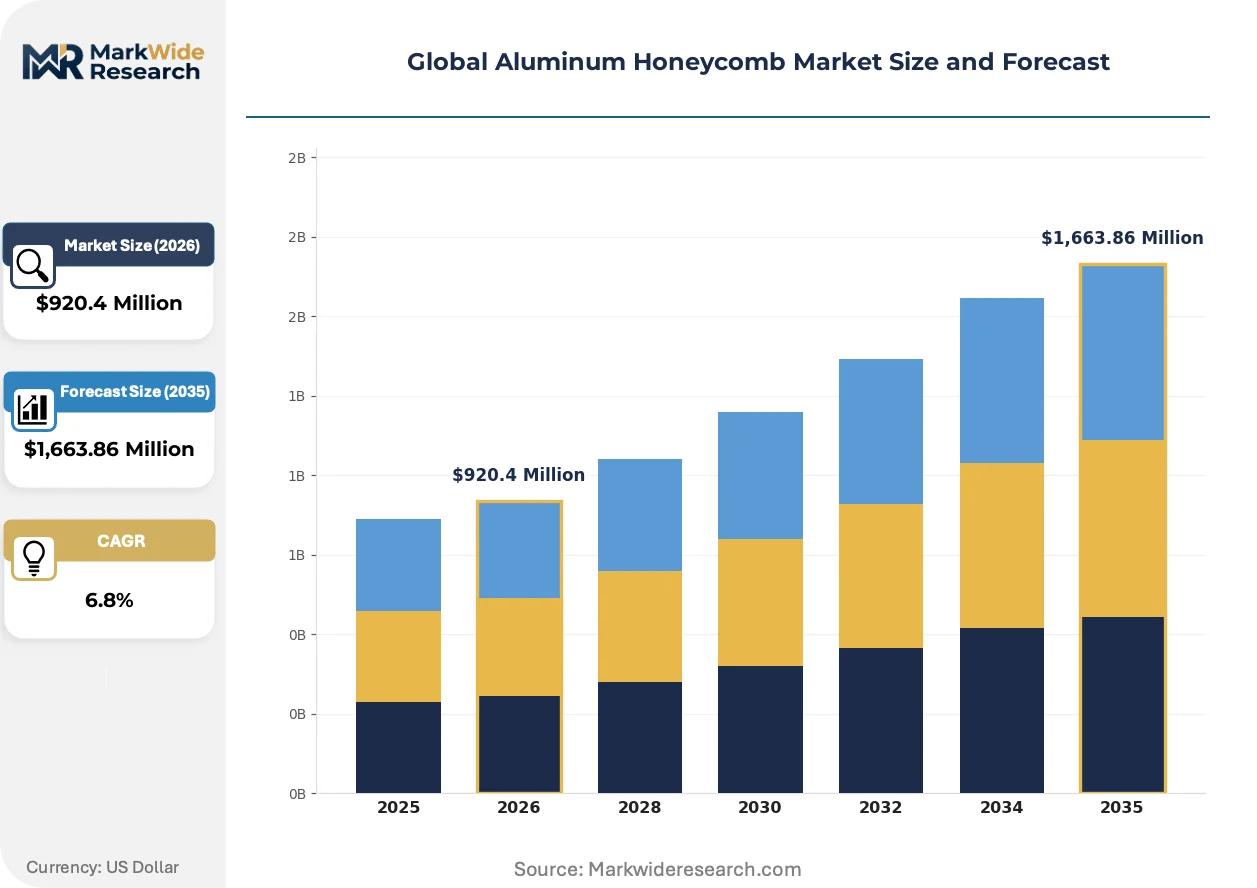
| Market Size in 2026 | $920.4 Million |
| Market Size in 2035 | $1,663.86 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Aluminum-Lithium, Aluminum-Magnesium, Aluminum-Zinc, Aluminum-Silicon, Aluminum-Titanium Application: Aerospace, Marine Vessels, Construction Panels, Rail Transit, Packaging Solutions, Furniture Manufacturing End User: Aircraft Manufacturers, Shipbuilders, Building Contractors, Railway Operators, Logistics Providers, Interior Designers Cell Size: 3mm, 6mm, 9mm, 12mm, 15mm, 25mm |
| Companies Covered | Argosy International Inc., Alucoil, SAU, Hexcel Corporation, The Gill Corporation, Schütz GmbH & Co. KGaA, Plascore, Inc., 3A Composites GmbH, RelCore Composites Inc., Toray Advanced Composites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aluminum Honeycomb Market Shifts & Advancements
Process automation and regulatory disclosure requirements are converging to reshape how aluminum honeycomb moves from foil rolling to qualified sandwich panel. Three developments are compressing traditional value chain boundaries.
Continuous roll-forming expansion technology is hybridizing with in-line node bonding to eliminate batch handling. Aerospace tier-one suppliers in Toulouse and Hamburg are piloting these integrated lines to halve core-to-panel lead times. The technology is hybridizing quality assurance and production speed into single-flow operations that reduce work-in-process inventory.
REACH chemical restrictions are forcing reformulation of phenolic and epoxy adhesives used in node bonding. ECHA substance evaluation timelines are extending qualification cycles for new chemistries by 18-24 months. European suppliers with early SVHC screening programs are securing first-mover advantage in next-generation fire-resistant core specifications.
Aftermarket panel refurbishment is fragmenting procurement authority away from OEM engineering centers. MRO facilities in Singapore and Dallas are establishing direct relationships with core expanders for damage-tolerant replacement panels. This channel bypass is most visible in commercial aviation where lease-return inspections drive unscheduled honeycomb demand outside OEM service networks.
Global Aluminum Honeycomb Market Segmentation
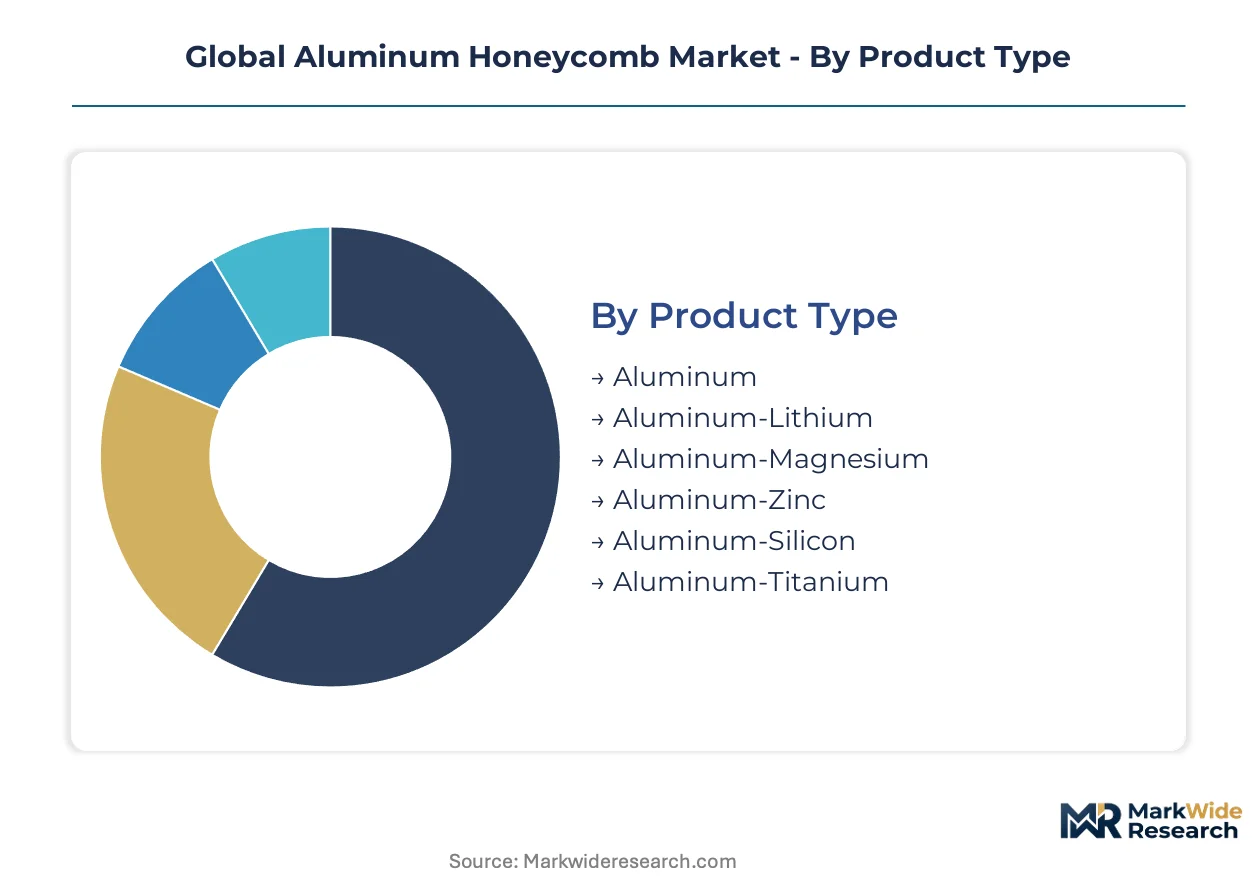
Aluminum honeycomb markets fragment across alloy chemistry, cell geometry, and end-use certification requirements. Each dimension creates distinct procurement channels with divergent margin structures and qualification timelines.
Product Type:
Use-case spectrum spans legacy aerospace specifications through emerging marine corrosion resistance demands.
- Aluminum:Standard 3003 and 5052 alloy foils constitute the baseline specification for commercial aviation interior panels. Procurement concentrates at Airbus facilities in Toulouse and Hamburg where legacy CS-25 qualification pathways favor proven material sets.
- Aluminum-Magnesium:5xxx series alloys deliver superior saltwater corrosion resistance for hull structural applications. Norwegian and South Korean shipyards are specifying these cores for offshore platform decking and high-speed ferry bulkheads.
- Aluminum-Lithium:Density reduction of 8-10% versus standard grades supports satellite payload fairing applications.
- Aluminum-Zinc:7xxx series precipitation-hardened cores serve military aircraft armor panels.
- Aluminum-Silicon:Cast-compatible alloys enable near-net-shape node bonding for complex curved panels.
- Aluminum-Titanium:Hybrid metallurgy targets hypersonic vehicle thermal protection systems under development.
The dominant share belongs to standard Aluminum grades, while Aluminum-Magnesium is closing the gap fastest.
Application:
Volume distribution reflects regulatory fire-rating mandates and fuel-efficiency enforcement intensity across transport modes.
- Aerospace:Sandwich panels for flooring, ceilings, and galley structures absorb the largest value share. FAA and EASA flammability directives force adhesive chemistry validation that extends qualification cycles to 24-36 months.
- Construction Panels:Curtain wall and facade systems represent the steepest expansion trajectory. Germany's EnEV energy code and Singapore's SCDF fire safety mandates are elevating engineered core specifications for high-rise cladding.
- Marine Vessels:Bulkhead and decking applications leverage saltwater-resistant alloy variants.
- Rail Transit:Metro floor and ceiling panels require EN 45545-2 fire certification.
- Packaging Solutions:Reusable shipping containers for semiconductor equipment utilize crush-resistant core structures.
- Furniture Manufacturing:Lightweight tabletops and exhibition systems serve commercial interior fit-outs.
Aerospace commands premium pricing, yet construction panels are gaining share fastest.
End User:
Procurement authority concentrates with OEM engineering centers for qualified applications, fragmenting toward MRO facilities in aftermarket channels.
- Aircraft Manufacturers:Boeing, Airbus, and COMAC drive specification lock-in through approved supplier lists. Tier-one panel fabricators in Japan and Italy maintain exclusive relationships for wing-to-body fairing structures.
- Shipbuilders:Hyundai Heavy Industries and Fincantieri specify corrosion-resistant cores for cruise ship and naval contracts.
- Building Contractors:Facade specialists in Dubai and Frankfurt source fire-certified panels for mixed-use towers.
- Railway Operators:Deutsche Bahn and Indian Railways procurement frameworks emphasize lifecycle cost over first cost.
- Logistics Providers:Cold-chain container lessors specify moisture-resistant edge closures.
- Interior Designers:Hospitality fit-out firms in Milan and Tokyo commission custom cell sizes for aesthetic panel effects.
Aircraft Manufacturers dominate qualified volume, while Building Contractors are expanding procurement fastest.
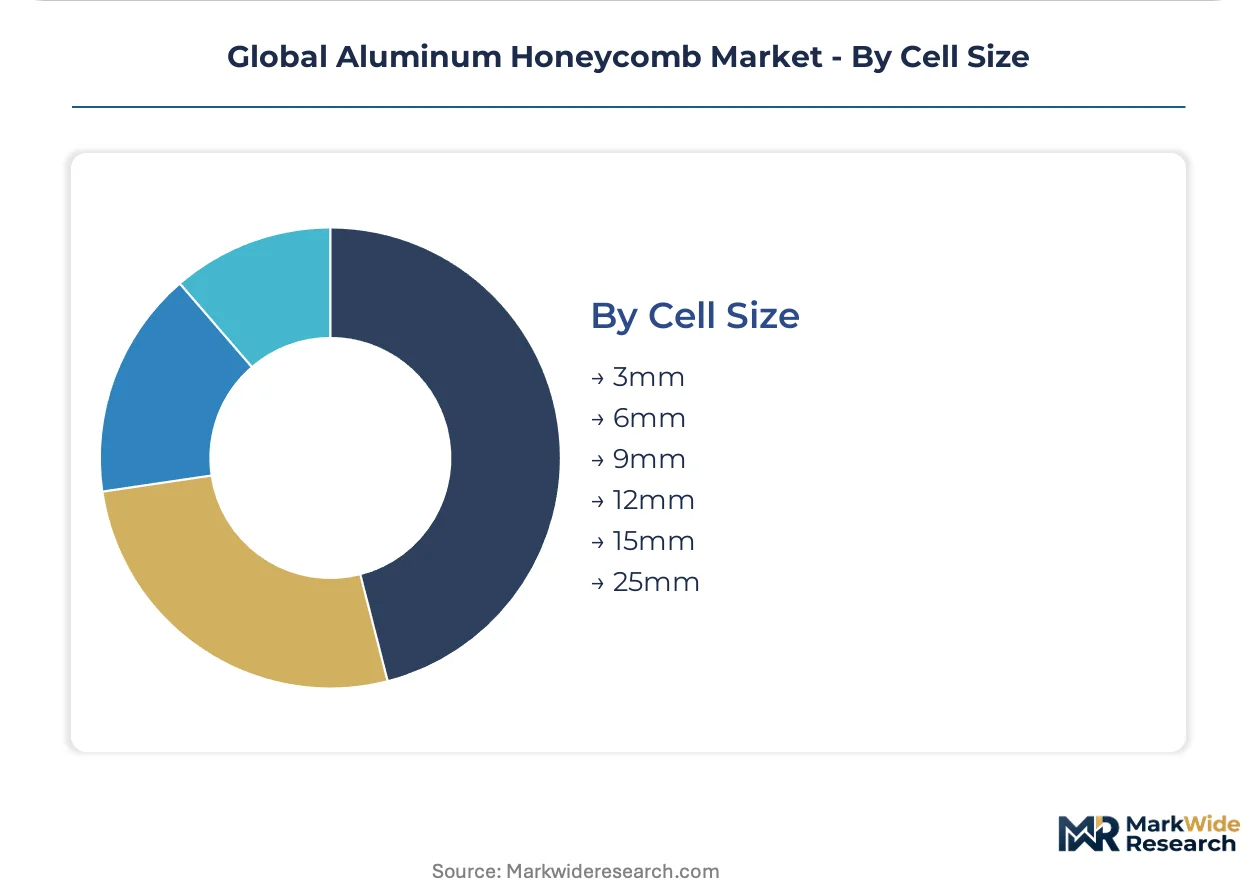
Cell Size:
Geometric selection trades structural efficiency against surface finish requirements and adhesive bonding area.
- 6mm:Aerospace interior panels favor this geometry for optimal stiffness-to-weight with acceptable drape characteristics. Airbus A350 galleys and lavatories specify 6mm cores with phenolic resin node bonding.
- 12mm:Marine decking and rail flooring applications prioritize this larger cell for crush resistance under concentrated wheel loads.
- 3mm:Precision optical benches and semiconductor equipment tables require fine cell structures.
- 9mm:General industrial panels balance cost and performance for machinery enclosures.
- 15mm:Architectural sunshades and acoustic baffles utilize expanded geometry.
- 25mm:Blast mitigation and impact absorption systems employ maximum cell depth.
The 6mm specification holds dominant share, while 12mm is climbing fastest on rail and marine demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: Germany concentrates aerospace-qualified procurement, the United States fragments between defense and commercial aviation, China scales industrial volume, Japan refines precision applications, and India expands rail infrastructure demand. Each geography deploys aluminum honeycomb toward distinct priority outcomes.
Germany
Airbus supply chain localization and Bavarian composite cluster density concentrate qualified honeycomb procurement. EASA CS-25 certification frameworks and REACH chemical restrictions force adhesive chemistry documentation across the value chain. Engineering centers in Munich and Hamburg sustain tier-one relationships with certified core expanders.
United States
Defense aerospace programs and commercial aviation MRO networks generate dual demand streams. FAA airworthiness directives mandate flammability thresholds that shape node-bonding process validation. Dallas-Fort Worth and Seattle-Tacoma clusters anchor aftermarket refurbishment channels bypassing OEM procurement.
China
Industrial volume expansion in rail transit and construction panels drives scale-focused production. MEE emissions standards and dual carbon goals pressure smelting-to-expansion traceability for Western OEM qualification access. Yangtze River Delta fabricators invest in low-carbon aluminum partnerships.
Japan
Precision optical benches and semiconductor equipment tables demand fine-cell geometries. METI industrial standards and JIS certification frameworks govern material specifications for high-technology applications. Nagoya and Osaka manufacturing belts specialize in 3mm cell structures.
India
Metro and high-speed rail programs generate demand for lightweight floor and ceiling panels. Indian Railways procurement frameworks emphasize lifecycle cost optimization over first-cost minimization. Mumbai and Delhi engineering centers specify EN 45545-2 fire-certified cores for urban transit systems.
Global Aluminum Honeycomb Market Competitive Landscape
Capability concentration sits with aerospace-qualified fabricators holding EASA and FAA certifications; scale advantage sits with industrial-volume producers serving rail and construction segments. The vendor base stratifies into three tiers: integrated resin-formulation specialists, automated expansion-line operators, and regional certification-focused suppliers. Dominant competitive moves include backward integration into foil rolling and geographic expansion toward Asian rail infrastructure markets.
Among Germany-based fabricators, Schütz GmbH & Co. KGaA and 3A Composites GmbH exemplify the European certification-density archetype, while Hexcel Corporation anchors the integrated-resin-specialist position. These three represent distinct strategic postures: proximity to Airbus engineering centers, REACH-compliant adhesive expertise, and captive bonding chemistry respectively.
| Leading Market Players |
|---|
| Argosy International Inc. |
| Alucoil, SAU |
| Hexcel Corporation |
| The Gill Corporation |
| Schütz GmbH & Co. KGaA |
| Plascore, Inc. |
| 3A Composites GmbH |
| RelCore Composites Inc. |
| Toray Advanced Composites |
| Others |
Supply & Pricing Matrix
Undercapacity in European foil rolling capacity is concentrating procurement leverage among qualified expanders, compressing margins for non-integrated fabricators while rewarding those with captive smelting partnerships and REACH-compliant adhesive chemistry.
Pricing Analysis
Long-term offtake contracts dominate aerospace procurement, locking in volume commitments from Airbus and Boeing tier-one panel fabricators against spot-market volatility in raw aluminum. Three-tier pricing structure across EASA-certified premium grades, standard industrial specifications, and economy construction cores reflects certification burden and node-bonding process validation intensity. Pricing pressure stems from LME aluminum volatility transmitting directly to foil rolling costs, with non-integrated expanders absorbing margin compression. Building contractors exhibit highest price sensitivity due to first-cost procurement frameworks, while aircraft manufacturers accept premium positioning for qualified supply security.
Supply Chain Analysis
Export-control regimes on advanced node-bonding equipment limit technology transfer to Chinese fabricators, constraining their qualification access for Western aerospace programs. Supply concentrates in Germany, China, and the United States, with Bavarian clusters anchoring EASA-certified production and Yangtze River Delta facilities scaling industrial volume. Raw material dependencies span primary aluminum ingot, phenolic resin formulations, and precision-rolled foil gauges. Single-source vulnerability in REACH-compliant adhesive chemists concentrates expertise among aging specialists in German and Swiss research clusters. Distribution runs through tier-one panel fabricators for qualified aerospace, direct MRO channels for aftermarket refurbishment, and building material distributors for construction applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics logic is reshaping this market as digital thread integration across OEM engineering centers, certified expanders, and MRO facilities creates interoperability moats that lock in specification authority.
For Market Incumbents: Entrench specification control by deepening backward integration into low-carbon aluminum smelting partnerships that satisfy EU Green Deal embodied-carbon tracking mandates. Extend certification density through early SVHC screening programs that compress ECHA substance evaluation timelines for next-generation fire-resistant core specifications. Threat of aramid and thermoplastic substitution in interior panels demands accelerated R&D in hybrid metallurgy for thermal protection systems. For New Entrants and Emerging Players: Mid-scale automated cell expansion lines serving Indian rail infrastructure and Southeast Asian marine vessel retrofit markets represent the most penetrable entry points outside Airbus-Boeing qualification barriers. Capital-light modular production systems enable service of industrial volume segments without EASA CS-25 certification burden. Go-to-market positioning should emphasize EN 45545-2 fire certification for metro and high-speed rail programs where lifecycle cost frameworks displace first-cost procurement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among certified core expanders with captive resin formulation and multi-site qualification across Toulouse, Hamburg, and Dallas-Fort Worth aerospace clusters. Long-term viability rests on adhesive chemistry expertise concentration and MRO channel bypass trends fragmenting procurement authority. Acquisition targets should demonstrate proven node-bonding process validation with real-time production data feed compatibility for legacy MRP integration. Signal to monitor: Chinese fabricator progress in MEE emissions standards compliance and Western OEM qualification access restoration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Aluminum Smelting | Captive supply of traceable primary metal satisfies EU Green Deal documentation requirements for German aerospace procurement. |
| Automated Cell Expansion Line Deployment | Robotic bonding convergence enables mid-scale entrants to serve Indian rail and Southeast Asian marine volume segments. |
| EASA CS-25 Certification Investment | Parallel qualification tracks with FAA compress timeline risk for Airbus and Boeing tier-one panel fabricator relationships. |
| MRO Channel Direct Relationship Development | Singapore and Dallas aftermarket refurbishment bypasses OEM procurement fragmentation, capturing unscheduled lease-return demand. |
| REACH-Compliant Adhesive Reformulation | Early SVHC screening programs secure first-mover positioning in next-generation fire-resistant core specifications for curtain wall mandates. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with tier-one panel fabricators, certified core expanders, aerospace procurement officers, MRO facility managers, and adhesive formulation chemists; and secondary validation through EASA certification databases, FAA airworthiness directives, REACH substance registrations, LME aluminum price series, and customs trade flows. Bottom-up segmentation modeling across alloy chemistry, cell geometry, and end-use certification requirements was triangulated against top-down macroeconomic drivers.
Forecast inputs considered fuel-efficiency mandate intensity, embodied-carbon tracking enforcement progression, and substitution threat velocity from aramid and thermoplastic cores across the projection horizon. Segmentation dimensions modeled include product type tier, application fire-rating requirement, end-user procurement authority structure, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume projections calibrated to OEM qualification timeline compression and aftermarket channel fragmentation patterns.
Macroeconomic conditions sit as an overlay; deviation in primary aluminum price volatility, REACH chemical restriction expansion, or MEE emissions standards enforcement would shift the trajectory. Forecasts reflect assumptions around EASA-FAA certification timeline stability and Chinese fabricator qualification access restoration. Material shifts in adhesive formulation chemist availability or aramid core flammability threshold advancement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Rigid Foam Market
Advanced Materials
Nomex Honeycomb Market
Advanced Materials
Silver Nanowires Market
Advanced Materials
Si-C Anode Material Market
Advanced Materials
Carbon Graphite Market
Advanced Materials
Global Diamond-Like Carbon (DLC) Market
Advanced Materials
Lithium Hydride Market
Advanced Materials
Corundum Market
Advanced Materials
Curable Materials Market
Advanced Materials
High-Purity Amorphous Boron Market
Advanced Materials
APAC Advanced Building Materials Market
Advanced Materials
Boron Nitride Market
Advanced Materials
Advanced Carbon Materials Market
Advanced Materials
Advanced Nanomaterials Market
Advanced Materials
Flexible Bio-Foams Market
Advanced Materials
Anisotropic Conductive Films (ACF) Market