
 Continuous Glucose Monitoring Market | 2026-2036
Continuous Glucose Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Glucose Monitoring Market Analysis
Market Context with Strategic Players
The boundary between hospital-based and home-based glucose management is collapsing as patients demand real-time metabolic visibility outside clinical settings. Abbott Laboratories leverages integrated sensor-to-reader ecosystems that anchor its position in retail pharmacy channels across North America and Europe. Dexcom, Inc. competes through aggressive R&D intensity and cloud-native data architectures that extend its reach into consumer wellness platforms. Medtronic PLC dominates the insulin pump-CGM convergence space with closed-loop algorithms that differentiate its offering for intensive insulin users.
Technical Definition and Structural Segments
Continuous glucose monitoring comprises electrochemical sensor systems that measure interstitial glucose concentrations through a subcutaneous filament, transmitting data every one to fifteen minutes to receivers or smartphones for trend analysis and hypoglycemic alerting. Flash glucose monitoring occupies the largest installed base due to lower cost and calibration-free operation, while implantable CGM represents the fastest-growing product category as ninety-day sensor longevity reduces insertion burden and improves adherence. Mobile app-based delivery mode captures expanding margin pools as software subscriptions and data analytics services layer recurring revenue atop hardware sales, whereas standalone devices face commoditization pressure from smartphone-integrated alternatives.
Regulatory Framework and Forward Outlook
FDA breakthrough device pathways and CMS national coverage determinations shape United States demand acceleration by compressing time-to-market and expanding reimbursable indications. EMA medical device regulation and CE marking requirements under the EU MDR govern European market access with intensified clinical evidence standards. Japan's PMDA and METI reimbursement frameworks determine commercial viability in a market where aging-related diabetes burden is concentrating. Stakeholders must monitor evolving interoperability mandates and cybersecurity standards as regulators integrate connected device governance into premarket review criteria.
Market Dynamics
The convergence of smartphone-native data architectures with calibration-free sensor chemistry is collapsing the traditional hardware-software boundary in glucose management, forcing incumbent manufacturers to rebuild revenue models around recurring digital subscriptions rather than disposable sensor sales.
Growth Catalysts
- FDA Breakthrough Device Pathway:Compressed premarket review timelines for novel CGM systems are accelerating clinical validation cycles and expanding reimbursable indications for intensive insulin users.
- Home Care Migration:Patient demand for metabolic visibility outside hospital settings is pulling sensor deployment toward retail pharmacy and direct-to-consumer channels.
- Interoperability Mandates:CMS national coverage determinations requiring data portability between devices are standardizing communication protocols across the installed base.
Market Restraints
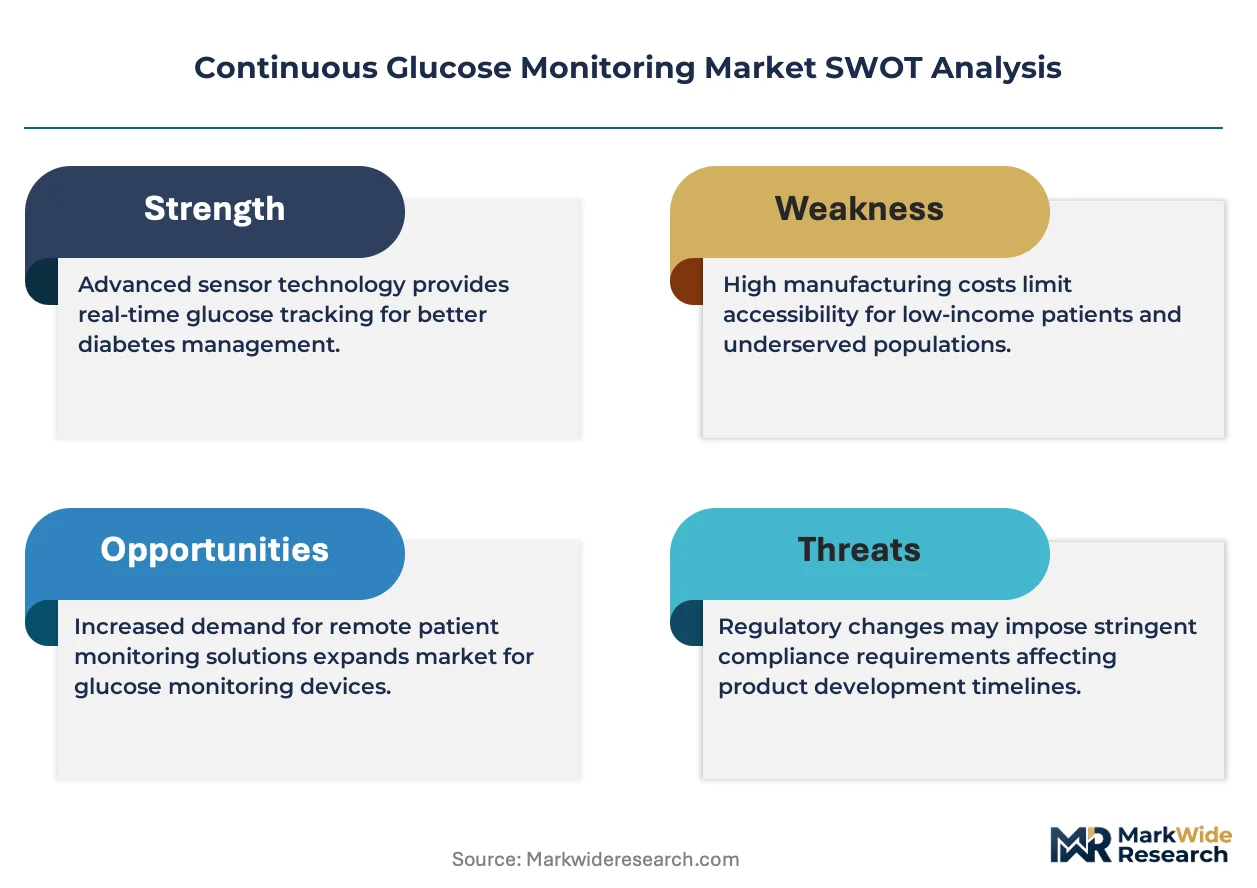
- Platinum Electrode Supply Concentration:Electrochemical sensor manufacturing depends on refined platinum inputs sourced from concentrated South African and Russian smelter networks.
- EU MDR Clinical Evidence Burden:Intensified post-market surveillance requirements under the Medical Device Regulation are extending recertification timelines for legacy sensor platforms.
- Optical Glucose Sensing Substitution:Non-invasive spectroscopic alternatives using near-infrared transdermal measurement are capturing wellness-seeking consumers averse to filament insertion.
Strategic Opportunities
- Type 2 Non-Intensive Segment:Oral medication-managed diabetes populations in India and Brazil remain substantially underpenetrated by prescription CGM relative to insulin-dependent cohorts.
- Insulin Pump Convergence:Closed-loop algorithm integration with patch pump hardware is creating integrated metabolic management platforms for intensive users.
- Remote Patient Monitoring Reimbursement:CMS expansion of CPT codes for continuous physiologic monitoring is enabling physician practice revenue models tied to glucose data interpretation.
Industry Challenges
- Biocompatibility Engineering Talent Scarcity:Sensor filament design requires specialized expertise in foreign body response mitigation and membrane chemistry that outpaces academic program output.
- Cybersecurity Certification Complexity:FDA premarket submission requirements for connected device security architecture are extending development timelines for cloud-native data platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Glucose Monitoring Market |
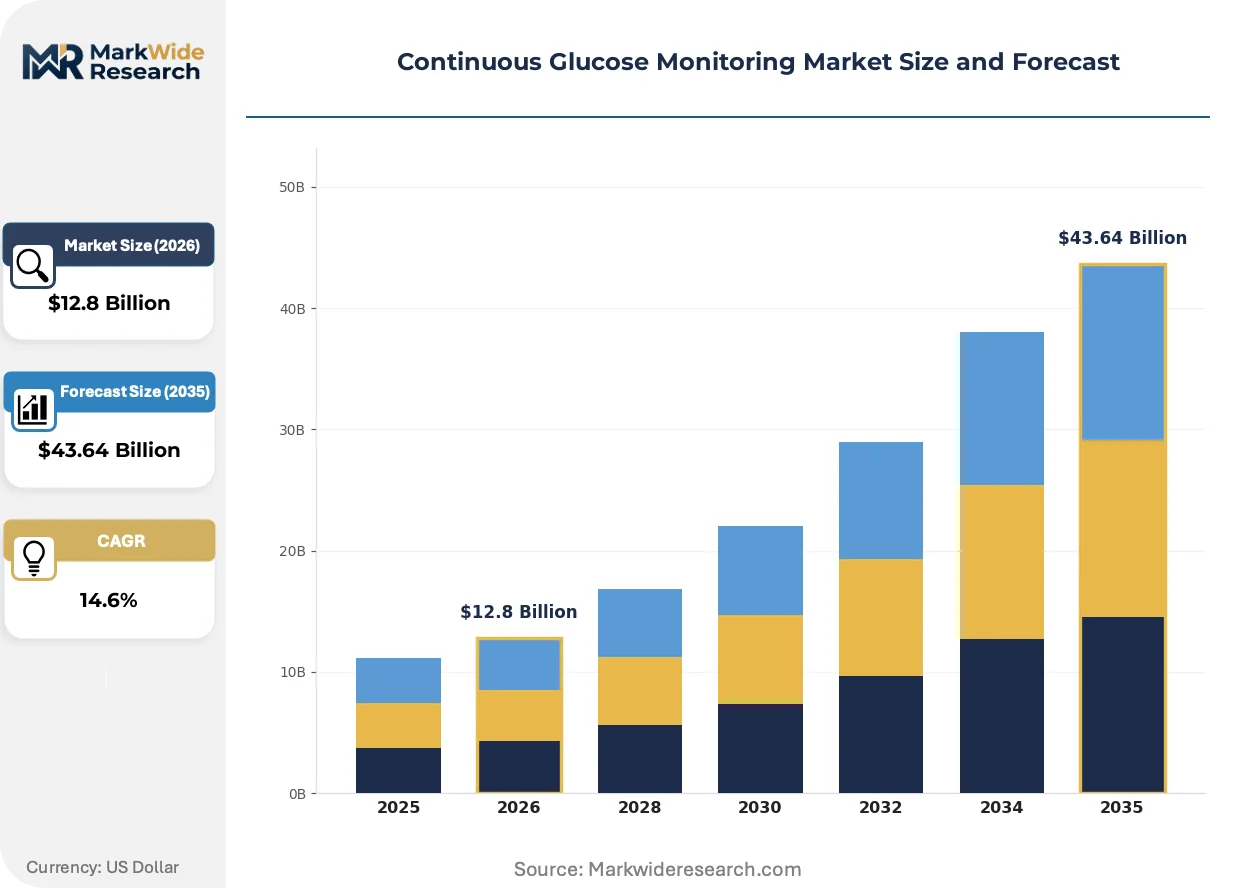
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $43.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flash Glucose Monitoring, Traditional CGM, Implantable CGM, Wearable Sensors End User: Home Care, Hospitals, Diabetes Clinics, Research Laboratories Delivery Mode: Mobile App-based, Cloud-based, Standalone Devices, Integrated Systems Technology: Electrochemical Sensors, Optical Sensors, Microneedle Technology, Continuous Monitoring Systems |
| Companies Covered | Senseonics Holdings, Inc., Ypsomed AG, Abbott Laboratories, A. Menarini Diagnostics Ltd., Novo Nordisk A/S, Dexcom, Inc., F. Hoffmann-La Roche Ltd., GlySens, Incorporated, Medtronic PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Glucose Monitoring Market Emerging Trajectories
Sensor longevity extension and algorithm-driven predictive alerting are repositioning glucose monitoring from reactive measurement toward anticipatory metabolic intervention, compressing the window between glucose excursion and clinical response.
Implantable ninety-day sensor platforms are supplanting traditional fourteen-day wearable systems in intensive insulin user segments. Endocrinology practices managing complex type 1 populations are adopting these platforms to reduce patient insertion burden and improve adherence metrics. The shift is compressing replacement revenue cycles while expanding per-patient lifetime value through improved retention.
Japan's PMDA has streamlined reimbursement pathways for real-time CGM systems under revised METI pricing frameworks. The policy revision enables broader coverage for non-intensive insulin users previously excluded from national health insurance. Domestic manufacturers are accelerating clinical trial enrollment to capture expanded indication eligibility.
Patients are consolidating glucose data interpretation within primary care relationships rather than specialist endocrinology visits. Retail clinic networks and telehealth platforms are capturing this demand migration through remote monitoring service bundles. The United States exhibits the most pronounced channel shift as accountable care organizations incentivize population-level glucose management.
Continuous Glucose Monitoring Market Segmentation
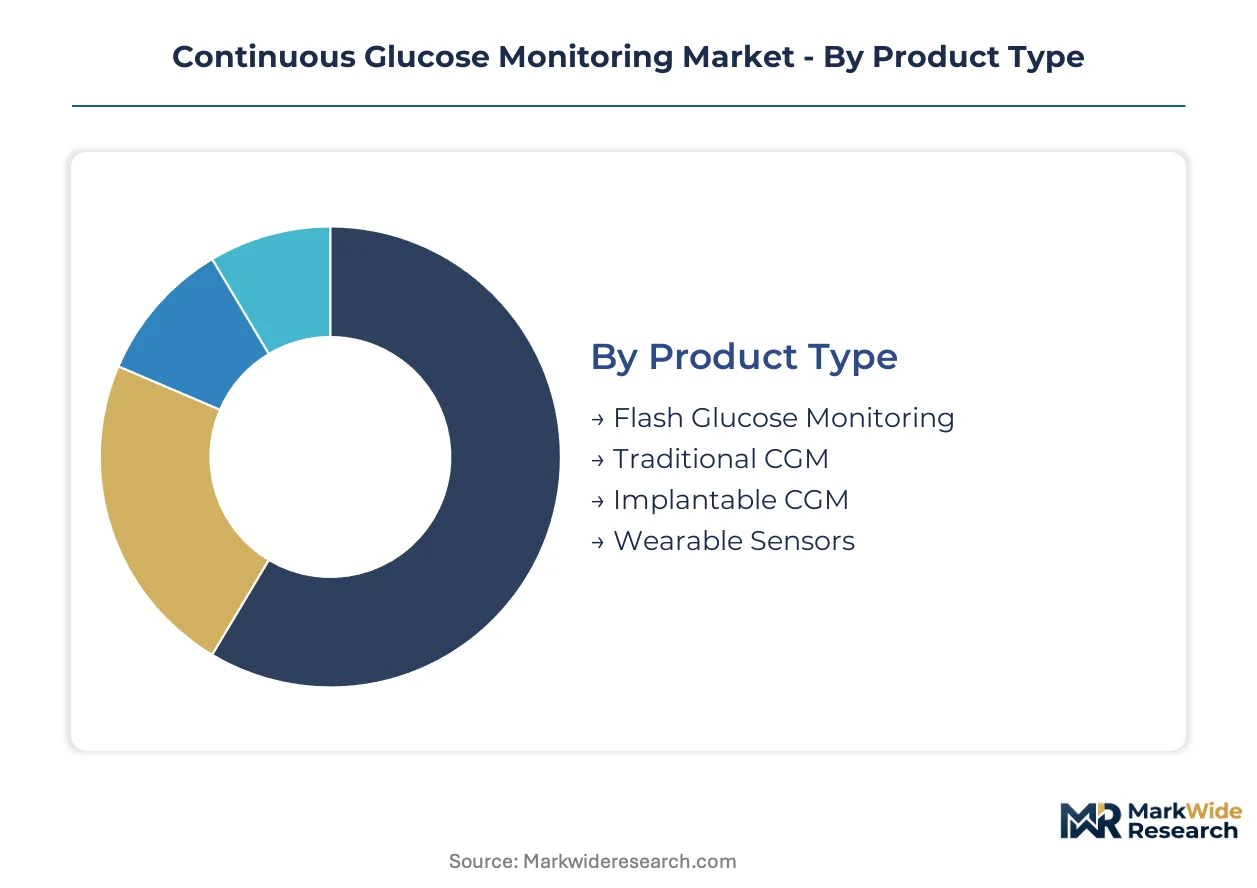
Segmentation in continuous glucose monitoring reveals how sensor chemistry, data architecture, and care setting interact to determine commercial viability. Manufacturers configure product portfolios around reimbursement pathways and patient self-management preferences rather than clinical indication alone.
Product Type:
Channel distribution varies sharply by insertion burden and calibration requirements, with pharmacy retail dominating low-touch formats and specialty distributors handling implantable platforms.
- Flash Glucose Monitoring:Factory-calibrated electrochemical sensors eliminate fingerstick confirmation and transmit data on patient demand through handheld readers. Home care settings in Germany and Japan capture the greatest volume as national insurers expand reimbursable indications for type 2 non-intensive users.
- Implantable CGM:Subcutaneous ninety-day sensors reduce insertion frequency through biocompatible membrane engineering that mitigates foreign body response. Endocrinology practices managing complex type 1 populations in the United States are migrating toward these platforms to improve adherence metrics and reduce clinic visit burden.
- Traditional CGM:Fourteen-day wearable systems with real-time alerting remain the standard for intensive insulin users requiring hypoglycemia prediction.
- Wearable Sensors:Skin-surface optical and electrochemical patches target wellness consumers outside prescription channels.
By volume, Flash Glucose Monitoring leads. By growth pace, Implantable CGM is ahead.
End User:
Cost tier stratification separates acute institutional procurement from retail pharmacy and direct-to-consumer channels, with reimbursement density determining margin capture.
- Home Care:Patient-directed glucose management outside clinical settings concentrates demand for calibration-free, smartphone-integrated systems. The United States exhibits the most pronounced channel shift as CMS expands remote physiologic monitoring reimbursement and accountable care organizations incentivize population-level management.
- Hospitals:Inpatient glycemic control requires wired connectivity to electronic health records and nurse station alerting. Japanese tertiary centers are standardizing on interoperable platforms that satisfy METI data portability mandates.
- Diabetes Clinics:Specialist practices generate recurring revenue through interpretation services bundled with sensor prescriptions.
- Research Laboratories:Clinical trial sponsors demand raw data export capabilities and algorithm transparency for regulatory submission.
Revenue concentrates in Home Care. Margin expansion is steepest in Diabetes Clinics.
Delivery Mode:
Software subscription attach rates determine lifetime value, with cloud-native architectures capturing recurring revenue streams that standalone hardware cannot match.
- Mobile App-based:Smartphone-native data visualization and predictive alerting reposition glucose monitoring as digital health service. United States consumers are consolidating interpretation within primary care relationships rather than specialist visits, pulling demand toward telehealth-integrated platforms.
- Cloud-based:Centralized data lakes enable population analytics and remote monitoring reimbursement for physician practices. German diabetes networks leverage these architectures to coordinate care across fragmented ambulatory settings.
- Standalone Devices:Dedicated receivers face commoditization pressure as smartphone integration becomes standard.
- Integrated Systems:Closed-loop pump-CGM convergence demands unified data architectures and algorithm interoperability.
Mobile App-based systems claim the largest installed base. Cloud-based delivery is climbing the fastest as reimbursement codes mature.
Technology:
Supply concentration in platinum electrode refining and biocompatibility engineering talent shapes which sensor chemistries achieve commercial scale.
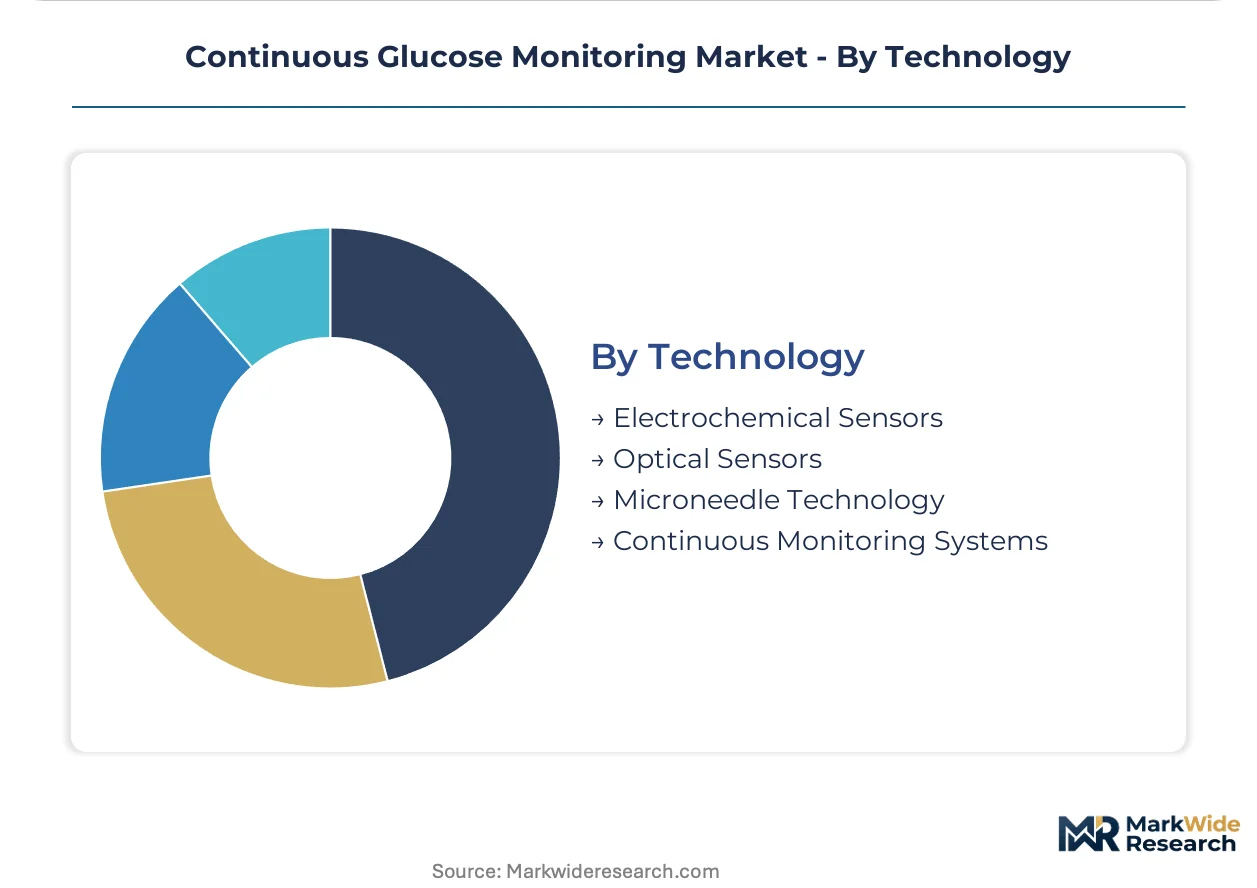
- Electrochemical Sensors:Enzyme-based glucose oxidase detection through platinum-working electrodes dominates prescription CGM manufacturing. Supply security concerns intensify as South African and Russian smelter networks concentrate refined platinum inputs.
- Microneedle Technology:Minimally invasive filament arrays enable continuous interstitial fluid sampling with reduced insertion trauma. Japanese materials science programs are advancing polymer formulations that extend functional longevity beyond current fourteen-day limits.
- Optical Sensors:Near-infrared spectroscopic alternatives target non-invasive wellness applications but struggle with accuracy validation for therapeutic decisions.
- Continuous Monitoring Systems:Integrated hardware-software platforms combine sensor, transmitter, and algorithm in unified architectures.
Electrochemical Sensors anchor current revenue. Microneedle Technology shows the steepest patent filing acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refined platinum electrode supply chains concentrate in South African and Russian smelter networks, creating geographic vulnerability for electrochemical sensor manufacturing. Demand acceleration varies sharply by reimbursement density and diabetes prevalence across national markets.
United States
Medicare remote physiologic monitoring reimbursement and FDA breakthrough device pathways compress commercialization timelines for novel sensor platforms. CMS national coverage determinations now extend to non-intensive insulin users, expanding addressable populations. The Minneapolis-St. Paul corridor anchors Medtronic's closed-loop algorithm development and clinical trial infrastructure.
Germany
National health insurance expansion for flash glucose monitoring in type 2 non-intensive populations drives pharmacy retail volume. EMA medical device regulation intensifies post-market surveillance requirements for legacy sensor recertification. The Mannheim-Heidelberg medical technology cluster concentrates diabetes device manufacturing and biocompatibility engineering talent.
Japan
Aging demographics concentrate diabetes burden among populations over sixty-five, intensifying demand for adherence-improving implantable platforms. PMDA streamlined reimbursement pathways under revised METI pricing frameworks now cover real-time CGM for broader insulin user categories. The Tokyo-Osaka corridor hosts domestic clinical trial enrollment and sensor materials science programs.
India
Oral medication-managed type 2 diabetes populations remain substantially underpenetrated by prescription CGM relative to insulin-dependent cohorts. CDSCO medical device registration pathways are harmonizing with international standards to accelerate market entry for multinational manufacturers. The Mumbai-Pune pharmaceutical corridor is developing local sensor assembly capacity for cost-sensitive market segments.
Brazil
Private health insurance coverage expansion for continuous glucose monitoring is outpacing public sector reimbursement, creating dual-tier market dynamics. ANVISA medical device regulation requires in-country clinical validation for novel sensor chemistries, extending registration timelines. The São Paulo metropolitan area concentrates diabetes specialist practices and private hospital networks driving premium sensor adoption.
Continuous Glucose Monitoring Market Vendor Landscape
Concentration sits with diversified medical technology conglomerates and specialized diabetes device manufacturers. The market structure tiers across integrated pump-CGM convergence platforms, standalone sensor specialists, and pharmaceutical-affiliated diagnostic divisions. Two strategic archetypes dominate: vertically integrated closed-loop system providers and calibration-free flash monitoring specialists. Competitive moves center on sensor longevity extension and cloud-native data architecture licensing.
Among diversified medical technology conglomerates, Abbott Laboratories and Medtronic PLC exemplify scale-driven platform integration. Dexcom, Inc. occupies a position within the standalone CGM specialist tier, representing cloud-native data architecture approaches. Ypsomed AG exemplifies the European specialist archetype, anchoring insulin delivery convergence capabilities from Swiss manufacturing bases.
| Leading Market Players |
|---|
| Senseonics Holdings, Inc. |
| Ypsomed AG |
| Abbott Laboratories |
| A. Menarini Diagnostics Ltd. |
| Novo Nordisk A/S |
| Dexcom, Inc. |
| F. Hoffmann-La Roche Ltd. |
| GlySens, Incorporated |
| Medtronic PLC |
| Others |
Supply Flow & Price Mechanics
FDA breakthrough device designation and CE marking under EU MDR simultaneously gate supplier qualification and stratify price tiers, compressing time-to-market for certified manufacturers while relegating uncertified competitors to commodity positioning in direct-to-consumer channels.
Pricing Analysis
FDA breakthrough device pathways and CMS national coverage determinations dictate the pricing tier structure across prescription and direct-to-consumer channels. Three-tier pricing separates implantable ninety-day platforms from fourteen-day wearable systems and from wellness-oriented optical alternatives. Price differentiation hinges on calibration-free operation and real-time alerting certification. Cost compression in flash glucose monitoring intensifies as smartphone integration becomes standard. Home care patients exhibit highest price sensitivity; intensive insulin users in closed-loop pump convergence show lowest.
Supply Chain Analysis
Sensor manufacturers carry ninety-day platinum electrode inventories against South African and Russian smelter lead-time volatility. Electrochemical sensor production draws from concentrated platinum refining in South Africa and Russia, with biocompatible membrane chemistry anchored in German and Japanese materials science programs. Single-source vulnerability concentrates in refined platinum electrode supply. Distribution runs through specialty medical device distributors for implantable platforms and retail pharmacy networks for flash monitoring systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical glucose sensing substitution threatens electrochemical sensor incumbents as wellness-seeking consumers bypass filament insertion entirely, forcing prescription manufacturers to defend reimbursement-protected clinical indications against non-invasive alternatives.
For Market Incumbents: Compound sensor longevity advantages through biocompatibility engineering investments that extend functional life beyond current ninety-day limits. Deepen backward integration into platinum electrode sourcing to mitigate South African and Russian supply concentration. Defend against optical substitution by anchoring clinical validation in hypoglycemia prediction accuracy that non-invasive alternatives cannot match. For New Entrants and Emerging Players: Anchor in type 2 non-intensive segments across India and Brazil where prescription CGM penetration remains minimal against oral medication-managed populations. Target direct-to-consumer optical wellness applications where regulatory burden is lowest and consumer price sensitivity is offset by convenience preference. Pursue telehealth platform partnerships as primary go-to-market channel. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cloud-native data architecture development as software subscription attach rates determine lifetime value capture. Five-to-ten year viability favors acquiring specialized biocompatibility engineering teams with foreign body response mitigation expertise rather than hardware manufacturing assets. Watch FDA premarket submission timelines for connected device security architecture as inflection indicator for development cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Longevity Extension | Ninety-day implantable platforms reduce insertion burden and improve adherence metrics in type 1 populations. |
| Cloud-Native Data Architecture | Software subscription models capture recurring revenue streams atop hardware sales in mobile app-based delivery. |
| Closed-Loop Algorithm Development | Pump-CGM convergence creates integrated metabolic management platforms for intensive insulin users. |
| Reimbursement Strategy Expansion | CMS remote physiologic monitoring codes enable physician practice revenue tied to glucose data interpretation. |
| Biocompatibility Engineering Investment | Foreign body response mitigation expertise extends functional sensor longevity beyond current limits. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) submissions, CMS national coverage determinations, and hospital procurement databases. Primary interviews engaged endocrinologists, biomedical engineers, GPO contracts managers, and diabetes device procurement leads at integrated delivery networks. Secondary sources included SEC 10-K filings, PMDA reimbursement bulletins, and EMA medical device regulation guidance documents. Bottom-up sensor shipment estimates triangulated against top-down diabetes prevalence projections and reimbursement expansion timelines.
Segmentation dimensions modeled span product type, end user setting, delivery mode, and technology chemistry across the analysis window. CAGRs derived from regression against historical adoption curves in analogous diagnostic device categories and adjusted for regulatory pathway acceleration effects. Forecast inputs incorporated PMDA streamlined reimbursement timelines and EU MDR recertification burden impacts on legacy platform commercialization.
Decision-makers should treat outputs as directional under assumptions of continued CMS reimbursement expansion and stable platinum electrode supply; material deviation in either would warrant model refresh. Specific risk factors include optical sensing accuracy breakthroughs and South African smelter network disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
South Korea Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Self-Monitoring Blood Glucose Strips Market
Diabetes Care
Continuous Glucose Monitoring Device Market
Diabetes Care
Egypt Diabetes Care Devices Market
Diabetes Care
Self-Monitoring Blood Glucose (SMBG) Market
Diabetes Care
Vietnam Diabetes Care Devices Market
Diabetes Care
North America Diabetes Care Devices Market
Diabetes Care
Brazil Continuous Glucose Monitoring Market
Diabetes Care
Vietnam Insulin Drug and Delivery Device Market
Diabetes Care
OTC Glucose Monitors Market
Diabetes Care
Asia-Pacific Insulin Delivery Devices Market
Diabetes Care
Brazil Oral Anti-Diabetic Drug Market
Diabetes Care
Philippines Diabetes Drugs and Devices Market
Diabetes Care
Global Blood Glucose Test Strip Market
Diabetes Care
India Insulin Infusion Pump Market
Diabetes Care
Diabetic Gastroparesis Treatment Market