
 Cardioscope Market | 2026-2036
Cardioscope Market Size, Share, and Industry Trends Forecast 2026-2036
Cardioscope Market Analytics
Multi-source procurement of cardiac monitoring components is consolidating around established device manufacturers with captive supply chains. Abbott Laboratories anchors its position through in-house production of electrophysiology catheters and sensors. Medtronic Plc leverages vertical integration across implantable and external monitoring platforms to sustain margin control. Koninklijke Philips N.V. competes through integrated diagnostic imaging and telemetry ecosystems that span hospital and homecare channels.
A cardioscope is a diagnostic instrument that captures, amplifies, and displays electrical signals from the heart, typically operating through electrode arrays with sampling rates exceeding 250 Hz for clinical-grade arrhythmia detection. The device serves cardiologists and emergency physicians in real-time cardiac assessment, perioperative monitoring, and longitudinal patient management. Portable monitors and Holter monitors occupy the mature core of the product mix, while telemetry systems and AI-based analytics represent the fastest-expanding margin pools as health systems shift toward decentralized care models. Wireless technology and cloud storage infrastructure now underpin most new platform deployments, though advanced imaging modules command premium positioning in electrophysiology labs.
FDA premarket notification requirements and the EU Medical Device Regulation shape product development timelines and clinical evidence thresholds for market access. The EPA and ISO 13485 standards additionally govern material biocompatibility and quality management systems across manufacturing facilities. Stakeholders must monitor evolving reimbursement codes for remote cardiac monitoring as payer policies increasingly determine which technology configurations achieve commercial scale.
Market Dynamics
Cardioscope platforms are pivoting toward AI-native architectures as health systems demand predictive arrhythmia detection and seamless electronic health record integration. This technical reconfiguration is compressing product development cycles and elevating software validation requirements.
Growth Catalysts
- FDA 510(k) clearance streamlining:Expedited pathways for predicate-based submissions accelerate time-to-market for iterative sensor designs. Device developers leverage this mechanism for rapid algorithm updates.
- Ambulatory surgical center expansion:Outpatient cardiac procedure volumes in the United States drive procurement of portable monitoring systems with wireless telemetry. These facilities prioritize compact footprint and rapid deployment.
- Cloud infrastructure maturation:Amazon Web Services and Microsoft Azure health-compliant environments enable real-time data streaming from implantable devices to clinician dashboards. This architecture supports longitudinal patient management.
Market Restraints
- Electrode array supply concentration:Silver-silver chloride sensor manufacturing clusters in Southeast Asia create single-source vulnerability for multiple device OEMs.
- EU MDR clinical evidence thresholds:Stricter post-market surveillance and notified body capacity constraints extend certification timelines by eighteen to thirty-six months.
- Consumer-grade wearable substitution:Apple Watch and similar photoplethysmography devices capture low-acuity cardiac monitoring demand outside acute care settings.
Strategic Opportunities
- Japan's super-aging demographic:The Ministry of Health, Labour and Welfare reimbursement expansion for home-based cardiac telemetry creates demand for wearable Holter alternatives.
- AI-ECG multimodal fusion:Integration of electrical signal analysis with echocardiographic imaging enables single-device comprehensive assessment in electrophysiology labs.
- Direct-to-hospital distribution:Bypassing traditional medical device distributors through specialized cardiac monitoring sales teams improves margin capture and clinical training attachment.
Industry Challenges
- Electrophysiologist training pipeline:Fellowship program capacity constraints in Germany and the United States limit deployment of advanced mapping-enabled cardioscope systems.
- Legacy device interoperability:Proprietary data formats from installed telemetry bases complicate integration with cloud-native analytics platforms.
- Cybersecurity certification complexity:FDA premarket guidance on device software security requires specialized engineering resources that strain mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardioscope Market |
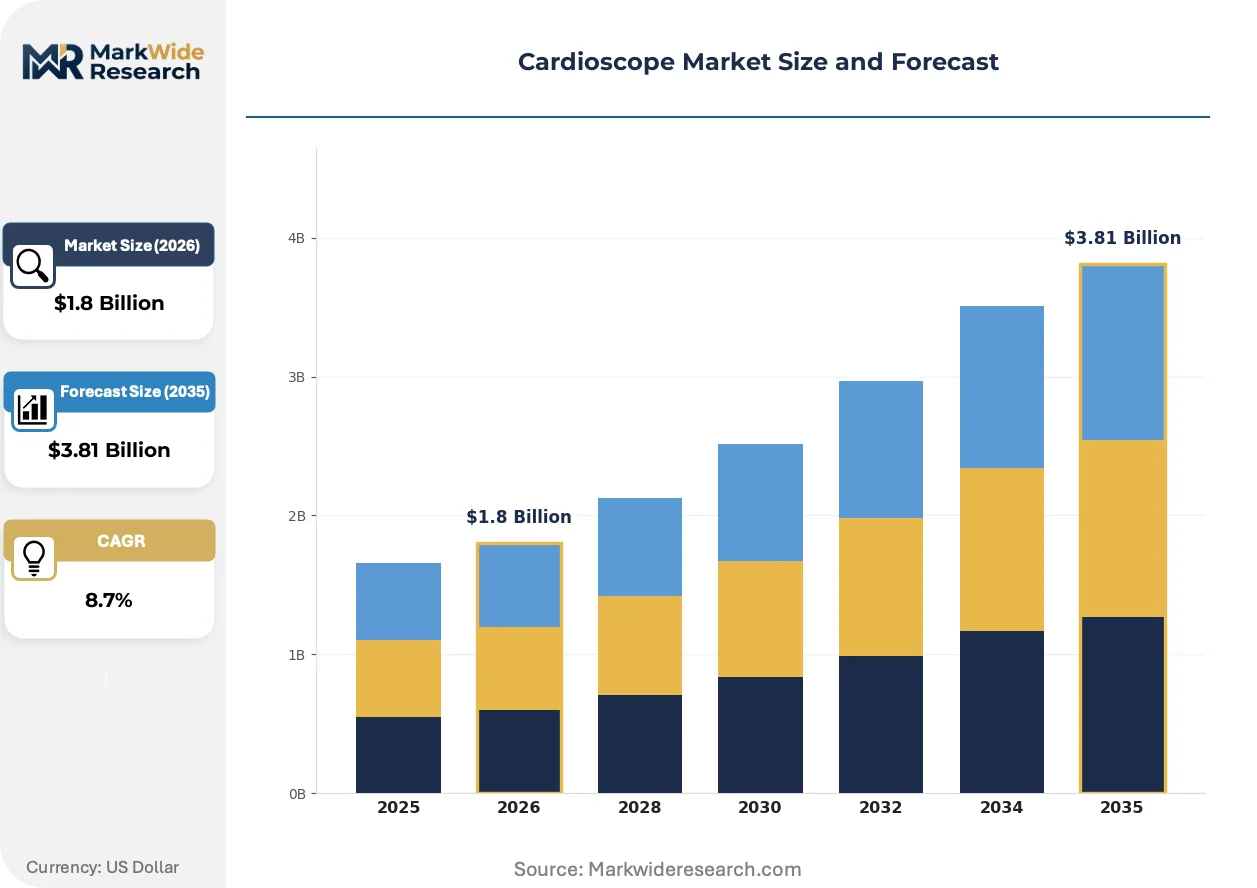
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Holter Monitors, Telemetry Systems, Electrophysiology Devices End User: Cardiology Clinics, Emergency Departments, Homecare Settings, Ambulatory Surgical Centers Technology: Wireless Technology, AI-Based Analytics, Cloud Storage, Advanced Imaging Application: Cardiac Monitoring, Arrhythmia Detection, Patient Management, Heart Failure Assessment |
| Companies Covered | Parker Hannifin Corp, Benaka Healthcare, Beijing Carejoy Technology Co., Ltd, Abbott Laboratories, Medtronic Plc, Boston Scientific Corporation, Koninklijke Philips N.V., Nihon Kohden Corporation, Schiller AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardioscope Market Evolving Landscape
Cardioscope technology trajectories center on computational integration, regulatory recalibration of software-as-medical-device, and procurement model compression that favors ecosystem vendors over point-solution suppliers.
Deep learning algorithms for automated arrhythmia classification are consolidating diagnostic authority previously held by specialized cardiac electrophysiologists. Major academic medical centers in the United States and Japan now deploy FDA-cleared AI modules for preliminary ECG interpretation. This capability compression enables generalist clinicians to manage low-complexity monitoring cases.
EU MDR Article 10 post-market clinical follow-up requirements are reshaping evidence generation budgets for cardioscope manufacturers. Companies must maintain active registries and periodic safety reporting that extends five to ten years post-certification. Small and mid-sized device developers face capital constraints that favor partnership with established notified body networks.
Hospital procurement committees are consolidating vendor relationships around full-stack cardiac monitoring ecosystems rather than discrete hardware purchases. Integrated platforms spanning bedside telemetry, ambulatory Holter, and implantable loop recorders command preference in United States IDN RFP processes. This bundling dynamic disadvantages standalone device manufacturers lacking software analytics capabilities.
Cardioscope Market Segmentation
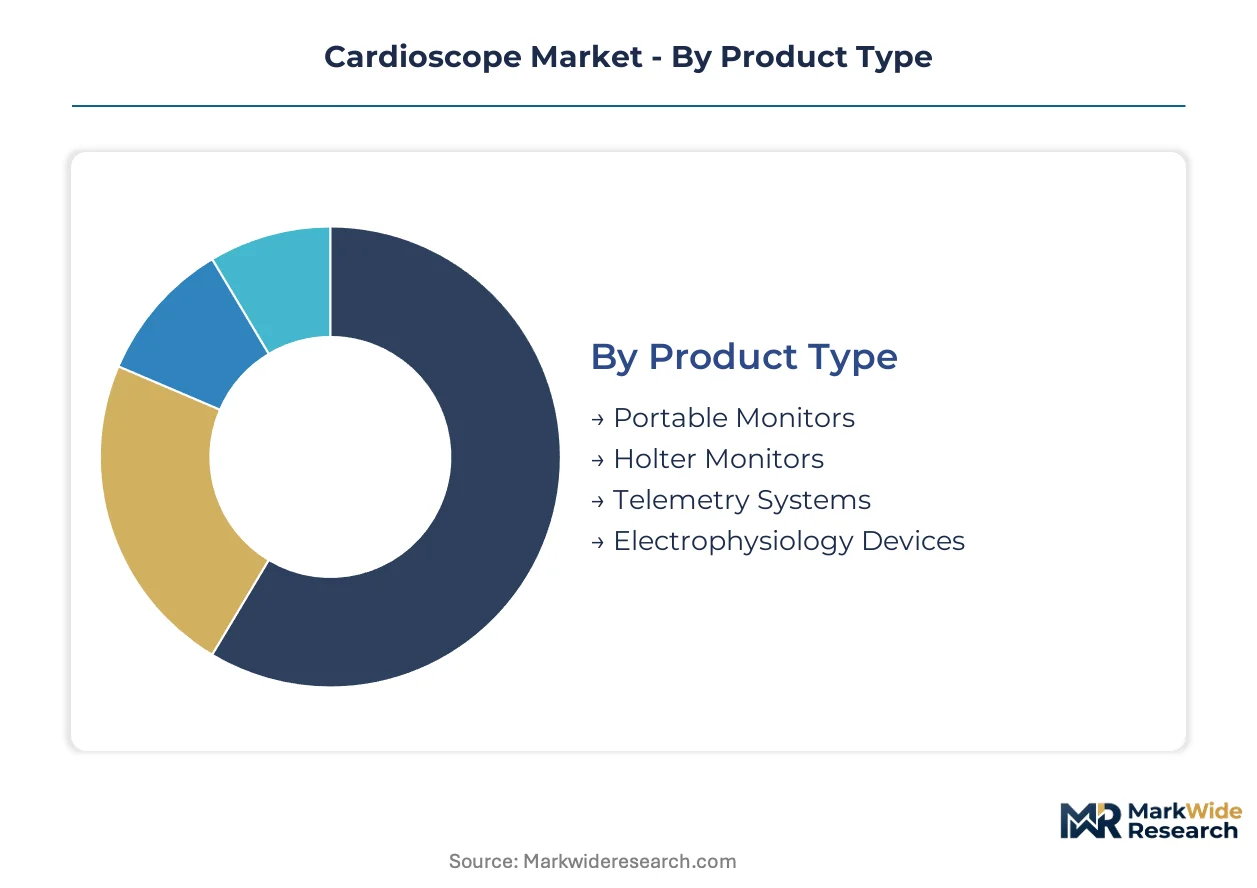
Cardioscope segmentation reveals divergent capital requirements across hardware platforms, software architectures, and care delivery settings. Procurement committees evaluate total cost of ownership spanning device acquisition, integration engineering, and ongoing clinical training. Understanding these segment economics informs vendor positioning and R&D allocation decisions.
Product Type:
Capital intensity varies sharply across this category, with electrophysiology devices demanding multimillion-dollar lab investments while portable monitors require minimal infrastructure.
- Electrophysiology Devices:Three-dimensional mapping systems integrate catheter navigation, signal processing, and ablation energy delivery in integrated platforms. United States academic medical centers concentrate demand for these systems as electrophysiology procedure volumes expand beyond traditional hospital settings.
- Telemetry Systems:Continuous wireless monitoring infrastructure spans bedside receivers, central nursing stations, and cloud-based clinician dashboards. Germany's university hospitals drive procurement of enterprise-scale deployments supporting hundreds of concurrent patient connections.
- Portable Monitors:Battery-powered units with integrated displays serve point-of-care cardiac assessment. Ambulatory surgical centers favor these for preoperative screening and postoperative surveillance.
- Holter Monitors:Wearable recorders capture 24- to 48-hour ECG data for outpatient arrhythmia diagnosis. Japan's aging population generates sustained demand for extended monitoring alternatives.
Telemetry systems absorb the bulk of installed capacity; electrophysiology devices are expanding most quickly.
End User:
Customer type determines purchasing authority complexity, with hospital procurement committees imposing extended vendor qualification cycles compared to direct clinic acquisitions.
- Cardiology Clinics:Specialized outpatient facilities prioritize diagnostic throughput and EHR integration over enterprise networking features. These settings favor compact Holter and event monitor configurations.
- Ambulatory Surgical Centers:Outpatient procedure volumes in the United States drive demand for rapid-deployment monitoring with wireless telemetry. Capital budgets here favor leased equipment over outright purchase.
- Emergency Departments:High-acuity triage environments require defibrillator-integrated cardioscope platforms with immediate arrhythmia alerting. FDA 510(k) clearance for emergency use indications shapes vendor selection.
- Homecare Settings:Remote patient monitoring reimbursement expansion supports wearable telemetry adoption. Japan's Ministry of Health, Labour and Welfare coverage decisions directly influence device configuration requirements.
Cardiology clinics represent the largest installed base; ambulatory surgical centers show the steepest expansion trajectory.
Technology:
Software-enabled capabilities command recurring revenue streams that hardware-centric segments cannot match, reshaping R&D investment priorities.
- AI-Based Analytics:Deep learning algorithms automate arrhythmia classification and risk stratification from raw ECG signals. United States academic centers deploy FDA-cleared modules for preliminary interpretation workflow acceleration.
- Wireless Technology:Bluetooth Low Energy and proprietary radio protocols enable real-time streaming from wearable sensors to clinical dashboards. FCC equipment authorization requirements govern transmission power and spectrum allocation.
- Cloud Storage:HIPAA-compliant and GDPR-aligned data architectures support longitudinal patient record accumulation. Amazon Web Services and Microsoft Azure health-cloud environments dominate infrastructure procurement.
- Advanced Imaging:Intracardiac echocardiography integration with electroanatomical mapping enables single-procedure comprehensive assessment. Premium positioning in electrophysiology labs sustains margin concentration.
Wireless technology underpins the majority of new deployments; AI-based analytics is gaining share fastest.
Application:
Clinical use case specificity determines sensor configuration, algorithm training data requirements, and regulatory clearance pathway selection.
- Arrhythmia Detection:Algorithm development targets atrial fibrillation, ventricular tachycardia, and conduction abnormality identification with high negative predictive value. United States emergency departments prioritize sensitivity over specificity for critical event capture.
- Cardiac Monitoring:Continuous electrical signal surveillance supports perioperative management and intensive care unit staffing optimization. Germany's hospital networks standardize on interoperable telemetry platforms.
- Patient Management:Longitudinal data accumulation enables medication titration and lifestyle intervention guidance. Japan's home-based care reimbursement expansion supports remote monitoring service models.
- Heart Failure Assessment:Impedance monitoring and multi-sensor fusion track fluid status and hemodynamic trends. These applications require implantable device integration for comprehensive data capture.
Cardiac monitoring commands the greatest installed base; arrhythmia detection is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silver-silver chloride electrode manufacturing clusters in Southeast Asia supply component feedstock for cardioscope assembly across major demand centers. Device procurement concentrates where cardiac procedure volumes and remote monitoring reimbursement policies align.
United States
Ambulatory surgical center expansion and Medicare reimbursement for remote patient monitoring drive hardware procurement. FDA 510(k) clearance pathways enable rapid algorithm updates for AI-native devices. Minneapolis anchors electrophysiology device development through concentrated medical technology infrastructure.
Germany
University hospital networks standardize on interoperable telemetry platforms for enterprise-scale deployments. EU MDR Article 10 post-market surveillance requirements extend certification timelines and evidence generation budgets. Baden-Württemberg hosts precision sensor manufacturing for electrode array supply chains.
Japan
Super-aging demographics generate sustained demand for home-based cardiac telemetry and wearable Holter alternatives. Ministry of Health, Labour and Welfare reimbursement expansion directly shapes device configuration requirements. Kansai region concentrates diagnostic imaging integration expertise for electrophysiology labs.
China
Domestic hospital procurement prioritizes cost-competitive portable monitors for tier-two and tier-three facility networks. NMPA regulatory harmonization with international standards accelerates approval timelines for predicate-based submissions. Yangtze River Delta clusters medical device contract manufacturing capacity.
India
Private cardiology clinic chains drive demand for compact Holter configurations with EHR integration capabilities. CDSCO medical device rules enforcement tightens quality management system requirements for imported devices. Maharashtra concentrates diagnostic equipment distribution infrastructure for western and southern markets.
Cardioscope Market Competitive Landscape
Global majors compete with regional champions across technology licensing and distribution reach. The vendor base stratifies into three tiers: diversified conglomerates with captive healthcare divisions, pure-play cardiac monitoring specialists, and emerging regional fabricators serving price-sensitive procurement channels. Two dominant competitive moves define current positioning: backward integration into sensor manufacturing to secure electrode supply, and strategic partnerships with cloud infrastructure providers to embed analytics capabilities.
Within the diversified healthcare technology tier, Abbott Laboratories and Medtronic Plc exemplify integrated platform strategies spanning implantable and external monitoring modalities. Koninklijke Philips N.V. occupies a position bridging diagnostic imaging and telemetry ecosystems. Among Asia-Pacific specialists, Nihon Kohden Corporation and Beijing Carejoy Technology Co., Ltd represent regional champions with concentrated domestic market penetration. Parker Hannifin Corp anchors industrial-to-medical crossover positioning through precision motion and control technologies. Boston Scientific Corporation and Schiller AG sit within the electrophysiology-focused specialist archetype, while Benaka Healthcare exemplifies emerging market fabrication capabilities serving cost-optimized procurement segments.
| Leading Market Players |
|---|
| Parker Hannifin Corp |
| Benaka Healthcare |
| Beijing Carejoy Technology Co., Ltd |
| Abbott Laboratories |
| Medtronic Plc |
| Boston Scientific Corporation |
| Koninklijke Philips N.V. |
| Nihon Kohden Corporation |
| Schiller AG |
| Others |
Value Network & Pricing Analysis
Silver-silver chloride electrode costs cascade from Southeast Asian manufacturing clusters through three distinct pricing tiers, with raw material volatility in sensor-grade silver concentrates margin pressure on mid-tier device OEMs while premium electrophysiology systems absorb input fluctuations through service-bundled contracts.
Pricing Analysis
Warranty and algorithm update bundling separate premium electrophysiology platforms from unbundled portable monitor transactions. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, ISO 13485 certification status, and after-sales clinical training inclusion. Cost compression in economy-tier Holter monitors intensifies because of consumer-grade wearable substitution from Apple and similar entrants. Ambulatory surgical centers exhibit highest price sensitivity; United States academic medical centers show lowest sensitivity due to bundled ecosystem procurement.
Supply Chain Analysis
Direct-to-hospital distribution channels handle hyperscale demand from United States integrated delivery networks, bypassing traditional medical device distributors. Silver-silver chloride sensor manufacturing concentrates in Malaysia, Thailand, and Vietnam; assembly of finished devices centers on Germany, the United States, and China. Electrode array supply draws from single-source Southeast Asian clusters, creating tariff exposure from regional trade policy shifts. Distribution runs through specialized cardiac monitoring sales teams with attached clinical training capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around full-stack ecosystem vendors as FDA cybersecurity guidance and EU MDR clinical evidence thresholds force capital-constrained mid-tier manufacturers toward partnership or exit.
For Market Incumbents: Lock in electrode supply through backward integration into silver-silver chloride sensor manufacturing or long-term offtake agreements with Southeast Asian suppliers. Secure cloud-native analytics partnerships with AWS or Azure health-compliant environments to defend against AI-native entrants lacking infrastructure scale. Consumer-grade wearable substitution from Apple Watch and photoplethysmography devices threatens low-acuity monitoring segments.
For New Entrants and Emerging Players: Capture Japan's home-based cardiac telemetry expansion as Ministry of Health, Labour and Welfare reimbursement creates white-space demand for wearable Holter alternatives. Target ambulatory surgical center procurement in the United States, where leased equipment models lower capital barriers and rapid-deployment wireless systems address unmet workflow needs. Direct-to-hospital sales teams with embedded clinical training support offer the strongest go-to-market angle against distributor-dependent incumbents.
For Investors and Strategic Acquirers: FDA premarket software security guidance issuance is the leading indicator that mid-tier manufacturers lacking specialized engineering resources will face forced consolidation or distressed sale scenarios. The five-to-ten year viability window favors acquisition of electrophysiology-focused specialists with installed telemetry bases and proprietary algorithm portfolios. Watch for notified body capacity constraints in EU MDR certification as the signal that European market access timelines will extend, compressing valuations for unprepared targets.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Expedited predicate-based submissions accelerate algorithm update deployment for AI-native cardioscope platforms. |
| CE Marking Pathway | EU MDR Article 10 compliance extends evidence generation budgets but secures long-term European market access. |
| Hospital System Partnership | United States IDN ecosystem bundling commands preference over standalone device procurement in RFP processes. |
| Software Companion Development | AI-ECG multimodal fusion with echocardiographic imaging enables single-device comprehensive electrophysiology lab assessment. |
| Reimbursement Strategy | Japan's Ministry of Health, Labour and Welfare coverage decisions directly shape home-based telemetry device configurations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) premarket notification databases, EU MDR notified body certification records, and Medicare reimbursement code updates provided validation sources. Bottom-up device shipment modeling and top-down healthcare expenditure allocation triangulated market sizing across the analysis window.
Granularity-level modeling operated at product type, end user, technology, and application dimensions, with additional geographic regulatory cluster segmentation for United States, Germany, Japan, China, and India. CAGRs derived from trend extrapolation of historical procedure volumes, reimbursement policy trajectories, and technology adoption curves. Cloud infrastructure maturation rates and AI algorithm validation timelines served as cardioscope-specific forecast inputs throughout the projection horizon.
The model holds under stable FDA and EU MDR regulatory frameworks; deviation in cybersecurity certification requirements or notified body capacity constraints would shift growth trajectories. Forecasts reflect documented assumptions regarding reimbursement expansion, cloud infrastructure reliability, and electrophysiologist training pipeline capacity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Smart Bed Market
Medical Devices
Mexico Electrocardiograph (ECG) Market
Medical Devices
Band Ligators Market
Medical Devices
Foot Massage Machine Market
Medical Devices
Wearable Breast Pumps Market
Medical Devices
Manual Wheelchair Market
Medical Devices
Functional Electrical Stimulation Market
Medical Devices
France Contraceptive Devices Market
Medical Devices
Global Digital Dose Inhaler Market
Medical Devices
Prefilled Syringe Small Molecule Market
Medical Devices
Pleural Catheters Market
Medical Devices
Micro Syringes Market
Medical Devices
Ostomy Drainage Systems Market
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
Latin America Biomedical Sensors Market
Medical Devices
MIS Sacroiliac Joint Fusion Market