
 Global Capillary Blood Collection Devices Market | 2026-2036
Global Capillary Blood Collection Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Capillary Blood Collection Devices Market Foresight
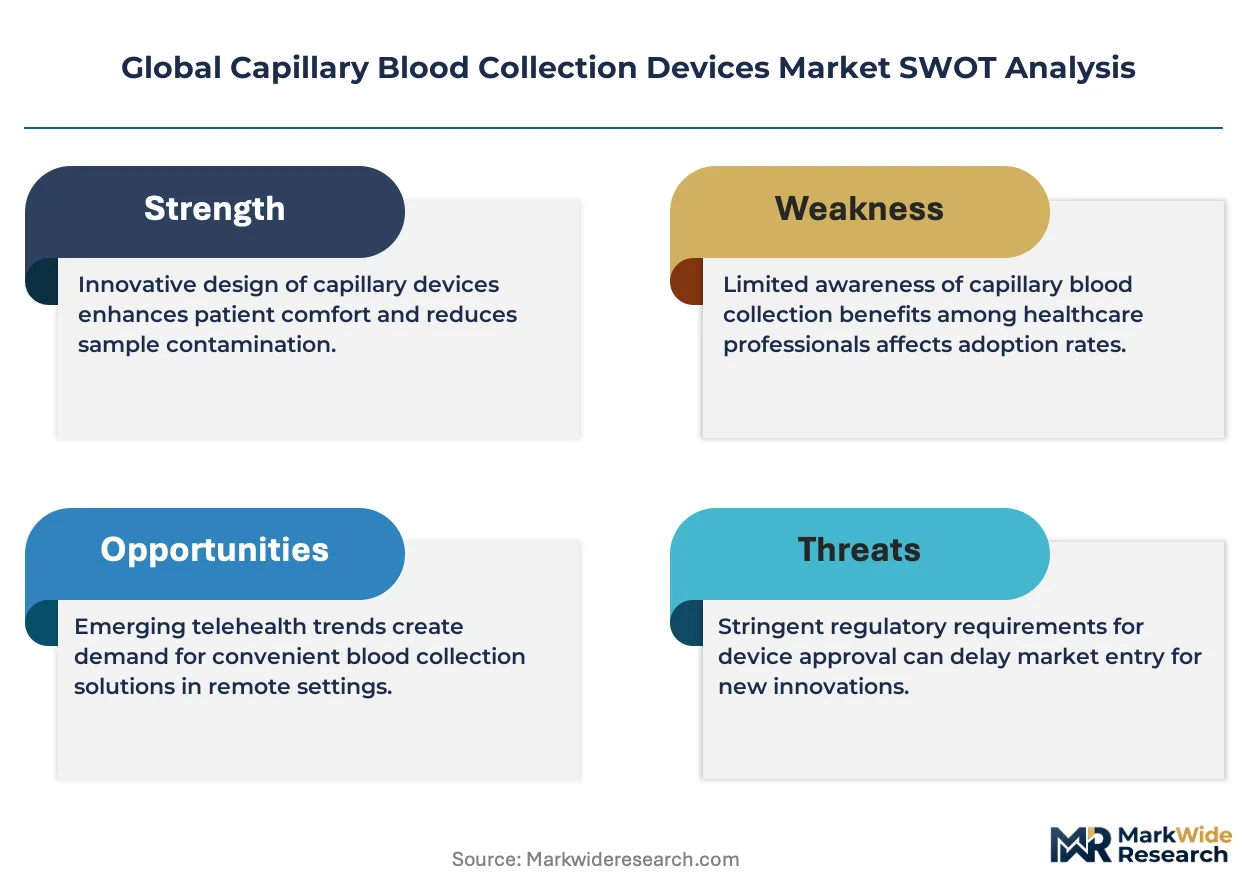
Project finance for automated lancet manufacturing lines is fragmenting competitive access, as smaller point-of-care suppliers gain capacity without owning fixed assets. Becton, Dickinson and Company leverages its integrated plastic molding network to sustain cost advantages across high-volume microcontainer output. Greiner Bio-One International GmbH anchors European supply through specialized glass and polymer capillary tube production. SARSTEDT AG & Co. KG differentiates via precision-engineered safety-lancet systems for neonatal and pediatric applications.
Capillary blood collection devices comprise sterile instruments engineered to extract small-volume blood samples—typically 20–500 microliters—through skin puncture or fingertip incision, with lancets specified by blade depth and gauge, microtainers designed for serum/plasma separation, and capillary tubes calibrated for anticoagulant fill ratios. These devices serve diagnostic workflows where venipuncture is impractical, enabling glucose monitoring, newborn metabolic screening, and infectious disease serology at decentralized sites. Lancets command the largest product share due to universal diabetes management protocols, while microtainers represent the fastest-expanding category as laboratories automate high-throughput hematology processing. Point-of-care clinics emerge as the most dynamic end-user channel, overtaking traditional hospital phlebotomy for routine HbA1c and lipid panel testing.
The FDA enforces 21 CFR quality standards for blood collection device sterility and sharps injury prevention, while the EU Medical Device Regulation mandates clinical evidence for lancet safety claims and traceability across supply chains. ISO 15197 governs glucose monitoring system accuracy, indirectly constraining lancet performance specifications that affect sample integrity. China's NMPA accelerates local registration for polymer-based microsampling devices under revised Class II medical device pathways. Stakeholders must monitor evolving harmonization between FDA breakthrough device criteria and EMA parallel scientific advice, as divergent evidentiary requirements threaten launch synchronization for next-generation integrated sampling platforms.
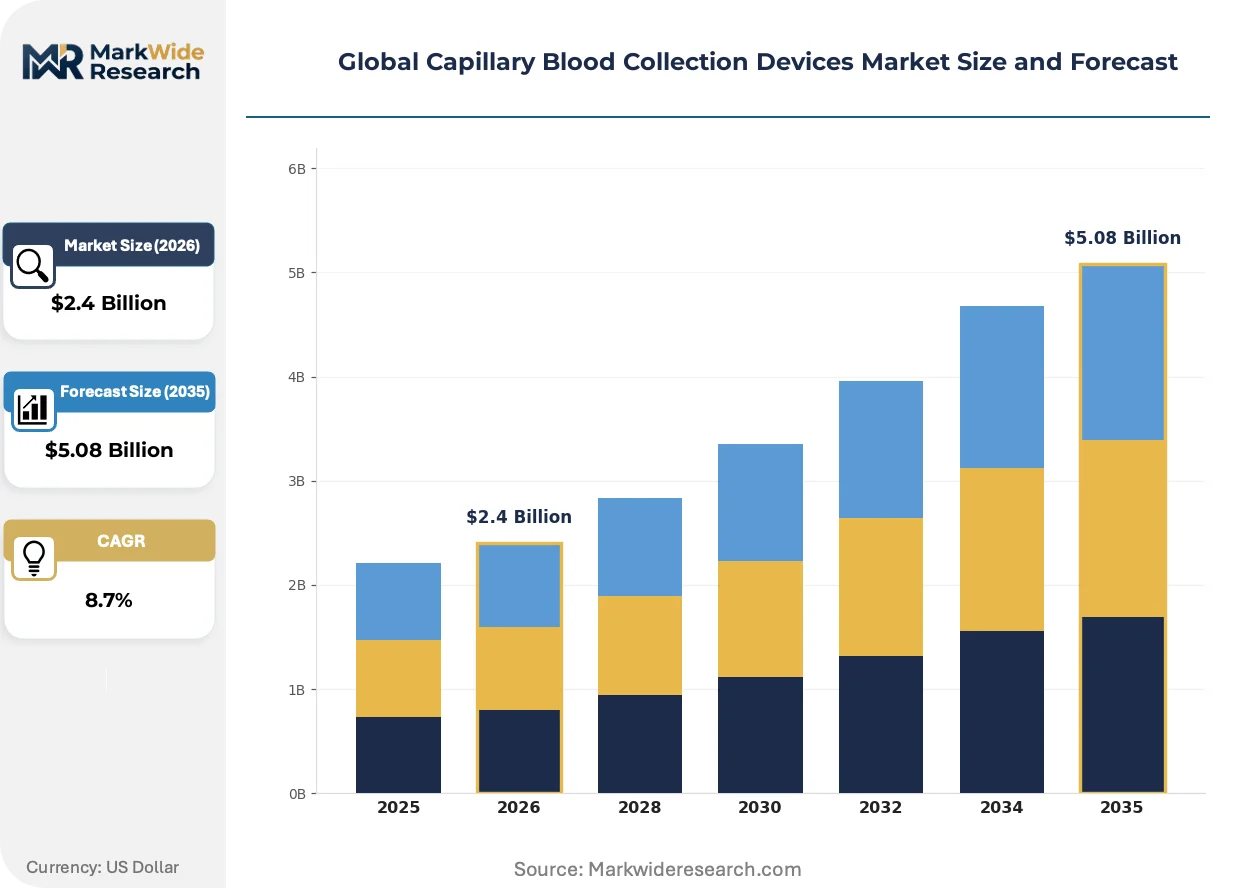
Market Dynamics
Project finance for automated lancet manufacturing lines is fragmenting competitive access, as smaller point-of-care suppliers gain capacity without owning fixed assets. Becton, Dickinson and Company leverages its integrated plastic molding network to sustain cost advantages across high-volume microcontainer output. Greiner Bio-One International GmbH anchors European supply through specialized glass and polymer capillary tube production. SARSTEDT AG & Co. KG differentiates via precision-engineered safety-lancet systems for neonatal and pediatric applications.
Growth Catalysts
- Point-of-care clinic expansion in rural India:Government health missions deploy lancet-based microsampling kits to bypass centralized phlebotomy infrastructure, accelerating device penetration in tier-3 cities and village clusters.
- FDA's updated blood-borne pathogen standards:Tightened material specifications for plastic capillary tubes force incumbent suppliers to upgrade sterilization protocols, creating replacement demand across hospital networks.
- Automated hematology processing:High-throughput laboratories in Germany's diagnostic corridor spanning Mannheim, Heidelberg, and Freiburg drive microtainer volume as pre-analytical automation standardizes.
Market Restraints
- Medical-grade polymer feedstock concentration:Specialty cyclo-olefin polymer supply concentrates among three Asian resin compounders, exposing device manufacturers to input cost volatility and allocation risk.
- EU MDR clinical evidence requirements:Safety-lancet safety claims now demand prospective injury-prevention studies, extending regulatory timelines and freezing SKU rationalization for mid-tier suppliers.
- Venous blood draw substitution in affluent markets:Ultra-low-volume vacuum tube technology from integrated diagnostic platforms threatens capillary sampling relevance in premium hospital segments.
Strategic Opportunities
- Home-based metabolic monitoring:Direct-to-consumer HbA1c and lipid panel testing creates channel bypass potential, with pharmacy chains in Brazil and Mexico piloting subscription lancet replenishment models.
- China's NMPA Class II pathway acceleration:Revised registration timelines for polymer-based microsampling devices compress market entry barriers for foreign manufacturers with local manufacturing partners.
- Neonatal screening protocol expansion:WHO newborn metabolic screening guidelines drive demand for precision-engineered safety-lancets in Sub-Saharan African public health programs.
Industry Challenges
- ISO 15197 glucose system integration:Lancet performance specifications must now demonstrate sample integrity correlation with meter accuracy, requiring cross-functional metrology capabilities rare among pure-play device suppliers.
- Legacy hospital phlebotomy workflow inertia:Nursing staff training protocols and electronic health record integration create switching friction even where capillary methods reduce patient wait times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Capillary Blood Collection Devices Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lancets, Microtainers, Capillary Tubes, Slide Collection Cards, Adhesive Patches Application: Diabetes Monitoring, Neonatal Screening, Infectious Disease Testing, Hematology Analysis, Therapeutic Drug Monitoring End User: Diagnostic Laboratories, Blood Banks, Research Institutions, Point-of-Care Clinics, Pharmacies Distribution Channel: Direct Sales, Online Retailers, Medical Distributors, Hospital Supply Chains, Pharmacy Chains |
| Companies Covered | Becton, Dickinson and Company, Greiner Bio-One International GmbH, SARSTEDT AG & Co. KG, Terumo Medical Corp., B. Braun Melsungen AG, Abbott Laboratories, Cardinal Health, Improve Medical, Retractable Technologies Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Capillary Blood Collection Devices Market Shifts & Advancements
Capillary blood collection devices comprise sterile instruments engineered to extract small-volume blood samples—typically 20–500 microliters—through skin puncture or fingertip incision. Lancets specified by blade depth and gauge, microtainers designed for serum/plasma separation, and capillary tubes calibrated for anticoagulant fill ratios now face technology and regulatory inflection points.
Silicone-coated lancet blades reduce puncture force variance and tissue trauma. Pediatric end-users and geriatric diabetes management programs in Japan and South Korea specify these surfaces to improve compliance. The technology is migrating from premium safety-lancet SKUs toward standard product lines as coating costs compress below three cents per unit.
REACH substance restrictions on phthalate plasticizers in polymer capillary tubes force compounders to validate alternative flexibilizers. German manufacturers face the tightest compliance deadlines, with Heidelberg-area suppliers accelerating bio-based polymer pilot programs. Glass capillary tube demand revives as laboratories seek regulatory certainty over material substitution risk.
Subscription replenishment models for lancet consumables displace hospital purchasing consortium dominance. Pharmacy chains and telehealth platforms in the United States and Brazil now bundle monthly lancet shipments with glucose meter data analytics. This channel shift concentrates volume among logistics-integrated distributors and erodes traditional medical device distributor margins.
Global Capillary Blood Collection Devices Market Segmentation
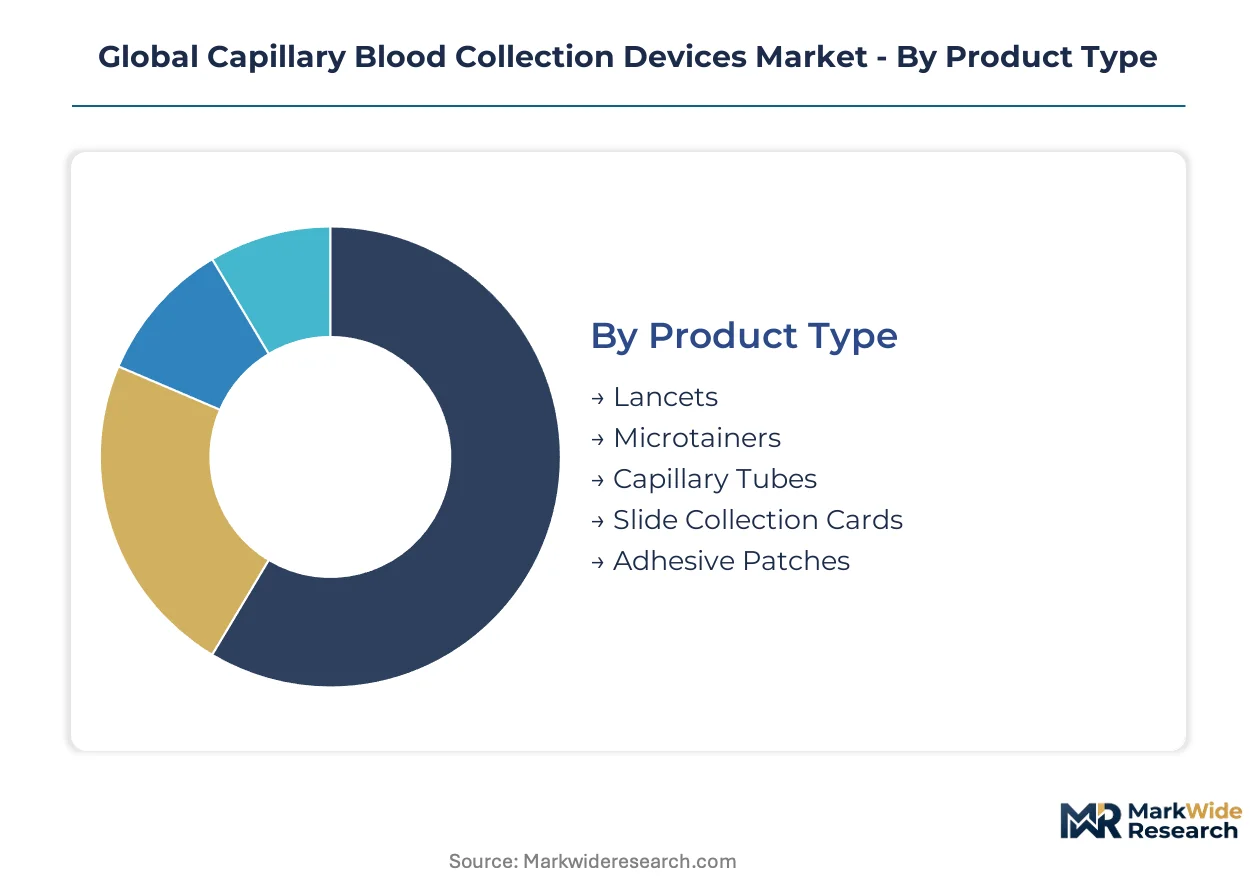
Device specification varies sharply across clinical workflows. Lancet blade geometry, microtainer additive formulations, and capillary tube anticoagulant calibrations each map to distinct diagnostic protocols and reimbursement pathways.
Product Type:
Use-case spectrum spans chronic disease management, newborn metabolic screening, and decentralized infectious disease surveillance.
- Lancets:Spring-loaded or pressure-activated devices with 28-33 gauge blades and 0.8-2.0mm penetration depths. Diabetes management protocols in India's tier-3 cities and village clusters drive volume through government health mission deployments.
- Microtainers:Polypropylene containers with serum separator gel or EDTA/heparin coatings, engineered for 250-500 microliter draws. Automated hematology processing in Germany's Mannheim-Heidelberg-Freiburg diagnostic corridor accelerates adoption as laboratories standardize pre-analytical workflows.
- Capillary Tubes:Glass or polymer tubes calibrated for precise anticoagulant fill ratios, typically heparin or EDTA-coated.
- Slide Collection Cards:Dried blood spot matrices for remote sampling and postal transport to centralized laboratories.
- Adhesive Patches:Microneedle arrays or passive collection membranes for continuous or minimally invasive sampling.
Established volume favors lancets; emerging adoption favors microtainers.
Application:
Clinical utility concentrates where venipuncture access is limited or sample volume must be minimized.
- Diabetes Monitoring:HbA1c and glucose self-monitoring protocols. Pharmacy chains in Brazil and Mexico pilot subscription replenishment models that bypass traditional hospital purchasing.
- Neonatal Screening:Metabolic and genetic disorder detection via heel-prick sampling. WHO guideline expansion across Sub-Saharan African public health programs drives precision-engineered safety-lancet procurement.
- Infectious Disease Testing:HIV, hepatitis, and malaria serology at decentralized sites.
- Hematology Analysis:Complete blood count and coagulation profiling.
- Therapeutic Drug Monitoring:Immunosuppressant and antiepileptic level assessment.
Diabetes monitoring commands installed base; neonatal screening climbs the fastest.
End User:
Channel configuration determines sterility requirements, training protocols, and reimbursement complexity.
- Diagnostic Laboratories:High-throughput facilities with automated processing lines. Germany's diagnostic corridor laboratories standardize microtainer specifications to reduce pre-analytical variation.
- Point-of-Care Clinics:Decentralized sites with limited phlebotomy infrastructure. Rural India government health missions deploy lancet-based microsampling kits to replace centralized blood draws.
- Blood Banks:Donor screening and infectious disease marker testing.
- Research Institutions:Clinical trial sample collection and biomarker discovery.
- Pharmacies:Retail channels with direct-to-consumer testing and subscription logistics.
Laboratories anchor procurement volume; point-of-care clinics gain share fastest.
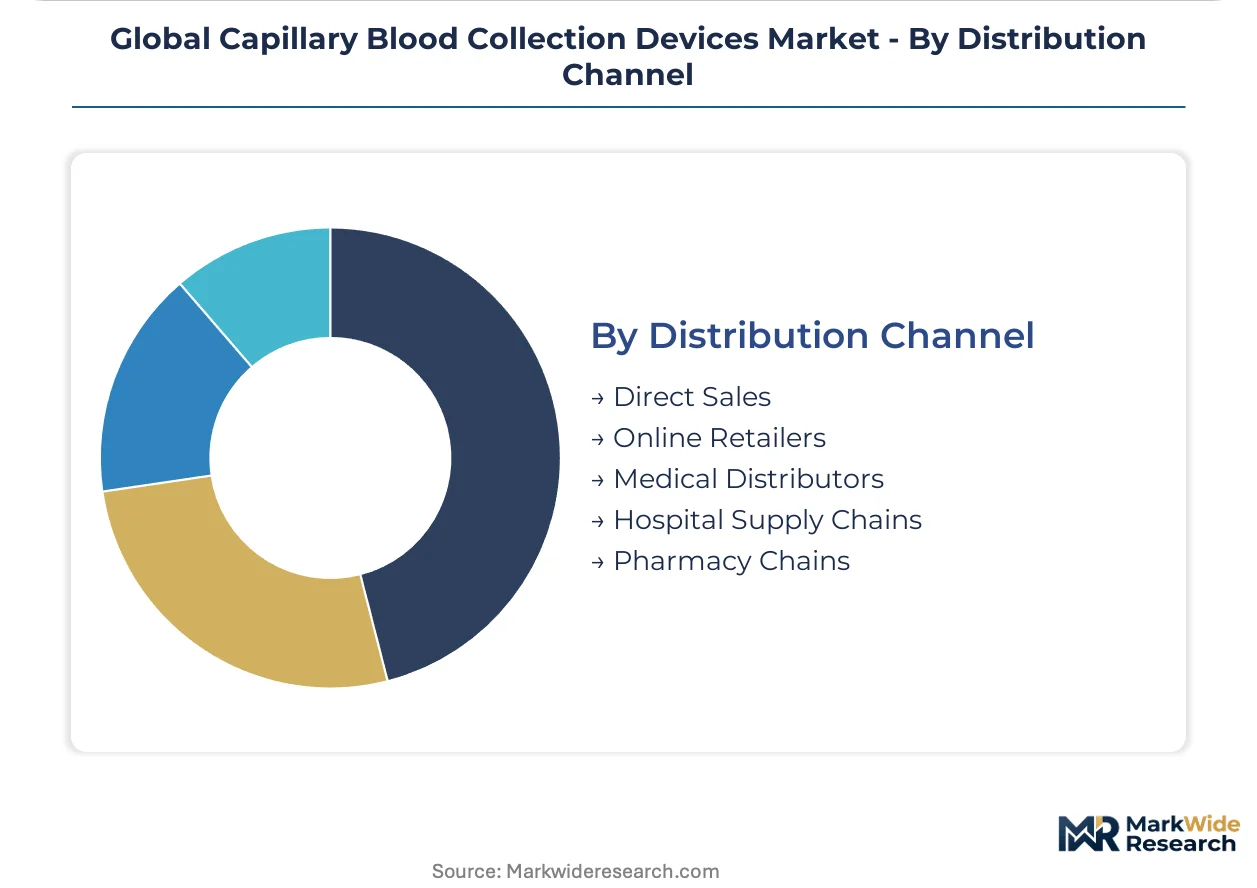
Distribution Channel:
Logistics integration separates high-volume institutional supply from emerging consumer-direct pathways.
- Direct Sales:Manufacturer contracts with hospital networks and laboratory chains. Becton, Dickinson and Company leverages integrated plastic molding for cost-advantaged microcontainer supply.
- Medical Distributors:Regional warehousing and sterile supply chain management. Greiner Bio-One International GmbH anchors European distribution through specialized glass and polymer tube production.
- Online Retailers:E-commerce platforms for home-use lancet and meter replenishment.
- Hospital Supply Chains:Group purchasing organization contracts with formulary restrictions.
- Pharmacy Chains:Retail networks with subscription bundling and data analytics integration.
Direct sales dominate contract value; pharmacy chains show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government health missions in rural India subsidize lancet-based microsampling kits to bypass centralized phlebotomy infrastructure, while Germany's diagnostic corridor laboratories standardize microtainer specifications for automated hematology processing. FDA material specification updates and EU MDR clinical evidence requirements reshape procurement protocols across hospital networks. China's NMPA accelerates polymer-based device registrations under revised Class II pathways.
United States
Pharmacy chains and telehealth platforms pilot subscription lancet replenishment models bundled with glucose meter data analytics, bypassing traditional hospital purchasing consortiums. FDA enforces 21 CFR quality standards for sterility and sharps injury prevention, tightening compliance timelines for safety-lancet suppliers. Boston-area diagnostic laboratories integrate capillary sampling into decentralized HbA1c and lipid panel workflows.
Germany
High-throughput laboratories across the Mannheim-Heidelberg-Freiburg diagnostic corridor drive microtainer volume as pre-analytical automation standardizes. REACH substance restrictions on phthalate plasticizers force Heidelberg-area compounders to accelerate bio-based polymer pilot programs. Greiner Bio-One anchors European glass and polymer capillary tube supply from specialized production facilities in the region.
India
Point-of-care clinics in tier-3 cities and village clusters deploy lancet-based microsampling kits through national health mission programs, replacing centralized blood draws. CDSCO aligns device registration requirements with international standards to accelerate quality-assured imports. Maharashtra and Karnataka host the largest concentration of diagnostic laboratory chains expanding capillary-based testing infrastructure.
China
NMPA compresses registration timelines for polymer-based microsampling devices under revised Class II medical device pathways, lowering market entry barriers for foreign manufacturers with local partners. MIIT promotes domestic production of medical-grade cyclo-olefin polymers to reduce resin import dependency. Yangtze River Delta diagnostic equipment manufacturers integrate capillary collection modules into automated hematology platforms.
Brazil
Pharmacy chains pilot direct-to-consumer HbA1c and lipid panel testing with subscription lancet replenishment models, creating channel bypass opportunities outside hospital networks. ANVISA strengthens post-market surveillance for imported safety-lancet devices following regional adverse event reporting. São Paulo and Minas Gerais concentrate the largest diagnostic laboratory chains adopting capillary-based metabolic screening protocols.
Global Capillary Blood Collection Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. Hospital purchasing consortiums and group purchasing organizations concentrate contract value among integrated distributors, while point-of-care clinics and pharmacy chains enable smaller suppliers to bypass traditional intermediaries. Three archetypes dominate: vertically integrated plastic molding networks, specialized glass and polymer tube fabricators, and precision-engineered safety-device specialists. Competitive moves center on automated manufacturing line financing through project-based arrangements and sterilization protocol upgrades to meet tightened blood-borne pathogen standards.
Among integrated medical technology conglomerates, Becton, Dickinson and Company and Abbott Laboratories occupy positions defined by captive plastic molding capacity and glucose monitoring system integration. Specialized European manufacturers exemplify the precision-device archetype: Greiner Bio-One International GmbH represents glass and polymer capillary tube specialization, while SARSTEDT AG & Co. KG anchors safety-lancet engineering for neonatal and pediatric applications. These named entities sit within broader competitive tiers rather than defining them exclusively.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Greiner Bio-One International GmbH |
| SARSTEDT AG & Co. KG |
| Terumo Medical Corp. |
| B. Braun Melsungen AG |
| Abbott Laboratories |
| Cardinal Health |
| Improve Medical |
| Retractable Technologies Inc |
| Others |
Supply & Pricing Matrix
Overcapacity in Asian medical-grade polymer compounding is compressing resin pricing and forcing device manufacturers to absorb sterilization protocol upgrade costs rather than pass through to hospital purchasers. This utilization dynamic concentrates pricing power among integrated molders with captive feedstock while fragmenting margin recovery options for pure-play device suppliers dependent on spot resin markets.
Pricing Analysis
Certification level (FDA 21 CFR-grade versus CE-marked standard tier) creates the primary spread between premium safety-lancets and commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels maps to sterilization assurance depth and traceability documentation depth. Pricing pressure stems from REACH phthalate substitution costs concentrated among Heidelberg-area compounders facing compressed compliance timelines. Hospital purchasing committees exhibit lowest price sensitivity for neonatal safety-lancets where liability exposure dominates procurement criteria, while point-of-care clinics in rural India prioritize unit economics over certification tier.
Supply Chain Analysis
Medical-grade cyclo-olefin polymer feedstock concentrates among South Korean, Japanese, and Chinese resin compounders, exposing device manufacturers to allocation risk during semiconductor-industry demand spikes. Specialized glass capillary tube production draws from German and Czech fabrication clusters, while precision lancet blade stamping rests on Swiss and Japanese tooling networks. Single-source vulnerability in phthalate-free flexibilizer chemistry threatens polymer tube supply continuity as REACH deadlines accelerate. Distribution runs through hospital group purchasing organizations in North America and specialized medical distributors in Europe, with pharmacy chains and telehealth platforms emerging as direct-to-consumer bypass channels in Brazil and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capillary blood collection devices are shifting toward platform-economics dynamics as glucose meter data analytics and subscription replenishment models create interoperability dependencies between hardware consumables and software ecosystems.
For Market Incumbents: Harden sterilization protocol differentiation against mid-tier competitors by accelerating FDA breakthrough device qualification for integrated sampling platforms. Defend channel position through backward integration into medical-grade polymer compounding or exclusive offtake agreements with Yangtze River Delta resin suppliers. Lock in hospital system partnerships via electronic health record integration investments that raise switching costs for nursing staff workflows.
For New Entrants and Emerging Players: Build out microtainer supply capabilities targeting Germany's Mannheim-Heidelberg-Freiburg diagnostic corridor where automated hematology standardization drives specification-sensitive procurement. Capture share in Brazil's pharmacy chain subscription channel where incumbent distributor relationships remain underdeveloped. Lead with silicone-coated lancet offerings positioned for pediatric and geriatric compliance advantages in Japanese and South Korean diabetes management programs.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because project finance fragmentation for automated lancet manufacturing is creating distressed asset opportunities among capacity-constrained mid-tier suppliers. Target precision-engineered safety-device specialists with neonatal regulatory dossiers and established WHO procurement relationships. Monitor NMPA Class II registration acceleration timelines as the inflection signal for China market entry viability.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Qualification | Accelerates review timelines for integrated capillary sampling platforms with glucose meter interoperability. |
| Backward Integration into Polymer Compounding | Captures REACH compliance cost recovery through in-house phthalate-free flexibilizer formulation control. |
| Hospital EHR Integration Investment | Raises workflow switching costs and secures preferred vendor status in GPO contract renewals. |
| Pharmacy Chain Subscription Partnership | Bypasses traditional distributor margins and captures direct-to-consumer replenishment economics in Brazil. |
| WHO Prequalification for Neonatal Safety-Lancets | Unlocks public health procurement across Sub-Saharan African metabolic screening program expansions. |
Research Methodology
Cross-validation between primary interviews with hospital purchasing committee members, GPO contracts managers, and biomedical engineers anchors the qualitative findings on procurement workflow friction and sterilization protocol requirements. Secondary validation draws from FDA 510(k) filings, EUDAMED device registrations, CDSCO import notifications, and hospital procurement database extracts. Bottom-up triangulation across lancet, microtainer, and capillary tube unit economics converges with top-down diagnostic laboratory capital expenditure tracking across Germany, India, and the United States.
Calibration against historical capacity utilization rates in medical-grade polymer compounding and automated lancet manufacturing line deployment schedules shapes the projection framework. Segmentation dimensions span product type, application protocol, end-user channel configuration, and regional regulatory cluster. CAGRs derive from installed base erosion modeling for venipuncture-dependent workflows and penetration curve analysis for point-of-care clinic expansion. Cyclo-olefin polymer price elasticity and REACH compliance cost pass-through assumptions feed supply-side constraints.
Stress conditions across resin allocation disruption, EU MDR clinical evidence timeline extension, and vacuum tube technology substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts embed assumptions on government health mission subsidy continuity and NMPA registration pathway stability. Cross-checking against WHO newborn screening guideline implementation schedules and diagnostic laboratory automation capex surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Italy Minimally Invasive Surgery Devices Market
Medical Devices
Carotid Stents Market
Medical Devices
Human Anatomical Models Market
Medical Devices
Artificial Cornea and Corneal Implant Market
Medical Devices
Next Generation Infusion Pump Market
Medical Devices
Urine Collection Devices Market
Medical Devices
Asia-Pacific Electroencephalography Devices Market
Medical Devices
Portable OT Light Market
Medical Devices
Intravenous Stopcock Market
Medical Devices
Middle East and Africa Medical Device Reprocessing Market
Medical Devices
Penile Implants Market
Medical Devices
Medical Device Outsourcing Market
Medical Devices
Diode Laser Hair Removal Equipment Market
Medical Devices
Germany Contraceptive Devices Market
Medical Devices
US Contact Lenses Market
Medical Devices
Auto-Transfusion Systems Market