
 North America Invisible Orthodontics Market | 2026-2036
North America Invisible Orthodontics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Invisible Orthodontics Market Outlook
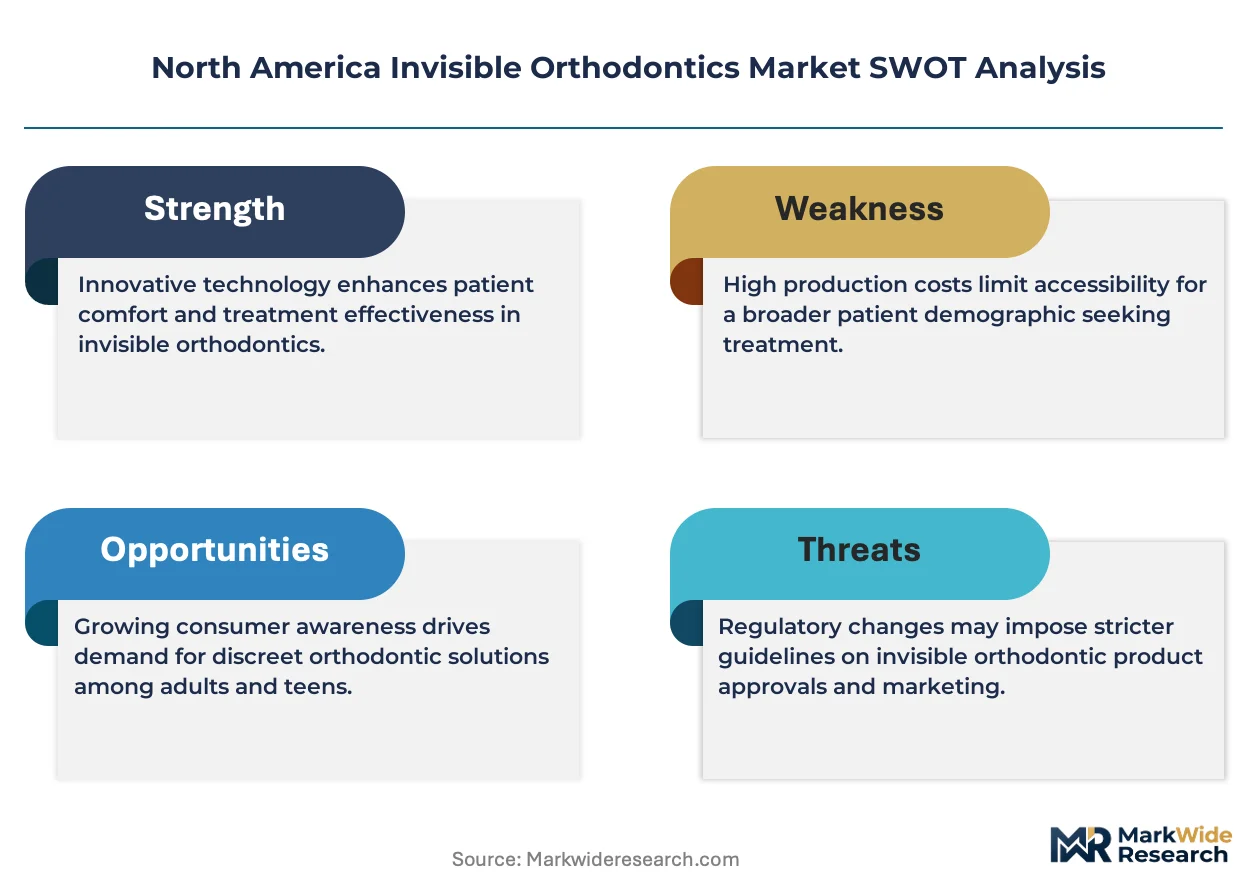
The North America invisible orthodontics sector is rebalancing between premium doctor-directed clear aligner protocols and direct-to-consumer commodity offerings. Align Technology sustains its technology leadership through proprietary intraoral scanning ecosystems and orthodontist-exclusive software. SmileDirectClub competes aggressively on price through remote treatment models, while Straumann Holding anchors the premium segment with its Straumann Group orthodontic portfolio.
Invisible orthodontics encompasses removable transparent polymer trays, lingual fixed appliances, and digitally planned tooth movement systems fabricated via thermoforming or direct 3D printing from biocompatible PETG or polyurethane materials, primarily serving aesthetic dental correction without visible metal components. Clear aligners dominate volume due to patient preference for removability and near-invisibility, though lingual braces retain margin strength among adult professionals demanding absolute concealment. Digital scanning and CAD/CAM treatment planning represent the fastest-expanding technology layer, displacing traditional polyvinyl siloxane impressions across orthodontic clinics and dental hospitals.
FDA 510(k) premarket notification requirements govern clear aligner material safety and mechanical performance in the United States, while Health Canada and COFEPRIS regulate parallel pathways for Canadian and Mexican market access respectively. The FTC monitors direct-to-consumer advertising claims, shaping how at-home aligner brands position treatment outcomes versus professionally supervised alternatives. Stakeholders must track evolving state dental board rulings on teledentistry scope, as these determinations will define competitive boundaries between remote and clinic-based delivery models.
Market Dynamics
The invisible orthodontics sector is bifurcating between orthodontist-supervised premium protocols and remote direct-to-consumer models, with state dental board rulings on teledentistry scope determining competitive boundaries between delivery channels.
Growth Catalysts
- FDA 510(k) Streamlining:The FDA's premarket notification pathway for clear aligner materials accelerates product entry timelines, enabling faster commercialization of biocompatible PETG and polyurethane tray systems across the United States.
- Teenager Demographic Expansion:Adolescent patients seeking aesthetic alternatives to metal braces now represent the fastest-growing patient segment, driving volume in suburban orthodontic clinics across California, Texas, and Florida.
- Digital Scanning Displacement:Intraoral scanning ecosystems are eliminating polyvinyl siloxane impressions from orthodontic workflows, reducing chair time and improving treatment planning precision in dental hospitals.
Market Restraints
- Raw Material Concentration:Medical-grade PETG and specialized polyurethane formulations depend on a limited supplier base concentrated in North American chemical manufacturing corridors, exposing aligner producers to input volatility.
- Technical Limitation:Complex tooth rotation and vertical movement cases exceed the biomechanical capabilities of thermoformed polymer trays, restricting clear aligner applicability to moderate malocclusions.
- Regulatory Friction:The FTC's monitoring of direct-to-consumer advertising claims constrains how remote aligner brands position treatment outcomes versus professionally supervised alternatives.
Strategic Opportunities
- Mexican Market Access:COFEPRIS regulatory pathways for clear aligner systems remain underpenetrated relative to United States saturation, offering first-mover positioning in Monterrey and Guadalajara dental markets.
- Lingual Appliance Convergence:CAD/CAM-designed lingual fixed appliances combining absolute concealment with digital precision capture unmet demand among adult professionals in Toronto and Vancouver financial districts.
- Direct 3D Printing:Photopolymerization technologies enabling same-day aligner fabrication eliminate thermoforming bottlenecks, creating channel innovation opportunities for same-visit delivery models.
Industry Challenges
- Orthodontist Training Bottleneck:Digital treatment planning proficiency requires specialized certification timelines that lag behind scanner deployment rates, constraining clinic throughput in high-demand metropolitan corridors.
- Software-Hardware Integration:Proprietary intraoral scanning ecosystems create interoperability friction with third-party CAD/CAM platforms, complicating multi-vendor technology stacks in group dental practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Invisible Orthodontics Market |
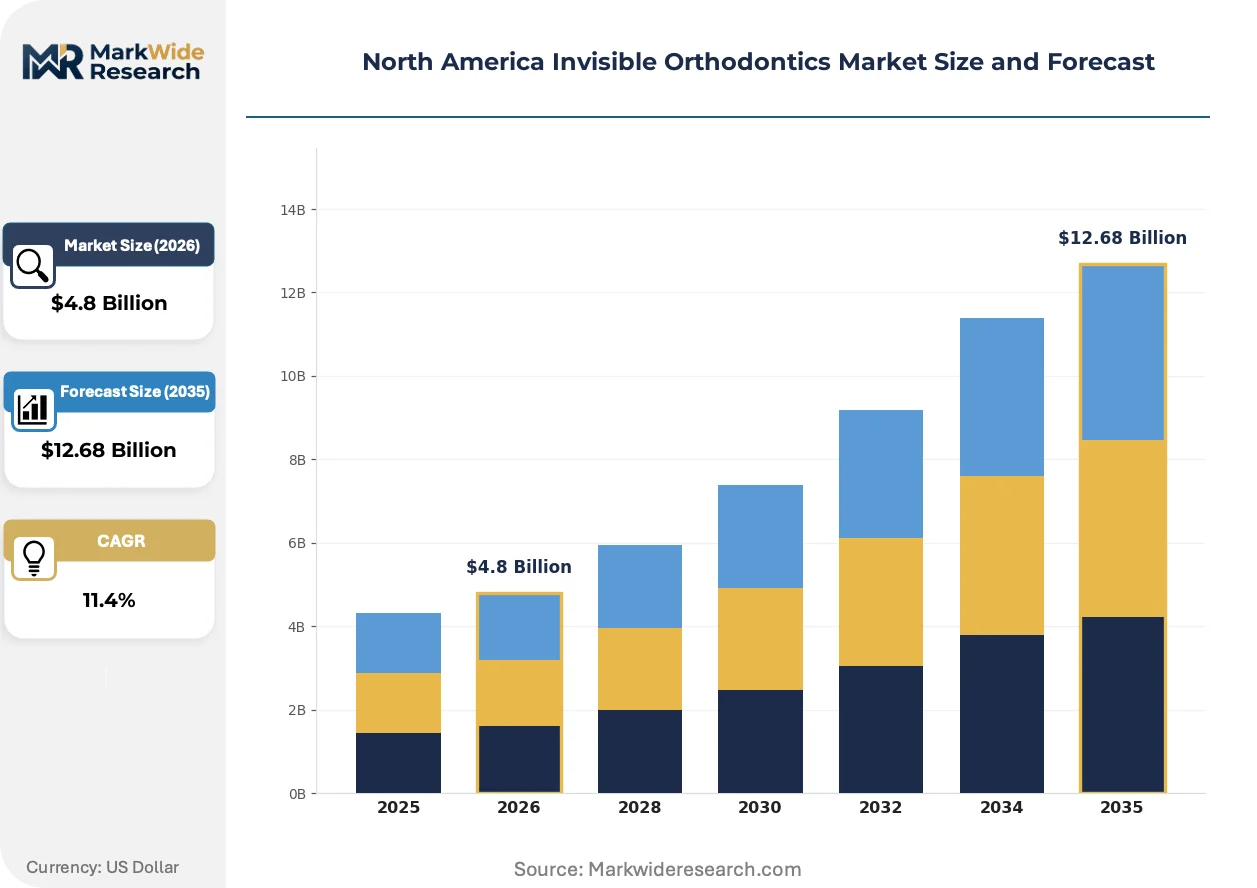
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Aligners, Lingual Braces, Removable Retainers, Fixed Appliances Technology: 3D Printing, Digital Scanning, CAD/CAM, Force Control End User: Orthodontic Clinics, Dental Hospitals, Home Care, Research Institutions Age Group: Adults, Teenagers, Children, Seniors |
| Companies Covered | Align Technology, 3M, Dentsply Sirona, Envista Holdings, Henry Schein, SmileDirectClub, Straumann Holding, Ormco Corporation, TP Orthodontics, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Invisible Orthodontics Market Strategic Shifts
Digital fabrication methods and regulatory clarity around remote delivery are compressing traditional orthodontic workflows while expanding addressable patient populations beyond conventional clinic boundaries.
Artificial intelligence-driven treatment planning software is unifying diagnostic imaging, tooth movement simulation, and manufacturing file generation into single-platform workflows. Mid-sized orthodontic groups in Dallas and Miami are adopting these systems at accelerating pace, compressing the traditional multi-appointment consultation cycle into same-day treatment initiation.
The FTC's evolving enforcement posture on teledentistry advertising claims is reshaping competitive positioning between remote and clinic-based providers. Direct-to-consumer brands must now substantiate outcome parity with orthodontist-supervised treatment, forcing documentation investments that favor established players with clinical trial infrastructure. California and Texas dental boards are responding with supplemental disclosure requirements for at-home impression kits.
Subscription-based aligner programs are displacing traditional fee-for-service pricing in younger patient segments. Dental service organizations in Florida are unbundling comprehensive treatment into monthly payment structures, with patient acquisition shifting from referral networks to social media channels. This pattern concentrates most visibly in metropolitan markets where smartphone penetration and digital payment adoption intersect with high aesthetic sensitivity.
North America Invisible Orthodontics Market Segmentation
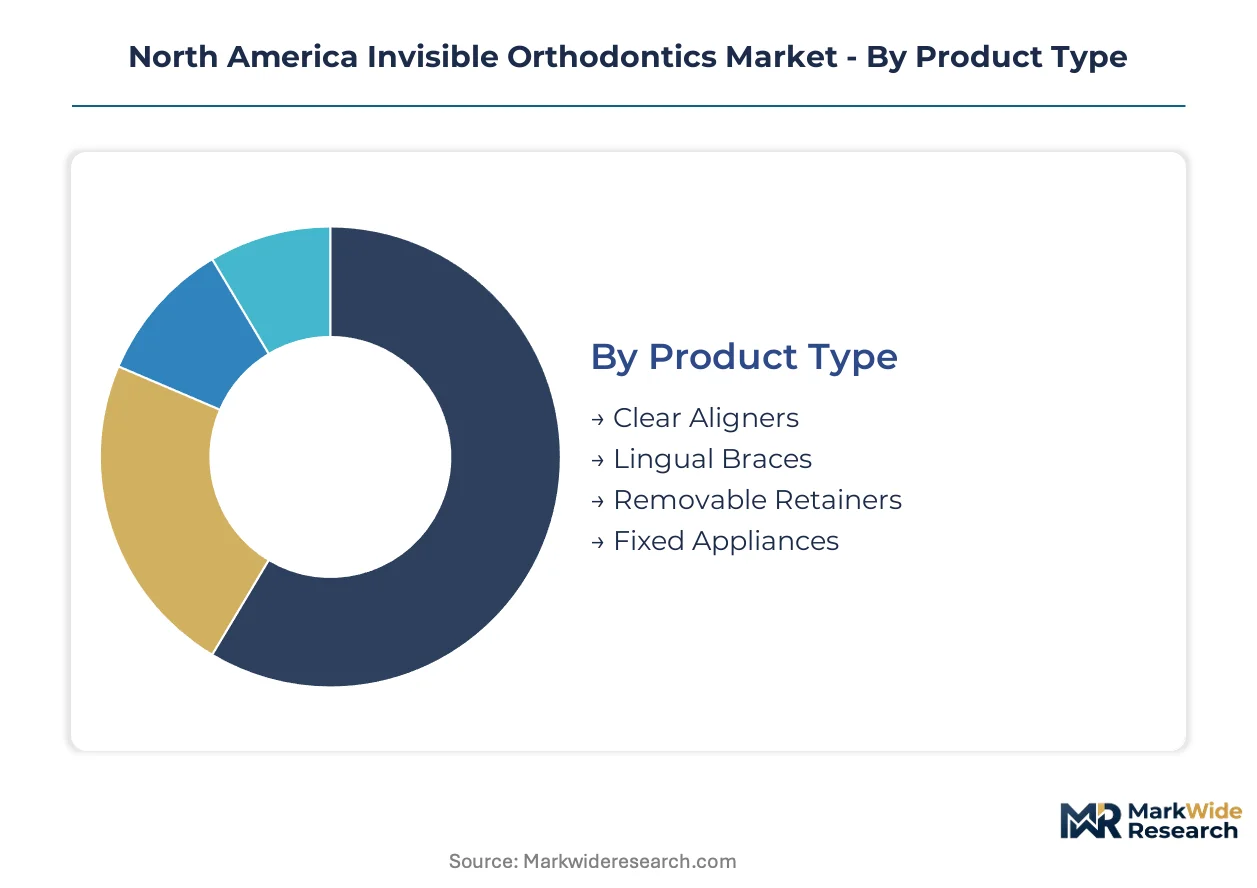
Segmentation reveals how invisible orthodontics manufacturers allocate R&D and manufacturing capacity across distinct technical and customer profiles. Supply chain configuration varies sharply between polymer-based removable systems and precision-machined fixed appliances.
Product Type:
Medical-grade polymer suppliers concentrate in Texas and Ohio chemical corridors, creating geographic clustering for thermoformed tray manufacturers versus machined lingual appliance producers.
- Clear Aligners:Transparent PETG or polyurethane trays fabricated via thermoforming or direct 3D printing from intraoral scan data. Demand concentrates in California suburban orthodontic clinics where teenager patient volume drives replacement tray throughput.
- Lingual Braces:CAD/CAM-machined fixed appliances bonded to tooth lingual surfaces for absolute concealment. Adult professionals in Toronto and Vancouver financial districts drive premium pricing for customized wire systems requiring specialized orthodontist certification.
- Removable Retainers:Post-treatment retention devices using similar polymer formulations as active aligners but with passive mechanical design.
- Fixed Appliances:Ceramic or composite bracket systems offering aesthetic compromise between metal visibility and lingual complexity.
Today's leader: Clear Aligners. Tomorrow's challenger: Lingual Braces.
Technology:
Cost tiers separate capital-intensive fabrication methods from diagnostic software layers, with hardware margins compressing faster than recurring software licensing.
- 3D Printing:Photopolymerization and material extrusion systems enabling same-day aligner fabrication chairside. Dallas and Miami dental service organizations deploy these systems to eliminate thermoforming bottlenecks and central lab shipping delays.
- Digital Scanning:Intraoral scanner ecosystems capturing sub-millimeter accuracy tooth morphology data. Scanner deployment rates in Florida orthodontic groups now exceed certified treatment planner availability, creating workflow friction.
- CAD/CAM:Computer-aided design and manufacturing software unifying diagnostic imaging with fabrication file generation.
- Force Control:Biomechanical simulation algorithms predicting optimal tooth movement sequences and attachment placement.
Volume concentrates in Digital Scanning. Margin expansion favors Force Control.
End User:
Customer type determines regulatory exposure and reimbursement complexity, with institutional buyers demanding outcome documentation that remote direct-to-consumer channels struggle to provide.
- Orthodontic Clinics:Specialist practices in California, Texas, and Florida metropolitan corridors where FDA 510(k)-cleared systems dominate and teenager patient acquisition drives volume. Clinic density in these states creates competitive pressure on per-case pricing.
- Dental Hospitals:Academic and institutional settings in Mexico City and Guadalajara where COFEPRIS regulatory pathways for clear aligner training programs remain underdeveloped relative to United States saturation.
- Home Care:Direct-to-consumer remote treatment models constrained by FTC advertising claim monitoring and state dental board teledentistry scope rulings.
- Research Institutions:University orthodontic departments driving clinical validation studies for AI-driven treatment planning algorithms.
Orthodontic Clinics anchor current revenue. Home Care faces regulatory headwinds.
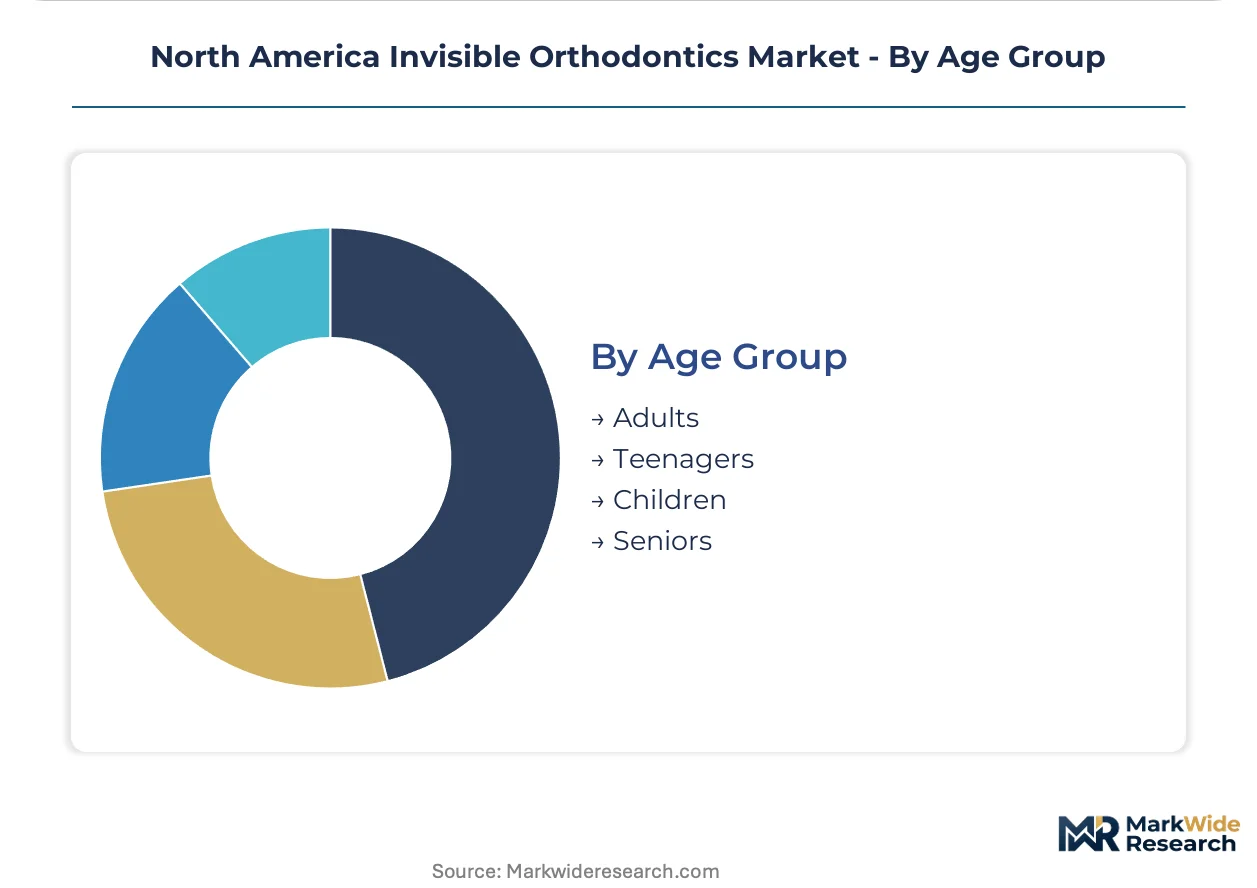
Age Group:
Maturity gradients separate established adult segments from expanding teenager demand, with pediatric and senior applications requiring modified biomechanical protocols.
- Adults:Established patient base in professional employment seeking aesthetic correction without workplace visibility concerns. Lingual braces retain strongest preference among this cohort in Toronto financial district clinics.
- Teenagers:Adolescent patients now expanding fastest across suburban California and Texas orthodontic practices where social media aesthetic sensitivity intersects with parental disposable income. Removability for sports and social events drives clear aligner preference over fixed alternatives.
- Children:Early interceptive treatment applications requiring modified tray designs for mixed dentition.
- Seniors:Aesthetic correction in aging populations with periodontal considerations limiting biomechanical options.
Adults hold current share. Teenagers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates invisible orthodontics volume through FDA-cleared clear aligner systems, while Mexico's COFEPRIS regulatory pathways remain underdeveloped relative to northern saturation. Canada occupies a middle position with Health Canada oversight and concentrated demand in Toronto and Vancouver metropolitan corridors.
United States
California, Texas, and Florida concentrate teenager patient acquisition where suburban orthodontic clinic density intersects with parental disposable income. The FDA's 510(k) premarket notification pathway governs clear aligner material safety and mechanical performance standards. Dallas dental service organizations deploy intraoral scanning ecosystems to compress traditional multi-appointment consultation cycles.
Canada
Toronto and Vancouver financial districts drive premium demand for CAD/CAM-designed lingual fixed appliances among adult professionals seeking absolute concealment. Health Canada regulates clear aligner market access through parallel pathways to FDA frameworks. Ontario orthodontic groups face certified treatment planner availability constraints that lag behind scanner deployment rates.
Mexico
Monterrey and Guadalajara dental markets present first-mover positioning opportunities as COFEPRIS regulatory pathways for clear aligner systems mature. Mexico City academic institutions house underdeveloped clear aligner training programs relative to United States saturation. Guadalajara's dental hospital network requires outcome documentation that remote direct-to-consumer channels struggle to provide.
North America Invisible Orthodontics Market Competitive Environment
Top-tier vendors anchor the premium doctor-directed segment, while remote direct-to-consumer brands compete aggressively on price through teledentistry models. The market structure bifurcates between orthodontist-supervised protocols and at-home impression kit delivery, with state dental board rulings determining competitive boundaries between channels. Strategic archetypes include technology-integrated incumbents with proprietary scanning ecosystems, direct-to-consumer disrupters leveraging remote treatment models, and diversified dental conglomerates with multi-product orthodontic portfolios. Dominant competitive moves encompass M&A activity targeting digital scanning capabilities and strategic partnerships with dental service organizations for channel access.
Within the technology-integrated tier, Align Technology exemplifies proprietary intraoral scanning ecosystem dominance through orthodontist-exclusive software positioning. SmileDirectClub occupies the remote delivery archetype with aggressive price-based competition through teledentistry infrastructure. Straumann Holding anchors the premium segment archetype through its orthodontic portfolio concentration. Henry Schein and Dentsply Sirona represent diversified dental conglomerates with multi-vendor technology distribution capabilities. Envista Holdings and Ormco Corporation sit within the traditional orthodontic equipment supplier tier adapting to digital workflow transitions.
| Leading Market Players |
|---|
| Align Technology |
| 3M |
| Dentsply Sirona |
| Envista Holdings |
| Henry Schein |
| SmileDirectClub |
| Straumann Holding |
| Ormco Corporation |
| TP Orthodontics |
| Others |
Value Chain & Pricing Dynamics
FDA biocompatibility requirements for medical-grade PETG and polyurethane formulations gate qualified supply access and sustain premium-tier pricing for orthodontist-supervised clear aligner protocols. Manufacturers lacking FDA 510(k) clearance face exclusion from California and Texas clinic networks where parental demand for teenager treatments concentrates purchasing power.
Pricing Analysis
Capacity additions in Texas and Ohio chemical manufacturing corridors are reshaping price floors for thermoformed tray systems while premium lingual appliance pricing holds firm. Three-tier pricing structure across orthodontist-exclusive, dental service organization, and direct-to-consumer levels stratifies by supervision intensity and outcome documentation depth. Cost compression in remote delivery channels intensifies because SmileDirectClub's teledentistry infrastructure eliminates chair time overhead. Teenager patient segments show highest price sensitivity, while Toronto financial district professionals accept premium lingual systems without visible negotiation.
Supply Chain Analysis
Specialized polymer chemist availability in Texas, Ohio, and North Carolina manufacturing corridors constrains expansion timelines for medical-grade PETG production lines. Raw material inputs draw from petroleum-derived ethylene glycol, specialty diisocyanates for polyurethane variants, and photoinitiator packages for direct 3D printing resins. Single-source vulnerability pervades FDA-audited resin formulations where supplier qualification cycles exceed twelve months. Distribution runs through centralized thermoforming labs serving multi-state orthodontic group networks, with same-day 3D printing deployments disrupting traditional shipping-dependent models in Dallas and Miami metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America invisible orthodontics market functions as a stable compounder where teenager demographic expansion sustains volume growth irrespective of economic cycle positioning. FDA regulatory clarity on clear aligner materials provides predictable commercialization timelines that support long-term capacity planning.
For Market Incumbents: Anchor proprietary intraoral scanning ecosystems through orthodontist-exclusive software licensing that locks treatment planning workflows against third-party CAD/CAM interoperability. Defend against direct-to-consumer remote models by investing in same-day 3D printing deployments that compress delivery timelines below centralized lab competitors. Channel control through dental service organization partnerships in Florida and Texas metropolitan corridors sustains volume access against price-based disrupters. For New Entrants and Emerging Players: Launch via COFEPRIS regulatory pathway specialization targeting Monterrey and Guadalajara dental markets where United States saturation has not yet replicated. Underpenetrated lingual appliance demand among Toronto and Vancouver adult professionals offers white-space positioning against clear aligner commodity competition. Go-to-market execution through certified orthodontist training partnerships overcomes the treatment planner availability bottleneck constraining incumbent scanner deployment rates. For Investors and Strategic Acquirers: Roll-up economics work for regional orthodontic group consolidation because fragmented clinic ownership in California suburban corridors enables platform-scale procurement leverage against aligner manufacturers. Five-to-ten year viability hinges on teenager patient acquisition sustainability and state dental board teledentistry rulings that define competitive boundaries. Monitor FTC enforcement posture on direct-to-consumer advertising claims as inflection indicator for remote delivery model margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Investment | Accelerates market access for biocompatible PETG tray systems across United States orthodontic networks. |
| Intraoral Scanner Ecosystem Integration | Locks orthodontist workflows into proprietary treatment planning software, displacing third-party CAD/CAM alternatives. |
| Dental Service Organization Partnership | Concentrates volume access in Florida and Texas metropolitan corridors where clinic density drives competitive pricing. |
| Direct 3D Printing Deployment | Eliminates thermoforming bottlenecks and central lab shipping delays for same-visit aligner delivery in Dallas. |
| COFEPRIS Regulatory Pathway Development | Establishes first-mover positioning in Monterrey and Guadalajara markets ahead of United States saturation replication. |
Study Parameters
Bottom-up orthodontic clinic throughput modeling reconciled against top-down medical-grade polymer supply tracking forms the analytical core of this study. Primary interviews with orthodontist practice owners, dental service organization procurement directors, clear aligner manufacturing engineers, and FDA regulatory affairs specialists combined with secondary validation against FDA 510(k) filings, Health Canada device licensing databases, COFEPRIS registration records, and orthodontic trade association membership data. Triangulation between patient volume estimates and resin consumption patterns verified market sizing integrity.
Historical trendline analysis across clear aligner adoption curves in California, Texas, and Florida informed projection parameters over the analysis window. Segmentation modeling incorporated product type, fabrication technology, end-user channel, and patient age cohort dimensions with biomechanical capability limitations and teledentistry regulatory scope as industry-specific forecast inputs. CAGRs derived from weighted average of technology diffusion rates and demographic penetration ceilings.
Several conditions sit outside the modeled scope, including potential FDA reclassification of direct-to-consumer aligners as prescription devices, state dental board rulings restricting teledentistry scope, and raw material supply disruptions in Texas chemical manufacturing corridors. Forecasts reflect assumptions regarding continued teenager patient preference for aesthetic alternatives and stable FDA 510(k) clearance timelines. Material deviation in FTC enforcement posture or COFEPRIS pathway maturation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neuromodulation Market
Medical Devices
Global Ablation Technologies Market
Medical Devices
Global PC-Based Audiometer Market
Medical Devices
Global Breast Pumps Market
Medical Devices
Nephrostomy Catheters Market
Medical Devices
Global Transdermal Skin Patches Market
Medical Devices
Medical Electronics Market
Medical Devices
Medical Device Validation and Verification Market
Medical Devices
Pressure Ulcer Devices Market
Medical Devices
Global Vaccine Delivery Devices Market
Medical Devices
Global Therapeutic Respiratory Devices Market
Medical Devices
3D Printing in Healthcare Market
Medical Devices
Global Ultrasound Devices Market
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
Absorbable Nasal Implant Market
Medical Devices
High Frequency Chest-Wall Oscillation Devices Market