
 Global External Fixators Market | 2026-2036
Global External Fixators Market Size, Share, and Industry Trends Forecast 2026-2036
Global External Fixators Market Foresight
The EU Medical Device Regulation is repositioning the cost-of-entry calculus for external fixator manufacturers seeking CE marking access. Stryker Corporation leverages its trauma portfolio breadth to sustain European market presence under tightened clinical evaluation requirements. Zimmer Biomet anchors its competitive stance through specialized circular fixator systems designed for complex deformity correction protocols.
External fixators are mechanical stabilization devices employing percutaneous pins connected to an external frame, typically constructed from aluminum, carbon fiber, or stainless steel alloys, to stabilize bone segments without implanting hardware directly into the medullary canal. Their primary commercial purpose centers on provisional or definitive stabilization of open fractures, limb length discrepancies, and angular deformities where internal fixation carries excessive infection or soft-tissue risk. Circular fixator systems command premium positioning in deformity correction and limb lengthening applications due to their multiplanar adjustability and Ilizarov-derived biomechanical principles. Trauma management applications within hospital-based deployment settings represent the most mature volume segment, while ambulatory surgical centers are gaining traction for selected fracture repair procedures.
The FDA enforces 510(k) clearance pathways with predicate device comparisons for external fixator systems entering the United States, while Japan's PMDA maintains stringent quality management system inspections for foreign manufacturers. The EU MDR's heightened post-market surveillance obligations and unique device identification mandates are reshaping documentation burdens across the vendor base. Stakeholders must monitor evolving notified body capacity constraints and harmonized standards revisions to preserve market access timelines.
Market Dynamics
EU MDR clinical evidence requirements are compressing vendor margins while simultaneously raising barriers for mid-tier manufacturers seeking CE marking access, fundamentally restructuring competitive positioning across European trauma centers.
Growth Catalysts
- Trauma center expansion:Germany, Japan, and the United States are expanding dedicated trauma infrastructure, driving circular fixator system procurement for complex fracture management protocols.
- EU MDR compliance differentiation:Manufacturers with established quality management systems capture market share as smaller competitors withdraw from CE marking pathways due to tightened biocompatibility documentation.
- Carbon fiber frame adoption:Radiolucent materials enable intraoperative imaging without frame removal, accelerating adoption in deformity correction procedures requiring frequent radiographic monitoring.
Market Restraints
- Notified body capacity constraints:EU MDR transition has created bottlenecks in conformity assessment, extending time-to-market for novel external fixator designs by 12-18 months.
- Pin tract infection protocols:Standardized antibiotic prophylaxis requirements in tertiary hospitals add procedural cost layers without reimbursement adjustment.
- Orthopedic surgeon specialization:Limited fellowship-trained limb reconstruction specialists concentrate demand in urban academic centers, constraining addressable market expansion.
Strategic Opportunities
- Ambulatory surgical center penetration:Selected closed fracture repairs are migrating to outpatient settings in the United States, creating demand for simplified unilateral fixator configurations.
- Hybrid fixator system development:Convergence of circular and unilateral biomechanical principles enables single-device versatility across trauma and reconstructive applications.
- PMDA streamlined pathways:Japan's priority review designation for innovative orthopedic devices accelerates market entry for manufacturers with robust clinical data packages.
Industry Challenges
- Biomechanical engineering talent scarcity:Specialized expertise in Ilizarov-derived frame mechanics concentrates in Eastern European and Russian research institutes, complicating Western R&D staffing.
- Legacy inventory reconciliation:Transition from stainless steel to carbon fiber frames requires hospital supply chain reconfiguration and surgeon retraining investments.
- Post-market surveillance documentation:EU MDR mandates systematic pin tract complication reporting, imposing data infrastructure requirements on smaller manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global External Fixators Market |
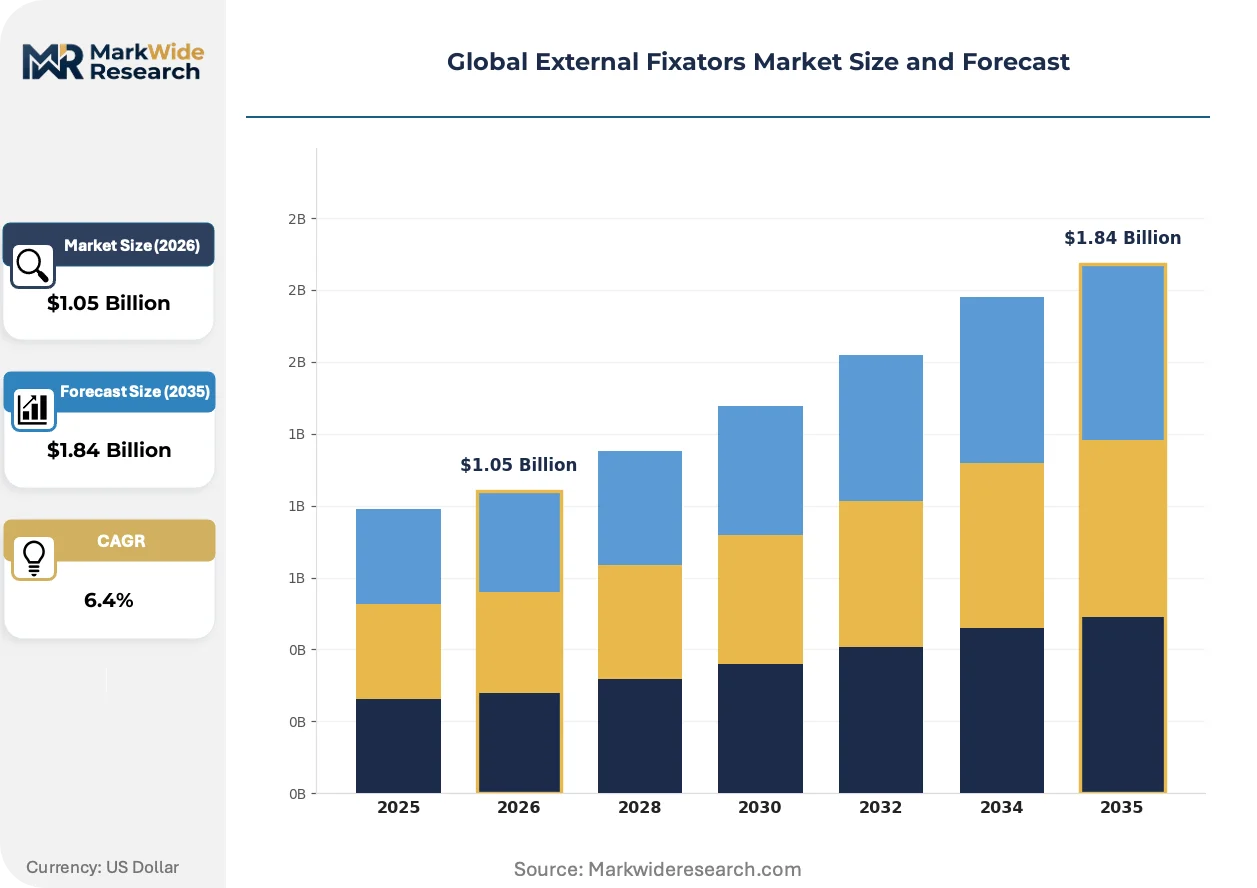
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
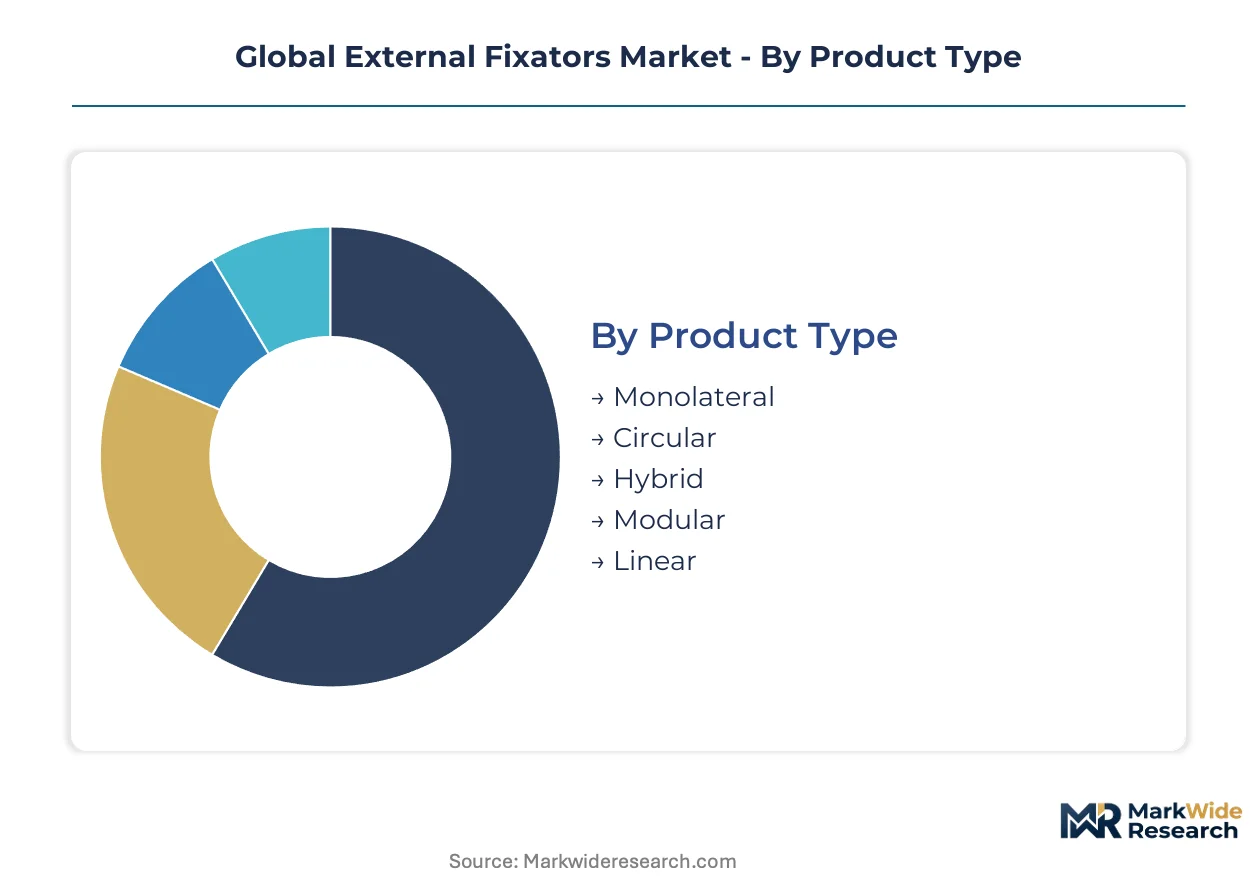
| Segmentation | Product Type: Monolateral, Circular, Hybrid, Modular, Linear Application: Fracture Repair, Limb Lengthening, Deformity Correction, Trauma Management, Orthopedic Reconstruction End User: Orthopedic Clinics, Trauma Centers, Ambulatory Surgical Centers, Rehabilitation Facilities, Specialty Hospitals Deployment: Hospital-based, Outpatient, Mobile Units, Specialized Care Centers, Research Institutes |
| Companies Covered | Johnson & Johnson (DePuy Synthes), Stryker Corporation, Zimmer Biomet, Smith & Nephew, Orthofix Medical Inc., Globus Medical, Acumed LLC, Medtronic, B. Braun (Aesculap), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global External Fixators Market Shifts & Advancements
Digital planning tools and patient-specific frame configurations are compressing the traditional gap between preoperative simulation and intraoperative execution, reshaping how orthopedic trauma centers approach complex deformity cases.
Computer-assisted external fixation is unifying preoperative 3D planning with intraoperative navigation, enabling precise mechanical axis restoration. Academic medical centers in Germany and the United States are piloting these integrated workflows for multiplanar deformity correction. This convergence is compressing revision surgery rates and extending the addressable case complexity for community hospital orthopedic departments.
EU MDR unique device identification mandates are forcing serialization infrastructure investments across the vendor base. Manufacturers must now maintain device lifecycle traceability from production through explant, fundamentally altering quality management system architecture. Trauma centers face parallel obligations in inventory management system upgrades, with German university hospitals leading implementation timelines.
Surgeon preference is consolidating around modular frame platforms that accommodate unilateral, circular, and hybrid configurations through standardized component libraries. This standardization is displacing single-purpose device procurement in favor of versatile system contracts. United States group purchasing organizations are leveraging this convergence to negotiate consolidated orthopedic trauma portfolios with preferred vendors.
Global External Fixators Market Segmentation
External fixator procurement patterns diverge sharply across clinical settings and anatomical complexity. Product architecture, procedure type, and care venue collectively determine purchasing authority and technical specification requirements.
Product Type:
Trauma centers and deformity correction specialists select frame geometries based on mechanical adjustability demands and pin configuration flexibility.
- Circular:Multiplanar ring systems employ tensioned wires and half-pins to enable gradual bone transport and angular correction. German and United States academic medical centers concentrate demand for these systems in limb reconstruction protocols requiring precise mechanical axis restoration.
- Monolateral:Single-bar configurations with unilateral pin placement dominate acute fracture stabilization where rapid assembly and minimal soft-tissue disruption matter. United States trauma centers favor these systems for provisional stabilization of open tibial fractures.
- Hybrid:Converging circular and linear principles, hybrid frames attach proximal ring constructs to distal monolateral bars. These systems address periarticular fractures demanding both angular stability and joint-spanning flexibility.
- Modular:Standardized component libraries enable intraoperative reconfiguration across unilateral, circular, and hybrid geometries. Hospital supply chains in Japan prioritize these platforms to consolidate vendor relationships.
- Linear:Simple telescoping bar designs target temporary bridging applications in mass casualty scenarios. Military medical research institutes evaluate these systems for field deployability.
Monolateral systems lead volumes today; circular configurations are gaining share fastest in tertiary deformity centers.
Application:
Reimbursement pathways and surgical subspecialty training determine which indications attract manufacturer investment and clinical adoption.
- Trauma Management:Emergency stabilization of open fractures and polytrauma cases represents the foundational commercial volume. United States Level I trauma centers drive procurement of rapid-application unilateral systems for damage control orthopedics.
- Deformity Correction:Multiplanar osteotomy procedures requiring gradual mechanical axis restoration command premium system pricing. German university hospitals concentrate fellowship-trained limb reconstruction specialists performing these complex cases.
- Fracture Repair:Definitive treatment of closed fractures with compromised soft-tissue envelopes occupies the boundary between internal and external fixation. Ambulatory surgical centers in the United States are selectively adopting simplified configurations.
- Limb Lengthening:Distraction osteogenesis protocols demand precise rate-and-rhythm control through adjustable frame mechanics. Russian and Eastern European research institutes pioneered these techniques now diffusing to Western academic centers.
- Orthopedic Reconstruction:Post-oncologic and post-infectious bone defect management requires prolonged frame retention. Specialty hospitals in Japan maintain dedicated units for these extended-treatment patients.
Trauma management anchors current revenue; deformity correction applications are climbing the fastest as fellowship training expands.
End User:
Capital equipment budgets and surgeon specialization levels create distinct purchasing behaviors across care settings.
- Trauma Centers:Dedicated emergency infrastructure with 24-hour orthopedic coverage drives high-volume fixator consumption. These facilities in Germany, Japan, and the United States maintain diversified frame inventories for polytrauma response.
- Orthopedic Clinics:Private practice settings with elective deformity correction focus concentrate demand for premium circular systems. Patient self-pay dynamics in select markets influence equipment financing structures.
- Ambulatory Surgical Centers:Outpatient fracture repair protocols are migrating selected closed injuries to lower-acuity venues. United States reimbursement incentives accelerate this shift.
- Specialty Hospitals:Limb lengthening and congenital deformity centers maintain dedicated frame fabrication workshops. These institutions in Germany and the United States train visiting surgeons on advanced assembly techniques.
- Rehabilitation Facilities:Extended care settings manage pin tract care and frame adjustments during prolonged treatment courses. These facilities interface with academic centers for complication escalation protocols.
Trauma centers dominate procurement volumes today; ambulatory surgical centers are expanding most quickly in the United States.
Deployment:
Care delivery location determines regulatory oversight intensity and supply chain configuration requirements.
- Hospital-based:Inpatient surgical suites with full sterilization infrastructure support the complete range of fixator procedures. FDA and EU MDR compliance documentation concentrates in these settings.
- Outpatient:Standalone surgical facilities perform selected fracture repairs without overnight admission. United States certificate-of-need regulations shape geographic distribution.
- Specialized Care Centers:Dedicated limb reconstruction institutes combine surgical and rehabilitation services under single governance. German university-affiliated centers exemplify this integrated model.
- Mobile Units:Deployable surgical platforms address humanitarian and military trauma scenarios. Research institutes evaluate carbon fiber frame durability under field conditions.
- Research Institutes:Biomechanical testing and surgical training facilities consume fixator systems for non-clinical applications. These sites generate preclinical data supporting regulatory submissions.
Hospital-based deployment leads procedure volumes today; outpatient settings are gaining share fastest in markets with favorable reimbursement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fellowship-trained limb reconstruction specialists concentrate in German university hospitals, Japanese academic centers, and United States Level I trauma facilities, anchoring demand for advanced circular and hybrid fixation systems across these markets.
United States
Level I trauma centers in Baltimore, Houston, and Los Angeles drive procurement of rapid-application unilateral systems for damage control orthopedics. FDA 510(k) clearance pathways with predicate device comparisons govern market entry timelines. The Southeast and Midwest regions are expanding ambulatory surgical center networks for selected closed fracture repairs.
Germany
University hospitals in Berlin, Hamburg, and Munich maintain dedicated limb reconstruction units with fellowship-trained specialists performing complex deformity corrections. EU MDR tightened biocompatibility documentation requirements filter mid-tier manufacturers from CE marking access. The Baden-Württemberg and Bavaria clusters lead carbon fiber frame adoption for intraoperative imaging compatibility.
Japan
PMDA quality management system inspections for foreign manufacturers create structured entry barriers that favor established trauma portfolio vendors. Tokyo and Osaka academic medical centers concentrate demand for modular frame platforms enabling intraoperative reconfiguration. METI priority review designation for innovative orthopedic devices accelerates regulatory timelines for novel fixation mechanics.
China
NMPA medical device registration requirements are harmonizing toward international standards, reshaping documentation burdens for domestic and foreign manufacturers alike. The Yangtze River Delta and Pearl River Delta regions are expanding tertiary orthopedic hospital infrastructure. Shanghai and Beijing trauma centers are piloting computer-assisted external fixation workflows for multiplanar deformity correction.
United Kingdom
NHS England specialized commissioning frameworks concentrate complex limb reconstruction cases in designated supra-regional centers. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining UK-specific market access. The London and Manchester academic clusters are consolidating frame procurement through standardized component library contracts.
Global External Fixators Market Competitive Landscape
The competitive structure tilts toward diversified orthopedic conglomerates with trauma portfolio breadth. Three to five multinational device manufacturers anchor procurement decisions in tertiary hospitals, while specialized circular fixator specialists occupy premium niches in deformity correction. M&A activity targets deformity correction technology assets, and strategic partnerships with academic medical centers secure clinical evaluation data for regulatory submissions.
Among diversified orthopedic conglomerates, Johnson & Johnson (DePuy Synthes), Stryker Corporation, and Zimmer Biomet occupy positions defined by trauma portfolio scale and European regulatory compliance infrastructure. These entities exemplify the archetype of manufacturers leveraging quality management system maturity to sustain market presence under tightened EU MDR clinical evidence requirements. Their geographic distribution across United States, European, and Asia-Pacific headquarters reflects the global concentration of external fixator demand in Germany, Japan, and United States trauma centers.
| Leading Market Players |
|---|
| Johnson & Johnson (DePuy Synthes) |
| Stryker Corporation |
| Zimmer Biomet |
| Smith & Nephew |
| Orthofix Medical Inc. |
| Globus Medical |
| Acumed LLC |
| Medtronic |
| B. Braun (Aesculap) |
| Others |
Supply & Pricing Matrix
EU MDR-mandated biocompatibility documentation and unique device identification serialization are forcing manufacturers to absorb compliance infrastructure costs without commensurate pricing power, compressing margins across mid-tier vendors while concentrating procurement leverage in United States group purchasing organizations and German university hospital consortia.
Pricing Analysis
Bundled system contracts with standardized component libraries now dominate over unbundled per-procedure pricing. Three-tier pricing structure across premium carbon fiber circular systems, standard aluminum monolateral configurations, and economy stainless steel trauma sets differentiates by frame material and adjustability complexity. Cost compression in standard tiers is intensifying because GPOs are consolidating vendor panels. Ambulatory surgical centers exhibit highest price sensitivity; German limb reconstruction units show lowest.
Supply Chain Analysis
Single-source vulnerability sits with carbon fiber prepreg suppliers concentrated in Japan and Germany, where Toray and SGL Carbon anchor aerospace-medical crossover material flows. Frame machining and pin fabrication draw from Switzerland, the United States, and China. Tariff exposure on Chinese-sourced titanium pins threatens cost stability. Distribution runs through orthopedic implant distributors with hospital consignment inventory models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global External Fixators Market functions as a stable compounder anchored by irreplaceable trauma center demand and the non-discretionary nature of open fracture stabilization protocols.
For Market Incumbents: Acquire deformity correction technology assets and digital planning software capabilities to fortify against software-enabled orthopedic entrants. Deepen backward integration into carbon fiber frame manufacturing to capture margin from Japanese material suppliers. Prioritize EU MDR notified body relationship investments to sustain CE marking velocity as smaller competitors withdraw. For New Entrants and Emerging Players: Launch via ambulatory surgical center focused distribution partnerships targeting simplified monolateral configurations for closed fracture migration. White-space concentrates in United States outpatient settings and Japanese modular platform niches where incumbent portfolios lack configuration flexibility. Pursue PMDA priority review designation to accelerate market entry timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized circular fixator specialists possessing Ilizarov-derived biomechanical IP and academic medical center training relationships. Five-to-ten year viability hinges on software integration capabilities and regulatory data infrastructure. Watch EU notified body capacity expansion as inflection signal for mid-tier vendor re-entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR compliance infrastructure separates viable vendors from market exiters across German trauma centers. |
| Hospital System Partnership | Academic medical center alliances generate clinical evidence packages for FDA 510(k) predicate comparisons. |
| Software Companion Development | Digital planning tools compress revision surgery rates and extend addressable case complexity for community hospitals. |
| Carbon Fiber Supply Agreement | Radiolucent material security enables intraoperative imaging compatibility premium positioning. |
| Reimbursement Strategy | CPT code optimization for ambulatory surgical center fracture repair protocols unlocks United States outpatient volume. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged orthopedic trauma surgeons, hospital purchasing committee members, biomedical engineers specializing in frame mechanics, GPO contracts managers, and regulatory affairs leads at notified bodies. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare utilization data. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue assessments.
Segment-weighting applied product type, application, end user, and deployment mode dimensions across the analysis window. Trauma management, deformity correction, and limb lengthening indications received distinct growth trajectory modeling. CAGRs derived from procedure volume elasticities to trauma center infrastructure expansion, regulatory approval velocity assumptions, and material substitution patterns in frame construction.
Forecast precision tightens around the base case; tail outcomes carry wider variance under notified body capacity constraints and carbon fiber supply disruption scenarios. Forecasts reflect documented assumptions regarding EU MDR transition timelines and PMDA inspection cadence for foreign manufacturers. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United States Contraceptive Devices Market
Medical Devices
India Biopsy Devices Market
Medical Devices
Global Brachytherapy Treatment Planning Systems Market
Medical Devices
Biomedical Temperature Sensors Market
Medical Devices
Permanent Artificial Skin Market
Medical Devices
Medical Hydrophilic Coatings Market
Medical Devices
Ocular Trauma Devices Market
Medical Devices
Nasal Implant Market
Medical Devices
Global Obstetrics Devices Market
Medical Devices
Pharmaceutical Robots Market
Medical Devices
Global Contrast Media Injector Market
Medical Devices
Liver-On-Chip Market
Medical Devices
Phakic Intraocular Lenses (IOL) Market
Medical Devices
Global Connected Medical Devices Market
Medical Devices
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Knee Braces Market