
 Global Monopolar Electrosurgery Market | 2026-2036
Global Monopolar Electrosurgery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Monopolar Electrosurgery Market Foresight
ISO 13485 certification cycles are rotating faster among active manufacturers as EU MDR and FDA QSR requirements tighten quality management obligations. Medtronic plc leverages its vertically integrated generator-to-electrode portfolio to sustain pricing power across hospital procurement channels. Johnson & Johnson (Ethicon) anchors North American market presence through deep laparoscopic instrument ecosystems.
Monopolar electrosurgery employs radiofrequency current delivered through a single active electrode to cut or coagulate tissue, with generators typically operating between 300 kHz and 3 MHz to minimize neuromuscular stimulation while producing thermal tissue effects. The technology serves general surgery, gynecology, urology, neurosurgery, and ENT disciplines where precise hemostasis and tissue division are required. Electrosurgical generators dominate device type revenue due to capital replacement cycles and software-upgrade dependencies, while handpieces and electrodes generate recurring consumable income streams. Radiofrequency technology leads the technology dimension, though ultrasonic alternatives are gaining traction in vessel-sealing applications where thermal spread minimization commands premium positioning.
FDA 510(k) clearance and EU MDR conformity assessment shape product development timelines and market access costs for manufacturers targeting Western markets. China's NMPA registration requirements add a separate regulatory layer for suppliers seeking volume in Asia's largest hospital expansion program. Stakeholders must monitor how divergent sterilization validation standards across FDA, EMA, and NMPA jurisdictions fragment manufacturing configurations and inflate compliance overhead.
Market Dynamics
Generator-to-electrode platform consolidation is compressing supplier margins while hospital procurement centralization concentrates purchasing power among integrated delivery networks in the United States, Germany, and China.
Growth Catalysts
- EU MDR recertification waves:Accelerated conformity assessment timelines are forcing incumbent manufacturers to upgrade quality management systems, creating temporary supply gaps that agile certified suppliers can exploit.
- Laparoscopic expansion in general surgery:Minimally invasive procedure volumes in hospital systems are pulling monopolar handpiece and electrode consumption upward through standardized surgical protocols.
- China's NMPA registration pathway streamlining:Simplified Class II medical device approvals are compressing market entry timelines for foreign manufacturers targeting provincial hospital procurement tenders.
Market Restraints
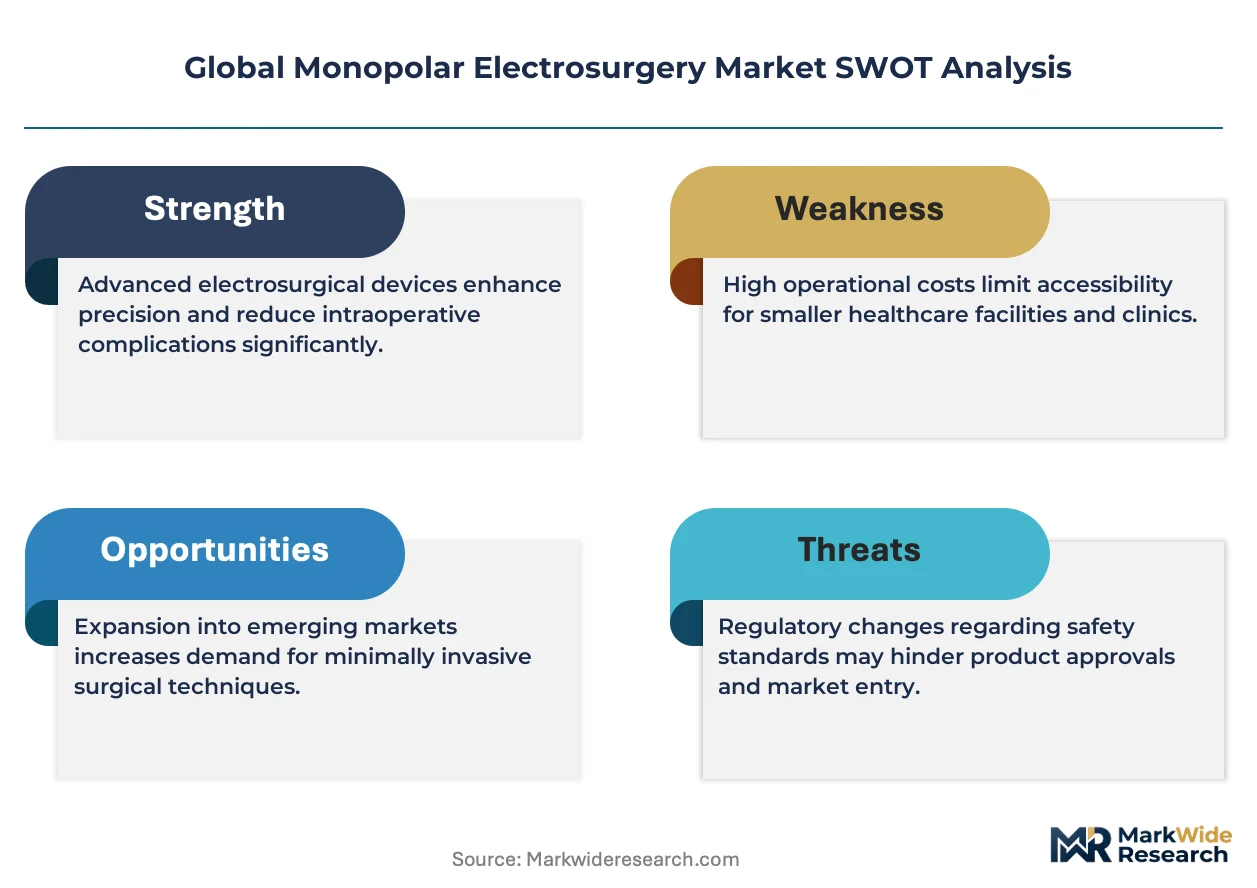
- Copper and tungsten electrode material volatility:Raw material cost swings in conductive alloys are squeezing consumable gross margins without proportional pricing recovery mechanisms.
- Generator manufacturing concentration in Germany and the United States:Capital equipment production clusters in Bavaria and Minnesota create geographic supply risk and logistics cost premiums for Asian hospital systems.
- Ultrasonic vessel-sealing substitution:Advanced energy platforms in gynecologic and colorectal surgery are capturing premium hemostasis cases previously served by monopolar coagulation.
Strategic Opportunities
- India's underserved tier-2 and tier-3 hospital infrastructure:District hospital modernization programs under Ayushman Bharat are creating first-time generator installation demand outside metropolitan surgical centers.
- Radiofrequency-integrated smoke evacuation convergence:Combined generator-plume management systems address operating room air quality mandates while differentiating capital equipment offerings.
- Direct-to-hospital digital procurement channels:E-commerce platforms and group purchasing organization portals are disintermediating traditional surgical instrument distributors in China's provincial markets.
Industry Challenges
- Biomedical engineering technician shortages:Hospital maintenance departments lack personnel trained on radiofrequency generator calibration and safety interlock verification, extending equipment downtime.
- ISO 13485:2016 transition fatigue:Smaller electrode and handpiece manufacturers face documentation burden and audit cost pressures without dedicated quality regulatory staff.
- Legacy electrosurgical unit integration complexity:New generator software architectures require middleware development for connectivity with outdated hospital information systems, delaying installation acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Monopolar Electrosurgery Market |
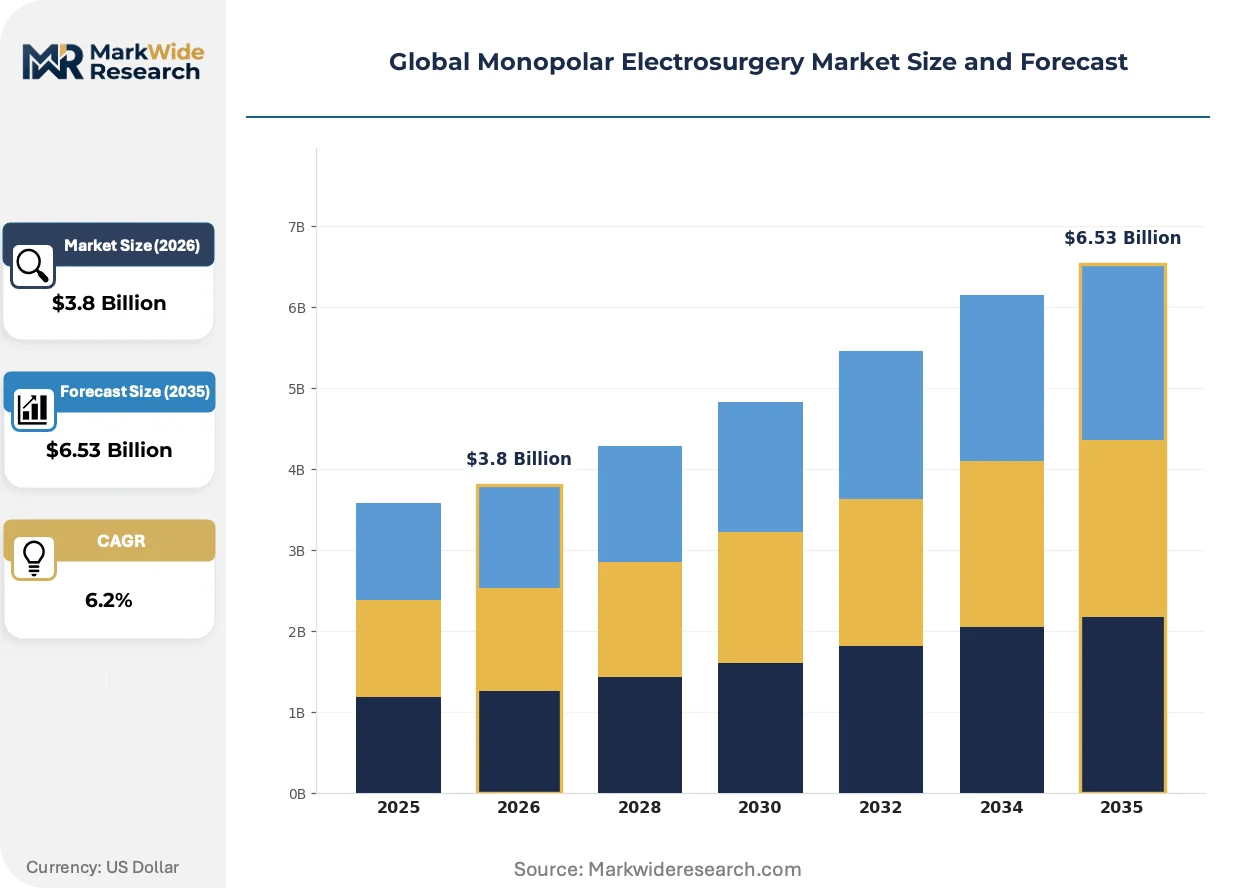
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Electrosurgical Generators, Handpieces, Electrodes, Accessories Technology: Radiofrequency, Ultrasonic, Bipolar, Plasma, Laser Application: General Surgery, Gynecology, Urology, Neurosurgery, ENT End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes |
| Companies Covered | Medtronic plc, Johnson & Johnson (Ethicon), Olympus Corporation, CONMED Corporation, B. Braun Melsungen AG, Erbe Elektromedizin GmbH, Boston Scientific Corporation, Stryker Corporation, KLS Martin Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Monopolar Electrosurgery Market Shifts & Advancements
Software-defined generator architectures are displacing analog hardware platforms, enabling real-time tissue impedance feedback and procedure-specific energy algorithms that reshape competitive differentiation beyond raw power specifications.
Intelligent cutting algorithms with tissue-sensing feedback loops are decomposing the traditional separation between cut and coagulation modes. Academic medical centers in the United States and university hospitals in Germany are piloting these platforms for hepatic and splenic resections where thermal injury depth control is critical. The technology is decomposing established generator tiering by enabling mid-range hardware to deliver precision previously reserved for premium capital equipment.
EU MDR Article 10 technical documentation requirements are extending conformity assessment durations for electrosurgical accessories. Notified bodies in Germany and the Netherlands are prioritizing high-risk device reviews, delaying handpiece and electrode recertification timelines by six to twelve months. Manufacturers are responding by consolidating product families and withdrawing marginal SKUs to focus resources on core generator-compatible portfolios.
Hospital procurement departments are unbundling generator capital purchases from multi-year electrode supply agreements. Integrated delivery networks in the United States are negotiating separate tenders for capital equipment and consumables, enabling competitive switching between handpiece suppliers. This pattern is most visible in Texas and Florida health systems where surgical volume concentration creates leverage for split-source contracting.
Global Monopolar Electrosurgery Market Segmentation
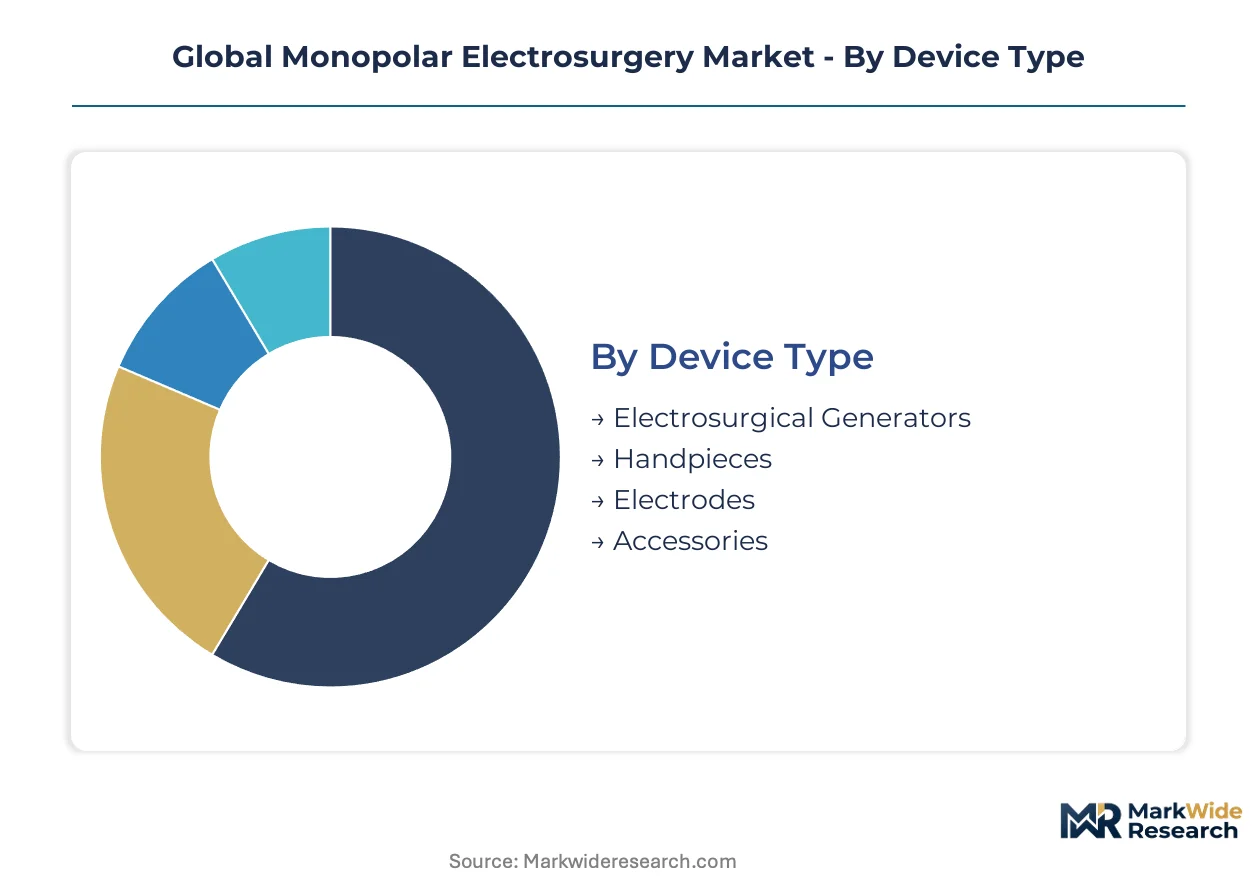
Monopolar electrosurgery market segmentation reveals divergent margin profiles across capital equipment and consumable categories. Regulatory classification tiers—FDA Class II for generators versus Class I for many accessories—shape investment priorities and certification timelines for manufacturers.
Device Type:
FDA 510(k) clearance pathways and EU MDR conformity assessments stratify capital intensity and recurring revenue potential across device categories.
- Electrosurgical Generators:Capital equipment operating between 300 kHz and 3 MHz with software-defined architectures enabling real-time tissue impedance feedback. Demand concentrates in United States integrated delivery networks and German university hospitals where capital replacement cycles and software-upgrade dependencies sustain pricing power. Generator procurement centralization among hospital systems in Texas and Florida creates leverage for multi-year service contracts.
- Handpieces:Reusable and single-use instruments delivering radiofrequency current from generator to active electrode. China's provincial hospital procurement tenders under NMPA Class II streamlined pathways are pulling volume expansion for mid-tier handpiece suppliers targeting tier-2 infrastructure.
- Electrodes:Copper and tungsten alloy consumables subject to raw material cost volatility without proportional pricing recovery mechanisms.
- Accessories:Cables, adapters, and footswitches completing circuit pathways; standardized connectivity specifications limit differentiation.
Established volume favors electrosurgical generators; emerging adoption favors handpieces in Asia-Pacific provincial markets.
Technology:
Energy delivery modalities differentiate by thermal spread precision, hemostasis speed, and tissue interaction mechanics.
- Radiofrequency:Dominant technology employing alternating current at 300 kHz–3 MHz to minimize neuromuscular stimulation while producing controlled thermal tissue effects. United States academic medical centers and German university hospitals anchor demand for advanced generators with intelligent cutting algorithms and tissue-sensing feedback loops.
- Ultrasonic:Mechanical vibration energy for vessel sealing with minimized thermal spread; capturing premium hemostasis cases in gynecologic and colorectal surgery previously served by monopolar coagulation.
- Bipolar:Current confined between instrument jaws; lower power requirements reduce collateral tissue damage in neurosurgical applications.
- Plasma:Ionized gas energy for precision cutting at lower temperatures; ENT and ophthalmic surgery adoption.
- Laser:Photonic energy delivery for specific wavelength-tissue interactions; limited penetration in general surgery due to capital cost and safety training requirements.
Radiofrequency maintains installed base dominance; ultrasonic applications are expanding most quickly in vessel-sealing segments.
Application:
Surgical discipline requirements dictate generator specification, handpiece ergonomics, and electrode selection criteria.
- General Surgery:Broadest utilization spanning open and laparoscopic procedures with standardized protocols pulling monopolar handpiece and electrode consumption upward. United States hospital system procurement centralization concentrates volume in integrated delivery networks negotiating split-source contracts for capital and consumables.
- Gynecology:Hysterectomy and myomectomy procedures requiring precise hemostasis; ultrasonic alternatives gaining share in vessel-sealing applications.
- Urology:Transurethral resection and nephrectomy applications; electrode design specialization for fluid immersion environments.
- Neurosurgery:Bipolar preference for critical structure proximity; monopolar utilization limited to specific access routes.
- ENT:Plasma and laser competition in precision cutting; monopolar retained for hemostasis in tonsillectomy and sinus procedures.
General surgery anchors procurement volume; gynecology presents the steepest substitution risk from ultrasonic platforms.
End User:
Facility scale and procedure complexity determine capital equipment tier selection and consumable contract structures.
- Hospitals:Tertiary and secondary surgical departments with full generator-to-electrode platform integration. Germany's Bavarian medical device manufacturing cluster and Minnesota's generator production concentration supply hospital systems in United States, Germany, and China modernizing aging infrastructure.
- Ambulatory Surgical Centers:Focused procedure volumes favoring portable generator platforms and disposable handpiece economics; United States Medicare reimbursement shifts expanding site-of-service migration.
- Specialty Clinics:Dermatology and gastroenterology applications with limited generator requirements; electrode and accessory consumable focus.
- Research Institutes:Preclinical and clinical trial equipment procurement; non-standard specifications and extended validation timelines.
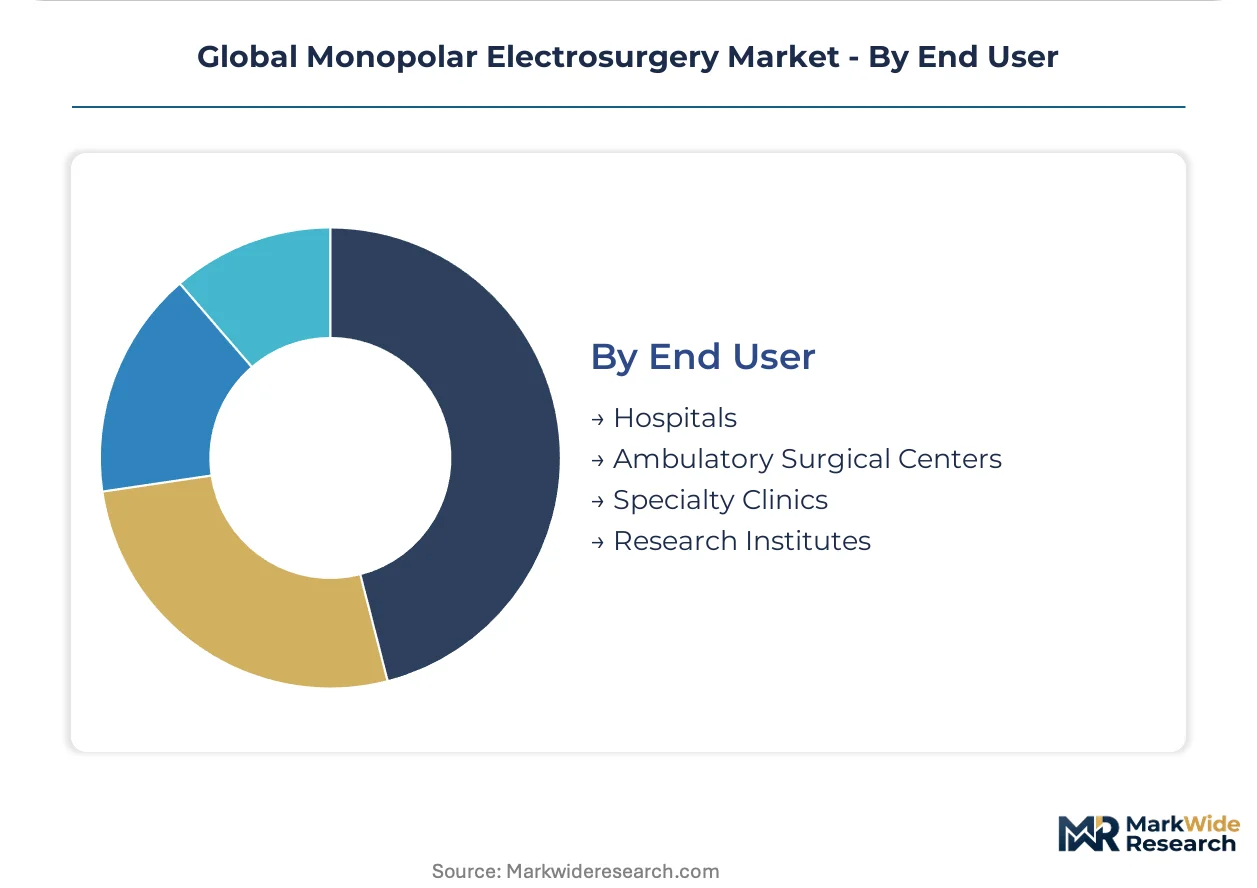
Hospitals concentrate capital purchasing power; ambulatory surgical centers are gaining share fastest in United States outpatient migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital infrastructure modernization programs across major surgical markets are accelerating generator replacement cycles and consumable procurement standardization. Government procurement tenders and regulatory harmonization initiatives are reshaping competitive access in each geography.
United States
Medicare reimbursement shifts toward outpatient surgical settings are expanding ambulatory surgical center generator installations. FDA 510(k) clearance pathways maintain stringent quality benchmarks for capital equipment entry. Minnesota's medical device manufacturing cluster anchors generator production for domestic hospital systems and export markets.
Germany
University hospital procurement centralization concentrates demand for premium generators with intelligent tissue-sensing algorithms. EU MDR Article 10 technical documentation requirements extend conformity assessment timelines for electrosurgical accessories. Bavaria's precision engineering corridor hosts concentrated generator and handpiece manufacturing serving European hospital networks.
China
Provincial hospital expansion under national healthcare infrastructure programs is pulling first-time generator installations into tier-2 and tier-3 cities. NMPA Class II streamlined approval pathways compress market entry timelines for foreign manufacturers. Yangtze River Delta manufacturing bases are scaling domestic handpiece production for provincial procurement tenders.
India
Ayushman Bharat district hospital modernization is creating initial electrosurgical platform demand outside metropolitan surgical centers. CDSCO medical device registration requirements govern import and distribution pathways for foreign suppliers. Maharashtra and Karnataka medical device corridors are emerging as domestic assembly hubs for regional market supply.
Japan
Aging surgical infrastructure in tertiary hospitals is driving capital replacement demand for software-defined generator platforms. PMDA quality management system requirements align with international standards while maintaining distinct technical documentation protocols. Kanto region hospital networks anchor procurement volume for precision surgical energy systems.
Global Monopolar Electrosurgery Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with vertically integrated generator-to-electrode portfolios. Market structure concentrates around three to five dominant suppliers controlling capital equipment procurement channels, with fragmented electrode and handpiece specialists competing on consumable contracts. Strategic archetypes include integrated platform providers, regional procurement specialists, and component-focused contract manufacturers. Competitive moves center on backward integration into generator software development and strategic partnerships with hospital group purchasing organizations.
Among diversified medical technology conglomerates, Medtronic plc and Johnson & Johnson (Ethicon) occupy positions exemplifying integrated platform dominance across North American and European procurement channels. Olympus Corporation represents the precision surgical instrument archetype with established presence in Asian hospital networks. Erbe Elektromedizin GmbH anchors the German engineering-specialist tier within European markets. These named entities illustrate how geographic origin and corporate structure shape competitive positioning without dictating specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Medtronic plc |
| Johnson & Johnson (Ethicon) |
| Olympus Corporation |
| CONMED Corporation |
| B. Braun Melsungen AG |
| Erbe Elektromedizin GmbH |
| Boston Scientific Corporation |
| Stryker Corporation |
| KLS Martin Group |
| Others |
Supply & Pricing Matrix
Generator manufacturing scale in Bavaria and Minnesota creates dual-hemisphere capacity anchors that shape both supply concentration and price floors for hospital procurement. Capital equipment production clusters concentrate quality management investment, while consumable electrode suppliers face margin compression without matching scale economies.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA 510(k)-cleared and EU MDR-certified generators commanding hospital procurement premiums over unvalidated alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by software-defined feature depth and tissue-sensing algorithm sophistication. Pricing pressure stems from copper and tungsten electrode material volatility squeezing consumable gross margins without proportional recovery mechanisms. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement compression, while German university hospitals prioritize intelligent algorithm performance over unit cost.
Supply Chain Analysis
Inventory lead times for radiofrequency generator power electronics extend equipment delivery windows, compressing supplier responsiveness to hospital replacement cycles. Manufacturing concentrates in Germany, the United States, and China's Yangtze River Delta, with Bavarian precision engineering corridors and Minnesota medical device clusters anchoring capital equipment supply. Raw material dependencies center on copper-tungsten electrode alloys, semiconductor power modules, and radiofrequency shielding components. Single-source vulnerability in specialized generator transformer winding creates supply risk for mid-tier manufacturers. Distribution runs through integrated delivery network procurement portals and group purchasing organization contracts in the United States, provincial hospital tenders in China, and centralized university hospital frameworks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects as software-defined generator architectures decompose hardware tiering and enable mid-range systems to deliver precision previously reserved for premium capital equipment. Interoperability mandates from hospital information system integration requirements reshape competitive moats around data connectivity rather than raw power specifications.
For Market Incumbents: Shield installed base retention by accelerating software companion development for legacy electrosurgical unit middleware integration, addressing hospital maintenance department technician shortages through remote calibration services. Deepen backward integration into intelligent cutting algorithm R&D to differentiate beyond hardware specifications. Prioritize EU MDR Article 10 technical documentation consolidation to compress handpiece and electrode recertification timelines against agile certified competitors.
For New Entrants and Emerging Players: Biomedical engineering technician training gaps present service-layer white space where incumbents under-serve hospital maintenance departments with radiofrequency generator calibration and safety interlock verification. Target India's tier-2 and tier-3 district hospitals under Ayushman Bharat modernization programs for first-time generator installation demand outside metropolitan surgical centers. Deploy direct-to-hospital digital procurement channels in China's provincial markets to disintermediate traditional surgical instrument distributors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component-specialist acquisition targets with ISO 13485:2016 certification and established notified body relationships that accelerate EU MDR conformity assessment timelines. Long-term viability hinges on software-defined architecture transitions enabling recurring revenue streams through algorithm licensing rather than transactional hardware sales. Monitor ultrasonic vessel-sealing substitution rates in gynecologic and colorectal surgery as inflection indicator for monopolar coagulation addressable market compression.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment Acceleration | Compressed recertification timelines enable agile suppliers to exploit temporary supply gaps from incumbent documentation burdens. |
| Software Companion Development | Middleware integration with hospital information systems reduces installation acceptance delays and extends generator replacement cycles. |
| Biomedical Technician Training Programs | Addressing calibration and safety interlock verification shortages reduces hospital equipment downtime and strengthens service relationships. |
| Radiofrequency-Integrated Smoke Evacuation | Combined generator-plume management systems address operating room air quality mandates while differentiating capital equipment offerings. |
| Provincial Digital Procurement Channel Buildout | E-commerce platforms and GPO portals disintermediate traditional distributors in China's tier-2 and tier-3 hospital markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, biomedical engineering directors, electrosurgical equipment procurement managers, and group purchasing organization contract specialists. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body submission records, NMPA Class II registration filings, hospital procurement tender documentation, and CMS Medicare reimbursement schedules. Bottom-up generator installation and electrode consumption estimates were triangulated against top-down capital equipment replacement cycle modeling.
Across the analysis window, forecast outputs reflect segment-level modeling across device type, technology modality, surgical application discipline, and end-user facility scale. CAGRs were derived from procedure volume elasticity analysis, capital replacement cycle timing, and consumable attach rate assumptions. Industry-specific inputs incorporated laparoscopic expansion protocols, EU MDR recertification wave timing, and China's NMPA pathway streamlining impact on provincial market entry.
Forecasts assume regulatory continuity in FDA 510(k), EU MDR, and NMPA regimes; material policy shifts in sterilization validation standards or electromagnetic compatibility requirements would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Manometry System Market
Medical Devices
Oxygen Therapy Devices Market
Medical Devices
Italy Medical Device Regulatory Affairs Market
Medical Devices
Global Pressure Relief Devices Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
Endodontic Files Market
Medical Devices
Pulse Electromagnetic Field (PEMF) Therapy Devices Market
Medical Devices
Radiofrequency (RF) Ablation System Market
Medical Devices
Global Uterine Manipulation Devices Market
Medical Devices
South Africa Neurology Devices Market
Medical Devices
Cardiac Poc Testing Devices Market
Medical Devices
Global Stent Graft Balloon Catheter Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
Urinary Collection Device Market
Medical Devices
Osteotomy Plates Market
Medical Devices
UHD Surgical Display Market