
 Global Asthma Therapeutics Market | 2026-2036
Global Asthma Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Asthma Therapeutics Market Foresight
The EU Green Deal is consolidating demand around low-global-warming-potential inhaler propellants across European hospital formularies. GlaxoSmithKline plc leverages its respiratory manufacturing scale to supply transitioned HFA-152a platforms. AstraZeneca plc anchors its position through sustained R&D intensity in IL-5 and IL-13 biologic pathways. Teva Pharmaceutical Industries Ltd. competes aggressively in the generic corticosteroid segment across Central and Eastern European tenders.
Asthma therapeutics comprise pharmaceutical agents and biologic interventions designed to control bronchial inflammation, prevent exacerbations, and restore reversible airflow obstruction through targeted immunomodulation or direct smooth muscle relaxation. Inhaled corticosteroids remain the backbone of maintenance therapy due to their localized anti-inflammatory action and established safety profile, while monoclonal antibodies represent the fastest-growing margin pool as they displace chronic oral corticosteroid dependence in severe eosinophilic phenotypes. The therapy area dimension shows severe persistent asthma commanding premium pricing power, whereas mild persistent asthma sustains volume leadership through broad primary care prescribing.
FDA, EMA, and Japan's PMDA each enforce distinct bioequivalence and environmental standards that shape inhaler device approvals and cross-border market access timelines. REACH and the EU F-Gas Regulation are forcing reformulation investments that favor companies with captive device engineering capabilities. Stakeholders must monitor how regulator divergence on propellant transition deadlines fragments manufacturing scale economies and reshapes regional supply commitments.
Market Dynamics
The EU F-Gas Regulation is compressing manufacturing timelines for metered-dose inhalers, forcing wholesale platform transitions toward dry powder and soft-mist alternatives while redistributing competitive advantage toward device engineering specialists.
Growth Catalysts
- EMA accelerated assessment pathways:Severe asthma biologics receive conditional marketing authorizations that compress development-to-revenue cycles. Pediatric hospital networks in Germany and France are expanding dedicated biologics infusion centers.
- Eosinophil-targeted therapy expansion:IL-5 and IL-4/13 pathway inhibitors are displacing chronic oral corticosteroid dependence in steroid-refractory patient populations. Pulmonology practices in the United States are restructuring around biologic eligibility screening protocols.
- Japan PMDA Sakigake designation:Fast-track approvals for novel biologic entities are shortening Japan's historical lag behind Western launch timelines. Severe asthma centers in Tokyo and Osaka are prioritizing these agents in formulary negotiations.
Market Restraints
- HFA-152a propellant supply concentration:Three chemical manufacturers control global supply of low-global-warming-potential propellants, creating input bottleneck risk for transitioned inhaler platforms.
- Biologics cold-chain infrastructure gaps:Sub-Saharan Africa and parts of Southeast Asia lack validated temperature-controlled distribution networks for monoclonal antibody therapies, excluding severe asthma populations from access.
- REACH registration cost barriers:Small and mid-sized generic inhaler manufacturers face disproportionate compliance burdens for novel excipient documentation, consolidating formulation expertise among large-scale producers.
Strategic Opportunities
- India's CDSCO biosimilar pathway:The country's abbreviated approval framework for reference biologics creates first-mover positioning for domestically manufactured IL-5 and IgE-targeted alternatives.
- Telehealth-integrated adherence monitoring:Connected inhaler devices paired with remote patient management platforms are opening subscription-based revenue models beyond drug-plus-device bundling.
- China NMPA priority review vouchers:Rare disease designations for severe eosinophilic asthma subtypes are attracting multinational licensing activity toward domestic development partnerships.
Industry Challenges
- Complex generic bioequivalence demonstration:FDA and EMA divergence on in-vitro/in-vivo correlation requirements for orally inhaled products is fragmenting development programs and duplicating clinical investment.
- Legacy device platform obsolescence:Manufacturers with captive HFA-134a supply chains face stranded asset risk as propellant phase-out deadlines accelerate across European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Asthma Therapeutics Market |
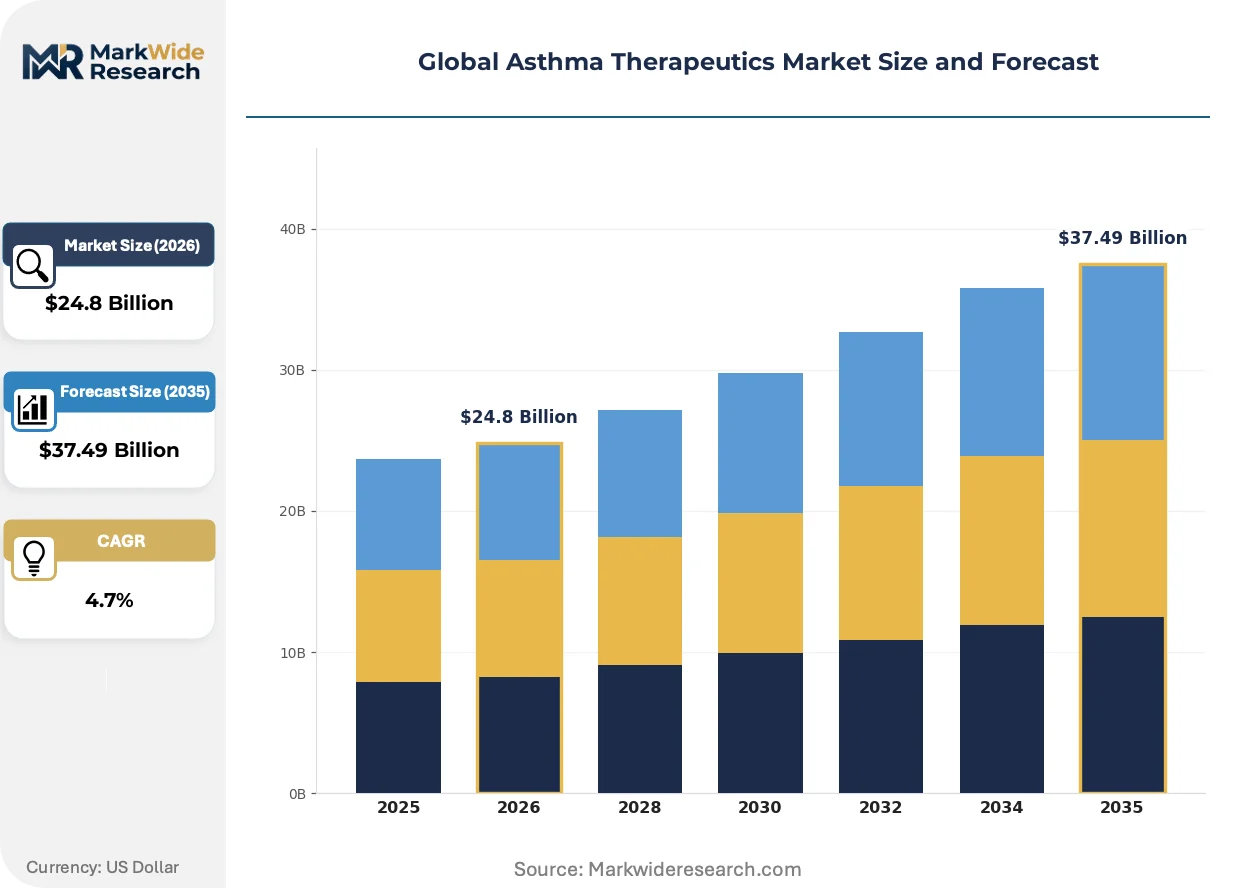
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.49 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhaled Corticosteroids, Long-Acting Beta Agonists, Leukotriene Modifiers, Monoclonal Antibodies, Short-Acting Beta Agonists Therapy Area: Mild Persistent Asthma, Moderate Persistent Asthma, Severe Persistent Asthma, Exercise-Induced Bronchoconstriction, Nocturnal Asthma End User: Pulmonology Clinics, Specialty Pharmacies, Respiratory Therapy Centers, Pediatric Care Units, Home Healthcare Providers Route of Administration: Inhalation, Oral Tablets, Nebulization, Subcutaneous Injection, Intravenous Injection |
| Companies Covered | GlaxoSmithKline plc, AstraZeneca plc, Teva Pharmaceutical Industries Ltd., Novartis AG, Boehringer Ingelheim International GmbH, Sanofi, F. Hoffmann-La Roche Ltd., Merck & Co., Inc., Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Asthma Therapeutics Market Shifts & Advancements
Dry powder inhaler technology is consolidating market share as environmental regulations eliminate legacy propellant platforms, while biologic delivery systems and digital adherence tools are redefining competitive differentiation beyond molecule patents.
Soft-mist inhaler platforms are consolidating position in the maintenance therapy segment through superior lung deposition efficiency and reduced oropharyngeal deposition compared with traditional pressurized devices. Pulmonology clinics in Germany and the United Kingdom are prioritizing these systems for elderly patients with impaired hand-breath coordination. The technology is consolidating manufacturing scale around a narrower supplier base of precision pump and nozzle specialists.
REACH authorization requirements for novel propellant substances are extending development timelines for next-generation metered-dose alternatives. ECHA's stricter hazard classification protocols are forcing reformulation investments that favor companies with integrated analytical toxicology capabilities. European hospital procurement consortia are now requiring documented lifecycle carbon footprints for inhaler device selections.
Specialty pharmacy distribution is displacing traditional wholesale channels for severe asthma biologics as patient support programs and prior authorization management become core value-added services. United States payers are mandating specialty pharmacy lock-in for IL-5 and IL-4/13 inhibitors to capture rebate transparency and adherence data. This channel consolidation is most advanced in Medicare Part D and commercial managed care plans.
Global Asthma Therapeutics Market Segmentation
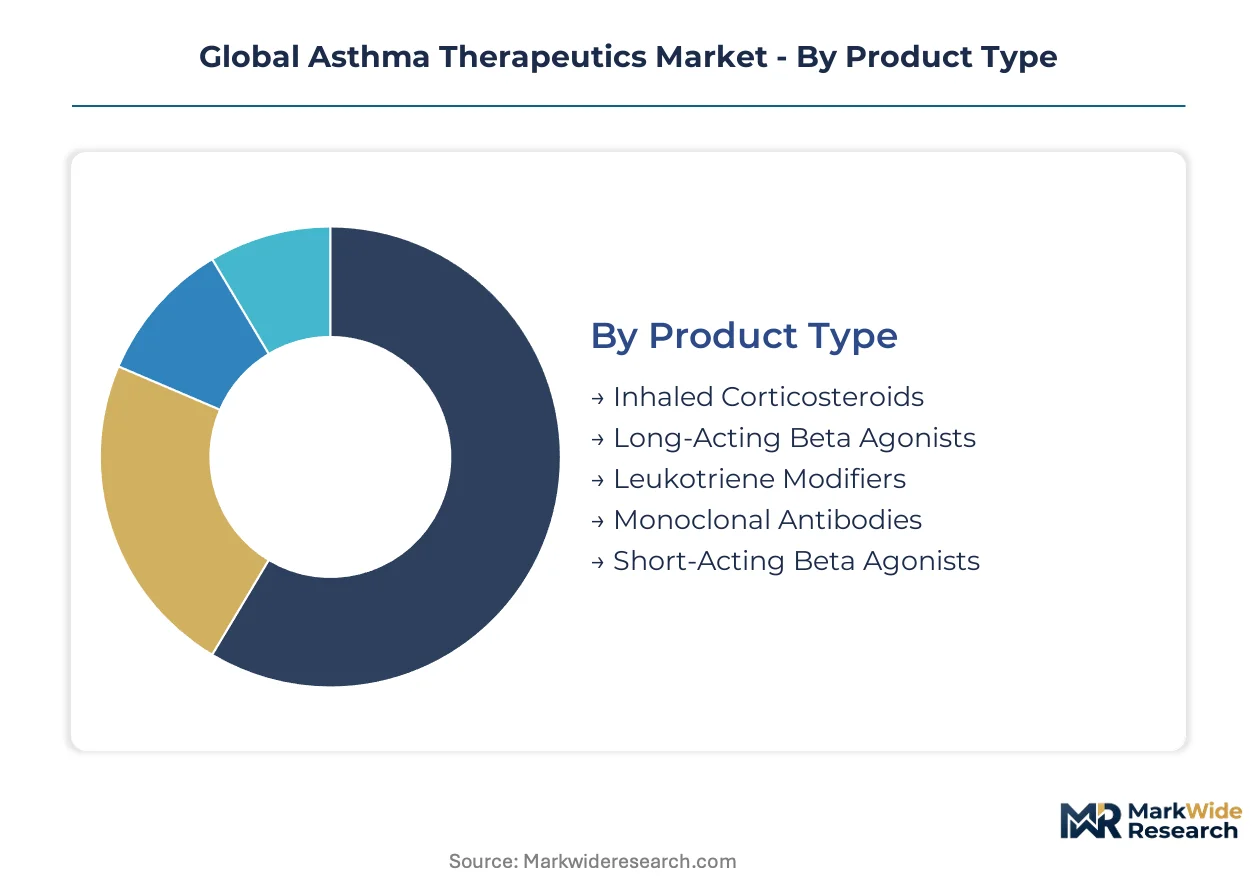
Asthma therapeutics segmentation reveals how treatment modality, disease severity, and care setting interact to determine access pathways and reimbursement structures. Product type and therapy area dimensions capture the core clinical decision hierarchy, while end user and route of administration segments reflect evolving site-of-care economics and patient self-management capabilities.
Product Type:
Standalone maintenance therapies dominate prescribing volume, whereas biologic platforms increasingly embed within comprehensive severe asthma management protocols.
- Inhaled Corticosteroids:These agents deliver localized glucocorticoid activity directly to bronchial tissue, minimizing systemic exposure. Demand concentrates in primary care networks across Germany and Japan where first-line maintenance protocols standardize budesonide and fluticasone propionate prescribing. EMA bioequivalence requirements for generic substitutions are tightening analytical validation standards.
- Monoclonal Antibodies:Engineered proteins targeting IL-5, IL-4/13, or IgE pathways interrupt eosinophilic inflammation cascades. Severe asthma centers in the United States prioritize these agents for steroid-refractory patients, with specialty pharmacy networks managing cold-chain distribution and prior authorization workflows.
- Long-Acting Beta Agonists:These bronchodilators provide sustained smooth muscle relaxation through beta-2 adrenergic receptor activation. Formoterol and salmeterol dominate combination products with inhaled corticosteroids.
- Leukotriene Modifiers:Oral agents blocking cysteinyl leukotriene receptors or synthesis enzymes suit pediatric populations with adherence challenges to inhaled regimens.
- Short-Acting Beta Agonists:Rapid-onset rescue medications remain essential for acute symptom relief, though overuse patterns trigger care pathway interventions.
Volume placements concentrate in inhaled corticosteroids; the faster expansion belongs to monoclonal antibodies.
Therapy Area:
Severe persistent phenotypes command premium pricing through biologic eligibility, while mild persistent cases sustain volume through broad primary care penetration.
- Severe Persistent Asthma:Characterized by poor control despite high-dose inhaled corticosteroid-plus-long-acting beta agonist therapy, this segment requires phenotypic stratification for biologic selection. Tertiary referral centers in Tokyo and Osaka are establishing dedicated severe asthma units with embedded eligibility screening.
- Mild Persistent Asthma:Low-dose inhaled corticosteroid maintenance defines this population, with symptom-guided adjustment protocols reducing overtreatment. Community health systems in the United States leverage this segment for value-based contract performance metrics.
- Moderate Persistent Asthma:Medium-dose controller therapy with periodic exacerbation risk assessment occupies the clinical middle ground.
- Exercise-Induced Bronchoconstriction:Pre-exercise short-acting beta agonist use or leukotriene modifier prophylaxis addresses this discrete trigger-specific phenotype.
- Nocturnal Asthma:Circadian symptom patterns drive modified release formulations and sleep-disordered breathing screening protocols.
Patient volumes cluster in mild persistent asthma; severe persistent asthma is climbing the fastest on a value basis.
End User:
Site-of-care migration from institutional settings toward home-based administration is redistributing stakeholder influence across the value chain.
- Specialty Pharmacies:These channels integrate biologic dispensing with patient support programs, adherence monitoring, and payer prior authorization management. United States Medicare Part D and commercial plans increasingly mandate lock-in arrangements for IL-5 and IL-4/13 inhibitors to capture rebate transparency.
- Pulmonology Clinics:Specialist-directed care coordinates diagnostic workup, phenotyping, and treatment escalation decisions. German hospital-affiliated respiratory centers are expanding biologic infusion capacity.
- Pediatric Care Units:Age-appropriate device selection and caregiver education priorities shape this segment's service requirements.
- Respiratory Therapy Centers:These facilities concentrate nebulization services and pulmonary rehabilitation for complex cases.
- Home Healthcare Providers:Subcutaneous biologic self-administration and connected inhaler programs are extending this segment's scope.
Prescription volumes flow through pulmonology clinics; specialty pharmacies are gaining share fastest in biologic distribution.
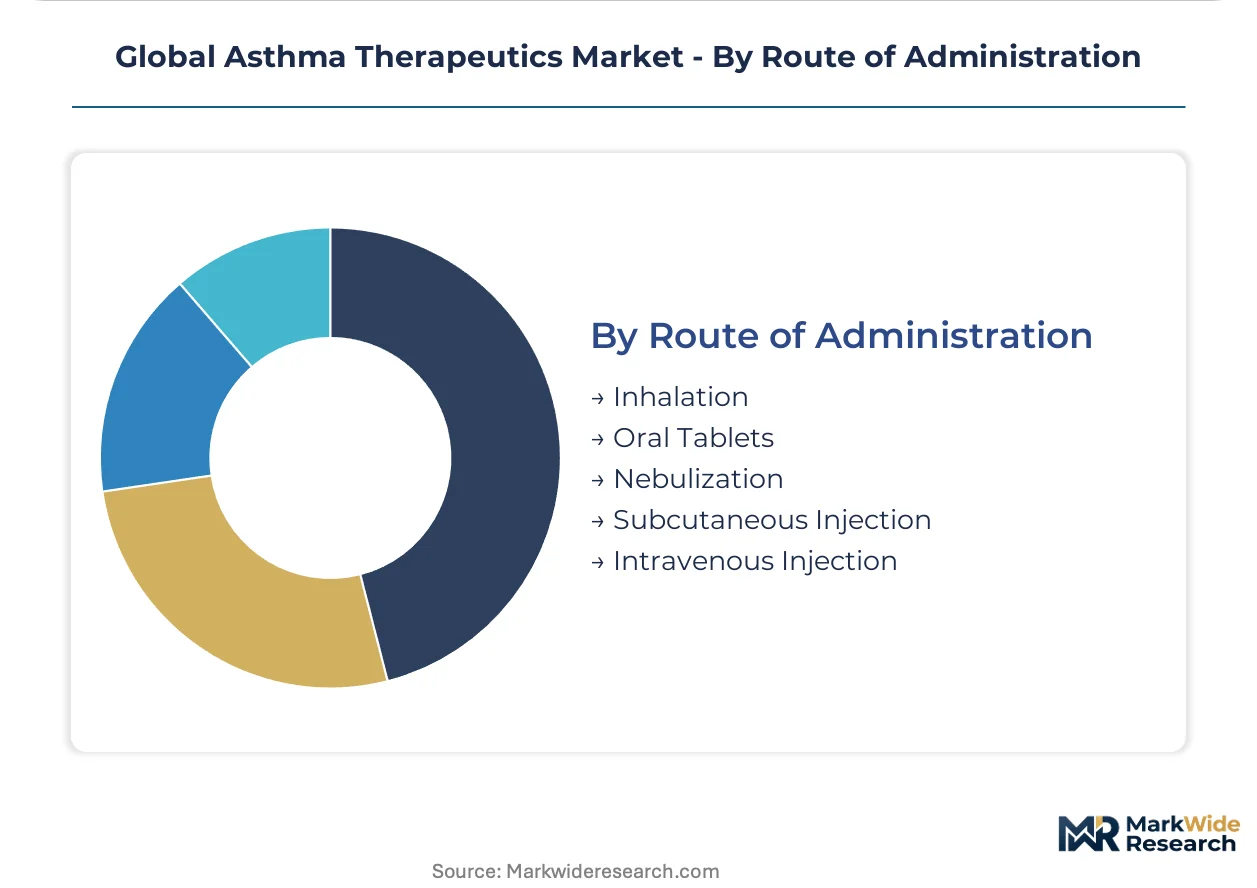
Route of Administration:
Device-dependent inhalation maintains dominance, though injection routes are capturing biologic-eligible severe asthma populations.
- Inhalation:Pressurized metered-dose and dry powder devices deliver medication directly to target airways. EU F-Gas Regulation timelines are accelerating transitions toward HFA-152a propellants and powder platforms in France and the United Kingdom.
- Subcutaneous Injection:Prefilled syringe and autoinjector formats enable biologic self-administration after loading doses. Patient training programs in Japanese severe asthma centers are standardizing home injection protocols.
- Nebulization:Aerosol generation for patients unable to coordinate breath-actuated devices persists in acute and pediatric settings.
- Oral Tablets:Leukotriene modifiers and theophylline derivatives serve adherence-challenged populations.
- Intravenous Injection:Hospital-based biologic loading doses and acute rescue protocols retain limited application.
Administration volumes rest with inhalation; subcutaneous injection is expanding most quickly among severe asthma biologics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors severe asthma biologics access in Asia-Pacific through PMDA's Sakigake fast-track pathway, while the EU F-Gas Regulation drives inhaler platform transitions across European hospital networks.
United States
Pulmonology practices in Boston and New York Metro restructure around biologic eligibility screening protocols. FDA accelerated approval pathways compress development timelines for IL-5 pathway inhibitors. Specialty pharmacy networks in California and Texas manage cold-chain distribution for monoclonal antibodies under Medicare Part D lock-in arrangements.
Germany
Hospital-affiliated respiratory centers in Munich and Hamburg expand dedicated biologics infusion capacity for severe eosinophilic phenotypes. EMA conditional marketing authorizations enable earlier patient access to novel biologic entities. The EU F-Gas Regulation accelerates dry powder inhaler procurement across Bavarian and North Rhine-Westphalian hospital consortia.
Japan
Severe asthma centers in Osaka and Nagoya prioritize PMDA Sakigake-designated agents in formulary negotiations. METI industrial policy supports domestic manufacturing scale for precision inhaler devices. Patient training programs standardize subcutaneous biologic self-administration protocols in Kanto region clinics.
United Kingdom
NHS England procurement frameworks mandate lifecycle carbon footprint documentation for inhaler device selections. REACH authorization requirements extend development timelines for HFA-152a propellant formulations. Pulmonology clinics in London and Manchester prioritize soft-mist inhaler platforms for elderly populations with impaired coordination.
India
CDSCO's abbreviated biosimilar approval framework attracts domestic manufacturing investment for IL-5 and IgE-targeted alternatives. Maharashtra and Gujarat-based producers scale generic corticosteroid output for Central and Eastern European tender markets. Cold-chain infrastructure gaps in sub-regional markets limit biologic penetration outside major metros.
Global Asthma Therapeutics Market Competitive Landscape
The competitive structure tilts toward integrated pharmaceutical conglomerates with captive respiratory device engineering capabilities. Large-scale manufacturers with dual biologics and small-molecule portfolios dominate severe asthma segments, while generic specialists capture maintenance therapy volume through tender participation. Three archetypes prevail: biologics-focused innovators, diversified respiratory platforms, and cost-optimized generic manufacturers. M&A activity concentrates on device technology acquisitions and regional distribution network consolidation.
Within the diversified respiratory platform tier, GlaxoSmithKline plc and AstraZeneca plc exemplify integrated players with end-to-end control from molecule development through precision inhaler manufacturing. Teva Pharmaceutical Industries Ltd. occupies a distinct position as a scale-driven generic specialist with established Central and Eastern European market presence. These three anchors represent the spectrum from premium biologics innovation to volume-leadership in established maintenance therapies.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| AstraZeneca plc |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Boehringer Ingelheim International GmbH |
| Sanofi |
| F. Hoffmann-La Roche Ltd. |
| Merck & Co., Inc. |
| Amgen Inc. |
| Others |
Supply & Pricing Matrix
Severe persistent asthma biologics command a three-tier pricing structure across premium, standard, and economy levels that stratifies procurement across United States specialty pharmacies, German hospital consortia, and Indian tender markets, with each tier tethered to distinct cold-chain infrastructure investments and regulatory documentation burdens.
Pricing Analysis
Value-based pricing anchors biologic reimbursement through measurable exacerbation reduction and oral corticosteroid-sparing outcomes. FDA breakthrough therapy designations and EMA conditional marketing authorizations enable premium positioning for IL-5 and IL-4/13 pathway inhibitors. Price differentiation separates originator biologics from emerging biosimilars, with CDSCO abbreviated pathways in India compressing margins for reference products. Pricing pressure stems from European hospital procurement consortia mandating lifecycle carbon footprint documentation for inhaler selections. United States Medicare Part D plans exhibit highest price sensitivity through mandatory specialty pharmacy lock-in arrangements, while Japanese severe asthma centers show lowest sensitivity due to PMDA Sakigake fast-track premium positioning.
Supply Chain Analysis
Reverse-logistics networks for temperature-controlled biologics remain underdeveloped across Sub-Saharan Africa and Southeast Asia, constraining patient access and creating regional supply fragmentation. Manufacturing concentrates in the United States, Germany, and Japan for precision inhaler devices, with India scaling generic corticosteroid output for Central and Eastern European tenders. Raw material dependencies center on HFA-152a propellant supply from three chemical manufacturers, monoclonal antibody active pharmaceutical ingredients, and specialized polymer components for dry powder inhaler reservoirs. Single-source vulnerability in low-global-warming-potential propellant production creates input bottleneck risk. Distribution runs through specialty pharmacy networks for biologics and wholesale channels for maintenance therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
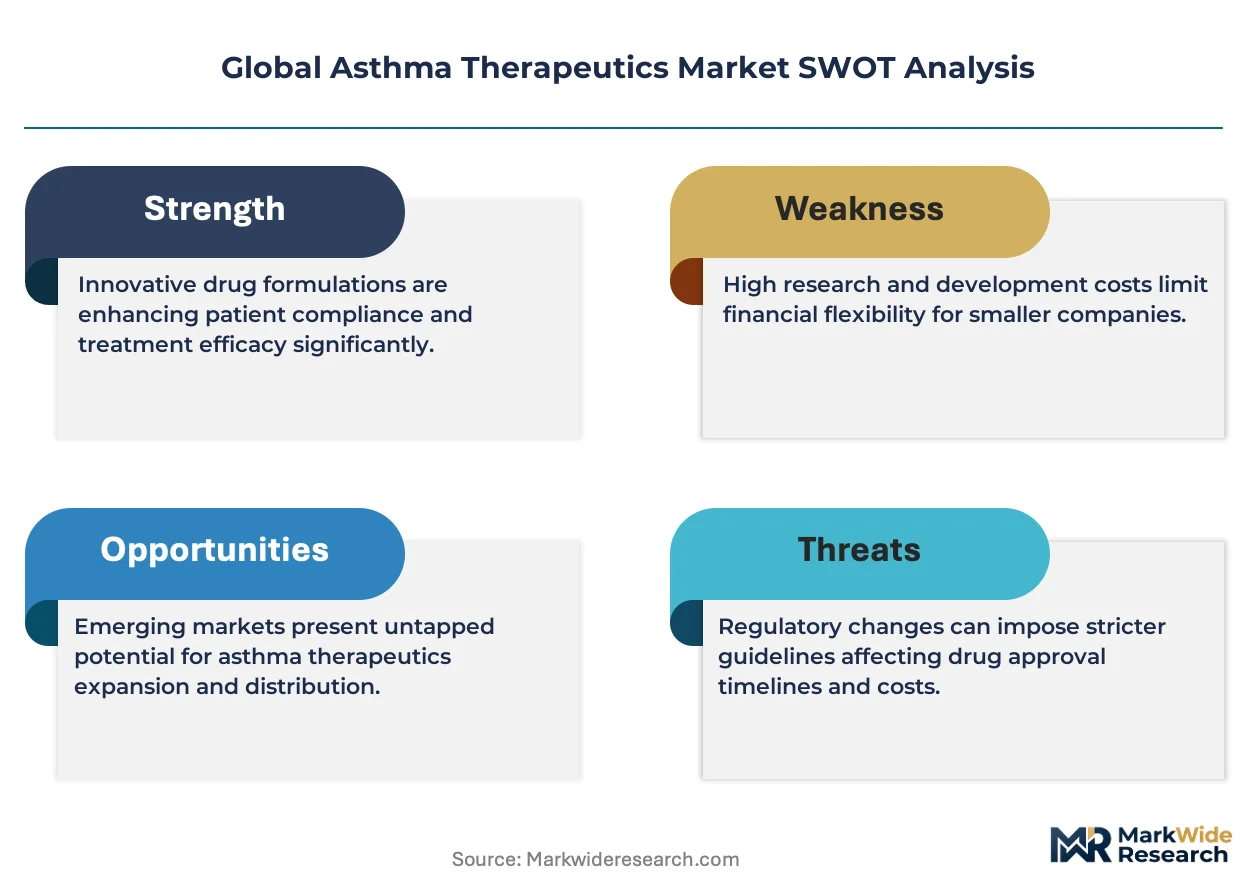
The Global Asthma Therapeutics Market operates as a cost-of-compliance story where EU F-Gas Regulation timelines and REACH authorization requirements erect formidable barriers to entry that favor incumbents with integrated device engineering and analytical toxicology capabilities.
For Market Incumbents: Anticipate stranded asset risk in legacy HFA-134a supply chains by accelerating dry powder inhaler platform transitions and securing captive HFA-152a propellant offtake agreements. Consolidate formulation expertise through targeted acquisition of precision pump and nozzle specialists to defend against device engineering specialists gaining share in soft-mist segments. For New Entrants and Emerging Players: Launch via India's CDSCO biosimilar pathway to capture first-mover positioning in IL-5 and IgE-targeted alternatives for domestic and export markets. Target telehealth-integrated adherence monitoring platforms as the most penetrable white space, deploying connected inhaler devices with subscription-based revenue models beyond traditional drug-plus-device bundling. For Investors and Strategic Acquirers: Re-rating potential sits with diversified respiratory platforms given biologics-plus-device integration requirements and propellant transition timelines compressing competitive windows. Long-term viability favors manufacturers with backward integration into precision inhaler components and validated cold-chain infrastructure. Monitor ECHA hazard classification protocol revisions as the critical signal for reformulation investment intensity and consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Device Platform Transition | EU F-Gas Regulation deadlines force HFA-152a and dry powder investments by 2027. |
| Biosimilar Development Partnership | CDSCO abbreviated pathways enable Indian domestic manufacturing for IL-5 alternatives. |
| Specialty Pharmacy Network Acquisition | Medicare Part D lock-in arrangements capture rebate transparency and adherence data. |
| Precision Pump Supplier Integration | Soft-mist inhaler consolidation narrows supplier base for nozzle engineering specialists. |
| Connected Inhaler Platform Launch | Remote patient management opens subscription revenue beyond drug-plus-device bundling. |
Research Methodology
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists across the United States, Germany, and Japan. Secondary validation drew from SEC 10-K disclosures, EU Green Deal implementation reports, and PMDA Sakigake designation announcements. Bottom-up patient flow modeling and top-down pharmaceutical market sizing were triangulated to cross-verify volume and value estimates.
Output metrics span treatment line, dosage form, administration route, patient population severity tiers, and regional regulatory clusters across the analysis window. CAGRs were derived from log-linear trend fitting applied to historic pricing and volume trajectories, adjusted for propellant transition timelines and biologics penetration curves. Forecast inputs incorporated EMA accelerated assessment pathway success rates, specialty pharmacy network expansion trajectories, and CDSCO biosimilar approval velocity.
Regulatory deadline delays, propellant supply disruptions, and biologics cold-chain infrastructure failures are the dominant revision risks to modeled projections. Practitioners should monitor ECHA hazard classification updates, HFA-152a manufacturer capacity announcements, and PMDA Sakigake designation grants for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Ibuprofen API Market
Pharmacology
Intranasal Drug and Vaccine Delivery Market
Pharmacology
Artemisinin Antimalarial Drugs Market
Pharmacology
Global Migraine Therapeutics Market
Pharmacology
Clot Busting Drugs Market
Pharmacology
Medication Adherence Market
Pharmacology
Anti-Asthma Drugs Market
Pharmacology
Antimycotics Market
Pharmacology
Cough Remedies Market
Pharmacology
Anti-Hypertensive Drugs Market
Pharmacology
Autacoids and Related Drugs Market
Pharmacology
Ketoprofen API Market
Pharmacology
Anti-Obesity Therapeutics Market
Pharmacology
Hydroxychloroquine Drugs Market
Pharmacology
Global Olanzapine Market
Pharmacology
Alzheimer Drugs Market