
 Embolization Plugs Market | 2026-2036
Embolization Plugs Market Size, Share, and Industry Trends Forecast 2026-2036
Embolization Plugs Market Foresight
Multi-source procurement for nitinol and polymer feedstocks is rebalancing as device makers diversify away from concentrated Asian suppliers. Medtronic leverages captive manufacturing in Costa Rica and Ireland to sustain supply continuity for its embolization portfolio. Boston Scientific Corporation anchors its competitive position through deep specialization in peripheral interventional devices. Terumo Corporation differentiates via integrated catheter and plug systems that reduce procedural variability in Japanese and European hospital settings.
Embolization plugs are implantable devices, typically constructed from nitinol, synthetic polymers, or biological matrices, designed to mechanically occlude blood vessels or abnormal vascular channels through catheter-based delivery. These devices function by inducing controlled thrombosis or permanent physical blockage, serving primary purposes in hemorrhage control, tumor devascularization, and structural cardiac defect management. Non-absorbable plugs and plug delivery systems command the dominant revenue share due to their established reimbursement pathways and repeat-use economics in hospital catheterization labs. Bioactive plugs represent the fastest-expanding material category as drug-eluting and pro-healing surface modifications attract investment from interventional radiology departments seeking reduced recurrence rates.
The FDA enforces Class II medical device controls through 510(k) premarket notifications, requiring substantial equivalence demonstrations that shape product development timelines and clinical trial investments for embolization plug manufacturers. The EU Medical Device Regulation and ISO 10993 biocompatibility standards impose additional testing burdens on polymer and biological material selections, directly influencing R&D allocation and market access costs. Stakeholders must monitor evolving FDA guidance on permanent implantable device long-term safety surveillance and the European Commission's ongoing refinement of clinical evidence requirements under MDR Article 61.
Market Dynamics
Catheter-based delivery precision is reshaping embolization plug specifications as interventional radiologists demand tighter size gradations and enhanced fluoroscopic visibility. Device makers now engineer nitinol frameworks with proprietary surface coatings to accelerate thrombosis while maintaining mechanical stability under pulsatile flow conditions.
Growth Catalysts
- FDA 510(k) pathway refinement:Streamlined substantial equivalence demonstrations for second-generation devices accelerate commercialization timelines for manufacturers with predicate device portfolios.
- Interventional radiology program expansion:Tertiary hospitals in Germany and the United States are establishing dedicated vascular malformation centers that generate recurring plug consumption.
- Bioactive surface modifications:Drug-eluting polymer coatings that reduce recanalization rates are attracting clinical investment from departments seeking durable occlusion outcomes.
Market Restraints
- Nitinol feedstock concentration:Specialized shape-memory alloy supply chains cluster in select Asian metallurgical centers, exposing device makers to alloying element price volatility and export licensing delays.
- EU MDR clinical evidence escalation:Article 61 requirements for permanent implantable devices mandate extended follow-up studies that extend time-to-market by 18-36 months for novel materials.
- Mechanical embolization alternatives:Detachable coils and liquid embolics compete for intracranial and peripheral vascular indications where plug delivery catheter access remains challenging.
Strategic Opportunities
- Pediatric congenital heart defect closure:Bioabsorbable plug platforms address unmet need in growing patients where permanent implants complicate future surgical interventions.
- Japanese integrated delivery systems:Terumo's catheter-plug bundled configurations demonstrate procurement preference in metropolitan hospital networks seeking reduced procedural variability.
- Outpatient interventional suites:Ambulatory surgical centers in the United States are expanding embolization capacity for uterine fibroid and varicocele procedures previously confined to inpatient settings.
Industry Challenges
- Interventional radiology fellowship pipeline constraints:Specialized training programs in Germany and Japan produce insufficient operators to match installed catheterization lab capacity, creating procedural bottlenecks.
- ISO 10993 biocompatibility testing backlog:Contract laboratory capacity constraints for cytotoxicity and sensitization assays delay regulatory submission timelines for polymer formulation iterations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embolization Plugs Market |
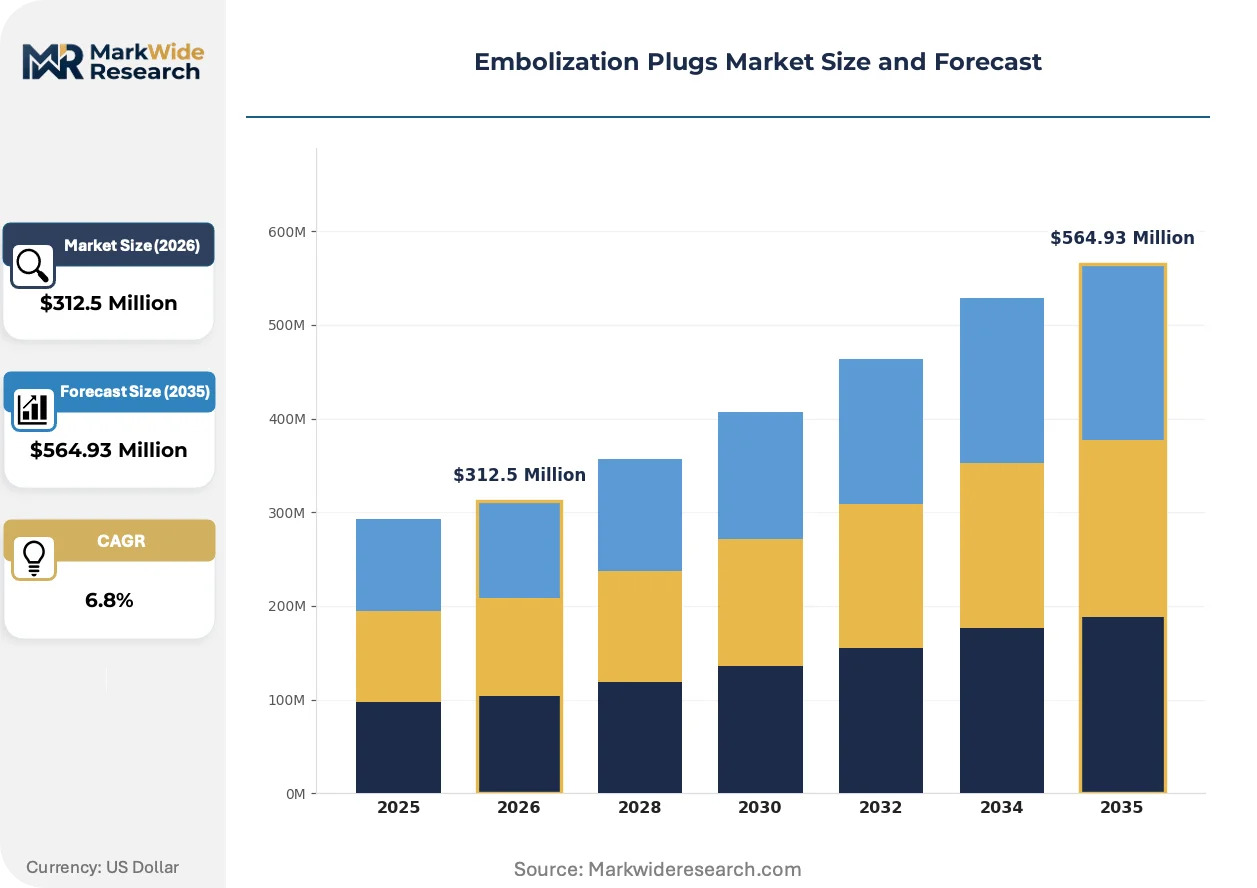
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable Plugs, Non-Absorbable Plugs, Plug Delivery Systems, Bioactive Plugs End User: Hospitals, Outpatient Clinics, Specialty Clinics, Research Laboratories Application: Vascular Embolization, Tumor Embolization, Gastrointestinal Bleeding, Uterine Fibroids Material: Polymer, Metal, Biological, Composite |
| Companies Covered | Medtronic, Boston Scientific Corporation, Terumo Corporation, Abbott Laboratories, Stryker Corporation, Cook Medical, Merit Medical Systems, Shape Memory Medical, ArtVentive Medical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embolization Plugs Market Shifts & Advancements
Surface engineering and delivery system integration are displacing standalone device competition. Manufacturers now compete on thrombogenic kinetics and fluoroscopic traceability rather than mechanical occlusion alone.
Shape-memory polymer composites are converging with radiopaque filler technologies to produce plugs with enhanced visualization under reduced radiation dose protocols. Interventional radiology departments in German university hospitals are piloting these platforms for complex arteriovenous malformation embolizations. The structural consequence is compression of traditional nitinol-only devices into commodity positioning while premium pricing accrues to integrated material systems.
EU MDR recertification deadlines are forcing portfolio rationalization among mid-tier device manufacturers. Technical documentation gaps for legacy products are triggering voluntary market withdrawals that concentrate shelf space with firms possessing dedicated regulatory affairs infrastructure. Peripheral vascular plug categories face the steepest compliance cost escalation due to extended clinical follow-up requirements for permanent implants.
Hospital procurement committees are consolidating vendor relationships around full-line interventional suppliers capable of catheter, guidewire, and plug system integration. Independent device specialists without captive catheter platforms face exclusion from preferred supplier agreements in United States hospital networks. This consolidation is most visible in integrated delivery networks where standardization across multiple catheterization labs drives volume commitments to single-source contracts.
Embolization Plugs Market Segmentation
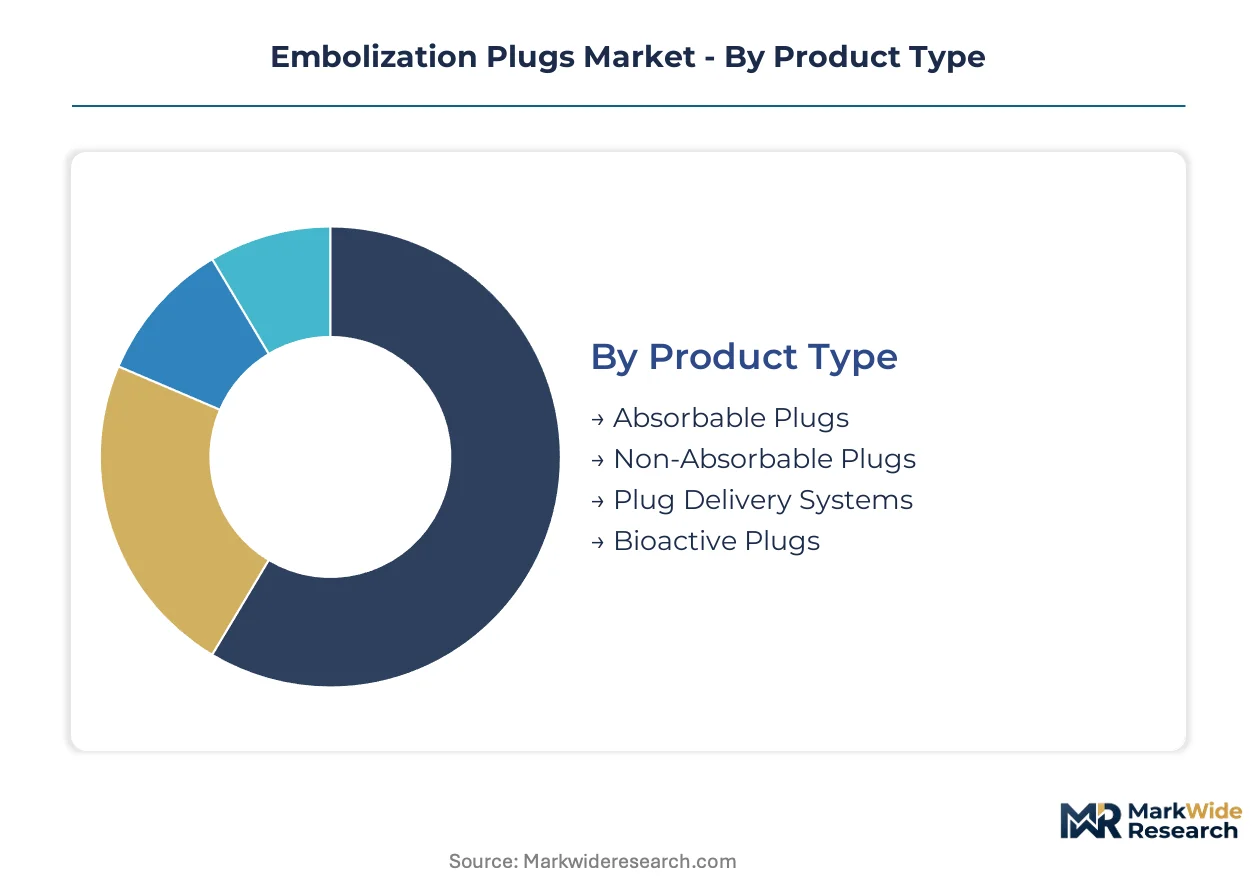
Segmentation in embolization plugs reveals how procurement committees, reimbursement pathways, and procedural settings fragment demand across incompatible technical specifications. Material choices and delivery system integration determine hospital vendor consolidation patterns.
Product Type:
Reimbursement tier and procedural repeat-use economics drive hospital procurement decisions across plug categories.
- Non-Absorbable Plugs:Nitinol and polymer constructs provide permanent mechanical occlusion with established CPT coding for peripheral vascular and structural heart indications. Tertiary hospital networks in the United States and Germany generate recurring consumption through dedicated interventional radiology programs treating vascular malformations.
- Plug Delivery Systems:Integrated catheter-plug configurations reduce procedural variability and fluoroscopy time in complex embolizations. Japanese metropolitan hospital networks demonstrate procurement preference for bundled systems that standardize operator technique across multiple catheterization labs.
- Absorbable Plugs:Bioabsorbable polymer matrices address pediatric congenital heart defects where permanent implants complicate future surgical interventions.
- Bioactive Plugs:Drug-eluting and pro-healing surface modifications attract investment from departments seeking reduced recanalization rates in tumor devascularization.
Volume sits with Non-Absorbable Plugs; growth tilts toward Bioactive Plugs.
End User:
Facility accreditation status and catheterization lab infrastructure determine addressable market boundaries.
- Hospitals:Tertiary academic medical centers with interventional radiology fellowship programs perform complex embolizations requiring multiple plug sizes and rescue device availability. German university hospitals and United States integrated delivery networks concentrate the highest procedure volumes.
- Outpatient Clinics:Ambulatory surgical centers in the United States are expanding embolization capacity for uterine fibroid and varicocele procedures previously confined to inpatient settings.
- Specialty Clinics:Dedicated vascular malformation centers in Japan and Germany generate concentrated demand for precision delivery systems.
- Research Laboratories:Preclinical testing facilities support bioactive coating development and thrombogenicity validation for regulatory submission pipelines.
Procedure concentration favors Hospitals; capacity expansion runs through Outpatient Clinics.
Application:
Clinical indication complexity dictates plug material selection and delivery catheter specifications.
- Vascular Embolization:Arteriovenous malformation and aneurysm occlusion requires precise size matching and radiopaque visualization under reduced radiation dose protocols. German university hospitals pilot shape-memory polymer composites for these complex procedures.
- Uterine Fibroids:Uterine artery embolization demands consistent occlusion durability with minimal recurrence; bioactive surface modifications are gaining clinical investment for this indication.
- Tumor Embolization:Hepatic and renal tumor devascularization utilizes permanent plugs for pre-surgical embolization and palliative care.
- Gastrointestinal Bleeding:Emergency hemorrhage control requires rapid deployment capability and mechanical stability under pulsatile flow conditions.
Technical complexity peaks in Vascular Embolization; standardization pressure concentrates in Uterine Fibroids.
Material:
Supply chain geography and regulatory testing burden shape material selection trade-offs.
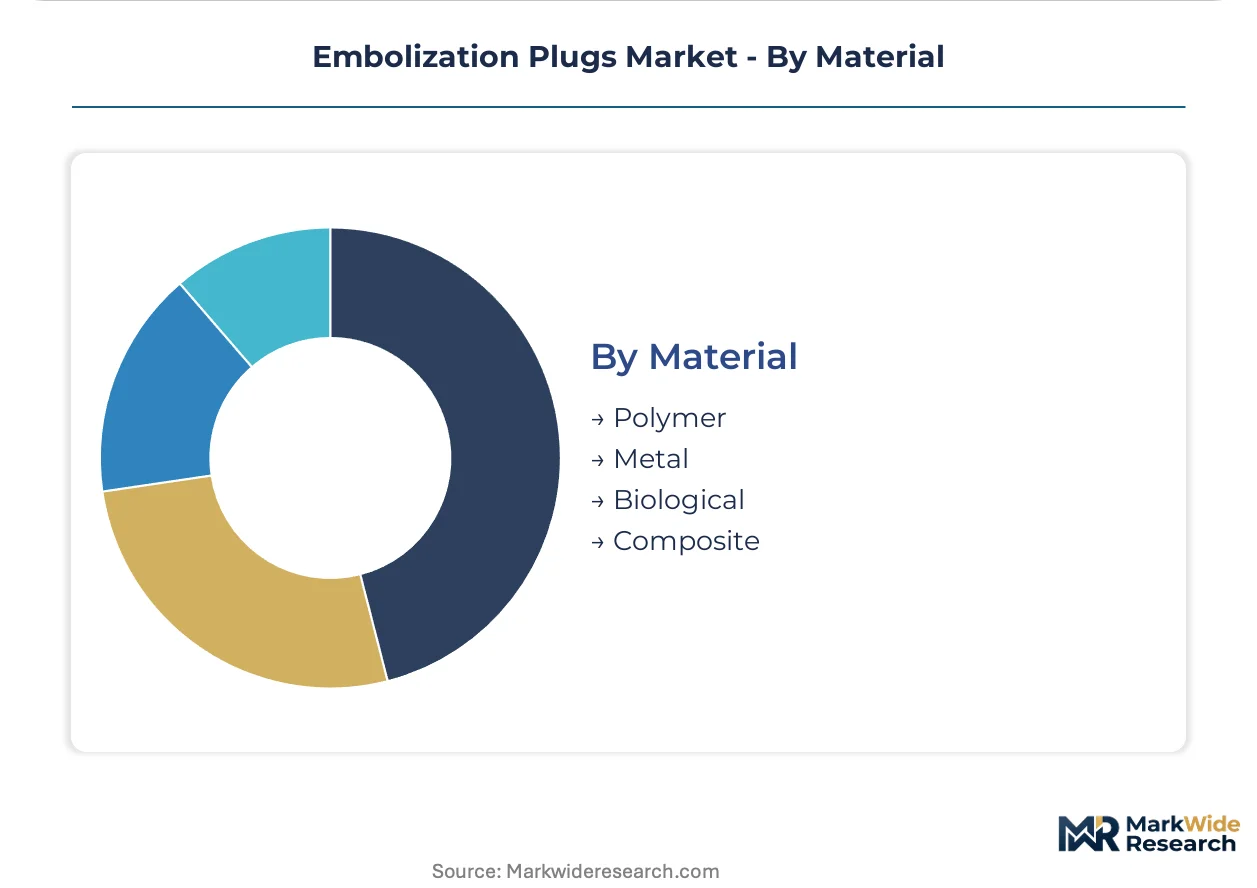
- Metal:Nitinol shape-memory alloys dominate permanent plug frameworks; specialized metallurgical supply chains cluster in select Asian centers, exposing device makers to alloying element price volatility.
- Polymer:Synthetic matrices enable absorbable and drug-eluting configurations; ISO 10993 biocompatibility testing backlogs delay formulation iterations.
- Biological:Collagen and extracellular matrix derivatives address pro-healing requirements; EU MDR Article 61 mandates extended follow-up studies for novel biological materials.
- Composite:Hybrid metal-polymer systems integrate mechanical stability with surface modifiability; radiopaque filler technologies enhance fluoroscopic traceability.
Established revenue flows through Metal; formulation innovation concentrates in Composite.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States and Germany concentrate the highest procedure volumes for embolization plugs, while Japanese metropolitan networks drive integrated delivery system adoption. Tertiary academic medical centers across these three countries anchor interventional radiology program expansion.
United States
Ambulatory surgical centers in Florida and Texas are expanding uterine fibroid embolization capacity previously confined to inpatient settings. FDA 510(k) pathway refinements for second-generation devices accelerate commercialization timelines for manufacturers with predicate portfolios. Integrated delivery networks in the Southeast standardize catheterization lab procurement across multiple facilities.
Germany
University hospitals in Bavaria and North Rhine-Westphalia pilot shape-memory polymer composites for complex arteriovenous malformation procedures. EU MDR Article 61 mandates extended clinical follow-up studies that extend time-to-market for novel materials. The Munich and Berlin metropolitan clusters concentrate vascular malformation center establishment.
Japan
Metropolitan hospital networks in Tokyo and Osaka demonstrate procurement preference for bundled catheter-plug systems that reduce procedural variability. PMDA consultation procedures shape clinical evidence requirements for permanent implantable devices. The Kanto region anchors integrated delivery system adoption.
China
Provincial hospital networks in Shanghai and Beijing expand interventional radiology fellowship programs to address operator pipeline constraints. NMPA medical device registration pathways require substantial equivalence demonstrations for imported embolization technologies. The Yangtze River Delta concentrates tertiary hospital infrastructure investment.
United Kingdom
NHS England specialized commissioning frameworks concentrate complex embolization procedures in designated vascular centers across London and Manchester. MHRA post-market surveillance requirements align with EU MDR clinical evidence standards during regulatory transition. The Southeast and Midlands regions host the highest catheterization lab density.
Embolization Plugs Market Competitive Landscape
Portfolio rationalization dominates the current landscape as EU MDR recertification deadlines force technical documentation gaps into voluntary market withdrawals. The vendor base concentrates around full-line interventional suppliers capable of catheter, guidewire, and plug system integration. Three strategic archetypes emerge: diversified medical technology conglomerates with captive manufacturing infrastructure, specialized peripheral interventional device makers, and integrated catheter-plug system specialists. Competitive moves center on regulatory affairs infrastructure investment and preferred supplier agreement consolidation with hospital procurement committees.
Among diversified medical technology conglomerates, Medtronic and Boston Scientific Corporation exemplify scale-driven positions anchored by captive manufacturing in Costa Rica and Ireland. Terumo Corporation occupies a specialist tier representing integrated delivery system configurations that reduce procedural variability in Japanese and European hospital settings. These three entities illustrate how manufacturing geography and bundled product architectures differentiate competitive positioning.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Terumo Corporation |
| Abbott Laboratories |
| Stryker Corporation |
| Cook Medical |
| Merit Medical Systems |
| Shape Memory Medical |
| ArtVentive Medical Group |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between FDA-cleared Class II devices and economy-tier alternatives manifests in both procurement premiums and metallurgical sourcing strategies. Premium plug manufacturers command price multiples through captive nitinol supply arrangements in Ireland and Costa Rica, while commodity competitors absorb margin compression from concentrated Asian alloy feedstock exposure.
Pricing Analysis
Volume concentration in non-absorbable nitinol plugs runs counter to margin capture in bioactive surface-modified devices. Three-tier pricing structure across premium integrated systems, standard standalone plugs, and economy bare-metal configurations reflects FDA predicate pathway investment and EU MDR compliance burden differentiation. Pricing pressure stems from EU MDR Article 61 clinical evidence escalation extending time-to-market for novel materials. Hospital procurement committees in United States integrated delivery networks demonstrate lowest price sensitivity for bundled catheter-plug systems, while ambulatory surgical centers prioritize per-unit economy.
Supply Chain Analysis
Domestic-content mandates under the EU Medical Device Regulation and Japan's PMDA consultation procedures are reshaping sourcing toward European and Japanese manufacturing footprints. Nitinol shape-memory alloy supply concentrates in China, Japan, and specialized German metallurgical centers; polymer feedstock draws from South Korean and United States chemical producers. Single-source vulnerability in Asian alloying element supply exposes device makers to export licensing delays. Distribution runs through hospital procurement committees and GPO contracts in United States tertiary networks, with direct manufacturer relationships dominating Japanese metropolitan hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The embolization plugs market sits in a material-transition phase as shape-memory polymer composites displace traditional nitinol-only constructs in complex vascular procedures. This technology inflection demands repositioning across incumbent, entrant, and investor archetypes.
For Market Incumbents: To counter portfolio rationalization pressures from EU MDR recertification deadlines, Medtronic and Boston Scientific Corporation should deepen captive manufacturing infrastructure in Costa Rica and Ireland while accelerating bioactive coating R&D pipelines. Backward integration into nitinol feedstock through dedicated metallurgical partnerships reduces Asian supply concentration risk. For New Entrants and Emerging Players: The premium-to-economy price gap in pediatric absorbable plugs offers white-space entry for specialized polymer formulation specialists. Target United States ambulatory surgical center expansion for uterine fibroid procedures with simplified delivery catheter configurations. Pursue hospital system partnership models that bundle training with device procurement to overcome interventional radiologist pipeline constraints. For Investors and Strategic Acquirers: Re-rating potential sits with integrated catheter-plug system specialists given Japanese procurement preference for bundled configurations reducing procedural variability. Five-to-ten year viability favors firms with dedicated regulatory affairs infrastructure navigating FDA 510(k) pathway refinements. Monitor EU MDR technical documentation completion rates as inflection indicator for market share consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Extended clinical follow-up studies under Article 61 preserve market access for permanent implantable devices. |
| Bioactive Surface Modification Development | Drug-eluting polymer coatings attract interventional radiology department investment for reduced recanalization outcomes. |
| Integrated Delivery System Bundling | Catheter-plug configurations reduce procedural variability in Japanese and German metropolitan hospital networks. |
| Pediatric Absorbable Platform Expansion | Bioabsorbable matrices address unmet need in growing patients where permanent implants complicate future interventions. |
| Ambulatory Surgical Center Partnership | United States outpatient clinic expansion for uterine fibroid procedures shifts volume from inpatient settings. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with interventional radiologists, hospital procurement managers, biomedical engineers, and GPO contracts specialists combined with FDA 510(k) premarket notifications, EU MDR technical documentation databases, and hospital procurement records. Bottom-up procedure volume estimates triangulated against top-down device shipment data.
Data-stream reconciliation across manufacturer-reported segment revenues and hospital purchasing records validated analytical outputs over the projection horizon. Segmentation dimensions modeled include product type, material composition, end-user facility accreditation, and application complexity. CAGRs derived from procedure volume growth trajectories and device utilization rates per intervention, with nitinol price volatility and EU MDR compliance cost escalation incorporated as scenario variables.
Inputs from FDA premarket databases and EU notified body technical documentation were available through the study window; gaps in private hospital procurement contract terms introduce uncertainty bands around pricing estimates. Forecasts reflect assumptions regarding interventional radiology fellowship pipeline expansion and regulatory pathway stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Vascular Access Devices Market
Medical Devices
Robotic Biopsy Devices Market
Medical Devices
Medical Laser Cutting Device Market
Medical Devices
Prescription Goggles Market
Medical Devices
France Ophthalmic Devices Market
Medical Devices
Spain Aesthetic Devices Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
Fluorescence-Guided Surgery Systems Market
Medical Devices
Depression Devices Market
Medical Devices
Transseptal Access Systems Market
Medical Devices
Artificial Disc Replacement Market
Medical Devices
Global Female Sterilization Devices Market
Medical Devices
GCC Biopsy Devices Market
Medical Devices
Gastroretentive Drug Delivery Systems Market
Medical Devices
Unilateral Biportal Endoscopy Market
Medical Devices
Endodontic Devices Market