
 Non-Invasive Brain Trauma Monitoring Devices Market | 2026-2036
Non-Invasive Brain Trauma Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Invasive Brain Trauma Monitoring Devices Market Intelligence
The EU Medical Device Regulation is hardening conformity requirements for Class IIa and IIb neuromonitoring equipment, compelling manufacturers to expand clinical evidence portfolios. Medtronic leverages its neurosurgical portfolio depth to sustain bedside system placements across Level I trauma centers in North America. Koninklijke Philips N.V. anchors its competitive position through integrated informatics platforms that bridge emergency response workflows with intensive care monitoring. Siemens Healthineers differentiates via magnetic resonance compatibility protocols that enable multimodal trauma assessment protocols.
Non-invasive brain trauma monitoring devices employ acoustic, optical, or electromagnetic sensing modalities to detect cerebral blood flow velocity, tissue oxygenation, or electrical activity without cranial penetration, typically operating at wavelengths between 650-1000 nanometers for near-infrared spectroscopy applications. These systems serve primarily to triage traumatic brain injury severity, guide therapeutic interventions, and flag neurological deterioration before irreversible damage manifests. Electroencephalography systems occupy the largest installed base among product types due to decades of clinical validation in seizure detection and depth-of-anesthesia monitoring, though near-infrared spectroscopy represents the fastest-expanding category as point-of-care cerebral oximetry gains trauma bay adoption. Wearable device architectures are capturing disproportionate R&D investment as ambulatory monitoring protocols extend into post-discharge rehabilitation phases, while cloud-based solutions concentrate margin pools through recurring software licensing structures layered atop hardware placements.
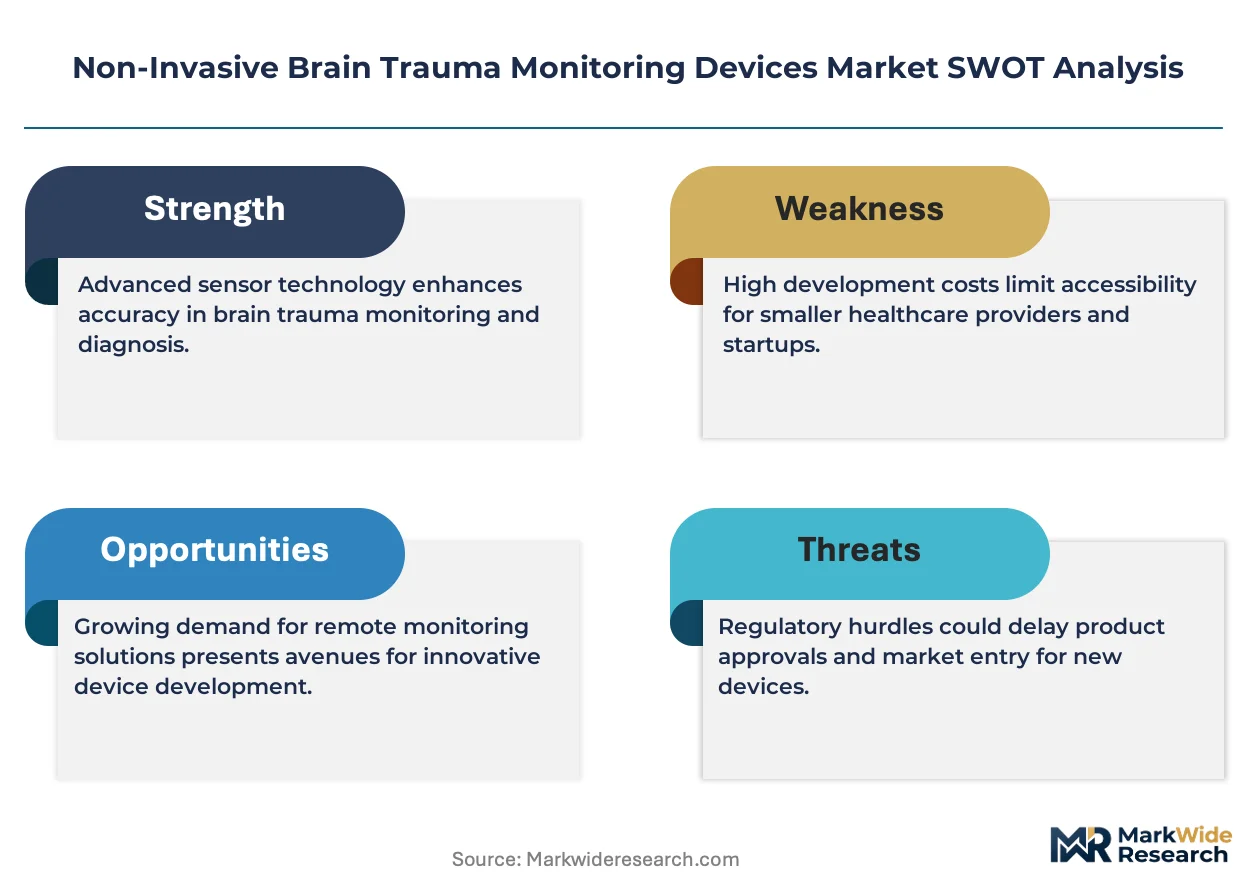
The FDA's breakthrough devices program and the EU MDR's notified body recertification timeline jointly reshape competitive access conditions, with FDA-cleared products commanding premium positioning in US procurement channels while MDR compliance costs filter smaller European entrants. Japan's PMDA enforces distinct clinical trial requirements for software-as-medical-device algorithms, creating separate validation burdens for artificial intelligence-enabled trauma classification tools. Stakeholders must weigh regulatory capital intensity against the pace of sensor miniaturization and wireless power delivery advances that could redefine form factor economics.
Market Dynamics
The FDA breakthrough device designation pathway is compressing commercialization timelines for neurological diagnostics while simultaneously intensifying competitive pressure on evidence-generation standards. This regulatory acceleration mechanism is reshaping capital allocation across sensor modalities and clinical trial designs.
Growth Catalysts
- Emergency department expansion:Level I trauma centers in the United States mandate continuous intracranial pressure surveillance capabilities, creating institutional pull for portable neuromonitoring systems.
- EU MDR recertification timelines:The Medical Device Regulation's notified body capacity constraints are filtering smaller competitors, concentrating procurement authority among established manufacturers with robust quality management systems.
- Near-infrared spectroscopy miniaturization:Advances in 650-1000 nanometer wavelength sensor arrays enable point-of-care cerebral oximetry deployment beyond traditional intensive care settings.
Market Restraints
- Clinical validation costs:Large-scale traumatic brain injury outcome studies require multi-site coordination across tertiary hospital networks, elevating pre-market evidence thresholds.
- Notified body concentration:European Union MDR implementation has reduced the number of designated conformity assessment bodies, extending certification queues for Class IIb neuromonitoring equipment.
- Invasive monitor substitution:Intraparenchymal pressure transducers maintain reference-standard status in severe trauma protocols, limiting reimbursement parity for non-invasive alternatives.
Strategic Opportunities
- Post-discharge ambulatory monitoring:Wearable device architectures for rehabilitation-phase neurological surveillance remain underdeveloped relative to acute-care systems.
- Japan PMDA software-as-medical-device pathway:Distinct clinical trial requirements for artificial intelligence-enabled trauma classification tools create first-mover advantages for algorithm developers.
- Cloud-based recurring revenue models:Software licensing layered atop hardware placements concentrates margin pools through subscription structures in North American hospital procurement channels.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in electromagnetic sensing modality integration with trauma bay workflows commands premium compensation, constraining R&D scaling.
- Legacy electronic health record integration:Intensive care monitoring data streams require proprietary interface development for each major hospital information system vendor, fragmenting deployment resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Invasive Brain Trauma Monitoring Devices Market |
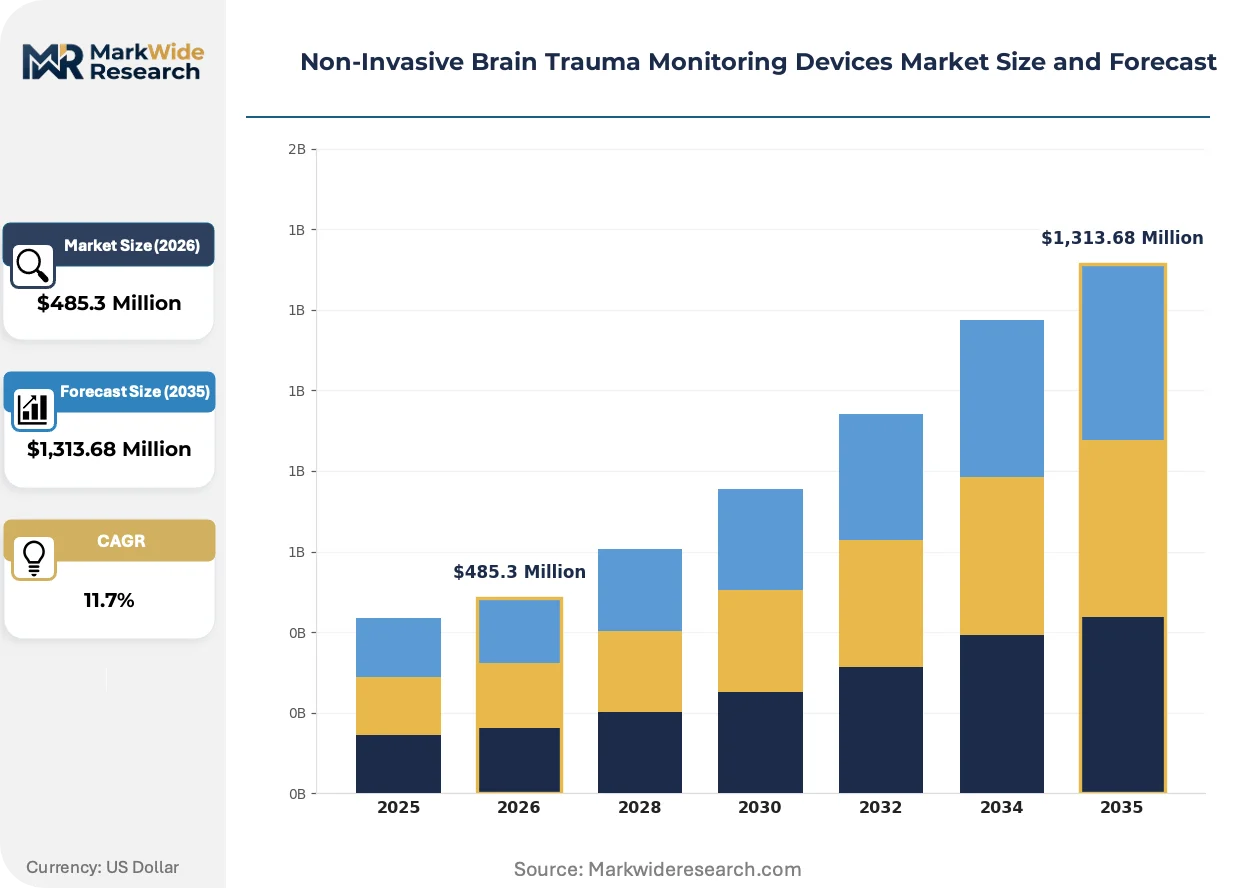
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,313.68 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroencephalography, Transcranial Doppler, Near-Infrared Spectroscopy, Functional MRI Technology: Wearable Devices, Portable Monitors, Bedside Systems, Cloud-Based Solutions End User: Hospitals, Rehabilitation Centers, Research Institutions, Home Care Application: Trauma Assessment, Patient Monitoring, Neurological Research, Emergency Response |
| Companies Covered | Medtronic, Koninklijke Philips N.V., GE Healthcare Technologies, Nihon Kohden Corporation, Natus Medical Incorporated, Siemens Healthineers, Canon Medical Systems Corporation, Advanced Brain Monitoring Inc., Cadwell Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Invasive Brain Trauma Monitoring Devices Market Strategic Shifts & Innovations
Sensor fusion architectures and wireless power delivery systems are redefining form factor economics for bedside neurological assessment. These hardware advances intersect with evolving regulatory frameworks to reshape competitive access conditions.
Near-infrared spectroscopy is overtaking electroencephalography as the dominant modality for point-of-care cerebral oxygenation monitoring. Emergency medicine departments in tertiary hospitals are adopting portable NIRS systems at accelerating rates. This shift is compressing installed base maintenance revenue for traditional EEG vendors while expanding addressable market boundaries into pre-hospital and transport medicine.
MDR notified body recertification timelines in the European Union are hardening conformity requirements for Class IIa and IIb neuromonitoring equipment. Manufacturers must expand clinical evidence portfolios to satisfy expanded post-market surveillance obligations. Smaller European entrants without dedicated regulatory affairs infrastructure are exiting the market, consolidating procurement authority among established players with captive notified body relationships.
Hospital procurement committees now unbundle hardware acquisition from software licensing and service contracts, treating each component as distinct spend categories. Traditional bundled pricing models face pressure from value-analysis teams in United States health systems. This disaggregation is most visible in Level I trauma centers where capital equipment committees operate independently from information technology governance structures.
Non-Invasive Brain Trauma Monitoring Devices Market Segmentation
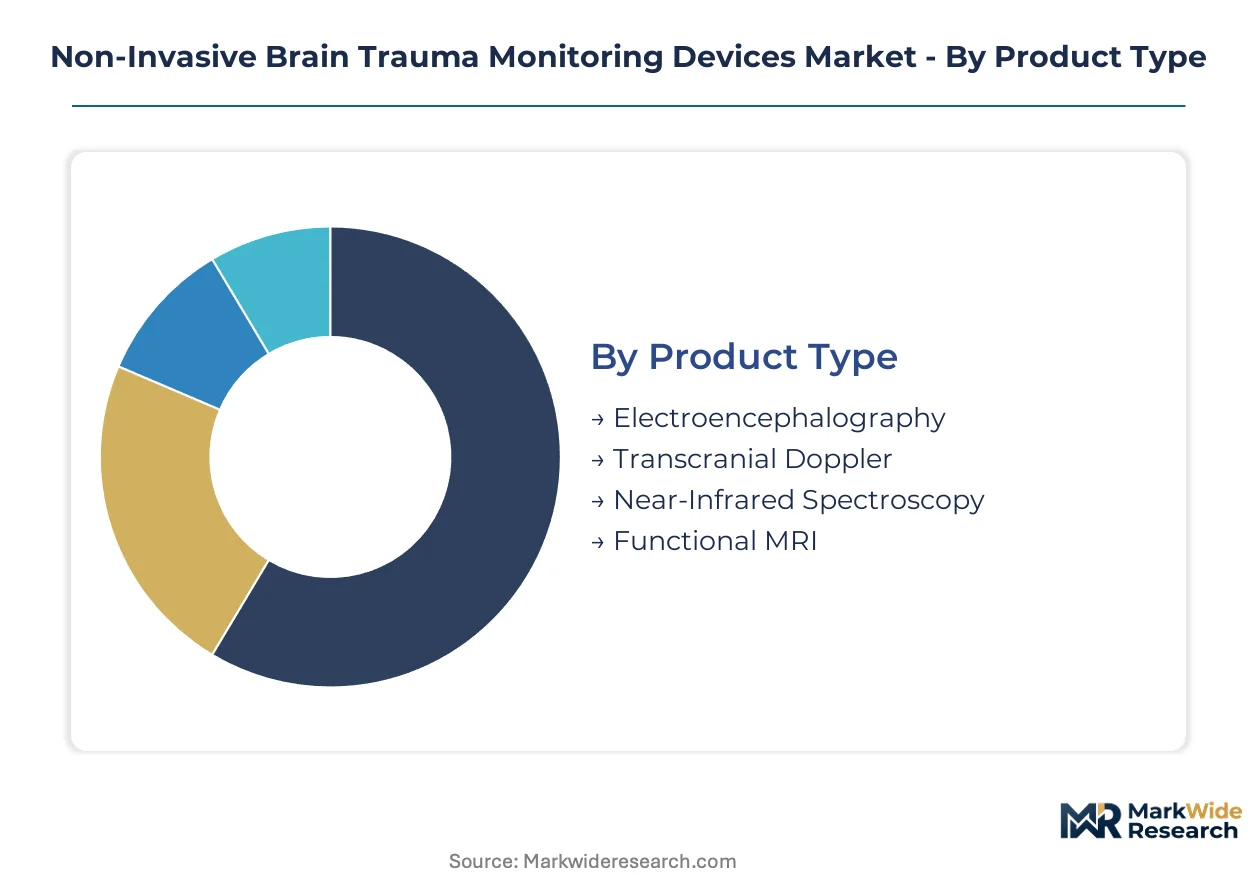
Segmentation in non-invasive brain trauma monitoring reveals how procurement committees allocate capital across acute-care hardware, ambulatory platforms, and data infrastructure. Purchase decisions hinge on clinical workflow integration, reimbursement pathways, and the balance between upfront equipment costs and recurring software commitments.
Product Type:
Hospital capital committees weigh installed base maintenance against modality-specific reimbursement rates when selecting monitoring platforms for trauma bay deployment.
- Electroencephalography:Multi-channel electrical signal acquisition systems detect seizure activity and depth-of-anesthesia states through scalp electrode arrays. Level I trauma centers in the United States maintain extensive EEG installations for continuous cortical monitoring, though capital replacement cycles are lengthening as hospitals defer non-essential upgrades amid budget constraints.
- Near-Infrared Spectroscopy:Optical sensors operating at 650-1000 nanometer wavelengths measure cerebral tissue oxygenation without ionizing radiation. Emergency departments across Germany and Japan are adopting portable NIRS units for point-of-care triage, driven by trauma center certification requirements mandating rapid neurological assessment capabilities.
- Transcranial Doppler:Ultrasound-based cerebral blood flow velocity measurement for vasospasm detection and emboli monitoring.
- Functional MRI:Magnetic resonance-based hemodynamic response imaging for research protocols and pre-surgical mapping.
Volume sits with Electroencephalography; growth tilts toward Near-Infrared Spectroscopy.
Technology:
Form factor economics determine whether procurement authority rests with capital equipment committees or information technology governance structures.
- Portable Monitors:Battery-powered units with wireless data transmission enable intra-hospital transport and pre-hospital deployment. German emergency medical services are expanding NIRS-equipped ambulance fleets to shorten time-to-treatment intervals for severe traumatic brain injury.
- Cloud-Based Solutions:Software-as-medical-device platforms aggregate multi-site monitoring data for centralized interpretation and predictive analytics. Japan's PMDA software-specific trial requirements create regulatory moats for algorithm developers targeting trauma classification automation.
- Wearable Devices:Ambulatory sensor patches for post-discharge neurological surveillance during rehabilitation phases.
- Bedside Systems:Hardwired intensive care installations with proprietary interface modules for electronic health record integration.
Revenue concentrates in Bedside Systems; margin expansion favors Cloud-Based Solutions.
End User:
Reimbursement parity and clinical evidence requirements vary sharply across institutional settings, filtering addressable market boundaries.
- Hospitals:Tertiary trauma centers with Level I certification drive demand for multimodal monitoring suites. United States hospitals command the largest installed base, though procurement cycles are fragmenting as value-analysis teams unbundle hardware from software and service contracts.
- Home Care:Post-acute monitoring for traumatic brain injury patients transitioning from inpatient rehabilitation. Japanese long-term care insurance structures and German ambulatory care reimbursement codes are creating payment pathways for remote neurological surveillance.
- Rehabilitation Centers:Subacute facilities focused on functional recovery and cognitive rehabilitation protocols.
- Research Institutions:Academic medical centers conducting outcome studies and device validation trials.
Installed base dominance rests with Hospitals; penetration rates are climbing fastest in Home Care.
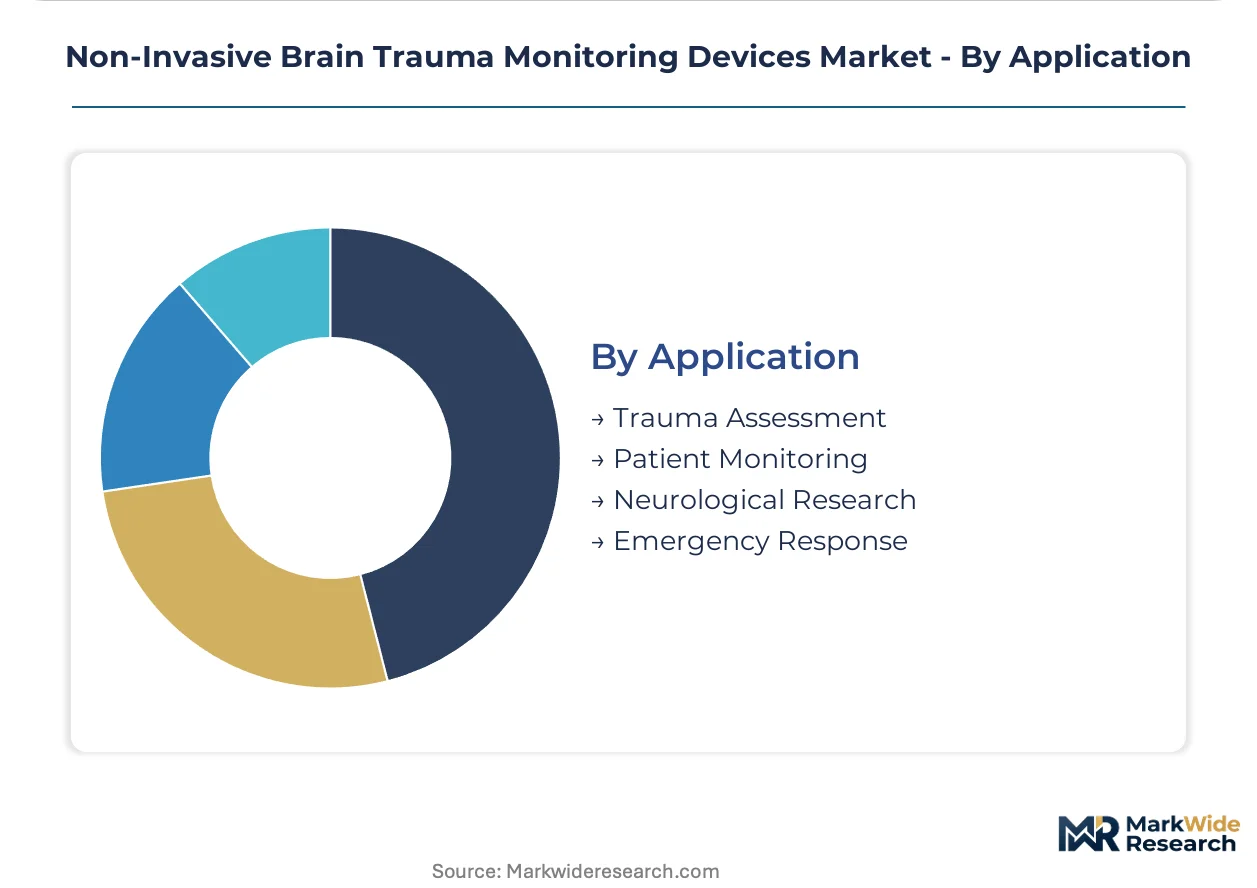
Application:
Clinical use case specificity determines sensor modality selection and regulatory predicate device pathways.
- Trauma Assessment:Point-of-care severity stratification and intracranial pressure surrogate measurement. United States emergency departments are expanding portable neuromonitoring deployment to meet trauma center certification surveillance mandates.
- Emergency Response:Pre-hospital neurological monitoring during ambulance transport and aeromedical evacuation. German and Japanese emergency medical systems are piloting wearable NIRS for field triage, though evidence gaps limit reimbursement parity with invasive alternatives.
- Patient Monitoring:Continuous surveillance for neurological deterioration in intensive care settings.
- Neurological Research:Cohort studies and biomarker validation for traumatic brain injury outcomes.
Procurement volume clusters in Patient Monitoring; regulatory innovation is advancing most quickly in Emergency Response.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates among German precision sensor manufacturers and Japanese optical equipment specialists, while consumption tilts toward United States trauma centers and German emergency medical networks. The geographic split reflects divergent regulatory timelines and reimbursement structures.
United States
Level I trauma centers in Houston, Baltimore, and Los Angeles drive procurement of portable neuromonitoring suites for emergency department certification compliance. The FDA breakthrough device designation pathway accelerates market entry for novel optical sensing modalities. Boston's medical technology corridor anchors R&D activity for wearable brain monitoring architectures.
Germany
Emergency medical services in Bavaria and North Rhine-Westphalia are deploying near-infrared spectroscopy-equipped ambulance fleets for pre-hospital triage. The EU MDR notified body recertification timeline filters smaller competitors from Class IIb neuromonitoring procurement. Baden-Württemberg's precision optics cluster supplies wavelength-specific sensor arrays to trauma device manufacturers.
Japan
Tokyo and Osaka metropolitan trauma centers mandate continuous intracranial pressure surveillance for severe traumatic brain injury protocols. The PMDA enforces distinct clinical trial requirements for software-as-medical-device algorithms, creating regulatory moats for trauma classification tools. Kansai's medical device manufacturing belt produces miniaturized optical sensors for point-of-care deployment.
United Kingdom
NHS England's trauma network reconfiguration is expanding neurocritical care capacity in Manchester, Birmingham, and London. The MHRA operates recognition routes for FDA-cleared devices, shortening time-to-market for United States-validated platforms. Cambridge's neuroscience research cluster validates non-invasive monitoring biomarkers for clinical adoption.
China
Class III medical device registration requirements under the NMPA are hardening clinical evidence standards for imported neuromonitoring systems. Shanghai and Beijing's tertiary hospitals pilot multimodal trauma assessment protocols in emergency departments. The Yangtze River Delta medical device manufacturing base is developing domestic alternatives to optical sensing components.
Non-Invasive Brain Trauma Monitoring Devices Market Key Industry Players
The competitive structure tilts toward diversified medical technology conglomerates with captive neurosurgical portfolios. Consolidation pressure intensifies as regulatory capital requirements filter specialized entrants without dedicated quality management infrastructure. Three archetypes dominate: integrated hospital solution providers, precision sensor specialists, and software-centric analytics platforms. Strategic moves concentrate on M&A for regulatory predicate device acquisition and strategic partnerships for electronic health record integration.
Within the integrated solution provider tier, Medtronic and Koninklijke Philips N.V. occupy positions that exemplify bedside system dominance through neurosurgical portfolio depth and informatics platform integration respectively. Siemens Healthineers anchors the multimodal imaging compatibility segment. These three entities represent how regulatory scale and installed base maintenance capabilities concentrate procurement authority among established manufacturers with captive notified body relationships and proprietary interface development resources.
| Leading Market Players |
|---|
| Medtronic |
| Koninklijke Philips N.V. |
| GE Healthcare Technologies |
| Nihon Kohden Corporation |
| Natus Medical Incorporated |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| Advanced Brain Monitoring Inc. |
| Cadwell Industries Inc. |
| Others |
Cost & Logistics Intelligence
EU MDR post-market surveillance obligations gate qualified supply access and premium-tier pricing power, compelling manufacturers to absorb clinical evidence costs or forfeit high-margin procurement channels in German and Japanese trauma centers. This regulatory filter concentrates margin pools among incumbents with captive notified body relationships while squeezing mid-tier competitors into price-sensitive standard-equipment tiers.
Pricing Analysis
Value-based pricing anchored to trauma center certification compliance and patient throughput metrics dominates procurement negotiations in United States Level I centers. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA breakthrough designation status, EU MDR Class IIb certification tier, and bundled software licensing depth. Cost compression in standard-tier bedside systems is intensifying because hospital value-analysis teams unbundle hardware from service contracts. Emergency medical services in Germany exhibit highest price sensitivity due to municipal budget constraints, while Japanese metropolitan trauma centers show lowest sensitivity given long-term care insurance reimbursement structures.
Supply Chain Analysis
Refurbishment and remanufacturing flows for optical sensor arrays and electromagnetic sensing modules extend equipment lifecycle value in North American hospital networks. Precision manufacturing concentrates in Germany, Japan, and the United States, with Baden-Württemberg supplying wavelength-specific 650-1000 nanometer sensor arrays and Kansai producing miniaturized optical components. Component sourcing draws from Taiwan for semiconductor substrates, Switzerland for precision optics, and domestic Japanese suppliers for electromagnetic shielding materials. Single-source vulnerability in FDA-designated breakthrough device predicate chains poses structural risk. Distribution runs through specialized medical device distributors with neurosurgical portfolio expertise and direct hospital contracting teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU MDR notified body recertification timelines filter capital-constrained competitors, concentrating procurement authority among established manufacturers with dedicated quality management infrastructure.
For Market Incumbents: Anticipate displacement pressure from near-infrared spectroscopy miniaturization advances by deepening software-as-medical-device capabilities and securing cloud-based recurring revenue streams. Defensive consolidation moves should prioritize acquisition of algorithm developers with Japan PMDA software-specific trial experience and expansion of proprietary electronic health record interface libraries to lock in bedside system placements. For New Entrants and Emerging Players: FDA breakthrough device designation pathway in the United States opens a window for optical sensing modality innovators to bypass traditional 510(k) queue delays and command premium positioning. White-space targets concentrate in post-discharge ambulatory monitoring architectures for traumatic brain injury rehabilitation and pre-hospital emergency response deployment in German ambulance fleets. Go-to-market execution should anchor on trauma center certification compliance narratives rather than clinical efficacy claims alone. For Investors and Strategic Acquirers: Notified body exit announcements from Class IIb neuromonitoring categories is the leading indicator that regulatory capital requirements have crossed threshold for sustainable independent operation, signaling acquisition window opening for distressed assets with predicate device clearances. Long-term viability over the coming decade rests on software licensing margin expansion and ambulatory monitoring protocol adoption. Target acquisition archetypes include precision sensor specialists with electromagnetic sensing modality integration expertise and cloud analytics platforms with trauma classification algorithm validation. Monitor Japan PMDA software-as-medical-device approval velocity as inflection signal for algorithm-centric valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Notified Body Partnership | Secures CE marking pathway for Class IIb neuromonitoring equipment in German trauma centers. |
| Cloud-Based Software Licensing | Concentrates margin pools through subscription structures atop North American hardware placements. |
| Wearable Architecture Development | Captures post-discharge rehabilitation monitoring demand in Japanese long-term care insurance channels. |
| Electronic Health Record Integration | Locks in bedside system placements via proprietary interface modules for major hospital information vendors. |
| Japan PMDA Software Pathway | Creates regulatory moats for AI-enabled trauma classification tools in Tokyo and Osaka metropolitan markets. |
Research Approach
Multi-period observation of trauma center certification adoption curves, portable neuromonitoring deployment rates, and regulatory approval timelines anchored the trend analysis, supplemented by interviews with biomedical engineering directors at Level I trauma centers, hospital purchasing committee members, GPO contracts managers, regulatory affairs leads at device manufacturers, and emergency medical services procurement officers. Secondary validation drew from FDA 510(k) and breakthrough device designation filings, EU MDR notified body designation records, Japan PMDA software-as-medical-device guidance documents, hospital procurement databases, and CMS Medicare reimbursement coding updates. Bottom-up installed base estimates triangulated against top-down market sizing across product type, technology, and end-user segmentation dimensions.
Segment-weighting approaches distributed value and volume projections across electroencephalography, near-infrared spectroscopy, transcranial Doppler, and functional MRI product categories, further disaggregated by portable monitor, cloud-based solution, wearable device, and bedside system technology tiers. End-user segmentation modeled hospitals, home care, rehabilitation centers, and research institutions with application-specific weighting for trauma assessment, emergency response, patient monitoring, and neurological research use cases. CAGRs were derived from logistic adoption curve fitting and replacement cycle analysis. Industry-specific forecast inputs incorporated sensor miniaturization cost curves and wireless power delivery technology readiness levels.
The model assumes a particular technology adoption path; alternative pathways for wearable ambulatory monitoring or cloud-native algorithm deployment would alter the outlook if reimbursement parity with invasive alternatives accelerates or stalls. Forecasts reflect underlying assumptions regarding regulatory timeline stability and trauma center certification mandate continuity. Practitioners should monitor FDA breakthrough device designation grant velocity, EU MDR notified body capacity expansion announcements, and Japan PMDA software-specific trial enrollment rates for early signals of competitive access condition shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Blood Banking Devices Market
Medical Devices
High Tibial Osteotomy (HTO) Plates Market
Medical Devices
Canada Insulin Delivery Devices Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
External Pacemakers Market
Medical Devices
Water Flosser Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
Spain Contraceptive Devices Market
Medical Devices
Global Image Guided Surgery Devices Market
Medical Devices
Eye Sphere Implants Market
Medical Devices
Next Generation Infusion Pump Market
Medical Devices
GCC Organ Preservation Market
Medical Devices
North America Refractive Surgery Devices Market
Medical Devices
Ligament Augmentation Market
Medical Devices
Bone Fixation Plates Market
Medical Devices
Intervertebral Implants Market