
 Brain Monitoring Systems Market | 2026-2036
Brain Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Brain Monitoring Systems Market Analysis
Neurology clinics is recalibrating demand patterns as outpatient epilepsy monitoring shifts toward ambulatory wearable platforms. Medtronic leverages its deep neurostimulation heritage to extend into adjacent brain sensing modalities. Natus Medical specializes in electroencephalography hardware and software workflows that dominate pediatric neurology departments. Koninklijke Philips N.V. anchors hospital system procurement through bundled diagnostic imaging and monitoring contracts.
Brain monitoring systems comprise electrophysiological and hemodynamic measurement instruments that capture neural activity through electrodes, magnetic fields, or metabolic tracers, with typical EEG sampling rates exceeding 256 Hz for clinical-grade seizure detection. These systems serve diagnostic, intraoperative, and research functions across acute care and ambulatory settings. EEG devices occupy the largest installed base among product categories, reflecting decades of standardized clinical protocols and lower capital barriers relative to functional MRI or PET platforms. Non-invasive monitoring technology leads volume adoption, though invasive intracranial electrodes command premium pricing in epilepsy surgical planning. Sleep studies and epilepsy monitoring together represent the most mature application segments, while cognitive assessment gains traction from aging-population dementia screening programs.
FDA breakthrough device designations and EU MDR conformity requirements jointly shape product development timelines and market access pathways for manufacturers. HIPAA privacy frameworks and GDPR health data provisions constrain cloud-based neural data architectures, pushing vendors toward edge-computing device designs. Stakeholders must weigh regulatory jurisdiction complexity against the clinical pull for real-time remote monitoring capabilities as reimbursement models evolve toward value-based neurological care.
Market Dynamics
The FDA's breakthrough device designation pathway is compressing commercialization timelines for novel neurotechnologies, while neurology clinics simultaneously pivot toward ambulatory wearable platforms that displace traditional inpatient monitoring infrastructure.
Growth Catalysts
- Breakthrough Device Designation:The FDA pathway accelerates review cycles for seizure detection algorithms and intracranial sensing implants, reducing time-to-market for epilepsy surgical planning tools.
- Ambulatory Monitoring Protocols:Neurology clinics in the United States are standardizing take-home EEG workflows that extend monitoring duration beyond 72 hours without bed occupancy costs.
- Veterans Health Administration Procurement:Federal integrated care networks are consolidating traumatic brain injury and post-traumatic epilepsy monitoring into single-vendor platform contracts.
Market Restraints
- EEG Electrode Supply Concentration:Silver-silver chloride electrode manufacturing concentrates in East Asian contract manufacturers, exposing procurement to raw material price volatility and logistics disruptions.
- Intracranial Hardware Cost Structure:Invasive depth electrodes and subdural grids require precision-machined biocompatible alloys that sustain premium pricing tiers inaccessible to community hospital budgets.
- GDPR Neural Data Friction:EU health data provisions impose localization requirements on cloud-architected neural signal databases, constraining vendors from centralized processing architectures.
Strategic Opportunities
- Home-Based Sleep Diagnostics:Underpenetrated residential sleep apnea and nocturnal seizure monitoring in Germany and France offers white-space expansion beyond clinic-centric EEG deployment.
- Edge Computing Architectures:On-device signal processing for HIPAA-compliant epilepsy alerting bypasses cloud transmission latency and privacy constraints in United States skilled nursing facilities.
- EU MDR Conformity Acceleration:Harmonized medical device regulations enable single-certification market access across 27 member states for wearable brain sensing platforms.
Industry Challenges
- Clinical Neurophysiologist Talent Scarcity:Fellowship-trained epileptologists capable of interpreting long-term ambulatory recordings remain concentrated at academic medical centers, constraining community clinic expansion.
- Legacy EMR Integration Complexity:Proprietary EEG data formats from Natus and Medtronic systems require custom HL7 interface development that prolongs hospital IT procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brain Monitoring Systems Market |
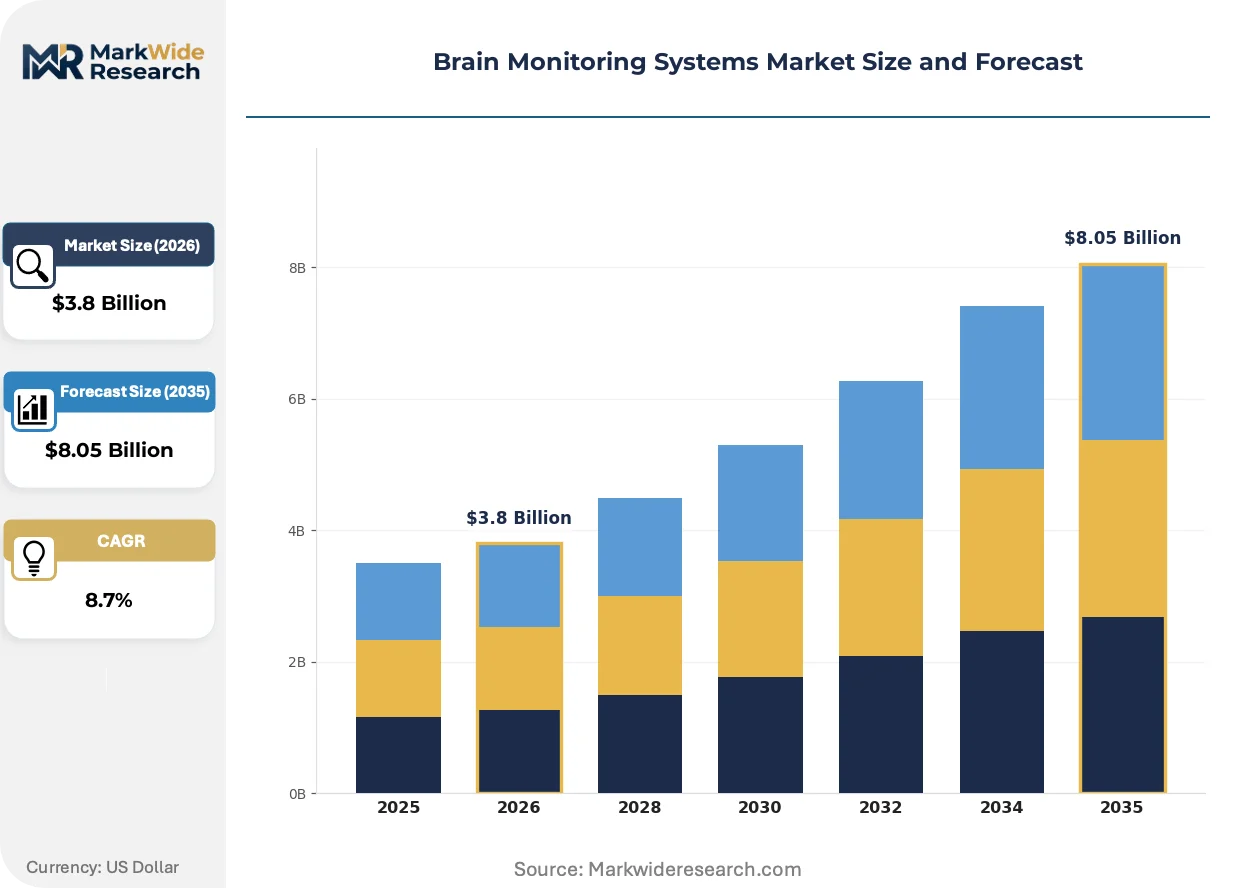
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EEG Devices, fMRI Systems, PET Scanners, Neurostimulators End User: Neurology Clinics, Research Institutes, Hospitals, Rehabilitation Centers Technology: Wearable Devices, Non-invasive Monitoring, Invasive Monitoring, Signal Processing Application: Sleep Studies, Epilepsy Monitoring, Cognitive Assessment, Pain Management |
| Companies Covered | Medtronic, Natus Medical Incorporated, Nihon Kohden Corporation, Koninklijke Philips N.V., GE HealthCare Technologies Inc., Edwards Lifesciences Corporation, Advanced Brain Monitoring Inc., Compumedics Limited, Masimo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brain Monitoring Systems Market Emerging Trajectories
Wearable electrophysiology is displacing capital-intensive imaging modalities while regulatory frameworks and procurement models co-evolve to accommodate decentralized neural monitoring.
Dry-electrode EEG headsets with active impedance compensation are consolidating ambulatory epilepsy monitoring around patient-administered recording protocols. Community neurology practices in Texas and Florida are deploying these devices for 7-14 day seizure diaries that previously required video-EEG telemetry admission. This consolidation is compressing revenue per patient for inpatient monitoring suites while expanding addressable screening volumes.
EU MDR conformity requirements are reshaping technical documentation obligations for intracranial electrode manufacturers. Class III device re-certification demands extended clinical follow-up data that delays product line extensions by 18-24 months. Epilepsy surgical centers in the Netherlands and Sweden are responding by consolidating procurement around established vendors with legacy MDD certificates valid through 2027-2028 transition deadlines.
Hospital systems are unbundling after-sales service contracts from hardware acquisition, particularly for EEG amplifier maintenance and software upgrade subscriptions. Pediatric neurology departments in California and New York now negotiate separate technical support agreements with third-party biomedical engineering firms. This disintermediation is most visible in academic medical centers with captive clinical engineering departments capable of in-house amplifier calibration and electrode inventory management.
Brain Monitoring Systems Market Segmentation
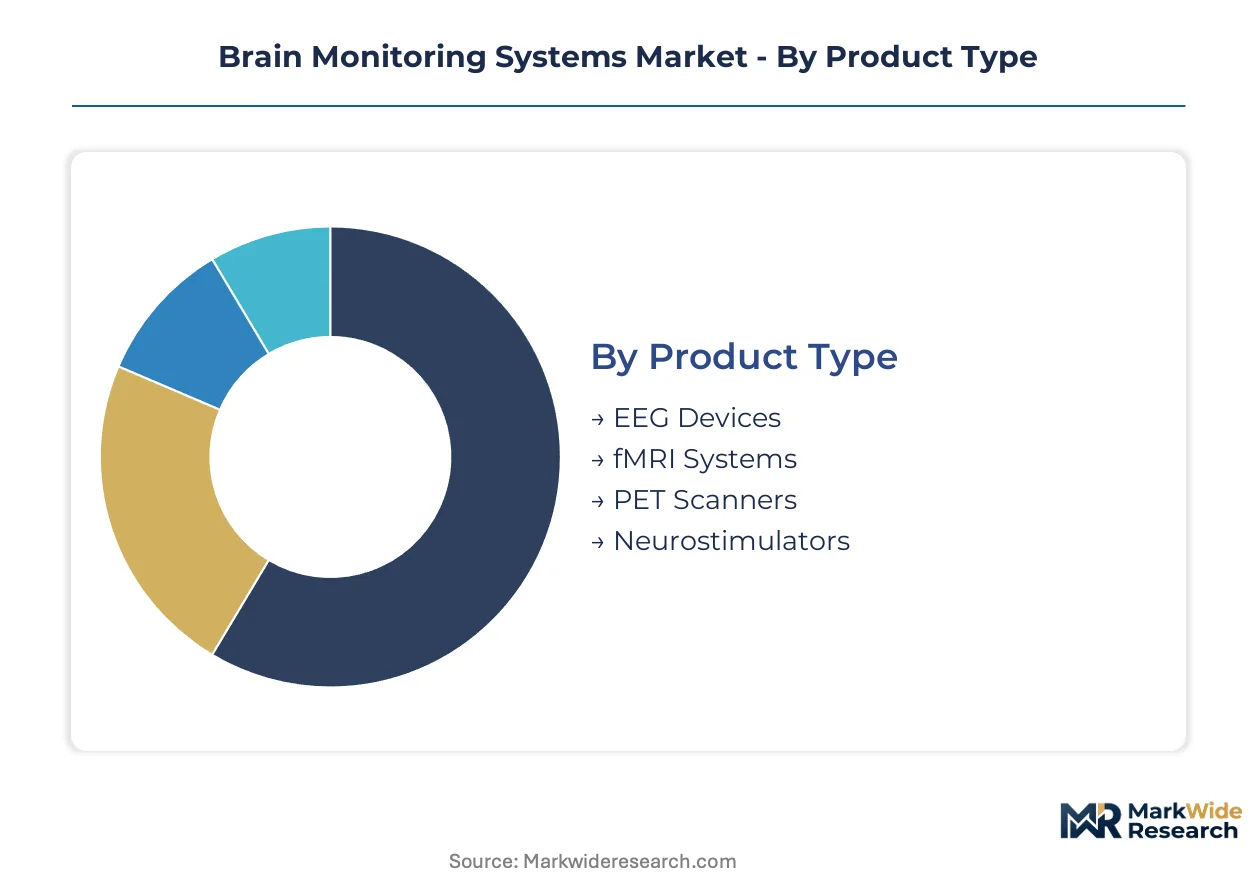
Brain monitoring systems fragment across hardware modalities, care settings, and signal acquisition methods. Each segmentation axis reveals distinct procurement patterns, reimbursement pathways, and integration requirements that shape vendor positioning.
Product Type:
Standalone diagnostic platforms dominate capital budgets, while embedded sensing modules penetrate surgical workflows and implantable therapies.
- EEG Devices:Electrophysiological amplifiers with 256+ Hz sampling rates capture cortical electrical activity through scalp electrodes. Demand clusters in United States pediatric neurology departments and Veterans Health Administration epilepsy surgical planning programs, driven by ambulatory monitoring protocol expansion.
- fMRI Systems:Magnetic resonance platforms measuring blood-oxygen-level-dependent contrast map hemodynamic neural correlates. Academic medical centers in Germany and the Netherlands concentrate procurement for pre-surgical eloquent cortex localization, constrained by helium supply chain volatility and siting infrastructure costs.
- PET Scanners:Positron emission tomography systems utilizing metabolic tracers for neurodegenerative disease staging.
- Neurostimulators:Implantable pulse generators with integrated sensing capabilities for responsive epilepsy therapy.
Volume placements concentrate in EEG Devices; the faster expansion belongs to Neurostimulators.
End User:
Procurement authority varies sharply across settings, with hospital systems leveraging scale while research institutes prioritize experimental flexibility.
- Neurology Clinics:Outpatient facilities standardizing take-home EEG workflows for extended seizure monitoring. Community practices in Texas and Florida drive dry-electrode headset adoption, displacing inpatient telemetry admissions.
- Hospitals:Integrated delivery networks consolidating multi-modal neurodiagnostic platforms under single-vendor contracts. Academic medical centers in California and New York unbundle service agreements from hardware acquisition, engaging third-party biomedical engineering firms.
- Research Institutes:Neuroscience laboratories requiring high-density intracranial recordings and closed-loop brain-computer interface development.
- Rehabilitation Centers:Post-acute facilities integrating cognitive assessment tools for traumatic brain injury recovery monitoring.
Procurement volume tilts toward Hospitals; Research Institutes post the steepest expansion trajectory.
Technology:
Signal acquisition methods stratify by invasiveness, with regulatory burden and reimbursement rates tracking clinical risk profiles.
- Non-invasive Monitoring:Scalp EEG and functional neuroimaging platforms avoiding cranial breach. United States skilled nursing facilities and German residential sleep diagnostics drive demand, constrained by signal artifact susceptibility and spatial resolution limitations.
- Wearable Devices:Ambulatory dry-electrode headsets with active impedance compensation and edge-computing architectures. FDA breakthrough device designations accelerate commercialization for seizure detection algorithms, while GDPR neural data friction constrains cloud-dependent architectures in EU markets.
- Invasive Monitoring:Intracranial depth electrodes and subdural grids for epilepsy surgical planning.
- Signal Processing:On-device algorithmic pipelines for real-time artifact rejection and feature extraction.
Non-invasive Monitoring holds the largest installed base; Wearable Devices are climbing the fastest.
Application:
Clinical maturity varies across indications, with established protocols in epilepsy and sleep contrasting experimental traction in cognitive screening.
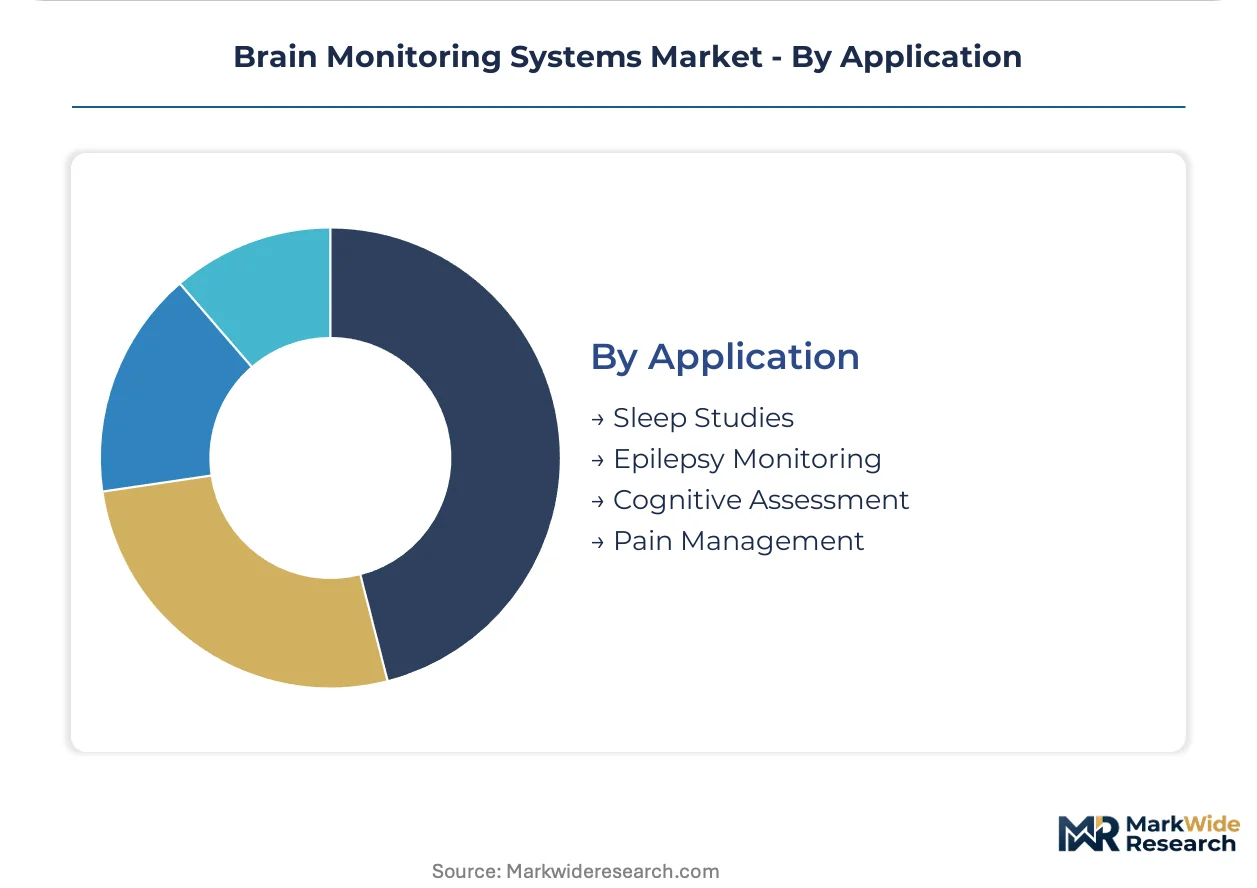
- Epilepsy Monitoring:Long-term video-EEG telemetry and ambulatory seizure diary protocols. Veterans Health Administration facilities and United States academic medical centers consolidate procurement, shifting toward 7-14 day take-home recordings that reduce bed occupancy costs.
- Sleep Studies:Polysomnography and nocturnal seizure detection for sleep apnea and parasomnia diagnosis. Underpenetrated residential markets in Germany and France offer white-space expansion beyond clinic-centric deployment.
- Cognitive Assessment:Dementia screening and traumatic brain injury evaluation tools.
- Pain Management:Neurostimulation targeting and chronic pain pathway mapping applications.
Epilepsy Monitoring commands the deepest clinical penetration; Cognitive Assessment is gaining share fastest from aging-population screening programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Research Triangle Park in North Carolina and similar biomedical innovation zones concentrate brain monitoring R&D through state-level tax incentives and federal grant proximity, drawing device manufacturers and clinical trial networks into clustered development corridors.
United States
The Veterans Health Administration operates the largest integrated procurement network for traumatic brain injury and epilepsy monitoring platforms, consolidating multi-hospital contracts under single-vendor agreements. FDA breakthrough device designations compress review timelines for seizure detection algorithms, accelerating commercialization for ambulatory EEG developers. Academic medical centers in California and New York unbundle service contracts from hardware acquisition, engaging third-party biomedical engineering firms for amplifier maintenance.
Germany
University hospitals in Munich and Heidelberg anchor demand for functional MRI systems used in pre-surgical eloquent cortex localization, constrained by helium supply chain volatility and siting infrastructure costs. EU MDR conformity requirements impose extended clinical follow-up obligations on intracranial electrode manufacturers, delaying product line extensions by 18-24 months. The KBA medical device regulatory framework intersects with GDPR neural data provisions, pushing vendors toward edge-computing architectures that avoid cloud transmission.
Japan
PMDA accelerated approval pathways for novel neurotechnologies support domestic manufacturers expanding into responsive neurostimulation with integrated sensing capabilities. METI funding programs for aging-population healthcare infrastructure drive dementia screening tool adoption in prefectural hospital networks. Osaka-based industrial clusters concentrate precision machining capabilities for biocompatible alloy components used in invasive depth electrodes.
Netherlands
Epilepsy surgical centers in Amsterdam and Rotterdam consolidate procurement around established vendors with legacy MDD certificates valid through 2027-2028 EU MDR transition deadlines. EMA regulatory guidance on brain-computer interface medical devices shapes technical documentation requirements for research institutes pursuing closed-loop therapeutic platforms. The Eindhoven high-tech ecosystem supplies miniaturized electronics for wearable dry-electrode headsets with active impedance compensation.
Australia
TGA conformity assessment procedures for active implantable medical devices create parallel regulatory pathways for neurostimulator manufacturers seeking market access across Asia-Pacific. Sleep diagnostic networks in Melbourne and Sydney drive polysomnography platform demand, with residential sleep apnea monitoring gaining traction beyond clinic-centric deployment. Commonwealth Scientific and Industrial Research Organisation grants support local development of on-device signal processing algorithms for real-time artifact rejection.
Brain Monitoring Systems Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated neurotechnology conglomerates commanding hospital system procurement through bundled diagnostic contracts while boutique electrophysiology firms capture ambulatory monitoring niches. The vendor base stratifies into three tiers: multinational platform providers with neurostimulation heritage, mid-scale EEG hardware specialists dominating pediatric neurology workflows, and emerging wearable sensor developers leveraging FDA breakthrough pathways. Competitive moves concentrate on portfolio diversification into adjacent sensing modalities and strategic partnerships to bypass legacy EMR integration complexity.
Within the multinational platform tier, Medtronic leverages deep neurostimulation heritage to extend into adjacent brain sensing modalities, while Koninklijke Philips N.V. anchors hospital system procurement through bundled diagnostic imaging and monitoring contracts. Natus Medical Incorporated exemplifies the electrophysiology specialist archetype, occupying a position in pediatric neurology department workflows that standardized EEG protocols over decades. These three entities represent distinct strategic postures: neurostimulation-platform expansion, imaging-to-monitoring bundling, and clinical-workflow specialization.
| Leading Market Players |
|---|
| Medtronic |
| Natus Medical Incorporated |
| Nihon Kohden Corporation |
| Koninklijke Philips N.V. |
| GE HealthCare Technologies Inc. |
| Edwards Lifesciences Corporation |
| Advanced Brain Monitoring Inc. |
| Compumedics Limited |
| Masimo |
| Others |
Supply Flow & Price Mechanics
Captive manufacturing of silver-silver chloride electrodes in East Asian contract facilities anchors both supply security and premium pricing power for EEG hardware vendors. This integration choice insulates tier-one manufacturers from raw material volatility while locking community hospitals into long-term electrode supply agreements that sustain recurring revenue streams.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with hospital systems paying elevated rates for expedited intracranial electrode delivery during surgical scheduling windows. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated seizure detection platforms from legacy amplifier systems and refurbished hardware. Cost compression in the standard tier is intensifying because community neurology clinics negotiate bundled service unbundling. Pediatric neurology departments show highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize certification tier over unit cost.
Supply Chain Analysis
Silver-silver chloride electrode supply rests on Japanese specialty chemical producers and Taiwanese precision coating facilities, with secondary machining capacity concentrated in South Korea. Biocompatible alloy feedstocks for invasive depth electrodes draw from Osaka-based industrial clusters, while helium for fMRI magnet cooling sources from Qatar and Algeria extraction sites. Single-source vulnerability in silver chloride precursor chemicals exposes manufacturers to commodity price volatility. Distribution runs through hospital GPO contracts and direct academic medical center procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The brain monitoring systems market reads as a cost-of-compliance story where EU MDR conformity requirements create a barrier-to-entry moat for manufacturers with legacy MDD certificates valid through transition deadlines.
For Market Incumbents: Cement platform stickiness through proprietary EEG data format lock-in that prolongs hospital IT procurement cycles for competitive displacement. Fortify electrode supply captive manufacturing in East Asian facilities to neutralize raw material price volatility threats. Deepen backward integration into biocompatible alloy machining capabilities for invasive monitoring hardware. For New Entrants and Emerging Players: Capture underpenetrated residential sleep diagnostics in Germany and France where clinic-centric EEG deployment leaves white-space for ambulatory dry-electrode headsets. Exploit FDA breakthrough device designation pathways to compress commercialization timelines against established MDR-constrained competitors. Lead with edge-computing architectures that bypass GDPR neural data friction in EU markets. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by neurostimulation conglomerates seeking adjacent sensing modality expansion. Long-term viability favors vendors with demonstrated EU MDR technical documentation capabilities and Veterans Health Administration contract eligibility. Watch FDA breakthrough designation grant velocity as inflection indicator for ambulatory EEG platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pursuit | Accelerates review cycles for seizure detection algorithms, compressing time-to-market against MDR-constrained rivals. |
| EU MDR Conformity Acceleration | Enables single-certification market access across member states for wearable brain sensing platforms. |
| Hospital System Partnership | Secures multi-hospital procurement consolidation under single-vendor integrated platform contracts. |
| Edge Computing Architecture Development | Bypasses HIPAA and GDPR cloud transmission constraints in United States skilled nursing facilities. |
| Software Companion Development | Extends hardware platform lifecycle through algorithmic seizure detection upgrades and EMR integration modules. |
Methodological Framework
FDA 510(k) filings, EU MDR technical documentation databases, and Veterans Health Administration procurement records formed the secondary backbone of this analysis. Primary interviews with epileptologists, hospital biomedical engineers, GPO contracts managers, and neurostimulation platform executives combined with secondary validation. Bottom-up triangulation across product category shipment estimates and top-down reconciliation against healthcare capital expenditure surveys anchored market sizing.
Historical trendline analysis of EEG amplifier placements, neurostimulator implants, and functional MRI system installations established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type, end-user setting, technology invasiveness, and regional regulatory cluster dimensions. CAGRs derived from weighted average of equipment replacement cycles, protocol adoption curves, and reimbursement pathway expansion timelines. Forecast inputs included ambulatory monitoring protocol penetration rates and EU MDR transition deadline impacts.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA breakthrough designation grant velocity and helium supply chain disruptions for fMRI platforms. Forecasts reflect documented assumptions regarding reimbursement model evolution toward value-based neurological care. A small set of named triggers—including EU MDR certificate expiration schedules and Veterans Health Administration contract recompete outcomes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Multi-Channel Remote ECG Monitors Market
Patient Monitoring
Non-Invasive Respiratory Monitoring Market
Patient Monitoring
Europe Patient Monitoring Devices Market
Patient Monitoring
South Africa Patient Monitoring Market
Patient Monitoring
Ambulatory Heart Monitor Market
Patient Monitoring
Heart Beat Monitor and Sensor Market
Patient Monitoring
North America Self-Monitoring Blood Glucose Market
Patient Monitoring
Wearable Ambulatory Monitoring Device Market
Patient Monitoring
North America Hemodynamic Monitoring Market
Patient Monitoring
Patient Monitoring Pods Market
Patient Monitoring
Wireless Healthcare Market
Patient Monitoring
Epro, E-Patient Diaries and Ecoa Market
Patient Monitoring
Home Care Monitoring and Diagnostics Market
Patient Monitoring
Asia-Pacific Remote Patient Monitoring Systems Market
Patient Monitoring
Patient Monitoring and Ultrasound Devices Display Market
Patient Monitoring
Hemoglobin Monitor Market