
 Next Generation Infusion Pump Market | 2026-2036
Next Generation Infusion Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Infusion Pump Market Foresight
Silicone elastomer is expanding its presence in pump tubing and valve assemblies, displacing older PVC formulations that leach plasticizers during extended infusions. Becton, Dickinson and Company leverages backward integration into polymer compounding to secure supply continuity for its Alaris platform. Baxter International Inc. anchors its position through hospital-wide service contracts that bundle pump placement with preventive maintenance. Fresenius Kabi AG competes on manufacturing scale, operating dedicated infusion device plants in Germany and the United States.
Next generation infusion pumps are electromechanical devices programmed to deliver fluids, medications, or nutrients into a patient's circulatory system at controlled rates, typically achieving flow precision within plus or minus five percent through peristaltic or syringe-driven mechanisms. These systems incorporate drug error reduction software, dose calculation libraries, and wireless connectivity to central monitoring stations, serving acute care environments where medication safety is paramount. Volumetric pumps dominate installed base value due to their versatility across high-volume fluid delivery scenarios, while ambulatory pumps capture the fastest growth trajectory as homecare reimbursement expands. Smart pump technology with integrated barcode verification concentrates margin pools, since hospitals pay premiums for closed-loop safety architectures that reduce adverse drug events.
The FDA enforces premarket notification requirements under 510(k) pathways for infusion pump modifications, while the EU Medical Device Regulation mandates clinical evidence for software-driven dose error reduction systems. These frameworks elevate compliance costs for new entrants but reinforce incumbent positions among manufacturers with established quality management systems. Stakeholders must monitor evolving cybersecurity guidance from health regulators, as wireless pump connectivity introduces attack surfaces that could trigger mandatory patching protocols and reshape product lifecycle obligations.
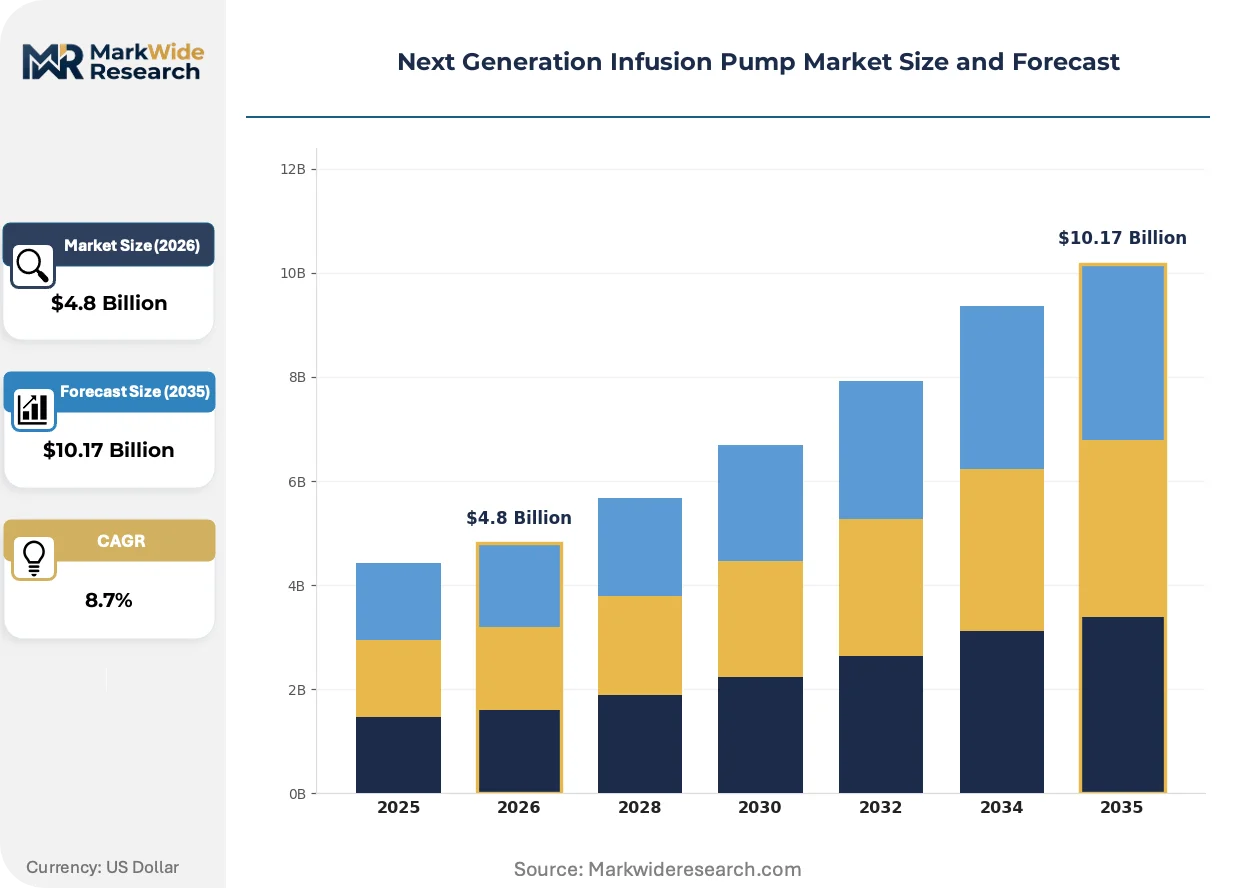
Market Dynamics
Closed-loop drug library compliance mandates are compressing replacement cycles for legacy infusion equipment, forcing acute care facilities to prioritize wireless connectivity and dose error reduction architectures in procurement specifications.
Growth Catalysts
- Closed-loop safety mandates:The FDA's renewed emphasis on drug library compliance is accelerating hospital replacement of non-compliant legacy pumps with integrated barcode verification systems.
- Homecare reimbursement expansion:Ambulatory infusion services are capturing expanded insurance coverage for oncology and pain management therapies delivered outside acute settings.
- Silicone elastomer migration:Extended infusion protocols are displacing PVC tubing formulations that leach plasticizers, driving material specification changes across pump valve assemblies.
Market Restraints
- Specialized polymer supply concentration:Medical-grade silicone compounding capacity clusters among a limited supplier base, creating input vulnerability for tubing manufacturers.
- Premarket notification burden:FDA 510(k) pathways for software-driven dose modifications elevate compliance costs and extend time-to-market for feature iterations.
- Wireless-enabled attack surfaces:Cybersecurity patching protocols for connected pumps introduce operational disruption risks and lifecycle cost uncertainties.
Strategic Opportunities
- Underpenetrated homecare channels:Germany's expanding outpatient infusion reimbursement frameworks create white space for portable pump deployment beyond hospital walls.
- EHR convergence architectures:Bidirectional data exchange between infusion pumps and electronic health record systems is opening premium pricing tiers for interoperability-certified devices.
- Preventive maintenance bundling:Hospital-wide service contracts that combine pump placement with uptime guarantees are displacing transactional equipment sales models.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized firmware development for peristaltic mechanism precision control outpaces available expertise pools.
- Legacy system integration friction:Retrofitting wireless connectivity into installed bases of non-networked pumps requires costly middleware deployments.
- Software validation timelines:EU MDR clinical evidence requirements for dose error reduction algorithms extend certification cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Infusion Pump Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Volumetric Pumps, Syringe Pumps, Peristaltic Pumps, Ambulatory Pumps End User: Hospitals, Homecare Settings, Outpatient Clinics, Surgical Centers Technology: Smart Pumps, Needle-free Technology, Wireless Integration, Error Prevention Systems Application: Pediatrics, Oncology, Pain Management, Anesthesia |
| Companies Covered | Becton, Dickinson and Company, Baxter International Inc., B. Braun Melsungen AG, ICU Medical, Inc., Fresenius Kabi AG, Medtronic plc, Terumo Corporation, Mindray Medical International Limited, Insulet Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Infusion Pump Market Shifts & Advancements
Software-defined dose control architectures are displacing hardware-centric safety mechanisms, enabling remote algorithm updates that shift value capture toward subscription-based service models.
Peristaltic pump mechanics are modularizing around cartridge-based disposable sets that separate fluid path from capital equipment, allowing hospitals to standardize across multiple therapy types while reducing cross-contamination protocols. Acute care facilities in the United States are adopting these configurations fastest, compressing capital expenditure cycles into recurring consumable revenue streams for manufacturers.
EU MDR mandates for clinical evidence on software-driven dose error reduction systems are elevating documentation burdens for algorithm modifications, forcing manufacturers to front-load validation costs before market entry. German notified bodies are processing these submissions with extended review timelines, concentrating compliance expertise among incumbent quality management systems.
Buying committees are consolidating vendor relationships around single-platform standardization, displacing mixed-fleet procurement that previously segmented volumetric, syringe, and ambulatory pump purchases across different suppliers. Integrated electronic health record connectivity has become a disqualifying criterion in United States hospital RFPs, compressing consideration sets to vendors with certified interoperability modules.
Next Generation Infusion Pump Market Segmentation
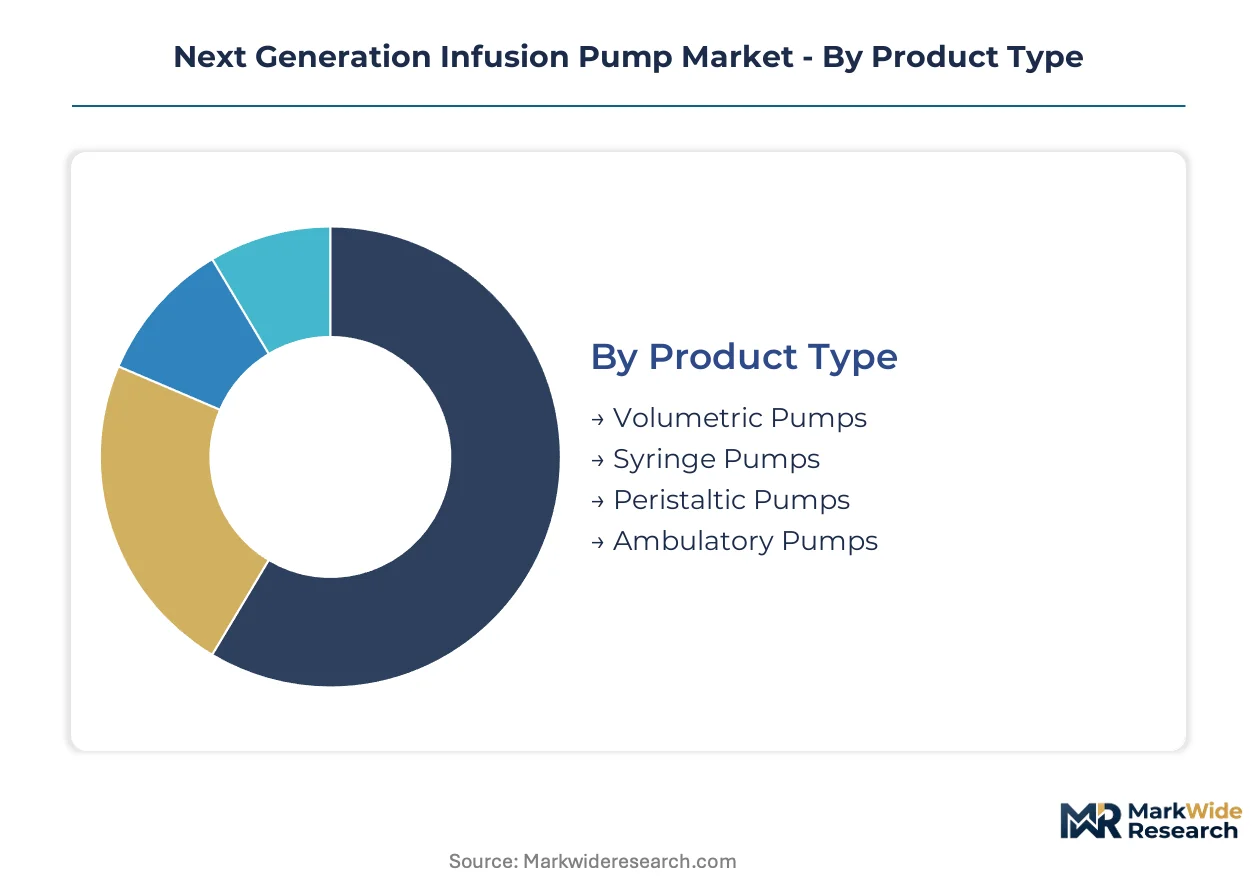
Segmentation in next generation infusion pumps reveals how regulatory pathways and clinical use cases fragment procurement priorities across acute and ambulatory environments. Manufacturers must align product architectures with distinct compliance burdens and reimbursement frameworks governing each category.
Product Type:
FDA 510(k) premarket notification requirements apply uniformly across all pump categories, though volumetric and syringe variants face heightened scrutiny for high-risk infusion protocols, while ambulatory pumps navigate simpler documentation for lower-acuity applications.
- Volumetric Pumps:These systems deliver large fluid volumes through peristaltic or cassette mechanisms, achieving flow precision within plus or minus five percent for high-volume resuscitation and nutrition support. Demand concentrates in United States tertiary hospitals where integrated drug libraries and wireless connectivity have become mandatory procurement criteria under FDA safety mandates.
- Ambulatory Pumps:Portable devices weighing under two pounds enable continuous infusion during patient mobility, powered by rechargeable batteries and disposable cassette reservoirs. Homecare channels in Germany and the United States are expanding fastest as outpatient reimbursement frameworks broaden coverage for oncology and pain management therapies delivered outside acute settings.
- Syringe Pumps:Precision instruments designed for low-volume, high-accuracy medication delivery in neonatal and pediatric intensive care units.
- Peristaltic Pumps:Mechanisms utilizing rotating rollers to compress flexible tubing, separating fluid path from pump hardware through disposable cartridge sets.
Volumetric pumps sit at the top of the volume ranking, with ambulatory pumps climbing the fastest.
End User:
Cost tier stratification separates capital-intensive hospital deployments from consumable-driven homecare models, with surgical centers occupying a mid-tier position balancing equipment sophistication against case volume economics.
- Hospitals:Acute care facilities command the largest installed base, requiring enterprise-scale pump fleets with centralized asset management, bidirectional EHR integration, and 24/7 biomedical engineering support. United States health systems are consolidating vendor relationships around single-platform standardization, displacing mixed-fleet procurement that previously segmented pump purchases across different suppliers.
- Homecare Settings:Patients receiving infusion therapy in residential environments drive demand for portable, intuitive devices with simplified programming interfaces and remote monitoring capabilities. Germany's expanding outpatient reimbursement frameworks create white space for ambulatory pump deployment beyond hospital walls, while United States Medicare Advantage plans increasingly cover home infusion for specialty pharmaceuticals.
- Outpatient Clinics:Limited-service facilities requiring intermittent pump access for chemotherapy and antibiotic administration, prioritizing rental and lease arrangements over capital purchase.
- Surgical Centers:Ambulatory surgery facilities emphasizing rapid turnover and standardized anesthesia protocols, favoring compact syringe pumps with pre-programmed drug libraries.
Hospitals capture the dominant revenue share, though homecare settings are gaining share fastest as reimbursement shifts toward site-neutral payment models.
Technology:
Margin concentration follows certification complexity, with smart pumps and error prevention systems commanding premium pricing tied to FDA-validated dose reduction algorithms and EU MDR clinical evidence requirements.
- Smart Pumps:Integrated systems incorporating drug error reduction software, dose calculation libraries, and barcode medication administration verification. Hospitals pay premiums for closed-loop safety architectures that reduce adverse drug events, with wireless connectivity to central monitoring stations becoming a non-negotiable purchasing criterion in United States RFPs.
- Wireless Integration:Radio-frequency and Wi-Fi-enabled connectivity enabling real-time pump status transmission to central nursing stations and electronic health record systems. Cybersecurity patching protocols for connected pumps introduce operational disruption risks, yet bidirectional data exchange architectures open premium pricing tiers for interoperability-certified devices.
- Needle-free Technology:Connector systems eliminating sharp components from fluid path assemblies, reducing needlestick injury exposure for healthcare workers.
- Error Prevention Systems:Software-driven dose limit checking and clinical decision support modules requiring extensive validation under EU MDR frameworks.
Smart pumps dominate margin pools, with wireless integration expanding most quickly as EHR convergence becomes a disqualifying criterion in procurement evaluations.
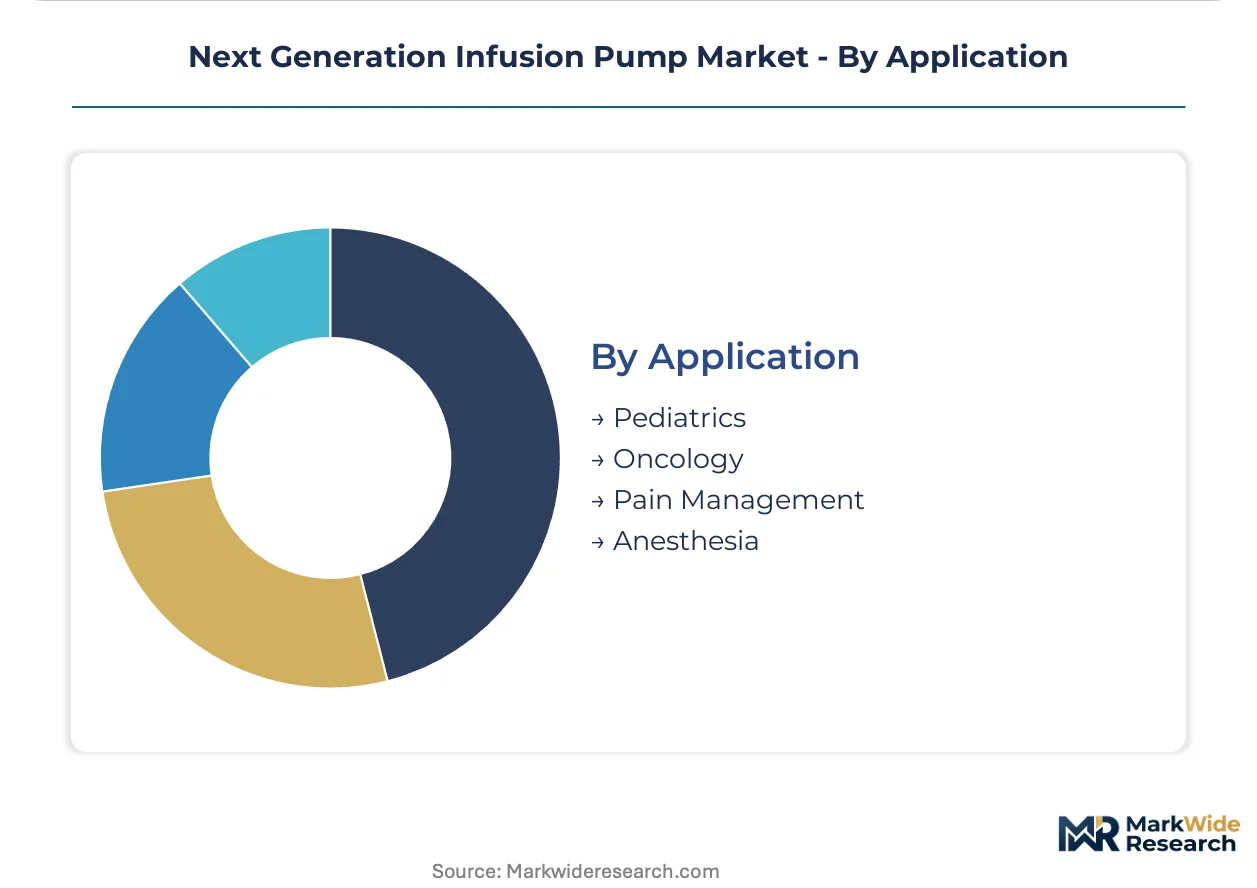
Application:
Patient population risk profiles determine regulatory intensity, with pediatrics and anesthesia facing the most stringent safety validation, while pain management applications navigate broader prescribing authority and less centralized oversight.
- Oncology:Chemotherapy infusion protocols demand precise control over vesicant and irritant medications, with extended infusion schedules driving specification changes toward silicone elastomer tubing that resists plasticizer leaching. United States cancer centers are standardizing on smart pump platforms with integrated barcode verification to prevent high-consequence dosing errors.
- Pediatrics:Neonatal and infant populations require specialized low-flow precision and weight-based dosing calculations, with FDA emphasizing closed-loop drug library compliance for this vulnerable demographic. Extended infusion protocols in pediatric intensive care are displacing PVC tubing formulations, accelerating material migration across pump valve assemblies.
- Pain Management:Patient-controlled analgesia and continuous nerve block applications utilizing ambulatory pumps for postoperative and chronic pain therapy.
- Anesthesia:Operating room environments requiring rapid-response syringe pumps with target-controlled infusion algorithms and volatile anesthetic compatibility.
Oncology sits at the top of the volume ranking, with pediatrics climbing the fastest as safety mandates intensify for vulnerable patient populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt Rhine-Main anchors the global infusion pump manufacturing footprint, with specialized polymer compounding and notified body certification expertise clustering in the Hesse region. Hospital procurement specifications diverge sharply across national reimbursement frameworks, creating distinct competitive entry barriers in each major market.
United States
Tertiary health systems in Texas and the Northeast Corridor are replacing legacy pump fleets with wireless-enabled platforms featuring bidirectional EHR connectivity. FDA closed-loop drug library compliance mandates now disqualify non-compliant equipment from federal reimbursement eligibility. Minneapolis-St. Paul hosts concentrated biomedical engineering talent pools serving firmware development for peristaltic precision control.
Germany
Outpatient infusion reimbursement expansion in Bavaria and North Rhine-Westphalia is accelerating ambulatory pump deployment beyond hospital walls. EU MDR clinical evidence requirements for dose error reduction algorithms extend certification timelines by 12-18 months through German notified bodies. Freiburg and Tübingen medical technology clusters specialize in silicone elastomer tubing formulations for extended infusion protocols.
Japan
Metropolitan Tokyo health systems prioritize compact syringe pumps with target-controlled infusion algorithms for aging surgical populations. PMDA premarket approval pathways emphasize software validation documentation for connected device architectures. Osaka-Kobe manufacturing corridors concentrate precision peristaltic mechanism production for export markets.
China
Provincial hospital tier-upgrade programs in Jiangsu and Guangdong are driving volumetric pump procurement with localized drug library configurations. NMPA innovation channel approvals for software-defined dose control architectures compress registration timelines for domestic manufacturers. Shenzhen electronics corridors supply modular wireless connectivity modules for integration into pump platforms.
United Kingdom
NHS England's medical device interoperability frameworks mandate EHR-certified infusion systems for acute trust procurement. MHRA post-Brexit regulatory pathways maintain alignment with EU MDR clinical evidence standards while streamlining UK-specific conformity assessment. London-Oxford-Cambridge health technology clusters concentrate digital health integration expertise for pump-to-hospital-network connectivity.
Next Generation Infusion Pump Market Competitive Landscape
Global majors compete with regional champions across regulatory certification capabilities and hospital service contract reach. Market structure tilts toward consolidation among manufacturers with captive polymer supply chains and established quality management systems. Three archetypes dominate: diversified medical technology conglomerates with backward integration into materials science, pure-play infusion device specialists scaling through manufacturing footprint expansion, and emerging platform vendors leveraging software subscription models. Capacity expansion in medical-grade silicone compounding and strategic partnerships for EHR interoperability certification represent the dominant competitive moves reshaping vendor positioning.
Within the diversified conglomerate tier, Becton, Dickinson and Company and Baxter International Inc. occupy positions defined by integrated supply chain control and hospital-wide service contract penetration. Fresenius Kabi AG exemplifies the manufacturing-scale archetype through dedicated infusion device production facilities. These three entities anchor competitive dynamics by representing distinct pathways to market access: materials science integration, bundled service offerings, and geographic manufacturing scale respectively.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Baxter International Inc. |
| B. Braun Melsungen AG |
| ICU Medical, Inc. |
| Fresenius Kabi AG |
| Medtronic plc |
| Terumo Corporation |
| Mindray Medical International Limited |
| Insulet Corporation |
| Others |
Supply & Pricing Matrix
Medical-grade silicone elastomer pricing indices cascade through pump manufacturing tiers, with polymer cost volatility compressing margins on standard volumetric platforms while premium smart pump architectures absorb input fluctuations through subscription-based service bundling. FDA drug library compliance mandates concentrate procurement authority among health systems with scale to negotiate enterprise pricing, fragmenting tier structures between certified interoperability platforms and legacy replacement equipment.
Pricing Analysis
Input-cost pass-through from silicone compounding and wireless connectivity modules drives three-tier pricing structure across premium, standard, and economy levels. Price differentiation centers on FDA 510(k) certification tier and EHR interoperability grade, with premium architectures commanding service-contract multiples. Pricing pressure stems from hospital GPO consolidation demanding volume discounts. Homecare channels exhibit highest price sensitivity; tertiary health systems with bundled maintenance agreements show lowest.
Supply Chain Analysis
Reverse-logistics flows for pump refurbishment and drug library software updates create secondary value streams, with remanufactured units penetrating outpatient clinic price tiers. Supply concentrates in Germany, the United States, and China for peristaltic mechanisms and silicone tubing formulations. Raw material dependencies include medical-grade silicone, lithium-ion cells, and precision stepper motors. Single-source vulnerability clusters in specialized polymer compounding. Distribution runs through hospital GPO contracts and direct manufacturer service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Next generation infusion pump markets function as regulatory compounders, where FDA closed-loop drug library compliance mandates generate replacement demand that compounds across installed base depreciation cycles.
For Market Incumbents: Acquire biomedical engineering talent pools specializing in peristaltic firmware precision control to defend against software-native entrants. Consolidate polymer compounding capabilities through backward integration into silicone elastomer supply, mitigating input concentration risk. Expand preventive maintenance contract coverage to lock hospital switching costs before ambulatory pump commoditization accelerates. For New Entrants and Emerging Players: Cloud-native dose error reduction algorithms offer technology-first wedge into mid-tier health systems lacking capital for full platform replacement. Target Germany's expanding outpatient reimbursement frameworks as the most penetrable geography, where EHR interoperability requirements remain less stringent than United States mandates. Pursue software subscription models that decouple revenue from hardware shipment cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play infusion device specialists possessing dedicated manufacturing footprints and established EU MDR quality systems. Long-term viability favors vendors with captive silicone supply and hospital service contract density exceeding hardware replacement cycles. Monitor FDA cybersecurity guidance evolution as inflection signal for connected pump lifecycle cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Premarket notification speed determines replacement cycle capture against compliance deadlines. |
| Hospital System Partnership | Enterprise service contracts displace transactional sales through uptime guarantee bundling. |
| Silicone Elastomer Backward Integration | Captive polymer compounding insulates margin from medical-grade silicone supply concentration. |
| Software Companion Development | Remote algorithm update architectures shift value capture toward recurring subscription revenue. |
| EHR Interoperability Certification | Bidirectional data exchange modules qualify platforms for United States hospital RFP shortlists. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with biomedical engineering directors, hospital purchasing committee chairs, GPO contracts managers, and infusion pump service technicians combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body submission tracking. Triangulation between demand-side capital expenditure surveys and supply-side production capacity assessments anchors volume estimates.
Historical trendline analysis of replacement cycle timing and drug library compliance adoption rates informed projection frameworks across the analysis window. Segmentation dimensions modeled include pump product type, end-user facility tier, technology certification grade, and therapy application. CAGRs derived from weighted average of equipment replacement velocity and consumable attachment rate trajectories. Forecast inputs incorporate FDA regulatory timeline assumptions and homecare reimbursement expansion patterns.
The model holds under steady regulatory enforcement intensity; deviation in FDA cybersecurity mandate timing or EU MDR notified body processing delays would shift replacement cycle phasing. Practitioners should monitor German outpatient reimbursement rulemaking and United States health system GPO consolidation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Medical Coatings Market
Medical Devices
Blood Lancet Market
Medical Devices
Hormonal Implants Market
Medical Devices
High Volume Dispensing Systems Market
Medical Devices
Medical Polyetheretherketone Market
Medical Devices
Needle-Free Drug Delivery Devices Market
Medical Devices
Global Cryotherapy Market
Medical Devices
Hybrid Grafts Market
Medical Devices
Global Robotic Wheelchairs Market
Medical Devices
Europe Ventilator Market
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
Blood Warmer Devices/Sample Warmer Market
Medical Devices
North America Medical Devices Market
Medical Devices
Stimulation Therapies Market
Medical Devices
Respiratory Devices Market