
 Middle East and Africa Electroencephalography Devices Market | 2026-2036
Middle East and Africa Electroencephalography Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Electroencephalography Devices Market Foresight
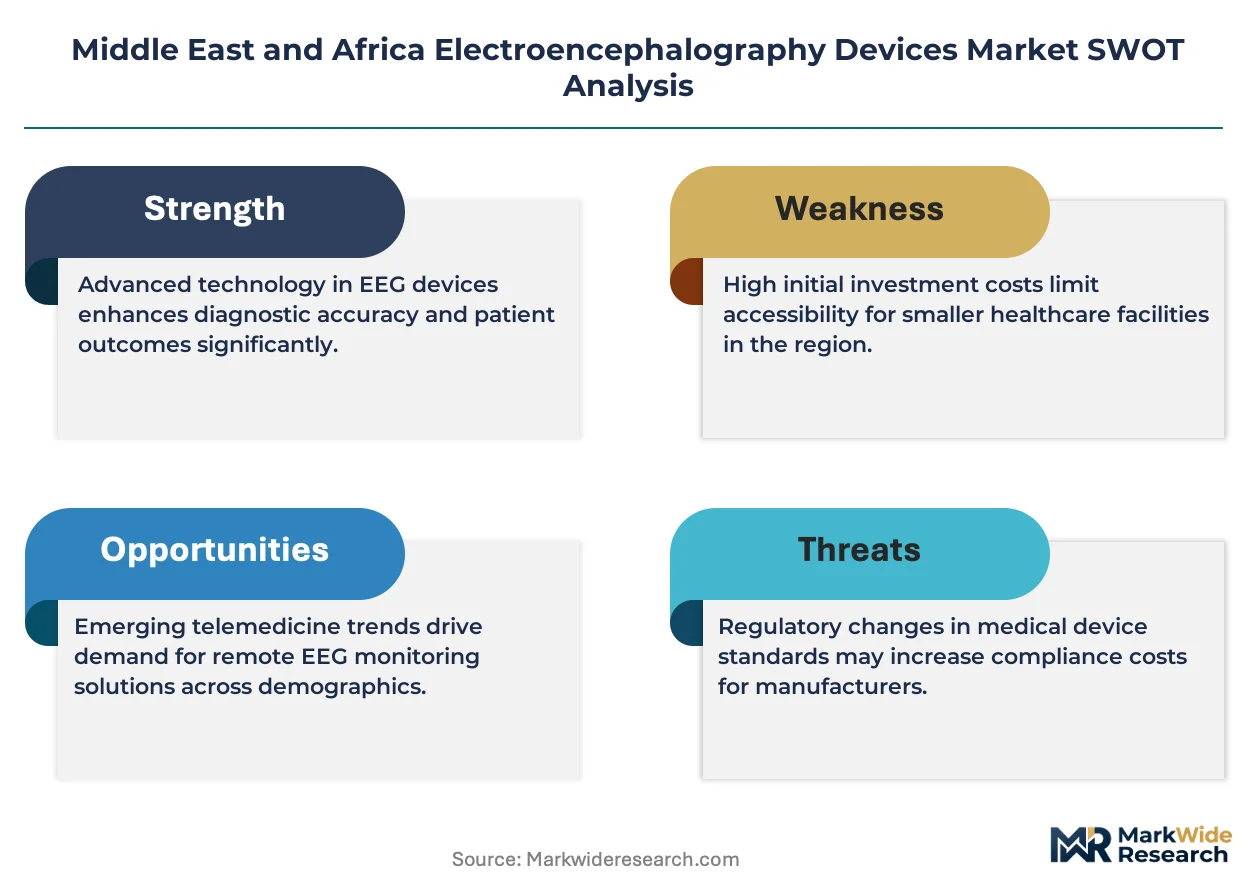
SFDA medical device registration requirements in Saudi Arabia is repositioning the cost-of-entry calculus for EEG manufacturers seeking market access. Natus Medical leverages its established distribution infrastructure across Gulf Cooperation Council states. Medtronic competes through deep specialization in intraoperative monitoring systems. Nihon Kohden Corp anchors its regional presence via hospital-direct service networks in South Africa and Nigeria.
Electroencephalography devices capture electrical activity from the scalp through arrays of electrodes, with modern digital systems sampling neural signals at 256–1024 Hz and filtering artifacts through adaptive algorithms for clinical and research diagnostics. Portable EEG systems lead volume sales across the Middle East and Africa due to their suitability for resource-limited clinical settings and mobile neurology outreach programs. Wireless EEG technology represents the fastest-expanding segment as telemedicine infrastructure proliferates in Kenya, Egypt, and Morocco. Scalp EEG maintains the largest installed base within hospital neurology departments, while intracranial EEG commands premium pricing tied to epilepsy surgery centers in South Africa and Israel.
SFDA, South Africa's Health Products Regulatory Authority, and the UAE's Ministry of Health and Prevention collectively shape product standards, import licensing timelines, and post-market surveillance obligations across the region. These frameworks elevate compliance costs for new entrants while rewarding manufacturers with established quality management systems and local regulatory affairs capabilities. Stakeholders must monitor harmonization efforts between Gulf national regulatory bodies and the African Medicines Regulatory Harmonization initiative to anticipate streamlined approval pathways or divergent technical requirements.
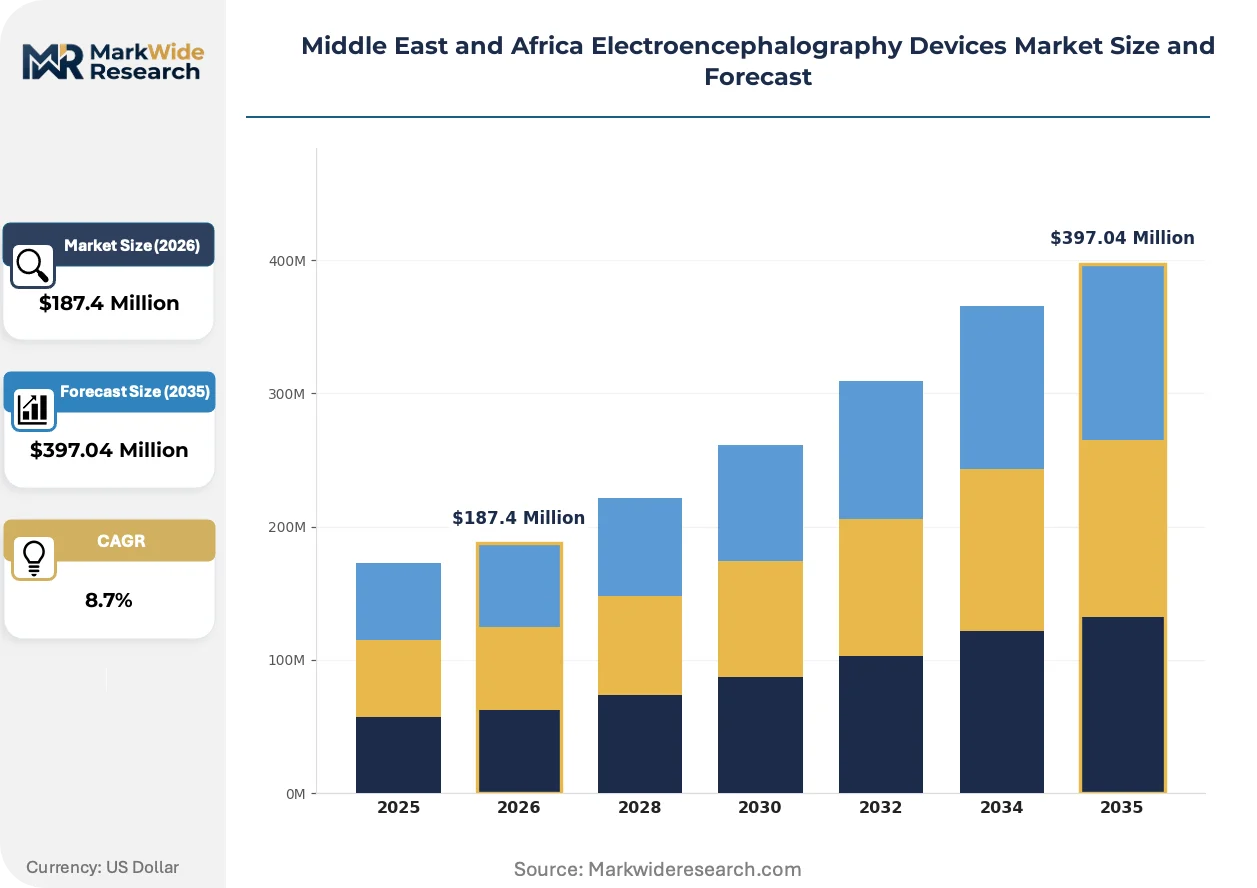
Market Dynamics
SFDA medical device registration requirements in Saudi Arabia are tightening the cost-of-entry calculus for EEG manufacturers, while wireless telemetry capabilities are compressing the traditional hospital-centered distribution model across Gulf Cooperation Council states.
Growth Catalysts
- Telemedicine infrastructure expansion:Kenya, Egypt, and Morocco are deploying national broadband backbones that enable real-time EEG data transmission from rural clinics to urban neurology centers.
- Epilepsy surgery center accreditation:South Africa's Department of Health is mandating intraoperative monitoring capabilities for Level 1 neurosurgical facilities.
- Mobile neurology outreach programs:Portable EEG systems are penetrating previously unreachable populations in Nigeria's northern states and Ethiopia's highland regions.
Market Restraints
- Import duty volatility:EEG electrode gel and disposable conductive pastes face unpredictable customs classifications across East African Community member states.
- Technical service concentration:Factory-trained biomedical engineers cluster in Johannesburg, Dubai, and Riyadh, leaving secondary cities dependent on third-party maintenance contracts.
- Substitution pressure:Transcranial Doppler and functional near-infrared spectroscopy systems are capturing share in sleep medicine and concussion assessment applications.
Strategic Opportunities
- Underpenetrated geography:Algeria's public hospital modernization program has not yet specified EEG procurement, creating first-mover positioning for vendors with French-language regulatory documentation.
- Technology convergence:Integration of artificial intelligence-based seizure detection algorithms with cloud-based EEG interpretation platforms is opening subscription revenue models.
- Channel innovation:Direct-to-neurologist equipment leasing is bypassing traditional hospital procurement committees in Ghana and Côte d'Ivoire.
Industry Challenges
- Clinical neurophysiologist scarcity:Fellowship-trained epileptologists and intraoperative monitoring specialists remain concentrated in South Africa, Israel, and Saudi Arabia.
- Biomedical certification timelines:South Africa's Health Products Regulatory Authority is extending technical file review periods for software-as-medical-device EEG analytics modules.
- Legacy system interoperability:Hospital information systems in Morocco and Tunisia use non-standard data formats that complicate EEG-LIS integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Electroencephalography Devices Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable EEG, Wireless EEG, Scalp EEG, Intracranial EEG Technology: Digital EEG, Analog EEG, Ambulatory EEG, Event-Related Potentials EEG End User: Hospitals, Clinics, Research Institutions, Home Care Application: Seizure Monitoring, Sleep Studies, Brain Mapping, Cognitive Research |
| Companies Covered | Natus Medical, Medtronic, Nihon Kohden Corp, Brain Products, Philips, Cadwell Laboratories, Compumedics, EB Neuro, KONINKLIJKE Philips N.V., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Electroencephalography Devices Market Shifts & Advancements
Wireless EEG telemetry is compressing the traditional equipment procurement cycle, while artificial intelligence-based artifact rejection is reducing reliance on specialized technologists. These shifts are redistributing value capture from hardware manufacturers toward software and service providers.
Dry-electrode arrays with active amplification circuits are overtaking conventional gel-based electrode systems in ambulatory and emergency department settings. Hospital neurology departments in the UAE and Qatar are adopting these systems for rapid seizure characterization. This technology is overtaking the established workflow of trained EEG technologists preparing patients with skin abrasion and conductive paste.
South Africa's Health Products Regulatory Authority is aligning its software-as-medical-device guidance with the International Medical Device Regulators Forum risk classification framework. This harmonization is accelerating approval timelines for cloud-based EEG interpretation platforms. Local distributors are responding by building in-house regulatory affairs capabilities rather than outsourcing to Johannesburg-based consultants.
Neurology departments are unbundling after-sales service contracts from equipment purchase agreements. Academic medical centers in Saudi Arabia and Egypt are negotiating separate multi-vendor maintenance agreements through group purchasing organizations. This pattern is most visible in the Gulf Cooperation Council states where Ministry of Health procurement reforms are mandating transparent lifecycle cost disclosure.
Middle East and Africa Electroencephalography Devices Market Segmentation
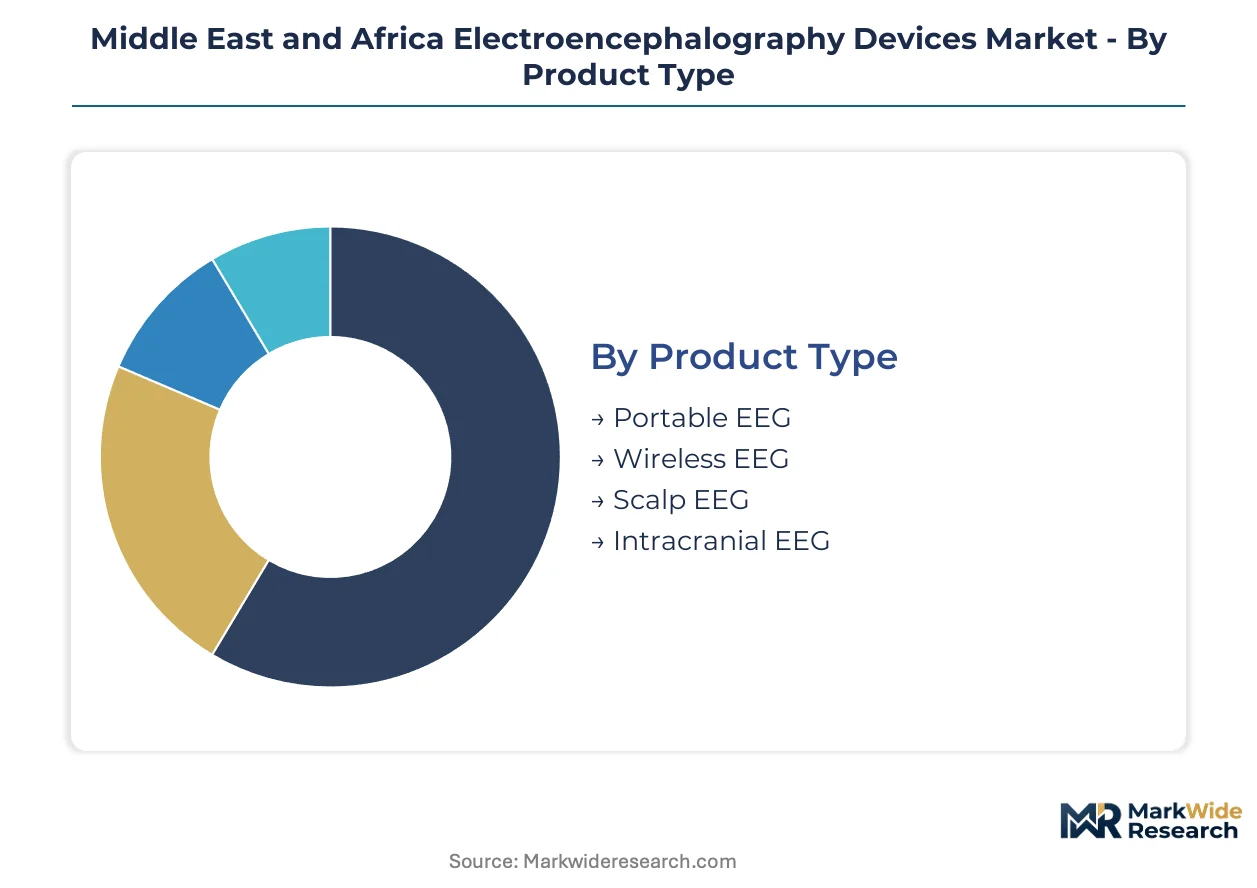
EEG device segmentation in the Middle East and Africa reflects divergent clinical workflows across resource-constrained rural clinics and capital-intensive neurosurgical centers. Procurement patterns split between portable systems for outreach programs and fixed installations for epilepsy surgery accreditation.
Product Type:
Standardized hardware platforms dominate high-volume tenders, while customized configurations prevail in specialized surgical settings across South Africa and Israel.
- Portable EEG:Battery-powered systems with 16-32 channel amplifiers and onboard storage enable deployment in Nigeria's northern states and Ethiopia's highland regions where grid reliability fluctuates. Demand concentrates in mobile neurology outreach programs sponsored by academic medical centers in Johannesburg and Addis Ababa. Procurement cycles compress when international development funding aligns with Ministry of Health rural access mandates.
- Wireless EEG:Bluetooth and Wi-Fi-enabled telemetry systems transmit real-time neural data to urban neurology hubs from peripheral clinics in Kenya and Morocco. Kenya's national broadband backbone deployment accelerates hospital procurement of these systems for county-level facilities. SFDA registration timelines in Saudi Arabia currently favor established vendors with existing 510(k) equivalency documentation.
- Scalp EEG:Conventional gel-based electrode arrays remain the institutional standard for routine diagnostic workups in hospital neurology departments across the Gulf Cooperation Council states.
- Intracranial EEG:Subdural and depth electrode systems command premium positioning within Level 1 neurosurgical facilities in South Africa and Israel.
Leading the category by volume: Portable EEG. Growing fastest: Wireless EEG.
Technology:
Cost tiers separate legacy analog installations from digital platforms with cloud-native architectures, with ambulatory systems occupying the mid-market in Egyptian and Moroccan hospital procurement.
- Digital EEG:256-1024 Hz sampling rates with adaptive artifact filtering algorithms support clinical diagnostics and research applications. Hospital neurology departments in Saudi Arabia and the UAE prioritize these systems for integration with electronic health records. South Africa's Health Products Regulatory Authority software-as-medical-device guidance accelerates approval of cloud-connected analytics modules.
- Ambulatory EEG:Extended monitoring configurations with patient-worn amplifiers capture ictal and interictal activity outside clinical settings. Demand clusters in sleep medicine programs at academic centers in Cairo and Casablanca where technician staffing constraints favor automated seizure detection. Reimbursement pathways remain fragmented across national health insurance schemes in the region.
- Analog EEG:Older amplification and paper-based recording systems persist in undercapitalized public hospitals in Algeria and Tunisia.
- Event-Related Potentials EEG:Time-locked averaging protocols for cognitive neuroscience applications concentrate in research institutions with external funding.
Dominating procurement value: Digital EEG. Expanding most quickly: Ambulatory EEG.
End User:
Customer type determines service contract structures, with hospitals demanding comprehensive maintenance and home care segments accepting remote technical support.
- Hospitals:Tertiary and quaternary facilities with dedicated neurophysiology laboratories drive equipment refresh cycles and intraoperative monitoring capability investments. South Africa's Department of Health Level 1 neurosurgical accreditation mandates compress procurement timelines for comprehensive EEG suites. Group purchasing organizations in the Gulf Cooperation Council states unbundle service contracts from equipment agreements.
- Clinics:Outpatient neurology practices and diagnostic centers in Ghana and Côte d'Ivoire adopt direct-to-physician equipment leasing to bypass hospital procurement committees. Wireless telemetry compatibility determines vendor selection for practices seeking telemedicine referral networks. Factory-trained biomedical engineer scarcity in secondary cities elevates third-party maintenance contract costs.
- Research Institutions:University-affiliated neuroscience centers in Israel and South Africa acquire specialized ERP and high-density mapping configurations.
- Home Care:Patient-operated monitoring systems for epilepsy and sleep disorders remain nascent outside South Africa's private insurance market.
Capturing largest equipment value: Hospitals. Fastest channel innovation: Clinics.
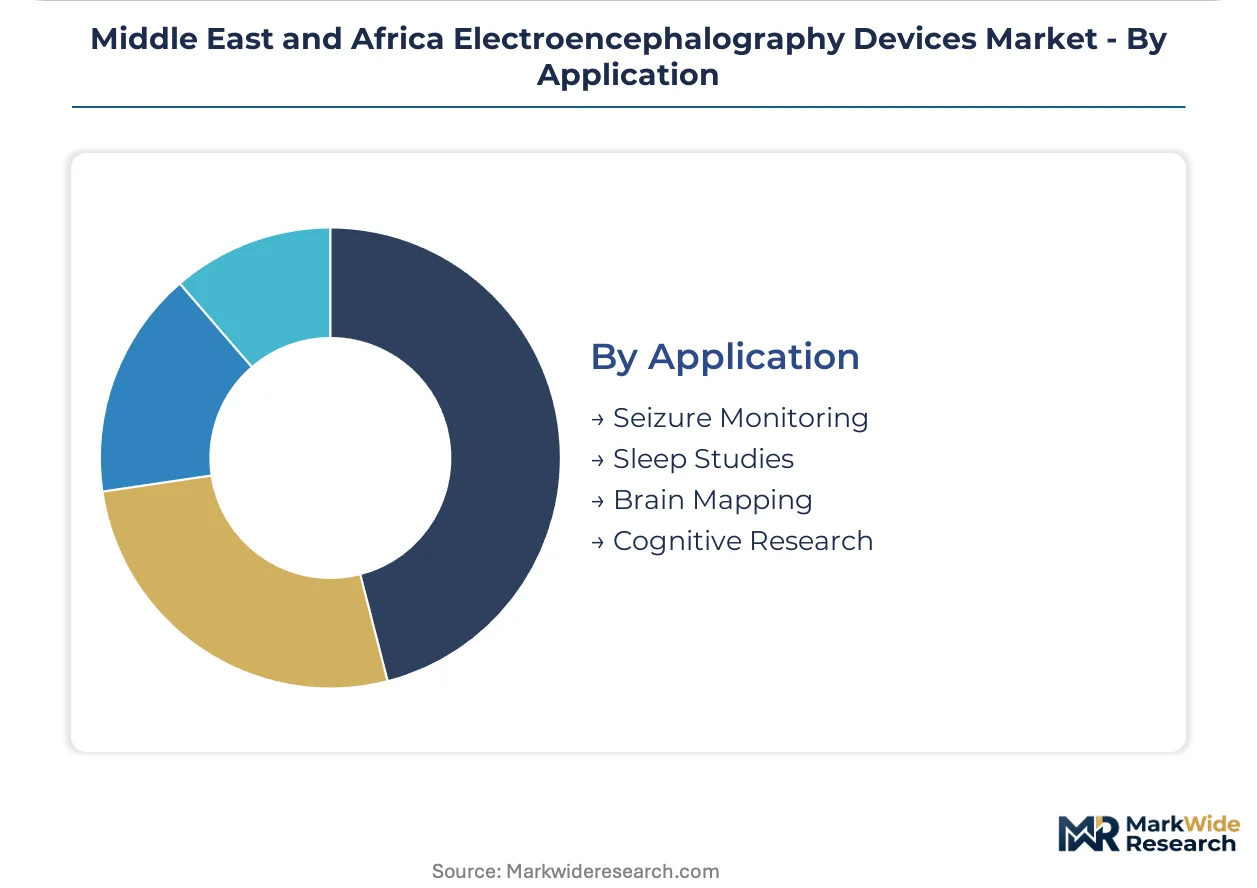
Application:
Maturity gradients separate established seizure monitoring protocols from emerging cognitive research platforms seeking consistent funding.
- Seizure Monitoring:Continuous and intermittent EEG protocols for epilepsy diagnosis and surgical candidacy evaluation constitute the core clinical indication. Dry-electrode arrays with active amplification circuits displace conventional gel-based preparation in emergency departments across the UAE and Qatar. Artificial intelligence-based artifact rejection reduces technologist staffing requirements.
- Sleep Studies:Polysomnography-integrated EEG channels for narcolepsy and parasomnia assessment face substitution pressure from transcranial Doppler and functional near-infrared spectroscopy systems. Sleep medicine programs in Saudi Arabia and Egypt prioritize multi-modal monitoring platforms over standalone EEG configurations.
- Brain Mapping:Pre-surgical functional localization for epilepsy and tumor resection concentrates in South African and Israeli surgical centers.
- Cognitive Research:Experimental paradigms for attention, memory, and language processing depend on external grant funding cycles.
Highest procedure volume: Seizure Monitoring. Steepest expansion trajectory: Sleep Studies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Economic City and Jeddah's healthcare corridor concentrate neurology infrastructure investment, while Dubai Healthcare City anchors Gulf medical device distribution networks. Special economic zones across the Middle East and Africa region accelerate EEG procurement through tax-advantaged import frameworks.
South Africa
Johannesburg's academic medical centers drive intraoperative monitoring system demand for Level 1 neurosurgical accreditation. South Africa's Health Products Regulatory Authority extends software-as-medical-device review timelines for EEG analytics modules. Cape Town's private hospital clusters unbundle service contracts from equipment purchase agreements.
Saudi Arabia
Riyadh's Ministry of Health procurement reforms mandate transparent lifecycle cost disclosure for hospital neurology departments. SFDA medical device registration requirements tighten cost-of-entry calculus for new EEG manufacturers. Eastern Province oil-company-funded healthcare facilities import wireless telemetry systems for remote workforce screening.
United Arab Emirates
Dubai's telemedicine infrastructure expansion enables real-time EEG data transmission from peripheral clinics to urban neurology hubs. MOHAP product standards shape import licensing timelines and post-market surveillance obligations across Gulf Cooperation Council states. Abu Dhabi's Cleveland Clinic affiliate adopts dry-electrode arrays for emergency department seizure characterization.
Egypt
Cairo's academic sleep medicine programs prioritize multi-modal monitoring platforms over standalone EEG configurations for narcolepsy assessment. The national broadband backbone deployment accelerates county-level hospital procurement of wireless telemetry systems. Alexandria's public hospital network maintains analog EEG installations pending modernization funding.
Kenya
Nairobi's national broadband backbone enables real-time EEG data transmission from rural clinics to urban neurology centers. Ministry of Health rural access mandates compress procurement cycles when international development funding aligns with outreach programs. Mombasa's county-level facilities represent emerging demand for portable battery-powered systems.
Middle East and Africa Electroencephalography Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Middle East and Africa EEG devices market. The vendor base clusters around three strategic archetypes: established neurology equipment manufacturers with Gulf Cooperation Council distribution infrastructure, surgical monitoring specialists with intraoperative system expertise, and hospital-direct service networks with regional biomedical engineering capabilities. Dominant competitive moves include regulatory affairs capability building in Johannesburg and Riyadh, plus unbundling of after-sales service contracts from equipment purchase agreements.
Among diversified medical technology conglomerates, Philips occupies a position exemplifying premium-tier hospital system relationships, while Medtronic represents the surgical monitoring specialization archetype through its intraoperative focus. Nihon Kohden Corp anchors the hospital-direct service network model with its biomedical engineering concentration in South Africa and Nigeria. Natus Medical sits within the established distribution infrastructure tier for Gulf Cooperation Council states.
| Leading Market Players |
|---|
| Natus Medical |
| Medtronic |
| Nihon Kohden Corp |
| Brain Products |
| Philips |
| Cadwell Laboratories |
| Compumedics |
| EB Neuro |
| KONINKLIJKE Philips N.V. |
| Others |
Supply & Pricing Matrix
Captive distribution networks across Gulf Cooperation Council states anchor both supply positioning and pricing power for EEG manufacturers, with exclusive agency agreements in Saudi Arabia and the UAE creating tiered access economics that reward early regulatory investment. SFDA registration timelines and MOHAP product standards act as gating mechanisms that concentrate margin capture among vendors with established Johannesburg and Riyadh regulatory affairs capabilities.
Pricing Analysis
Lead-time-driven pricing separates urgent procurement from planned replacement cycles, with hospital neurology departments in South Africa and Saudi Arabia paying premiums for factory-trained biomedical engineer deployment within 48 hours. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—CE-marked wireless telemetry systems command positioning above non-harmonized analog installations in Algeria and Tunisia. Cost compression in the portable EEG tier is intensifying because third-party maintenance contracts in secondary cities inflate total cost of ownership. Public hospital procurement committees in Egypt and Kenya exhibit highest price sensitivity, while private hospital clusters in Dubai and Abu Dhabi prioritize integration capabilities over unit cost.
Supply Chain Analysis
Certification and qualification gating through South Africa's Health Products Regulatory Authority, Saudi SFDA, and UAE MOHAP shapes component sourcing decisions for EEG amplifier modules and electrode arrays. Manufacturing concentration centers on Germany, Japan, and the United States for high-channel digital systems, with China supplying battery assemblies and disposable conductive accessories. Silver-silver chloride electrode production and medical-grade amplifier chip fabrication anchor raw material dependencies. Single-source vulnerability runs through specialized intraoperative monitoring cable assemblies. Distribution runs through Dubai Healthcare City logistics hubs for Gulf Cooperation Council states, with Johannesburg-based biomedical engineering networks serving sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as regulatory compliance costs and software-as-medical-device review timelines force undercapitalized distributors out of Saudi Arabia and South Africa. SFDA and Health Products Regulatory Authority harmonization pressures are accelerating this attrition.
For Market Incumbents: Deploy regulatory affairs capability expansion as the primary lever. Natus Medical and Nihon Kohden Corp should deepen in-house production of cloud-connected analytics modules to reduce software-as-medical-device approval dependencies. Channel control through direct hospital service networks in Johannesburg and Riyadh defends against emerging entrants with third-party maintenance models. Artificial intelligence-based seizure detection algorithm integration represents the critical R&D investment area to offset substitution pressure from transcranial Doppler systems. For New Entrants and Emerging Players: Direct-to-neurologist equipment leasing in Ghana and Côte d'Ivoire bypasses entrenched hospital procurement committee structures. Algeria's public hospital modernization program offers the most penetrable geography given French-language regulatory documentation requirements that incumbent vendors have not yet addressed. Wireless telemetry compatibility with Kenya's national broadband backbone enables county-level clinic penetration without competing for tertiary hospital tenders. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medical technology conglomerates seeking Gulf Cooperation Council distribution infrastructure. Long-term viability hinges on software subscription revenue models displacing transactional equipment sales. Acquisition targets should display regulatory affairs capabilities in both Riyadh and Johannesburg alongside established biomedical engineer training programs. The signal to watch is Health Products Regulatory Authority approval timeline compression for cloud-based EEG interpretation platforms, which would validate SaaS revenue model scalability.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Pathway Investment | Accelerates Saudi Arabia market access against competitors dependent on 510(k) equivalency documentation. |
| Hospital System Partnership | Cleveland Clinic Abu Dhabi and Johannesburg academic medical centers anchor reference site credibility. |
| Software Companion Development | Cloud-based EEG interpretation platforms unlock recurring revenue from AI-based artifact rejection modules. |
| Reimbursement Strategy | Navigation of South Africa's private insurance market and Egypt's fragmented national health insurance schemes determines home care segment viability. |
| CE Marking Pathway | Harmonization with South Africa's Health Products Regulatory Authority software-as-medical-device guidance accelerates multi-territory deployment. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, with primary interviews conducted across hospital purchasing committees, biomedical engineers, GPO contracts managers, and neurology department heads. SFDA submission databases, South Africa's Health Products Regulatory Authority guidance documents, and Ministry of Health procurement notices provided secondary validation. Bottom-up equipment unit estimates triangulated against top-down healthcare expenditure allocations for neurophysiology infrastructure.
Data-stream reconciliation across import volume records, hospital procurement database extracts, and distributor shipment reports informed the analytical framework. Segmentation dimensions modeled include product type, technology tier, end-user category, and application area across the analysis window. CAGRs were derived from regression-based trend extrapolation validated against regulatory milestone impacts. Forecast inputs incorporated national broadband deployment timelines in Kenya and Morocco, plus epilepsy surgery center accreditation mandates in South Africa.
The model holds under stable regulatory harmonization trajectories; deviation in SFDA-Health Products Regulatory Authority alignment timelines or Gulf Cooperation Council procurement reform implementation would shift equipment refresh cycle assumptions. A model refresh is warranted upon material change in software-as-medical-device classification guidance or telemedicine infrastructure deployment schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Therapeutic Contact Lenses Market
Medical Devices
Global Vitreoretinal Surgery Devices Market
Medical Devices
Global Dry Powder Inhaler (DPI) Market
Medical Devices
Middle East and Africa Refractive Surgery Devices Market
Medical Devices
Tissue Embedding Center Market
Medical Devices
Ultrasonic Medical Nebulizer Market
Medical Devices
Global Medical Laser Systems Market
Medical Devices
UK Artificial Organs and Bionic Implants Market
Medical Devices
Global Breast Biopsy Devices Market
Medical Devices
Face Mask Device Market
Medical Devices
Intelligent Electronic Sphygmomanometers Market
Medical Devices
Surgical Helmet Systems Market
Medical Devices
Collateral Ligament Stabilizer System Market
Medical Devices
Photorejuvenation Devices Market
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Global Medical Tricorder Device Market