
 Global Image Guided Surgery Devices Market | 2026-2036
Global Image Guided Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Image Guided Surgery Devices Market Foresight
Multi-source component sourcing is broadening among device manufacturers seeking resilient supply chains for optical sensors and electromagnetic coils. Medtronic leverages in-house manufacturing of surgical navigation platforms to control critical subassembly quality. Siemens Healthineers anchors its position through deep integration of intraoperative imaging with enterprise-wide hospital informatics. Brainlab AG specializes in software-driven surgical planning modules that differentiate its offerings from hardware-centric competitors.
Image guided surgery devices integrate real-time anatomical visualization with surgical instrument tracking to enhance procedural precision and reduce operative morbidity. These systems typically employ optical or electromagnetic tracking with sub-millimeter spatial resolution to correlate patient anatomy with preoperative imaging datasets. Navigation systems and robotic arms command the largest installed base, though intraoperative imaging segments attract disproportionate R&D investment due to recurring revenue from contrast agents and disposable components. Optical tracking dominates current deployments, while MRI guidance represents the fastest-growing technology category as magnet-compatible instrumentation matures.
FDA premarket clearance requirements under 21 CFR 892.1750 shape product development cycles for surgical navigation systems sold in the United States. The EU MDR and CE marking framework impose enhanced clinical evaluation obligations that extend time-to-market for European launches. Stakeholders must monitor evolving reimbursement pathways for robot-assisted procedures across national health technology assessment bodies.
Market Dynamics
The EU MDR's enhanced clinical evidence requirements and FDA's 510(k) pathway for Class II surgical navigation systems are compressing product development timelines while elevating barriers to market entry for device manufacturers.
Growth Catalysts
- Hybrid Operating Room Expansion:Tertiary hospitals in Germany, Japan, and the United States are retrofitting surgical suites with integrated imaging and navigation platforms to support complex neurosurgical and orthopedic procedures.
- Magnet-Compatible Instrumentation Maturation:MRI guidance technology is advancing rapidly as manufacturers resolve ferromagnetic interference challenges, enabling real-time soft tissue visualization during brain and spinal surgery.
- Reimbursement Pathway Clarification:National health technology assessment bodies in France, England, and South Korea are establishing clearer coding for robot-assisted procedures, reducing procurement uncertainty for hospital administrators.
Market Restraints
- Optical Sensor Supply Concentration:Precision optical tracking components rely heavily on specialized German and Japanese component suppliers, creating vulnerability to single-source disruptions.
- Electromagnetic Coil Input Volatility:Copper and rare earth magnet price fluctuations directly impact manufacturing costs for electromagnetic tracking systems, compressing margins for mid-tier device makers.
- EU MDR Clinical Evidence Burden:The European Medical Device Regulation's stricter post-market surveillance and clinical evaluation requirements extend time-to-market by 18-24 months for novel navigation platforms.
Strategic Opportunities
- Ambulatory Surgery Center Penetration:Outpatient facilities in the United States and Australia represent underdeveloped deployment channels for compact, lower-cost navigation systems designed for arthroscopic and ENT procedures.
- AI-Assisted Surgical Planning Convergence:Machine learning algorithms trained on preoperative imaging datasets are integrating with navigation hardware to predict anatomical deformation and optimize instrument trajectories.
- Japan's Aging Surgical Workforce:The country's demographic shift toward older practicing surgeons is accelerating demand for intuitive, software-guided platforms that compensate for declining manual dexterity prevalence.
Industry Challenges
- Electromagnetic-Optical System Interoperability:Hospitals struggle to integrate mixed-modality tracking platforms with legacy surgical equipment, requiring costly middleware development and staff retraining programs.
- Biomedical Engineer Talent Scarcity:The specialized skill set combining surgical workflow knowledge, imaging physics, and robotics programming concentrates in academic medical centers, limiting vendor field support capacity.
- CE Marking Timeline Compression:Notified body capacity constraints under the EU MDR are creating certification backlogs that delay product launches and tie up R&D capital for extended periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Image Guided Surgery Devices Market |
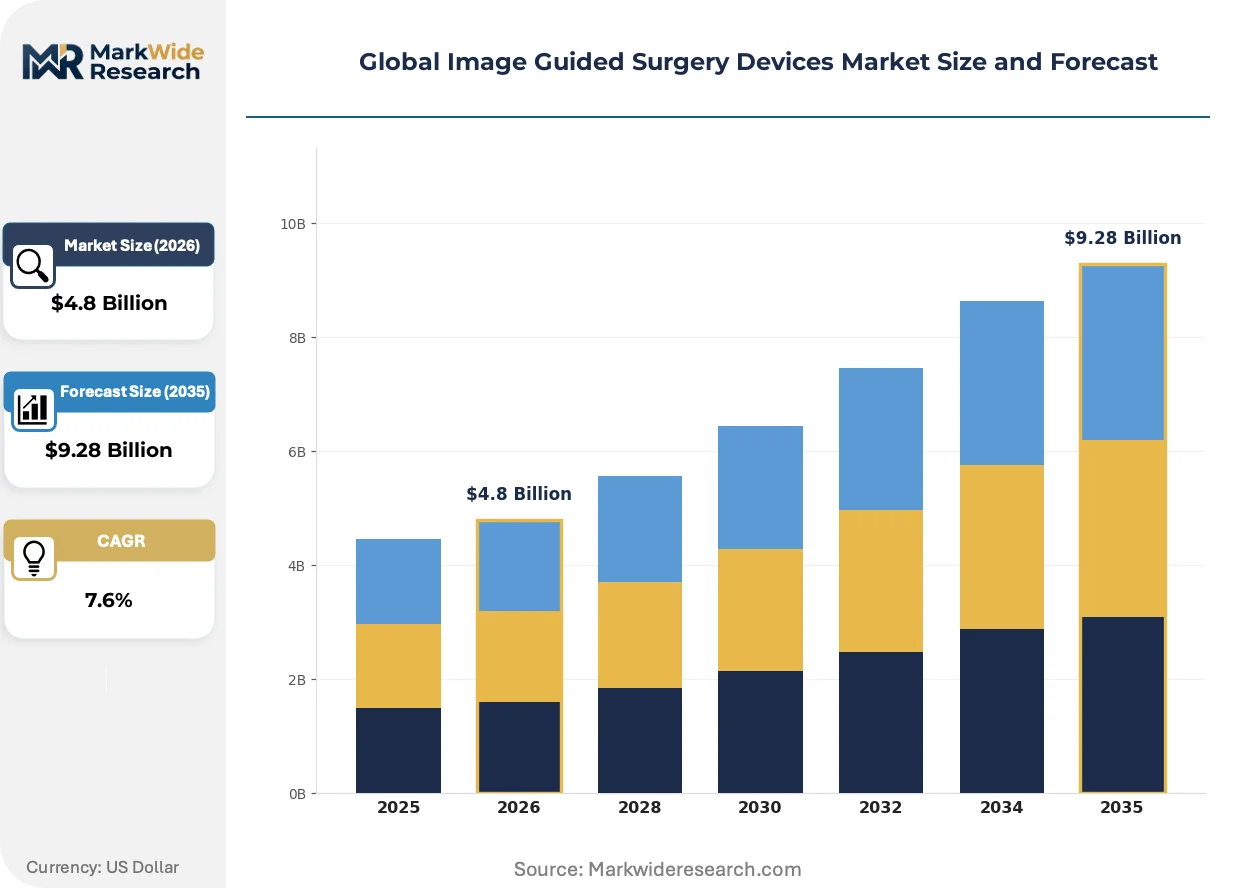
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Navigation Systems, Robotic Arms, Tracking Devices, Intraoperative Imaging, Surgical Microscopes Technology: Optical Tracking, Electromagnetic Tracking, Ultrasound Guidance, Fluoroscopy, MRI Guidance Application Area: Neurosurgery, Orthopedics, Cardiovascular Surgery, ENT Procedures, Urology End User: Specialty Clinics, Ambulatory Surgery Centers, Research Institutes, Educational Hospitals |
| Companies Covered | Medtronic, Stryker Corporation, GE Healthcare, Brainlab AG, Siemens Healthineers, Koninklijke Philips N.V., Zimmer Biomet Holdings, Olympus Corporation, Intuitive Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Image Guided Surgery Devices Market Shifts & Advancements
Real-time anatomical visualization is merging with predictive analytics and minimally invasive techniques, fundamentally altering how surgical teams plan, execute, and document complex procedures across subspecialties.
Intraoperative MRI guidance is rewriting the standard of care for brain tumor resection by enabling surgeons to verify complete lesion removal before closing the cranium. Academic neurosurgical departments in Switzerland, the United States, and South Korea are prioritizing magnet-compatible navigation platforms despite capital intensity. This capability is compressing revision surgery rates and redrawing competitive differentiation around soft tissue visualization rather than bone-anchored tracking alone.
The EU Medical Device Regulation's post-market clinical follow-up requirements are forcing manufacturers to embed real-world evidence collection into product architectures. Device makers must now design navigation systems with built-in outcome capture functionality to satisfy notified body surveillance expectations. European launches face extended validation phases as firms reconcile legacy hardware with new software-enabled data transmission protocols.
Hospital procurement committees are consolidating vendor relationships around enterprise-wide informatics integration rather than standalone device performance. Siemens Healthineers and Brainlab AG are capturing preference through hospital information system connectivity that competitors lacking software depth cannot match. This pattern concentrates purchasing authority in health system headquarters across Germany, the Netherlands, and Canada, marginalizing surgeon-driven device selection.
Global Image Guided Surgery Devices Market Segmentation
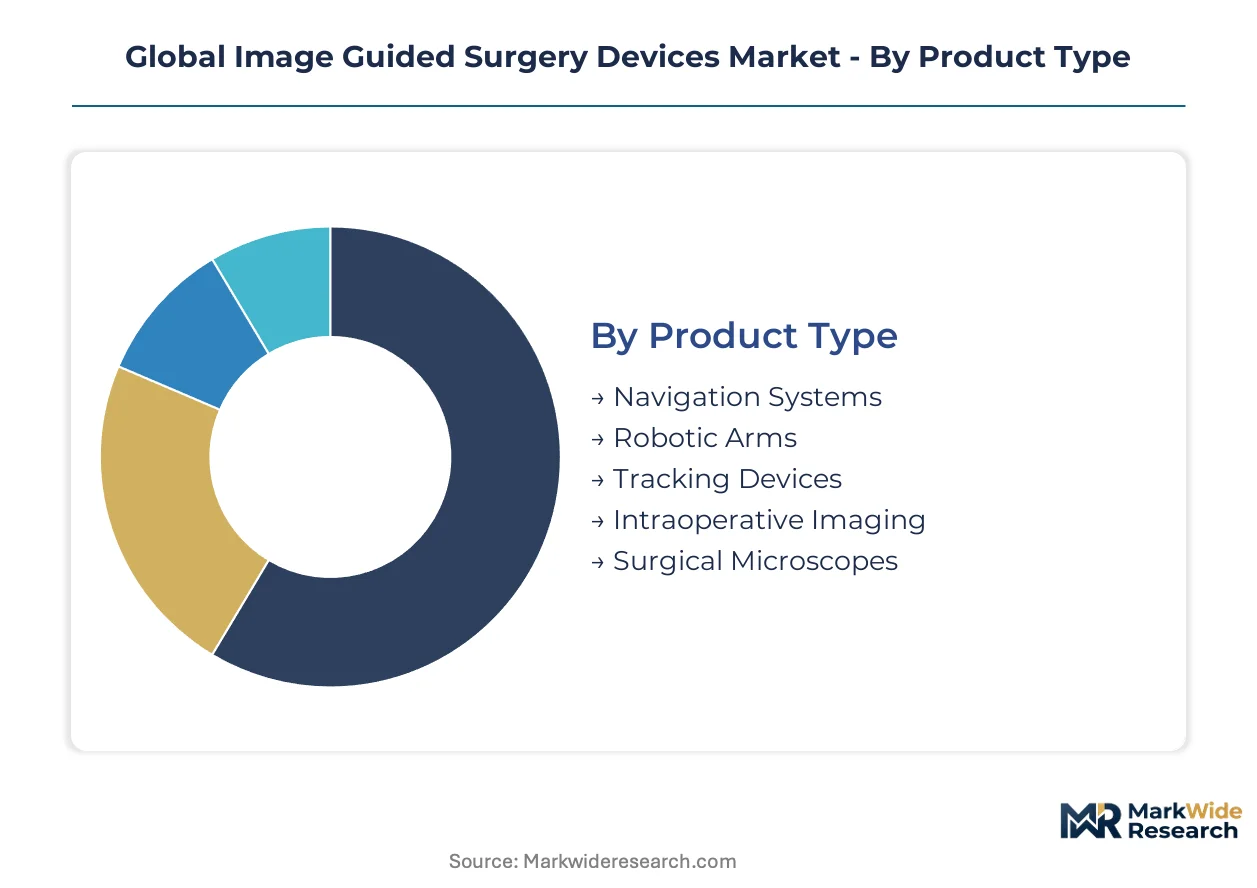
Segmentation in image guided surgery devices reveals how technical specifications, clinical workflows, and procurement authority distribute value across the supply chain. Product architecture and tracking modality determine installation complexity and recurring revenue potential. Application focus and facility type dictate pricing tolerance and replacement cycles.
Product Type:
Technology architecture defines capital intensity, service attach rates, and competitive differentiation for device manufacturers.
- Navigation Systems:These platforms fuse preoperative imaging with real-time instrument tracking through optical or electromagnetic sensors. Tertiary hospitals in Germany and the United States prioritize systems with sub-millimeter registration accuracy for cranial and spinal procedures. FDA 510(k) clearance timelines and EU MDR clinical evidence requirements compress development cycles for novel platforms.
- Robotic Arms:Motorized positioning systems with haptic feedback enable minimally invasive trajectories in orthopedic and urological surgery. Academic medical centers in Japan and South Korea drive procurement as surgical residency programs integrate robotics training into core curricula. Capital intensity limits penetration to hospitals with hybrid operating room infrastructure.
- Tracking Devices:Standalone optical and electromagnetic arrays provide spatial localization for third-party surgical instruments.
- Intraoperative Imaging:Mobile C-arms, O-arms, and cone-beam CT systems deliver real-time anatomical verification during complex interventions.
- Surgical Microscopes:Integrated navigation-enabled microscopes support ophthalmic and neurosurgical procedures requiring extreme magnification precision.
Navigation systems lead on scale; robotic arms lead on momentum.
Technology:
Tracking modality selection determines magnet compatibility, line-of-sight constraints, and integration complexity with existing surgical equipment.
- Optical Tracking:Infrared camera arrays triangulate reflective markers on instruments and patient reference frames with sub-millimeter precision. Current deployments dominate neurosurgical suites across Switzerland, the United States, and South Korea due to established validation and lower electromagnetic interference susceptibility. Line-of-sight requirements constrain surgical team positioning and instrument design.
- MRI Guidance:Magnet-compatible navigation enables real-time soft tissue visualization during brain tumor resection and functional neurosurgery. Academic departments in the United States and Switzerland prioritize these platforms despite ferromagnetic instrumentation challenges and higher capital requirements. This modality is expanding most quickly as coil design and shielding protocols mature.
- Electromagnetic Tracking:Sensor coils embedded in instruments enable tracking without direct visual contact.
- Ultrasound Guidance:Real-time sonographic imaging supports soft tissue navigation in orthopedic and cardiovascular applications.
- Fluoroscopy:Continuous X-ray imaging provides bone-anchored reference frames for spinal and trauma surgery.
Optical tracking dominates installed base; MRI guidance climbs the fastest.
Application Area:
Clinical specialization shapes hardware requirements, reimbursement pathways, and competitive vendor positioning.
- Neurosurgery:Cranial and spinal procedures demand the highest spatial precision and soft tissue visualization capabilities. Tertiary hospitals in Germany, Japan, and the United States anchor demand for integrated navigation and intraoperative MRI platforms. FDA premarket notification requirements under 21 CFR 892.1750 and EU MDR clinical evaluation obligations extend validation timelines for novel neurosurgical devices.
- Orthopedics:Joint replacement and trauma fixation procedures drive volume deployment of navigation systems with bone-anchored tracking. Ambulatory surgery centers in the United States and Australia represent underpenetrated channels for compact, lower-cost platforms designed for arthroscopic applications. Reimbursement coding clarity from national health technology assessment bodies influences procurement decisions.
- Cardiovascular Surgery:Structural heart interventions and electrophysiology procedures require specialized catheter tracking.
- ENT Procedures:Sinus and skull base surgery utilizes compact navigation systems with reduced workspace requirements.
- Urology:Prostate and renal interventions employ MRI-ultrasound fusion platforms for targeted biopsy and ablation.
Neurosurgery leads on scale; orthopedics leads on momentum.
End User:
Facility type determines capital availability, case volume, and integration requirements with enterprise informatics systems.
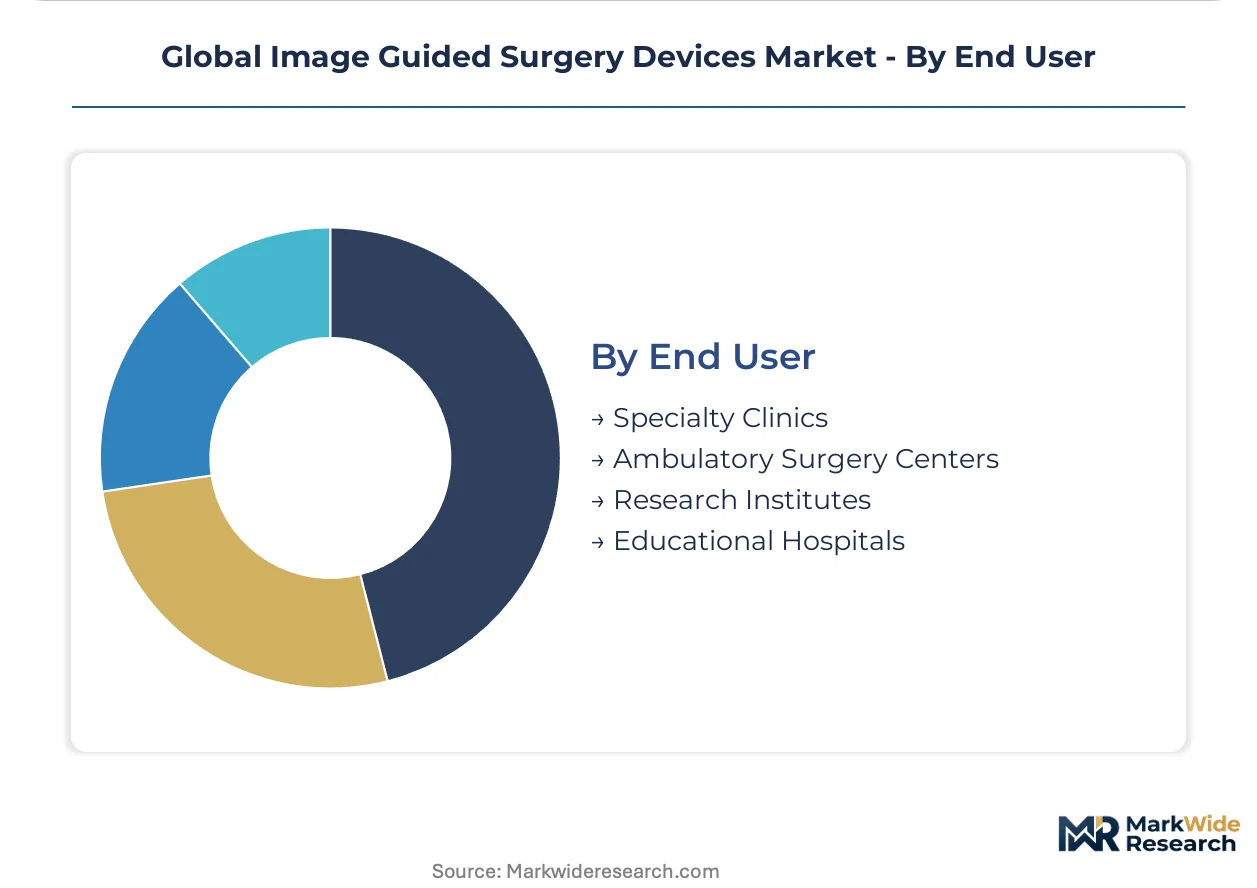
- Specialty Clinics:Focused surgical centers concentrate high-volume procedures in single specialties such as orthopedics or ENT. Germany and the Netherlands host established networks of independent clinics with procurement authority concentrated at regional health system headquarters. These facilities prioritize compact navigation platforms with streamlined workflows over comprehensive intraoperative imaging suites.
- Ambulatory Surgery Centers:Outpatient facilities in the United States and Australia perform same-day procedures requiring portable, lower-cost tracking systems. Reimbursement pathway clarification from Medicare and private payors shapes equipment investment timelines. Capital constraints favor leasing models and refurbished device procurement.
- Research Institutes:Academic laboratories validate novel navigation algorithms and instrument designs prior to clinical translation.
- Educational Hospitals:Teaching institutions integrate navigation platforms into surgical residency curricula across Japan and South Korea.
Specialty clinics lead on scale; ambulatory surgery centers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Baden-Württemberg region anchors European demand for surgical navigation platforms through its concentration of precision medical device engineering and university hospital networks.
United States
Academic medical centers in Boston and the San Francisco Bay Area drive procurement of intraoperative MRI guidance systems for neurosurgical applications. FDA premarket notification requirements under 21 CFR 892.1750 compress development timelines for novel navigation platforms seeking US market entry. The Cleveland Clinic and Mayo Clinic anchor adoption clusters in the Midwest and Southwest.
Germany
Tertiary hospitals in Berlin and Munich retrofit surgical suites with integrated hybrid operating room infrastructure for complex spinal procedures. The EU MDR's enhanced clinical evidence requirements extend validation phases for European device launches. Siemens Healthineers anchors industrial concentration in Erlangen and Forchheim.
Japan
Aging surgical demographics in Tokyo and Osaka accelerate demand for software-guided platforms that compensate for declining manual dexterity prevalence. The PMDA's streamlined review pathways for innovative medical devices shorten time-to-market for navigation systems with novel tracking modalities. Keio University Hospital and Tokyo Medical University anchor neurosurgical adoption clusters.
Switzerland
Academic neurosurgical departments in Zurich and Geneva prioritize magnet-compatible navigation platforms despite higher capital intensity. Swissmedic's alignment with EU MDR standards ensures regulatory continuity for device manufacturers serving both markets. The University Hospital of Zurich anchors intraoperative MRI guidance adoption.
South Korea
Educational hospitals in Seoul and Daegu integrate navigation platforms into surgical residency curricula as robotics training becomes mandatory. The MFDS establishes clearer reimbursement coding for robot-assisted procedures, reducing procurement uncertainty for hospital administrators. Samsung Medical Center and Asan Medical Center anchor adoption in the capital region.
Global Image Guided Surgery Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-driven differentiation and ambulatory surgery center penetration. The vendor base stratifies across three tiers: diversified conglomerates with enterprise informatics integration, specialized navigation platform developers, and component suppliers for optical and electromagnetic tracking subsystems. Dominant competitive moves include strategic partnerships with academic medical centers for clinical validation and portfolio diversification into AI-assisted surgical planning modules.
Within the diversified medical technology tier, Medtronic and Stryker Corporation represent archetypes of in-house manufacturing control and orthopedic navigation specialization respectively. Brainlab AG exemplifies the software-centric competitor archetype through its surgical planning modules that differentiate offerings from hardware-centric rivals. Siemens Healthineers anchors the imaging-integration archetype by embedding navigation platforms within enterprise-wide hospital informatics systems.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| GE Healthcare |
| Brainlab AG |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Zimmer Biomet Holdings |
| Olympus Corporation |
| Intuitive Surgical |
| Others |
Supply & Pricing Matrix
Copper and rare earth magnet price indices cascade through electromagnetic tracking system manufacturing into three-tier pricing structures across premium, standard, and economy levels. Component cost volatility compresses margins for mid-tier device makers while concentrated optical sensor sourcing in Germany and Japan elevates pricing power for integrated navigation platform vendors.
Pricing Analysis
Input-cost pass-through from ferromagnetic shielding alloys and precision optical arrays shapes tiered pricing across navigation platforms. FDA 510(k) certification tier and sub-millimeter registration accuracy separate premium neurosurgical suites from standard orthopedic deployments. Pricing pressure stems from EU MDR clinical evidence burdens extending validation timelines and tying up R&D capital. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraints and leasing preference, while academic medical centers prioritize performance over procurement cost.
Supply Chain Analysis
CE marking and FDA premarket notification requirements gate component qualification for optical tracking arrays and electromagnetic coil assemblies. Precision sensor manufacturing concentrates in Germany, Japan, and the United States, with magnet-compatible instrumentation development anchored in Switzerland and South Korea. Supply chains draw from copper windings, rare earth magnets, and infrared emitter substrates. Single-source vulnerability persists for specialized optical sensor suppliers. Distribution runs through direct hospital procurement committees and group purchasing organizations consolidating enterprise informatics contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU MDR's enhanced clinical evidence requirements compound regulatory barriers into sustainable competitive moats for prepared device manufacturers. This regulatory compounder effect accelerates demand for navigation platforms with embedded real-world evidence collection architectures.
For Market Incumbents: Deploy in-house manufacturing control over critical subassemblies to defend against optical sensor supply concentration risks. Medtronic's captive production of surgical navigation platforms exemplifies this lever. Consolidate hospital informatics integration partnerships before procurement authority shifts definitively to health system headquarters. Software-driven competitors like Brainlab AG threaten hardware-centric positioning through planning module differentiation.
For New Entrants and Emerging Players: Begin with ambulatory surgery center penetration for compact, lower-cost navigation systems designed for arthroscopic and ENT procedures. Australia's outpatient facilities and United States Medicare-certified ASCs represent underpenetrated white-space with clarified reimbursement pathways. Target AI-assisted surgical planning convergence as the go-to-market angle, integrating predictive algorithms with existing hardware rather than competing on capital intensity.
For Investors and Strategic Acquirers: Asymmetric upside sits with software-centric navigation specialists possessing hospital information system connectivity and AI-assisted planning modules. Long-term viability in this market hinges on regulatory compliance infrastructure and recurring revenue from disposable components. Watch for MFDS reimbursement coding clarity in South Korea and PMDA streamlined review completions in Japan as inflection indicators for regional demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements extend validation timelines for European device launches by notified bodies. |
| Hospital System Partnership | Siemens Healthineers captures preference through enterprise-wide informatics integration that marginalizes standalone vendors. |
| Software Companion Development | Brainlab AG differentiates through surgical planning modules that compensate for hardware commoditization pressures. |
| Reimbursement Strategy | National health technology assessment bodies in France and England establish clearer coding for robot-assisted procedures. |
| FDA Submission | Premarket notification under 21 CFR 892.1750 compresses development cycles for Class II surgical navigation systems. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to triangulate market sizing and growth trajectory assumptions. Primary discussions with neurosurgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers informed procedural adoption patterns and procurement authority shifts. Secondary validation drew from FDA 510(k) filings, EU MDR notified body guidance documents, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up installation base modeling and top-down healthcare capital expenditure analysis converged on segment-level estimates.
Segment-weighting across product architecture, tracking modality, clinical application, and facility type anchored the analytical framework across the analysis window. Navigation systems, robotic arms, and intraoperative imaging platforms were modeled separately with technology-specific replacement cycles and service attach rates. CAGRs were derived from procedure volume elasticity, capital expenditure forecasts, and regulatory timeline impacts. Magnet-compatible instrumentation maturation and AI-assisted surgical planning convergence served as technology-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen regulatory timeline compressions, supply chain disruptions from geopolitical events, and radical technology displacement from alternative surgical visualization modalities. Forecasts reflect assumptions about reimbursement pathway stability and hybrid operating room capital expenditure continuity. A model refresh is warranted upon material change in EU MDR notified body capacity constraints or FDA premarket review pathway restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spinal Cord Stimulators Market
Medical Devices
Tissue Embedding Center Market
Medical Devices
Global Surgical Microscopes Market
Medical Devices
Japan Anesthesia Devices Market
Medical Devices
Electric Breast Pumps Market
Medical Devices
Solar Surgical Light Market
Medical Devices
Oxygen Concentrators Market
Medical Devices
Urinary Flow Meters Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Japan Ultrasound Devices Market
Medical Devices
Enteral Stents Market
Medical Devices
Europe Mobility Aids Market
Medical Devices
3D Surgical Microscope Systems Market
Medical Devices
Urodynamic Catheter Market
Medical Devices
Speech Generating Devices Market
Medical Devices
Medical Smart Wearable Devices Market