
 Nuclear Magnetic Resonance Spectroscopy Market | 2026-2036
Nuclear Magnetic Resonance Spectroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Magnetic Resonance Spectroscopy Market Intelligence
Multi-source procurement of superconducting magnets and RF components is expanding as instrument manufacturers diversify supply chains beyond single cryogen vendors. Bruker Corporation leverages in-house magnet production to control lead times on high-field systems. JEOL Ltd. anchors its position through specialized probe design for solid-state applications. Thermo Fisher Scientific competes by integrating NMR software with broader analytical workflows.
Nuclear magnetic resonance spectroscopy employs strong static magnetic fields, typically 300–1,200 MHz proton frequency, to detect nuclear spin transitions and elucidate molecular structure with atomic resolution. The technique serves as the definitive method for determining three-dimensional protein conformations, metabolite identification, and synthetic compound verification in regulated laboratories. High-field NMR instruments command the largest revenue share due to irreplaceable resolution demands in structural biology, while low-field NMR gains traction for at-line process monitoring in pharmaceutical manufacturing where benchtop footprint and helium independence matter. Software and probes capture disproportionate margin pools as recurring revenue streams with shorter replacement cycles than magnet platforms.
FDA 21 CFR Part 11 electronic records requirements and EMA ICH Q2(R1) analytical validation guidelines compel pharmaceutical end users to select NMR platforms with embedded compliance architecture. ISO 17025 accreditation standards for testing laboratories further filter vendor qualification in contract research settings. Stakeholders must weigh magnet field strength against helium sustainability as cryogen-free alternatives mature and carbon accounting penetrates capital expenditure decisions.
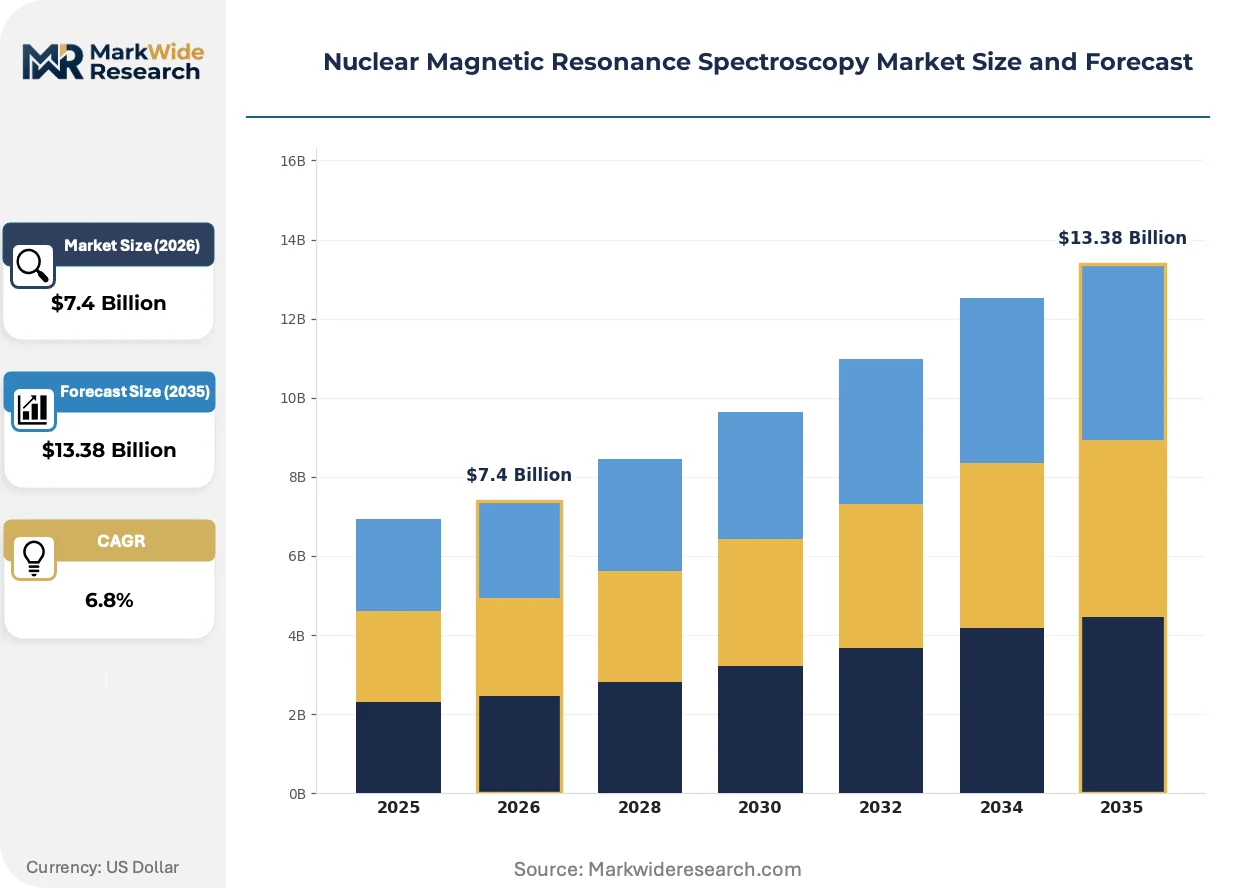
Market Dynamics
Helium supply constraints and cryogen-free magnet maturation are restructuring capital deployment patterns across pharmaceutical and academic procurement offices, forcing buyers to weigh field stability against operational sustainability in long-term instrument planning.
Growth Catalysts
- Structural biology pipelines:Pharmaceutical R&D expansion into biologics and precision therapeutics intensifies demand for high-field protein NMR characterization. Academic-industrial consortia in the United States, Germany, and Japan maintain dense instrument clusters.
- FDA 21 CFR Part 11:Electronic records mandates tighten software qualification requirements, favoring platforms with embedded compliance architecture over modular alternatives in regulated laboratories.
- Benchtop NMR maturation:Permanent magnet designs eliminate helium dependency and reduce footprint, opening at-line process monitoring applications in pharmaceutical manufacturing quality control.
Market Restraints
- Superconducting wire concentration:Niobium-titanium and niobium-tin supply chains concentrate among limited specialty metallurgy suppliers, creating lead time vulnerability for high-field magnet production.
- Technical resolution ceiling:Solid-state NMR of membrane proteins and large complexes remains constrained by probe sensitivity limits below 1.2 GHz proton frequency.
- EMA ICH Q2(R1) friction:Analytical validation guideline complexity extends instrument qualification timelines, delaying revenue recognition for contract research organizations.
Strategic Opportunities
- India biopharma expansion:CDSCO regulatory alignment with ICH standards and PLI scheme incentives create procurement windows for mid-field systems in contract manufacturing.
- AI-NMR convergence:Machine learning spectral interpretation tools compress analysis timeframes and expand operator pools beyond specialist spectroscopists.
- Carbon accounting mandates:EU Green Deal reporting requirements favor cryogen-free platforms in European capital expenditure decisions, disadvantaging helium-intensive alternatives.
Industry Challenges
- Specialized magnet engineer scarcity:Superconducting magnet winding and cryostat assembly expertise concentrates among retiring cohorts, constraining production scaling.
- Legacy software integration:ISO 17025 accreditation requirements clash with proprietary data formats from installed instrument bases, complicating laboratory information management system connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Magnetic Resonance Spectroscopy Market |
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NMR Instruments, Software, Probes, Accessories End User: Academic Institutions, Pharmaceutical Companies, Research Laboratories, Biotechnology Firms Technology: High-Field NMR, Low-Field NMR, Solid-State NMR, 2D NMR Application: Structural Biology, Chemical Analysis, Material Science, Drug Discovery |
| Companies Covered | Bruker Corporation, JEOL Ltd., Thermo Fisher Scientific Inc., Oxford Instruments plc, Nanalysis Scientific Corp., Magritek, Anasazi Instruments, Inc., QOneTec, Advanced Magnetic Resonance Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Magnetic Resonance Spectroscopy Market Strategic Shifts & Innovations
Cryogen-free magnet architectures, regulatory data integrity mandates, and service model unbundling are converging to restructure how NMR capability is procured, operated, and monetized across end-use verticals.
Dynamic nuclear polarization (DNP) is electrifying sensitivity limits for biological solid-state NMR by transferring electron polarization to nuclei at cryogenic temperatures. Structural biology departments at major research universities are adopting DNP-NMR systems for membrane protein and amyloid fibril characterization. The technology is compressing sample quantity requirements and enabling previously intractable biological targets.
REACH and the EU F-Gas Regulation are tightening containment and reporting requirements for helium used in superconducting magnet cooling. Pharmaceutical manufacturers and academic core facilities face expanded documentation burdens and supply security reviews. European buyers are accelerating evaluation of cryogen-free permanent magnet alternatives for routine quality control applications.
Service contract unbundling is fragmenting traditional full-service agreements into componentized offerings covering magnet maintenance, probe refurbishment, and software support separately. Academic core facilities and mid-sized contract research organizations are driving this shift toward à la carte coverage. The United States and Germany show the strongest uptake of unbundled service procurement.
Nuclear Magnetic Resonance Spectroscopy Market Segmentation
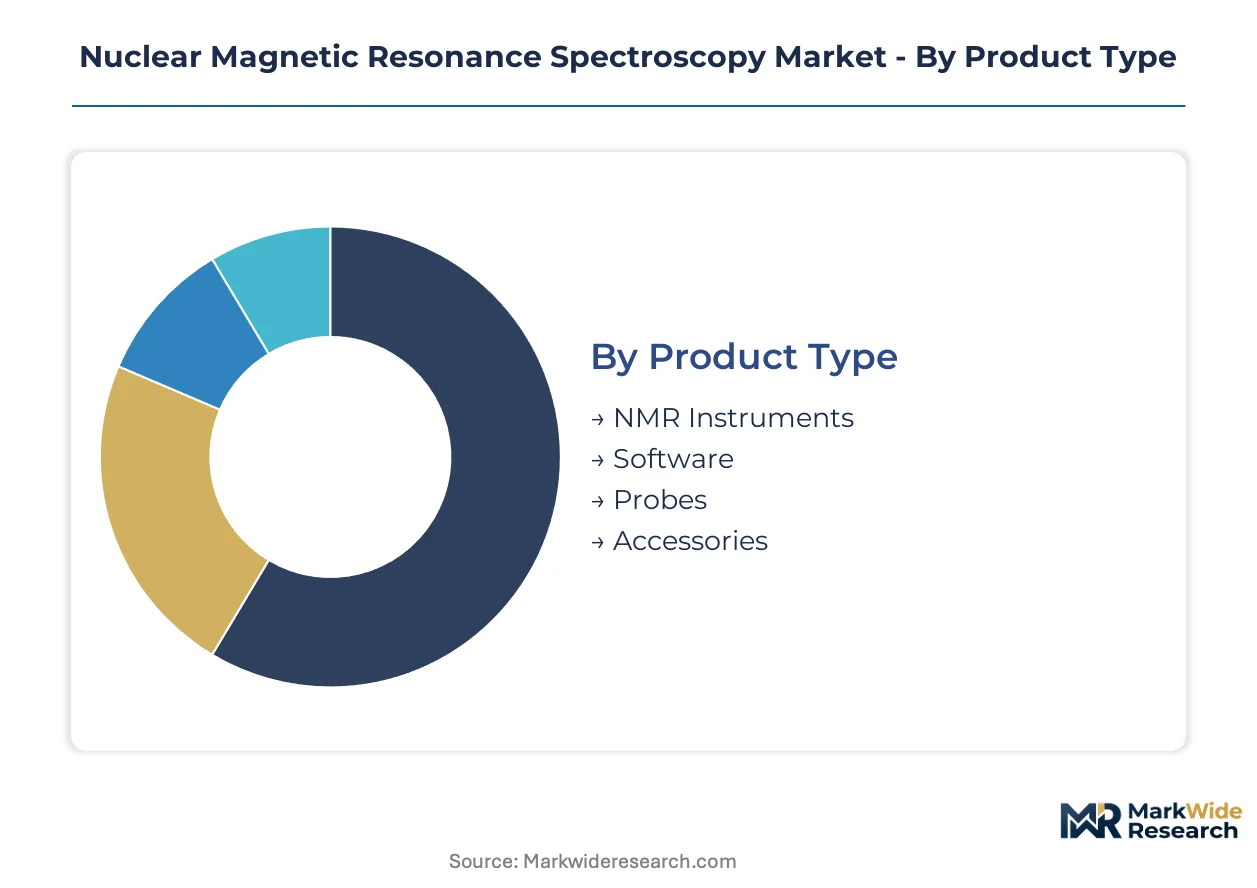
NMR spectroscopy segmentation reflects divergent procurement logics across capital-intensive magnet platforms and recurring consumables. Pharmaceutical buyers prioritize compliance architecture and throughput, while academic institutions balance field strength against grant sustainability. Understanding these segment boundaries clarifies where vendors can unbundle offerings versus where integrated platforms dominate.
Product Type:
Customization intensity spans from bespoke high-field magnet configurations to standardized software licenses, with margin concentration shifting toward recurring revenue streams.
- NMR Instruments:Superconducting magnet platforms ranging from 300 MHz benchtop systems to 1.2 GHz research spectrometers command the largest capital outlays. Procurement concentrates among United States, German, and Japanese academic-industrial clusters where dense infrastructure sustains high-field demand. FDA 21 CFR Part 11 compliance requirements increasingly filter vendor selection in pharmaceutical quality control laboratories.
- Software:Spectral processing suites, electronic laboratory notebook integration, and AI-assisted structure elucidation tools generate recurring licensing revenue with compressed replacement cycles. EMA ICH Q2(R1) validation mandates favor platforms with embedded audit trails over modular alternatives in regulated environments.
- Probes:Cryogenically cooled detection hardware and solid-state MAS probeheads differentiate application capabilities across liquid and biological samples.
- Accessories:Sample changers, automated tuning modules, and cryogen monitoring systems extend instrument functionality without magnet replacement.
Leading the category by volume: NMR Instruments. Growing fastest: Software.
End User:
Customer archetypes diverge sharply in procurement authority, with pharmaceutical consolidated buying power contrasting fragmented academic decision-making.
- Academic Institutions:University core facilities and departmental laboratories drive demand for high-field systems serving structural biology and materials research. Grant funding cycles from NIH, DFG, and JSPS shape replacement timelines, with shared instrumentation models spreading capital burden across multiple research groups.
- Pharmaceutical Companies:Large-cap biopharma and emerging biotech firms deploy NMR for biologics characterization, metabolite identification, and synthetic compound verification. CDSCO alignment with ICH standards in India is opening procurement windows for mid-field quality control systems in contract manufacturing organizations.
- Research Laboratories:Government and independent research institutes occupy intermediate scale between academic cores and industrial operations.
- Biotechnology Firms:Cell therapy and gene editing developers leverage NMR for process analytical technology and release testing.
Dominant procurement volume sits with Academic Institutions. Steepest expansion trajectory belongs to Biotechnology Firms.
Technology:
Field strength and sample environment define capability boundaries, with helium sustainability forcing trade-offs between resolution and operational continuity.
- High-Field NMR:Systems exceeding 600 MHz proton frequency deliver irreplaceable resolution for protein structure determination and complex natural product elucidation. Solid-state DNP-NMR at 1.2 GHz is compressing sample requirements for membrane protein characterization at major United States and German research universities.
- Low-Field NMR:Permanent magnet designs below 100 MHz eliminate helium dependency and enable at-line process monitoring in pharmaceutical manufacturing. EU Green Deal carbon accounting mandates are accelerating European evaluation of cryogen-free alternatives for routine quality control.
- Solid-State NMR:Magic angle spinning techniques access insoluble biological assemblies and materials with atomic resolution.
- 2D NMR:Correlation spectroscopy methods resolve complex molecular connectivities through multi-pulse sequences.
High-Field NMR retains revenue leadership. Low-Field NMR is climbing the fastest as manufacturing applications mature.
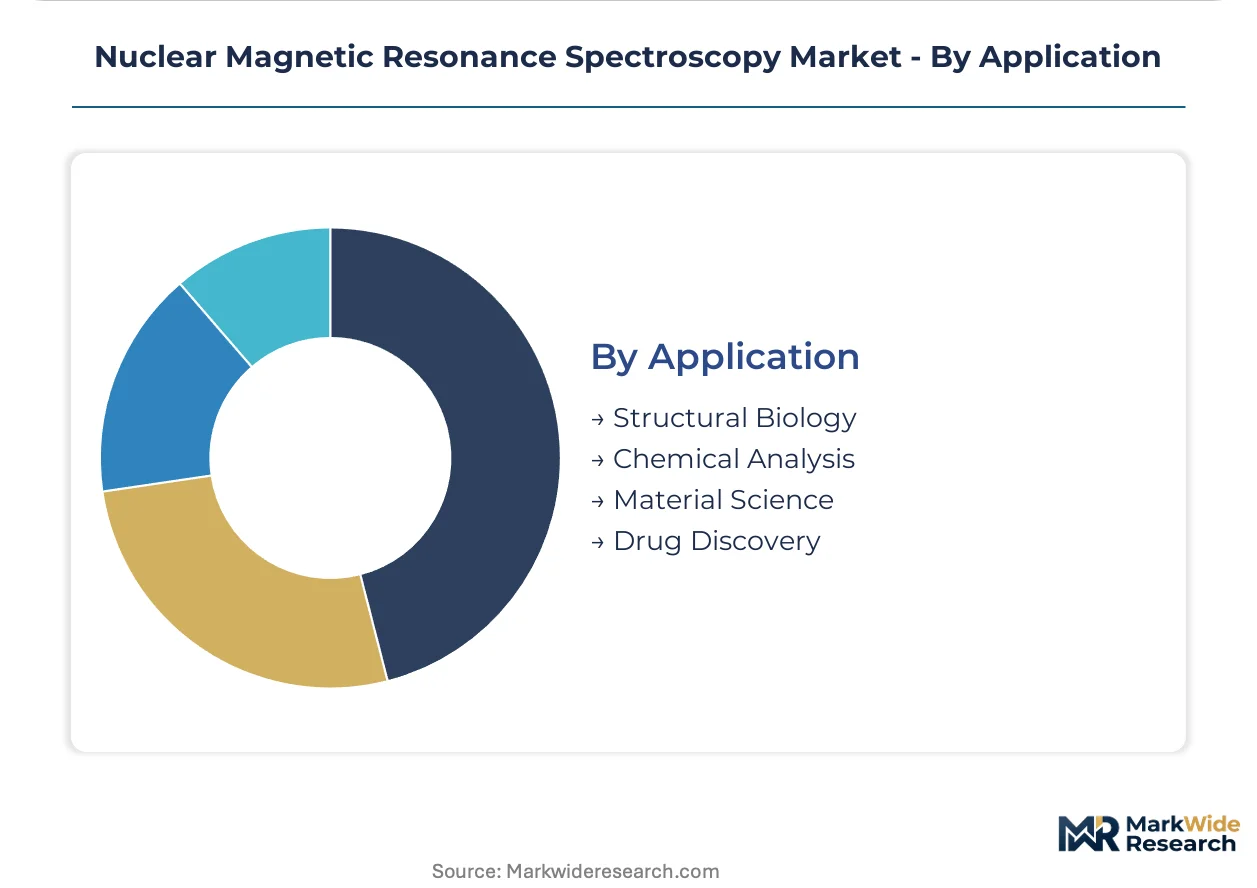
Application:
Use case specificity determines instrument configuration requirements, with structural biology demanding maximum field stability and chemical analysis prioritizing throughput.
- Structural Biology:Three-dimensional protein and nucleic acid structure determination represents the definitive application for high-field solution and solid-state NMR. Pharmaceutical R&D expansion into biologics and precision therapeutics intensifies demand for atomic-resolution characterization capabilities.
- Drug Discovery:Fragment-based screening, hit validation, and lead optimization workflows integrate NMR with complementary biophysical methods. Machine learning spectral interpretation tools are compressing analysis timeframes and expanding operator pools beyond specialist spectroscopists.
- Chemical Analysis:Synthetic compound verification and impurity profiling dominate routine quality control applications.
- Material Science:Polymer characterization, battery electrolyte analysis, and catalyst structure elucidation extend NMR into industrial R&D.
Structural Biology commands the largest dedicated installed base. Drug Discovery is gaining share fastest through biologics pipeline expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium extraction from the Hugoton natural gas field in Kansas anchors North American superconducting magnet supply chains, while niobium mining in Brazil and refined metallurgy in Germany shape magnet wire availability across procurement networks.
United States
NIH-funded structural biology consortia and FDA-regulated pharmaceutical quality control laboratories drive high-field system demand. The agency's 21 CFR Part 11 electronic records mandates filter vendor selection toward compliance-embedded platforms. Boston-Cambridge and San Diego biotech clusters maintain dense NMR infrastructure serving biologics characterization pipelines.
Germany
DFG grant cycles and Max Planck Institute instrumentation budgets sustain academic core facility renewal timelines. REACH and the EU F-Gas Regulation tighten helium containment documentation for superconducting magnet operations. Munich and Heidelberg research universities anchor DNP-NMR adoption for membrane protein structural biology.
Japan
JSPS funding and METI industrial technology programs support both academic high-field installations and manufacturing quality control deployment. PMDA alignment with ICH Q2(R1) validation standards shapes pharmaceutical laboratory procurement specifications. Osaka and Tsukuba science cities concentrate instrument density across public-private research partnerships.
India
CDSCO regulatory alignment with ICH standards and PLI scheme incentives create procurement windows for mid-field systems in contract manufacturing organizations. Academic research funding from DST and UGC supports core facility expansion at IISc Bangalore and IIT Bombay. Hyderabad and Ahmedabad pharmaceutical manufacturing corridors drive at-line quality control NMR adoption.
China
NMPA bioanalytical method validation requirements and MIIT advanced instrumentation programs accelerate domestic magnet technology development. Dual carbon goals under MEE oversight favor cryogen-free platform evaluation in capital expenditure decisions. Beijing and Shanghai academic-industrial clusters import high-field systems while cultivating local probe and software capabilities.
Nuclear Magnetic Resonance Spectroscopy Market Key Industry Players
Capacity expansion dominates the current landscape as instrument manufacturers diversify superconducting wire sourcing and magnet production footprints. The vendor base concentrates among integrated platform providers controlling magnet manufacturing, specialized probe designers, and modular software competitors. Three archetypes define positioning: vertically integrated magnet producers, application-specific probe specialists, and workflow-integrating analytical conglomerates. Geographic expansion into Indian biopharma corridors and technology licensing for cryogen-free architectures represent the dominant competitive vectors.
Among integrated platform providers, Bruker Corporation exemplifies the magnet-manufacturing archetype through in-house superconducting coil production, while JEOL Ltd. occupies a position as a specialized probe designer for solid-state applications. Thermo Fisher Scientific represents the workflow-integrating conglomerate archetype, anchoring software connectivity with broader analytical instrumentation suites. These three companies collectively illustrate the strategic tension between captive magnet supply, application-specific hardware differentiation, and cross-platform software ecosystems that defines vendor positioning.
| Leading Market Players |
|---|
| Bruker Corporation |
| JEOL Ltd. |
| Thermo Fisher Scientific Inc. |
| Oxford Instruments plc |
| Nanalysis Scientific Corp. |
| Magritek |
| Anasazi Instruments, Inc. |
| QOneTec |
| Advanced Magnetic Resonance Limited |
| Others |
Cost & Logistics Intelligence
Family-owned magnet engineering specialists in Germany and Japan anchor superconducting coil production, translating concentrated technical expertise into pricing discipline across high-field instrument tiers while procurement offices weigh helium sustainability against capital outlay commitments.
Pricing Analysis
Warranty and service contract bundling separates premium spectrometer offerings from unbundled alternatives in the mid-field segment. Three-tier pricing structure across premium, standard, and economy levels reflects field strength differentials and embedded compliance architecture for FDA 21 CFR Part 11 validation. Cost compression in economy-tier benchtop systems is intensifying because permanent magnet designs eliminate cryogen dependency. Academic core facilities show highest price sensitivity due to grant funding cycles, while pharmaceutical quality control laboratories prioritize compliance over unit cost.
Supply Chain Analysis
Niobium-titanium superconducting wire supply rests on specialty metallurgy producers in Germany, Japan, and the United States, with refined niobium feedstock drawing from Brazilian mining operations. High-purity helium for magnet cooling sources from the Hugoton field in Kansas and Algerian gas processing facilities. Single-source vulnerability concentrates in cryostat assembly expertise among retiring engineering cohorts in Munich and Oxford. Distribution runs through direct manufacturer sales for high-field systems and analytical instrument distributors for benchtop configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryogen-free permanent magnet architectures are displacing helium-cooled superconducting platforms in routine quality control applications, compressing the addressable market for legacy high-field systems in pharmaceutical manufacturing.
For Market Incumbents: Acquire specialized solid-state probe design capabilities to defend against application-specific competitors like JEOL Ltd. Consolidate magnet engineering talent through targeted recruitment in Germany and Japan where retiring cohorts threaten production scaling. Deepen backward integration into niobium-titanium wire drawing to reduce lead time exposure from specialty metallurgy suppliers. For New Entrants and Emerging Players: The price-point gap between premium 1.2 GHz systems and economy benchtop units opens white-space targeting of mid-field 400-600 MHz quality control spectrometers for Indian contract manufacturing organizations. CDSCO regulatory alignment with ICH standards creates procurement windows for compliance-embedded platforms. A software-first go-to-market angle leveraging AI-assisted spectral interpretation bypasses capital-intensive magnet manufacturing barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor cryogen-free technology licensors in European markets where EU Green Deal carbon accounting mandates accelerate platform transitions. Long-term viability centers on recurring revenue streams from software licensing and probe refurbishment with shorter replacement cycles than magnet platforms. The signal to watch is helium supply contract renegotiations at major academic core facilities as inflection indicator for cryogen-free adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogen-Free Magnet Development | Eliminates helium dependency for EU Green Deal compliance in pharmaceutical QC laboratories. |
| AI-Assisted Spectral Interpretation | Expands operator pools beyond specialist spectroscopists at biotechnology firms and CROs. |
| Probe Design Specialization | Differentiates capabilities for solid-state DNP-NMR applications in membrane protein research. |
| Regulatory Compliance Embedding | Secures FDA 21 CFR Part 11 qualification requirements in regulated pharmaceutical environments. |
| Service Contract Unbundling | Captures mid-sized CRO and academic core facility demand for à la carte maintenance coverage. |
Research Approach
Multi-period observation of NIH grant award patterns, CDSCO regulatory filing trajectories, and helium spot pricing anchored the trend analysis, supplemented by interviews with spectrometer procurement officers at pharmaceutical quality control laboratories, academic core facility directors, superconducting magnet engineers, and NMR software product managers. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA ICH Q2(R1) validation guidelines, EU F-Gas Regulation implementation reports, and SEC filings from listed instrument manufacturers. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, technology, and application dimensions.
Segment-weighting approaches applied differential growth assumptions to high-field versus low-field technology categories, with structural biology and drug discovery applications modeled separately from chemical analysis and quality control use cases. CAGRs were derived from instrument shipment volumes, replacement cycle analysis, and grant funding trajectories across the projection horizon. Industry-specific forecast inputs incorporated DNP-NMR adoption rates at major research universities and cryogen-free platform evaluation timelines in European capital expenditure decisions.
Inputs from primary stakeholder interviews and regulatory guidance documents were available through the study window; gaps in real-time helium supply contract terms and proprietary magnet production cost structures introduce uncertainty bands around high-field system demand forecasts. Forecasts reflect documented assumptions regarding CDSCO regulatory alignment pace and EU carbon accounting enforcement stringency. A small set of named triggers—including helium supply disruptions, superconducting wire tariff implementations, and AI-NMR convergence milestones—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
AI in Diagnostic Imaging Market
Medical Imaging
US Diagnostic Imaging Services Market
Medical Imaging
Brazil Digital Radiology Market
Medical Imaging
Europe Medical Imaging Market
Medical Imaging
China VNA and PACS Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market
Medical Imaging
Vascular Imaging Systems Market
Medical Imaging
Global Mobile Medical Imaging Services Market
Medical Imaging
India Nuclear Imaging Market
Medical Imaging
Mobile Vascular Imaging Market
Medical Imaging
Global Artificial Intelligence in Ultrasound Imaging Market
Medical Imaging
Global Vendor-Neutral Archive (VNA) and PACS Market
Medical Imaging
Global Medical Cameras Market
Medical Imaging
Italy Digital Radiology Market
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
AI Radiology Worklist Orchestration Market