
 Bone Fixation Plates Market | 2026-2036
Bone Fixation Plates Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Fixation Plates Market Analysis
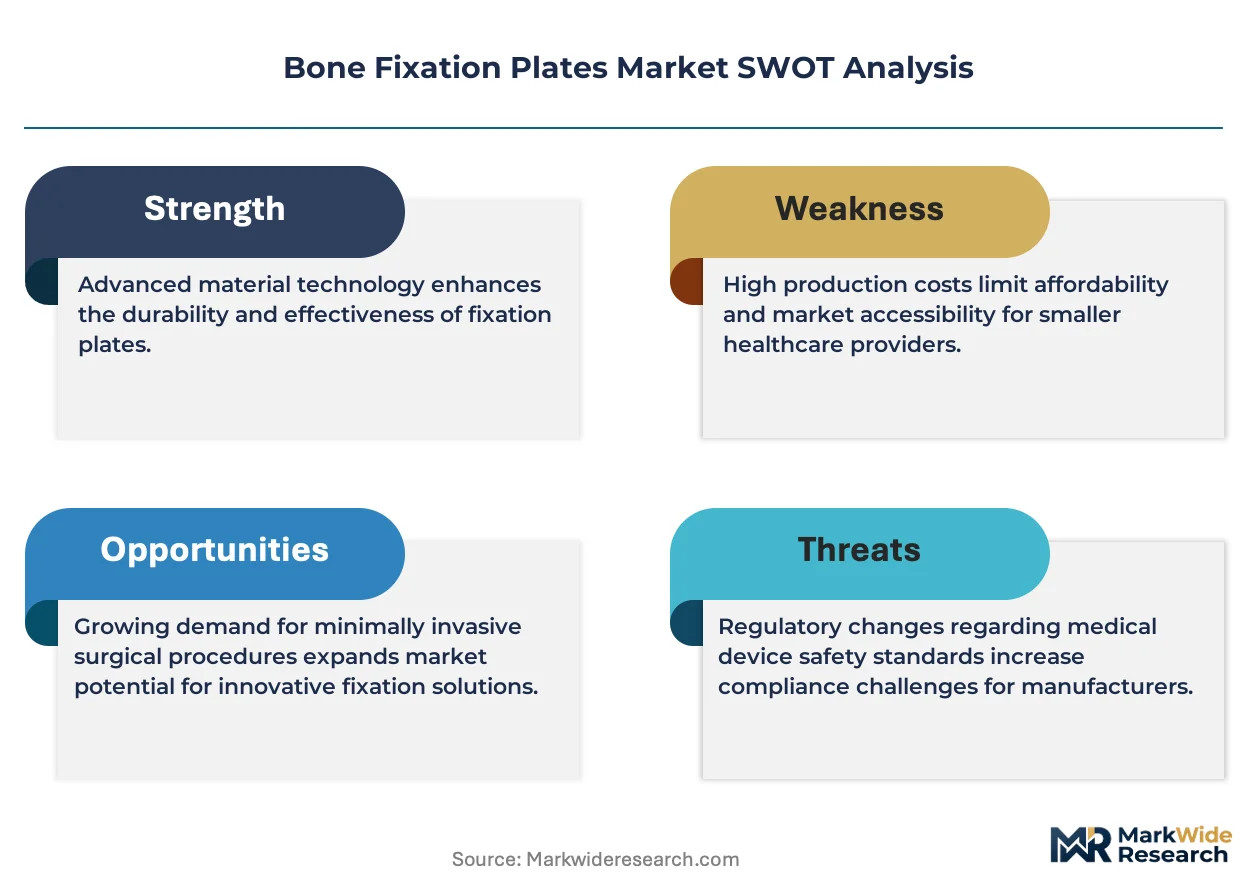
Hospital procurement is rewriting distribution economics for bone fixation plates. Medtronic plc leverages direct-to-facility contracts to sustain volume commitments across integrated delivery networks. Stryker Corporation anchors its position through specialized trauma sales forces that control surgeon training and instrumentation lock-in. Johnson & Johnson (DePuy Synthes) differentiates by navigating dual-brand strategies across premium titanium and value-tier stainless steel portfolios.
Bone fixation plates are rigid metallic or polymer implants manufactured from titanium alloys, stainless steel, or bio-absorbable polymers such as poly-L-lactic acid, designed to stabilize fractured bone segments through screw fixation and load-sharing mechanics until osseous union occurs. Locking plates command the largest revenue share due to angular stability advantages in osteoporotic fractures, while bio-absorbable polymers represent the fastest-expanding material category as surgeons seek to eliminate secondary removal procedures. Orthopedic surgery applications generate the deepest margin pools, though sports medicine is gaining traction among ambulatory surgical centers pursuing outpatient fracture management.
FDA 510(k) premarket notification requirements govern implant biocompatibility and mechanical testing standards, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence demands for CE marking renewal. ISO 5832 specifications for metallic implant materials shape global manufacturing benchmarks, with ASTM F138 and F136 titanium grades serving as default procurement references. Stakeholders must monitor evolving MDR notified body capacity constraints and FDA breakthrough device designations that could accelerate competitive entry timelines for novel plate geometries.
Market Dynamics
Surgeon training standardization and instrumentation lock-in are consolidating purchasing power around integrated delivery networks, compressing vendor margins while elevating compliance burdens for mid-tier manufacturers seeking trauma center access.
Growth Catalysts
- Aging demographics in the United States:Osteoporotic fracture volumes are expanding procedural indications for locking plate systems in Medicare populations.
- FDA 510(k) pathway streamlining:Expedited clearances for predicate-based designs are accelerating product refresh cycles and reducing time-to-revenue for established manufacturers.
- Locking compression mechanics:Angular stability advantages in metaphyseal fractures are displacing conventional plating in high-volume orthopedic departments.
Market Restraints
- Titanium alloy price volatility:Aerospace demand fluctuations and sponge supply concentration in Russia and China are compressing gross margins on premium implant grades.
- EU MDR notified body capacity:Stricter clinical evidence requirements and auditor shortages are extending CE marking timelines by 12-18 months for legacy product renewals.
- Bio-absorbable polymer degradation unpredictability:Variable resorption rates in poly-L-lactic acid constructs are limiting adoption in load-bearing long-bone applications.
Strategic Opportunities
- Ambulatory surgical center expansion:Outpatient fracture management protocols are creating dedicated instrumentation and disposable kit demand outside hospital settings.
- India's CDSCO harmonization:Alignment with ISO 5832 standards is reducing import registration friction for multinational trauma portfolios.
- Patient-specific 3D-printed plate geometries:CT-to-implant workflows are enabling anatomic customization in complex pelvic and mandibular reconstructions.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies are creating bottlenecks at contract research organizations, delaying 510(k) submissions.
- Surgeon retraining requirements:Locking plate biomechanics demand proficiency in indirect reduction techniques that conventional plating curricula do not address.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Fixation Plates Market |
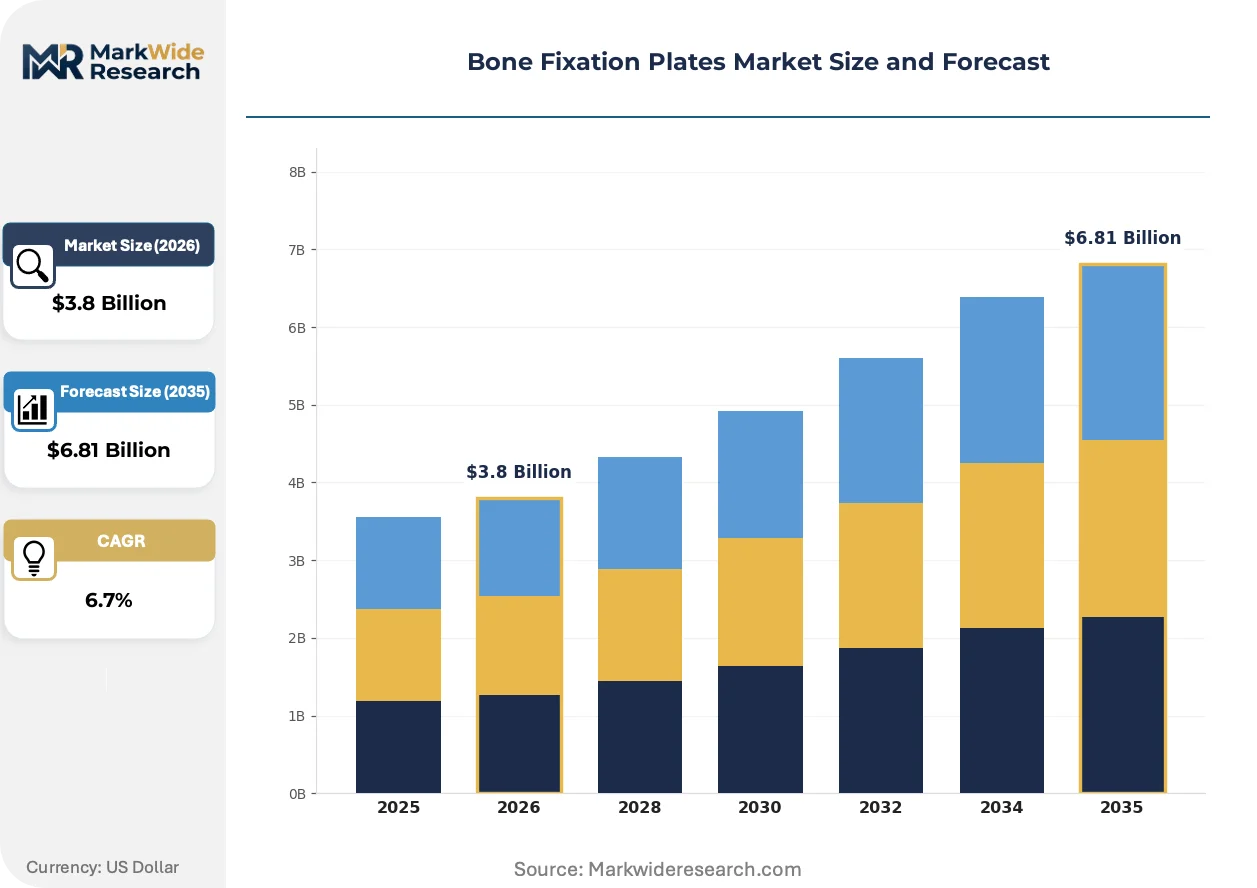
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression Plates, Locking Plates, Reconstruction Plates, Dynamic Compression Plates Material: Titanium, Stainless Steel, Bio-absorbable Polymers, Coated Alloys Application: Orthopedic Surgery, Trauma Surgery, Spinal Surgery, Sports Medicine End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Surgical Centers |
| Companies Covered | Medtronic plc, Arthrex Inc., Johnson & Johnson (DePuy Synthes), Orthofix Medical, Evonik Corporation, Stryker Corporation, Smith & Nephew plc, Bioretec, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Fixation Plates Market Emerging Trajectories
Digital preoperative planning and additive manufacturing are converging to collapse the design-to-implant timeline, while regulatory data requirements are forcing manufacturers to rebuild clinical evidence libraries from legacy predicate foundations.
Polyetheretherketone-carbon fiber composites are hybridizing radiolucency with mechanical stiffness for tumor reconstruction and spine applications. Academic medical centers in Germany and Japan are piloting these constructs for pelvic sarcoma cases where metal artifact obscures postoperative imaging. The technology is hybridizing material selection criteria across trauma and oncology divisions previously segmented by implant metallurgy.
EU MDR Article 120 transition deadlines are forcing systematic clinical evidence regeneration for CE-marked devices predating 2017. Manufacturers must compile post-market surveillance data and PMCF study protocols that legacy technical files never required. Trauma plate portfolios with decade-old predicates face the steepest compliance cliffs, driving portfolio rationalization ahead of 2027-2028 certificate expirations.
Surgeon preference for single-use sterile kits is displacing traditional loaner tray logistics in high-volume fracture clinics. Ambulatory surgery centers in Florida and Texas are negotiating all-inclusive case rates that bundle plate, screw, and disposable instrumentation costs. This consumption pattern compression is visible most acutely in sports medicine practices where case volume predictability supports inventory-light procurement models.
Bone Fixation Plates Market Segmentation
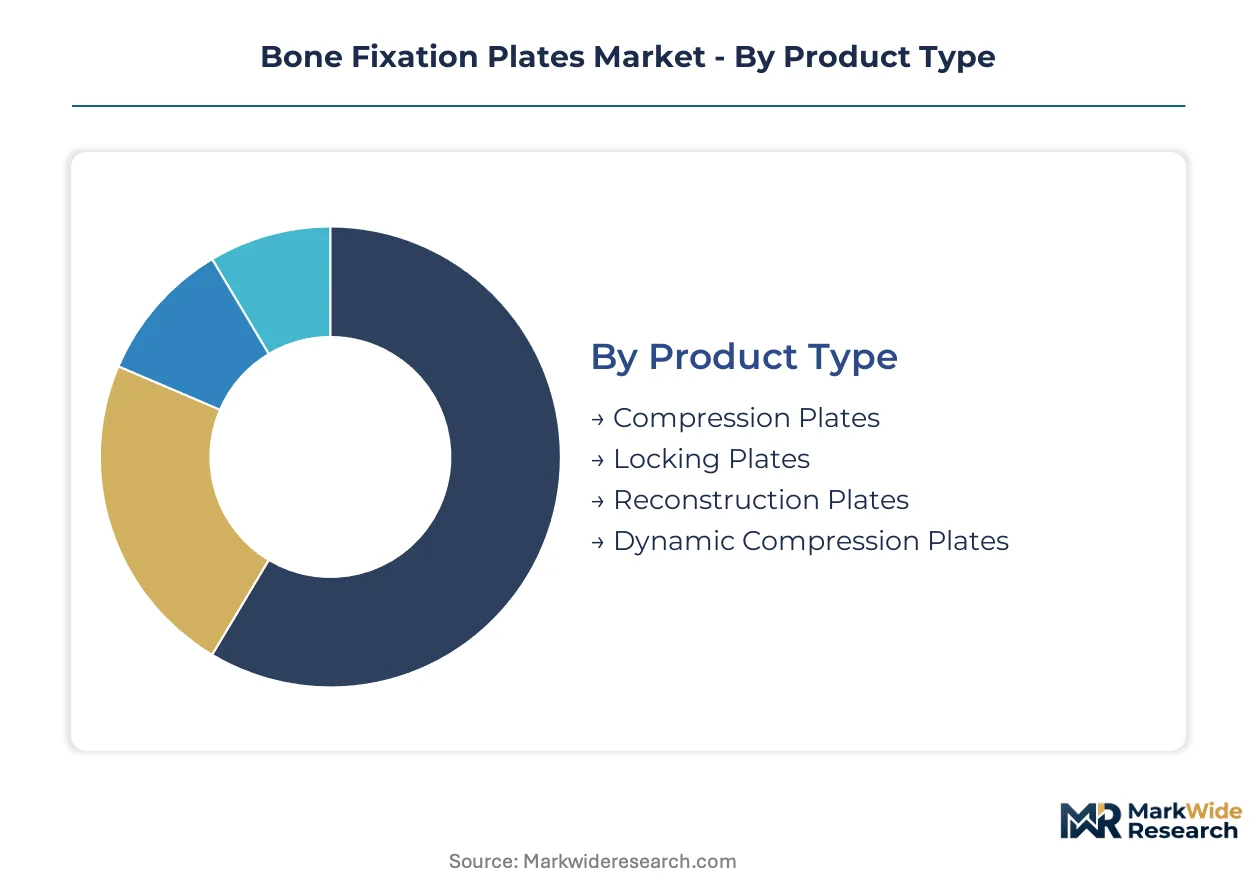
Segmentation in bone fixation plates reveals how procurement cycles, reimbursement pathways, and surgical training requirements fragment demand across product categories. Manufacturers must align inventory velocity with the procedural turnover rates of each segment to optimize working capital deployment.
Product Type:
Compression plates turn over fastest in high-volume trauma settings, while reconstruction plates linger longest in specialized oncology and revision inventories.
- Compression Plates:Conventional dynamic compression designs apply axial force across fracture gaps through eccentric screw loading in cortical bone. Demand concentrates in United States community hospitals where Medicare reimbursement for basic trauma procedures sustains high utilization rates despite titanium price pressure.
- Locking Plates:Fixed-angle constructs provide angular stability in osteoporotic metaphyseal fractures through threaded screw-plate interfaces that eliminate friction-dependent compression. United States tertiary trauma centers are expanding inventories as aging demographics expand indications for proximal humerus and distal femur fracture management.
- Reconstruction Plates:Contoured designs with multiple screw holes accommodate complex pelvic and mandibular reconstructions in academic medical centers.
- Dynamic Compression Plates:Hybrid mechanics combine compression and locking capabilities for transitional fracture patterns in mid-tier orthopedic departments.
Locking plates dominate installed base across United States trauma networks. Compression plates are where expansion concentrates as cost-containment pressures reshape procurement specifications.
Material:
Cost tiers separate premium titanium from value-engineered alternatives, with bio-absorbable polymers occupying a speculative premium position pending clinical validation.
- Titanium:Ti-6Al-4V ELI and commercially pure grades deliver strength-to-weight ratios and osseointegration properties essential for load-bearing long-bone applications. United States integrated delivery networks specify ASTM F136 titanium for high-volume trauma contracts despite aerospace demand volatility compressing supplier margins.
- Stainless Steel:316L and 22Cr-13Ni-5Mn compositions offer cost advantages in temporary fixation and pediatric applications where implant removal is planned. Demand clusters in Indian and Chinese public hospital systems where CDSCO and NMPA procurement tenders prioritize unit cost over lifecycle performance.
- Bio-absorbable Polymers:Poly-L-lactic acid and polyglycolic acid constructs eliminate secondary removal procedures in facial and pediatric applications.
- Coated Alloys:Hydroxyapatite and antibiotic-eluting surfaces target infection-prime fracture environments in combat trauma and open fracture protocols.
Titanium anchors revenue concentration in premium trauma segments. Bio-absorbable polymers are gaining share fastest as surgeons seek to eliminate hardware removal costs in Medicare Advantage populations.
Application:
Volume concentration in orthopedic surgery contrasts with margin depth in spinal applications, where instrumentation bundling sustains pricing power.
- Orthopedic Surgery:Extremity fracture management, arthrodesis, and deformity correction generate the deepest procedural volumes across general hospital operating rooms. United States ambulatory surgery centers are expanding plate inventories as outpatient fracture protocols gain payer approval in Florida and Texas markets.
- Trauma Surgery:Acute fracture stabilization in emergency departments demands rapid implant availability and sterilization turnaround. Level I trauma centers in United States urban corridors maintain consignment inventories that compress vendor margins while elevating compliance burdens.
- Spinal Surgery:Anterior cervical and thoracolumbar constructs command premium pricing through screw-rod system bundling.
- Sports Medicine:Arthroscopic-assisted fixation of tibial eminence and patellar fractures drives disposable kit demand in outpatient settings.
Orthopedic surgery commands procedural volume leadership. Sports medicine represents the steepest expansion trajectory as ambulatory migration accelerates.
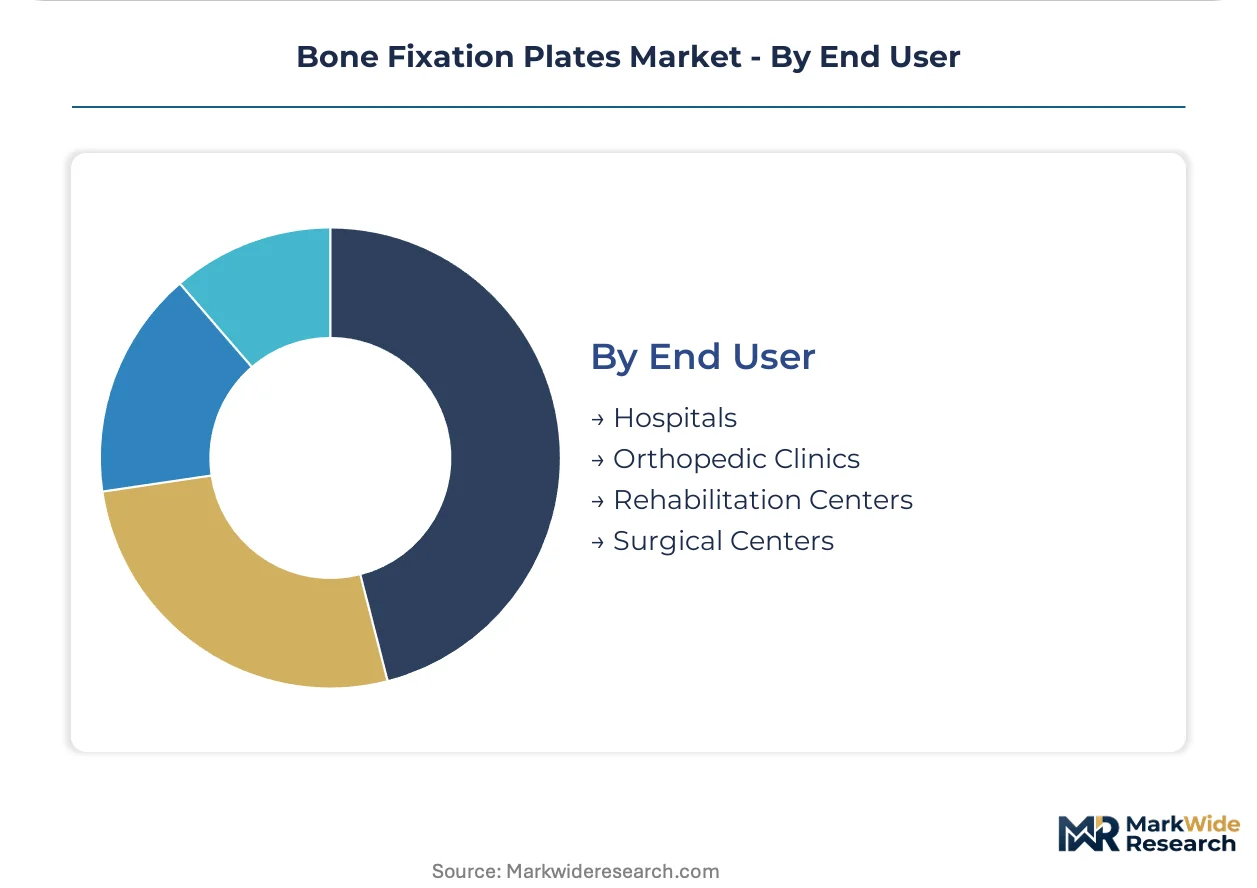
End User:
Customer type determines procurement complexity, with hospitals demanding full tray logistics and surgical centers pursuing inventory-light disposable models.
- Hospitals:Integrated delivery networks negotiate enterprise contracts covering trauma, oncology, and revision inventories across multiple facilities. United States hospital procurement committees are consolidating vendor lists around manufacturers with 510(k) predicate depth and dedicated sales force coverage.
- Orthopedic Clinics:Private practice groups specializing in sports medicine and hand surgery purchase procedure-specific mini-fragment sets. Concentration in United States metropolitan corridors with high commercial insurance penetration supports premium titanium specification.
- Rehabilitation Centers:Post-acute facilities require hardware for periprosthetic fracture management and conversion arthroplasty preparation.
- Surgical Centers:Ambulatory sites negotiate all-inclusive case rates bundling implant and disposable instrumentation costs.
Hospitals dominate purchasing volume through enterprise contract structures. Surgical centers concentrate expansion opportunity as outpatient fracture protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics hub underwrites European distribution efficiency for trauma implant manufacturers serving continental hospital networks.
United States
Tertiary trauma centers in Houston and Baltimore are expanding locking plate inventories as Medicare Advantage populations drive outpatient fracture volumes. FDA 510(k) pathway streamlining accelerates predicate-based clearances for titanium constructs. The Texas Medical Center cluster anchors surgeon training programs that standardize instrumentation protocols across Gulf Coast integrated delivery networks.
Germany
Academic medical centers in Munich and Heidelberg are piloting patient-specific 3D-printed plates for complex pelvic reconstructions. EU MDR Article 120 transition deadlines force systematic clinical evidence regeneration for legacy CE-marked trauma portfolios. The Baden-Württemberg medical technology corridor concentrates additive manufacturing competencies serving oncology and revision surgery applications.
China
Public hospital procurement tenders under NMPA oversight prioritize unit cost in stainless steel plate categories for high-volume trauma departments. Aerospace demand fluctuations compress titanium sponge availability from Russian and Chinese supplier concentration. The Yangtze River Delta manufacturing cluster around Shanghai anchors domestic production scale for value-tier implant grades.
India
CDSCO harmonization with ISO 5832 standards reduces import registration friction for multinational trauma portfolios entering tertiary hospital supply chains. Government medical college hospitals in Delhi and Mumbai are expanding orthopedic surgery departments as procedural volumes rise. The Maharashtra pharmaceutical and medical device corridor concentrates contract manufacturing capabilities serving domestic and export markets.
Japan
PMDA regulatory frameworks govern biocompatibility testing standards for metallic implant materials in aging demographic populations. Academic medical centers in Tokyo and Osaka are advancing polyetheretherketone-carbon fiber composite constructs for tumor reconstruction applications. The Kanto region's precision manufacturing base supports high-tolerance titanium machining for premium trauma segments.
Bone Fixation Plates Market Vendor Landscape
On the supply side, the industry is consolidating around integrated delivery network contracts that compress vendor margins while elevating compliance burdens for mid-tier manufacturers. Tiered competitive positioning separates premium titanium specialists from value-engineered stainless steel fabricators and emerging bio-absorbable polymer developers. Strategic archetypes include full-line trauma conglomerates, materials science innovators, and ambulatory-focused disposable kit suppliers. Dominant competitive moves center on direct-to-facility contracting and surgeon training program control.
Among diversified medical technology conglomerates, Medtronic plc and Stryker Corporation exemplify the integrated delivery network contracting archetype through direct-to-facility volume commitments and specialized trauma sales force deployment. Johnson & Johnson (DePuy Synthes) occupies a position bridging premium titanium and value-tier stainless steel portfolio strategies. These three anchors represent contrasting approaches to navigating FDA 510(k) predicate depth requirements and EU MDR clinical evidence regeneration demands.
| Leading Market Players |
|---|
| Medtronic plc |
| Arthrex Inc. |
| Johnson & Johnson (DePuy Synthes) |
| Orthofix Medical |
| Evonik Corporation |
| Stryker Corporation |
| Smith & Nephew plc |
| Bioretec |
| Zimmer Biomet |
| Others |
Supply Flow & Price Mechanics
The Port of Rotterdam's medical device logistics hub channels titanium alloy shipments from Russian and Chinese sponge suppliers into European trauma implant manufacturing, with freight cost volatility amplifying price spreads between ASTM F136 premium grades and 316L stainless steel alternatives across integrated delivery network contracts.
Pricing Analysis
Three-tier pricing structure across premium titanium, standard stainless steel, and economy bio-absorbable levels governs hospital procurement committees, with ASTM F136 certification and dedicated trauma sales force coverage commanding 15-20% brand premiums over value-tier alternatives. Aerospace demand fluctuations compress margins on Ti-6Al-4V ELI grades while Medicare Advantage populations drive price sensitivity in outpatient fracture segments. Ambulatory surgery centers in Florida and Texas exhibit highest price elasticity through all-inclusive case rate negotiations.
Supply Chain Analysis
Export-control scrutiny on aerospace-grade titanium sponge from Russian suppliers and Chinese state-owned enterprises constrains raw material flows into European and North American forging facilities, forcing manufacturers to diversify procurement toward Japanese and Saudi Arabian feedstock sources. Ti-6Al-4V ELI billet, poly-L-lactic acid resin, and hydroxyapatite coating precursors constitute critical input dependencies. Single-source vulnerability in Russian sponge concentration threatens supply continuity. Distribution runs through consignment inventory models at Level I trauma centers and direct-to-facility contracts across integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as ambulatory surgical center expansion and patient-specific 3D-printed plate demand create specialized niches outside incumbent trauma conglomerate control.
For Market Incumbents: Pre-empt mid-tier manufacturer encroachment by locking instrument tray standardization across Medicare Advantage networks and accelerating EU MDR Article 120 clinical evidence regeneration ahead of certificate expirations. Backward integration into titanium sponge sourcing mitigates aerospace demand volatility. For New Entrants and Emerging Players: Pursue disposable sterile kit supply to Texas and Florida ambulatory surgery centers where all-inclusive case rate bundling displaces traditional loaner tray logistics. India's CDSCO harmonization with ISO 5832 standards offers lowest import registration friction for multinational portfolio entry. For Investors and Strategic Acquirers: Additive manufacturing specialists with CT-to-implant workflows and pelvic reconstruction case volumes represent priority acquisition targets in the 5-10 year orthopedic consolidation window. Monitor FDA breakthrough device designation velocity as inflection signal for novel plate geometry competitive entry.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Predicate-based clearances compress time-to-revenue for titanium construct refreshes in trauma portfolios. |
| CE Marking Pathway Investment | EU MDR notified body capacity constraints demand early PMCF study protocol submission for legacy plate renewals. |
| Hospital System Partnership | Direct-to-facility contracts with integrated delivery networks secure volume commitments and instrumentation lock-in. |
| Software Companion Development | Digital preoperative planning platforms differentiate locking plate systems in academic medical center competitions. |
| Reimbursement Strategy | Medicare Advantage outpatient fracture protocol approval drives ambulatory surgical center inventory expansion. |
Methodological Framework
Cross-validation between orthopedic surgeon interviews and hospital procurement database analysis anchors the qualitative findings, with trauma department heads, biomedical engineers, GPO contracts managers, and regulatory affairs leads at multinational manufacturers providing primary insight. Secondary sources include FDA 510(k) premarket notification filings, EU MDR notified body certificates, hospital consignment inventory records, and CMS Medicare reimbursement schedules. Bottom-up procedure volume modeling triangulates against top-down titanium alloy consumption estimates from aerospace and medical grade suppliers.
Calibration against historical trauma procedure growth patterns and titanium price elasticity coefficients shapes the analytical framework across product type, material grade, application specialty, and end-user facility tier dimensions. CAGRs derive from segmented demand elasticity modeling and surgeon adoption curve analysis for locking plate mechanics. Inputs include osteoporotic fracture incidence projections, ambulatory surgery center certification expansion rates, and EU MDR transition timeline compliance costs.
Sensitivities concentrate around FDA 510(k) clearance velocity, EU MDR notified body audit capacity, and titanium sponge supply disruption scenarios. Forecasts reflect assumptions on surgeon training standardization adoption and Medicare outpatient fracture reimbursement expansion. Material shifts in aerospace demand competition for ELI-grade titanium or breakthrough device designation acceleration for patient-specific implants would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Ambulatory Infusion Pumps Market
Medical Devices
Arthroscopy Procedures and Products Market
Medical Devices
Expandable Interbody Fusion System Market
Medical Devices
Thoracic Surgery Devices Market
Medical Devices
North America Ultrasound Devices Market
Medical Devices
Depression Devices Market
Medical Devices
Below-The-Knee Implants Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
Light Therapy Market
Medical Devices
Computer Aided Trauma Fixators Market
Medical Devices
Hair Removal Devices Market
Medical Devices
Soft Contact Lenses Market
Medical Devices
Hearing Aids Market
Medical Devices
Disposable Needle Guides Market
Medical Devices
Prefilled Syringe Small Molecule Market
Medical Devices
Spain Artificial Organs and Bionic Implants Market