
 Ligament Augmentation Market | 2026-2036
Ligament Augmentation Market Size, Share, and Industry Trends Forecast 2026-2036
Ligament Augmentation Market Foresight
Shortage of fellowship-trained sports medicine surgeons is collapsing access to advanced ligament procedures in underserved metropolitan areas. Arthrex Inc. leverages its proprietary suture anchor platforms to dominate outpatient sports medicine settings. Stryker Corporation sustains R&D intensity across bioresorbable interference screw portfolios. Zimmer Biomet Holdings anchors geographic presence through specialized distributor networks in key orthopedic clusters.
Ligament augmentation encompasses surgical interventions that reinforce or replace damaged native ligaments using synthetic materials, allografts, autografts, or biologic scaffolds, typically requiring tensile strength exceeding 2000 Newtons to restore joint kinematics. The primary purpose centers on restoring mechanical stability to knee, shoulder, and ankle joints while enabling biological incorporation of graft tissue. Biologics represent the fastest-expanding product category as platelet-rich plasma and stem cell concentrates command premium positioning. Arthroscopy technology leads procedural volume due to reduced morbidity and accelerated rehabilitation protocols. Sports medicine facilities emerge as the highest-margin end-user segment through bundled procedure pricing and direct-to-patient marketing.
FDA 510(k) clearance requirements shape graft material biocompatibility standards while ISO 13485 certification mandates govern quality management across device manufacturers. The EU MDR transition imposes strengthened clinical evidence requirements on suture-based augmentation devices entering European markets. Stakeholders must monitor evolving CMS reimbursement determinations for biologic adjuncts as coverage decisions will reshape site-of-service economics.
Market Dynamics
Arthroscopic technique maturation is compressing inpatient stays and forcing facility-level capital redeployment toward ambulatory surgery centers. This procedural shift reconfigures surgeon training pipelines, graft procurement logistics, and payer reimbursement frameworks simultaneously.
Growth Catalysts
- FDA 510(k) Streamlining:Expedited clearance pathways for biologic scaffolds accelerate product-to-market timelines. Device manufacturers leverage predicate device strategies to reduce clinical trial burdens.
- Sports Medicine Facility Expansion:Dedicated orthopedic ambulatory centers in the United States deploy bundled pricing models. These facilities capture high-margin outpatient procedures previously concentrated in hospital settings.
- Platelet-Rich Plasma Adjuncts:Biologic concentrates command premium reimbursement when paired with mechanical grafts. Orthopedic surgeons integrate PRP protocols to differentiate service offerings.
Market Restraints
- Allograft Supply Volatility:Tissue bank consolidation in the United States creates single-source dependencies. Harvesting seasonality and donor screening failures interrupt graft availability.
- EU MDR Compliance Burden:Strengthened clinical evidence requirements for suture-based devices extend European market entry timelines. Notified body capacity constraints compound certification delays.
- Autograft Substitution:Hamstring and patellar tendon harvesting remains cost-competitive for younger patients. Synthetic grafts face resistance in high-activity demographic segments.
Strategic Opportunities
- Stem Cell Concentrate Integration:Mesenchymal stem cell therapies converge with bioresorbable scaffolds. Early-stage protocols target revision surgery populations with compromised healing capacity.
- India Orthopedic Infrastructure:Underpenetrated arthroscopy adoption in tier-2 Indian cities creates first-mover positioning. Local distributor partnerships reduce import tariff exposure.
- CMS Biologic Adjunct Coverage:Pending reimbursement determinations for PRP and cellular therapies reshape site-of-service economics. Favorable rulings would accelerate ambulatory migration.
Industry Challenges
- Fellowship Training Bottlenecks:Sports medicine surgeon shortages in underserved US metropolitan areas collapse access to advanced procedures. Academic medical centers control credentialing pipeline velocity.
- ISO 13485 Audit Complexity:Quality management recertification for multi-site manufacturers demands sustained documentation investment. Non-conformance findings trigger supply interruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ligament Augmentation Market |
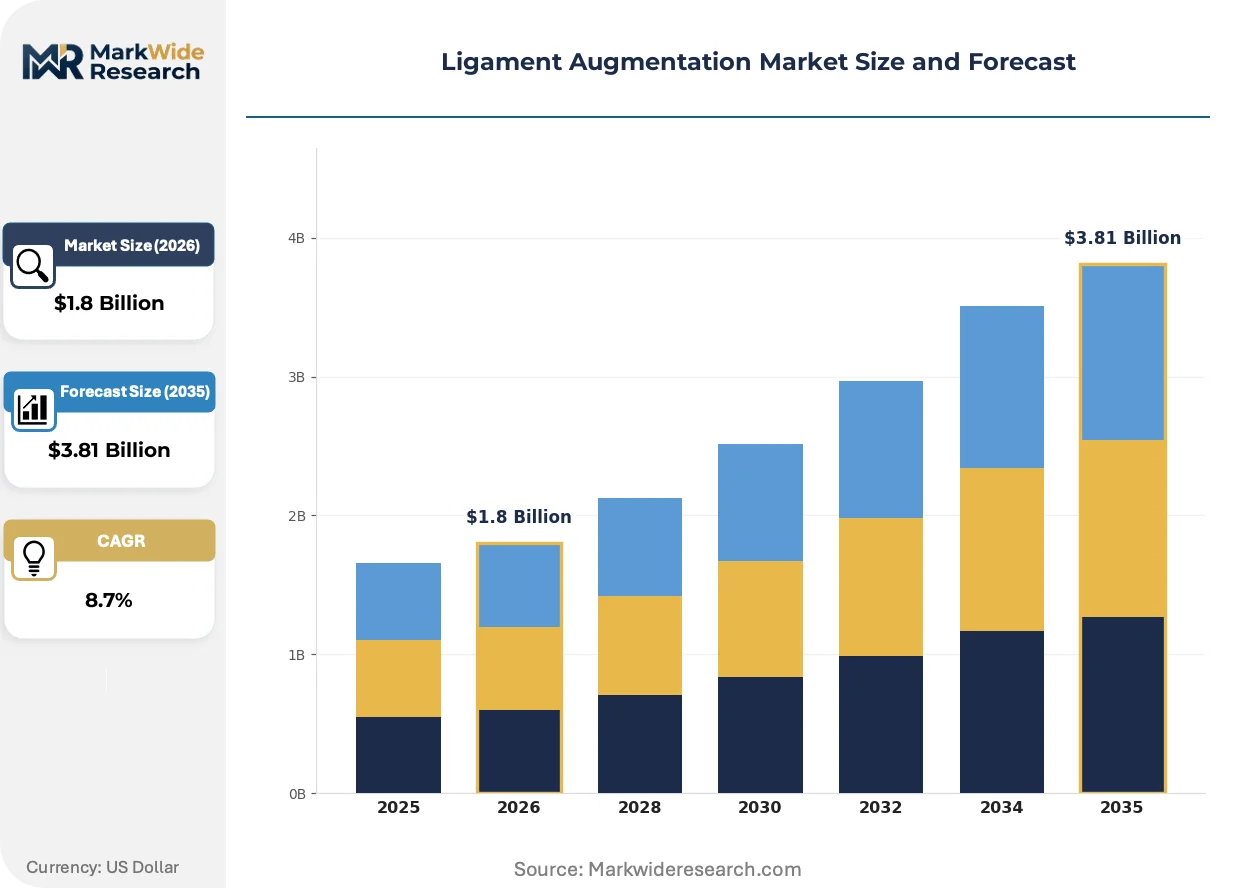
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sutures, Grafts, Biologics, Devices End User: Orthopedic Clinics, Hospitals, Rehabilitation Centers, Sports Medicine Facilities Technology: Open Surgery, Arthroscopy, Minimally Invasive, Hybrid Techniques Application: Injury Repair, Reconstruction, Stabilization, Enhancement |
| Companies Covered | Arthrex Inc., Stryker Corporation, Zimmer Biomet Holdings, Smith & Nephew plc, Corin Group, DJO Global, RTI Surgical Holdings, Integra LifeSciences Corporation, Mathys AG Bettlach, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ligament Augmentation Market Shifts & Advancements
Biologic-mechanical hybrid grafts are compressing the boundary between synthetic scaffolds and autologous tissue. Material science advances enable tunable degradation profiles matched to ligament remodeling timelines.
Resorbable interference screws incorporating magnesium alloys are fragmenting fixation device categories. Sports medicine surgeons in Germany and the United States adopt these implants for ACL reconstruction at accelerating rates. The technology is fragmenting market share previously captured by permanent polymer and metal screw manufacturers.
EU MDR transition requirements are reshaping clinical evidence standards for suture anchor devices. European manufacturers face expanded post-market surveillance obligations and biocompatibility testing mandates. Smaller device firms are withdrawing legacy product lines rather than absorbing compliance costs.
Patient-directed facility selection is disrupting traditional referral networks in the United States. Direct-to-consumer marketing by ambulatory surgery centers captures cases previously routed through hospital systems. This channel shift concentrates in metropolitan markets with high insurance plan flexibility and transparent pricing platforms.
Ligament Augmentation Market Segmentation
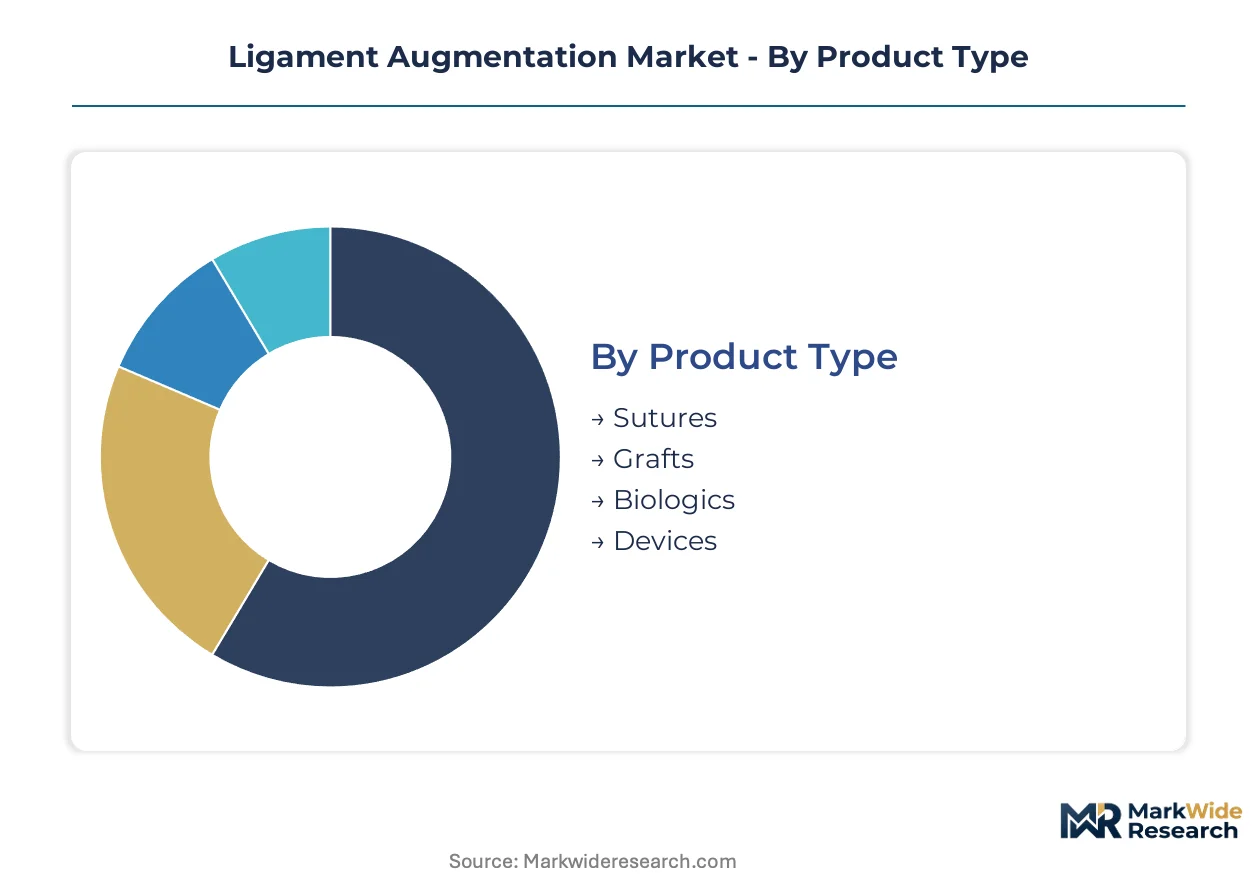
Segmentation in ligament augmentation reveals how margin pools concentrate in biologic-enhanced procedures and ambulatory settings. Product type and end-user configuration directly determine reimbursement rates and capital intensity requirements.
Product Type:
Margin pools concentrate in biologics and advanced fixation devices where premium pricing meets differentiated clinical outcomes.
- Biologics:Platelet-rich plasma and stem cell concentrates command premium positioning when paired with mechanical grafts. Sports medicine facilities in the United States drive demand concentration through direct-to-patient marketing and bundled procedure pricing.
- Grafts:Allografts and autografts provide structural scaffolding with tensile strength requirements exceeding 2000 Newtons. Supply volatility from tissue bank consolidation creates procurement challenges that reshape site-of-service economics.
- Sutures:High-tensile braided polymers anchor soft tissue to bone across arthroscopic procedures.
- Devices:Interference screws and suture anchors deliver mechanical fixation during ligament reconstruction.
Biologics holds installed capacity. Devices is rotating up the share rankings.
End User:
Volume concentration sits with hospital systems, though margin expansion accelerates in specialized ambulatory centers.
- Sports Medicine Facilities:Dedicated orthopedic ambulatory centers capture high-margin outpatient procedures through bundled pricing models. These facilities in metropolitan United States markets are compressing inpatient stays and forcing capital redeployment from hospital systems.
- Orthopedic Clinics:Community-based practices handle diagnostic workup and post-operative rehabilitation protocols. Patient-directed facility selection is disrupting traditional referral networks as transparent pricing platforms gain traction.
- Hospitals:Academic medical centers drive clinical protocol development and control credentialing pipeline velocity.
- Rehabilitation Centers:Post-surgical facilities manage return-to-activity protocols and physical therapy regimens.
Sports medicine facilities holds installed capacity. Orthopedic clinics is rotating up the share rankings.
Technology:
Cost tier stratification separates capital-intensive open procedures from scalable arthroscopic platforms.
- Arthroscopy:Camera-assisted joint access reduces morbidity and accelerates rehabilitation timelines. German and United States surgeons adopt resorbable magnesium alloy screws through arthroscopic portals at accelerating rates.
- Minimally Invasive:Smaller incisions with specialized instrumentation limit soft tissue disruption. The approach gains preference in revision surgeries where prior graft harvesting has compromised autograft availability.
- Open Surgery:Traditional arthrotomy remains necessary for complex multi-ligament injuries.
- Hybrid Techniques:Combined arthroscopic and mini-open approaches address anatomically challenging reconstructions.
Arthroscopy holds installed capacity. Minimally invasive is rotating up the share rankings.
Application:
Customer type segmentation tracks patient demographics from acute trauma through elective enhancement.
- Reconstruction:Complete ligament replacement using autograft, allograft, or synthetic scaffolds dominates procedural volume. Younger high-activity patients in the United States resist synthetic substitutes, preserving autograft demand.
- Injury Repair:Primary suture and augmentation of partial tears addresses acute traumatic disruptions. Demand concentrates in contact sports populations where ligamentous injuries occur at elevated rates.
- Stabilization:Secondary procedures reinforce compromised joint mechanics following failed primary repairs.
- Enhancement:Prophylactic augmentation targets athletes seeking mechanical advantage beyond native tissue capacity.
Reconstruction holds installed capacity. Injury repair is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the United States as the procedural volume leader, while EU MDR transition requirements reshape European market entry economics. Academic medical centers in specific metropolitan clusters drive clinical protocol development and surgeon training velocity.
United States
Sports medicine facilities in metropolitan markets deploy bundled pricing models that capture outpatient procedures previously concentrated in hospital settings. CMS reimbursement determinations for biologic adjuncts reshape site-of-service economics across ambulatory surgery centers. The Boston-Cambridge corridor and Stanford-Palo Alto corridor anchor clinical protocol development and fellowship training pipeline velocity.
Germany
Resorbable magnesium alloy interference screws gain preference among sports medicine surgeons performing ACL reconstruction through arthroscopic portals. EU MDR strengthened clinical evidence requirements extend certification timelines for suture-based augmentation devices. The Munich-Stuttgart orthopedic cluster concentrates R&D activity for bioresorbable fixation technologies.
United Kingdom
NHS England procurement frameworks prioritize cost-effective allograft solutions for ligament reconstruction procedures. The Medicines and Healthcare products Regulatory Agency enforces post-market surveillance obligations on biologic scaffold manufacturers. The London-Oxford-Cambridge golden triangle concentrates academic research into stem cell concentrate integration protocols.
India
Tier-2 cities present underpenetrated arthroscopy adoption opportunities for first-mover positioning in ligament augmentation. The Central Drugs Standard Control Organization governs import licensing requirements for orthopedic implants and biologic graft materials. The Mumbai-Pune corridor and Delhi-NCR cluster concentrate private hospital infrastructure expansion for sports medicine services.
Japan
The Pharmaceuticals and Medical Devices Agency mandates rigorous biocompatibility testing for synthetic ligament scaffolds entering domestic markets. Aging demographics expand demand for revision surgery populations with compromised healing capacity. The Tokyo-Osaka corridor anchors distributor networks for specialized orthopedic device importation.
Ligament Augmentation Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidation pressure intensifying around biologic-mechanical hybrid graft portfolios. The vendor base separates into three strategic archetypes: full-line orthopedic conglomerates with suture anchor platforms, tissue bank operators controlling allograft supply chains, and focused arthroscopy instrument specialists. Competitive moves concentrate on M&A activity targeting bioresorbable fixation technologies and strategic partnerships with academic medical centers for clinical evidence generation.
Within the integrated orthopedic tier, Arthrex Inc. and Stryker Corporation occupy positions exemplifying divergent platform strategies. Arthrex anchors outpatient sports medicine settings through proprietary suture anchor ecosystems. Stryker represents the scale-driven archetype sustaining R&D intensity across interference screw portfolios. Zimmer Biomet Holdings sits within the geographic expansion archetype, anchoring presence through specialized distributor networks in key orthopedic clusters.
| Leading Market Players |
|---|
| Arthrex Inc. |
| Stryker Corporation |
| Zimmer Biomet Holdings |
| Smith & Nephew plc |
| Corin Group |
| DJO Global |
| RTI Surgical Holdings |
| Integra LifeSciences Corporation |
| Mathys AG Bettlach |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between United States tissue banks and ambulatory surgery centers lock in allograft supply access while freezing price visibility for multi-quarter procurement cycles. These contracts insulate buyers from harvesting seasonality but expose them to donor screening failure penalties that reshape site-of-service economics when supply interruptions trigger spot-market purchases.
Pricing Analysis
Project-based pricing dominates ligament augmentation procedures, with bundled reimbursement models at sports medicine facilities separating premium biologic-enhanced reconstructions from standard mechanical grafts. Price differentiation hinges on FDA 510(k) clearance tier and surgeon credentialing level, with fellowship-trained specialists commanding premium positioning. Cost compression in allograft tiers is intensifying because tissue bank consolidation has collapsed supplier diversity. Price-sensitive orthopedic clinics in community settings resist biologic adjuncts, while least-sensitive academic medical centers absorb premium graft costs within research protocols.
Supply Chain Analysis
The United States anchors allograft tissue harvesting and processing, while Germany and Switzerland concentrate bioresorbable fixation device manufacturing. Raw material flows draw from donor tissue networks, magnesium alloy feedstock, and high-tensile polymer fiber suppliers. Single-source vulnerability runs through consolidated tissue bank operators that control procurement logistics for metropolitan surgical clusters. Distribution runs through specialized orthopedic distributor networks that maintain cold-chain integrity for biologic grafts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as United States ambulatory surgery center chains consolidate procurement volume, forcing graft suppliers into unfavorable contract terms. This fragmentation among sellers against consolidated buyers reshapes margin distribution across the value chain.
For Market Incumbents: Fortify biologic-mechanical hybrid graft portfolios through backward integration into stem cell concentrate processing, countering emerging entrant archetypes with pure-play biologic positioning. Expand ISO 13485-certified manufacturing capacity in the Munich-Stuttgart corridor to preempt EU MDR compliance bottlenecks that threaten European market access.
For New Entrants and Emerging Players: Anchor in tier-2 Indian cities where arthroscopy penetration remains underdeveloped and local distributor partnerships neutralize import tariff exposure. Target revision surgery populations with compromised healing capacity through mesenchymal stem cell protocol differentiation, leveraging direct-to-patient marketing channels that bypass entrenched hospital referral networks.
For Investors and Strategic Acquirers: Capital is best deployed toward bioresorbable fixation technology specialists with magnesium alloy screw platforms, positioned for displacement of permanent polymer and metal screw categories. Long-term viability over the coming decade rests on CMS reimbursement determinations for PRP and cellular therapies as the decisive inflection signal for ambulatory site-of-service economics.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Expedited predicate device strategies reduce clinical trial burdens for biologic scaffold entrants. |
| Hospital System Partnership | Academic medical center alliances control credentialing pipeline velocity for sports medicine surgeons. |
| Reimbursement Strategy | CMS coverage determinations for biologic adjuncts reshape ambulatory surgery center site economics. |
| CE Marking Pathway | EU MDR strengthened clinical evidence requirements extend certification timelines for suture-based devices. |
| Software Companion Development | Patient-directed facility selection platforms disrupt traditional hospital referral networks in metropolitan markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with sports medicine surgeons, tissue bank procurement directors, ambulatory surgery center administrators, and orthopedic distributor principals; and secondary validation against FDA 510(k) filings, CMS reimbursement determinations, EU MDR notified body records, and hospital procurement databases. Bottom-up procedure volume estimates triangulated with top-down market sizing across product type, end user, technology, and application dimensions.
Across the analysis window, the forecasting framework modeled product type segmentation by biologics, grafts, sutures, and devices alongside end-user configuration across sports medicine facilities, orthopedic clinics, hospitals, and rehabilitation centers. CAGRs derived from procedure volume trajectories, pricing elasticity assumptions, and technology adoption curves. Industry-specific inputs incorporated fellowship training pipeline velocity and EU MDR compliance cost absorption rates.
Material uncertainties — allograft supply disruptions from donor screening failures, CMS reimbursement rulings on biologic adjuncts, and EU MDR notified body capacity constraints — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and procurement consolidation trajectories. Recalibration cycles align with material shifts in tissue bank merger activity and ambulatory surgery center chain expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Neurosurgical Products Market
Medical Devices
Canada Ultrasound Devices Market
Medical Devices
Nanomedical Devices Market
Medical Devices
Appendage Management Market
Medical Devices
Wearable Cardioverter Defibrillators Market
Medical Devices
Subcutaneous Injection Ports Market
Medical Devices
Global Stroke Assistive Devices Market
Medical Devices
Global Vascular Embolization Devices Market
Medical Devices
Global Prosthetics Market
Medical Devices
Polyether Ether Ketone (PEEK) Interbody Devices Market
Medical Devices
Cervical Total Disc Replacement Device Market
Medical Devices
North America Ultrasound Devices Market
Medical Devices
Luer Lock Connector Market
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
Actigraphy Sensors & PSG Devices Market
Medical Devices
Next Generation Optical Biometry Devices Market