
 Eye Sphere Implants Market | 2026-2036
Eye Sphere Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Eye Sphere Implants Market Analytics
US-based silicone foundries is rebalancing output toward medical-grade ophthalmic polymers after years of serving industrial sealant buyers. Alcon leverages vertical integration across polymer synthesis and sterile packaging to control cost structures in hydrogel sphere production. Bausch Health Companies anchors North American distribution through direct hospital contracts and ambulatory surgical center networks. Carl Zeiss Meditec AG competes on optical metrology integration, bundling implant sizing systems with surgical visualization platforms.
Eye sphere implants are biocompatible orbital devices, typically 14–22 mm in diameter, fabricated from medical-grade silicone, polymethyl methacrylate, or hydrophilic hydrogel polymers to restore orbital volume and motility following enucleation or evisceration. Their primary commercial purpose centers on preventing post-surgical socket contracture and enabling prosthetic eye movement in anophthalmic patients. Silicone implants dominate current volume owing to established biocompatibility profiles and simplified surgical handling, while custom implants capture disproportionate margin pools through patient-specific orbital topography matching. Hospitals remain the principal procurement channel, though ambulatory surgical centers are expanding fastest as oculoplastic procedures migrate to outpatient settings.
The FDA premarket notification pathway shapes US commercial timelines, while the EU Medical Device Regulation imposes clinical evidence requirements on PMMA and hydrogel sphere categories entering European markets. ISO 10993 biocompatibility testing protocols govern material qualification across all major jurisdictions, creating compliance cost barriers for new polymer formulations. Stakeholders must monitor evolving reimbursement codes for custom orbital implants, as coding granularity will determine whether patient-specific manufacturing investments achieve adequate clinical returns.
Market Dynamics
US-based silicone foundries are rebalancing output toward medical-grade ophthalmic polymers after years of serving industrial sealant buyers, compressing lead times for implant manufacturers while reshaping raw material allocation patterns across North American supply chains.
Growth Catalysts
- FDA streamlined premarket notification:The updated 510(k) pathway for ocular prosthetics reduces commercial entry timelines for silicone sphere manufacturers targeting post-enucleation rehabilitation.
- Ambulatory surgical center migration:Oculoplastic procedures are shifting from inpatient settings to outpatient facilities, expanding addressable procedure volumes for implant suppliers.
- EU Medical Device Regulation harmonization:MDR clinical evidence requirements for PMMA and hydrogel spheres are consolidating quality standards across German, French, and Italian ophthalmology clinics.
Market Restraints
- Medical-grade silicone supply concentration:North American polymer synthesis capacity remains concentrated among a limited number of FDA-registered foundries, creating vulnerability to batch contamination events.
- ISO 10993 biocompatibility testing costs:Material qualification protocols impose fixed compliance burdens that disproportionately constrain new hydrogel formulation entrants.
- Custom implant manufacturing economics:Patient-specific orbital topography matching requires low-volume, high-mix production that resists scale efficiencies.
Strategic Opportunities
- Underpenetrated German oculoplastic units:Academic medical centers in Berlin and Munich are building dedicated orbital surgery divisions with procurement autonomy for advanced implant portfolios.
- Optical metrology bundling:Integration of implant sizing systems with surgical visualization platforms creates differentiated value propositions for high-volume hospital purchasers.
- Reimbursement code granularity expansion:Emerging CPT distinctions for custom orbital implants may justify patient-specific manufacturing investments through improved clinical returns.
Industry Challenges
- Oculoplastic surgeon training pipeline constraints:Fellowship program output limits the specialist workforce capable of complex socket rehabilitation procedures.
- Sterile packaging validation timelines:ISO 11607 compliance for hydrogel sphere shelf-life claims extends product launch schedules by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eye Sphere Implants Market |
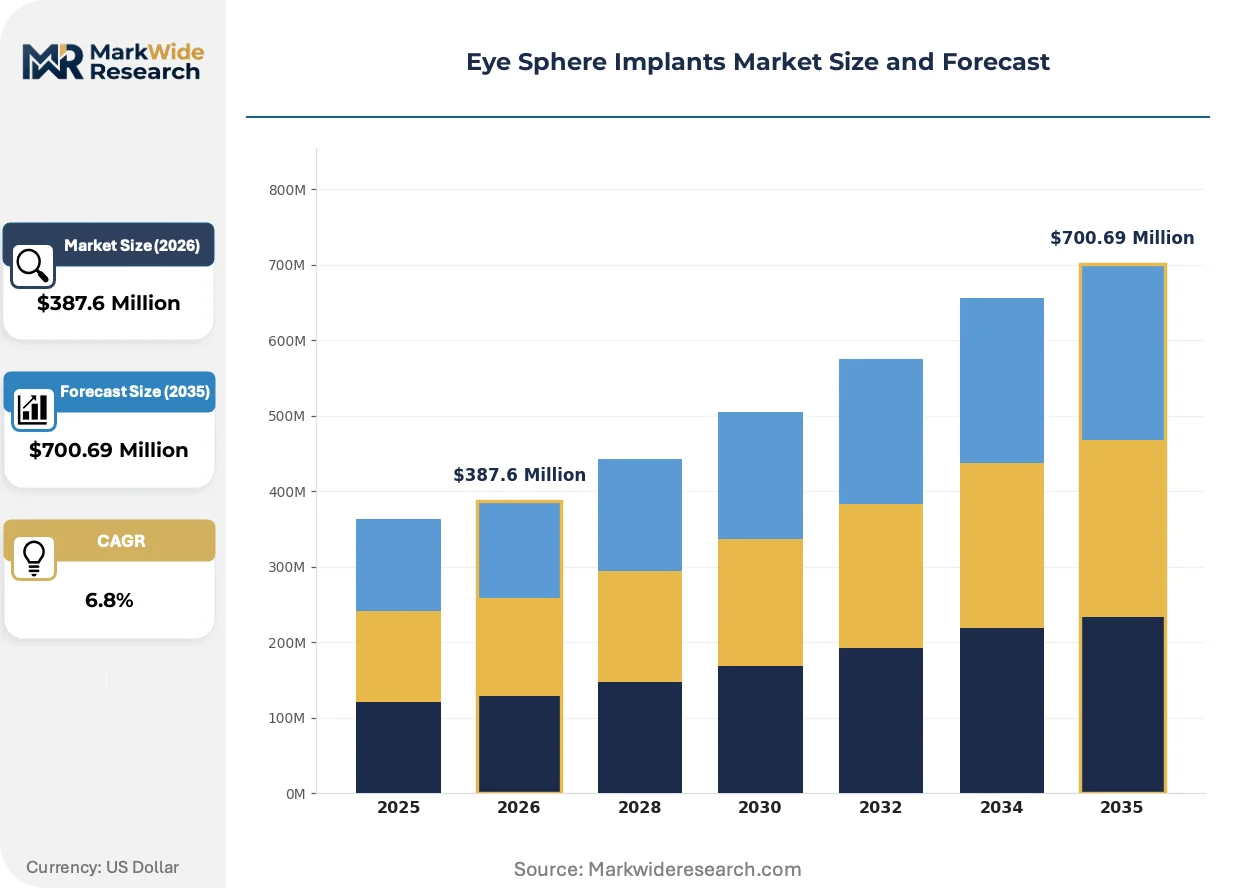
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Implants, PMMA Implants, Hydrogel Implants, Custom Implants Application: Cataract Surgery, Glaucoma Treatment, Retinal Repair, Ocular Trauma End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Rehabilitation Centers Delivery Mode: Intraocular Delivery, Extracapsular Delivery, Transscleral Delivery, Ocular Injections |
| Companies Covered | Hilco Vision, Gulden Ophthalmics, Porex Surgical Group, Molteno Ophthalmic, FCI Ophthalmics, Alcon, Bausch Health Companies, Carl Zeiss Meditec AG, Morcher GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eye Sphere Implants Market Evolving Landscape
Digital orbital modeling and patient-specific manufacturing workflows are compressing the traditional gap between diagnostic imaging and surgical implantation, enabling same-week custom sphere production that challenges standardized inventory models.
Computer-aided design coupled with additive manufacturing is automating the conversion of CT orbital scans into patient-matched silicone sphere geometries. Academic medical centers in Boston and Philadelphia are adopting these platforms for complex post-traumatic socket reconstructions. The technology is automating previously manual wax-carving steps, reducing revision surgery rates while compressing preoperative planning from weeks to days.
EU Medical Device Regulation Article 10 clinical evidence requirements are forcing hydrogel sphere manufacturers to generate post-market surveillance data beyond traditional biocompatibility studies. German notified bodies are interpreting MDR Annex XIV more stringently for porous polymer categories than for solid silicone alternatives. Smaller PMMA implant suppliers are responding by withdrawing from European markets rather than funding clinical follow-up studies.
Direct hospital contracting is displacing traditional distributor intermediaries in North American procurement channels. Bausch Health Companies and Alcon are building captive sales forces to serve ambulatory surgical center networks with consignment inventory models. This shift is most visible in Florida and Texas, where oculoplastic procedure volume concentrates among multi-site outpatient operators seeking price transparency and volume-based rebates.
Eye Sphere Implants Market Segmentation
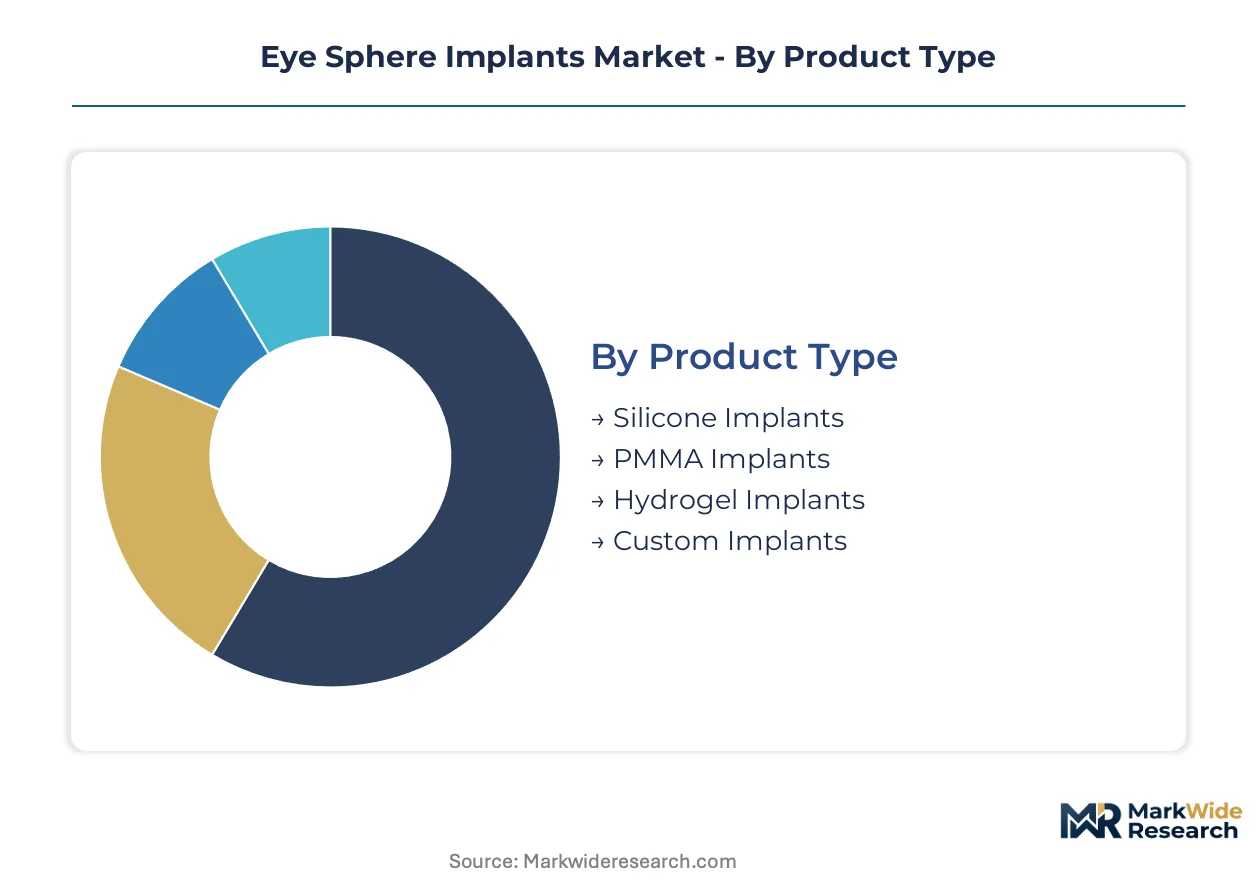
Segmentation in the eye sphere implants market reveals how regulatory pathways, surgical settings, and delivery mechanisms fragment procurement patterns. Manufacturers must align product portfolios with distinct approval requirements and end-user workflows across each category.
Product Type:
Silicone spheres navigate FDA 510(k) premarket notification with streamlined biocompatibility documentation, while hydrogel and PMMA variants face escalating clinical evidence demands under EU MDR Annex XIV.
- Silicone Implants:Medical-grade polymer spheres, 14–22 mm diameter, fabricated from platinum-cured silicone elastomer with established ISO 10993 compliance profiles. Demand concentrates in US ambulatory surgical centers where simplified surgical handling reduces operative time. FDA 510(k) pathway compresses commercial entry timelines relative to alternative materials.
- Custom Implants:Patient-specific orbital topography matching via CT-derived CAD/CAM workflows, typically milled or printed from medical-grade polymers. Academic medical centers in Boston and Philadelphia adopt these for complex post-traumatic reconstructions. Reimbursement code granularity remains the critical constraint on manufacturing investment returns.
- PMMA Implants:Polymethyl methacrylate spheres with rigid structural properties and long implantation history, requiring comprehensive biocompatibility testing under updated EU MDR frameworks.
- Hydrogel Implants:Hydrophilic polymer spheres with tissue-like water content, subject to stringent post-market surveillance requirements for porous polymer categories in European markets.
Silicone implants sit at the top of the volume ranking, with custom implants climbing the fastest.
Application:
Procedure complexity and socket rehabilitation timelines create distinct margin profiles across surgical indications, with trauma cases commanding premium pricing for rapid-turnaround custom fabrication.
- Ocular Trauma:Emergency enucleation and evisceration procedures requiring immediate orbital volume restoration, often with expedited custom implant production. Level I trauma centers in Florida and Texas generate concentrated demand for rapid-prototype silicone spheres. Reconstruction urgency compresses traditional weeks-long preoperative planning into same-week surgical workflows.
- Retinal Repair:Complex posterior segment procedures with concurrent orbital intervention, typically in academic medical center settings with integrated oculoplastic and vitreoretinal surgical teams.
- Cataract Surgery:Standard ophthalmic procedures with minimal orbital implant crossover, representing limited addressable volume for sphere manufacturers.
- Glaucoma Treatment:Anterior segment interventions occasionally requiring adjunctive orbital procedures in advanced disease stages.
Ocular trauma applications generate the steepest expansion trajectory as digital orbital modeling compresses diagnostic-to-surgical intervals.
End User:
Procurement autonomy and inventory management sophistication separate institutional buyers, with multi-site outpatient operators driving contract restructuring toward direct manufacturer relationships.
- Ambulatory Surgical Centers:Multi-site outpatient operators in Florida and Texas concentrating oculoplastic procedure volume, demanding consignment inventory models and price transparency. Direct hospital contracting displaces traditional distributor intermediaries in these settings. Volume-based rebate structures reshape procurement economics for standardized silicone sphere portfolios.
- Hospitals:Academic medical centers with dedicated oculoplastic surgery units and captive procurement committees, prioritizing optical metrology integration and surgical visualization platform bundling.
- Specialty Clinics:Focused ophthalmology practices with limited surgical capacity, typically referring complex socket rehabilitation to hospital-based specialists.
- Rehabilitation Centers:Post-surgical prosthetic fitting facilities with indirect influence on implant selection through prosthetist-surgeon coordination.
Hospitals retain the dominant procurement position, while ambulatory surgical centers gain share fastest as procedure migration accelerates.
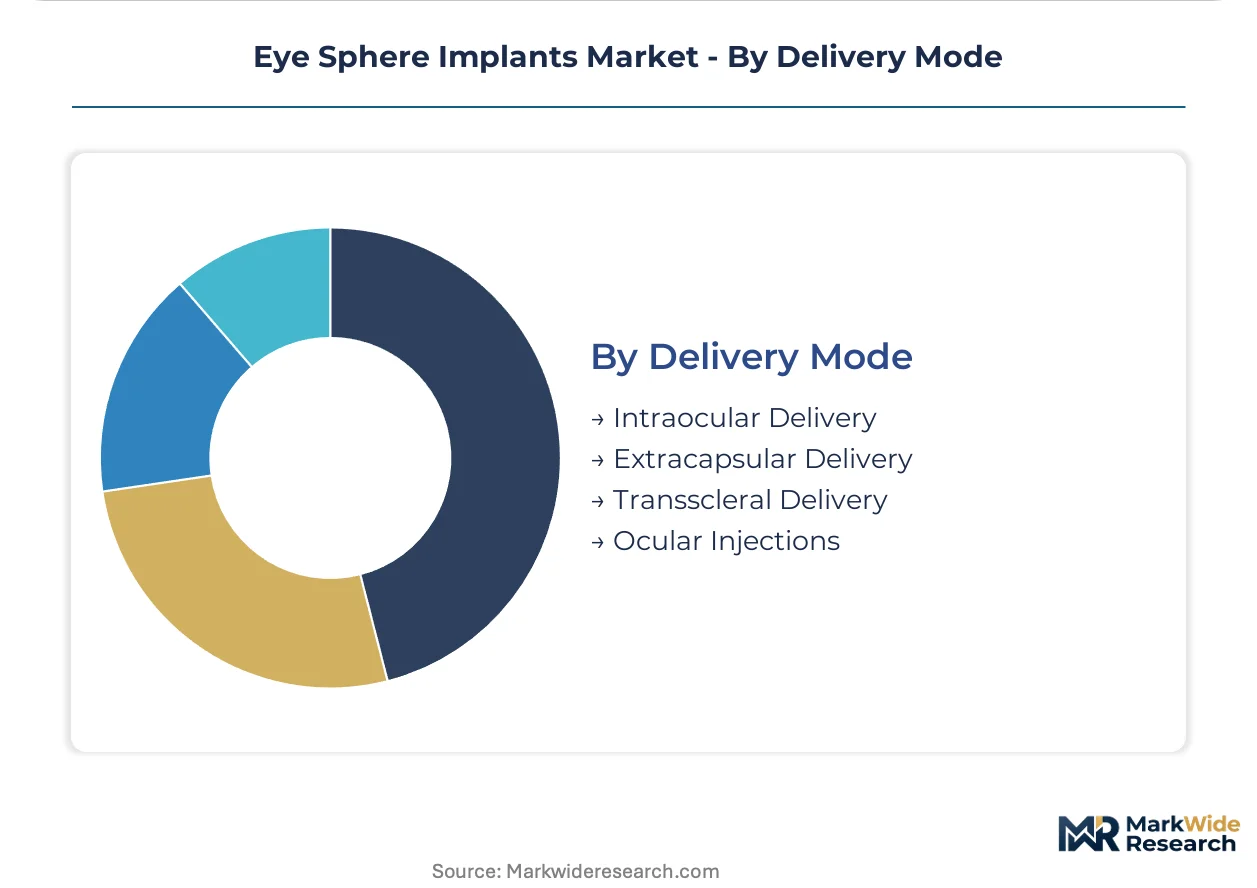
Delivery Mode:
Surgical approach selection determines implant specification requirements, with minimally invasive techniques demanding smaller-diameter spheres and specialized insertion instrumentation.
- Intraocular Delivery:Direct implant placement within the ocular cavity during enucleation or evisleration, the standard approach for silicone sphere insertion with established surgical training protocols.
- Transscleral Delivery:Scleral-fixed implantation techniques requiring modified sphere geometries and supplemental suturing systems, concentrated in complex revision surgeries.
- Extracapsular Delivery:Orbital implant placement outside the scleral shell, typically reserved for specific anatomical presentations or prior surgical history.
- Ocular Injections:Injectable filler adjuncts rather than primary sphere delivery, representing a peripheral category with limited implant manufacturer relevance.
Intraocular delivery maintains volume leadership, with transscleral approaches expanding most quickly as revision surgery rates drive technique diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's ophthalmology clinics expand silicone sphere adoption faster than French academic centers, reflecting divergent MDR implementation timelines across EU member states.
United States
Academic medical centers in Boston and Philadelphia build dedicated oculoplastic surgery units with procurement autonomy for advanced implant portfolios. The FDA's streamlined 510(k) premarket notification compresses commercial entry timelines for silicone sphere manufacturers. Florida and Texas multi-site ambulatory surgical centers concentrate procedure volume and drive direct manufacturer contracting.
Germany
Berlin and Munich academic hospitals establish dedicated orbital surgery divisions with independent purchasing authority for custom implant portfolios. EU Medical Device Regulation Annex XIV imposes stringent clinical evidence requirements on hydrogel and PMMA sphere categories. German notified bodies interpret porous polymer standards more strictly than solid silicone alternatives.
France
Parisian ophthalmology clinics adopt digital orbital modeling platforms for post-traumatic socket reconstructions with compressed diagnostic-to-surgical intervals. ANSM oversight aligns with EU MDR harmonization for ocular prosthetic device categories. Lyon and Marseille surgical centers concentrate demand for rapid-turnaround custom fabrication workflows.
Japan
Tokyo and Osaka medical centers integrate optical metrology systems with surgical visualization platforms for implant sizing accuracy. PMDA regulatory pathways require ISO 10993 biocompatibility documentation for medical-grade silicone imports. METI industrial policy supports domestic polymer synthesis capacity for ophthalmic device applications.
United Kingdom
London teaching hospitals maintain captive procurement committees prioritizing surgical visualization platform bundling. MHRA post-Brexit regulatory alignment retains EU MDR technical standards for ocular prosthetic categories. Manchester and Birmingham oculoplastic units expand fellowship training pipelines for complex socket rehabilitation.
Eye Sphere Implants Market Competitive Landscape
United States producers anchor one tier; German and Swiss specialists hold differentiated positions in optical metrology integration. The vendor base separates into consolidated polymer manufacturers, precision optics integrators, and patient-specific fabrication platforms. Three archetypes dominate: vertically integrated polymer synthesizers, surgical visualization bundlers, and digital workflow specialists. Capacity expansion and direct hospital contracting represent the dominant competitive moves reshaping procurement channels.
Among diversified ophthalmic manufacturers, Alcon and Bausch Health Companies exemplify scale-driven polymer synthesis and North American distribution architectures. Carl Zeiss Meditec AG occupies a position within the precision optics tier, representing surgical visualization platform integration. Morcher GmbH anchors German specialization in custom orbital implant fabrication. These three entities collectively illustrate the geographic and capability segmentation defining competitive positioning.
| Leading Market Players |
|---|
| Hilco Vision |
| Gulden Ophthalmics |
| Porex Surgical Group |
| Molteno Ophthalmic |
| FCI Ophthalmics |
| Alcon |
| Bausch Health Companies |
| Carl Zeiss Meditec AG |
| Morcher GmbH |
| Others |
Value Network & Pricing Analysis
Material-grade bifurcation between FDA-registered platinum-cured silicone and EU MDR-classified hydrogel polymers manifests in divergent pricing architectures and supply chain sourcing patterns. Premium silicone spheres command hospital procurement premiums through streamlined 510(k) pathways, while hydrogel alternatives face elongated validation timelines that compress manufacturer margins and concentrate production among German polymer foundries.
Pricing Analysis
Distributor margin compression in North American channels is accelerating direct manufacturer contracting for ambulatory surgical center networks. Pricing stratifies across premium custom-milled implants, standard silicone spheres, and economy-grade PMMA alternatives based on ISO 10993 certification tier and surgical handling complexity. Cost compression in standardized silicone categories stems from foundry capacity expansion in Texas and Ohio. Academic medical centers exhibit lowest price sensitivity due to bundled optical metrology procurement, while multi-site outpatient operators negotiate volume-based rebates aggressively.
Supply Chain Analysis
Specialized polymer chemist availability in Massachusetts and New Jersey anchors North American medical-grade silicone synthesis. Raw material flows draw from platinum catalyst suppliers in Pennsylvania and hydrophilic monomer producers in Germany. Single-source vulnerability concentrates in FDA-registered foundry certification, where batch contamination events would disrupt implant availability. Distribution runs through captive sales forces serving hospital systems with consignment inventory models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between FDA 510(k) streamlining in the United States and EU MDR clinical evidence burdens that force smaller PMMA suppliers toward German notified body concentration.
For Market Incumbents: Anticipate ambulatory surgical center procurement autonomy by building direct contracting capabilities in Florida and Texas before distributor relationships crystallize. Alcon and Bausch Health Companies should deepen backward integration into platinum-cured silicone polymer synthesis to defend against batch contamination risks. ISO 11607 sterile packaging validation timelines represent the critical margin pressure point requiring captive capacity investment. For New Entrants and Emerging Players: Digital orbital modeling platforms offer a technology-first wedge for rapid-turnaround custom implant production. White-space concentrates in Parisian and Lyon trauma centers adopting same-week CAD/CAM workflows for post-enucleation socket reconstruction. Target German academic hospitals in Berlin and Munich building dedicated orbital surgery divisions with independent purchasing authority. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR Annex XIV clinical evidence requirements exceed smaller PMMA implant supplier balance sheet capacity. Long-term viability favors vertically integrated polymer synthesizers with captive sterile packaging and direct hospital contracting infrastructure. Watch German notified body interpretation stringency for porous polymer categories as the inflection signal for hydrogel sphere manufacturer withdrawal.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Hospital Contracting | Bausch Health Companies and Alcon bypass distributor intermediaries to capture ambulatory surgical center volume in Florida and Texas. |
| Optical Metrology Bundling | Carl Zeiss Meditec AG integrates implant sizing systems with surgical visualization platforms for academic medical center procurement committees. |
| Digital Workflow Investment | Patient-specific CAD/CAM production compresses diagnostic-to-surgical intervals for Boston and Philadelphia trauma centers. |
| EU MDR Compliance Buildout | German notified body relationships determine hydrogel sphere market access versus PMMA supplier withdrawal. |
| Reimbursement Strategy | Emerging CPT code granularity for custom orbital implants shapes patient-specific manufacturing investment returns. |
Research Methodology
Bottom-up oculoplastic procedure volume modeling reconciled against top-down medical-grade polymer production tracking forms the analytical core of this study. Primary interviews with oculoplastic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers were cross-validated against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement codes. Secondary sources include ISO 10993 biocompatibility test reports and German academic hospital capital expenditure disclosures.
Input-output matrices across product type, application, end user, and delivery mode dimensions drive volume and value projections throughout the forecast period. CAGRs were derived from procedure migration trends and material adoption curves. Industry-specific inputs include fellowship program output rates for oculoplastic surgeon supply and ambulatory surgical center certification expansion timelines.
The model holds under stable FDA 510(k) pathway timelines and EU MDR implementation consistency; deviation in German notified body interpretation stringency or platinum catalyst supply disruption would shift hydrogel sphere availability assumptions. Practitioners should monitor reimbursement code granularity evolution and sterile packaging validation backlog for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Medical Bionic Implant Market
Medical Devices
US Peripheral Vascular Devices and Accessories Market
Medical Devices
Large Volume Nebulizers Market
Medical Devices
China Electrocardiograph (ECG) Market
Medical Devices
North America IVD Regulatory Affairs Outsourcing Market
Medical Devices
Global Glucometer Market
Medical Devices
Bovine Pericardial Valve Market
Medical Devices
Clinical Rollators Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
Drug Delivery Devices Market
Medical Devices
Global Radiofrequency Ablation Devices Market
Medical Devices
North America Cardiac Rhythm Management Devices Market
Medical Devices
Global Robotic Wheelchairs Market
Medical Devices
Global Bone Cement Delivery System Market
Medical Devices
Global Stereotactic Surgery Devices Market