
 Canada Insulin Delivery Devices Market | 2026-2036
Canada Insulin Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Insulin Delivery Devices Market Outlook
Recurring revenue from disposable pump supplies is tilting margin pools away from capital equipment sales toward consumable attachment models. Medtronic leverages its integrated CGM-pump ecosystem to sustain recurring revenue density across provincial procurement channels. Insulet Corporation differentiates through tubeless patch pump architecture that reduces patient training burden in community settings. Tandem Diabetes Care competes on algorithm-driven automated insulin delivery that tightens glycemic control margins.
Insulin delivery devices constitute electromechanical and disposable systems engineered to administer exogenous insulin with dosing precision typically within 0.025-unit increments, utilizing either piston-driven syringe barrels, spring-loaded pen mechanisms, or micro-pump fluidics with subcutaneous cannula interfaces. These devices serve the therapeutic purpose of replicating physiological insulin secretion patterns in patients with impaired pancreatic beta-cell function. Insulin Pens retain the largest installed base among device types due to portability and dose flexibility, though margin expansion concentrates in Insulin Pumps as automated basal-bolus algorithms penetrate Type 1 populations. Bluetooth-enabled Devices within the technology dimension are capturing fastest-growing demand as remote monitoring integrations satisfy provincial telehealth reimbursement criteria.
Health Canada regulates insulin pumps as Class III medical devices under the Medical Devices Regulations, requiring pre-market licensing that shapes product development timelines and clinical evidence requirements for algorithm-based systems. The Canadian Agency for Drugs and Technologies in Health conducts health technology assessments that influence provincial formulary inclusion and reimbursement rates for advanced delivery systems. Provincial health authorities in Ontario and Quebec maintain distinct tendering frameworks that fragment procurement pathways and complicate national launch strategies. Stakeholders must monitor Health Canada's anticipated software-as-a-medical-device guidance to determine whether AI-driven dosing algorithms trigger additional regulatory classification burdens.
Market Dynamics
The transition toward automated insulin delivery systems is compressing traditional pump replacement cycles while elevating software validation requirements under Health Canada's evolving Class III framework.
Growth Catalysts
- Ontario Telehealth Expansion:Provincial reimbursement for remote glucose monitoring creates pull-through demand for Bluetooth-enabled delivery systems in community diabetes clinics.
- Health Canada Software-as-a-Medical-Device Guidance:Anticipated regulatory clarity accelerates algorithm-based pump development timelines for manufacturers seeking pre-market licensing.
- CGM-Pump Convergence:Closed-loop integration between continuous glucose monitors and insulin pumps tightens glycemic control metrics in Type 1 patient populations.
Market Restraints
- Single-Source Cannula Supply:Concentrated manufacturing of subcutaneous infusion sets in offshore facilities exposes procurement channels to logistics disruption.
- Provincial Tender Fragmentation:Distinct procurement frameworks across Ontario, Quebec, Alberta, and British Columbia complicate national pricing strategies.
- Training Burden in Rural Networks:Patch pump adoption faces headwinds from limited certified diabetes educator availability in northern health authorities.
Strategic Opportunities
- Alberta Urban Care Corridors:Underserved diabetes populations in Calgary and Edmonton health zones present concentrated deployment potential for tubeless systems.
- AI-Driven Dosing Algorithms:Machine learning integration with existing pump hardware opens software-centric revenue streams independent of device replacement cycles.
- Pharmacy Channel Expansion:Community pharmacy networks in Quebec and British Columbia emerge as alternative distribution points for smart pen consumables.
Industry Challenges
- Cybersecurity Validation for Connected Devices:Bluetooth-enabled pumps require Health Canada scrutiny of data transmission protocols, extending pre-market review timelines.
- Legacy System Interoperability:Provincial electronic health record fragmentation forces device manufacturers to maintain multiple data exchange formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Insulin Delivery Devices Market |
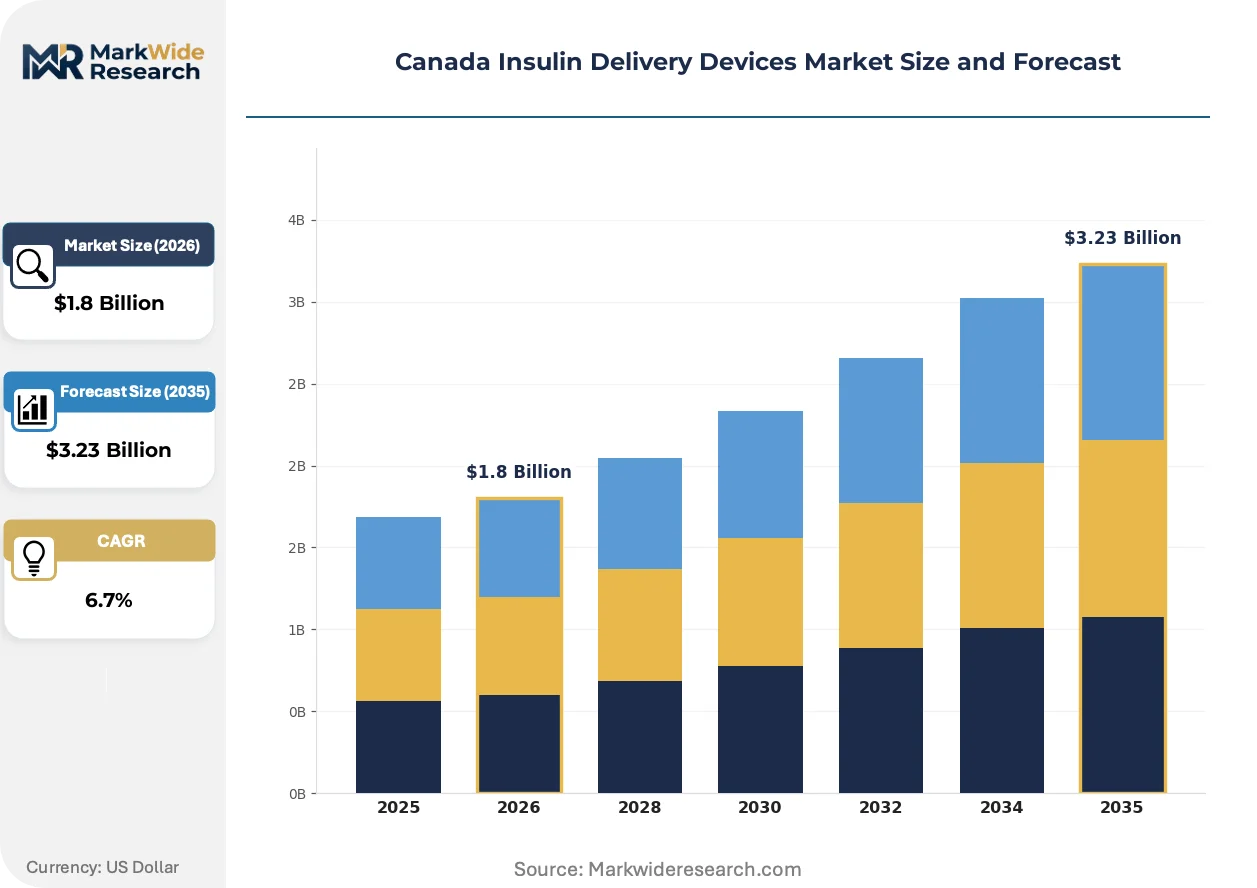
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Insulin Pens, Insulin Syringes, Insulin Pumps, Continuous Glucose Monitors End User: Patients, Hospitals, Clinics, Caregivers Administration Route: Subcutaneous, Intramuscular, Intravenous, Transdermal Technology: Smart Pumps, Wearable Devices, Automated Systems, Bluetooth-enabled Devices |
| Companies Covered | Sanofi, Tandem Diabetes Care, Medtronic, Becton Dickinson, Ypsomed, Novo Nordisk, Insulet Corporation, Roche, Eli Lilly, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Insulin Delivery Devices Market Strategic Shifts
Algorithmic automation is redefining competitive advantage in insulin delivery, shifting value capture from hardware durability toward software-driven dosing precision and remote monitoring integration.
Tubeless patch pump architecture is collapsing the distinction between intensive insulin therapy and lifestyle flexibility for Type 1 patients. Adolescent and young adult demographics in Ontario and Quebec are migrating toward these systems at accelerated replacement rates. This shift compresses addressable market boundaries between traditional tethered pumps and next-generation wearable platforms.
Health Canada's Medical Devices Regulations are tightening clinical evidence requirements for automated insulin delivery algorithms. The regulator's Class III classification framework now demands prospective trial data for hybrid closed-loop systems seeking pre-market approval. Pump manufacturers are responding by front-loading clinical development budgets and extending Canadian launch timelines relative to US FDA clearance pathways.
Provincial procurement authorities are consolidating purchasing power through multi-year tender frameworks. Ontario's centralized diabetes device procurement is displacing hospital-level purchasing autonomy with standardized formularies. British Columbia's health authorities are following this model, concentrating vendor selection decisions within regional health networks rather than individual endocrinology practices.
Canada Insulin Delivery Devices Market Segmentation
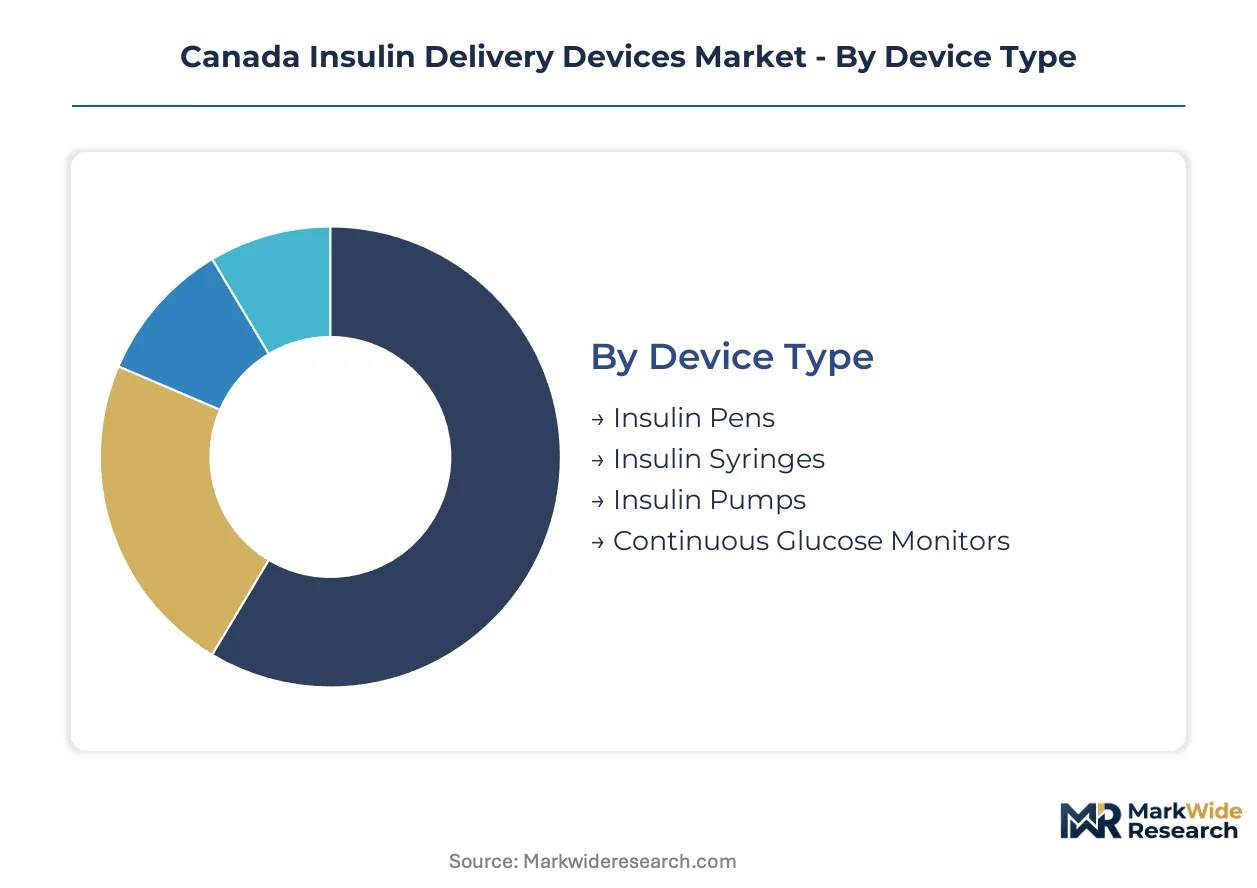
Segmentation in Canada's insulin delivery market reveals how reimbursement pathways, patient autonomy preferences, and provincial procurement frameworks reshape competitive boundaries across device categories. Understanding these divisions exposes where margin pools concentrate and where technology transitions disrupt established vendor positions.
Device Type:
Mature disposable formats coexist with emerging automated platforms, creating divergent margin structures across the therapeutic continuum.
- Insulin Pens:Spring-loaded cartridge systems with dial-dose mechanisms deliver 0.5-unit or 1-unit increments through disposable or reusable pen bodies. Demand concentrates in Quebec's community pharmacy networks and Ontario's long-term care facilities where caregiver-administered dosing dominates and provincial formularies favor cost-efficient disposable models.
- Insulin Pumps:Electromechanical reservoir systems with subcutaneous infusion sets enable programmable basal rates and bolus calculators. Alberta's urban diabetes corridors in Calgary and Edmonton health zones drive tethered pump adoption, though tubeless architectures are displacing traditional designs in adolescent Type 1 populations seeking lifestyle flexibility.
- Insulin Syringes:Piston-driven barrel systems with fixed or detachable needles remain the lowest-cost entry point for insulin initiation.
- Continuous Glucose Monitors:Factory-calibrated interstitial sensors with transmitter-receiver pairs enable real-time glucose trend visualization.
Insulin Pens retain volume leadership; Insulin Pumps hold the steepest expansion curve.
End User:
Cost-bearing responsibility shifts dramatically across patient versus institutional procurement channels, fragmenting pricing architectures.
- Patients:Self-directed consumers purchasing through retail pharmacy or private insurance reimbursement, with out-of-pocket exposure varying by provincial coverage tiers.
- Hospitals:Acute care facilities in Ontario's Local Health Integration Networks procure through centralized tenders with standardized formularies that limit vendor selection.
- Clinics:Community diabetes centers in British Columbia's regional health authorities drive CGM-pump convergence through endocrinologist-directed prescribing.
- Caregivers:Family members and home health aides administering insulin in domestic settings, particularly prevalent in Quebec's aging demographic corridors where smart pen training programs expand.
Patients dominate absolute unit consumption; Clinics command the fastest-growing technology adoption rates.
Administration Route:
Delivery mechanics determine regulatory classification burden and training infrastructure requirements across the care continuum.
- Subcutaneous:Tissue-level absorption through abdominal, thigh, or arm injection sites constitutes the standard of care for basal and prandial insulin delivery.
- Intramuscular:Muscle-tissue injection reserved for acute hyperglycemic emergencies and rapid-acting insulin scenarios in hospital settings.
- Intravenous:Direct vascular delivery restricted to intensive care units and perioperative management with continuous infusion protocols.
- Transdermal:Microneedle array and iontophoresis platforms in early Health Canada evaluation for needle-averse patient populations.
Subcutaneous delivery anchors installed base; Transdermal platforms are climbing the fastest toward commercial viability.
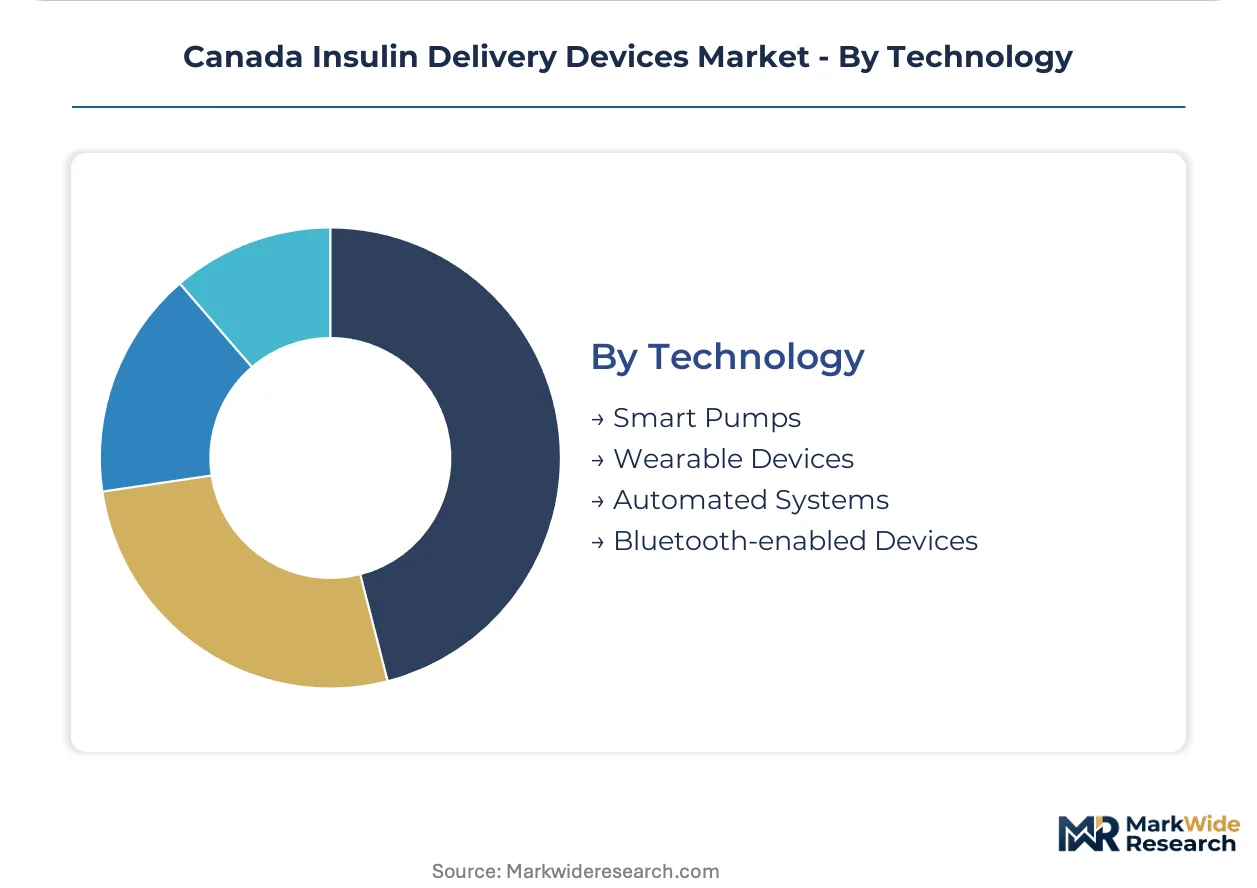
Technology:
Software-enabled differentiation is collapsing hardware replacement cycles while extending revenue capture through algorithm subscriptions.
- Bluetooth-enabled Devices:Wireless data transmission to smartphone applications enables remote monitoring and dose logging that satisfies Ontario's telehealth reimbursement criteria. Health Canada's scrutiny of data transmission protocols extends pre-market review timelines for manufacturers seeking Class III licensing.
- Automated Systems:Hybrid closed-loop algorithms modulate insulin delivery based on CGM inputs with minimal patient intervention. British Columbia's provincial health networks concentrate procurement for these systems as glycemic control metrics tighten reimbursement thresholds.
- Smart Pumps:Connected reservoir systems with dose calculators and compliance tracking, bridging traditional pump functionality with remote monitoring integration.
- Wearable Devices:Patch-form factor systems with adhesive-mounted pumps eliminating external tubing, reducing training burden in community settings across northern health authorities.
Bluetooth-enabled Devices retain connectivity leadership; Automated Systems hold the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Canadian provinces, with Quebec's centralized formulary driving aggressive generic substitution while Alberta's private insurance tiers sustain premium device uptake. Ontario occupies the middle ground, where telehealth reimbursement creates demand elasticity for connected systems without full provincial coverage.
Ontario
Telehealth expansion and community diabetes clinic networks pull Bluetooth-enabled delivery systems into the province's Local Health Integration Networks. Health Canada's Class III licensing requirements for algorithm-based pumps shape product launch timelines for manufacturers targeting Toronto and Ottawa endocrinology practices. The Greater Toronto Area concentrates procurement decision-making as centralized tenders displace hospital-level purchasing autonomy.
Quebec
Community pharmacy networks and aging demographic corridors sustain smart pen volume leadership through caregiver-administered dosing programs. The province's distinct tendering framework fragments procurement pathways from Ontario, complicating national pricing architectures for device manufacturers. Montreal's health technology assessment centers influence provincial formulary inclusion for advanced delivery systems.
Alberta
Urban diabetes care corridors in Calgary and Edmonton health zones concentrate tethered pump adoption among Type 1 populations with private insurance coverage. The province's health authorities maintain procurement frameworks separate from Ontario and Quebec, creating regional pricing differentiation. Northern health authorities face training infrastructure constraints that slow patch pump penetration in rural networks.
British Columbia
Regional health authority consolidation and CGM-pump convergence drive automated system procurement through endocrinologist-directed prescribing in Vancouver and Victoria clinics. Provincial electronic health record fragmentation forces device manufacturers to maintain multiple data exchange formats. The province follows Ontario's centralized procurement model, concentrating vendor selection within regional networks rather than individual practices.
Canada Insulin Delivery Devices Market Competitive Environment
Integrated ecosystem builders and specialized wearable platforms split the market between recurring revenue density and lifestyle-flexibility positioning. The vendor base concentrates around three strategic archetypes: diversified medical technology conglomerates with CGM-pump convergence capabilities, pure-play pump specialists with algorithm-driven automation, and disposable-focused manufacturers leveraging pharmacy channel scale. Dominant competitive moves include software-centric revenue stream development independent of hardware replacement cycles and provincial tender consolidation through multi-year framework agreements.
Among the integrated medical technology conglomerates, Medtronic anchors the ecosystem-builder archetype with its CGM-pump convergence positioning, while Tandem Diabetes Care and Insulet Corporation exemplify the pure-play pump specialist tier with differentiated automation and wearable form-factor strategies respectively. These three companies occupy positions that reflect the market's bifurcation between tethered systems with algorithmic precision and tubeless architectures reducing patient training burden.
| Leading Market Players |
|---|
| Sanofi |
| Tandem Diabetes Care |
| Medtronic |
| Becton Dickinson |
| Ypsomed |
| Novo Nordisk |
| Insulet Corporation |
| Roche |
| Eli Lilly |
| Others |
Value Chain & Pricing Dynamics
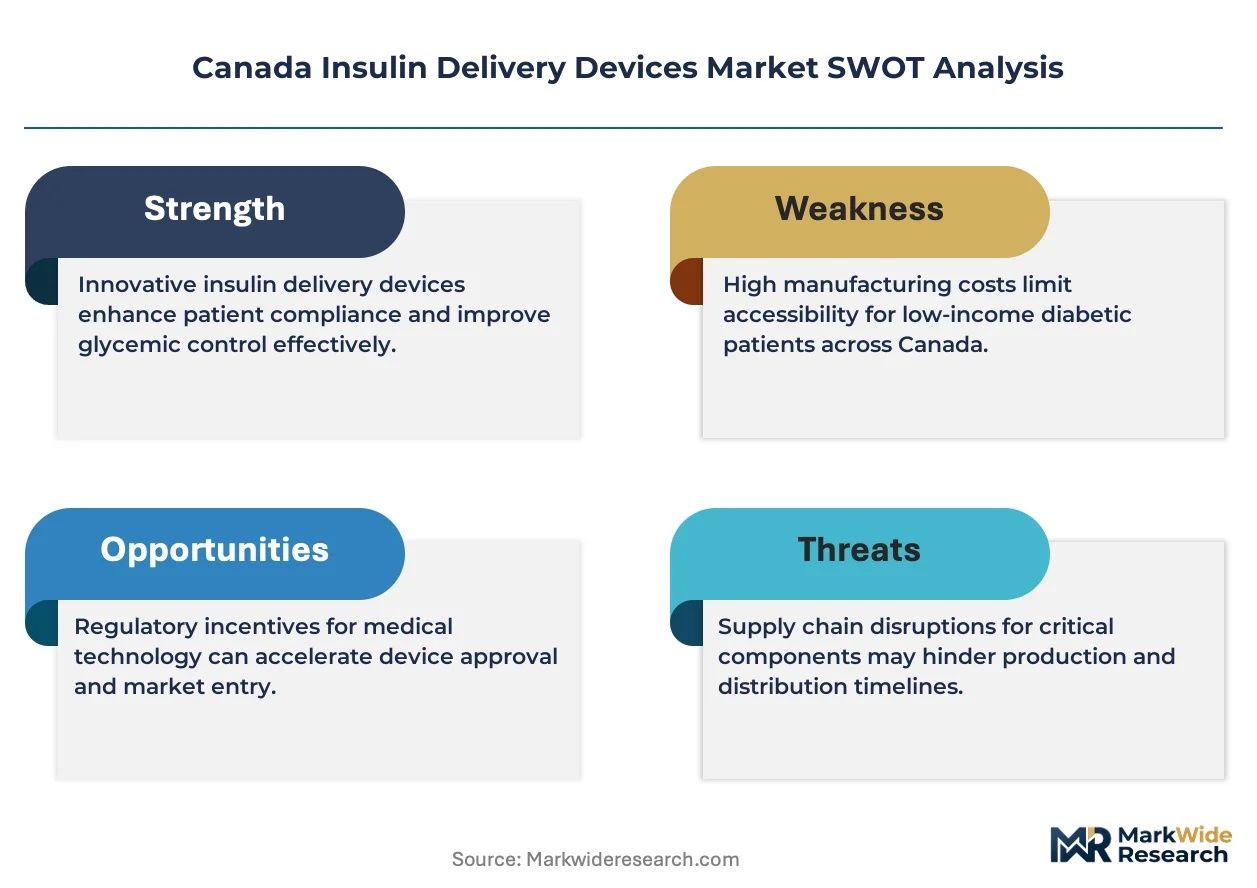
Single-source cannula manufacturing concentration in offshore facilities determines both premium-to-economy tier spreads and the shape of procurement resilience investments across Canadian provincial health networks. Health Canada's Class III device licensing framework amplifies this dependency by extending pre-market timelines for manufacturers lacking diversified component sourcing.
Pricing Analysis
Consumable attachment revenue from disposable infusion sets and reservoir cartridges drives lifetime value beyond initial pump hardware sales. Three-tier pricing structure across premium automated systems, standard tethered pumps, and economy pen formats stratifies by algorithm sophistication and CGM integration depth. Pricing pressure stems from provincial tender consolidation in Ontario and British Columbia that squeezes margin pools on capital equipment. Hospital procurement committees exhibit highest price sensitivity; private insurance-covered Type 1 patients in Alberta urban corridors show lowest sensitivity to premium tier positioning.
Supply Chain Analysis
Precision-machined pump motors and medical-grade plastics for reservoir housings draw from established manufacturing clusters in Germany, Switzerland, and the United States. Subcutaneous infusion sets, Bluetooth transmitter modules, and lithium-ion power cells constitute critical input dependencies. Single-source vulnerability concentrates in Asian contract manufacturers producing cannula assemblies for multiple OEM brands. Distribution runs through provincial health authority tender frameworks in Ontario and Quebec alongside pharmacy channel partnerships for smart pen consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from algorithm-validation cycle compression as Health Canada's software-as-a-medical-device guidance clarifies regulatory pathways for AI-driven dosing systems.
For Market Incumbents: Build algorithmic moats through Health Canada pre-market licensing for hybrid closed-loop systems ahead of guidance finalization. Deepen backward integration into CGM sensor supply to defend against convergent ecosystem threats from diversified medtech conglomerates. Secure multi-year provincial tender frameworks in British Columbia and Ontario to lock out emerging wearable platform competitors. For New Entrants and Emerging Players: Build out pharmacy channel presence for Bluetooth-enabled smart pens in Quebec's community networks where caregiver-administered dosing programs expand fastest. Target northern Alberta health authorities with tubeless patch pump training-light deployments where certified diabetes educator scarcity impedes incumbent penetration. Pursue software companion development partnerships with provincial telehealth platforms to satisfy Ontario reimbursement criteria. For Investors and Strategic Acquirers: The market sits at a regulatory-clarity phase that favors algorithm-integrated pump specialists with Health Canada submission momentum. Long-term viability hinges on software-centric revenue durability independent of hardware replacement cycles. Watch for provincial formulary inclusion decisions in Ontario and British Columbia as inflection indicators for automated system adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Pre-Market Licensing | Class III approval for hybrid closed-loop algorithms opens provincial procurement channels in Ontario and Quebec. |
| CGM-Pump Ecosystem Integration | Sensor-augmented pump convergence tightens glycemic control metrics and elevates reimbursement tier positioning. |
| Provincial Tender Framework Consolidation | Multi-year agreements with British Columbia regional health authorities displace fragmented hospital-level purchasing. |
| Software Companion Development | Remote monitoring applications satisfy Ontario telehealth reimbursement criteria and extend patient data capture. |
| Tubeless Patch Pump Training Programs | Reduced educator burden accelerates adoption in northern health authorities with workforce constraints. |
Study Parameters
Initial hypotheses were tested against primary input from endocrinologists, biomedical engineers, provincial procurement officers, and certified diabetes educators and refined through secondary validation against Health Canada device licensing databases, CADTH health technology assessments, provincial formulary listings, and hospital GPO contract records. Bottom-up patient population modeling and top-down revenue triangulation anchored market size estimation.
Demand-supply balance across device type, end user, and technology segments shaped the analytical framework over the projection horizon. Segmentation dimensions included administration route, connectivity protocol, and provincial reimbursement tier. CAGRs were derived from installed base replacement cycles and algorithm penetration curves. Forecast inputs incorporated Health Canada regulatory timeline assumptions and provincial telehealth expansion trajectories.
Stress conditions across Health Canada software guidance delays, provincial tender award timing, and CGM supply chain disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against CADTH reimbursement recommendation patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Soft Tissue Allografts Market
Medical Devices
Global Prosthetics Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Neonatal Hearing Screening Devices Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
Global High-Flow Nasal Cannula Market
Medical Devices
Global Hydrocephalus Shunts Market
Medical Devices
Medical Puncture Navigation Robot Market
Medical Devices
Veterinary Injectable Devices Market
Medical Devices
Carotid Stenting Systems Market
Medical Devices
Vascular Guidewires Market
Medical Devices
Portable OT Light Market
Medical Devices
Global Esophageal Catheters Market
Medical Devices
Genitourinary Prosthetics Market
Medical Devices
Epistaxis Devices Market
Medical Devices
Cardiac Catheters and Guidewires Market