
 High Tibial Osteotomy (HTO) Plates Market | 2026-2036
High Tibial Osteotomy (HTO) Plates Market Size, Share, and Industry Trends Forecast 2026-2036
High Tibial Osteotomy (HTO) Plates Market Analysis
Patient-specific instrumentation and 3D-printed surgical guides is tilting preoperative planning toward digital workflows that reduce operative time and improve coronal plane accuracy. Stryker Corporation leverages its trauma and extremities infrastructure to sustain broad hospital access across North America and Europe. Zimmer Biomet Holdings anchors its position through an integrated portfolio spanning osteotomy systems to total knee platforms, enabling surgeons to transition patients across treatment stages. Arthrex specializes in arthroscopy-adjacent orthopedic solutions and competes aggressively on surgeon education and technique development.
High tibial osteotomy plates are metallic or polymer implants designed to stabilize the proximal tibia after medial opening-wedge or lateral closing-wedge osteotomy, typically manufactured from titanium alloys or stainless steel with locking screw interfaces to maintain angular correction under physiological load. These devices redistribute mechanical axis alignment to unload damaged medial compartment cartilage, delaying or eliminating the need for total knee arthroplasty in younger, active patients with unicompartmental osteoarthritis. Locking plates capture the dominant share of product type demand due to superior fixation stability in osteoporotic bone, while titanium material grades command preference over stainless steel for magnetic resonance imaging compatibility and reduced stress shielding. Hospitals remain the primary end-user channel, though ambulatory surgical centers are gaining volume as anesthesia protocols and minimally invasive techniques shorten length of stay.
The FDA's 510(k) clearance framework governs HTO plate market entry in the United States, requiring substantial equivalence demonstrations to predicate devices with documented clinical outcomes. The EU Medical Device Regulation imposes stricter post-market surveillance and clinical evaluation requirements through notified bodies, extending certification timelines and elevating documentation burdens for manufacturers. Japan's PMDA maintains distinct pharmaceutical and medical device agency review pathways that prioritize biocompatibility data and domestic clinical evidence. Stakeholders must monitor evolving reimbursement thresholds for knee-preservation procedures against accelerated arthroplasty episode-based payment models that could reshape surgeon economic incentives.
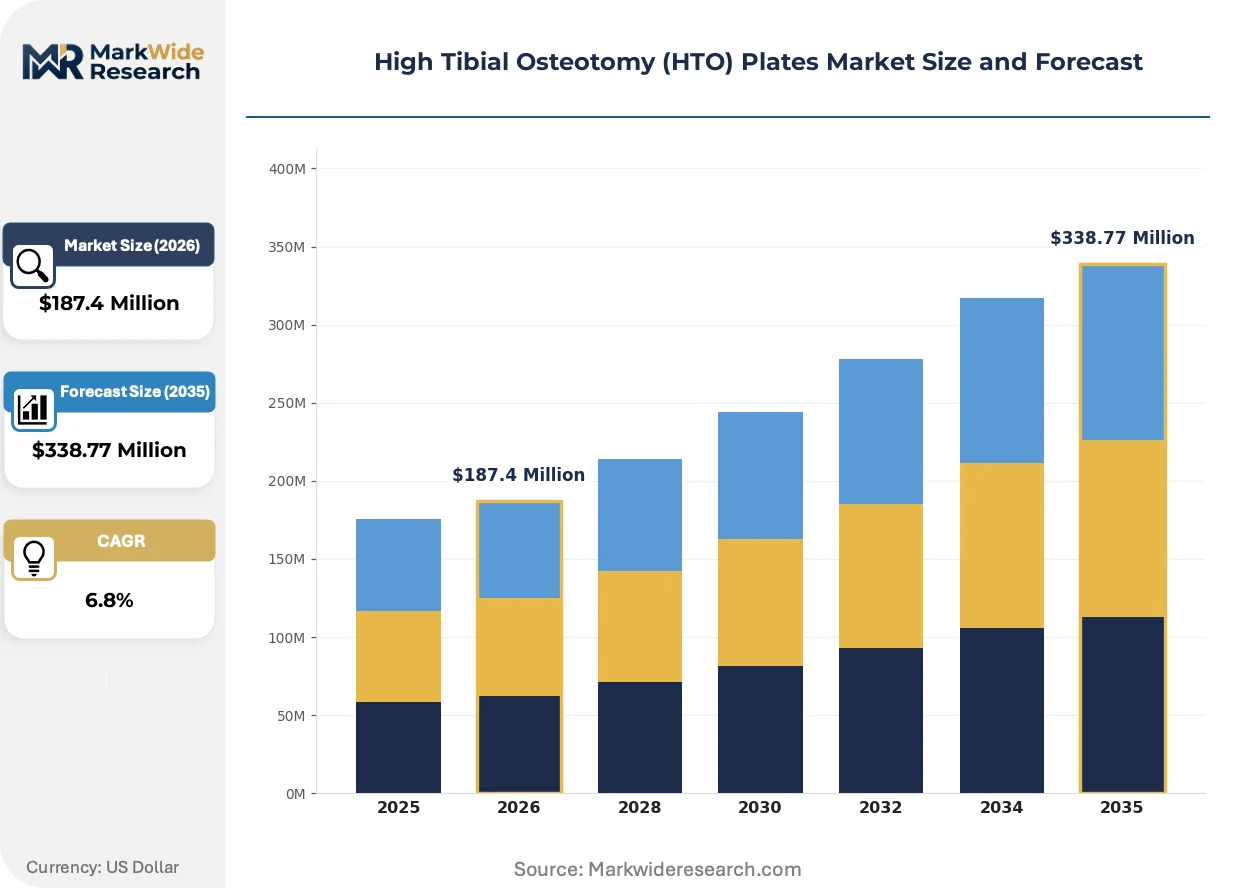
Market Dynamics
Patient-specific 3D-printed surgical guides are compressing operative planning timelines and forcing plate manufacturers to integrate digital workflows or lose hospital procurement cycles to competitors with end-to-end navigation ecosystems.
Growth Catalysts
- Japan's aging surgical protocols:Conservative knee-preservation guidelines from the Japanese Orthopaedic Association sustain osteotomy preference over arthroplasty in patients under 65, anchoring demand for locking plate systems.
- EU MDR biocompatibility mandates:Stricter post-market surveillance requirements for permanent implants are filtering out lower-tier suppliers and consolidating procurement toward manufacturers with documented clinical follow-up infrastructure.
- Titanium alloy stress-shielding reduction:Grade 5 Ti-6Al-4V plates with optimized modulus matching are capturing preference in osteoporotic bone applications where stainless steel fixation failure rates run higher.
Market Restraints
- Titanium sponge supply concentration:Russian and Ukrainian feedstock disruptions have compressed raw material availability for European plate foundries, elevating input cost volatility.
- Total knee arthroplasty substitution threat:Improved polyethylene insert durability and robotic alignment systems are narrowing the functional lifespan gap that previously justified osteotomy delay.
- EU MDR certification friction:Extended notified body timelines and elevated clinical evaluation documentation burdens are delaying new plate geometry introductions by 18-24 months.
Strategic Opportunities
- Ambulatory surgical center channel expansion:Minimally invasive osteotomy techniques and short-acting spinal anesthesia protocols are enabling same-day discharge models in Germany and the Netherlands.
- Patient-matched instrumentation convergence:Preoperative CT-to-3D-printed guide workflows are hybridizing with standard plate inventories, creating premium positioning for manufacturers with integrated digital surgical planning platforms.
- India's orthopedic infrastructure buildout:Government medical device parks in Andhra Pradesh and Tamil Nadu are offering tax incentives and streamlined CDSCO registration for implant manufacturers establishing local forging capacity.
Industry Challenges
- Surgeon education bandwidth constraints:Conversion from arthroplasty-focused training programs to osteotomy competency requires extended proctorship models that strain manufacturer clinical specialist deployment.
- Legacy PACS integration complexity:Digital surgical planning software must interface with hospital radiology archives running disparate DICOM standards, extending IT validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Tibial Osteotomy (HTO) Plates Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Locking Plates, Non-Locking Plates, Cannulated Plates, Custom Plates Material: Titanium, Stainless Steel, Bioabsorbable Polymers, Composite Materials End User: Hospitals, Orthopedic Clinics, Ambulatory Surgical Centers, Rehabilitation Centers Technology: 3D Printing, Machining, Forging, Surface Coating |
| Companies Covered | Johnson & Johnson (DePuy Synthes), Stryker Corporation, Zimmer Biomet Holdings, Inc., Smith & Nephew Plc, Arthrex, Inc., B. Braun, aap Implantate AG, Amplitude Surgical, Newclip Technics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Tibial Osteotomy (HTO) Plates Market Emerging Trajectories
Digital preoperative planning ecosystems are displacing conventional fluoroscopic alignment methods and forcing plate manufacturers to embed navigation compatibility or cede hospital contracts to integrated platform vendors.
Patient-specific 3D-printed osteotomy guides are hybridizing conventional plate fixation with computed tomography-derived cutting jigs that reduce coronal plane malalignment rates. Academic medical centers in Germany and Japan are adopting these workflows for complex multiplanar corrections. The structural consequence is compressing standalone plate suppliers into partnerships with surgical navigation firms or surgical guide specialists.
The EU Medical Device Regulation's post-market clinical follow-up requirements are extending surveillance obligations for permanent implants across 15-year lifecycles. Manufacturers must now maintain active implant registries and submit periodic safety update reports to notified bodies. High-volume plate suppliers with established European clinical affairs infrastructure are absorbing these costs while smaller competitors exit the certification pipeline.
Surgeon preference is rotating toward bundled procedure payments that combine plate, guide, and navigation system costs into single episode rates. Hospital procurement committees in the United States are consolidating vendor relationships to capture volume discounts. This compression is most visible in integrated delivery networks where orthopedic service lines negotiate enterprise-wide contracts spanning trauma, sports medicine, and joint preservation divisions.
High Tibial Osteotomy (HTO) Plates Market Segmentation
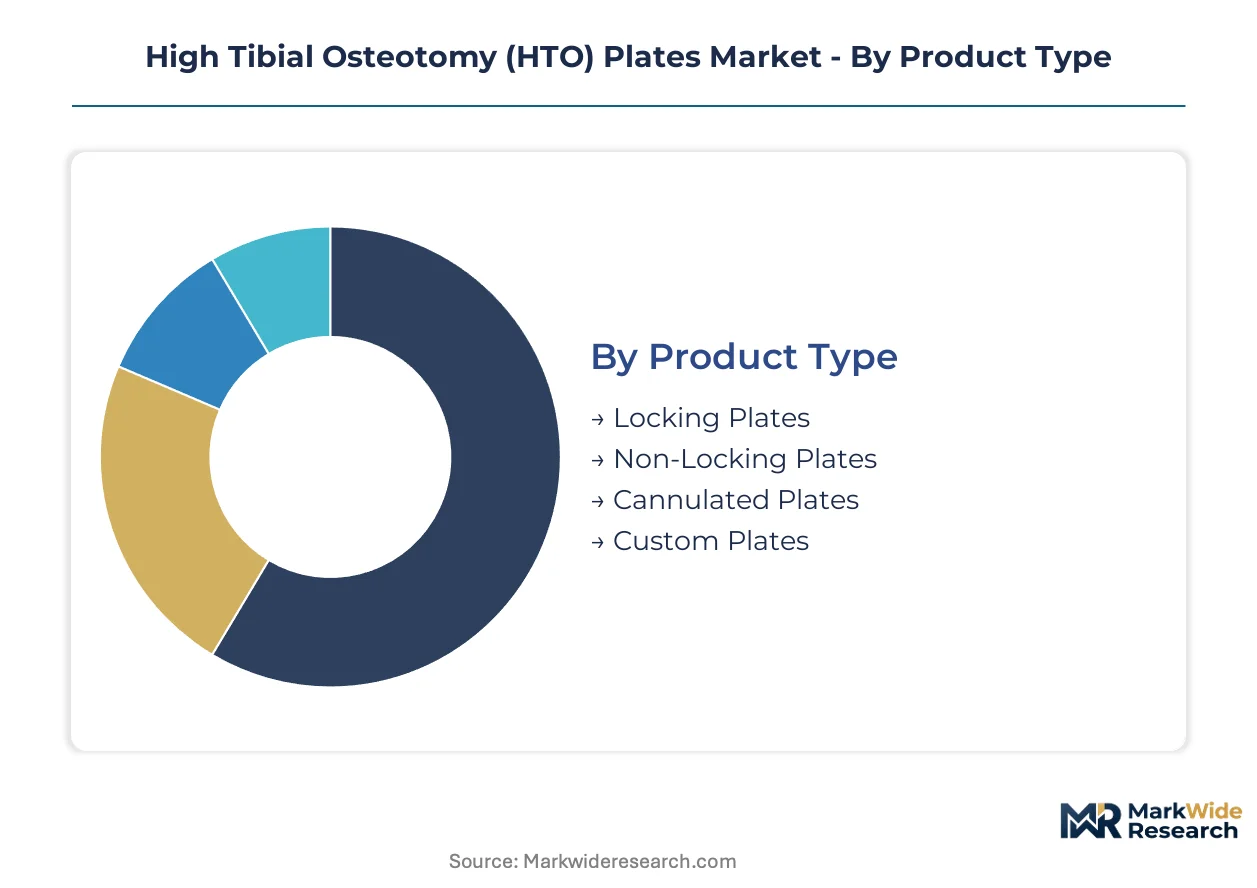
HTO plate procurement splits across four distinct axes that determine reimbursement pathways, surgical technique compatibility, and manufacturer R&D allocation. Product type and material selection drive clinical outcomes in osteoporotic bone, while end-user channel and manufacturing technology govern margin structure and competitive positioning.
Product Type:
After-sales service intensity peaks with locking plate systems due to screw inventory management, surgeon training commitments, and revision surgery support protocols.
- Locking Plates:Angular-stable constructs with threaded screw-plate interfaces maintain fixation in compromised bone. German orthopedic clinics anchor demand for these systems in early-stage osteoarthritis protocols where long-term stability determines arthroplasty delay success.
- Non-Locking Plates:Compression-dependent fixation relies on friction between plate and bone surface. Ambulatory surgical centers in the Netherlands favor these for select low-demand patients where cost compression and shorter operative time align with same-day discharge models.
- Cannulated Plates:Hollow screw designs accommodate guidewire placement for minimally invasive insertion techniques.
- Custom Plates:Patient-specific geometries derived from preoperative CT workflows address complex multiplanar deformities.
By volume, Locking Plates leads. By growth pace, Custom Plates is climbing the fastest.
Material:
Cost tier stratification separates premium titanium grades from standard stainless steel, with bioabsorbable options commanding niche positioning in younger patient cohorts.
- Titanium:Grade 5 Ti-6Al-4V alloys with optimized elastic modulus reduce stress shielding in osteoporotic proximal tibia. Japanese surgeons sustain preference for titanium HTO plates under PMDA biocompatibility protocols that prioritize MRI compatibility and long-term implant tolerance.
- Stainless Steel:316L surgical grade offers lower material cost and established forging infrastructure. European plate foundries face input volatility from Russian and Ukrainian titanium sponge disruptions, temporarily elevating stainless steel share in cost-sensitive procurement cycles.
- Bioabsorbable Polymers:PLLA and PGA composites eliminate implant removal surgery in younger active patients.
- Composite Materials:Carbon fiber-reinforced polymers bridge metallic strength with radiolucent imaging properties.
By installed base, Titanium dominates. By expansion trajectory, Bioabsorbable Polymers gains share fastest.
End User:
Application severity splits procurement between high-acuity hospital settings and volume-focused outpatient channels with divergent staffing and anesthesia protocols.
- Hospitals:Academic medical centers with residency programs maintain comprehensive HTO plate inventories across all product categories. These institutions in Germany and Japan anchor demand for complex revision cases and combined ligament reconstruction procedures.
- Orthopedic Clinics:Specialized knee preservation practices concentrate elective osteotomy volume with dedicated physical therapy integration. EU MDR post-market surveillance requirements filter supplier relationships toward manufacturers with documented clinical follow-up infrastructure.
- Ambulatory Surgical Centers:Short-acting spinal anesthesia protocols enable same-day discharge for select patients.
- Rehabilitation Centers:Postoperative bracing and early mobilization protocols influence plate selection for load-sharing requirements.
By procedure volume, Hospitals leads. By channel expansion rate, Ambulatory Surgical Centers is ahead.
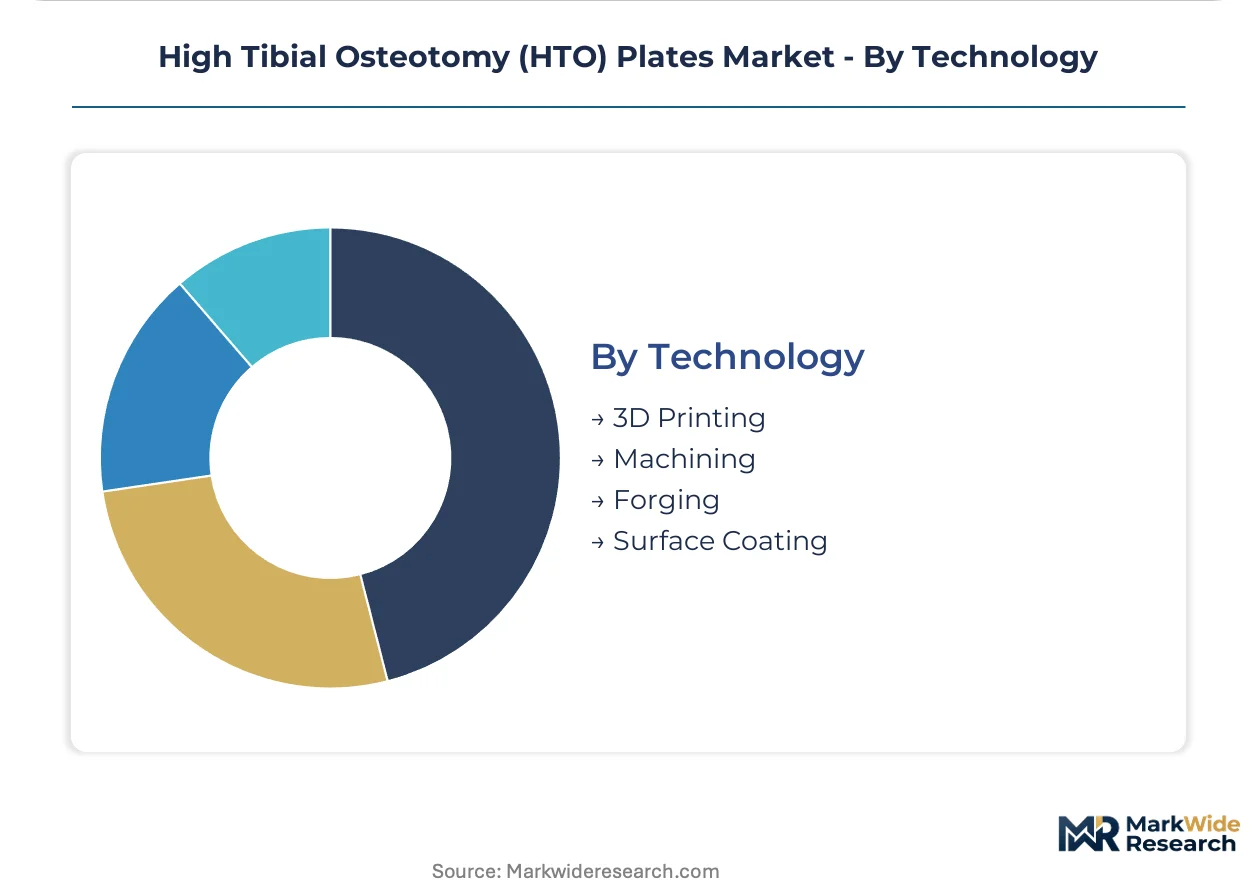
Technology:
Manufacturing maturity separates established forging operations from emerging additive production methods with distinct capital intensity and lot size economics.
- 3D Printing:Electron beam melting and selective laser sintering enable patient-specific plate geometries with optimized porosity for bone ingrowth. Academic medical centers in Japan adopt these workflows for complex multiplanar corrections where standard inventory fails.
- Machining:CNC milling from wrought titanium billet delivers tight tolerances for locking screw interfaces. Established suppliers leverage this technology for high-volume standard plate production with predictable lead times.
- Forging:Hot die forging of titanium alloys yields grain structure alignment for fatigue resistance.
- Surface Coating:Hydroxyapatite and porous titanium plasma spray enhance osseointegration kinetics.
By production volume, Machining leads. By technology investment pace, 3D Printing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orthopedic surgeons in Germany and Japan anchor procurement volume for locking plate systems, while ambulatory surgical centers in the Netherlands and specialized clinics in the United States expand same-day discharge protocols for select patient cohorts.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia drive demand for complex revision osteotomies and combined ligament reconstruction procedures. The EU Medical Device Regulation imposes stricter post-market surveillance through notified bodies, filtering supplier relationships toward manufacturers with documented clinical follow-up infrastructure. Orthopedic clinics in Berlin-Brandenburg and Hamburg are expanding HTO plate utilization for early-stage osteoarthritis patients under conservative knee-preservation protocols.
Japan
Aging demographics and conservative surgical guidelines from the Japanese Orthopaedic Association sustain osteotomy preference over arthroplasty in patients under 65. The PMDA maintains distinct review pathways prioritizing biocompatibility data and domestic clinical evidence for permanent implants. Academic medical centers in Kanto and Kansai regions adopt patient-specific 3D-printed surgical guides for complex multiplanar corrections where standard inventory geometries fail.
United States
Integrated delivery networks negotiate enterprise-wide contracts spanning orthopedic service lines, consolidating vendor relationships for volume discounts. The FDA's 510(k) clearance framework governs market entry, requiring substantial equivalence demonstrations to predicate devices with documented clinical outcomes. Ambulatory surgical centers in the Southeast and Pacific Northwest gain volume as anesthesia protocols and minimally invasive techniques shorten length of stay.
Netherlands
Specialized knee preservation practices concentrate elective osteotomy volume with dedicated physical therapy integration and same-day discharge models. Short-acting spinal anesthesia protocols enable ambulatory surgical centers in the Randstad region to compete on cost compression and operative efficiency. Orthopedic clinics favor non-locking plate systems for select low-demand patients where shorter operative time aligns with outpatient economic incentives.
India
Government medical device parks in Andhra Pradesh and Tamil Nadu offer tax incentives and streamlined CDSCO registration for implant manufacturers establishing local forging capacity. Rising orthopedic infrastructure investment supports demand for cost-sensitive stainless steel plate systems in urban hospital networks. Domestic clinical evidence requirements from the national pharmaceutical regulator shape import substitution strategies for multinational suppliers.
High Tibial Osteotomy (HTO) Plates Market Vendor Landscape
Channel-controlling players compete with product-specialist players across hospital procurement cycles and surgeon education platforms. The vendor base stratifies into three tiers: multinational orthopedic conglomerates with trauma and extremities infrastructure, mid-sized European implant specialists with regional certification depth, and emerging Asian fabricators leveraging cost-advantaged production. Consolidation pressure intensifies as integrated delivery networks demand bundled episode payments combining plates, guides, and navigation systems.
Among diversified orthopedic technology conglomerates, Stryker Corporation and Zimmer Biomet Holdings occupy positions spanning osteotomy systems to total knee platforms, enabling surgeons to transition patients across treatment stages. Arthrex exemplifies the arthroscopy-adjacent specialist archetype, competing aggressively on surgeon education and technique development. These three companies represent distinct strategic postures: Stryker leverages broad hospital access, Zimmer Biomet anchors through integrated portfolio breadth, and Arthrex concentrates on procedure-specific clinical training infrastructure.
| Leading Market Players |
|---|
| Johnson & Johnson (DePuy Synthes) |
| Stryker Corporation |
| Zimmer Biomet Holdings, Inc. |
| Smith & Nephew Plc |
| Arthrex, Inc. |
| B. Braun |
| aap Implantate AG |
| Amplitude Surgical |
| Newclip Technics |
| Others |
Supply Flow & Price Mechanics
Titanium sponge supply concentration in Russian and Ukrainian feedstock corridors compresses European plate foundry margins and forces pricing tier spreads that separate Grade 5 Ti-6Al-4V premium positioning from cost-sensitive stainless steel alternatives.
Pricing Analysis
Cost-plus contracts with London Metal Exchange titanium sponge indexation anchor procurement agreements between German orthopedic clinics and plate manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates MRI-compatible titanium systems with 15-year surveillance commitments from stainless steel alternatives favored in India's cost-sensitive hospital networks. Pricing pressure stems from total knee arthroplasty substitution as robotic alignment systems narrow the functional lifespan justification for osteotomy delay. Ambulatory surgical centers in the Netherlands exhibit highest price sensitivity due to episode-based payment compression, while Japanese academic medical centers absorb premium positioning for patient-matched instrumentation.
Supply Chain Analysis
Contract manufacturing capacity concentrates in Swiss precision machining specialists and German forging operations with established medical device quality management systems. Raw material flows draw from Ukrainian titanium sponge processors, Chinese rare earth stabilizer suppliers, and Indian stainless steel billet producers. Single-source vulnerability in Eastern European titanium feedstock exposes European plate foundries to input cost volatility following geopolitical disruptions. Distribution runs through orthopedic distributor networks with consignment inventory models at major hospital systems, supplemented by direct procurement relationships for integrated delivery networks negotiating enterprise-wide contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient-specific 3D-printed surgical guide convergence with standard plate fixation represents a technological inflection that rewards manufacturers with integrated digital surgical planning platforms.
For Market Incumbents: Harden EU MDR clinical follow-up infrastructure to absorb post-market surveillance costs that filter smaller competitors from certification pipelines. Deepen backward integration into titanium forging capacity to offset raw material volatility from Eastern European supply disruptions. Anchor hospital procurement relationships through bundled episode payments combining plates, guides, and navigation systems. For New Entrants and Emerging Players: Build out CDSCO registration pathways and local forging capacity in Andhra Pradesh and Tamil Nadu medical device parks to capture India's cost-sensitive stainless steel plate demand. Target ambulatory surgical center channels in Germany and the Netherlands with non-locking plate systems optimized for same-day discharge protocols. Differentiate through surgeon education platforms addressing osteotomy competency gaps in arthroplasty-focused training programs. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-sized European implant specialists with regional certification depth and established clinical affairs infrastructure. Long-term viability hinges on digital workflow integration capabilities spanning preoperative planning to postoperative surveillance. Watch for PMDA biocompatibility protocol evolution as signal for Japanese market access premium expansion or compression.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR notified body relationships compress 18-24 month certification timelines for new plate geometries. |
| Hospital System Partnership | Integrated delivery networks consolidate vendor relationships for bundled episode payment capture. |
| Software Companion Development | Digital surgical planning platforms embed navigation compatibility to defend procurement cycles. |
| Reimbursement Strategy | Knee-preservation procedure thresholds shape surgeon economic incentives against arthroplasty substitution. |
| Manufacturing Scale-Up | Local forging capacity in Indian medical device parks captures CDSCO registration advantages. |
Methodological Framework
A standing panel of orthopedic surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body documentation, PMDA submission records, and hospital procurement contract disclosures. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data.
Scenario-bracketing anchored projections across conservative, baseline, and accelerated adoption pathways over the analysis window. Segmentation dimensions modeled include product type, material grade, end-user channel, and manufacturing technology. CAGRs derived from logistic diffusion curves fitted to historical procedure penetration patterns, with titanium alloy modulus optimization and 3D printing adoption curves as key forecast inputs.
Practitioners should monitor EU MDR post-market surveillance cost absorption rates and PMDA biocompatibility protocol amendments for early signals of competitive filtering intensity. Forecasts embed assumptions regarding arthroplasty substitution pace and ambulatory surgical center anesthesia protocol diffusion. Quarterly review of titanium sponge price indices and notified body certification queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
Global Urinary Incontinence Treatment Devices Market
Medical Devices
South Africa Artificial Organs and Bionic Implants Market
Medical Devices
Global Embolic Protection Device Market
Medical Devices
Germany Spinal Surgery Devices Market
Medical Devices
Europe Invisible Orthodontics Market
Medical Devices
Chile Respiratory Devices Market
Medical Devices
Solar Surgical Light Market
Medical Devices
Brazil Cardiac Pacemakers Market
Medical Devices
Saudi Arabia Anesthesia Devices Market
Medical Devices
Body Contouring Devices and Procedures Market
Medical Devices
Computer Assisted Surgical (CAS) Systems Market
Medical Devices
Lacrimal Dilator Market
Medical Devices
Breast Prosthesis Market
Medical Devices
Clinical Rollators Market
Medical Devices
Pelvic Floor Electrical Stimulation Devices Market