
 Europe Organic Fertilizer Market | 2026-2036
Europe Organic Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Organic Fertilizer Market Insights
Agricultural store networks across southern Europe is narrowing as distributor consolidation favors volume suppliers with direct farm relationships. Fertikal N.V. leverages its Belgian production base to dominate Benelux horticulture channels. Koppert Biological Systems BV sustains dual positioning across biological crop protection and organic nutrition, extending its advisory-led sales model into Spain and Portugal. Novonesis Group anchors microbial inoculant supply for premium vineyard and orchard segments where biological efficacy commands price premiums.
Europe organic fertilizer comprises nutrient-bearing materials derived from plant, animal, or mineral origins with minimum 30% organic carbon content, processed through composting, fermentation, or enzymatic digestion to release nitrogen, phosphorus, and potassium in plant-available forms. Composted manure leads volume across broad-acre cereal rotations where cost-per-hectare governs procurement, while seaweed extract captures margin concentration in high-value greenhouse tomato and pepper operations demanding stress tolerance and trace element bioavailability. Bone meal retains steady demand in French viticulture for phosphorous supplementation during pre-flowering stages, though supply fluctuates with rendering industry output cycles.
The EU Green Deal and Farm to Fork Strategy mandate 50% synthetic fertilizer reduction targets, compelling national agriculture ministries to expand organic input subsidy eligibility. ECHA bio-based substance registration requirements under REACH create compliance barriers for imported formulations, advantaging European manufacturers with established dossier portfolios. Stakeholders must monitor CAP strategic plan implementation timelines across member states, as payment scheme designs determine farmer switching economics between conventional and organic nutrient regimes.
Market Dynamics
The EU Green Deal's synthetic nitrogen reduction mandates are compressing farmer switching economics, redirecting procurement toward certified organic inputs across nitrate-vulnerable zones in northern Italy, the Netherlands, and Denmark.
Growth Catalysts
- Farm to Fork Strategy:The EU's 50% synthetic fertilizer reduction target compels national agriculture ministries to expand organic input subsidy eligibility, accelerating certified product procurement timelines.
- Seaweed extract adoption:Greenhouse tomato and pepper operations in Almería and Sicily demand stress tolerance formulations with enhanced trace element bioavailability, creating pull-through for premium organic nutrition.
- Po Valley concentration:Intensive horticulture clusters in Emilia-Romagna converge with strict nitrate-vulnerable zone designations, generating localized demand density for composted manure and microbial inoculants.
Market Restraints
- Bone meal supply volatility:Rendering industry output cycles in France and Spain create phosphorous input instability, disrupting vineyard pre-flowering supplementation schedules.
- ECHA registration barriers:REACH bio-based substance dossier requirements disadvantage imported formulations, limiting supplier diversity for specialty crop growers.
- Composted manure logistics:Low value-to-weight ratios constrain economically viable transport radii beyond 150 kilometers from production facilities in Benelux and northern Germany.
Strategic Opportunities
- Portuguese vineyard conversion:Underpenetrated Douro Valley acreage presents white space for advisory-led biological nutrition services as growers transition from conventional viticulture.
- CAP strategic plan alignment:Member state payment scheme redesigns in Poland and Romania create regulatory tailwinds for first-time organic nutrient adopters in broad-acre cereal rotations.
- Microbial-enzymatic convergence:Fermentation-derived biofertilizers combining nitrogen-fixing bacteria with enzymatic digestion unlock premium positioning in orchard segments where biological efficacy commands price premiums.
Industry Challenges
- Carbon accounting expertise gap:Farm advisors lack standardized training in soil organic carbon measurement protocols, slowing farmer confidence in input switching decisions.
- Certification timeline compression:EU organic regulation compliance audits create 18-24 month product approval windows, constraining formulation innovation cycles.
- Legacy equipment incompatibility:Conventional spreader calibration for synthetic granules requires reconfiguration for heterogeneous organic matter, generating mechanical integration friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Organic Fertilizer Market |
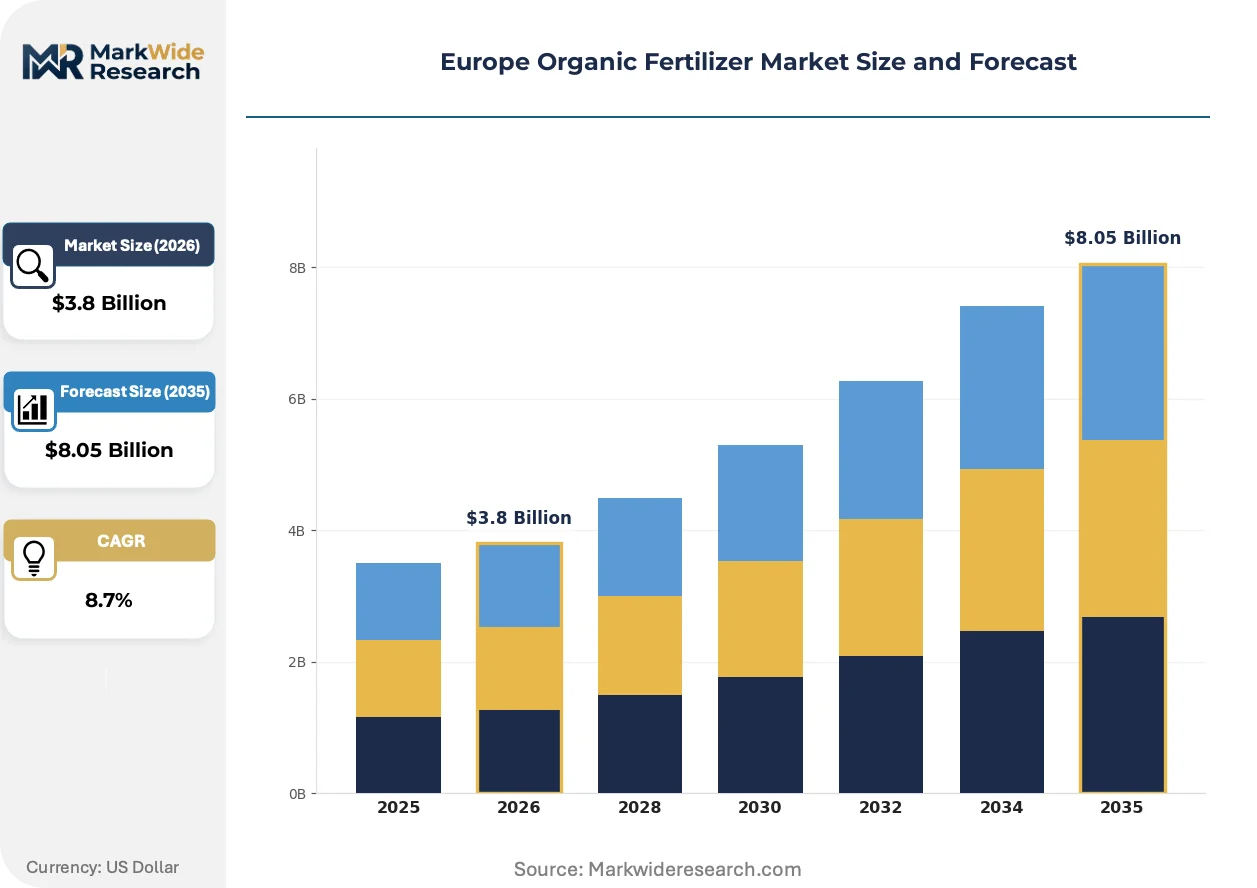
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composted Manure, Green Manure, Bone Meal, Seaweed Extract Application: Agriculture, Horticulture, Turf, Landscaping End User: Farmers, Gardeners, Landscape Professionals, Institutions Distribution Channel: Online Retail, Agricultural Stores, Garden Centers, Distributors |
| Companies Covered | Fertikal N.V., Koppert Biological Systems BV, BIOLCHIM, Novonesis Group, Hello Nature International Srl, Italpollina SpA, RovensaNext, Andermatt Group AG, ILSA S.p.A, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Organic Fertilizer Market Trends and Innovations
Biological efficacy verification is displacing cost-per-hectare as the primary procurement criterion across high-value cropping systems, reshaping competitive positioning toward advisory-intensive service models.
Enzymatic digestion technology is hybridizing traditional composting with controlled fermentation, accelerating nitrogen mineralization rates while preserving microbial diversity. Premium vineyard and orchard operators in Bordeaux and Tuscany adopt these hybrid formulations within 24-month switching windows. The technology is compressing the performance gap between organic and synthetic nutrient release curves, enabling substitution in previously inaccessible growth stages.
REACH bio-based substance registration requirements under ECHA oversight are tightening import formulation compliance thresholds, advantaging European manufacturers with established dossier portfolios. National agriculture ministries in Germany and France now mandate third-party biological efficacy certification for subsidy eligibility. Specialty crop segments in protected horticulture absorb these compliance costs most readily, passing premiums through contract pricing structures.
Direct farm relationships are displacing agricultural store networks as the dominant distribution channel across southern Europe. Volume suppliers with embedded agronomist teams capture switching growers in Spain's Murcia region and Italy's Puglia. This channel compression concentrates procurement decision-making among fewer buyer interfaces, elevating technical advisory capability as a competitive differentiator.
Europe Organic Fertilizer Market Segmentation
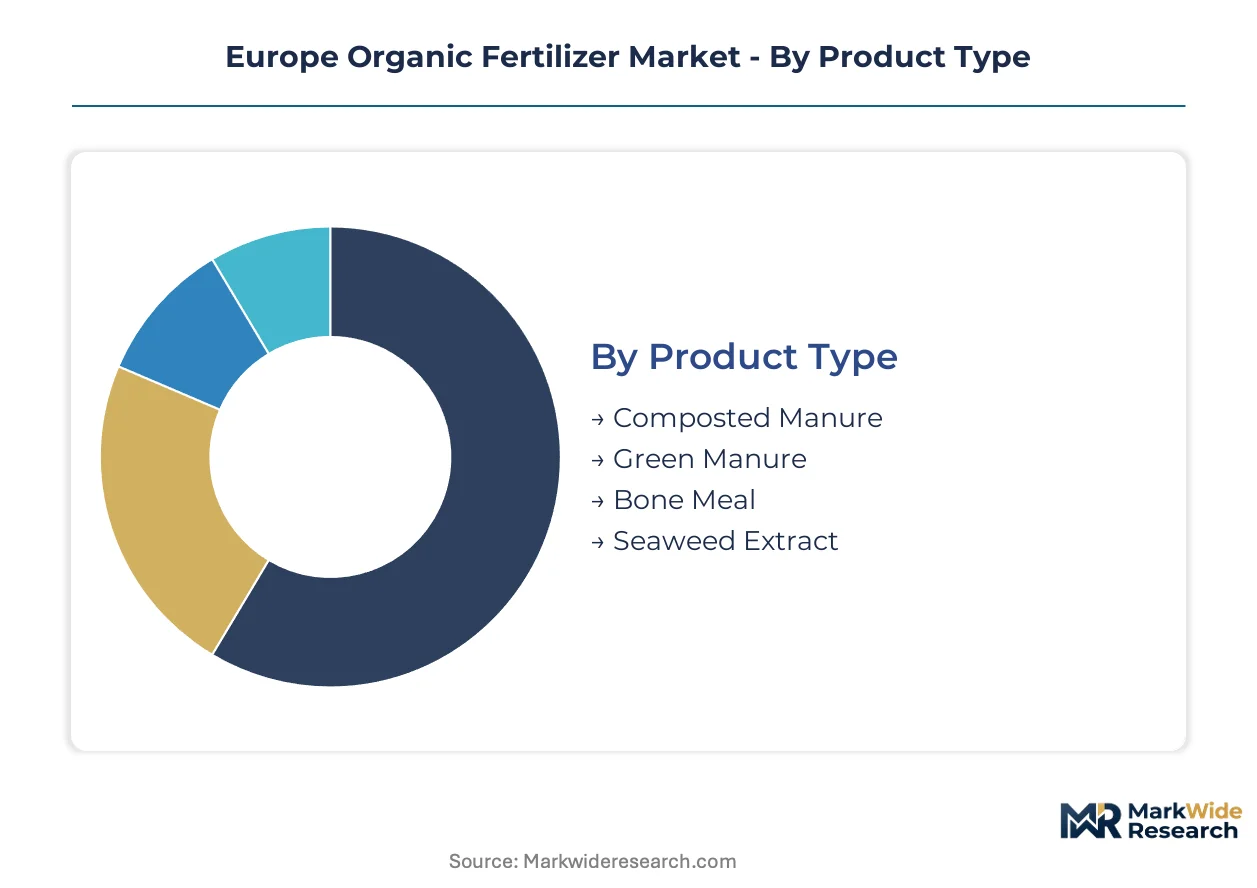
Segmentation in Europe's organic fertilizer market reflects divergent procurement logics across commodity broad-acre systems and precision-driven specialty operations. Input selection varies sharply by crop value intensity, regulatory exposure, and equipment compatibility requirements.
Product Type:
Mature composting technologies dominate volume flows, while enzymatic fermentation unlocks premium positioning in high-value segments.
- Composted Manure:Anaerobically digested livestock waste with 30-50% organic carbon content serves as the baseline input for cereal rotations across northern Germany and Poland. Cost-per-hectare procurement in broad-acre systems limits transport radii to 150 kilometers from production facilities.
- Seaweed Extract:Laminaria and Ascophyllum-derived formulations with cytokinin and auxin bioactives command price premiums in Almería greenhouse operations. Stress tolerance and trace element bioavailability drive adoption in tomato and pepper protected horticulture.
- Green Manure:Leguminous cover crop incorporation supplies nitrogen fixation in organic cereal rotations across Denmark and Sweden.
- Bone Meal:Rendered animal byproduct phosphorous source faces supply volatility from French and Spanish rendering industry cycles.
Composted manure handles the majority of throughput; seaweed extract is expanding most quickly on share.
Application:
Cost tier stratification separates commodity field systems from margin-intensive protected operations with divergent input specifications.
- Agriculture:Broad-acre cereal and oilseed rotations across France and Germany absorb standardized composted manure at volume scale. EU Green Deal synthetic nitrogen reduction mandates redirect procurement toward certified organic inputs in nitrate-vulnerable zones.
- Horticulture:Intensive vegetable and fruit production in Italy's Po Valley and Spain's Murcia region demands precision-formulated organic nutrition with documented biological efficacy.
- Turf:Golf course and sports pitch maintenance in the UK and Ireland drives seasonal demand for low-odor, homogeneous granular formulations.
- Landscaping:Municipal and commercial green space management across Benelux urban corridors prioritizes visual acceptability and rapid establishment.
Agriculture absorbs the greatest tonnage; horticulture generates the steepest margin expansion trajectory.
End User:
Customer type determines advisory intensity and switching economics across the procurement spectrum.
- Farmers:Commercial agricultural operations in Emilia-Romagna and Andalusia drive certified organic input demand with subsidy-dependent procurement timelines.
- Gardeners:Amateur cultivation in UK suburban markets sustains retail-packaged specialty formulations with convenience-driven purchasing.
- Landscape Professionals:Contract maintenance firms across German metropolitan regions require consistent product availability and bulk logistics.
- Institutions:Municipal parks departments and university agricultural research stations in the Netherlands specify third-party certified inputs for compliance documentation.
Farmers represent the dominant demand base; landscape professionals are climbing the fastest in procurement sophistication.
Distribution Channel:
Supply concentration is compressing traditional retail networks toward direct farm relationships with embedded technical service.
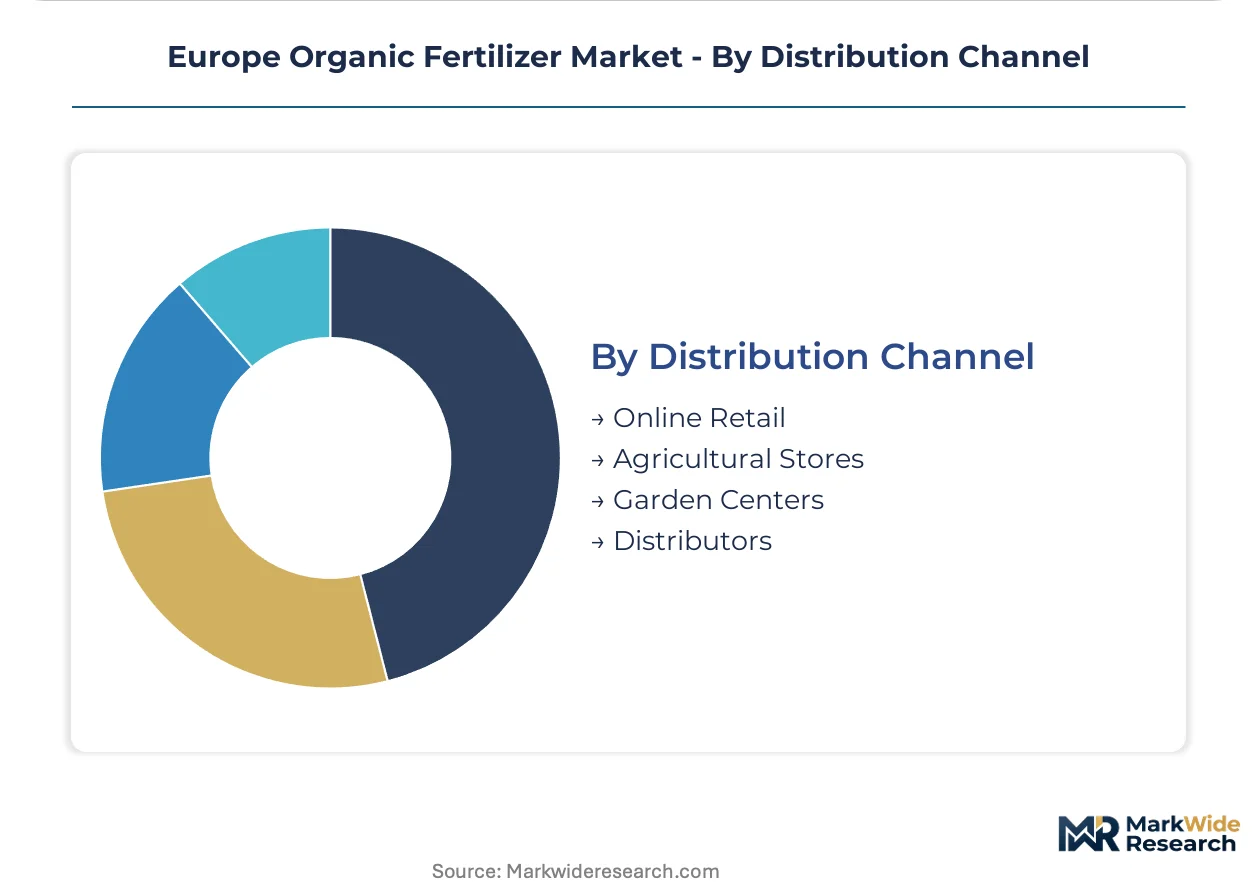
- Agricultural Stores:Consolidating southern European networks favor volume suppliers with direct farm relationships over independent retailers.
- Distributors:Belgian and Dutch horticulture channels remain anchored by producers with integrated logistics and agronomist field teams.
- Online Retail:UK and German amateur gardening segments absorb packaged specialty formulations through e-commerce platforms with subscription replenishment models.
- Garden Centers:French and Italian retail garden networks sustain seasonal demand peaks for consumer-scale organic nutrition products.
Distributors retain the largest commercial throughput; online retail is gaining share fastest in consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine rail corridor and Rotterdam-Antwerp port complex underwrite bulk organic fertilizer flows into northwestern Europe, connecting Benelux production basins to German and French demand centers.
Germany
Anaerobic digestion facilities in Lower Saxony supply composted manure to cereal rotations across the North German Plain. The Federal Ministry of Food and Agriculture channels CAP subsidies toward organic nutrient adoption in nitrate-vulnerable zones. The Emsland cluster concentrates biogas-to-fertilizer processing capacity serving Dutch and Danish cross-border procurement.
France
Bordeaux vineyard operators drive bone meal demand for pre-flowering phosphorous supplementation. ANSM and regional prefectures enforce EU Green Deal synthetic nitrogen limits in Brittany dairy regions. The Grand Est corridor links German compost producers to Alsatian vegetable growers through integrated logistics networks.
Italy
Po Valley horticulture in Emilia-Romagna generates concentrated demand for microbial inoculants and enzymatic digestates. The Ministry of Agricultural, Food and Forestry Policies aligns national CAP strategic plans with Farm to Fork fertilizer reduction targets. Sicily's greenhouse belt around Ragusa pulls seaweed extract formulations for stress-tolerant tomato and pepper production.
Spain
Almería's protected horticulture sector absorbs premium organic nutrition for export-oriented vegetable operations. Regional governments in Andalusia and Murcia administer organic conversion subsidies under revised CAP implementation timelines. The Segura River basin integrates composted manure from livestock operations into citrus orchard rotations.
Netherlands
Intensive greenhouse complexes in Westland and Aalsmeer specify certified organic inputs for compliance with supermarket sustainability protocols. The Dutch Ministry of Agriculture, Nature and Food Quality mandates third-party biological efficacy certification for subsidy eligibility. The Port of Rotterdam handles imported seaweed extract and microbial formulations for redistribution across Benelux and German markets.
Europe Organic Fertilizer Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The European organic fertilizer market structures around three tiers: volume producers with captive raw material supply, advisory-intensive biological specialists, and imported formulation distributors. Strategic archetypes include anaerobic digestion operators leveraging waste-to-nutrient vertical integration, fermentation technology licensors, and horticulture channel specialists embedding agronomist field teams. Competitive moves concentrate on distributor consolidation in southern Europe and enzymatic digestion capacity expansion for premium vineyard and orchard segments.
Within the advisory-led biological tier, Koppert Biological Systems BV and Novonesis Group exemplify dual-positioning strategies spanning crop protection and organic nutrition. Fertikal N.V. anchors the Benelux volume segment through integrated production and direct farm relationships. These three occupy positions reflecting divergent geographic and technological bets: Dutch-Belgian horticulture channel control, microbial inoculant premium positioning, and anaerobic digestion scale economics respectively.
| Leading Market Players |
|---|
| Fertikal N.V. |
| Koppert Biological Systems BV |
| BIOLCHIM |
| Novonesis Group |
| Hello Nature International Srl |
| Italpollina SpA |
| RovensaNext |
| Andermatt Group AG |
| ILSA S.p.A |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Alpine rail corridor's bulk freight economics compress transport radii for low value-to-weight organic inputs, concentrating supply-side pricing power among Benelux anaerobic digestion operators while forcing downstream differentiation through certification tiering and advisory bundling.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts across broad-acre cereal rotations in northern Germany and Poland, with composted manure pricing stratifying across premium certified organic, standard farm-grade, and economy bulk tiers. Price differentiation rests on EU organic regulation compliance status and embedded agronomist advisory hours rather than raw nutrient content alone. Cost compression in economy tiers intensifies as distributor consolidation in southern Spain and Portugal squeezes independent retailer margins. Specialty crop growers in Italy's Po Valley exhibit lowest price sensitivity, absorbing premium enzymatic digestate pricing for documented biological efficacy in nitrate-vulnerable zones.
Supply Chain Analysis
Upstream feedstock availability draws from livestock rendering cycles in France, anaerobic digestion output in Belgium and the Netherlands, and imported seaweed biomass through Rotterdam port facilities. Raw material dependencies include phosphorous-rich bone meal from French abattoirs, nitrogen-dense poultry litter from concentrated animal feeding operations in northern Italy, and laminaria seaweed harvested from North Atlantic coastlines. Single-source vulnerability permeates bone meal supply chains where rendering industry output fluctuations disrupt vineyard pre-flowering supplementation schedules. Distribution runs through direct farm relationships with embedded agronomist teams, displacing traditional agricultural store networks across Spain's Murcia region and Portugal's Alentejo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's synthetic nitrogen reduction mandates constitute a structural inflection, compressing farmer switching economics and opening acquisition opportunities for biological efficacy specialists with established REACH dossier portfolios.
For Market Incumbents: Harden advisory-led service capabilities against distributor consolidation threats in southern Europe by embedding agronomist field teams directly with switching growers in Spain and Portugal. Expand enzymatic digestion capacity in Benelux production basins to capture premium vineyard and orchard demand in Bordeaux and Tuscany. Secure captive supply of rendering industry phosphorous outputs through long-term offtake agreements with French and Spanish abattoir networks.
For New Entrants and Emerging Players: Portugal's Douro Valley vineyard acreage offers white-space penetration for advisory-intensive biological nutrition services as growers transition from conventional viticulture. Poland's broad-acre cereal rotations under revised CAP strategic plans present subsidy-dependent procurement entry points for first-time organic nutrient adopters. Pursue microbial-enzymatic convergence formulations targeting orchard segments where biological efficacy commands price premiums, leveraging third-party certification for subsidy eligibility.
For Investors and Strategic Acquirers: The EU Green Deal's 50% synthetic fertilizer reduction target reshapes the acquisition landscape toward European manufacturers with established ECHA bio-based substance dossiers and integrated anaerobic digestion assets. Long-term viability centers on platform integrators spanning crop protection and organic nutrition with direct farm channel control. Monitor CAP strategic plan implementation timelines across member states as the primary inflection signal for farmer switching economics acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Digestion Capacity Expansion | Compresses performance gaps between organic and synthetic nutrient release curves for vineyard substitution. |
| Backward Integration into Rendering Feedstock | Secures phosphorous supply stability against French and Spanish abattoir output cycle volatility. |
| Direct Farm Relationship Cultivation | Displaces agricultural store networks in Spain's Murcia region with embedded agronomist teams. |
| Third-Party Biological Efficacy Certification | Unlocks Dutch and German subsidy eligibility under national agriculture ministry mandates. |
| Microbial-Inoculant Premium Positioning | Captures price premiums in Po Valley horticulture where stress tolerance formulations command margin. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, engaging farm advisors in Emilia-Romagna, procurement managers at Dutch greenhouse cooperatives, technical directors at Belgian anaerobic digestion facilities, and regulatory affairs specialists navigating ECHA REACH compliance. Secondary validation incorporated EU CAP strategic plan documentation, ECHA bio-based substance registration databases, national agriculture ministry subsidy scheme filings, and Benelux customs trade flow records. Bottom-up farmer procurement intention surveys triangulated against top-down production capacity assessments across the analysis window.
Calibration approaches anchored volume projections to anaerobic digestion facility throughput disclosures and seaweed extract import manifests through Rotterdam-Antwerp port complexes, with value outputs reflecting pricing stratification across premium certified, standard farm-grade, and economy bulk tiers. Segmentation dimensions spanned product type, application intensity, end-user procurement sophistication, and distribution channel concentration. CAGRs derived from regression modeling against EU Green Deal implementation trajectory assumptions and CAP payment scheme redesign timelines.
Practitioners should monitor ECHA registration backlog processing speeds and member state organic conversion subsidy uptake rates for early signals of forecast revision triggers. Cross-checking against national agriculture ministry fertilizer consumption statistics and third-party organic certification body acreage reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Chelated Micronutrient Fertilizers Market
Fertilizers
Malaysia NPK Fertilizer Market
Fertilizers
Boron Fertilizers Market
Fertilizers
US Seaweed Fertilizers Market
Fertilizers
France Fertilizer Market
Fertilizers
Russia Specialty Fertilizer Market
Fertilizers
Slow Release NPK Fertilizer Market
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
GCC Fertilizer Market
Fertilizers
Sulfur Fertilizer Market
Fertilizers
Middle East and Africa Specialty Fertilizer Market
Fertilizers
India Micronutrient Fertilizer Market
Fertilizers
Middle East and Africa Micronutrient Fertilizer Market
Fertilizers
Global Specialty Fertilizer Market
Fertilizers
China Specialty Fertilizer Market
Fertilizers
Global Controlled Release Fertilizer Market