
 China Micronutrient Fertilizer Market | 2026-2036
China Micronutrient Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
China Micronutrient Fertilizer Market Outlook
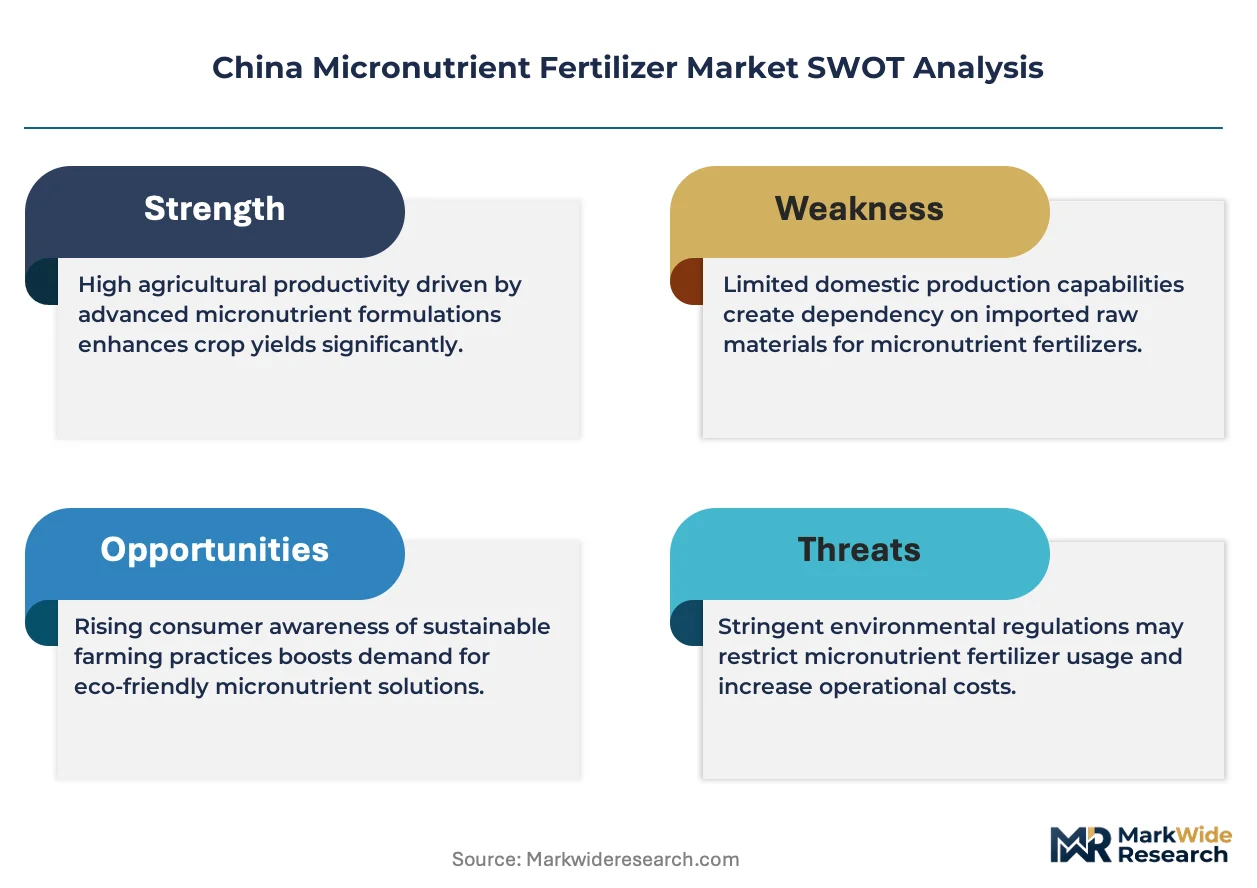
China's updated fertilizer registration rules under the Ministry of Agriculture and Rural Affairs is decoupling market access from legacy product portfolios, forcing manufacturers to recertify formulations against stricter purity benchmarks. Sinochem leverages its state-backed distribution network to sustain volume leadership across provincial agricultural supply cooperatives. Kingenta Ecological Engineering Group anchors its position through backward integration into amino acid chelate production. Hubei Xinyangfeng Fertilizer competes on manufacturing scale, operating one of China's largest integrated NPK-micronutrient compounding facilities.
China micronutrient fertilizer refers to inorganic or organically complexed trace element preparations containing iron, manganese, zinc, copper, boron, molybdenum, or chlorine at concentrations typically below one percent by weight, manufactured through acidulation, chelation with EDTA or lignosulfonates, or dissolution in liquid carriers for precise crop delivery. These inputs correct latent deficiencies in intensively farmed soils, preventing yield loss in high-value horticulture and quality degradation in export-oriented fruit production. Chelated micronutrients command premium positioning due to superior bioavailability in alkaline soils, while liquid micronutrients represent the fastest-expanding application format as fertigation systems penetrate Shandong and Xinjiang greenhouse clusters. Non-chelated micronutrients remain the volume baseline for broad-acre cereals, though margin compression from sulfur and metal feedstock volatility limits producer profitability in this segment.
China's Ministry of Agriculture and Rural Affairs, the National Agricultural Technology Extension Service Center, and GB standard-setting committees under the Standardization Administration collectively govern product registration, field trial requirements, and maximum permissible heavy metal limits in micronutrient formulations. MEE environmental compliance audits now extend to fertilizer manufacturing effluent, adding capital requirements for acid recovery and wastewater treatment systems. Stakeholders must monitor the convergence of soil health mapping initiatives with precision agriculture subsidies, as this policy alignment will determine which micronutrient delivery formats receive preferential procurement status in provincial extension programs.
Market Dynamics
China's Ministry of Agriculture zero-growth chemical fertilizer action plan is decoupling market access from legacy product portfolios, forcing manufacturers to recertify formulations against stricter GB purity benchmarks for water-soluble fertilizers.
Growth Catalysts
- Greenhouse horticulture expansion:Specialty vegetable cultivation in Shandong and Yunnan provinces is expanding micronutrient application rates for high-value crops.
- GB standard modernization:Updated water-soluble fertilizer standards are tightening product registration requirements and elevating quality benchmarks across the sector.
- Chelate technology penetration:Amino acid and EDTA chelation processes are improving bioavailability in alkaline soils prevalent across northern China.
Market Restraints
- Feedstock cost volatility:Sulfur and metal input price swings compress margins for non-chelated micronutrient producers serving broad-acre cereal markets.
- Distribution concentration:State-backed agricultural supply cooperatives dominate provincial channels, limiting independent manufacturer market access.
- Soil heterogeneity:Latent deficiency patterns vary sharply across loess plateaus versus southern paddy systems, complicating standardized formulation strategies.
Strategic Opportunities
- Xinjiang greenhouse clusters:Liquid micronutrient formats for fertigation systems are penetrating this underdeveloped region's protected agriculture infrastructure.
- Precision agriculture alignment:Soil health mapping initiatives converging with provincial extension subsidies will determine preferential procurement status for specific delivery formats.
- Environmental compliance services:MEE wastewater treatment and acid recovery system mandates create ancillary revenue streams for technology providers.
Industry Challenges
- Recertification timeline compression:Ministry of Agriculture and Rural Affairs field trial requirements are extending product registration cycles for reformulated chelates.
- Technical talent scarcity:Formulation chemists with expertise in lignosulfonate and amino acid complexation command premium compensation in a shallow labor pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Micronutrient Fertilizer Market |
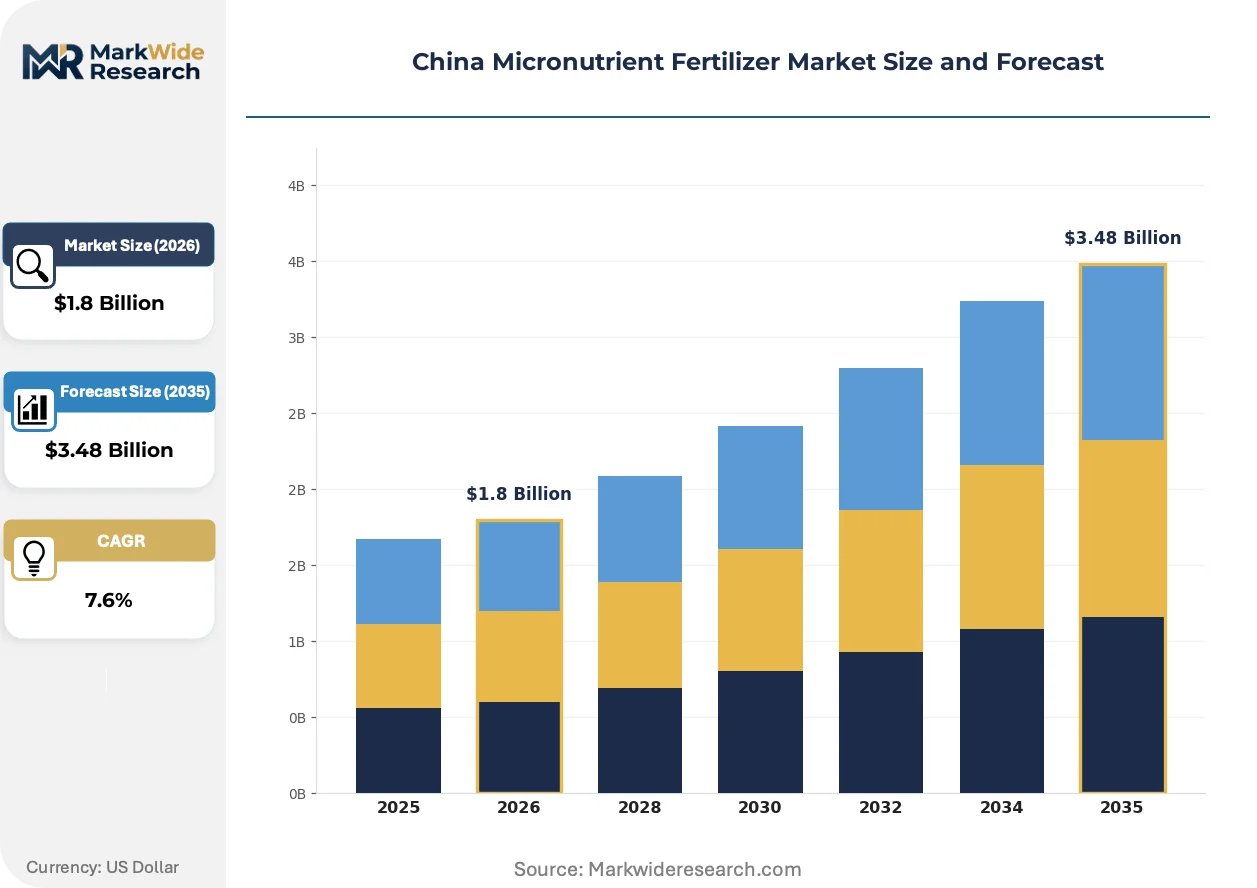
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chelated Micronutrients, Non-Chelated Micronutrients, Complex Micronutrient Fertilizers, Liquid Micronutrients Application Method: Fertigation, Foliar Application, Soil Application, Seed Treatment Crop Type: Cereals, Fruits, Vegetables, Oilseeds Distribution Channel: Direct Sales, Wholesale Distributors, Retail Stores, Online Platforms |
| Companies Covered | Hubei Xinyangfeng Fertilizer Co., Ltd., Hebei Monband Water Soluble Fertilizer Co. Ltd., Sinochem, Shandong Huibaichuan New Materials Co., Ltd., Sinofert, ChemChina, Kingenta Ecological Engineering Group Co., Ltd., Shenyang MASL Biotechnology Co., Ltd., Yuntianhua Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Micronutrient Fertilizer Market Strategic Shifts
Formulation chemistry and delivery system design are absorbing capital allocation as manufacturers differentiate beyond commodity sulfate salts. Three developments are restructuring competitive positioning.
Amino acid chelation is absorbing technical investment from producers seeking differentiation in alkaline soil zones. Shandong and Yunnan greenhouse operators are adopting these formulations for high-value vegetable crops at accelerating rates. This technology is absorbing margin pressure from sulfur feedstock volatility by commanding premium positioning over inorganic alternatives.
GB standard updates under the Standardization Administration are tightening heavy metal limits and dissolution specifications for water-soluble fertilizers. Manufacturers must retrofit acidulation lines or exit the premium tier entirely. Chelated micronutrient categories face the steepest compliance costs, driving consolidation among small-scale compounders.
Buyer concentration among provincial agricultural supply cooperatives is consolidating procurement authority and compressing supplier margins. Direct manufacturer relationships with large greenhouse operators in Xinjiang are displacing traditional distributor channels. This pattern is most visible in liquid micronutrient segments where technical service requirements favor integrated supply arrangements.
China Micronutrient Fertilizer Market Segmentation
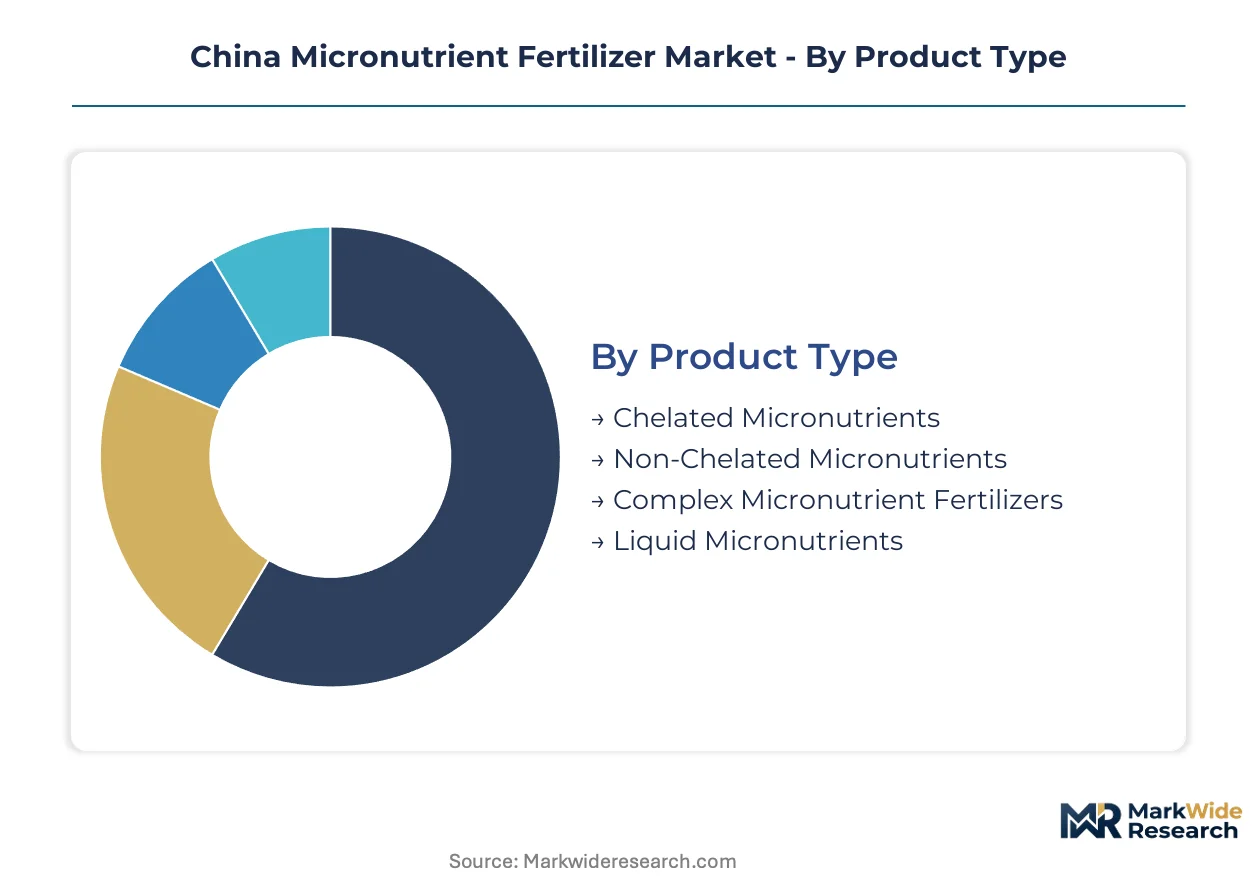
Micronutrient fertilizer segmentation in China reflects divergent technical requirements across soil conditions, crop value tiers, and application infrastructure maturity. Manufacturers configure product portfolios around chelation chemistry, delivery format, and channel access rather than pursuing undifferentiated coverage.
Product Type:
Chelated formulations integrate into precision agriculture systems as standalone inputs, while non-chelated variants typically embed within compound fertilizer programs for broad-acre deployment.
- Chelated Micronutrients:Iron, zinc, and manganese complexed with EDTA, EDDHA, or amino acids deliver stable nutrient availability in alkaline soils exceeding pH 7.5 across northern China. Shandong greenhouse operators prioritize these formulations for tomato and cucumber cultivation where deficiency correction timing is critical.
- Liquid Micronutrients:Dissolved sulfate and chloride salts in aqueous carriers enable fertigation compatibility with drip systems penetrating Xinjiang protected agriculture clusters. Technical service requirements favor integrated supply arrangements with large greenhouse operators displacing traditional distributor channels.
- Non-Chelated Micronutrients:Inorganic sulfate salts serve as volume baseline for wheat and maize production on neutral to acidic soils.
- Complex Micronutrient Fertilizers:Multi-element blends address poly-deficiency patterns identified through provincial soil health mapping initiatives.
Non-chelated micronutrients lead volumes today; liquid micronutrients are gaining share fastest.
Application Method:
Cost tier differentiation separates high-infrastructure fertigation from low-capital foliar and soil application methods.
- Fertigation:Liquid micronutrient injection through drip irrigation systems achieves uniform distribution and labor efficiency in Shandong and Xinjiang greenhouse complexes. Provincial precision agriculture subsidies accelerate infrastructure deployment, though upfront capital requirements exclude smaller operations.
- Foliar Application:Aerial or ground-based spraying delivers rapid deficiency correction during critical growth stages for high-value fruit crops. Yunnan citrus and grape producers deploy this method where soil fixation risks compromise root uptake efficiency.
- Soil Application:Granular or powder incorporation remains dominant for cereal production with lower per-hectare input budgets.
- Seed Treatment:Micronutrient coating of planting material addresses early-stage deficiency in germination-sensitive oilseed crops.
Soil application retains the largest installed base; fertigation demonstrates the steepest expansion trajectory.
Crop Type:
Customer type segmentation aligns micronutrient specification intensity with crop value realization and export orientation.
- Vegetables:Greenhouse tomato, cucumber, and pepper production in Shandong and Yunnan commands premium chelated formulations with documented heavy metal compliance for export certification. Ministry of Agriculture zero-growth chemical fertilizer mandates intensify micronutrient substitution rates in these high-input systems.
- Fruits:Apple, citrus, and grape cultivation for domestic premium and export markets requires precise boron and zinc management to prevent quality degradation. Xinjiang's emerging protected fruit sector drives liquid formulation demand.
- Cereals:Wheat and maize production across the North China Plain utilizes non-chelated micronutrients as compound fertilizer additives.
- Oilseeds:Rapeseed and soybean cultivation in the Yangtze River basin addresses molybdenum and boron requirements for nitrogen fixation efficiency.
Cereals dominate tonnage consumption; vegetables command the highest value per hectare.
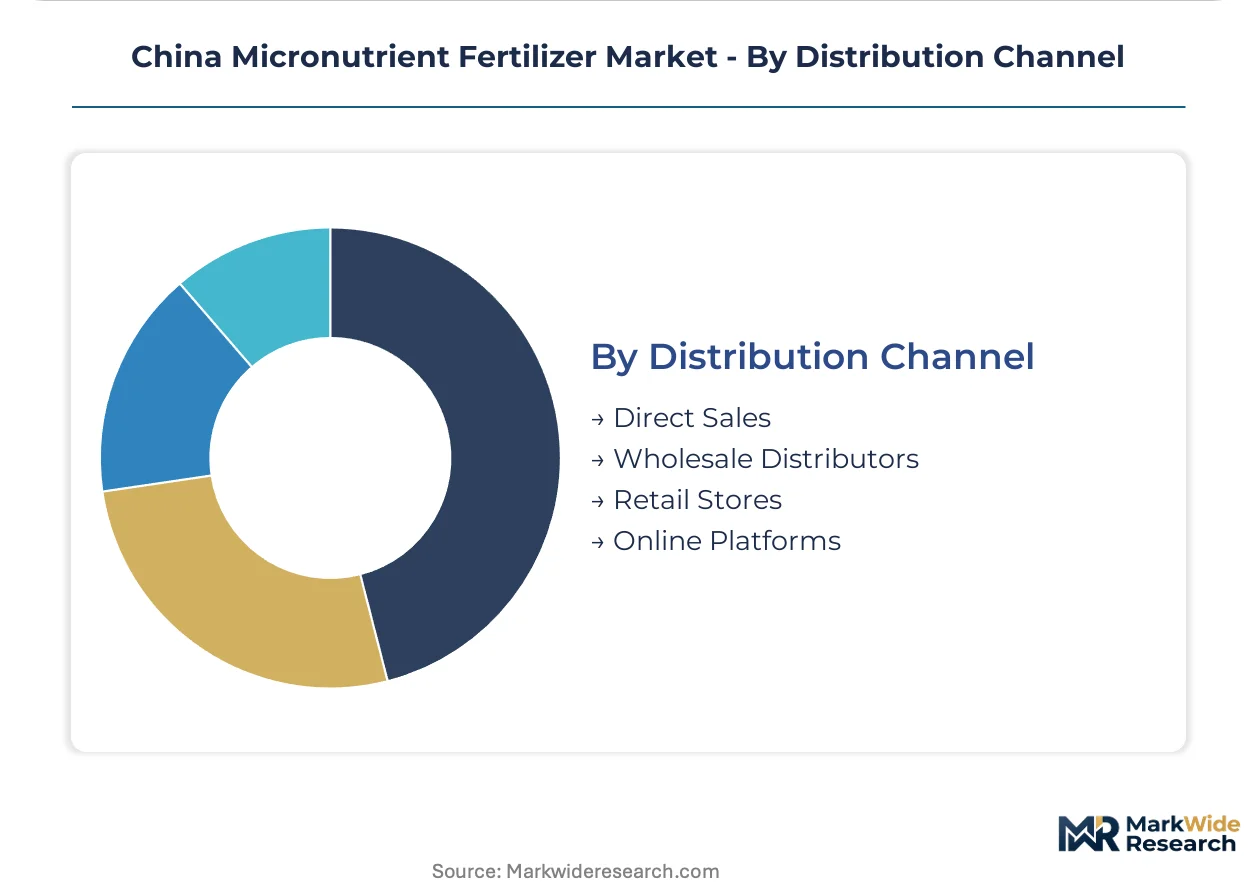
Distribution Channel:
Supply concentration dynamics favor state-backed cooperatives over independent wholesale networks.
- Wholesale Distributors:Provincial agricultural supply cooperatives aggregate procurement authority and compress supplier margins through volume concentration. Sinochem leverages this channel structure to sustain coverage across county-level extension networks.
- Direct Sales:Large greenhouse operators in Xinjiang and Shandong negotiate integrated supply contracts with manufacturers for liquid micronutrient and technical service bundles. This pattern displaces traditional distributor intermediaries where application complexity requires direct manufacturer expertise.
- Retail Stores:Township-level agricultural input shops serve smallholder vegetable and fruit producers with packaged micronutrient products.
- Online Platforms:E-commerce penetration remains limited by formulation technicality and application guidance requirements.
Wholesale distributors maintain volume leadership; direct sales channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agricultural extension specialists and soil science researchers concentrate in Shandong and Yunnan provinces, anchoring technical service capacity for precision micronutrient application.
Shandong Province
Greenhouse tomato and cucumber cultivation drives chelated iron and zinc consumption in Weifang and Qingdao clusters. Provincial agricultural supply cooperatives enforce GB standard compliance for export-bound vegetable shipments. Weifang's protected agriculture zone absorbs liquid micronutrient volumes through integrated drip fertigation systems.
Yunnan Province
High-altitude flower and vegetable production elevates boron and molybdenum application intensity for quality-sensitive export crops. The provincial agricultural technology extension center coordinates soil health mapping initiatives with micronutrient subsidy allocation. Kunming's horticulture belt sources amino acid chelates directly from manufacturers, bypassing wholesale intermediaries.
Xinjiang Uygur Autonomous Region
Cotton and protected fruit cultivation in Turpan and Kashgar prefectures creates demand for liquid micronutrient formats compatible with scarce water resources. The regional agricultural development bureau channels precision agriculture subsidies toward greenhouse infrastructure expansion. Urumqi's emerging agribusiness cluster attracts direct manufacturer technical service contracts.
Hebei Province
Winter wheat and maize rotation systems utilize non-chelated micronutrients as compound fertilizer additives across the North China Plain. Ministry of Agriculture zero-growth chemical fertilizer mandates intensify micronutrient substitution in these high-yield cereal zones. Baoding's fertilizer compounding district processes bulk sulfate salts for provincial distribution networks.
Hubei Province
Double-cropping rice and rapeseed systems in the Jianghan Plain address zinc and boron deficiencies through foliar application programs. Provincial environmental regulations under MEE oversight tighten effluent standards for acidulation facilities. Yichang's chemical processing corridor hosts integrated NPK-micronutrient manufacturing complexes serving central China.
China Micronutrient Fertilizer Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across China's micronutrient fertilizer sector. State-backed chemical groups leverage captive raw material access and provincial distribution networks to sustain volume positions. Three archetypes dominate: integrated chemical conglomerates with backward fertilizer integration, ecological engineering specialists with chelation technology focus, and regional compounders serving cooperative procurement channels. Competitive intensity centers on GB standard recertification speed and direct technical service relationships with large greenhouse operators.
Among state-affiliated chemical groups, Sinochem anchors the diversified conglomerate tier through provincial cooperative coverage. Kingenta Ecological Engineering Group occupies the specialist position with amino acid chelate production integration. Hubei Xinyangfeng Fertilizer represents the scale-driven manufacturing archetype with integrated compounding capacity. These three exemplify divergent strategic postures: distribution leverage versus technical specialization versus production scale.
| Leading Market Players |
|---|
| Hubei Xinyangfeng Fertilizer Co., Ltd. |
| Hebei Monband Water Soluble Fertilizer Co. Ltd. |
| Sinochem |
| Shandong Huibaichuan New Materials Co., Ltd. |
| Sinofert |
| ChemChina |
| Kingenta Ecological Engineering Group Co., Ltd. |
| Shenyang MASL Biotechnology Co., Ltd. |
| Yuntianhua Group |
| Others |
Value Chain & Pricing Dynamics
Sulfur and metal feedstock volatility cascades through China's micronutrient fertilizer tiers, compressing margins for non-chelated sulfate producers while amplifying premium capture for EDTA and amino acid chelate manufacturers serving Shandong greenhouse operators.
Pricing Analysis
Bundled technical service contracts with large greenhouse operators command 15-25% premiums over unbundled product-only transactions. Three-tier pricing structure across chelated premium, liquid specialty, and non-chelated economy levels separates value realization by soil alkalinity and crop value intensity. Pricing pressure stems from state cooperative procurement concentration, which compresses supplier margins through volume aggregation. Smallholder cereal producers exhibit highest price sensitivity, while export-oriented vegetable growers prioritize heavy metal compliance and deficiency correction timing over unit cost.
Supply Chain Analysis
Reverse logistics for empty chelate containers and spent acidulation residues remains underdeveloped, creating compliance cost burdens for compounders without integrated recovery systems. Raw material sourcing draws from domestic sulfur refineries in Shandong, imported EDTA precursors through Shanghai port, and amino acid feedstock from regional fermentation facilities. Single-source vulnerability concentrates in lignosulfonate complexation agents, where European specialty chemical imports face tariff exposure. Distribution runs through provincial agricultural supply cooperatives for volume tiers, while direct manufacturer relationships displace intermediaries in liquid micronutrient segments requiring technical service integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's micronutrient fertilizer market represents a late-cycle quality story as Ministry of Agriculture zero-growth mandates shift demand toward chelated formulations with documented purity certification for export-bound horticulture.
For Market Incumbents: Anchor market position through backward integration into amino acid chelate production, mirroring Kingenta's captive supply model. Accelerate GB standard recertification timelines to outpace smaller compounders facing compliance-driven exit. State cooperative procurement concentration threatens margin sustainability; defend through exclusive technical service contracts with Xinjiang greenhouse clusters requiring direct manufacturer expertise.
For New Entrants and Emerging Players: Xinjiang's emerging protected agriculture infrastructure presents the most penetrable white-space target, where liquid micronutrient demand outpaces established supplier technical service capacity. Direct sales relationships with large greenhouse operators bypass cooperative channel barriers. Pursue environmental compliance technology licensing to MEE-affected acidulation facilities as an ancillary revenue entry point.
For Investors and Strategic Acquirers: Consolidation pressure builds where GB recertification costs exceed small-scale compounder balance sheet capacity. Five-to-ten year viability favors manufacturers with integrated chelation chemistry and provincial cooperative network access. Monitor Ministry of Agriculture subsidy allocation shifts toward precision agriculture formats as the inflection signal for preferential procurement status.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Acid Chelate Production | Kingenta's captive supply model demonstrates margin defense against sulfur feedstock volatility. |
| GB Standard Recertification Acceleration | First-mover compliance captures market share from exiting small-scale compounders. |
| Direct Technical Service Contracts with Xinjiang Greenhouses | Displaces cooperative intermediaries where fertigation complexity demands manufacturer expertise. |
| Environmental Compliance System Licensing | MEE wastewater mandates create recurring revenue from acid recovery technology. |
| Precision Agriculture Subsidy Alignment | Soil health mapping convergence determines preferential provincial procurement status. |
Study Parameters
Direct dialogue with fertilizer plant managers, provincial cooperative procurement leads, greenhouse technical directors, and Ministry of Agriculture extension officers grounded qualitative insights. Secondary validation drew from customs trade data, GB standard committee filings, MEE environmental audit disclosures, and agricultural subsidy allocation records. Bottom-up volume modeling across chelation chemistry tiers triangulated against top-down macroeconomic projections for China's horticulture sector.
Output projections span the analysis window across product type, application method, crop value tier, and distribution channel dimensions. CAGRs derived from segmented growth rate analysis incorporating greenhouse expansion trajectories in Shandong and Yunnan, GB standard implementation timelines, and precision agriculture subsidy penetration curves. Modeled inputs included provincial soil alkalinity mapping data and cooperative procurement volume concentration indices.
Underlying measurement precision varies by segment; chelated micronutrient and liquid formulation categories carry tighter precision than non-chelated commodity tiers due to registration disclosure requirements. Forecasts reflect documented assumptions on subsidy continuity and standard implementation schedules. Practitioners should monitor Ministry of Agriculture field trial queue lengths and MEE enforcement intensity for early signals of competitive structure shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Fertilizer Bags Market
Fertilizers
Soil Conditioners Market
Fertilizers
Global Water Soluble Fertilizer Market
Fertilizers
Fertilizer Spreader Market
Fertilizers
Italy Foliar Fertilizer Market
Fertilizers
Vietnam Biofertilizer Market
Fertilizers
Europe Fertilizers Market
Fertilizers
Europe Specialty Fertilizer Market
Fertilizers
United States Specialty Fertilizer Market
Fertilizers
Europe Liquid Fertilizers Market
Fertilizers
Africa Micronutrient Fertilizer Market
Fertilizers
Brazil Fertilizers Market
Fertilizers
Biochar Fertilizer Market
Fertilizers
North America Controlled Release Fertilizer Market
Fertilizers
Potash Market
Fertilizers
Sulfur Fertilizer Market