
 Water Soluble NPK Fertilizers Market | 2026-2036
Water Soluble NPK Fertilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Water Soluble NPK Fertilizers Market Insights
ISO 18643 certification for water-soluble fertilizer quality is bifurcating the competitive landscape into qualified suppliers and marginal producers. Yara International ASA leverages its integrated ammonia-to-fertilizer value chain to sustain cost leadership across European distribution networks. Haifa Group specializes in premium potassium nitrate formulations, anchoring its position in high-value horticulture segments across the Middle East and Latin America.
Water soluble NPK fertilizers are homogeneous or blended compounds containing nitrogen, phosphorus, and potassium in ratios designed for complete dissolution in irrigation water, typically achieving solubility exceeding 99% at 20°C to enable fertigation and foliar feeding applications. Their primary commercial purpose is to deliver precise nutrient dosing in intensive cropping systems where soil-based fertilization cannot match uptake efficiency requirements. Powder formulations currently dominate volume throughput in emerging markets due to lower logistics costs and extended shelf stability, while liquid concentrates command premium positioning in automated greenhouse hydroponics where dosing accuracy directly influences yield consistency. The hydroponics application segment exhibits the steepest growth trajectory as substrate-based cultivation expands beyond traditional leafy greens into fruiting vegetables and berries.
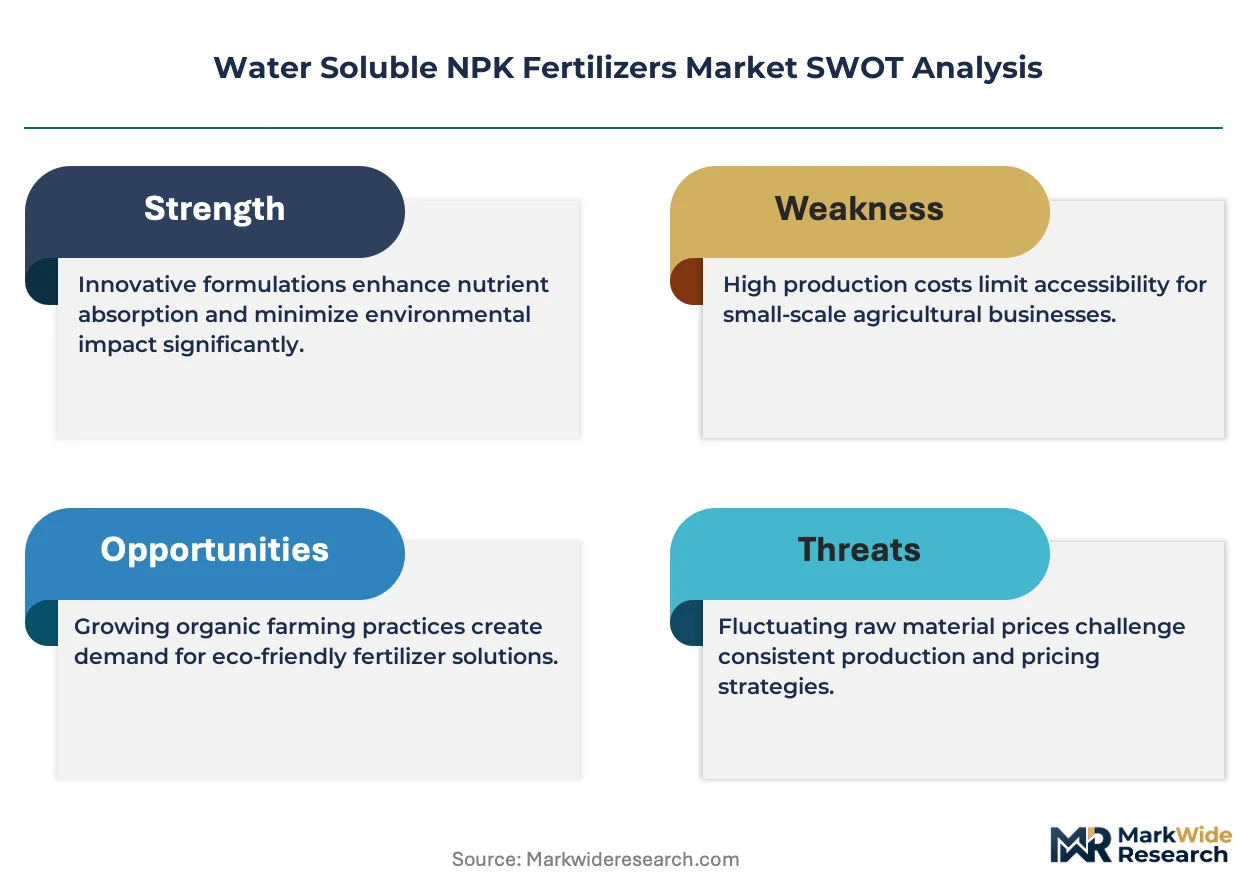
The EU F-Gas Regulation and REACH chemical registration framework impose stringent environmental compliance burdens on nitrogen-based fertilizer production within Europe, while EPA Clean Water Act provisions in the United States restrict runoff losses from open-field fertigation systems. India's FSSAI and BIS standards govern micronutrient additive claims and heavy metal limits in imported water-soluble blends, creating non-tariff barriers for new market entrants. Stakeholders must monitor evolving carbon border adjustment mechanisms and nutrient use efficiency mandates as these frameworks increasingly determine product formulation decisions and geographic sourcing strategies.
Market Dynamics
Precision fertigation systems are displacing broadcast fertilization in intensive horticulture, forcing manufacturers to reformulate for compatibility with automated dosing equipment and recirculating hydroponic infrastructure.
Growth Catalysts
- EU F-Gas Regulation:Carbon reduction mandates are accelerating greenhouse operator investment in closed-loop nutrient recovery systems that favor water-soluble inputs over conventional granular products.
- Controlled-environment agriculture clusters:Substrate-based berry cultivation in Spain's Almería province is generating concentrated demand for potassium-optimized NPK formulations with drip-line compatibility.
- ISO 18643 certification:Quality standardization is creating procurement preference hierarchies among commercial greenhouse operators seeking insurance-backed crop performance guarantees.
Market Restraints
- Ammonia feedstock volatility:Natural gas price swings directly compress nitrogen fertilizer margins, exposing non-integrated blenders to input cost spikes without pass-through pricing power.
- Phosphate rock concentration:Moroccan and Chinese state-controlled suppliers dominate upstream phosphorus sourcing, constraining European formulators' supply security during trade disputes.
- Heavy metal contamination thresholds:India's BIS cadmium and arsenic limits for imported water-soluble blends create non-tariff barriers that delay product registration by 12-18 months.
Strategic Opportunities
- Sub-Saharan greenhouse expansion:Kenya's Naivasha flower export zone lacks qualified water-soluble fertilizer suppliers, creating first-mover positioning for ISO-certified exporters with local blending partnerships.
- Carbon border adjustment mechanisms:EU CBAM implementation will penalize high-emission nitrogen imports, rewarding European producers with renewable ammonia supply chains and verified carbon footprints.
- Drone-based foliar application:Ultralow-volume spraying systems in Brazilian citrus orchards demand micronized powder formulations with anti-clogging additives, opening premium product tiers.
Industry Challenges
- Fertigation technician shortage:Greenhouse operators in the Netherlands report 23% vacancy rates for irrigation system managers capable of calibrating EC/pH-controlled nutrient dosing.
- REACH registration timelines:Novel chelated micronutrient additives require 18-24 month ECHA evaluation periods, delaying product launches behind formulation-ready competitors.
- Legacy equipment incompatibility:Retrofitting open-field center-pivot systems for soluble fertilizer injection requires capital expenditure that smallholder cooperatives cannot finance without state subsidy programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Soluble NPK Fertilizers Market |
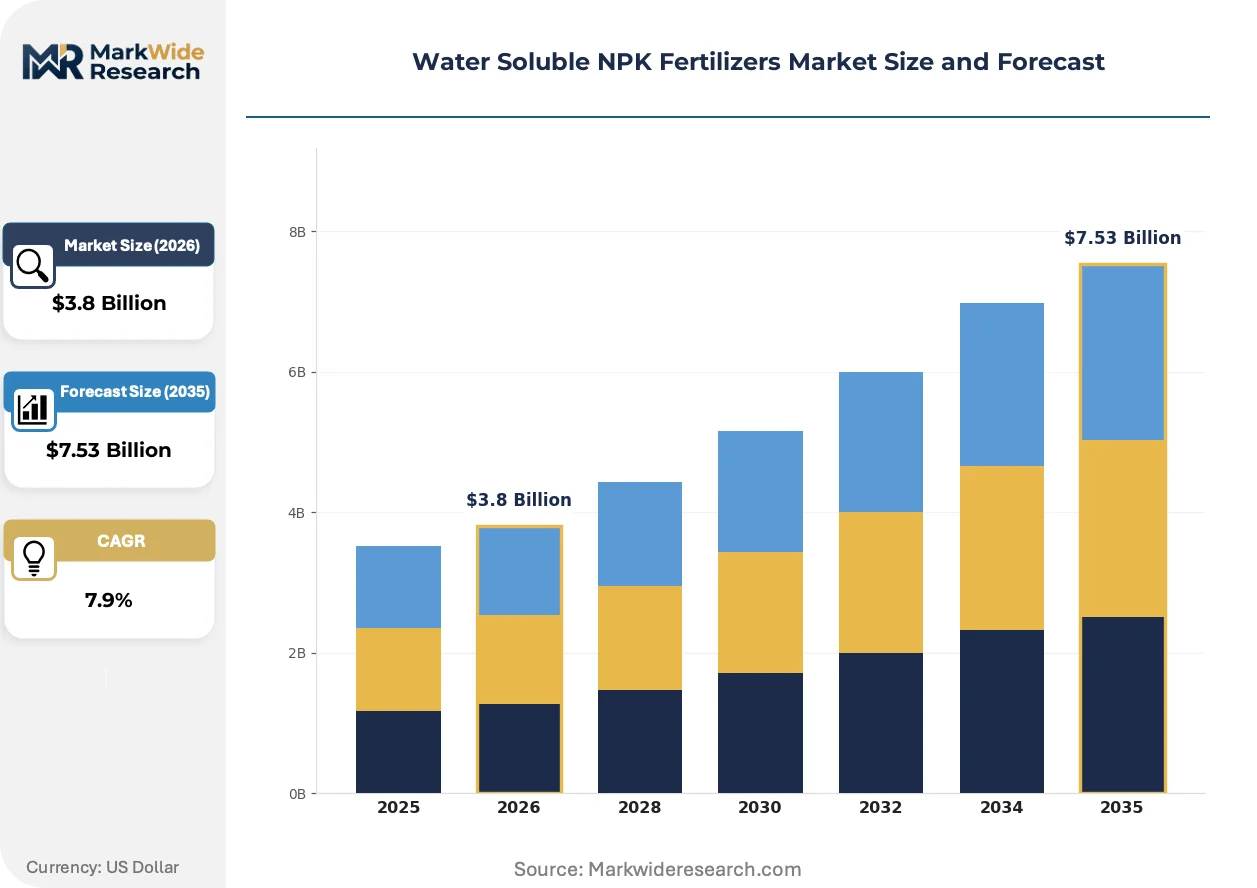
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.53 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Tablets Application: Agriculture, Horticulture, Turf, Hydroponics End User: Farmers, Commercial Growers, Retailers, Distributors Distribution Channel: Online Retailers, Local Stores, Agricultural Co-ops, Others |
| Companies Covered | Yara International ASA, Nutrien Ltd, ICL Group Ltd, The Mosaic Company, Coromandel International Limited, SQM S.A., EuroChem Group AG, Haifa Group, PhosAgro Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Soluble NPK Fertilizers Market Trends and Innovations
Formulation chemistry and application hardware are converging to enable sub-kilogram-per-hectare precision dosing, compressing the viable performance gap between commodity and specialty fertilizer tiers.
Nano-encapsulated controlled-release NPK granules are fragmenting the traditional soluble-versus-slow-release dichotomy. Dutch greenhouse operators in Westland are piloting these hybrid formulations for tomato vine crops. The technology is fragmenting procurement patterns by enabling single-pass application schedules that reduce labor costs by eliminating mid-cycle top-dressing.
REACH chemical registration expansion to include fertilizer additives is forcing reformulation of legacy micronutrient chelates. ECHA's 2023 updated guidance on EDTA biodegradability is accelerating substitution with biodegradable alternatives. High-value horticulture segments in Belgium and the Netherlands are absorbing 15-20% price premiums for compliant formulations to maintain EU market access.
Direct-to-grower digital platforms are compressing traditional distributor margins in North American specialty crop regions. Subscription-based nutrient prescription services in California's Salinas Valley are displacing independent agronomist recommendations. The channel shift is most visible among berry producers seeking real-time tissue analysis integration with automated reordering systems.
Water Soluble NPK Fertilizers Market Segmentation
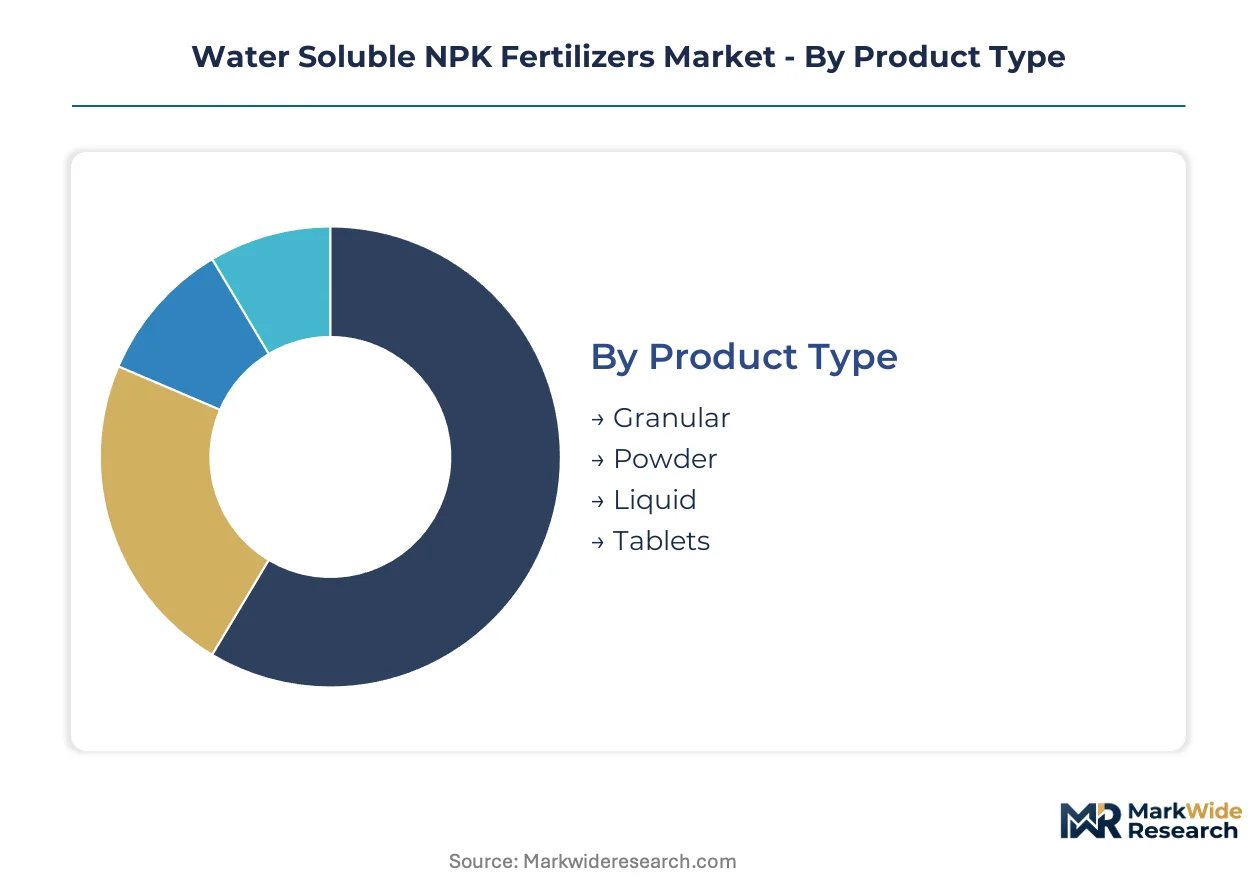
Water soluble NPK fertilizers fragment across formulation physics, application infrastructure, and procurement relationships. Each dimension carries distinct margin profiles and substitution vulnerabilities that reshape competitive positioning.
Product Type:
Granular formulations face the most acute substitution pressure from precision fertigation systems that demand complete dissolution.
- Powder:Finely milled crystalline blends achieve solubility exceeding 99% at 20°C, enabling rapid dissolution in drip irrigation. Demand concentrates among smallholder cooperatives in India and Southeast Asia where logistics costs favor concentrated dry shipments over water-heavy liquid alternatives. India's BIS heavy metal limits and FSSAI additive claims create 12-18 month registration delays for imported powder blends.
- Liquid:Pre-dissolved concentrates with buffered pH and anti-precipitation stabilizers command premium positioning in automated greenhouse hydroponics. Netherlands' Westland cluster operators absorb 15-20% price premiums for REACH-compliant formulations with biodegradable chelates replacing legacy EDTA. The EU F-Gas Regulation accelerates closed-loop nutrient recovery investments that favor liquid dosing precision.
- Granular:Slow-dissolving compressed compounds retain relevance in open-field broadcast applications but lose share to soluble alternatives in intensive horticulture. Compatibility gaps with automated injection equipment constrain adoption among commercial greenhouse operators.
- Tablets:Compressed single-nutrient or balanced formulations serve hobbyist and small-scale greenhouse segments with simplified dosing. Limited scalability restricts penetration beyond retail garden center channels.
Powder retains volume leadership; liquid holds the steepest expansion curve.
Application:
Margin structures diverge sharply between soil-based and soilless cultivation systems.
- Hydroponics:Substrate-based and deep-water culture systems require complete nutrient solutions with zero insoluble residue. Spain's Almería province berry cultivation generates concentrated demand for potassium-optimized NPK with drip-line compatibility. REACH registration timelines for novel chelated micronutrients delay competitive entry by 18-24 months.
- Horticulture:Protected cultivation of vegetables, ornamentals, and nursery stock drives specification-grade procurement. Commercial growers in Belgium and the Netherlands enforce ISO 18643 certification as a procurement gate, bifurcating supplier tiers.
- Agriculture:Open-field row crops and orchards apply soluble fertilizers through center-pivot and micro-sprinkler systems. EPA Clean Water Act runoff restrictions in the United States constrain fertigation expansion without capital-intensive retrofitting.
- Turf:Golf courses and sports field maintenance demand rapid green-up response with minimal burn risk. Seasonal demand concentration and price sensitivity limit supplier margins relative to year-round greenhouse accounts.
Agriculture dominates absolute volume; hydroponics climbs the fastest.
End User:
Procurement sophistication separates price-taker segments from specification-setters.
- Commercial Growers:Greenhouse operators and intensive horticulture enterprises with in-house agronomy staff negotiate formula customization and performance guarantees. Subscription-based nutrient prescription services in California's Salinas Valley displace independent distributor relationships.
- Farmers:Broadacre and specialty crop producers rely on cooperative purchasing and seasonal credit terms. Kenya's Naivasha flower export zone lacks qualified local suppliers, creating first-mover positioning for ISO-certified exporters with blending partnerships.
- Distributors:Regional agricultural supply chains aggregate fragmented demand and provide technical support. Direct-to-grower digital platforms compress traditional margins in North American specialty crop regions.
- Retailers:Garden centers and farm supply stores serve hobbyist and smallholder segments with standardized SKUs. Limited technical consultation capability constrains attachment of premium formulations.
Commercial growers drive margin expansion; farmers anchor volume throughput.
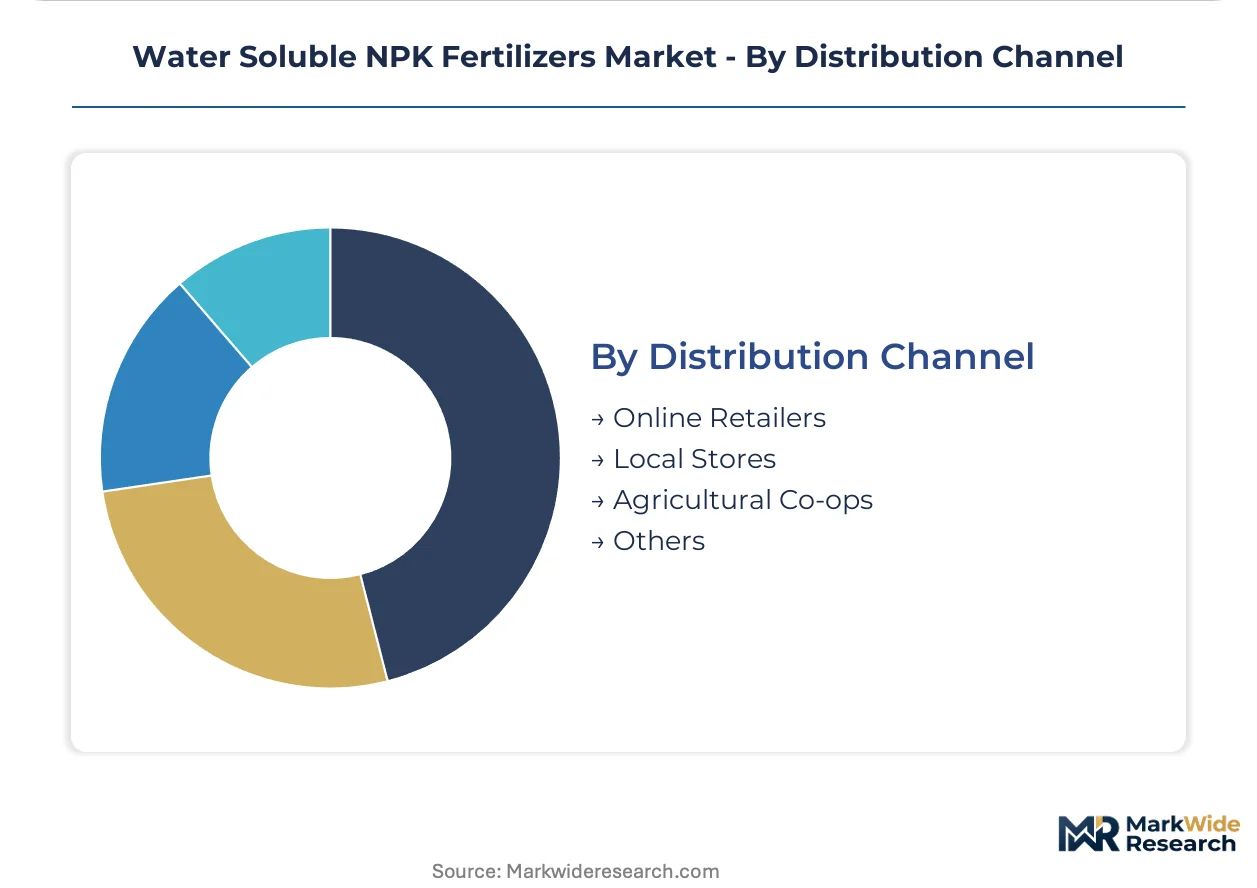
Distribution Channel:
Channel economics reflect customer scale and service intensity requirements.
- Agricultural Co-ops:Member-owned purchasing organizations aggregate smallholder demand for volume pricing and shared technical services. India's cooperative structure governs micronutrient distribution in key producing states.
- Local Stores:Independent agricultural retailers provide last-mile delivery and credit access in fragmented rural markets. Inventory carrying costs favor powder and granular over liquid formulations with shorter shelf stability.
- Online Retailers:E-commerce platforms serve remote growers and specialty crop segments with direct fulfillment. Real-time tissue analysis integration with automated reordering systems emerges among berry producers.
- Others:Direct manufacturer relationships and government procurement programs serve institutional accounts and subsidy-eligible smallholders.
Local stores retain channel dominance; online retailers gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial greenhouse operators and intensive horticulture enterprises concentrate procurement power in four countries where substrate-based cultivation and precision fertigation infrastructure have achieved critical scale.
Netherlands
Westland greenhouse cluster operators drive specification-grade demand for REACH-compliant liquid concentrates with biodegradable chelates. The EU F-Gas Regulation accelerates closed-loop nutrient recovery investments that favor water-soluble inputs over conventional granular products. Amsterdam-Rotterdam distribution corridors anchor European supply chain logistics for premium horticulture formulations.
Spain
Almería province berry cultivation generates concentrated demand for potassium-optimized NPK formulations with drip-line compatibility. National carbon reduction mandates reshape manufacturing compliance requirements for imported blends. Murcia and Valencia protected agriculture zones expand substrate-based tomato and pepper cultivation requiring complete solubility.
United States
California Salinas Valley berry producers adopt subscription-based nutrient prescription services with real-time tissue analysis integration. EPA Clean Water Act provisions restrict runoff losses from open-field fertigation systems without capital-intensive retrofitting. Florida and Arizona greenhouse clusters absorb premium liquid concentrates for automated hydroponics infrastructure.
China
Shandong and Yunnan province protected agriculture expansion drives powder formulation volume through smallholder cooperative purchasing. The country's national chemical registration framework governs micronutrient additive claims and heavy metal limits in imported water-soluble blends. Yangtze River Delta greenhouse operators pilot nano-encapsulated controlled-release hybrids for single-pass application schedules.
India
Maharashtra and Karnataka state horticulture cooperatives aggregate fragmented demand for powder blends with extended shelf stability. BIS cadmium and arsenic limits and FSSAI additive claims create 12-18 month registration delays for imported products. Gujarat chemical manufacturing corridors develop domestic blending capacity to substitute qualified imported formulations.
Water Soluble NPK Fertilizers Market Competitive Landscape
Player mix skews toward integrated nitrogen producers and specialty potassium nitrate formulators with divergent margin structures. The supplier base bifurcates along ISO 18643 certification lines that determine procurement access to commercial greenhouse accounts. Three archetypes dominate: integrated ammonia-to-fertilizer value chains, premium horticulture specialists, and regional blending operations. Competitive moves center on backward integration into phosphate rock sourcing and formulation partnerships for automated dosing equipment compatibility.
Within the integrated producer tier, Yara International ASA and Nutrien Ltd occupy positions defined by captive ammonia supply and continental distribution density. Haifa Group exemplifies the premium specialist archetype through potassium nitrate formulation focus. ICL Group Ltd represents mid-scale diversification across multiple nutrient chemistries. These three anchors illustrate how certification status and feedstock integration separate qualified suppliers from marginal competitors in procurement hierarchies.
| Leading Market Players |
|---|
| Yara International ASA |
| Nutrien Ltd |
| ICL Group Ltd |
| The Mosaic Company |
| Coromandel International Limited |
| SQM S.A. |
| EuroChem Group AG |
| Haifa Group |
| PhosAgro Group |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Moroccan phosphate rock facilities and Russian ammonia plants sets floor prices for nitrogen and phosphorus derivatives, compressing margin recovery for non-integrated European blenders during feedstock spikes. Powder formulations in India and Southeast Asia absorb logistics-driven discounts against liquid concentrates, while REACH-compliant biodegradable chelates in the Netherlands command 15-20% procurement premiums from Westland greenhouse operators.
Pricing Analysis
Cost-plus contracts with natural gas indexation dominate nitrogen fertilizer procurement, exposing non-integrated blenders to margin compression when feedstock prices spike without pass-through power. Three-tier pricing structure across premium, standard, and economy levels separates ISO 18643-certified suppliers from marginal producers, with certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from ammonia feedstock volatility, with smallholder cooperatives in India exhibiting highest price sensitivity and Netherlands commercial growers showing lowest due to yield-performance guarantees.
Supply Chain Analysis
Strait of Hormuz transit security underwrites phosphate rock shipments from Moroccan state-controlled suppliers to European formulators, creating chokepoint vulnerability during regional tensions. Upstream concentration centers on Morocco, China, and Russia for phosphate rock and ammonia feedstocks; formulation chemistry draws from sulfuric acid, nitric acid, and potassium chloride inputs. Single-source vulnerability in phosphorus sourcing constrains European supply security during trade disputes. Distribution runs through Amsterdam-Rotterdam corridors for premium horticulture formulations, with agricultural co-ops aggregating fragmented smallholder demand in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fertigation hardware and nutrient prescription software are converging into integrated platform ecosystems, with subscription-based reordering systems in California's Salinas Valley displacing independent distributor relationships and reordering stakeholder value capture.
For Market Incumbents: Compound defensive positioning through backward integration into renewable ammonia supply chains and captive phosphate rock sourcing, securing cost leadership against feedstock volatility while accelerating ISO 18643 certification investments to maintain procurement access among commercial greenhouse accounts facing REACH compliance deadlines. For New Entrants and Emerging Players: Anchor in Kenya's Naivasha flower export zone where qualified water-soluble fertilizer suppliers remain scarce, targeting ISO-certified exporter partnerships with local blending operations as the most penetrable white-space entry path before incumbent distribution networks solidify. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty potassium nitrate formulators with biodegradable chelate portfolios and drone-compatible micronized powder capabilities; five-to-ten year viability hinges on carbon border adjustment mechanism adaptation. The signal to watch is EU CBAM implementation pace penalizing high-emission nitrogen imports.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Ammonia | Captive supply from electrolysis-based production secures margin stability against natural gas price spikes. |
| ISO 18643 Certification Investment | Quality standardization unlocks procurement access to Netherlands Westland greenhouse operator accounts. |
| Biodegradable Chelate Formulation Transition | EDTA substitution maintains EU market access under ECHA 2023 biodegradability guidance updates. |
| Drone-Compatible Micronized Powder Development | Anti-clogging additives address Brazilian citrus orchard ultralow-volume spraying system requirements. |
| Direct-to-Grower Digital Platform Launch | Real-time tissue analysis integration displaces independent agronomist recommendations in California berry production. |
Research Methodology
Desk research of trade customs databases, EU F-Gas Regulation implementation documents, and ECHA REACH registration filings preceded structured interviews with greenhouse operations managers, fertilizer procurement leads at agricultural co-ops, technical R&D directors at formulation companies, and distribution channel partners across Netherlands, Spain, and India. Primary fieldwork with commercial growers and secondary validation against BIS and FSSAI regulatory filings enabled bottom-up volume estimation and top-down market reconciliation.
Variance decomposition across formulation physics, application infrastructure, and procurement relationships structured the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, cultivation system, end-user sophistication, and regional regulatory cluster. CAGRs derived from trend extrapolation of precision agriculture adoption curves, weighted by ammonia feedstock price scenario sensitivity. Industry-specific inputs incorporated fertigation equipment penetration rates and closed-loop nutrient recovery investment cycles.
Decision-makers should treat outputs as directional under base assumptions of sustained natural gas price volatility and steady EU carbon border adjustment mechanism implementation; material deviation in feedstock cost trajectories or regulatory enforcement timelines would warrant model refresh. Practitioners should keep alternative scenarios live as Morocco-China phosphate rock supply dynamics and India BIS heavy metal enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
North America Fertilizers Market
Fertilizers
Global Potash Fertilizer Market
Fertilizers
Asia-Pacific Fertilizers Market
Fertilizers
Fertilizer Bags Market
Fertilizers
Catalyst Fertilizers Market
Fertilizers
Compound Fertilizer Market
Fertilizers
Controlled and Slow Release Fertilizers Market
Fertilizers
Global Micronutrient Fertilizer Market
Fertilizers
Brazil Fertilizers Market
Fertilizers
Russia Micronutrient Fertilizer Market
Fertilizers
Global Specialty Fertilizer Market
Fertilizers
Europe Specialty Fertilizer Market
Fertilizers
Asia-Pacific Organic Fertilizer Market
Fertilizers
Global Controlled Release Fertilizer Market
Fertilizers
Humate Fertilizer Market
Fertilizers
Nitrogen Fertilizer Additives Market