
 Asia-Pacific Specialty Fertilizer Market | 2026-2036
Asia-Pacific Specialty Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Specialty Fertilizer Market Outlook
The EU Green Deal's indirect pressure on Asian agricultural export standards is broadening compliance requirements for specialty fertilizer formulations across the region. Yara International ASA leverages its integrated supply chain to sustain premium positioning in controlled-release products. Coromandel International Ltd. anchors its southern India manufacturing base while competing aggressively in micronutrient blends for horticulture. Haifa Group specializes in water-soluble formulations and dominates Israel-origin exports into Southeast Asian markets.
Asia-Pacific specialty fertilizers encompass value-added nutrient products engineered with specific release kinetics, coating technologies, or chelated micronutrient complexes designed for targeted crop uptake and reduced environmental losses. These formulations typically incorporate polymer-coated urea, sulfur-coated compounds, or EDTA-chelated trace elements manufactured through controlled granulation and encapsulation processes for precision agriculture applications. Micronutrient segments command disproportionate margin pools due to technical complexity and limited supplier bases across the region. Nitrogenous fertilizers occupy the largest volume share but face margin compression from commodity urea competition. Fertigation application methods represent the fastest-expanding channel, driven by drip irrigation proliferation in China's Shandong province and India's Maharashtra state.
China's MEE enforces stricter nutrient runoff limits that force reformulation toward slow-release and stabilized products. India's FSSAI residue monitoring and BIS quality certification create dual compliance thresholds for domestic and export-oriented producers. Australia's TGA-equivalent agricultural chemical regulator influences registration pathways for specialty products entering Pacific markets. Stakeholders must monitor evolving carbon-border adjustment mechanisms and water-use regulations that will reshape product registration priorities and manufacturing location decisions across the region.
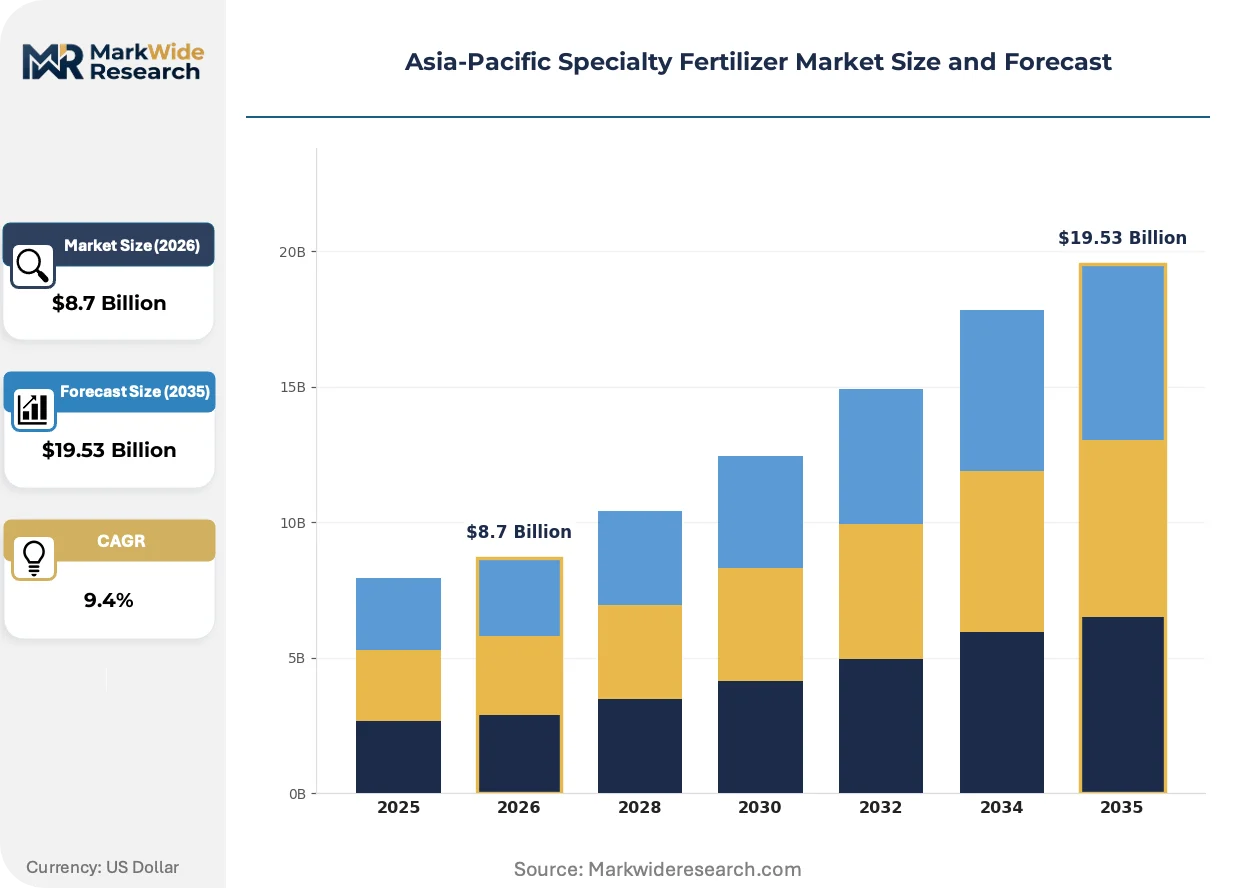
Market Dynamics
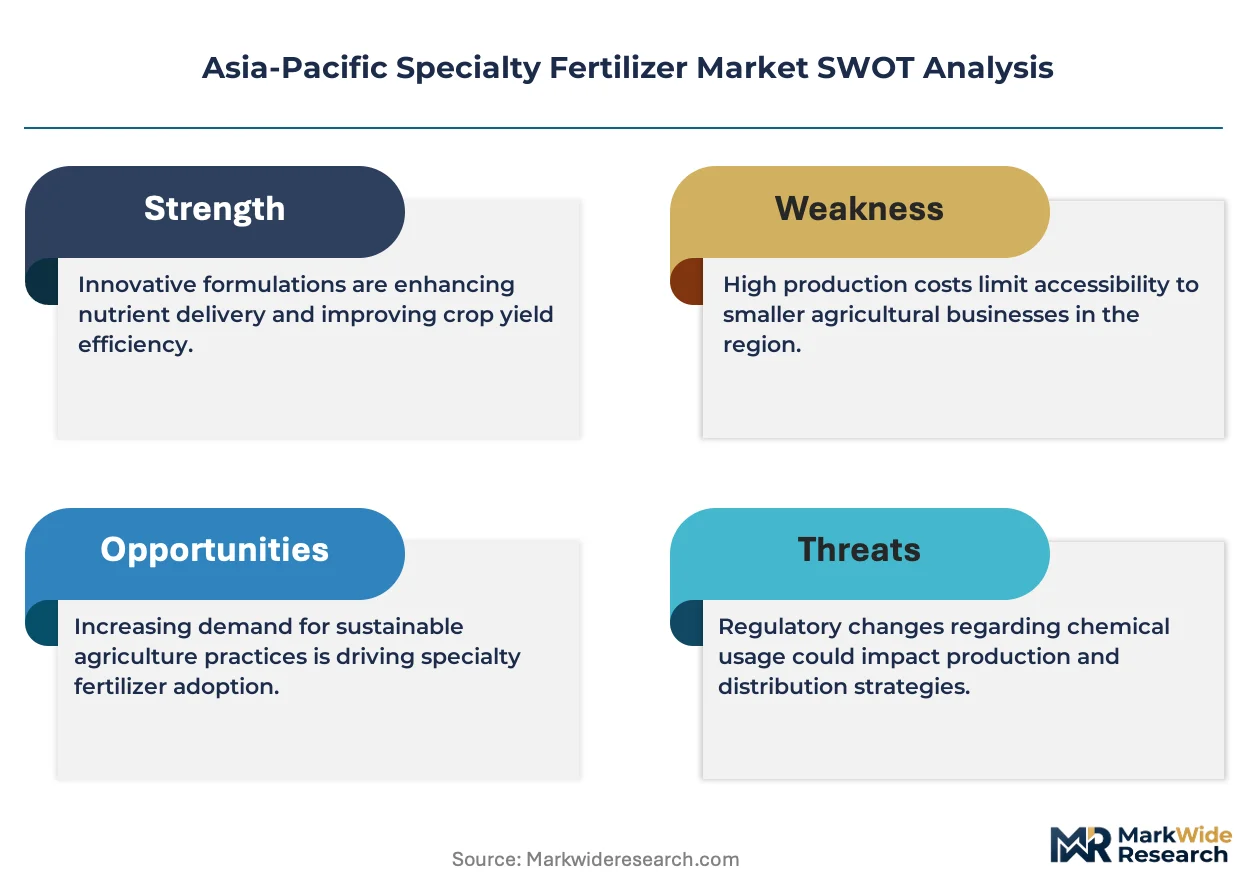
China's MEE nutrient runoff limits and India's PLI scheme for agrochemical manufacturing are forcing dual-track reformulation investments across the Asia-Pacific specialty fertilizer landscape. These regulatory pressures are compressing commodity urea margins while elevating controlled-release and micronutrient blend premiums.
Growth Catalysts
- PLI scheme incentives:India's production-linked incentive framework for agrochemical manufacturing is accelerating domestic encapsulation technology capacity and reducing import dependency for polymer-coated formulations.
- Shandong drip irrigation proliferation:China's intensive vegetable cultivation belts are expanding fertigation infrastructure, creating concentrated demand for water-soluble and stabilized nitrogen products.
- EU Green Deal compliance:Export-oriented producers across the region are reformulating to meet residue and carbon-intensity standards for agricultural goods entering European markets.
Market Restraints
- Phosphate rock supply concentration:Input cost volatility from Moroccan and Chinese phosphate rock suppliers constrains margin stability for blended fertilizer producers.
- EDTA chelation complexity:Technical limitations in micronutrient complex manufacturing create capability scarcity and extend lead times for customized trace element formulations.
- BIS-FSSAI dual thresholds:India's overlapping quality certification and residue monitoring requirements generate regulatory friction for domestic producers serving both local and export channels.
Strategic Opportunities
- Maharashtra horticulture expansion:India's western state is underpenetrated for micronutrient blends in grape and pomegranate cultivation, offering white space for technical-grade suppliers.
- Southeast Asian fertigation channels:Drip irrigation adoption in Vietnam and Thailand creates emerging application demand for soluble NPK formulations with tailored release kinetics.
- Carbon-border preparation:Early alignment with anticipated EU carbon-border adjustment mechanisms positions reformulation-capable producers for premium export access.
Industry Challenges
- Encapsulation engineering talent:The region faces a skill gap in polymer-coating process optimization and controlled-release granulation technology.
- Legacy urea infrastructure integration:Retooling existing ammonia-urea plants for specialty production requires capex intensity that strains mid-tier balance sheets.
- Multi-jurisdiction registration timelines:Australia's TGA-equivalent agricultural chemical pathways and China's GB standard updates create certification complexity for regional product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Specialty Fertilizer Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micronutrients, Nitrogenous Fertilizers, Phosphate Fertilizers, Potassium Fertilizers End Use Industry: Agriculture, Horticulture, Turf, Forestry Distribution Channel: Online Retail, Wholesale, Direct Sales, Agricultural Cooperatives Application Method: Foliar Application, Soil Application, Fertigation, Seed Treatment |
| Companies Covered | Haifa Group, Sociedad Quimica y Minera de Chile SA, Coromandel International Ltd., Grupa Azoty S.A. (Compo Expert), Vardhaman Fertilizers and Seeds, Yara International ASA, Sinochem Group, Zhongchuang xingyuan chemical technology co. ltd, ICL Group Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Specialty Fertilizer Market Strategic Shifts
Polymer-coating and stabilization chemistry is actively displacing conventional fertilizer applications across precision agriculture systems in the Asia-Pacific region. Formulation science is converging with digital farming infrastructure to create demand for site-specific nutrient delivery.
Controlled-release urea with biodegradable polymer coatings is absorbing volume share from conventional prilled products in China's vegetable-intensive provinces. Large-scale farming cooperatives in Shandong and Hebei are adopting these formulations to meet MEE runoff limits while maintaining yield targets. The technology is absorbing capital investment that previously flowed to commodity nitrogen expansion, compressing the addressable market for uncoated urea.
India's FSSAI residue monitoring protocols are tightening enforcement timelines for specialty fertilizer contaminants in export-oriented horticulture. The regulation is forcing reformulation of micronutrient carriers away from certain chelating agents toward plant-derived alternatives. Grape and pomegranate producers in Maharashtra and Karnataka are most affected, with compliance costs shifting procurement toward certified technical-grade suppliers.
Direct-to-farm digital platforms are disintermediating traditional distributor networks for water-soluble fertilizers in Southeast Asian markets. Agritech aggregators in Vietnam and Thailand are bundling fertigation scheduling software with micronutrient subscriptions, capturing buyer relationships that previously flowed through multi-tier dealer systems. This channel compression is most visible in high-value vegetable cultivation zones where precision application generates measurable yield premiums.
Asia-Pacific Specialty Fertilizer Market Segmentation
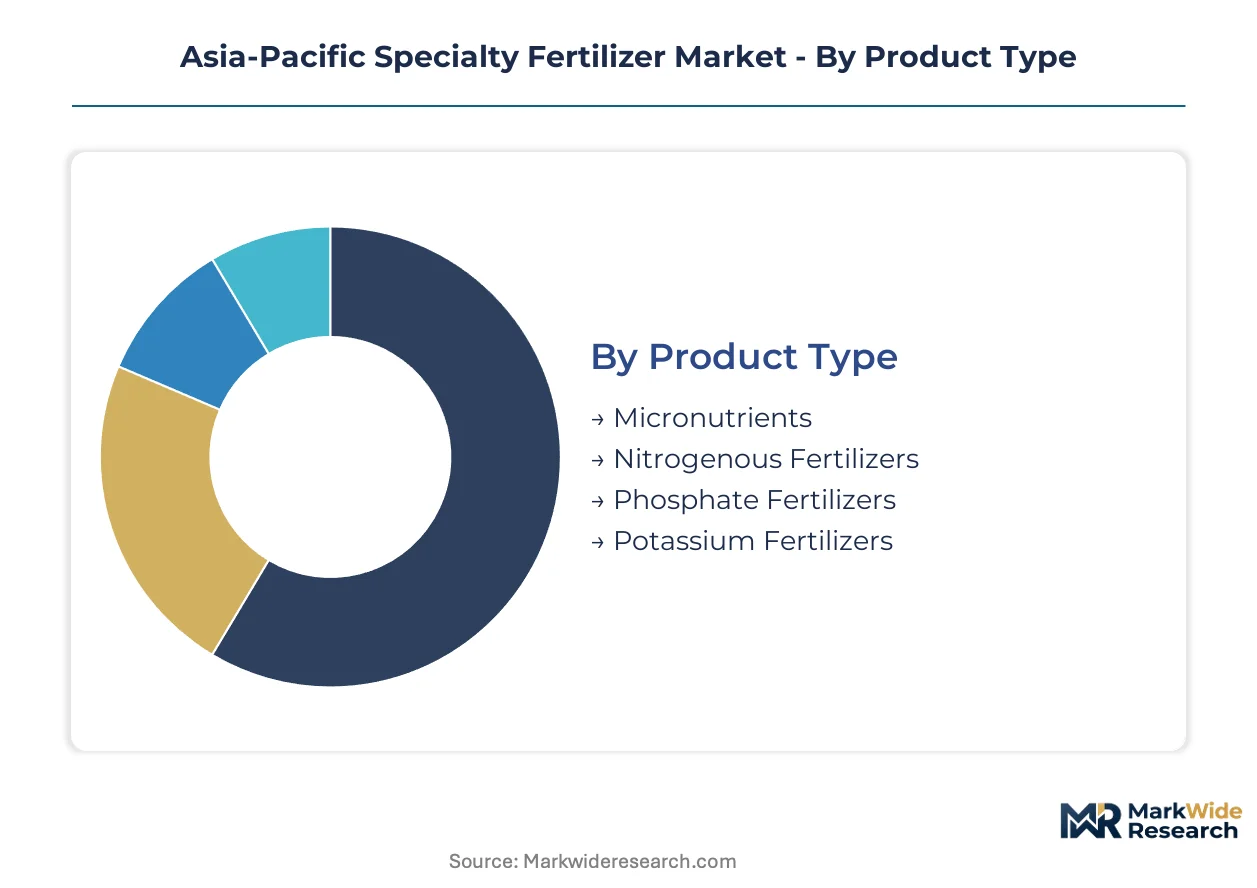
Specialty fertilizer segmentation in the Asia-Pacific region maps directly to supply chain capabilities and regulatory compliance thresholds. Product formulation complexity, application infrastructure requirements, and channel access determine margin capture across distinct market layers.
Product Type:
Manufacturing concentration clusters around coating technologies and chelation chemistry capabilities, with raw material access dictating regional production footprints.
- Micronutrients:EDTA-chelated and plant-derived trace element complexes command premium positioning due to technical synthesis barriers and limited qualified suppliers. Maharashtra grape cultivation and Karnataka pomegranate belts generate concentrated procurement for certified technical-grade formulations under tightening FSSAI residue protocols.
- Nitrogenous Fertilizers:Polymer-coated and stabilized urea variants absorb the largest volume flows, though commodity urea competition compresses margins. Shandong and Hebei vegetable cooperatives drive reformulation toward biodegradable coatings to satisfy MEE runoff enforcement.
- Phosphate Fertilizers:Value-added phosphate blends incorporate sulfur coating and acidification technologies for alkaline soil adaptation.
- Potassium Fertilizers:Controlled-release potassium sulfate targets chloride-sensitive horticulture in Australia's Murray-Darling basin.
Nitrogenous formulations absorb the bulk of installed capacity; micronutrients are expanding most quickly.
End Use Industry:
Customer sophistication tiers separate precision agriculture adopters from conventional commodity buyers, with compliance requirements acting as segmentation gates.
- Agriculture:Broadacre cereal and oilseed production in Australia's wheat belt and India's Punjab rice systems generates volume demand for stabilized nitrogen, though price sensitivity limits specialty penetration.
- Horticulture:China's protected vegetable cultivation and India's export-oriented grape and pomegranate sectors concentrate premium procurement for water-soluble and chelated micronutrient systems. EU Green Deal residue standards force reformulation investments in this segment.
- Turf:Golf course and sports field maintenance in Japan, South Korea, and Australia's metropolitan centers sustains demand for slow-release formulations with precise color response.
- Forestry:Plantation timber operations in Indonesia and Vietnam adopt micronutrient correction for eucalyptus and acacia establishment phases.
Horticulture commands the steepest expansion trajectory; agriculture retains the deepest volume base.
Distribution Channel:
Channel structure reflects farmer scale and digital infrastructure maturity, with disintermediation pressure strongest in high-value crop zones.
- Wholesale:Traditional multi-tier distribution through provincial dealers dominates commodity nitrogen flows in China's interior provinces and India's northern grain belts.
- Direct Sales:Large farming cooperatives in Shandong and Hebei negotiate bulk contracts for controlled-release formulations, bypassing dealer margins.
- Agricultural Cooperatives:Maharashtra and Karnataka horticulture collectives aggregate micronutrient demand for technical-grade supplier access.
- Online Retail:Agritech platforms in Vietnam and Thailand bundle fertigation scheduling with soluble NPK subscriptions, compressing channel layers in high-value vegetable zones.
Wholesale channels retain the largest throughput; online retail is climbing the fastest.
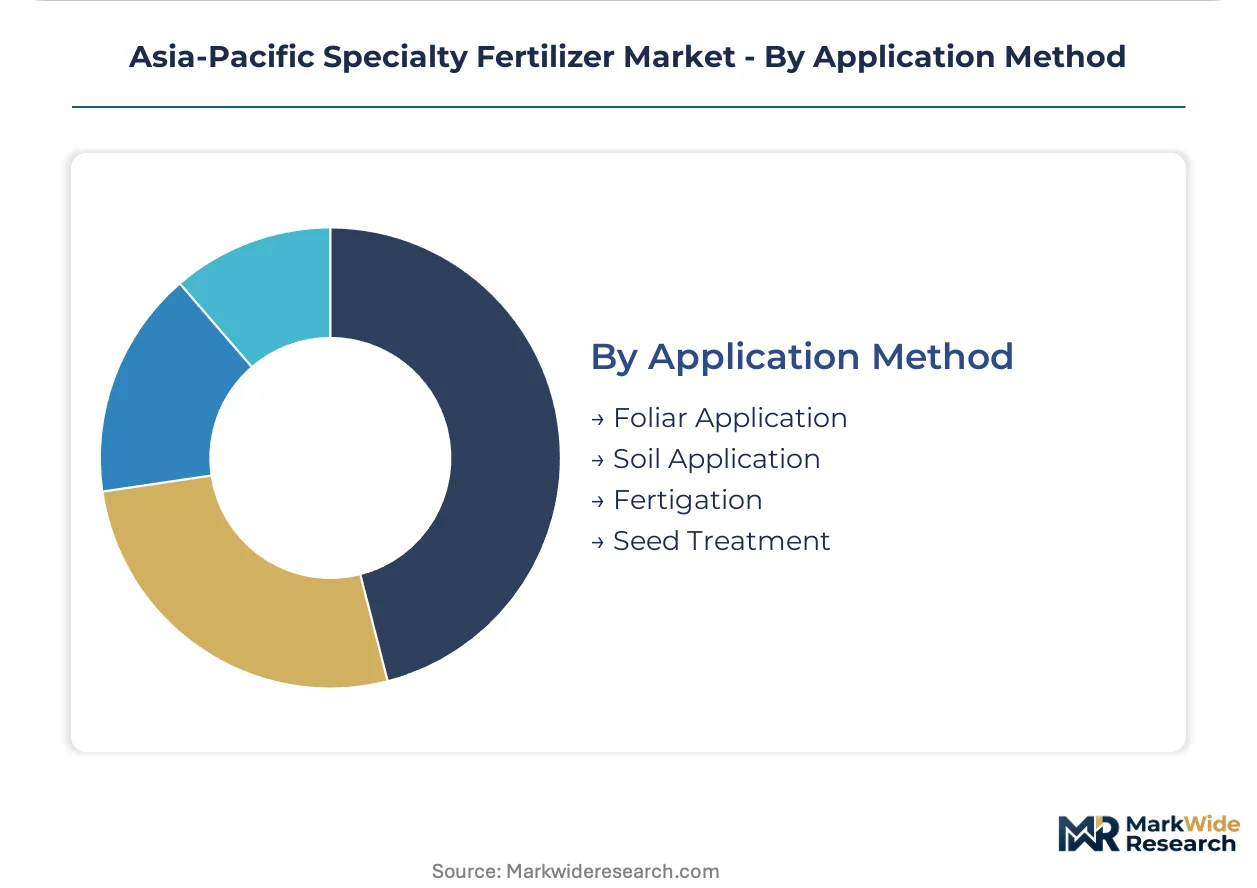
Application Method:
Equipment infrastructure and labor economics determine method adoption, with capital-intensive systems concentrating in high-yield crop districts.
- Fertigation:Drip irrigation proliferation in China's Shandong province and India's Maharashtra state drives water-soluble and stabilized nitrogen demand. Digital scheduling integration creates subscription revenue models for input suppliers.
- Foliar Application:Micronutrient correction in grape, pomegranate, and protected vegetable systems relies on aerial and ground-based spraying with chelated trace element formulations.
- Soil Application:Conventional broadcasting persists in broadacre systems with lower labor costs and limited equipment access.
- Seed Treatment:Micronutrient and biostimulant coating targets establishment-phase root development in Australia's precision planting systems.
Soil application maintains the widest installed base; fertigation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province anchors specialty fertilizer demand through its intensive vegetable cultivation belts, where drip irrigation infrastructure and MEE runoff enforcement drive reformulation toward controlled-release products.
China
Shandong and Hebei vegetable cooperatives absorb polymer-coated urea volumes to satisfy MEE nutrient runoff limits. The MEE enforces stricter discharge standards that compress commodity urea margins while elevating biodegradable coating premiums. Yangtze River Delta horticulture clusters adopt water-soluble formulations for protected cultivation under tightening environmental audits.
India
Maharashtra's grape and pomegranate belts generate concentrated procurement for chelated micronutrients under FSSAI residue monitoring expansion. The PLI scheme for agrochemical manufacturing accelerates domestic encapsulation capacity and reduces import dependency for polymer-coated formulations. Karnataka horticulture collectives aggregate demand for certified technical-grade trace element blends.
Australia
Murray-Darling basin horticulture sustains demand for chloride-sensitive potassium sulfate and precision planting seed treatments. The TGA-equivalent agricultural chemical regulator influences registration pathways for specialty products entering Pacific export markets. Victoria and New South Wales broadacre systems adopt stabilized nitrogen for wheat belt productivity targets.
Vietnam
Mekong Delta vegetable zones drive soluble NPK demand through expanding drip irrigation networks and agritech platform penetration. Digital fertigation scheduling bundles disintermediate traditional dealer tiers in high-value crop districts. Central Highlands coffee and pepper cultivation create emerging micronutrient correction requirements.
Thailand
Central Plains rice intensification zones absorb stabilized nitrogen formulations for yield optimization under water-use efficiency mandates. Eastern seaboard fruit export corridors concentrate procurement for EU Green Deal-compliant residue standards. Chiang Mai highland vegetable systems adopt foliar micronutrient applications for quality premiums.
Asia-Pacific Specialty Fertilizer Market Competitive Environment
The competitive structure tilts toward integrated supply chain operators with coating technology capabilities and regional formulation registration expertise. Mid-tier blenders face margin compression from commodity urea competition and phosphate rock input volatility. Three archetypes dominate: Israeli water-soluble specialists, European-controlled release technology licensors, and Indian domestic encapsulation scale players. Capacity expansion and strategic technology licensing represent the dominant competitive moves across the regional landscape.
Within the integrated supply chain tier, Yara International ASA and ICL Group Ltd occupy positions exemplifying premium controlled-release positioning through captive nutrient sourcing. Among Asia-Pacific domestic manufacturers, Coromandel International Ltd anchors southern India production capacity while competing in micronutrient blends. Haifa Group represents the water-soluble specialization archetype dominating Israel-origin exports into Southeast Asian fertigation channels.
| Leading Market Players |
|---|
| Haifa Group |
| Sociedad Quimica y Minera de Chile SA |
| Coromandel International Ltd. |
| Grupa Azoty S.A. (Compo Expert) |
| Vardhaman Fertilizers and Seeds |
| Yara International ASA |
| Sinochem Group |
| Zhongchuang xingyuan chemical technology co. ltd |
| ICL Group Ltd |
| Others |
Value Chain & Pricing Dynamics
Encapsulation engineering talent concentration in southern India and Israel feeds directly into labor-cost differentials that widen pricing-tier spreads between premium controlled-release formulations and commodity nitrogen alternatives. Technical synthesis capabilities for EDTA-chelated micronutrients command 40-60% manufacturing cost premiums over standard blends, compressing margins for mid-tier blenders lacking captive coating technology.
Pricing Analysis
Yield-linked value anchors pricing for controlled-release urea in Shandong vegetable cooperatives, where biodegradable polymer coatings justify premiums through measurable runoff compliance and yield maintenance. Three-tier pricing structure across premium certified-grade, standard technical-grade, and economy commodity-grade products stratifies procurement in Maharashtra horticulture belts. Cost compression in nitrogenous tiers intensifies because Moroccan phosphate rock volatility and Chinese urea dumping strain blended fertilizer margins. Export-oriented grape producers in Karnataka exhibit least price sensitivity due to FSSAI residue compliance mandates, while Punjab rice systems remain most price-sensitive, prioritizing volume procurement of stabilized nitrogen over specialty premiums.
Supply Chain Analysis
Empty polymer-coating drum returns and sulfur-coated compound refurbishment flows from Shandong cooperatives back to domestic encapsulation plants illustrate nascent reverse-logistics development in specialty fertilizer distribution. Manufacturing concentration clusters in China, India, and Israel, with Chinese plants feeding Yangtze River Delta horticulture and Israeli facilities exporting water-soluble formulations into Vietnam and Thailand. Phosphate rock from Moroccan suppliers, polymer resin from South Korean petrochemical complexes, and sulfur from Australian mining operations constitute critical input dependencies. Single-source vulnerability in EDTA chelation chemistry creates formulation lead-time risk for customized micronutrient orders. Distribution runs through provincial dealer networks for commodity nitrogen, while direct-to-farm platforms disintermediate tiers in high-value vegetable zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific specialty fertilizer markets operate under acute encapsulation technology scarcity, where qualified polymer-coating capacity constraints prop pricing premiums and reward early-mover capacity investments. Manufacturing bottlenecks in biodegradable coating production concentrate margin capture among integrated supply chain operators with captive R&D infrastructure.
For Market Incumbents: Deepen backward integration into sulfur and polymer resin sourcing to insulate margin structures from Moroccan phosphate rock volatility and South Korean petrochemical price swings. Prioritize certification investment for FSSAI technical-grade compliance to defend positioning in Maharashtra grape export corridors against emerging domestic encapsulation scale players. Expand capacity in southern India manufacturing clusters to capture PLI scheme incentives before mid-tier competitors secure equivalent production-linked support. For New Entrants and Emerging Players: Begin with Maharashtra pomegranate belt micronutrient white space, where agricultural cooperative procurement aggregation creates accessible demand concentration without entrenched distributor relationships. Target Vietnam Mekong Delta soluble NPK demand through agritech platform partnerships, bypassing traditional multi-tier dealer infrastructure entirely. Lead go-to-market with fertigation scheduling software bundling to capture subscription revenue models displacing transactional input sales. For Investors and Strategic Acquirers: Re-rating potential sits with Israeli water-soluble specialists given Southeast Asian drip irrigation proliferation and digital channel compression trends accelerating premium formulation adoption. Long-term viability over the coming decade hinges on carbon-border alignment capabilities and EU Green Deal residue compliance infrastructure. Monitor EU carbon-border adjustment mechanism implementation timelines as the critical inflection signal distinguishing reformulation-capable producers from stranded commodity exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Sourcing | South Korean petrochemical supply contracts stabilize coating cost structures for controlled-release manufacturers. |
| FSSAI Technical-Grade Certification Investment | Maharashtra grape export compliance creates procurement preference for certified micronutrient suppliers. |
| Agritech Platform Partnership Development | Vietnam and Thailand digital bundling displaces traditional dealer margins in high-value vegetable zones. |
| Biodegradable Coating R&D Scale-Up | China MEE runoff enforcement accelerates demand for environmentally compliant encapsulation technologies. |
| Carbon-Border Alignment Preparation | Early EU Green Deal compliance positioning secures premium export access ahead of adjustment mechanism activation. |
Study Parameters
Multi-period observation of polymer-coating adoption rates, drip irrigation installation data, and FSSAI enforcement timelines anchored the trend analysis, supplemented by interviews with plant managers at encapsulation facilities, procurement leads at Maharashtra horticulture cooperatives, distribution channel partners in Vietnam, technical R&D directors at Israeli formulation specialists, and regulatory affairs officers navigating BIS-FSSAI dual thresholds. Secondary validation drew from China customs/trade data, India PLI scheme disclosure filings, Australian TGA-equivalent registration databases, and ASEAN agricultural input import records. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic agriculture sector indicators.
Segment-weighting across product type, end-use industry, distribution channel, and application method dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from installed base growth curves, replacement demand patterns, and technology diffusion rates across precision agriculture adoption clusters. Fertigation infrastructure expansion in Shandong and Maharashtra, alongside micronutrient correction intensity in export-oriented horticulture, constituted primary forecast inputs.
Underlying measurement precision varies by segment; controlled-release nitrogen and water-soluble formulations carry tighter precision than commodity urea alternatives due to concentrated manufacturing reporting. Forecasts reflect assumptions regarding PLI scheme continuation, MEE enforcement intensity, and EU carbon-border implementation scope. Practitioners should monitor drip irrigation subsidy programs, FSSAI residue protocol expansion, and polymer resin price volatility for early signals warranting forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Polymer Coated Urea Market
Fertilizers
India Controlled Release Fertilizer Market
Fertilizers
Saudi Arabia Fertilizer Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
North America Fertilizers Market
Fertilizers
Boron Fertilizers Market
Fertilizers
France Fertilizer Market
Fertilizers
North America Liquid Fertilizers Market
Fertilizers
North America Micronutrient Fertilizers Market
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
Indonesia Fertilizer Market
Fertilizers
Global Starter Fertilizers Market
Fertilizers
Africa Micronutrient Fertilizer Market
Fertilizers
Diammonium Phosphate (DAP) Market
Fertilizers
Russia Specialty Fertilizer Market
Fertilizers
Phosphoric Fertilizer Market