
 Vietnam Biofertilizer Market | 2026-2036
Vietnam Biofertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Biofertilizer Market Analytics
Premium liquid formulations with guaranteed microbial counts above 10^8 CFU per milliliter is decoupling from commodity-grade granular products with unspecified viability. Bioway Organic High Tech Joint Stock Company leverages its R&D pipeline to dominate high-count liquid segments. Suståne Natural Fertilizer Inc anchors imported organic-matter blends for export-oriented vegetable farms. Que Lam Group competes through backward integration into microbial culture production, cutting third-party substrate costs.
Biofertilizers contain living microorganisms—nitrogen-fixing bacteria, phosphate-solubilizing fungi, or plant-growth-promoting rhizobacteria—formulated in liquid suspensions or solid carriers with shelf-life specifications typically spanning six to twelve months under controlled temperatures; their primary function is to enhance nutrient availability through biological rather than chemical pathways, reducing synthetic fertilizer dependency in intensive cropping systems. Liquid biofertilizers command margin pools in high-value horticultural applications where drip irrigation enables precise inoculation, while granular formats retain volume leadership in broad-acre rice production where broadcasting dominates application methods. Agricultural cooperatives represent the fastest-growing end-user channel as group procurement reduces per-unit packaging premiums and enables shared cold-storage of live cultures.
Vietnam's Ministry of Agriculture and Rural Development enforces registration requirements through the Plant Protection Department, mandating strain identification and efficacy documentation before commercial distribution. The national organic agriculture development scheme, alongside provincial biosafety protocols modeled on ASEAN harmonized standards, shapes product formulation decisions and factory certification requirements. Stakeholders must monitor how impending revisions to microbial strain import permits affect domestic production economics and foreign supplier market access.
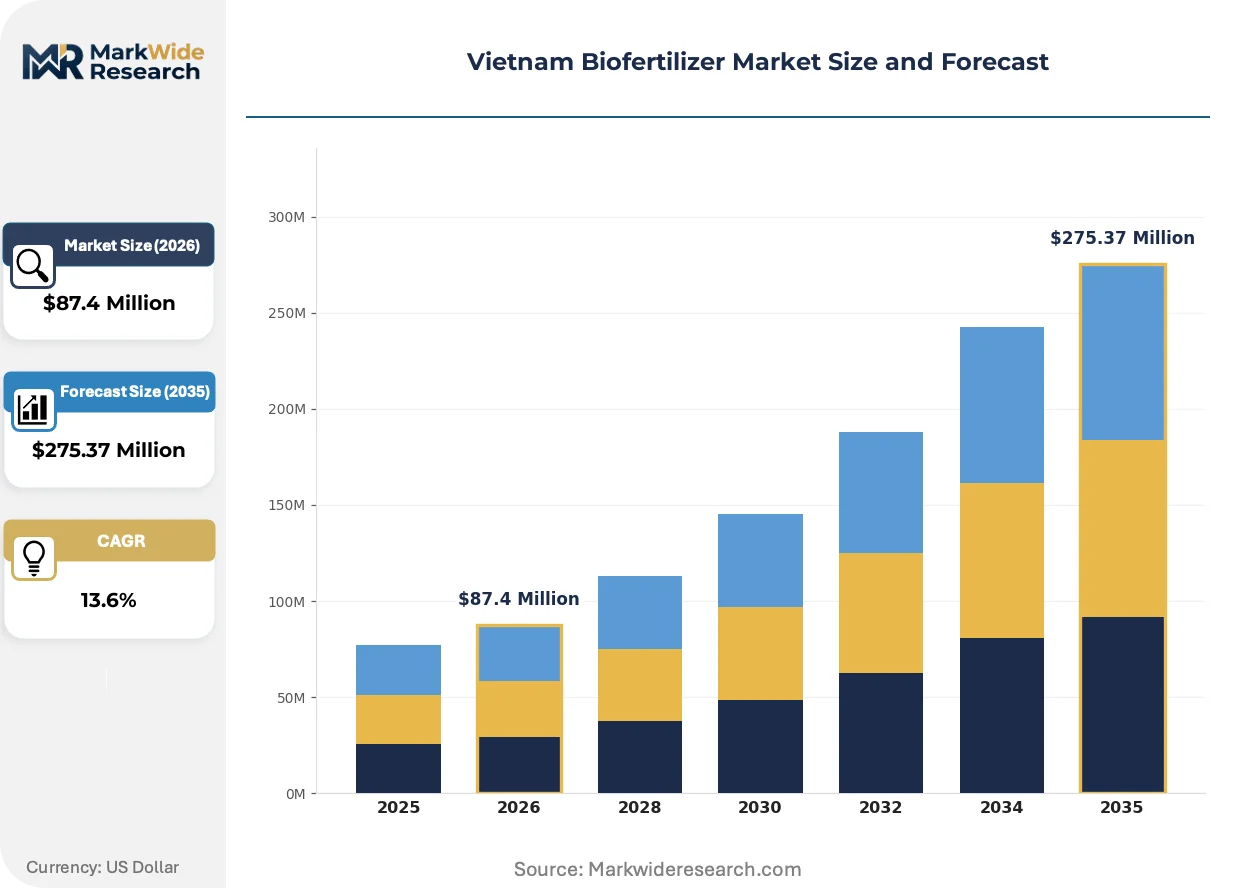
Market Dynamics
Vietnam's biofertilizer sector is being fundamentally restructured by the Ministry of Agriculture and Rural Development's organic agriculture transition mandates, which are compressing synthetic fertilizer use timelines across rice-intensive provinces while creating strain-specific registration bottlenecks at the Plant Protection Department.
Growth Catalysts
- National organic agriculture development scheme:Provincial targets for certified organic acreage in the Mekong Delta are mandating biological input substitution, creating guaranteed offtake pools for nitrogen-fixing formulations.
- Drip irrigation expansion in horticulture:High-value vegetable clusters around Hanoi are adopting precision inoculation systems that favor liquid biofertilizer compatibility over traditional broadcasting methods.
- ASEAN harmonized biosafety standards:Mutual recognition protocols are reducing cross-border strain validation costs for Vietnamese manufacturers seeking export markets in Cambodia and Laos.
Market Restraints
- Molasses and agricultural residue input volatility:Solid carrier substrate costs fluctuate with sugarcane processing seasonality, squeezing margins for granular biofertilizer producers in the off-season.
- Import dependency for specialized strains:Domestic culture collections lack phosphate-solubilizing fungal isolates with documented efficacy in acidic Mekong Delta soils, forcing reliance on Thai and Indian suppliers.
- Six-to-twelve month shelf-life constraints:Cold chain gaps in provincial distribution networks degrade viable cell counts before products reach Red River Delta smallholders.
Strategic Opportunities
- Central Highlands coffee rehabilitation:Degraded soil biology in Dak Lak and Lam Dong provinces is creating demand for mycorrhizal inoculants among export-oriented robusta cooperatives.
- Agricultural cooperative channel formalization:Group procurement entities are aggregating sufficient volume to justify dedicated cold-storage infrastructure at district level.
- Strain import permit revision anticipation:Pending simplification of microbial culture import documentation at the Plant Protection Department could accelerate R&D pipelines for domestic formulators.
Industry Challenges
- Microbiologist technician scarcity:Quality control laboratories struggle to recruit personnel capable of CFU enumeration and contamination detection under ISO 17025 protocols.
- Strain efficacy documentation burden:Registration dossiers require multi-season field trials in three distinct agro-ecological zones, stretching startup capital deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Biofertilizer Market |
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $275.37 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Biofertilizers, Granular Biofertilizers, Bio-Pesticides, Bio-Stimulants Application: Agricultural Crop, Horticultural Crop, Turf Management, Soil Health End User: Farmers, Agricultural Cooperatives, Research Institutions, Commercial Growers Distribution Channel: Online Retail, Direct Sales, Agricultural Supply Stores, Wholesale Distributors |
| Companies Covered | BIOWAY ORGANIC HIGH TECH JOINT STOCK COMPANY, Suståne Natural Fertilizer Inc, DAI THANH JOINT STOCK COMPANY, Binh Dien Fertilizer Joint Stock Company, DAI NAM MANUFACTURING & TRADING COMPANY LIMITED, Biotech Bio-Agriculture, Song Gianh Corporation Joint Stock Company, Biofertilizer Vietnam Co. Ltd, Que Lam Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Biofertilizer Market Evolving Landscape
Formulation science and delivery mechanisms are advancing faster than regulatory frameworks can adapt, creating temporary competitive windows for manufacturers that master viability preservation and precision application compatibility.
Encapsulation technology using alginate-based microbeads is extending shelf-life for phosphate-solubilizing fungi beyond eighteen months in ambient storage. Large-scale rice cooperatives in Thai Binh and Hai Duong provinces are piloting these formulations for pre-sowing seed treatment. The technology is converging with drone-based aerial application systems, enabling uniform inoculation across flooded paddies where ground equipment cannot operate.
Revisions to the Plant Protection Department's microbial strain registration guidelines are tightening efficacy documentation requirements for nitrogen-fixing bacteria. Domestic manufacturers must now submit qPCR-based enumeration protocols alongside traditional plating methods. Small and mid-scale formulators in the Red River Delta are responding by consolidating laboratory capabilities through third-party analytical service contracts.
Cooperative procurement aggregators are displacing individual smallholder purchases as the dominant channel for liquid biofertilizer distribution. These entities negotiate volume-based pricing directly with manufacturers, bypassing traditional agricultural input retailers. The shift is most visible in Hanoi-surrounding horticulture belts where high-value vegetable production justifies shared cold-storage investments at the commune level.
Vietnam Biofertilizer Market Segmentation
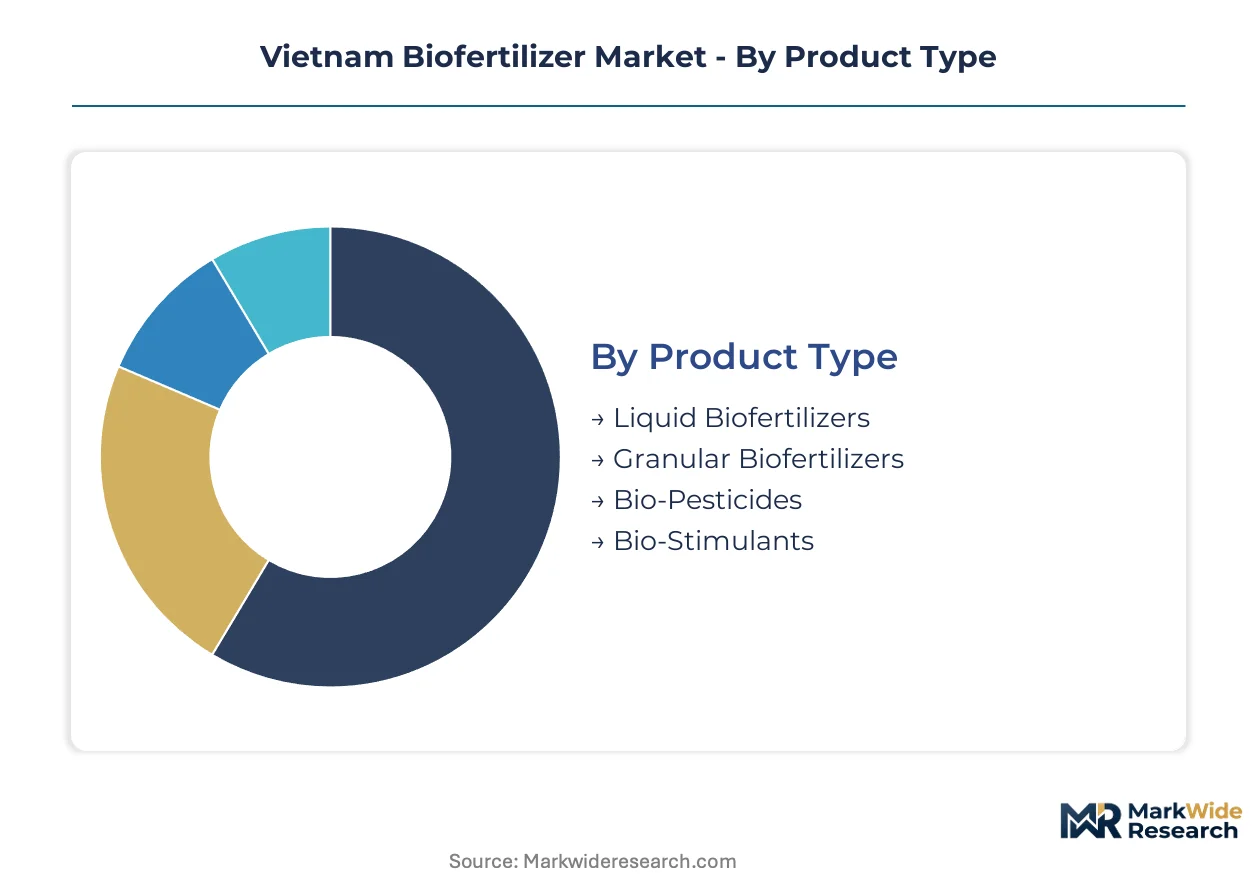
Vietnam's biofertilizer market segments around formulation stability, application precision, and cold-chain reach. Each dimension carries distinct margin profiles and regulatory burdens that shape manufacturer positioning.
Product Type:
Supply concentration tilts toward liquid formulations where R&D investment barriers filter out commodity competitors.
- Liquid Biofertilizers:Suspensions containing nitrogen-fixing bacteria or phosphate-solubilizing fungi at guaranteed counts above 10^8 CFU per milliliter. Demand concentrates in Red River Delta horticulture belts where drip irrigation infrastructure enables precise inoculation of high-value vegetables.
- Granular Biofertilizers:Solid carriers embedding microbial cultures in molasses or agricultural residue matrices, optimized for broadcasting across flooded rice paddies. Mekong Delta smallholders drive volume offtake despite seasonal substrate cost volatility.
- Bio-Pesticides:Microbial antagonists targeting rice blast and vegetable fungal pathogens, requiring dual registration under crop protection and biofertilizer protocols.
- Bio-Stimulants:Seaweed and humic acid derivatives enhancing plant stress tolerance without live culture constraints, bypassing cold-chain requirements.
Granular formats absorb the bulk of installed capacity; liquid formulations are expanding most quickly.
Application:
Cost tier differentiation separates intensive horticulture investments from broad-acre rice substitution economics.
- Agricultural Crop:Rice dominates tonnage demand through provincial organic transition mandates in Thai Binh and Long An provinces. National targets for certified organic acreage compress synthetic fertilizer timelines.
- Horticultural Crop:High-value vegetables and fruits around Hanoi command premium pricing for guaranteed-viability inoculants with documented efficacy in acidic soils.
- Turf Management:Golf course and urban landscape maintenance in Ho Chi Minh City periphery, limited by narrow strain registration for non-food applications.
- Soil Health:Rehabilitation of degraded Central Highlands coffee soils using mycorrhizal inoculants, constrained by multi-season field trial documentation requirements.
Agricultural crop applications anchor production volume; horticultural crop segments gain share fastest.
End User:
Customer type evolution is displacing individual procurement with aggregated purchasing power.
- Farmers:Mekong Delta smallholders purchasing through provincial extension networks, price-sensitive to per-unit packaging premiums.
- Agricultural Cooperatives:Group entities in Hai Duong and Vinh Phuc provinces negotiating volume-based pricing and sharing cold-storage infrastructure at commune level.
- Research Institutions:Cuu Long Delta Rice Research Institute and provincial agricultural academies conducting strain efficacy trials for Plant Protection Department registration dossiers.
- Commercial Growers:Export-oriented vegetable operations in Lam Dong and Dak Lak provinces requiring ISO 17025-certified quality documentation for EU market access.
Individual farmers retain the largest user base; agricultural cooperatives are climbing the fastest.
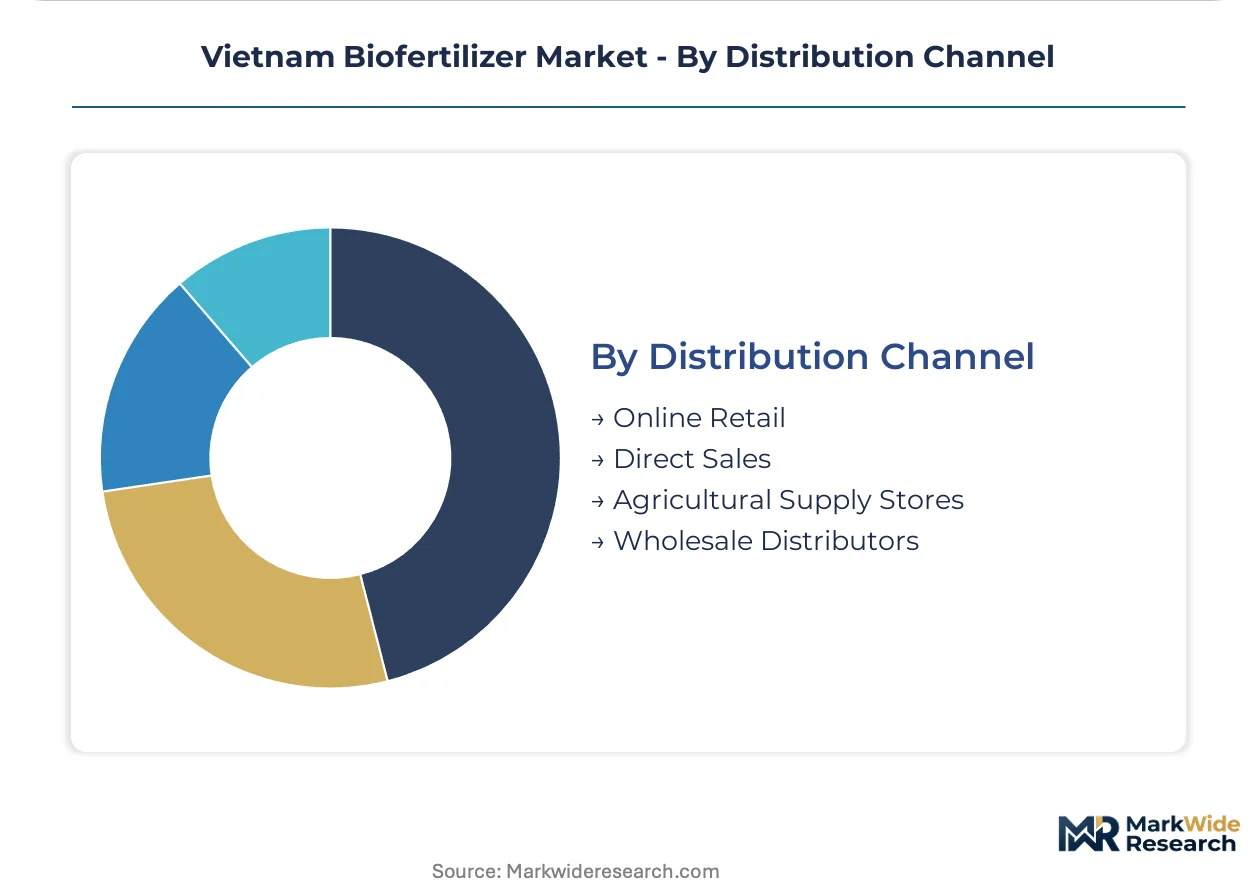
Distribution Channel:
Volume flows through traditional agricultural supply networks while digital channels capture specification-sensitive buyers.
- Online Retail:E-commerce platforms serving urban peri-commercial growers with documented strain specifications and cold-chain tracking.
- Direct Sales:Manufacturer relationships with large cooperatives bypassing retail markups, concentrated in Red River Delta high-value clusters.
- Agricultural Supply Stores:Provincial input retailers handling granular products with ambient storage tolerance, dominant in Mekong Delta rice provinces.
- Wholesale Distributors:Regional aggregators managing inventory rotation for six-to-twelve month shelf-life products, exposed to cold-chain degradation risks.
Agricultural supply stores handle the bulk of transaction volume; direct sales channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hanoi anchors Vietnam's biofertilizer demand through its surrounding Red River Delta horticulture belt, where precision drip irrigation enables high-count liquid inoculant adoption among vegetable cooperatives.
Mekong Delta
Rice intensification and provincial organic transition mandates in Long An and Tien Giang provinces drive granular biofertilizer offtake. The Ministry of Agriculture and Rural Development's certified organic acreage targets compress synthetic fertilizer timelines. Can Tho and An Giang host the densest cooperative procurement networks for nitrogen-fixing formulations.
Central Highlands
Degraded robusta coffee soils in Dak Lak and Lam Dong provinces generate demand for mycorrhizal inoculants among export-oriented cooperatives. The Plant Protection Department's multi-season field trial requirements constrain strain registration velocity. Bao Loc and Buon Ma Thuot concentrate commercial grower investment in soil rehabilitation programs.
Southeast Region
Ho Chi Minh City periphery turf management and urban landscape maintenance create niche demand for bio-stimulant applications. Provincial biosafety protocols modeled on ASEAN harmonized standards shape product formulation decisions. Bien Hoa and Thu Dau Mot host distributor networks managing six-to-twelve month shelf-life inventory rotation.
North Central Coast
Horticultural diversification in Thanh Hoa and Nghe An provinces expands addressable acreage for phosphate-solubilizing formulations. Cold chain gaps in provincial distribution networks degrade viable cell counts before products reach smallholders. Vinh and Thanh Hoa City represent emerging cooperative procurement aggregation points.
Vietnam Biofertilizer Market Competitive Landscape
Capital-heavy producers compete with asset-light formulators across Vietnam's biofertilizer sector. Backward-integrated culture manufacturers command margin advantages through captive microbial supply, while third-party-dependent blenders absorb substrate cost volatility. Three archetypes dominate: domestic R&D-anchored specialists, import-reliant organic-matter blenders, and provincial cooperative-integrated distributors. Competitive intensity concentrates on strain registration velocity and cold-storage infrastructure deployment.
Among domestic R&D-anchored specialists, Bioway Organic High Tech Joint Stock Company exemplifies the high-count liquid formulation tier through its integrated culture production capabilities. Suståne Natural Fertilizer Inc occupies a position representing import-dependent organic-matter blending for export-oriented vegetable operations. Que Lam Group sits within the backward-integrated archetype, cutting third-party substrate costs through in-house microbial culture manufacturing.
| Leading Market Players |
|---|
| BIOWAY ORGANIC HIGH TECH JOINT STOCK COMPANY |
| Suståne Natural Fertilizer Inc |
| DAI THANH JOINT STOCK COMPANY |
| Binh Dien Fertilizer Joint Stock Company |
| DAI NAM MANUFACTURING & TRADING COMPANY LIMITED |
| Biotech Bio-Agriculture |
| Song Gianh Corporation Joint Stock Company |
| Biofertilizer Vietnam Co. Ltd |
| Que Lam Group |
| Others |
Value Network & Pricing Analysis
Microbiologist technician scarcity in the Red River Delta widens pricing-tier spreads between ISO 17025-certified liquid formulations and commodity granular products, as qualified CFU enumeration personnel command wage premiums that filter into end-product pricing.
Pricing Analysis
Yield-guaranteed pricing anchors the Vietnam biofertilizer market, with manufacturers tying liquid formulation premiums to documented nitrogen-fixation outcomes in rice paddies. Three-tier pricing structure across premium, standard, and economy levels separates certified organic-matter blends from provincial cooperative-grade granular products. Price differentiation hinges on microbial count guarantees above 10^8 CFU per milliliter and cold-chain integrity documentation. Cost compression in commodity granular tiers is intensifying because molasses substrate costs fluctuate with sugarcane processing seasonality. Mekong Delta smallholders exhibit highest price sensitivity, while export-oriented vegetable cooperatives around Hanoi absorb premium tiers for EU market access compliance.
Supply Chain Analysis
Expired culture return flows remain underdeveloped, though alginate-encapsulation advances are extending viable shelf-life beyond eighteen months and reducing waste volumes. Domestic production draws from Thai and Indian phosphate-solubilizing fungal isolates, Vietnamese agricultural residue carriers, and imported laboratory equipment for qPCR enumeration. Raw material dependencies rest on molasses from domestic sugarcane processing, alginate from seaweed harvesting operations, and specialized microbial strains subject to Plant Protection Department import permit revisions. Single-source vulnerability concentrates in phosphate-solubilizing fungal supplies, where domestic culture collections lack documented efficacy in acidic Mekong Delta soils. Distribution runs through agricultural supply stores in rice-intensive provinces, direct sales to cooperatives in horticulture belts, and emerging e-commerce channels with cold-chain tracking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's biofertilizer sector is becoming a vertical-integration race, with manufacturers pursuing captive microbial culture production to escape third-party substrate cost volatility and strain import dependency.
For Market Incumbents: Anchor market position through backward integration into alginate microbead encapsulation manufacturing, eliminating third-party formulation premiums while extending shelf-life guarantees. Defend against emerging direct-to-cooperative challengers by securing exclusive cold-storage infrastructure leases at district-level aggregation points. Invest in Plant Protection Department relationship management to accelerate strain registration velocity ahead of pending import permit simplifications. For New Entrants and Emerging Players: Enter via the Central Highlands coffee rehabilitation segment, where mycorrhizal inoculant demand among Dak Lak export cooperatives outpaces registered supply. Target soil health applications for degraded robusta plantations, where multi-season field trial documentation requirements have constrained incumbent expansion. Pursue third-party analytical service contracts with Red River Delta formulators facing qPCR protocol compliance burdens as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with backward-integrated culture manufacturers given impending strain import permit revisions at the Plant Protection Department that could accelerate domestic R&D pipeline velocity. Long-term viability favors producers with captive microbial supply and ISO 17025-certified quality documentation capabilities. Monitor Plant Protection Department registration guideline revisions as the primary inflection indicator for domestic production economics versus import-dependent blenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbial Culture Production | Que Lam Group's captive substrate manufacturing eliminates third-party molasses cost volatility. |
| Alginate Microbead Encapsulation Scale-Up | Thai Binh rice cooperatives pilot eighteen-month shelf-life formulations for pre-sowing seed treatment. |
| Direct Sales Channel Formalization | Hanoi-surrounding vegetable cooperatives negotiate volume pricing bypassing agricultural supply retail markups. |
| Third-Party Analytical Service Consolidation | Red River Delta formulators outsource qPCR enumeration to meet Plant Protection Department registration protocols. |
| Cold-Storage Infrastructure Deployment | Hai Duong and Vinh Phuc cooperatives share commune-level live culture preservation investments. |
Research Methodology
Document review covered Plant Protection Department registration guidelines, ASEAN harmonized biosafety standards, and provincial organic agriculture transition mandates, complemented by interviews with biofertilizer formulators, agricultural cooperative procurement managers, and microbiology laboratory directors. Secondary validation drew from customs import records for microbial strains, Ministry of Agriculture and Rural Development acreage certification databases, and ISO 17025 accreditation registries. Bottom-up demand modeling triangulated against top-down sector expenditure estimates from national organic agriculture development scheme documentation.
Segment-level projections across formulation type, application crop, end-user channel, and regional cluster were generated through the analysis window using penetration rate assumptions tied to drip irrigation infrastructure expansion and cooperative formalization trends. CAGRs were derived from logistic adoption curves fitted to provincial organic transition mandate timelines and certified acreage targets. Industry-specific inputs included strain registration velocity at the Plant Protection Department and cold-chain infrastructure deployment rates in district cooperative networks.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt strain import permit restrictions or accelerated synthetic fertilizer phase-out schedules. Practitioners should monitor Plant Protection Department guideline revision announcements and provincial organic acreage certification velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Sulfur Fertilizer Market
Fertilizers
Compound Fertilizer Market
Fertilizers
Asia-Pacific Fertilizers Market
Fertilizers
North America Micronutrient Fertilizers Market
Fertilizers
Fertilizer Mixtures Market
Fertilizers
Nitrogen Fertilizer Additives Market
Fertilizers
Global Urea Market
Fertilizers
Fertilizer Tester Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
Biochar Fertilizer Market
Fertilizers
Global Liquid Fertilizer Market
Fertilizers
Slow Release NPK Fertilizer Market
Fertilizers
Europe Liquid Fertilizers Market
Fertilizers
Global Fertilizers Market
Fertilizers
Fertilizer Spreader Market