
 Biochar Fertilizer Market | 2026-2036
Biochar Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Biochar Fertilizer Market Analysis
The EU Green Deal is broadening the addressable market for carbon-negative soil amendments across member states. Biochar Now LLC leverages pyrolysis expertise to sustain cost leadership in bulk agricultural supply. Biogrow Limited anchors its position through specialized distribution to commercial horticulture clusters. SEEK Bio-Technology (Shanghai) Co. Ltd. competes on integrated production of bamboo-sourced formulations for Asian markets.
Biochar fertilizer denotes a carbon-rich soil amendment produced through thermal decomposition of biomass under oxygen-limited conditions, typically exhibiting pH ranges of 8.5–10.5 and surface areas exceeding 200 m²/g that enhance cation exchange capacity and water retention in degraded soils. Its primary commercial purpose centers on permanent carbon sequestration coupled with sustained nutrient delivery in intensive cropping systems. Hardwood biochar dominates volume flows due to established supply chains from timber processing residues, while bamboo biochar captures premium positioning in high-value horticultural applications where faster feedstock renewal supports sustainability credentials. Agricultural uses anchor overall demand through commodity crop adoption, though soil amendments represent the fastest-expanding category as regulators incorporate carbon permanence into environmental compliance frameworks.
The EPA oversees biochar classification under the Federal Insecticide, Fungicide, and Rodenticide Act when pesticidal claims arise, while USDA conservation programs increasingly subsidize biochar incorporation through Environmental Quality Incentives Program contracts. REACH registration requirements in Europe shape product composition transparency and restrict heavy metal thresholds in imported materials. Stakeholders must monitor evolving carbon credit verification protocols and fertilizer registration harmonization between jurisdictions to secure market access and capture policy-linked revenue streams.
Market Dynamics
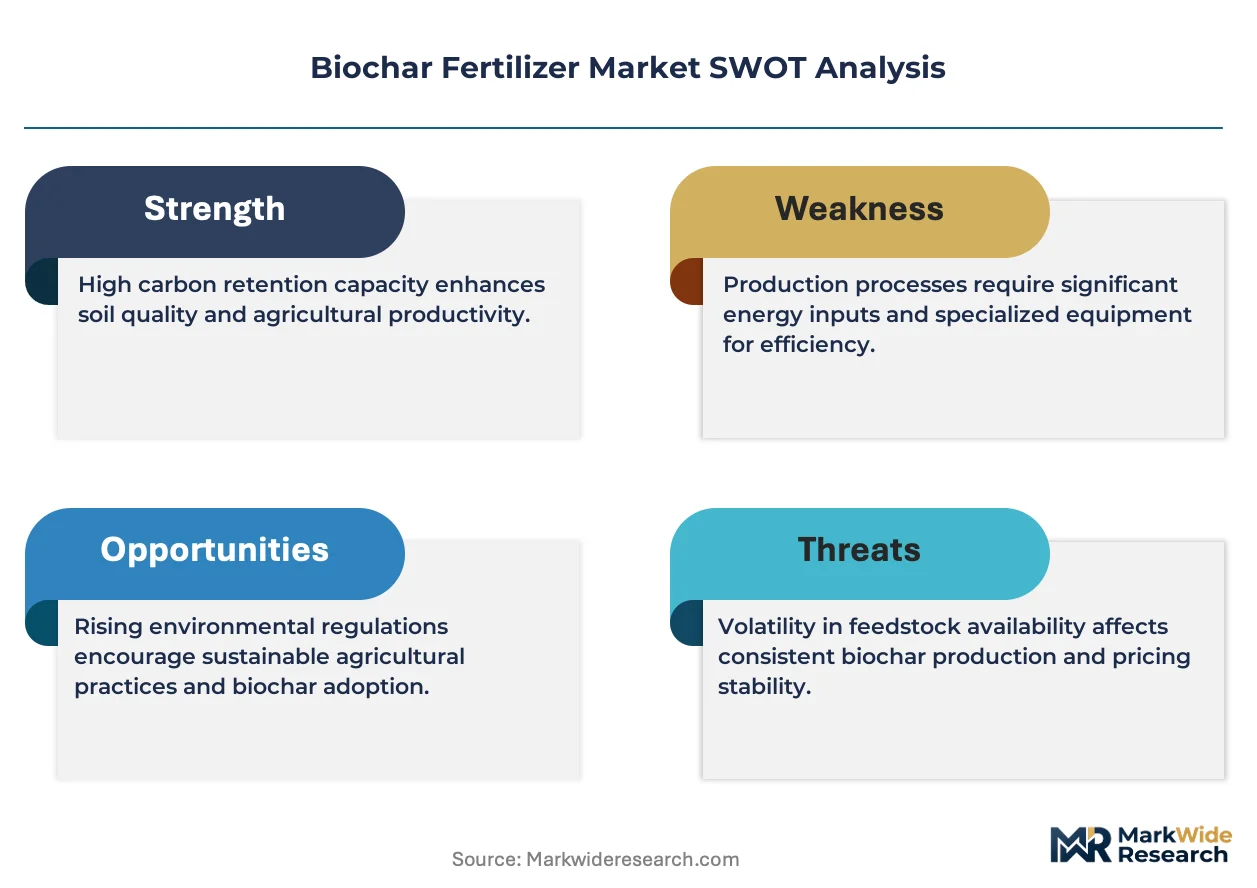
Carbon credit monetization protocols are restructuring competitive positioning across biochar fertilizer supply chains, forcing producers to secure third-party verification for soil carbon permanence claims.
Growth Catalysts
- EU Fertilizing Products Regulation:Harmonized cross-border approval pathways accelerate market access for carbon-based soil amendments across Germany, France, and the Netherlands.
- USDA Environmental Quality Incentives Program:Conservation contracts subsidize biochar incorporation costs for corn-soy operators in Iowa and Illinois.
- Hardwood residue pyrolysis:Established timber processing supply chains in the Pacific Northwest deliver feedstock cost advantages for bulk agricultural formulations.
Market Restraints
- Natural gas price volatility:Pyrolysis energy inputs constitute 35-40% of production costs, exposing margins to European benchmark fluctuations.
- Feedstock geographic concentration:Bamboo sourcing clusters in Sichuan and Zhejiang provinces create single-region dependency for premium horticultural grades.
- Heavy metal threshold restrictions:REACH registration requirements limit acceptable contaminant levels in imported biochar materials.
Strategic Opportunities
- Underpenetrated viticulture sector:Wine grape producers in California's Central Valley represent untapped demand for pH-adjusting soil amendments.
- Carbon removal credit stacking:Emerging verification frameworks enable dual revenue streams from soil amendment sales and offset certificate issuance.
- Direct-to-farm digital channels:E-procurement platforms are compressing distributor margins and enabling price transparency for Midwest commodity crop operators.
Industry Challenges
- Pyrolysis engineer scarcity:Specialized reactor operation expertise commands premium wages, constraining capacity expansion timelines.
- Carbon permanence certification delays:Third-party verification protocols require 18-24 month field trial documentation before credit issuance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biochar Fertilizer Market |
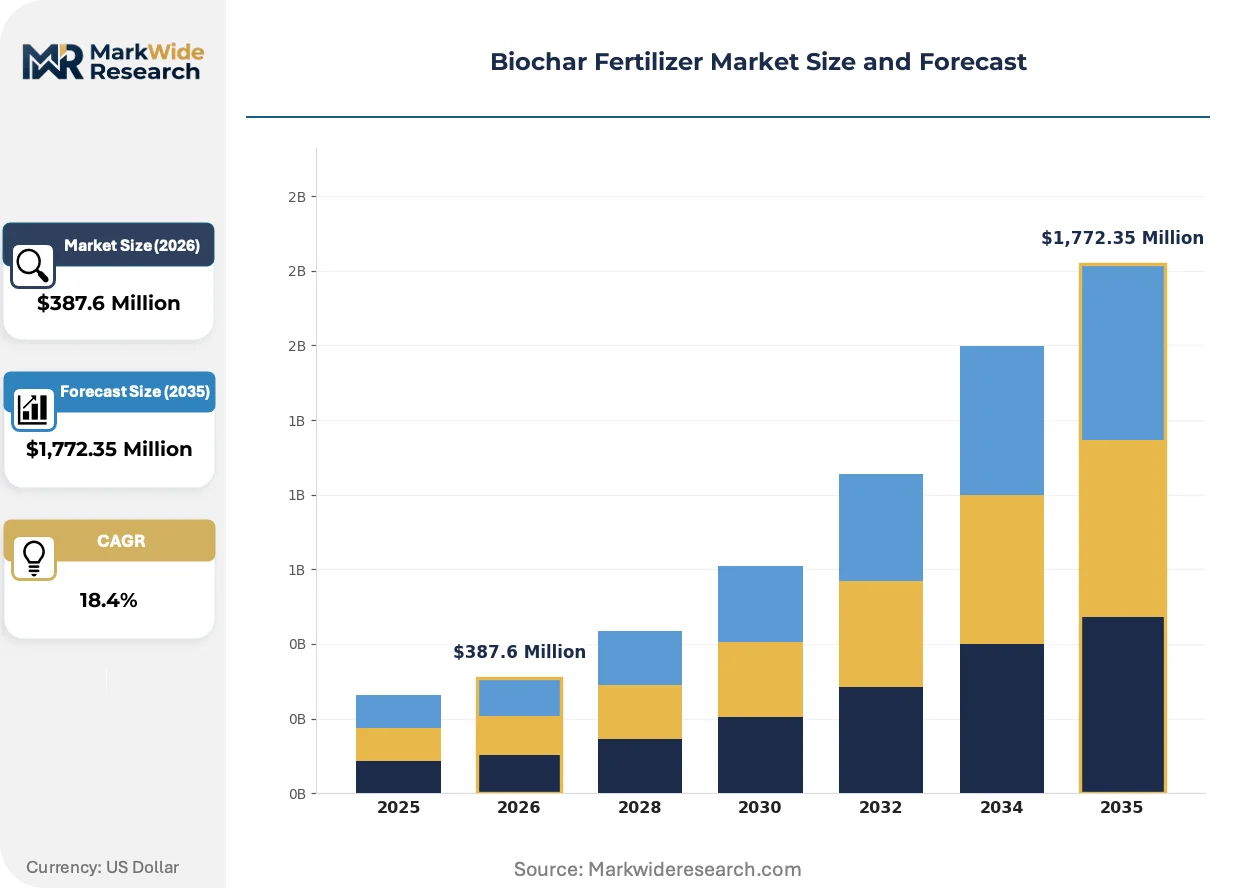
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pine Biochar, Bamboo Biochar, Coconut Coir Biochar, Hardwood Biochar Application: Agricultural Uses, Horticultural Uses, Soil Amendments, Waste Management End User: Agriculture Sector, Commercial Growers, Home Gardeners, Research Institutions Distribution Channel: Online Retail, Direct Sales, Agricultural Suppliers, Garden Stores |
| Companies Covered | Biochar Now LLC, Biochar Supreme LLC, FEECO International Inc., ArSta eco, Biogrow Limited, SEEK Bio-Technology (Shanghai) Co. Ltd., Bioforcetech Corporation, American Biochar Company, Phoenix Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biochar Fertilizer Market Emerging Trajectories
Thermal processing advances and regulatory recognition of carbon removal are compressing production costs while opening new revenue architectures for biochar suppliers.
Continuous-feed pyrolysis reactor designs are overtaking batch kiln configurations in commercial-scale operations. Corn ethanol producers in Minnesota and Nebraska deploy these systems to process agricultural residues with 40% lower labor intensity. The technology is compressing capital recovery timelines from five years to under three for integrated biorefinery operators.
REACH registration amendments in Europe mandate full heavy metal disclosure and restrict polycyclic aromatic hydrocarbon thresholds in imported biochar. German organic certifiers now require third-party laboratory documentation for sulfur and cadmium content. Dutch distributors have responded by establishing captive testing laboratories near Rotterdam port facilities to accelerate customs clearance.
Long-term offtake agreements are displacing spot market transactions among North American grain cooperatives. Iowa-based procurement consortia now contract three-year supply commitments with price collars indexed to natural gas benchmarks. The practice is most visible in the Corn Belt where input cost predictability outweighs flexibility premiums for risk-averse farm management companies.
Biochar Fertilizer Market Segmentation
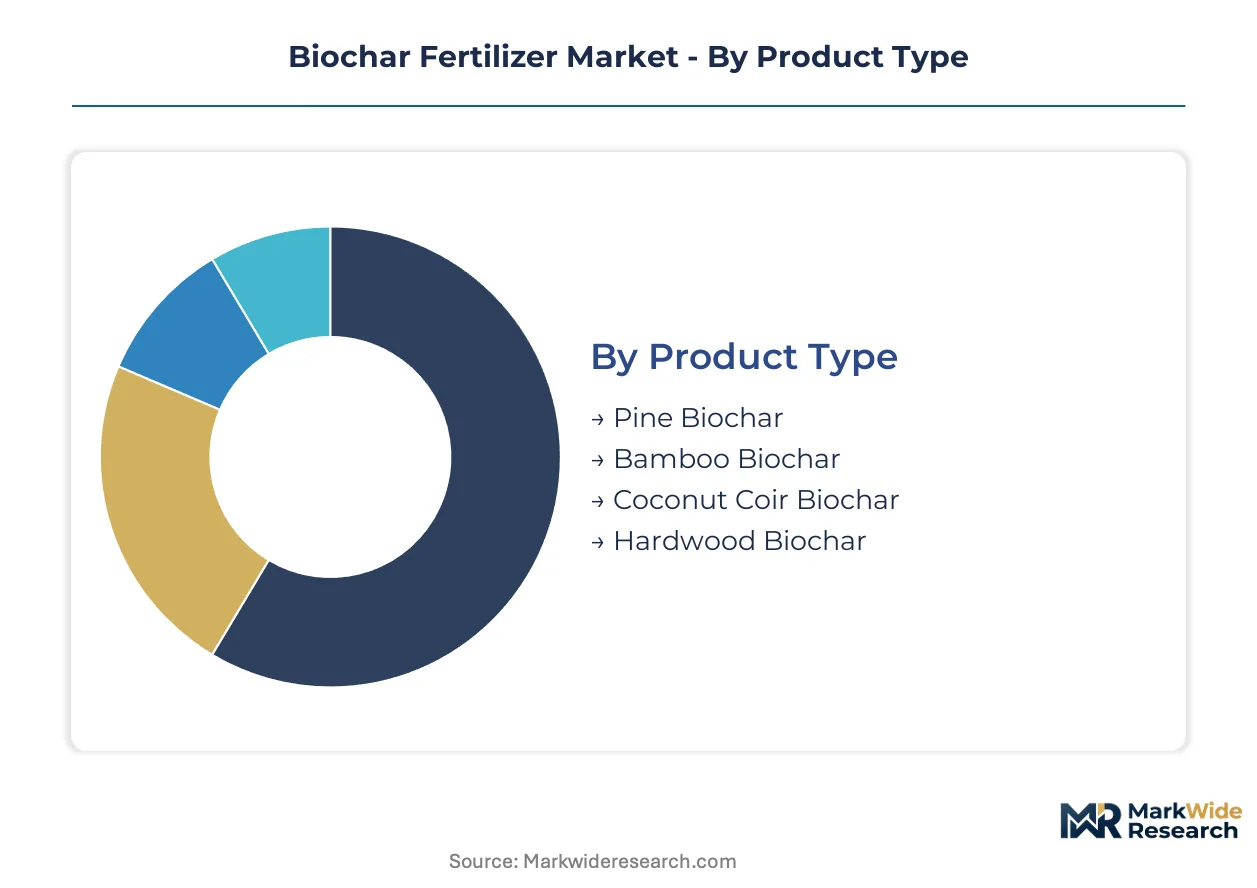
Biochar fertilizer segmentation reveals how feedstock chemistry, application intensity, and procurement sophistication create distinct commercial pockets. Suppliers configure pyrolysis parameters and certification levels to match buyer technical requirements and volume thresholds.
Product Type:
Cost tier differentiation separates commodity agricultural grades from premium horticultural formulations.
- Hardwood Biochar:Derived from oak, maple, and mixed deciduous residues with carbon content exceeding 75% and bulk density of 0.3-0.5 g/cm³. Corn-soy rotations across Iowa and Illinois drive procurement through USDA-subsidized conservation programs, though natural gas price volatility compresses pyrolysis margins.
- Bamboo Biochar:Rapid-renewal feedstock from Sichuan and Zhejiang provinces yields higher surface area (300-450 m²/g) and faster cation exchange kinetics. California viticulture and Dutch greenhouse clusters pay certification premiums for sustainability credentials tied to carbon credit verification.
- Pine Biochar:Softwood residues from Pacific Northwest timber operations deliver acidic pH variants suited for alkaline soil correction.
- Coconut Coir Biochar:Tropical biomass from Kerala and Sri Lanka processing facilities targets specialty orchid and bromeliad cultivation.
Hardwood biochar leads volumes today; bamboo biochar is gaining share fastest.
Application:
Application intensity governs formulation complexity and regulatory scrutiny levels.
- Soil Amendments:Carbon sequestration-focused incorporation at 5-20 tonnes per hectare requires third-party permanence verification under emerging EU carbon removal frameworks. German organic certifiers and Dutch distributors now mandate laboratory documentation for heavy metal thresholds before customs clearance.
- Agricultural Uses:Bulk commodity crop adoption emphasizes cost-per-tonne efficiency and equipment compatibility with existing spreader fleets. Minnesota and Nebraska corn ethanol producers integrate continuous-feed pyrolysis to process agricultural residues with reduced labor intensity.
- Horticultural Uses:Container media and greenhouse substrates demand consistent particle size distribution and low salinity indices.
- Waste Management:Biosolids co-composting applications face EPA classification review under FIFRA when pesticidal claims arise.
Agricultural uses anchor current demand; soil amendments show the steepest expansion trajectory.
End User:
Customer sophistication determines pricing architecture and technical service requirements.
- Commercial Growers:California Central Valley nut orchards and Florida citrus operations contract three-year supply commitments with price collars indexed to natural gas benchmarks. Iowa-based procurement consortia prioritize input cost predictability over flexibility premiums.
- Agriculture Sector:Commodity farm management companies leverage Environmental Quality Incentives Program contracts to offset biochar incorporation costs.
- Research Institutions:Field trial documentation for carbon permanence certification requires 18-24 month study periods before credit issuance.
- Home Gardeners:Small-package retail through garden stores and online channels emphasizes bagged convenience and application guidance.
The agriculture sector dominates procurement volumes; commercial growers are expanding fastest.
Distribution Channel:
Channel selection reflects order scale, technical support needs, and geographic concentration of demand.
- Direct Sales:Long-term offtake agreements displace spot market transactions among North American grain cooperatives. Integrated biorefinery operators in the Corn Belt compress capital recovery timelines through captive supply arrangements.
- Agricultural Suppliers:Established dealer networks in the Great Plains provide equipment compatibility guidance and bulk logistics coordination for hardwood-derived formulations.
- Online Retail:E-procurement platforms compress distributor margins and enable price transparency for Midwest commodity crop operators.
- Garden Stores:Premium horticultural grades reach home gardeners through specialty retail with sustainability labeling and application instructions.
Agricultural suppliers move the largest tonnages; direct sales channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pyrolysis engineers and agronomy researchers concentrate in Germany, the United States, and China, anchoring regional innovation clusters for biochar fertilizer production and field application science.
Germany
Organic farming cooperatives in Lower Saxony and Bavaria scale purchases of certified biochar amendments for soil carbon programs. The EU Fertilizing Products Regulation streamlines cross-border approval pathways for carbon-based soil inputs. Stuttgart-based testing laboratories now process heavy metal documentation for Dutch distributors seeking accelerated customs clearance.
United States
Corn-soy rotations across Iowa and Illinois drive bulk procurement of hardwood-derived formulations through subsidized conservation contracts. The USDA Environmental Quality Incentives Program offsets incorporation costs for commodity crop operators. Minnesota ethanol producers deploy continuous-feed pyrolysis systems to process agricultural residues with reduced labor intensity.
China
Bamboo sourcing clusters in Sichuan and Zhejiang provinces supply premium horticultural grades for Asian greenhouse markets. The country's dual carbon goals incentivize biochar integration into provincial soil remediation programs. Shanghai-based distributors coordinate export logistics for bamboo-sourced formulations targeting high-value cultivation segments.
Netherlands
Dutch greenhouse operators in Westland and Aalsmeer prioritize carbon-negative substrates for ornamental and vegetable production. REACH registration requirements mandate full heavy metal disclosure for imported biochar materials. Rotterdam port facilities host captive testing laboratories to accelerate verification workflows for arriving shipments.
India
Coconut coir processing facilities in Kerala generate tropical biomass feedstocks for specialty orchid cultivation markets. The country's agricultural extension programs pilot biochar incorporation in degraded soil districts. Maharashtra-based agritech startups coordinate field trials with state universities to document carbon permanence for emerging credit frameworks.
Biochar Fertilizer Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the biochar fertilizer landscape. Integrated pyrolysis operators with captive timber or agricultural residue supplies dominate bulk agricultural volumes, while specialized blenders and certification-focused distributors capture premium horticultural margins. The market structure separates into three archetypes: continuous-feed reactor operators, batch kiln regional suppliers, and carbon credit verification specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure feedstock offtake and field trial documentation for permanence certification.
Among North American operators, Biochar Now LLC and Biochar Supreme LLC exemplify the scale-driven archetype with integrated production models. SEEK Bio-Technology (Shanghai) Co. Ltd. occupies a position within the Asia-Pacific supply tier, representing the bamboo-sourced specialization vector. Biogrow Limited anchors the distribution-focused segment, exemplifying how European players leverage regulatory familiarity to capture premium positioning in certified organic channels.
| Leading Market Players |
|---|
| Biochar Now LLC |
| Biochar Supreme LLC |
| FEECO International Inc. |
| ArSta eco |
| Biogrow Limited |
| SEEK Bio-Technology (Shanghai) Co. Ltd. |
| Bioforcetech Corporation |
| American Biochar Company |
| Phoenix Energy |
| Others |
Supply Flow & Price Mechanics
Continuous-feed pyrolysis reactor adoption across Minnesota and Nebraska biorefineries compresses labor intensity by 40% while concentrating production economics among integrated operators with captive agricultural residue streams. This technology shift simultaneously lowers unit production costs and reinforces supply concentration around Corn Belt ethanol producers who control both feedstock sourcing and thermal processing capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates bamboo-sourced horticultural grades from hardwood-derived agricultural formulations and softwood residue commodity products. Certification premiums for EU Fertilizing Products Regulation compliance and carbon credit verification drive 15-25% price elevation at the premium tier. Cost compression in standard-grade hardwood biochar intensifies because natural gas price volatility exposes pyrolysis margins, with Iowa-based procurement consortia demanding price collars indexed to energy benchmarks. Commercial growers in California Central Valley nut orchards show least price sensitivity due to three-year supply commitment structures, while Midwest commodity crop operators exhibit highest sensitivity to per-tonne delivered costs.
Supply Chain Analysis
REACH registration and USDA conservation program certification gating restricts market access to producers with documented heavy metal thresholds and third-party laboratory verification capabilities. Feedstock sourcing concentrates in the United States, Germany, and China, with hardwood residues from Pacific Northwest timber operations, Lower Saxony organic farming cooperatives, and Sichuan bamboo plantations anchoring regional supply bases. Pyrolysis operations rest on natural gas energy inputs, specialized reactor engineering talent, and timber processing residue contracts. Single-region dependency for premium bamboo grades in Zhejiang province creates structural vulnerability to provincial environmental enforcement actions. Distribution runs through agricultural supplier dealer networks in the Great Plains for bulk volumes, direct long-term offtake agreements for integrated biorefinery operators, and e-procurement platforms compressing Midwest distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biochar fertilizer market compounds steadily as carbon removal credit verification frameworks institutionalize dual revenue streams from soil amendment sales and offset certificate issuance. Regulatory incorporation of carbon permanence into environmental compliance frameworks sustains demand visibility across agricultural and horticultural buyer segments.
For Market Incumbents: Extend captive feedstock control through backward integration into timber processing residues and agricultural waste streams to defend against pyrolysis margin compression from natural gas price volatility. Secure 18-24 month field trial documentation with German organic certifiers and Dutch distributors to accelerate carbon permanence certification timelines and capture policy-linked revenue streams before emerging verification protocols mature. For New Entrants and Emerging Players: California Central Valley viticulture operations represent an underserved buyer archetype with untapped demand for pH-adjusting soil amendments in wine grape production. Target this segment through specialized agronomic technical service bundled with certified organic grades, leveraging sustainability credentials tied to carbon credit verification to bypass established agricultural supplier channel control in commodity crop markets. For Investors and Strategic Acquirers: Valuations sit cheapest among batch kiln regional suppliers lacking integrated feedstock positions or certification infrastructure. The five-to-ten year viability window favors acquisition of continuous-feed reactor operators with USDA Environmental Quality Incentives Program contract pipelines and captive testing laboratory capabilities. Monitor EU Fertilizing Products Regulation harmonization progress across member states as the inflection signal for cross-border market access expansion and premium pricing capture.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Feed Pyrolysis Capacity Expansion | Corn Belt ethanol producers compress capital recovery timelines through integrated agricultural residue processing. |
| Captive Testing Laboratory Establishment | Dutch distributors near Rotterdam accelerate REACH compliance verification and customs clearance workflows. |
| Long-Term Offtake Agreement Structuring | Iowa procurement consortia secure input cost predictability through price collars indexed to natural gas benchmarks. |
| Carbon Credit Verification Partnership | German organic certifiers enable dual revenue streams from soil amendment sales and offset certificate issuance. |
| Direct-to-Farm Digital Channel Development | E-procurement platforms compress distributor margins and enable price transparency for Midwest commodity operators. |
Methodological Framework
Coverage spans Germany, the United States, China, and the Netherlands, with primary inputs from each market combining structured interviews with pyrolysis plant managers, agricultural procurement leads at grain cooperatives, regulatory affairs specialists at German organic certifiers, and distribution channel partners in Dutch greenhouse clusters. Secondary validation draws from EU Fertilizing Products Regulation filings, USDA Environmental Quality Incentives Program contract databases, REACH registration documentation, and SEC filings of integrated biorefinery operators. Bottom-up volume estimates triangulate against top-down carbon removal credit market projections.
Rate-of-change decomposition across the projection horizon segments growth by feedstock chemistry, application intensity, and end-user sophistication. The analytical framework models hardwood, bamboo, pine, and coconut coir variants; soil amendment, agricultural, horticultural, and waste management applications; and commercial grower, agriculture sector, research institution, and home gardener end users. CAGRs derive from regression analysis of historical conservation program enrollment, pyrolysis capacity expansion announcements, and carbon credit issuance trajectories. Forecast inputs include natural gas price volatility assumptions, EU Green Deal implementation pacing, and bamboo feedstock renewal rates.
Inputs from regulatory filing databases and primary stakeholder interviews were available through the study window; gaps in real-time carbon permanence field trial completion data introduce uncertainty bands around credit monetization timing assumptions. Forecasts reflect documented assumptions regarding pyrolysis technology adoption curves and conservation program subsidy continuity. A model refresh is warranted upon material change in EU carbon removal framework finalization or natural gas benchmark sustained price shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Fertilizer Mixtures Market
Fertilizers
Vietnam Specialty Fertilizer Market
Fertilizers
Vietnam Organic Fertilizer Market
Fertilizers
Saudi Arabia Fertilizer Market
Fertilizers
South America Micronutrient Fertilizer Market
Fertilizers
Egypt Fertilizer Market
Fertilizers
Humate Fertilizer Market
Fertilizers
South America Specialty Fertilizer Market
Fertilizers
United States Organic Fertilizers Market
Fertilizers
Russia Micronutrient Fertilizer Market
Fertilizers
Global Water Soluble Fertilizer Market
Fertilizers
Calcium Ammonium Nitrate Market
Fertilizers
Polymer Coated Urea Market
Fertilizers
Blue-Green Algae Fertilizer Market
Fertilizers
Phosphate Fertilizers Market
Fertilizers
Russia Fertilizers Market