
 Argentina Fertilizer Market | 2026-2036
Argentina Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Fertilizer Market Insights
ISO 9001 quality management certification is collapsing as a baseline barrier for Argentine fertilizer suppliers seeking export eligibility and domestic tender participation. Profertil leverages its integrated ammonia-urea complex at Bahía Blanca to control feedstock costs and supply reliability. EuroChem Group competes through specialized phosphate-based formulations tailored to Pampas soil chemistry. Yara International ASA extends its digital farming platform to Argentine cooperatives, bundling agronomic advisory with product sales.
Fertilizers encompass chemically synthesized or organically derived nutrient formulations containing nitrogen, phosphorus, and potassium compounds in specified N-P-K ratios, manufactured through Haber-Bosch ammonia synthesis, phosphate rock acidulation, or potash refining processes, designed to replenish soil macronutrients and correct micronutrient deficiencies in commercial crop systems. Urea dominates Argentine product volumes due to its high nitrogen concentration and established domestic manufacturing base, while NPK blends capture expanding share among precision agriculture adopters seeking customized nutrient prescriptions. Specialty calcium carbonate applications occupy a narrower but defensible niche in acidic soil correction programs across Misiones and Corrientes provinces.
SENASA enforces phytosanitary and residue limit protocols that govern fertilizer import approvals and domestic product registration timelines. The Secretariat of Agriculture, Livestock and Fisheries administers input subsidy programs that influence seasonal purchasing patterns and product specification requirements. Argentina's INTA research institute develops region-specific fertilization protocols that shift farmer preferences toward validated formulation types. Stakeholders must monitor evolving bio-input regulations and carbon footprint disclosure requirements that could reshape competitive positioning in Argentine fertilizer procurement channels.
Market Dynamics
SENASA phytosanitary certification requirements are compressing product registration timelines and reshaping competitive access for imported fertilizer formulations. Large-scale soybean cooperatives in Buenos Aires province now demand validated nutrient protocols from INTA, forcing suppliers to demonstrate field-efficacy data before contract awards.
Growth Catalysts
- INTA Fertilization Protocols:Region-specific research validating customized N-P-K blends accelerates adoption among precision agriculture operators in Córdoba and Santa Fe provinces.
- Soybean Cultivation Intensity:Expanding planted area across the Pampas drives sustained nitrogen demand, particularly for urea top-dressing applications during critical growth stages.
- Input Subsidy Programs:Secretariat of Agriculture administered credit lines for seasonal purchasing smooth cash-flow constraints for commercial farming enterprises above 500 hectares.
Market Restraints
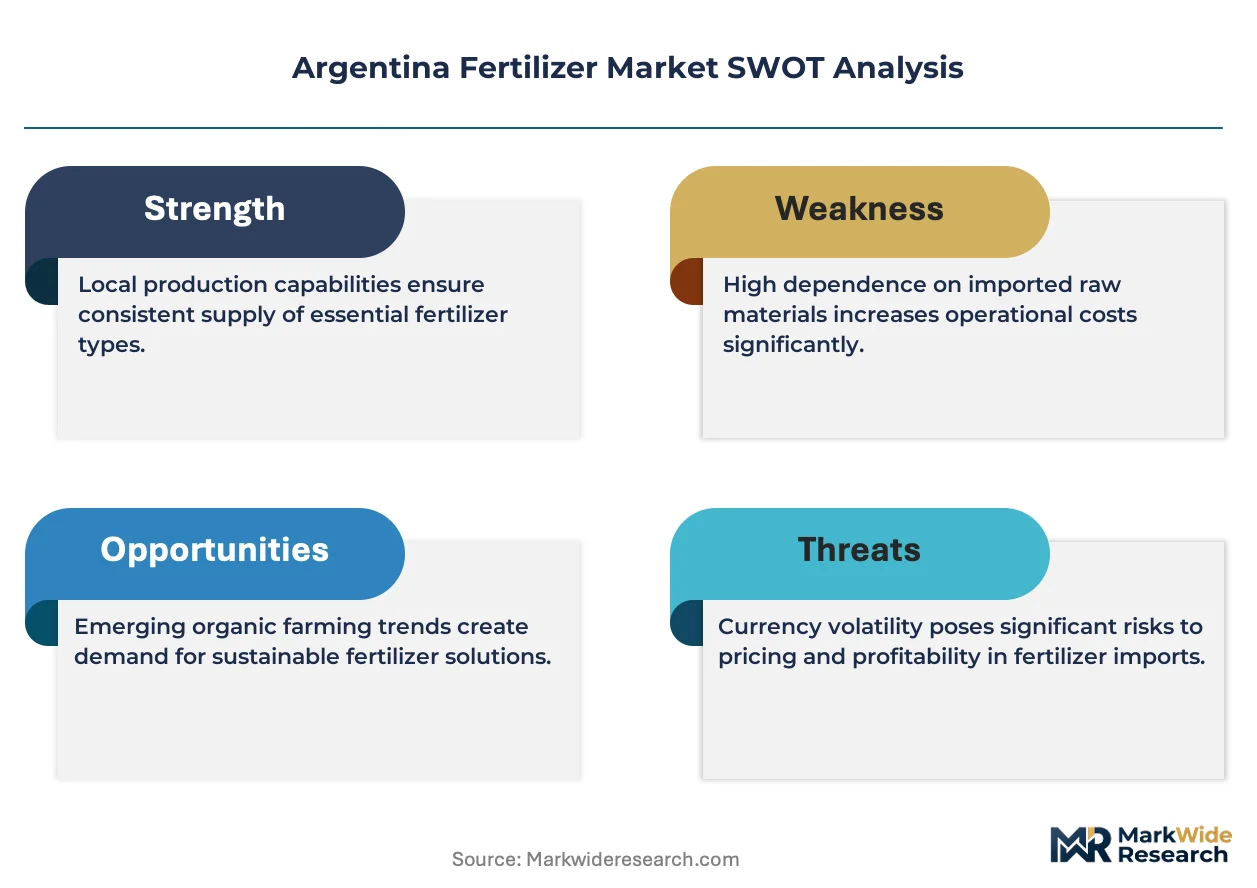
- Natural Gas Feedstock Volatility:Ammonia production costs at Bahía Blanca complexes fluctuate with domestic gas tariff adjustments, compressing margin visibility for nitrogen manufacturers.
- Import Dependency for Phosphate Rock:Domestic acidulation capacity relies on Moroccan and Brazilian phosphate concentrate, exposing blenders to ocean freight rate swings and port congestion at Rosario.
- SENASA Residue Limit Protocols:Extended laboratory testing timelines for new product registrations delay market entry by 18-24 months for specialty micronutrient formulations.
Strategic Opportunities
- Misiones Province Acidic Soils:Underpenetrated calcium carbonate correction programs present white-space expansion for specialty limestone distributors with localized grinding capacity.
- Digital Agronomy Bundling:Convergence of satellite imagery analytics with variable-rate application equipment enables outcome-based fertilizer prescriptions for cooperative members.
- Bio-Input Regulatory Tailwind:Draft frameworks for biological fertilizer categorization at SENASA create first-mover positioning for microbial inoculant developers with existing phytosanitary dossiers.
Industry Challenges
- Agronomic Advisory Talent Scarcity:Certified crop consultants capable of interpreting soil grid-sampling data remain concentrated in Buenos Aires, limiting precision-agriculture rollout to Entre Ríos and La Pampa.
- Legacy Equipment Integration:Variable-rate spreader retrofits for existing tractor fleets require capital outlays that mid-tier cooperatives defer amid interest rate volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Fertilizer Market |
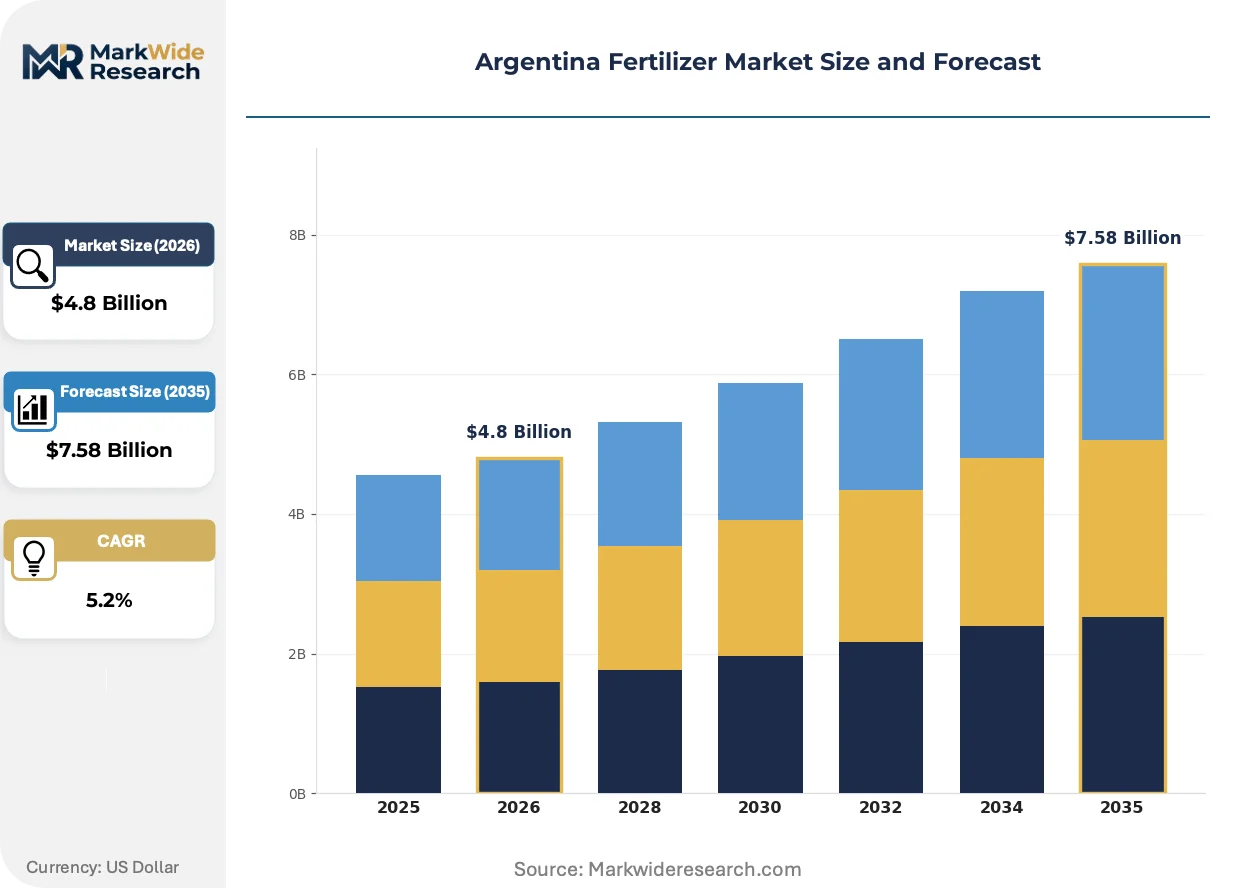
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urea, Ammonium Nitrate, NPK, Calcium Carbonate End User: Agriculture, Horticulture, Turf Management, Greenhouse Application: Crop Production, Soil Fertility, Turf Growth, Specialty Crops Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Profertil, EuroChem Group, Yara International ASA, Pampa Energía, Adecoagro, Nutrien Ltd., Grupa Azoty S.A. (Compo Expert), Adufértil Fertilizantes, Bunge Global SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Fertilizer Market Trends and Innovations
Digital farming platforms are embedding fertilizer decision-support tools directly into cooperative procurement workflows, collapsing the traditional separation between agronomic advice and product supply. This convergence is compressing distributor margins while elevating technical service capabilities as the primary competitive differentiator.
Controlled-release polymer coatings for urea granules are supplanting conventional split-application practices among large-scale operators. Farmers exceeding 2,000 hectares in Córdoba province are adopting these formulations to reduce labor costs and nitrogen volatilization losses. The technology is enabling single-pass fertilization windows that align with narrow planting schedules, compressing the traditional application service provider market.
SENASA is tightening residue limit documentation requirements for imported organic fertilizer substrates, particularly those derived from animal processing byproducts. This regulatory friction is extending registration timelines for Brazilian and Uruguayan biofertilizer exporters seeking Argentine market access. Specialty compounders with existing domestic composting infrastructure are capturing share from import-dependent distributors.
Cooperative procurement committees are consolidating annual fertilizer tenders into multi-year framework agreements with volume guarantees. This behavioral shift displaces spot-market purchasing that traditionally characterized seasonal input acquisition. The transformation is most visible in Buenos Aires province, where three large cooperatives now represent over 40 percent of regional urea offtake.
Argentina Fertilizer Market Segmentation
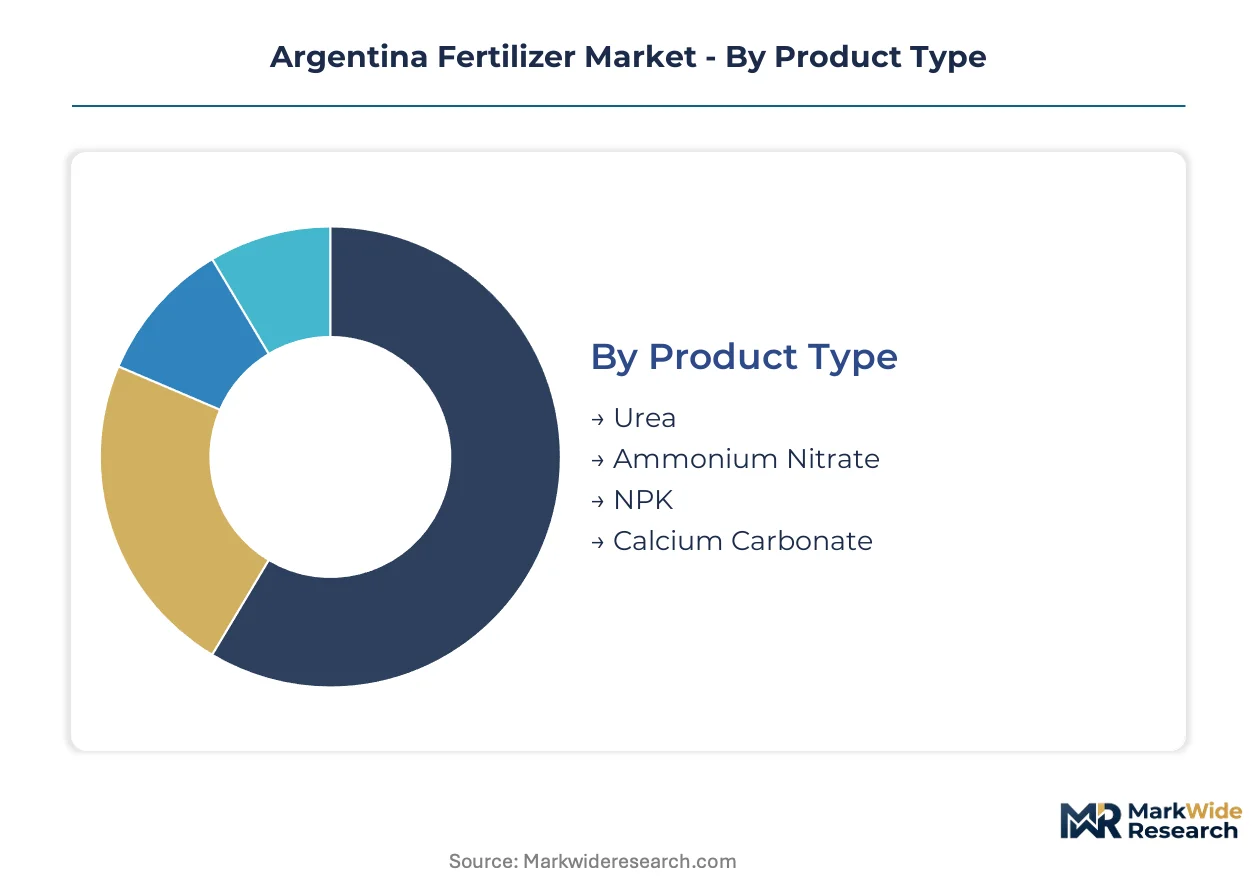
Segmentation in the Argentine fertilizer market reveals distinct procurement patterns across product chemistry, end-use intensity, and channel preference. Suppliers configure production and distribution assets differently for each slice, with SENASA registration requirements applying variably by formulation type.
Product Type:
Domestic manufacturing capacity concentrates on nitrogenous compounds, while phosphate and specialty products rely more heavily on imported inputs subject to port logistics at Rosario.
- Urea:High-nitrogen crystalline formulation produced through Haber-Bosch ammonia synthesis at Bahía Blanca complexes. Demand concentrates in Buenos Aires province soybean operations where top-dressing protocols dominate during R1-R2 reproductive stages. Natural gas tariff volatility at domestic ammonia plants compresses margin stability for nitrogen manufacturers.
- NPK:Custom-blended macronutrient formulations with variable N-P-K ratios tailored to Pampas soil grid sampling. Precision agriculture adopters in Córdoba and Santa Fe provinces drive expanding share for validated INTA protocols. Blenders source phosphate concentrate from Moroccan import streams, exposing formulations to ocean freight rate swings.
- Ammonium Nitrate:Granular explosive-grade derivative with secondary agricultural application, subject to strict transport and storage regulations. Security protocols limit distribution to authorized agricultural cooperatives with certified handling infrastructure.
- Calcium Carbonate:Finely ground limestone for acidic soil correction in Misiones and Corrientes provinces. Localized grinding capacity constraints limit penetration despite agronomic validation from INTA research stations.
Urea commands the established base. The steepest expansion runs through NPK precision blends.
End User:
Volume scale and technical sophistication diverge sharply across user categories, with subsidy eligibility and credit access filtering participation.
- Agriculture:Large-scale commercial farming enterprises above 500 hectares in the Pampas region, representing the dominant consumption base. Secretariat of Agriculture credit lines smooth seasonal purchasing for soybean-wheat rotation systems.
- Horticulture:Medium-scale fruit and vegetable producers in Mendoza and Río Negro valleys with specialized micronutrient requirements. Water quality concerns in irrigation districts elevate demand for chloride-free potassium sources.
- Turf Management:Golf course and sports field maintenance operations concentrated in Greater Buenos Aires and coastal resort municipalities. Aesthetic performance standards drive preference for slow-release nitrogen formulations with reduced burn risk.
- Greenhouse:Protected cultivation facilities in peri-urban zones supplying fresh produce to capital region markets. Hydroponic substrate systems require water-soluble fertilizer grades with guaranteed heavy metal limits.
Agriculture absorbs the volume concentration. Greenhouse operations are climbing the fastest on a percentage basis.
Application:
Functional purpose determines formulation specification, with SENASA residue protocols applying differentially to food versus non-food crop systems.
- Crop Production:Broad-acre grain and oilseed cultivation across the Pampas and Entre Ríos provinces. Variable-rate application equipment penetration remains concentrated in Buenos Aires due to agronomic advisory talent scarcity.
- Soil Fertility:Long-term nutrient capital restoration programs targeting degraded pasturelands in La Pampa and San Luis. Gypsum and organic amendment integration complicates pure fertilizer positioning in this segment.
- Turf Growth:Establishment and maintenance of recreational and ornamental grass surfaces with visual uniformity requirements. Iron and manganese micronutrient packages differentiate premium offerings from commodity nitrogen.
- Specialty Crops:High-value export-oriented production including blueberries in Tucumán and wine grapes in Mendoza. GLOBALG.A.P. certification requirements elevate documentation standards for input traceability.
Crop production anchors volume throughput. Specialty crops are gaining share fastest on value per hectare metrics.
Distribution Channel:
Channel selection reflects buyer scale, technical support requirements, and working capital management preferences across the agricultural calendar.
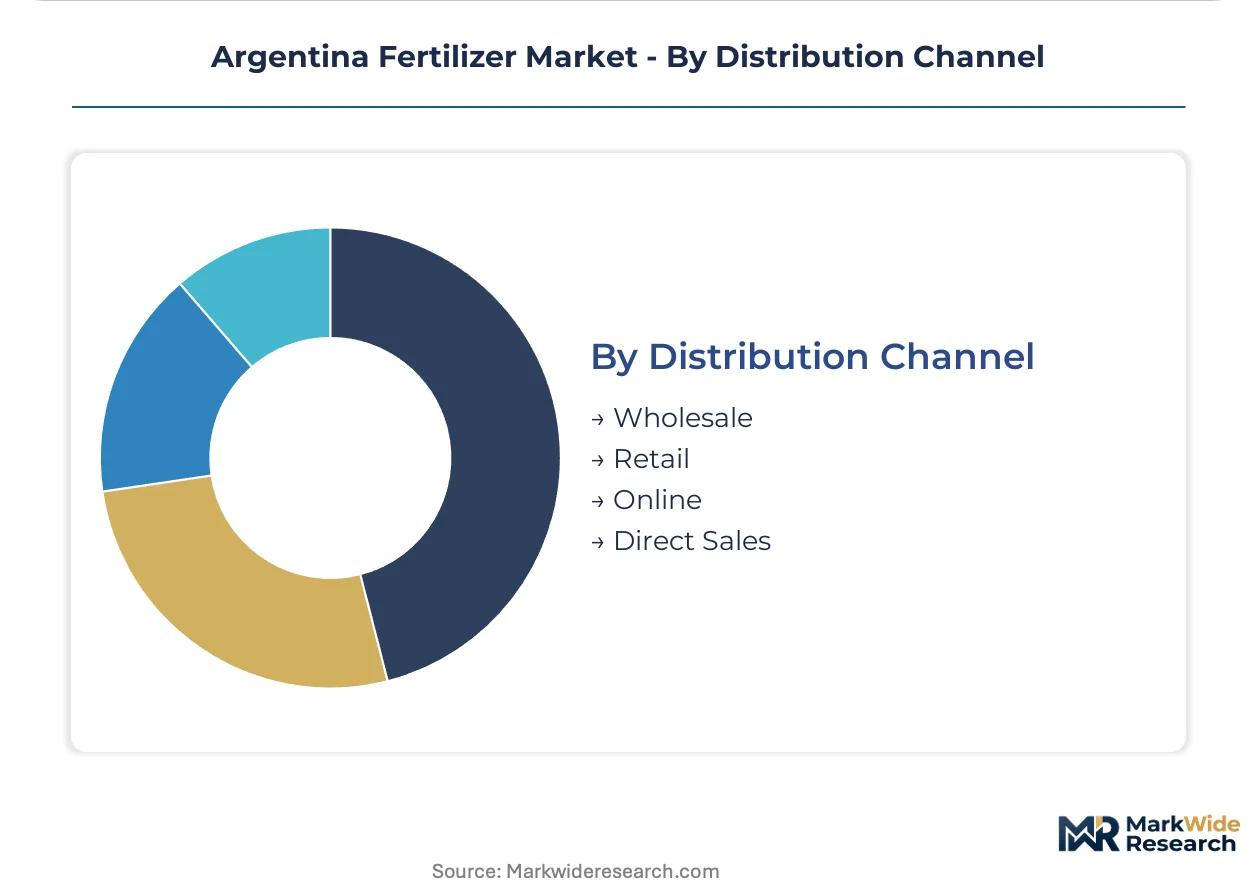
- Wholesale:Bulk procurement by cooperative federations and large commercial aggregators with storage infrastructure. Multi-year framework agreements with volume guarantees are displacing spot-market purchasing in Buenos Aires province.
- Retail:Regional distributor networks serving mid-tier farmers below 500 hectares with credit terms and agronomic advice. Margin compression from digital platform competition is forcing consolidation among independent agro-input stores.
- Online:Emerging procurement channel for standardized products with transparent pricing and documented specifications. Younger farm managers in Santa Fe and Entre Ríos are piloting platform-based purchasing for non-urgent input needs.
- Direct Sales:Manufacturer-to-farmer relationships for large accounts with dedicated agronomist support and custom blending services. Profertil and Yara maintain direct technical teams for cooperative network penetration.
Wholesale channels control the volume base. Online platforms are expanding most quickly from minimal starting penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale soybean cooperatives in Buenos Aires province dominate procurement volumes, with commercial farming enterprises above 500 hectares driving demand concentration across the Pampas region.
Buenos Aires Province
Soybean-wheat rotation systems consume the majority of urea volumes for top-dressing applications during R1-R2 reproductive stages. Secretariat of Agriculture credit lines smooth seasonal purchasing for cooperatives exceeding 2,000 hectares. Bahía Blanca hosts integrated ammonia-urea manufacturing complexes supplying nitrogen feedstock to regional blenders.
Córdoba Province
Precision agriculture adopters validate customized N-P-K blends through INTA research protocols. Variable-rate application equipment penetration accelerates among commercial operators seeking grid-sampled nutrient prescriptions. The Córdoba metropolitan corridor anchors distributor networks serving mid-tier farmers transitioning from commodity to specialty formulations.
Santa Fe Province
Younger farm managers pilot digital procurement platforms for standardized products with transparent pricing documentation. SENASA phytosanitary certification requirements compress registration timelines for imported specialty micronutrients. The Rosario port cluster handles phosphate concentrate imports from Moroccan sources for regional blending operations.
Entre Ríos Province
Agronomic advisory talent scarcity limits precision-agriculture rollout despite favorable soil conditions for diversified crop production. Legacy equipment integration challenges defer variable-rate spreader retrofits among mid-tier cooperatives facing interest rate volatility. The Paraná River corridor facilitates bulk fertilizer logistics for broad-acre grain cultivation.
Misiones Province
Acidic soil correction programs present underpenetrated expansion opportunities for specialty limestone distributors. INTA research stations validate calcium carbonate applications for degraded pastureland restoration. Localized grinding capacity constraints limit penetration despite agronomic validation and cooperative demand.
Argentina Fertilizer Market Competitive Landscape
Player mix skews toward integrated domestic manufacturers with captive feedstock supply and international specialty formulators with SENASA-registered product portfolios. Market structure concentrates around three to five dominant suppliers controlling ammonia production and import distribution infrastructure. Strategic archetypes include integrated nitrogen manufacturers, specialized phosphate compounders, and digital agronomy platform operators. Competitive dynamics center on backward integration into natural gas feedstocks and multi-year framework agreements with cooperative procurement committees.
Among integrated domestic producers, Profertil anchors the nitrogen manufacturing tier through its Bahía Blanca complex position. EuroChem Group and Yara International ASA represent the international specialty formulator archetype with SENASA-registered portfolios and direct technical service teams. These three companies exemplify the competitive tension between feedstock cost control and digital advisory bundling as alternative paths to cooperative network penetration.
| Leading Market Players |
|---|
| Profertil |
| EuroChem Group |
| Yara International ASA |
| Pampa Energía |
| Adecoagro |
| Nutrien Ltd. |
| Grupa Azoty S.A. (Compo Expert) |
| Adufértil Fertilizantes |
| Bunge Global SA |
| Others |
Pricing and Supply Chain Analysis
SENASA phytosanitary certification gates both supply qualification and price differentiation simultaneously, compressing registration timelines for importers while elevating technical validation premiums for domestic compounders with established dossiers. This regulatory architecture concentrates pricing power among incumbent suppliers with captive ammonia production or pre-cleared specialty portfolios.
Pricing Analysis
Cost-plus contracts with Henry Hub and Brent indexation dominate long-term offtake agreements between Bahía Blanca nitrogen manufacturers and Buenos Aires cooperative federations. Price differentiation hinges on SENASA registration tier and volume scale, with INTA-validated formulations commanding premiums over generic blends. Cost compression in standard urea intensifies as natural gas tariff volatility squeezes ammonia plant margins. Mid-tier cooperatives below 1,000 hectares exhibit acute price sensitivity, while large-scale operators prioritize supply security over per-tonne differentials.
Supply Chain Analysis
Argentina and Morocco anchor phosphate concentrate supply, with domestic acidulation capacity at Rosario drawing from Moroccan rock and Brazilian processed inputs. Ammonia production rests on domestic natural gas feedstock, while potash arrives from Canadian and Belarusian sources via Atlantic shipping lanes. Single-source vulnerability concentrates in phosphate rock imports through Rosario port congestion. Distribution runs through cooperative federations with seasonal storage infrastructure and direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: SENASA registration timelines create switching costs that lock cooperative procurement committees into validated supplier relationships.
For Market Incumbents: Fortify backward integration into natural gas feedstock through long-term tariff agreements with upstream producers, insulating margin visibility from domestic energy policy swings. Expand grinding capacity in Misiones to capture calcium carbonate demand before specialty distributors establish local presence. Digital agronomy bundling from Yara and EuroChem threatens technical service differentiation—invest in certified crop consultant training pipelines to maintain advisory edge. For New Entrants and Emerging Players: Lead with microbial inoculant formulations targeting SENASA's draft bio-input categorization framework, securing first-mover phytosanitary dossiers before regulatory clarity hardens. Misiones Province acidic soil correction offers the most penetrable white-space, with INTA validation already established and localized grinding capacity scarce. Partner with Entre Ríos mid-tier cooperatives facing agronomic advisory talent scarcity, delivering outcome-based nutrient prescriptions through satellite imagery analytics. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision-blending infrastructure as variable-rate application equipment penetration accelerates. Five-to-ten year viability favors acquiring domestic compounders with existing SENASA registrations and Rosario port access rather than greenfield import-dependent entrants. Monitor SENASA residue limit protocol amendments as the critical inflection signal—tightening timelines would compress specialty formulation margins while benefiting incumbent domestic manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Gas Feedstock | Profertil's Bahía Blanca complex demonstrates margin insulation through captive ammonia supply. |
| SENASA Bio-Input Registration Investment | Early microbial inoculant dossiers secure positioning ahead of regulatory framework finalization. |
| Digital Agronomy Platform Deployment | Yara's cooperative bundling collapses traditional distributor margins while elevating technical service value. |
| Misiones Grinding Capacity Expansion | Localized limestone production captures INTA-validated acidic soil correction demand. |
| Multi-Year Cooperative Framework Agreements | Buenos Aires volume guarantees displace spot-market purchasing and lock in offtake visibility. |
Research Methodology
Initial hypotheses were tested against primary input from cooperative procurement managers, SENASA regulatory affairs specialists, INTA research station agronomists, and blending plant operations directors, then refined through secondary validation against customs trade records, Secretariat of Agriculture subsidy disbursement data, SEC filings from listed agricultural input companies, and Rosario port logistics reports. Bottom-up volume estimates from provincial fertilizer consumption surveys were triangulated against top-down macroeconomic indicators.
Variance decomposition across product chemistry, end-use intensity, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth trajectory modeling incorporating soybean cultivation expansion rates, natural gas tariff adjustment scenarios, and precision agriculture equipment penetration curves. Forecast inputs included INTA protocol validation timelines and SENASA registration backlog projections.
The analysis sits within stated boundaries; outcomes outside sustained Secretariat of Agriculture credit line availability or stable SENASA regulatory interpretation would require recalibration. Forecasts reflect documented assumptions regarding phosphate rock import continuity and domestic ammonia plant operating rates. Recalibration cycles align with material shifts in bio-input regulatory frameworks and cooperative procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Global Phosphatic Fertilizers Market
Fertilizers
Fertilizer Additives Market
Fertilizers
Sulfur Fertilizer Market
Fertilizers
Russia Specialty Fertilizer Market
Fertilizers
Nitro Compound Fertilizers Market
Fertilizers
Neem-Based Fertilizers Market
Fertilizers
Russia Fertilizers Market
Fertilizers
South America Micronutrient Fertilizer Market
Fertilizers
Global Water Soluble Fertilizer Market
Fertilizers
United States Controlled Release Fertilizer Market
Fertilizers
EMEA Secondary Macronutrients Market
Fertilizers
China Micronutrient Fertilizer Market
Fertilizers
United States Fertilizers Market
Fertilizers
Silicon Fertilizer Market
Fertilizers
Africa Potash Fertilizer Market
Fertilizers
North America Fertilizers Market