
 Nitrile Butadiene Rubber Market | 2026-2036
Nitrile Butadiene Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Nitrile Butadiene Rubber Market Intelligence
The Nitrile Butadiene Rubber market is pivoting on a widening split between high-purity specialty grades for aerospace fuel systems and commodity bale rubber serving mass-market automotive hoses. ARLANXEO leverages its integrated butadiene feedstock position in Europe to sustain margin capture across acrylonitrile-content tiers. LG Chem competes through captive acrylonitrile supply from its Yeosu complex, while JSR Corporation differentiates via hydrogenated NBR technology leadership for extreme-temperature seals.
Nitrile Butadiene Rubber is a synthetic copolymer of acrylonitrile and butadiene, typically containing 18-50% acrylonitrile by mass, with higher ratios delivering superior resistance to oils, fuels, and aromatic hydrocarbons. The material is produced through emulsion or solution polymerization and is primarily used in sealing, hose, and gasket applications where elastomeric performance under chemical exposure is required. Among product types, high acrylonitrile grades command premium positioning due to their critical role in aerospace and automotive fuel systems, while carbon black filled formulations anchor volume throughput across industrial belting and molded goods. The seals application segment leads value contribution given its penetration into both OEM and aftermarket automotive channels, whereas adhesives represents a faster-growing but smaller niche driven by construction and footwear bonding demands.
REACH registration requirements and the EU F-Gas Regulation are tightening chemical disclosure and restricting certain process aids in European NBR compounding, pushing manufacturers toward cleaner formulation pathways. In the United States, EPA toxicity evaluations under TSCA and OSHA workplace exposure limits for acrylonitrile monomer are elevating compliance costs for domestic producers. Stakeholders must monitor regulatory divergence between jurisdictions as it reshapes cost structures and determines which product grades remain viable in premium versus commoditized regional markets.
Market Dynamics
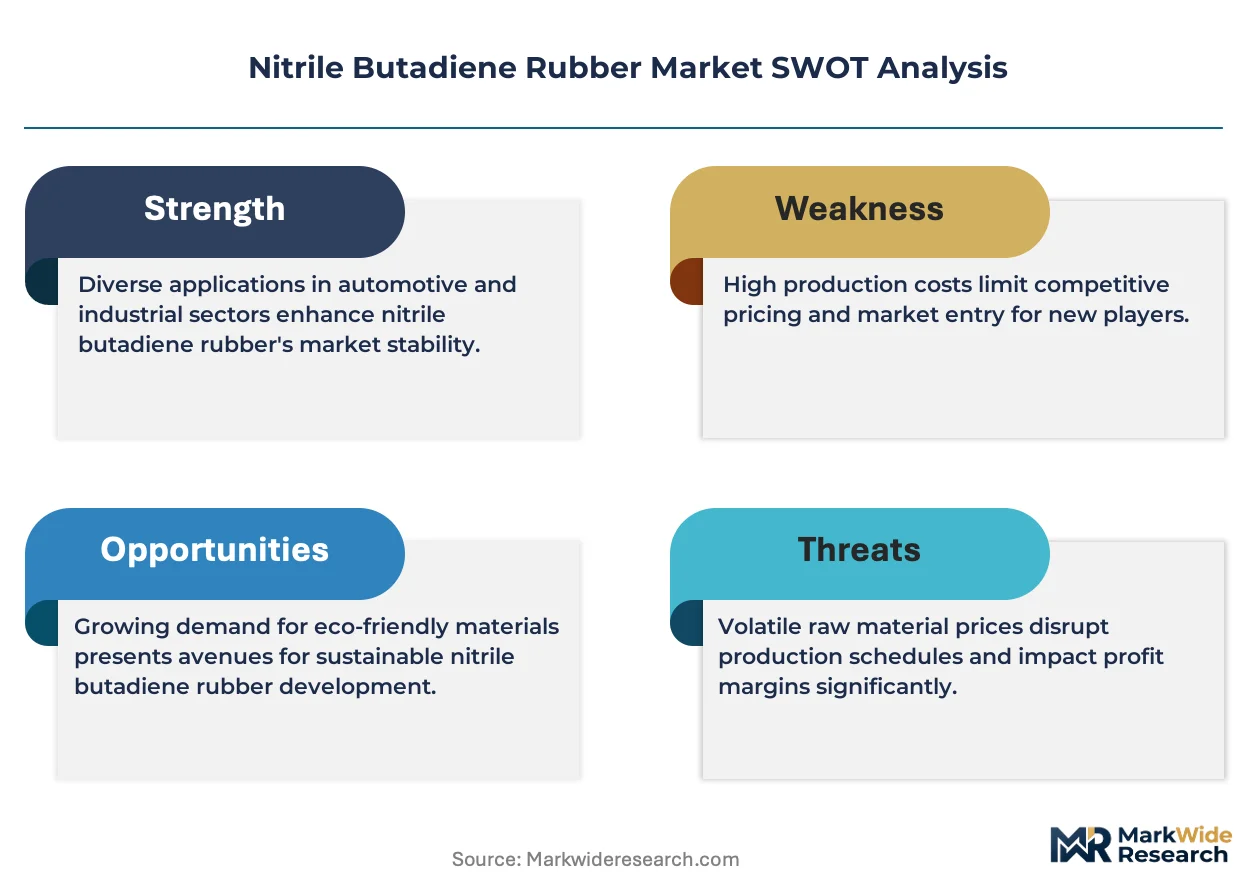
The Nitrile Butadiene Rubber market is bifurcating between high-acrylonitrile specialty grades for aerospace fuel seals and commodity bale rubber serving automotive hose manufacturers, with REACH phthalate restrictions forcing rapid reformulation of process oils across European compounders.
Growth Catalysts
- Fuel System Sealing Mandates:Stricter evaporative emission standards under EPA Tier 3 and Euro 6d are compelling automotive OEMs to specify high-acrylonitrile NBR for fuel line connectors and tank seals.
- REACH Plasticizer Phase-Out:The EU restriction on phthalate-based process oils is accelerating bio-based oil adoption, creating premium positioning for compounders with certified reformulation capabilities.
- China Captive Compounding:Domestic tire and hose producers in Shandong and Jiangsu provinces are scaling in-house NBR mixing capacity, pulling raw polymer demand toward localized supply contracts.
Market Restraints
- Butadiene Feedstock Volatility:NBR producers remain exposed to naphtha-cracker co-product swings, with butadiene spot prices amplifying margin compression during ethylene demand troughs.
- Acrylonitrile Monomer Concentration:Asian acrylonitrile supply clusters in South Korea and China create geographic single-source risk for European NBR compounders lacking backward integration.
- Hydrogenated NBR Substitution Ceiling:Standard NBR faces displacement limits in extreme-temperature aerospace seals where HNBR's saturated backbone delivers mandatory thermal stability.
Strategic Opportunities
- India Industrial Hose Expansion:BIS certification requirements for mining and agricultural equipment are creating localized NBR compounding demand as domestic manufacturers displace imported finished goods.
- Bio-Based Process Oil Convergence:The intersection of epoxidized soybean oil chemistry and NBR compatibility testing is opening formulation pathways for automotive suppliers targeting OEM sustainability scorecards.
- Construction Adhesive Channels:Direct-to-contractor distribution platforms are emerging for NBR-based contact cements in flooring and panel bonding, bypassing traditional industrial distributor markups.
Industry Challenges
- Formulation Chemist Scarcity:Compounders struggle to recruit specialists capable of balancing acrylonitrile content, cure systems, and bio-oil compatibility for multi-jurisdictional compliance.
- REACH Data Gap Bridging:The cost of generating substance safety data for novel bio-based plasticizers is extending new product qualification timelines beyond 18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitrile Butadiene Rubber Market |
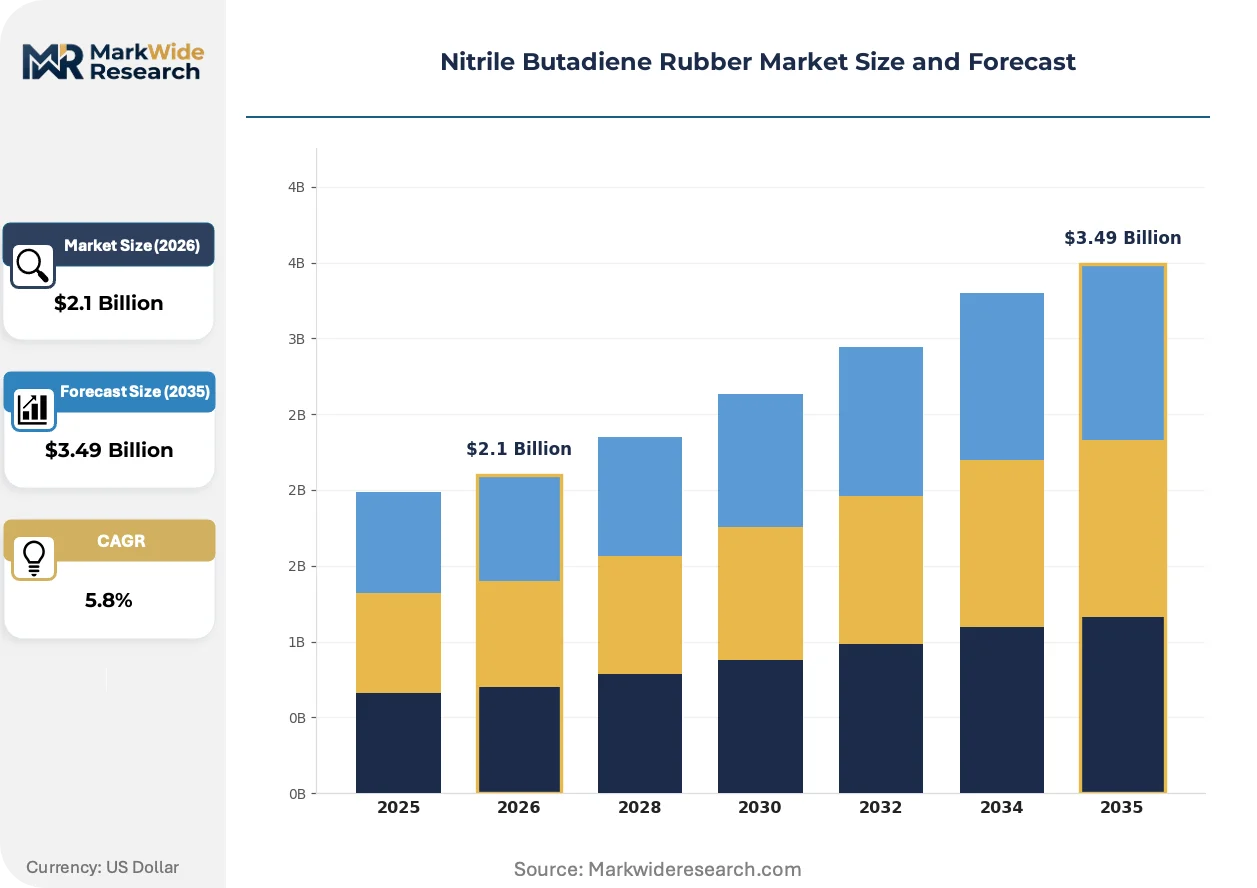
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Black Filled, Oil Resistant, Non-Filled, High Acrylonitrile End User: Automotive, Aerospace, Consumer Goods, Industrial Application: Seals, Hoses, Gaskets, Adhesives Form: Sheet, Molded, Extruded, Coated |
| Companies Covered | Zeon Corporation, China Petrochemical Corporation, ARLANXEO, Sibur, PetroChina Company Limited, LG Chem, JSR Corporation, Nantex Industry Co., Ltd., Kumho Petrochemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitrile Butadiene Rubber Market Strategic Shifts & Innovations
Reformulation chemistry and digital supply chain tools are compressing product development cycles while fragmenting procurement authority across tiered automotive supply networks.
Hydrogenated NBR is absorbing the most demanding thermal and chemical resistance requirements previously served by fluorocarbon elastomers in aerospace fuel system architecture. Tier 1 seal manufacturers are qualifying HNBR grades for temperatures exceeding 150°C in engine-mounted applications. This absorption is compressing the addressable market for standard high-acrylonitrile NBR in premium aerospace tiers while elevating HNBR technology licensing value.
The EU F-Gas Regulation is restricting process aids containing fluorinated compounds in NBR compounding operations, forcing European manufacturers to validate alternative release agents and internal lubricants. Industrial consequence includes extended mold-cleaning cycles and higher scrap rates during transition periods. Automotive seal producers in Germany and France are responding by consolidating qualification batches to amortize reformulation costs across multi-year OEM contracts.
Automotive OEMs are unbundling material specification authority from tiered supply agreements, permitting direct NBR grade approval relationships with compounders. This disintermediation is compressing tier 2 rubber processors into toll-compounding roles while elevating raw polymer producers to co-development partnerships. The pattern is most visible in German and Japanese automotive supply chains where OEM sustainability auditing now extends to monomer sourcing verification.
Nitrile Butadiene Rubber Market Segmentation
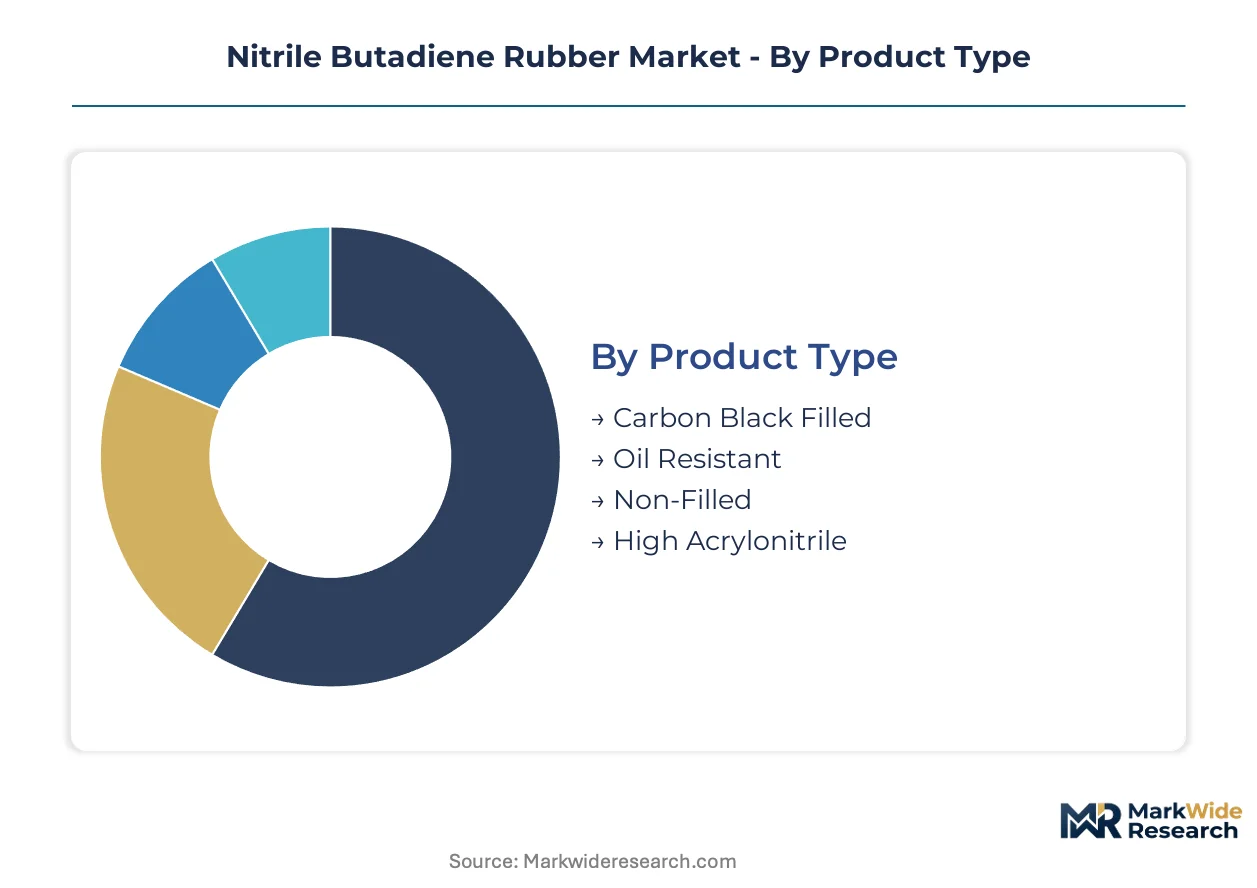
Nitrile Butadiene Rubber exhibits pronounced specification-driven fragmentation, where acrylonitrile content and filler loading determine thermal resistance, chemical compatibility, and ultimate application eligibility. Procurement patterns diverge sharply between automotive OEMs seeking certified fuel system grades and industrial buyers optimizing cost per cured kilogram.
Product Type:
Acrylonitrile content and filler composition define the technical specification hierarchy, separating commodity bale rubber from aerospace-qualified specialty grades.
- High Acrylonitrile:Grades containing 36-50% acrylonitrile by mass deliver mandatory resistance to aromatic fuels and synthetic lubricants. Aerospace seal manufacturers in Germany and Japan specify these grades for engine-mounted fuel system architecture where thermal cycling exceeds 135°C.
- Carbon Black Filled:Reinforced formulations with 30-50 phr carbon black loading anchor volume throughput across conveyor belting and molded industrial goods. Shandong tire producers are scaling captive compounding lines around these grades to displace imported finished rubber articles.
- Oil Resistant:Mid-range acrylonitrile tiers (25-35%) balance fuel resistance against low-temperature flexibility for hydraulic hose applications.
- Non-Filled:Unreinforced bale rubber serves adhesive compounders and custom mixers requiring in-house filler incorporation and cure system optimization.
Carbon Black Filled leads on scale; High Acrylonitrile leads on momentum.
End User:
Customer archetypes span regulated OEM supply chains, specification-critical aerospace tiers, price-sensitive industrial procurement, and fragmented consumer goods channels.
- Automotive:Tier 1 seal and hose manufacturers drive specification authority, with German OEMs unbundling material approval relationships to engage compounders directly. EPA Tier 3 evaporative emission mandates are compelling high-acrylonitrile adoption for fuel line connectors.
- Industrial:Mining equipment and agricultural machinery producers in India source BIS-certified NBR compounds for hydraulic systems and conveyor belting. Domestic manufacturers are displacing imported finished goods through localized mixing capacity.
- Aerospace:Engine seal manufacturers qualify hydrogenated NBR derivatives for temperatures exceeding 150°C, compressing standard NBR's addressable market in premium tiers.
- Consumer Goods:Footwear and household product manufacturers consume lower-acrylonitrile grades for gaskets, O-rings, and protective equipment where chemical exposure is intermittent.
Automotive dominates absolute volume; Industrial exhibits the steepest expansion trajectory.
Application:
Functional performance requirements dictate formulation complexity, with dynamic sealing applications commanding premium positioning against static gasket and adhesive uses.
- Seals:Dynamic O-rings, shaft seals, and fuel system gaskets require precise acrylonitrile-cure system balancing for compression set resistance. OEM and aftermarket automotive channels in Japan and Germany sustain value concentration here.
- Hoses:Hydraulic and fuel line constructions consume carbon black filled grades in high tonnage, with China captive compounding pulling raw polymer demand toward localized supply contracts.
- Gaskets:Static flange seals and sheet goods serve industrial maintenance markets with shorter qualification cycles and price-elastic procurement.
- Adhesives:NBR-based contact cements for flooring and panel bonding are gaining construction channel traction through direct-to-contractor distribution platforms.
Seals anchor revenue contribution; Adhesives is gaining share fastest.
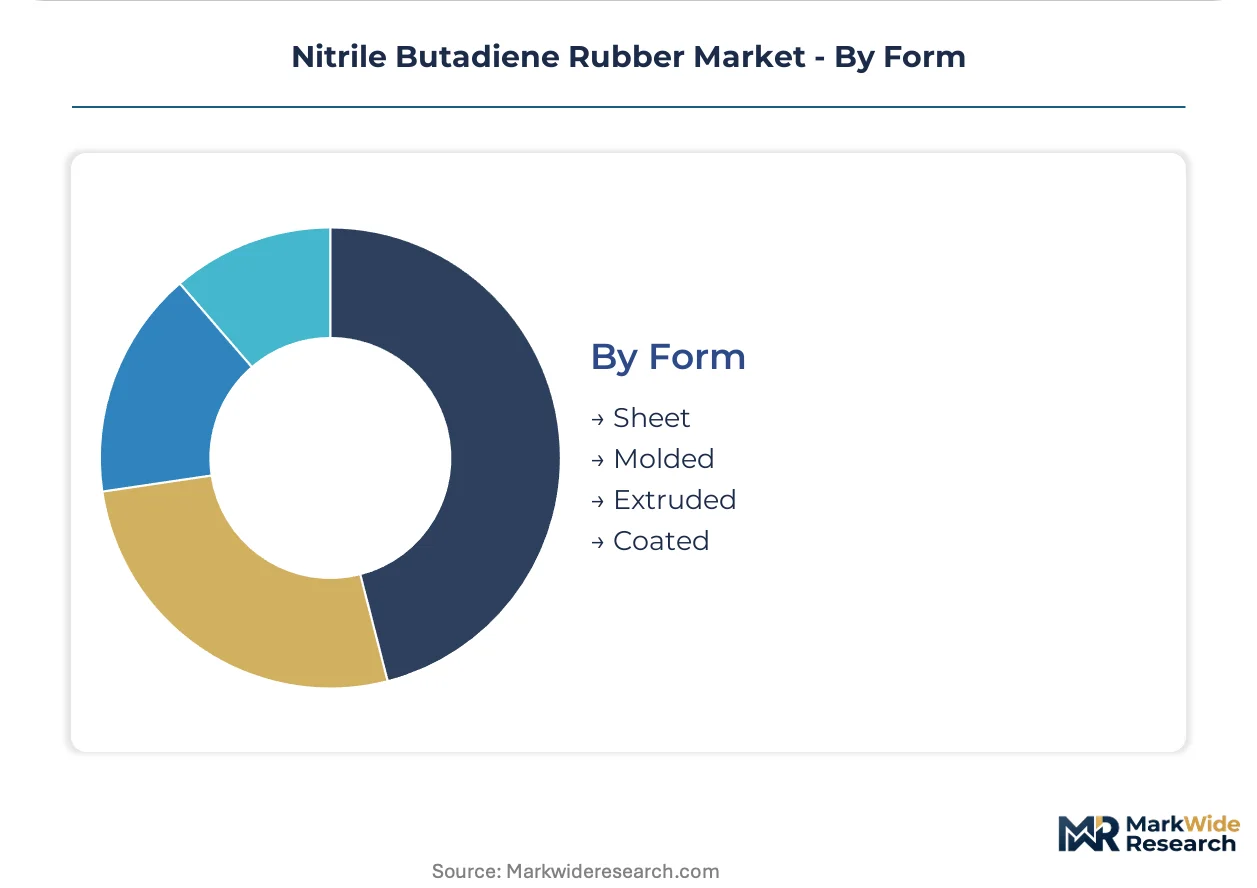
Form:
Processing methodology determines manufacturing integration depth, with extrusion and molding commanding distinct equipment footprints and labor skill requirements.
- Extruded:Continuous hose and profile production achieves economies of scale for automotive fluid transfer systems. Jiangsu province manufacturers are expanding extrusion-dedicated compounding lines.
- Molded:Compression and injection molding of complex seals requires tight cure rheology control, favoring compounders with in-house rheometer testing capabilities.
- Sheet:Calendered goods serve gasket fabrication and adhesive lamination with lower capital barriers to entry.
- Coated:Fabric and metal substrate coating applications demand specialized solvent-handling infrastructure and volatile organic compound compliance.
Extruded commands throughput leadership; Molded captures margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer chemists and formulation specialists cluster in Germany's industrial belt, Japan's Kansai chemical corridor, and China's Shandong petrochemical zone, anchoring regional capability depth for acrylonitrile-butadiene copolymer production.
Germany
Automotive seal manufacturers in Baden-Württemberg and Lower Saxony drive specification authority for high-acrylonitrile grades. The EU F-Gas Regulation restricts fluorinated process aids in compounding operations. Lanxess and BASF legacy sites in Leverkusen and Ludwigshafen sustain captive butadiene integration for margin capture across acrylonitrile-content tiers.
China
Domestic tire and hose producers in Shandong and Jiangsu provinces scale in-house NBR mixing capacity. GB standards under SAMR tighten volatile organic compound limits for solvent-based adhesive applications. The Yangtze River Delta petrochemical cluster near Ningbo and Shanghai pulls raw polymer demand toward localized supply contracts with Sinopec affiliates.
United States
EPA Tier 3 evaporative emission mandates compel Detroit-area OEMs to specify high-acrylonitrile NBR for fuel line connectors. OSHA workplace exposure limits for acrylonitrile monomer elevate compliance costs for domestic compounders. The Gulf Coast petrochemical corridor from Houston to Baton Rouge concentrates butadiene feedstock access for integrated producers.
Japan
METI industrial standards govern hydrogenated NBR qualification for aerospace engine seals exceeding 150°C. JSR Corporation and Zeon Corporation anchor technology leadership in saturated-backbone elastomers. The Kansai chemical belt between Osaka and Kobe sustains specialty polymer R&D infrastructure for extreme-temperature applications.
South Korea
Yeosu and Ulsan industrial complexes host captive acrylonitrile supply chains feeding NBR production. MFDS chemical registration requirements extend new product qualification timelines for bio-based process oil formulations. LG Chem leverages integrated feedstock positions to compete across standard and specialty acrylonitrile-content grades.
Nitrile Butadiene Rubber Market Key Industry Players
Capital-heavy producers compete with asset-light compounders across the Nitrile Butadiene Rubber value chain. Integrated petrochemical groups with captive butadiene and acrylonitrile supply dominate upstream polymer production, while toll compounders and custom mixers occupy midstream formulation tiers. Three archetypes define competitive positioning: feedstock-integrated majors, technology-specialty houses, and regional volume compounders. Capacity expansion and strategic technology licensing represent the dominant competitive moves as players defend margin positions against feedstock volatility.
Within the feedstock-integrated tier, ARLANXEO and LG Chem exemplify European and Asian producers leveraging backward integration into butadiene and acrylonitrile supply. JSR Corporation occupies a technology-specialist position, representing hydrogenated NBR capability for extreme-temperature aerospace applications. These three anchors illustrate how competitive advantage in this market derives from either feedstock control or specialty polymer chemistry expertise.
| Leading Market Players |
|---|
| Zeon Corporation |
| China Petrochemical Corporation |
| ARLANXEO |
| Sibur |
| PetroChina Company Limited |
| LG Chem |
| JSR Corporation |
| Nantex Industry Co., Ltd. |
| Kumho Petrochemical |
| Others |
Cost & Logistics Intelligence
Butadiene spot price volatility cascades through NBR value chains, compressing margins for non-integrated compounders while amplifying pricing power for producers with captive naphtha-cracker feedstock positions in Germany and South Korea.
Pricing Analysis
Bundled toll-compounding services command premiums against unbundled raw polymer sales, with three-tier pricing structure across aerospace-certified, automotive-specified, and industrial commodity grades. Price differentiation rests on acrylonitrile content certification and REACH compliance documentation. Cost compression in standard bale rubber intensifies because Chinese captive compounding capacity absorbs volume at compressed conversion margins. Industrial buyers in conveyor belting exhibit highest price sensitivity; aerospace seal manufacturers show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle German and Japanese automotive seal demand, while distributor networks serve fragmented industrial procurement across India and Southeast Asia. Feedstock concentration centers on South Korea, China, and Germany for acrylonitrile and butadiene supply. The chain draws from naphtha-cracker co-product streams, petroleum-derived process oils, and carbon black reinforcement. Single-source vulnerability in Asian acrylonitrile clusters exposes European compounders to geographic concentration risk. Distribution runs through tiered automotive supply hierarchies and direct contractor platforms for adhesive applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Tier 3 evaporative emission mandates and REACH phthalate restrictions are restructuring procurement specifications toward high-acrylonitrile grades and bio-based process oils.
For Market Incumbents: Deepen backward integration into butadiene feedstock to defend margin capture against naphtha-cracker co-product volatility. Secure multi-year OEM qualification batches to amortize REACH reformulation costs across contract lifecycles, countering displacement by hydrogenated NBR in extreme-temperature aerospace tiers. For New Entrants and Emerging Players: REACH plasticizer phase-out in Europe opens a window for bio-based process oil compounders with certified reformulation capabilities. Target Indian industrial hose segments where BIS certification requirements displace imported finished goods. Pursue direct-to-contractor distribution for construction adhesive channels bypassing traditional industrial markups. For Investors and Strategic Acquirers: Asymmetric upside sits with technology-specialty houses possessing hydrogenated NBR licensing capability for aerospace thermal stability requirements. Long-term viability favors producers with dual competence in standard and saturated-backbone elastomer chemistry. Watch JSR Corporation and Zeon Corporation technology licensing activity as inflection indicator for premium tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive butadiene supply from Ludwigshafen and Yeosu complexes insulates margin against ethylene demand troughs. |
| REACH Reformulation Certification | Bio-based process oil validation accelerates qualification for German automotive OEM sustainability scorecards. |
| Hydrogenated NBR Technology Licensing | Saturated-backbone chemistry access unlocks aerospace engine seal applications exceeding 150°C thermal thresholds. |
| India Industrial Hose Capacity | Localized BIS-certified compounding captures mining and agricultural equipment demand displacing imports. |
| Direct-to-Contractor Distribution | Bypassing industrial distributor markups improves NBR adhesive penetration in flooring and panel bonding channels. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polymer plant managers, automotive Tier 1 procurement leads, tire compounder R&D directors, and REACH compliance consultants with secondary validation. Sources included customs trade data, Cefic polymer statistics, SEC 10-K filings from petrochemical majors, and SAMR GB standard updates. Bottom-up volume modeling and top-down value triangulation cross-checked segment assumptions.
Segment-weighting applied acrylonitrile content tiers, end-use industry classifications, and regional production hub clusters across the projection horizon. CAGRs derived from elasticity-adjusted demand modeling for fuel system sealing mandates and evaporative emission regulatory trajectories. Forecast inputs incorporated butadiene feedstock price correlation coefficients and OEM qualification timeline distributions for bio-based process oil adoption.
Revisions become necessary when REACH substance safety data requirements extend beyond standard qualification windows or when acrylonitrile supply disruptions alter regional production economics. Forecasts reflect documented assumptions about regulatory enforcement consistency and feedstock price mean-reversion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Global Styrene Butadiene Styrene Market
Rubber
Chloro-Sulfonated Polyethylene Market
Rubber
Europe Rubber Derived Unrefined Pyrolysis Oil Market
Rubber
Global Rubber Market
Rubber
Rubber Bulbs Market
Rubber
Corrosion Protection Rubber Linings and Coatings Market
Rubber
Liquid Polybutadiene Market
Rubber
Europe Silicone Rubber Market
Rubber
Pre-Dispersed Rubber Chemicals Market
Rubber
Hydroxyl Terminated Polybutadiene Market
Rubber
EMEA and Asia Pacific Electrical Insulating Rubber Gloves Market
Rubber
Snap on Rubber Stopper Market
Rubber
Tire and Rubber Lubricants Market
Rubber
Oil Saver Rubber Market
Rubber
Chloroprene Rubber Tape Market
Rubber
Nitrile Butadiene Rubber (NBR) Latex Market