
 Corrosion Protection Rubber Linings and Coatings Market | 2026-2036
Corrosion Protection Rubber Linings and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Corrosion Protection Rubber Linings and Coatings Market Analysis
Buyer concentration in the chemical processing sector is shifting as midstream operators consolidate maintenance contracts under fewer national procurement umbrellas. PPG Industries leverages its North American distribution network to capture these bundled awards. Sherwin-Williams anchors its position through spec-grade formulations that meet refinery MRO standards. Akzo Nobel competes on application efficiency, reducing downtime during vessel turnaround cycles.
Corrosion protection rubber linings and coatings comprise elastomeric barriers and polymer-based films applied to metallic substrates, typically 3-12 mm thick for linings and 250-1000 microns for coatings, engineered to resist chemical permeation, abrasion, and galvanic degradation in aggressive process environments. Their primary industrial purpose is extending asset life in vessels, pipelines, and storage tanks exposed to acids, alkalis, and hydrocarbons. Linings for tanks command the deepest margin pools due to complex substrate preparation and certified applicator requirements, while coatings for pipelines represent the fastest-growing application segment driven by gathering system expansions. Synthetic rubber formulations dominate material demand, though polyurethane blends are gaining share in marine splash zone applications.
EPA NESHAP standards and OSHA Process Safety Management rules mandate documented coating integrity programs for chemical handling equipment, directly shaping inspection frequency and recoating specifications. The EU REACH regulation and associated SVHC restrictions limit certain curing agents and plasticizers, forcing formulation adjustments for exporters. ASTM D429 adhesion testing and ISO 8501 surface preparation grades function as de facto market access thresholds for project specifications. Stakeholders must monitor evolving state-level air quality regulations and assess applicator certification investments against the contracting base's technical demands.
Market Dynamics
Midstream operator consolidation is compressing the supplier base as national procurement umbrellas absorb regional maintenance contracts, forcing applicators to achieve certified status across multiple state jurisdictions simultaneously.
Growth Catalysts
- EPA NESHAP standards:Mandated coating integrity programs for chemical handling equipment are extending inspection cycles and accelerating recoating specifications across Gulf Coast facilities.
- Petrochemical capacity additions:Texas and Louisiana are driving vessel and pipeline demand as new ethane crackers and derivative units require protective infrastructure.
- Synthetic rubber formulations:Advanced elastomeric barriers with enhanced acid resistance are displacing conventional materials in sulfuric acid storage applications.
Market Restraints
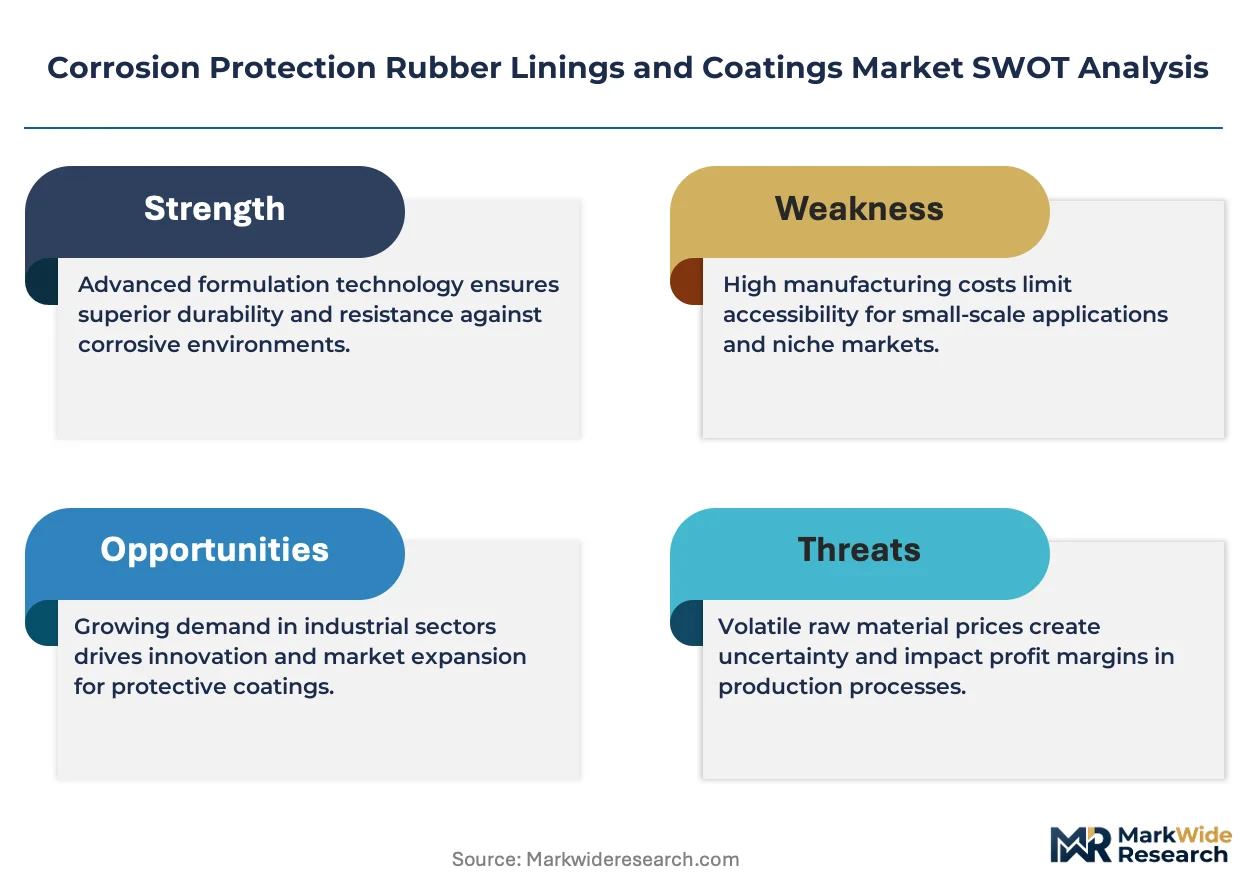
- Petroleum-derived feedstock volatility:Styrene-butadiene and chloroprene prices fluctuate with crude oil benchmarks, compressing margin predictability for formulation producers.
- Applicator certification scarcity:Qualified rubber lining technicians concentrate in Texas, Louisiana, and limited Gulf Coast hubs, creating regional bottlenecks during turnaround seasons.
- Polyurethane substitution in marine zones:Splash zone coatings increasingly favor polyurethane blends over rubber linings due to faster cure times and lower application complexity.
Strategic Opportunities
- Hydrogen infrastructure buildout:Emerging ammonia and hydrogen storage vessels require specialized high-pressure lining systems not yet standardized in current specifications.
- Carbon capture storage vessels:Amine-based CO2 absorption units create new lining specifications for amine corrosion resistance in industrial clusters.
- Digital inspection integration:Ultrasonic testing and drone-based coating assessment are enabling predictive maintenance contracts that bundle application with monitoring services.
Industry Challenges
- Certified applicator pipeline gaps:NACE and SSPC certification programs produce fewer qualified technicians than turnaround demand cycles require, extending project timelines.
- Substrate preparation bottlenecks:ISO 8501 Sa 2.5 surface grade requirements demand specialized abrasive blasting equipment that smaller contractors struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrosion Protection Rubber Linings and Coatings Market |
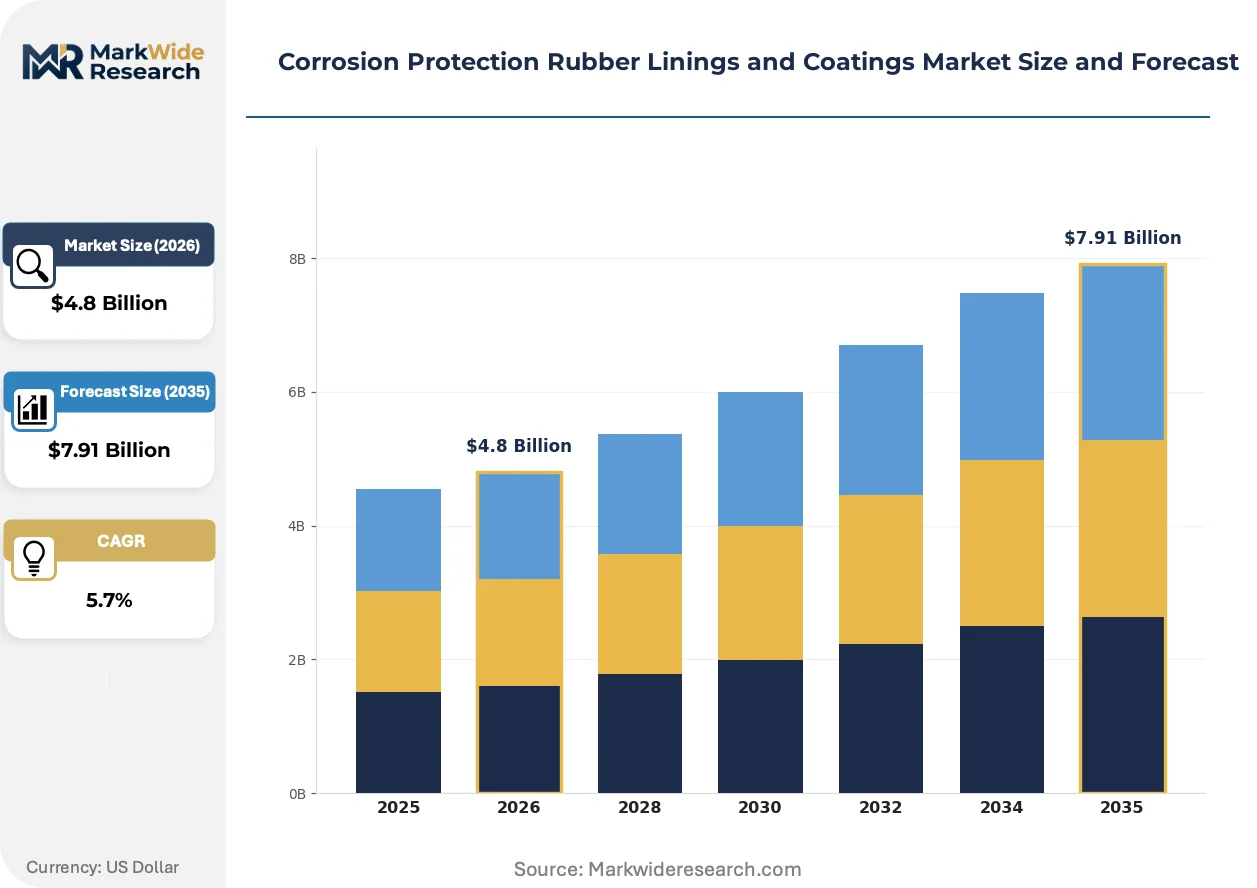
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sealants, Coatings, Linings, Adhesives Application: Pipelines, Tanks, Marine, Industrial Equipment User Type: Manufacturers, Contractors, Distributors, End Users Material: Synthetic Rubber, Natural Rubber, Polyurethane, Epoxy |
| Companies Covered | Arbonite, PPG Industries, Akzo Nobel, Sherwin-Williams, Jotun, Weir Group, Polycorp, REMA TIP TOP, Axalta Coating Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrosion Protection Rubber Linings and Coatings Market Emerging Trajectories
Application technology and specification standards are converging to reduce vessel downtime while expanding the serviceable substrate range for protective systems.
Polyurea spray technology is consolidating position in tank lining applications where rapid cure chemistry enables same-day return-to-service protocols. Chemical processors with compressed turnaround windows are specifying polyurea for secondary containment and process vessel interiors. This consolidation is compressing demand for conventional rubber sheet lining in non-critical service applications.
OSHA Process Safety Management rules are tightening documentation requirements for coating integrity in chemical handling equipment. Facilities must maintain traceable application records and inspection schedules tied to mechanical integrity programs. Refinery MRO departments are responding by centralizing specification authority under corporate engineering standards rather than site-level discretion.
Buyer concentration among national midstream operators is reshaping contract structures toward multi-site framework agreements. Regional applicators are losing direct access to procurement decisions as bundled awards consolidate under fewer procurement umbrellas. This pattern is most visible in Texas and Louisiana where pipeline gathering system expansions coincide with operator consolidation activity.
Corrosion Protection Rubber Linings and Coatings Market Segmentation
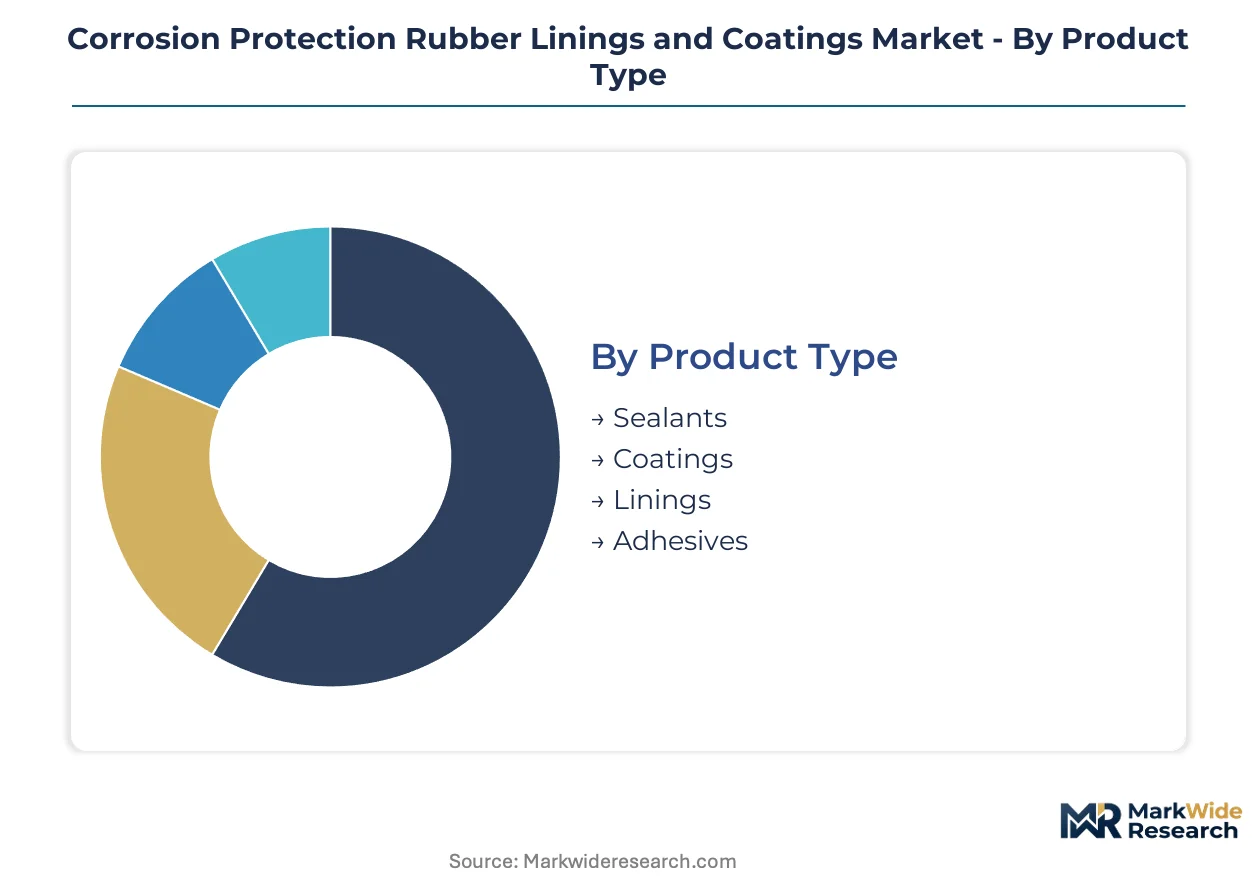
Segmentation in corrosion protection systems reveals distinct margin architectures and specification pathways. Product thickness, cure chemistry, and applicator certification requirements create divergent competitive dynamics across categories.
Product Type:
Integration depth varies sharply: linings demand vessel-specific engineering and certified installation, while sealants function as standalone maintenance consumables with minimal technical barriers.
- Linings:Elastomeric barriers applied at 3-12 mm thickness to vessel interiors, requiring ISO 8501 Sa 2.5 substrate preparation and NACE-certified applicators. Tank lining projects in Texas and Louisiana concentrate demand, driven by EPA NESHAP mandates for chemical storage integrity programs.
- Coatings:Polymer films at 250-1000 microns protecting pipelines and external surfaces. Gathering system expansions across Gulf Coast petrochemical corridors accelerate specifications, with polyurea spray technology displacing conventional systems in turnaround-critical applications.
- Sealants:Joint-filling compounds for flange connections and expansion joints. Maintenance departments specify these for quick repairs without vessel entry protocols.
- Adhesives:Bonding agents for rubber-to-metal substrate attachment per ASTM D429 testing standards. Formulators compete on cure speed and temperature resistance.
Linings lead volumes today; coatings are gaining share fastest.
Application:
Cost tier stratification dominates: tanks command premium pricing for complex geometry access, while pipelines compete on volume throughput and application speed.
- Tanks:Vertical and horizontal storage vessels for acids, alkalis, and hydrocarbons. Sulfic acid service in Gulf Coast chemical processing drives synthetic rubber specifications with enhanced permeation resistance.
- Pipelines:Transmission and gathering infrastructure spanning midstream networks. Texas-Louisiana capacity additions concentrate demand, with polyurea systems capturing share through rapid return-to-service protocols.
- Marine:Splash zone and submerged structures. Polyurethane blends increasingly displace rubber in this segment due to faster cure chemistry and simplified surface preparation.
- Industrial Equipment:Process vessels, heat exchangers, and reaction columns. Refinery MRO departments centralize specifications under corporate engineering standards.
Tanks anchor revenue pools; pipelines show steepest expansion trajectory.
User Type:
Customer type determines procurement pathway complexity and specification authority concentration.
- Contractors:Certified applicators executing substrate preparation and lining installation. Gulf Coast hubs concentrate qualified technicians, creating regional bottlenecks during turnaround seasons.
- End Users:Chemical processors, refineries, and storage terminal operators. Midstream consolidation shifts procurement to national framework agreements.
- Manufacturers:Formulation producers supplying spec-grade materials. These entities invest in applicator certification programs to secure downstream specification.
- Distributors:Regional logistics networks moving materials to job sites. National procurement umbrellas compress their role in direct customer relationships.
Contractors capture the largest service value; end users are consolidating procurement fastest.
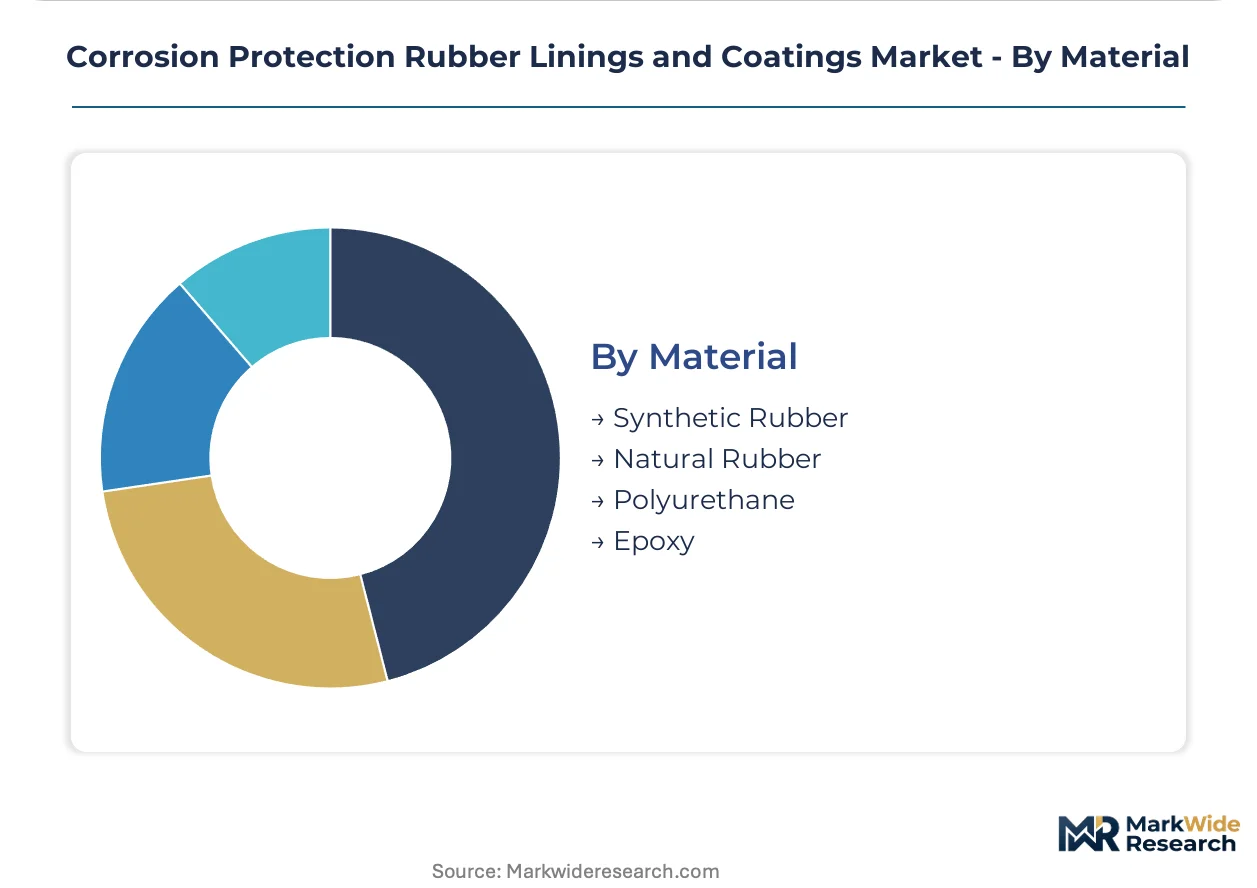
Material:
Maturity gradients separate established elastomers from advancing polymer systems competing on application efficiency.
- Synthetic Rubber:Styrene-butadiene and chloroprene formulations dominating acid-resistant applications. Petroleum-derived feedstock volatility compresses margin predictability for producers.
- Polyurethane:Rapid-cure spray systems penetrating tank lining and marine applications. Chemical processors specify these for compressed turnaround windows.
- Natural Rubber:Lower-cost alternative for mild chemical service. Limited temperature resistance restricts specifications.
- Epoxy:Rigid polymer films for external corrosion protection. Pipeline coatings favor these for abrasion resistance in soil environments.
Synthetic rubber dominates installed base; polyurethane climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States Gulf Coast facilities outpace Canadian chemical corridor investments in protective infrastructure spending, while German industrial clusters maintain stricter specification protocols than Asian manufacturing hubs.
United States
Texas and Louisiana petrochemical capacity additions drive vessel and pipeline demand as new ethane crackers require protective infrastructure. EPA NESHAP standards mandate documented coating integrity programs for chemical handling equipment. Houston-Beaumont-Port Arthur industrial corridor concentrates certified applicator capacity and turnaround service providers.
Germany
Ruhr industrial complex chemical processors specify high-grade elastomeric barriers for acid-resistant applications in sulfuric acid storage. EU REACH regulation restricts certain curing agents and plasticizers in formulations. Ludwigshafen-Cologne-Düsseldorf chemical belt maintains rigorous ASTM D429 adhesion testing protocols for project specifications.
China
Coastal petrochemical clusters in Jiangsu and Zhejiang provinces expand protective coating procurement for refinery MRO departments. GB standards and MEE emissions protocols tighten substrate preparation requirements. Yangtze River Delta manufacturing corridor concentrates synthetic rubber formulation production for domestic chemical processing demand.
India
Gujarat and Maharashtra chemical processing facilities accelerate protective infrastructure spending for acid and alkali storage applications. BIS certification requirements and state-level pollution control mandates shape applicator qualification standards. Hazira-Mundra industrial zone and Mumbai-Pune chemical corridor concentrate demand for certified lining installation services.
Saudi Arabia
Eastern Province petrochemical complexes expand protective coating specifications for hydrocarbon storage and processing vessels. SAMR technical regulations and SABIC engineering standards define substrate preparation grades. Jubail industrial city concentrates demand for high-temperature elastomeric barrier systems in aggressive process environments.
Corrosion Protection Rubber Linings and Coatings Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation and application service tiers. The supplier base compresses as national procurement umbrellas absorb regional maintenance contracts, consolidating specification authority under fewer decision-makers. Three archetypes dominate: integrated coating-to-application providers, formulation-focused chemical producers, and certified installation contractors. Competitive moves center on applicator certification program expansion and multi-site framework agreement capture.
Among North American coating specialists, PPG Industries and Sherwin-Williams occupy positions on the premium-formulation tier, while Akzo Nobel represents the European application-efficiency archetype. These three entities exemplify how geographic origin and corporate structure correlate with strategic positioning: Pittsburgh-based PPG leverages distribution scale, Cleveland-based Sherwin-Williams anchors through spec-grade formulations, and Amsterdam-based Akzo Nobel competes on reducing vessel turnaround downtime. Each sits within a distinct competitive vector without overlapping functional claims.
| Leading Market Players |
|---|
| Arbonite |
| PPG Industries |
| Akzo Nobel |
| Sherwin-Williams |
| Jotun |
| Weir Group |
| Polycorp |
| REMA TIP TOP |
| Axalta Coating Systems |
| Others |
Supply Flow & Price Mechanics
National midstream procurement umbrellas concentrate buying power across Texas and Louisiana petrochemical corridors, compressing supplier margins through multi-site framework agreements that standardize specifications and eliminate regional price premiums. This buyer consolidation shifts pricing power toward certified applicators with NACE credentials who can command project-based premiums during turnaround seasons.
Pricing Analysis
Capacity additions in Texas and Louisiana are reshaping price floors for vessel lining projects as qualified applicator scarcity creates regional bottlenecks. Three-tier pricing structure across premium, standard, and economy levels separates NACE-certified specialists from general contractors and commodity coating suppliers. Cost compression in standard-grade synthetic rubber formulations is intensifying because petroleum-derived feedstock volatility compresses margin predictability. Small regional contractors exhibit highest price sensitivity, while integrated formulation-to-application providers maintain pricing power through bundled service contracts.
Supply Chain Analysis
Regional distribution centers in Houston, Beaumont, and Port Arthur form a hub-and-spoke pattern feeding Gulf Coast petrochemical clusters with formulated materials and application equipment. Supply concentrates in the United States, Germany, and China for synthetic rubber base polymers and specialized curing agents. Raw material dependencies include styrene-butadiene, chloroprene, and isocyanate precursors that draw from petroleum and chemical processing streams. Single-source vulnerability characterizes certified applicator capacity, which clusters in limited Gulf Coast hubs. Distribution runs through manufacturer-direct channels for spec-grade formulations and regional applicator networks for installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage opportunities emerge between EPA-regulated US Gulf Coast markets and EU REACH-constrained European supply chains, where divergent plasticizer restrictions create formulation cost differentials of 15-25% for equivalent performance grades.
For Market Incumbents: Hedge against polyurethane substitution in marine and tank lining segments by accelerating polyurea spray technology certification programs. Acquire NACE-certified applicator capacity in Texas and Louisiana to secure bottlenecked installation resources. Backward integration into synthetic rubber formulation production reduces petroleum feedstock exposure and stabilizes input costs. For New Entrants and Emerging Players: Digital inspection platforms represent the most penetrable white-space target, bundling ultrasonic testing and drone-based coating assessment with predictive maintenance contracts. Target carbon capture storage vessel specifications in industrial clusters where amine corrosion resistance standards remain undefined. Pursue direct relationships with refinery MRO departments bypassing consolidated national procurement umbrellas. For Investors and Strategic Acquirers: Chemical processing conglomerates are the most active acquirer in this space, consolidating formulation and application capabilities under single engineering standards. The five-to-ten year viability window favors integrated coating-to-application providers with certified technician pipelines. Acquisition target archetype: regional applicators with NACE credentials and established turnaround relationships. Monitor hydrogen infrastructure specification standardization as inflection indicator for specialized high-pressure lining system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Applicator Certification Program Expansion | NACE-credentialed technician pipelines secure bottlenecked installation capacity during Gulf Coast turnaround seasons. |
| Polyurea Spray Technology Investment | Rapid-cure chemistry captures compressed turnaround window specifications from Texas and Louisiana refineries. |
| Backward Integration into Formulation | In-house synthetic rubber production reduces styrene-butadiene and chloroprene feedstock volatility exposure. |
| Digital Inspection Platform Development | Ultrasonic testing and drone-based assessment enable predictive maintenance contracts bundling monitoring with application. |
| Hydrogen Infrastructure Specification Development | Specialized high-pressure lining systems for ammonia storage vessels address emerging energy transition demand. |
Methodological Framework
Direct dialogue with plant managers at Gulf Coast petrochemical facilities, procurement leads at midstream operators, NACE-certified applicators, and technical R&D directors at formulation producers grounded qualitative assessments. Secondary validation drew from EPA NESHAP regulatory filings, OSHA Process Safety Management documentation, ASTM D429 adhesion test standards, SEC 10-K disclosures from coating specialists, and customs trade data for synthetic rubber imports. Bottom-up project pipeline analysis triangulated with top-down petrochemical capacity investment tracking.
Bottom-up modeling segmented demand across lining thickness grades, cure chemistry types, applicator certification tiers, and end-use vessel categories. Top-down verification cross-checked projections against petrochemical capacity addition announcements and EPA-mandated inspection cycle frequencies. CAGRs derived from regression analysis of historical protective infrastructure spending against ethane cracker commissioning schedules and regulatory compliance deadlines. Forecast inputs included turnaround season duration patterns and certified technician graduation rates from NACE programs.
The model assumes a particular technology adoption path; alternative pathways for polyurea spray displacement of conventional rubber sheet lining would alter the outlook. Forecasts reflect documented assumptions regarding petrochemical capacity buildout timing and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Acrylic Based Elastomers Market
Rubber
Global Medical Rubber Stopper Market
Rubber
Rubber Foam Materials Market
Rubber
Global Chloroprene Rubber Market
Rubber
Global Rubber Additives Market
Rubber
Industrial Rubber Market
Rubber
Acrylic Rubber Market
Rubber
EPDM Rubber Market
Rubber
Rubber Molding Market
Rubber
Performance Elastomers Market
Rubber
Gum Rosin Market
Rubber
Pre-Dispersed Rubber Chemicals Market
Rubber
Rubber Valve Stem Market
Rubber
Isobutylene Market
Rubber
Global Hydraulic Rubber Hose Market
Rubber
Recycled Elastomers Market