
 Global Rubber Market | 2026-2036
Global Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rubber Market Outlook
Aftermarket service revenue is narrowing as tire makers push integrated lifecycle contracts over standalone replacement sales. Bridgestone Corporation leverages its retail service network to capture recurring maintenance spend across fleet operators. Michelin sustains premium positioning through material science R&D in silica-reinforced compounds. Continental AG anchors European supply security with backward integration into synthetic rubber feedstocks.
Rubber comprises elastomeric polymers—primarily cis-1,4-polyisoprene in natural grades and styrene-butadiene or polybutadiene in synthetic variants—processed through mastication, compounding with sulfur and accelerators, and vulcanization to achieve elastic recovery and tensile strength exceeding 15 MPa. This material functions as the critical flexible interface in dynamic mechanical systems subject to cyclic deformation. Natural rubber still leads volume in tire applications where high resilience and heat buildup resistance command premium pricing, while thermoplastic elastomers are displacing conventional vulcanizates in consumer goods and medical seals where processing efficiency and design flexibility outweigh fatigue performance. Synthetic rubber margins concentrate in specialized grades for oil-resistant hoses and aerospace seals where polymer architecture customization creates formulation lock-in with compounders.
EPA emissions rules in the United States and REACH chemical restrictions in Europe are forcing reformulation of carbon black and aromatic oil extenders in tire manufacturing, raising compliance costs for exporters across all product categories. Thailand's industrial standards regulator and Indonesia's national quality agency are tightening plantation-to-port traceability rules to satisfy EU deforestation due diligence requirements. Stakeholders must monitor how bio-based feedstock certifications and carbon border adjustments reshape sourcing economics across natural and synthetic supply chains.
Market Dynamics
EU REACH chemical restrictions and EPA emissions rules are forcing simultaneous reformulation of carbon black and aromatic oil extenders, compressing margins for tire exporters while creating competitive advantage for compounders with advanced material science capabilities.
Growth Catalysts
- Automotive electrification:Battery electric vehicle platforms require specialized low-rolling-resistance tire compounds, pulling demand for high-performance styrene-butadiene formulations from German and South Korean automakers.
- EUDR deforestation due diligence:The EU Deforestation Regulation mandates plantation-to-port traceability for natural rubber imports, accelerating investment in Indonesian and Thai processing infrastructure to maintain market access.
- Silica-reinforced compound advances:Precipitated silica loadings above 20% by weight now deliver wet grip performance comparable to carbon black without aromatic oil dependencies, unlocking premium positioning for compounders mastering dispersion technology.
Market Restraints
- Crude oil price volatility:Synthetic rubber feedstocks including butadiene and styrene monomer track naphtha and crude benchmarks, exposing margin structures to energy market swings beyond operational control.
- Natural rubber supply concentration:Thailand, Indonesia, and Vietnam collectively account for over two-thirds of global natural rubber output, concentrating climate and labor disruption risks in a narrow geographic band.
- Thermoplastic elastomer substitution:TPEs are capturing medical seal and consumer goods applications where processing efficiency outweighs fatigue performance, capping volume growth in conventional vulcanizates.
Strategic Opportunities
- Indian tire manufacturing expansion:Domestic production capacity is scaling to serve both local automotive growth and export markets, creating demand for compound formulation partnerships with global suppliers.
- Bio-based feedstock certification:ISCC PLUS and RSB certification schemes for bio-butadiene and guayule-derived natural rubber open premium pricing channels as carbon border adjustments reshape sourcing economics.
- Integrated lifecycle contracts:Fleet operators are consolidating procurement around tire-as-a-service models, shifting revenue from transactional replacement sales to recurring maintenance partnerships with compounders.
Industry Challenges
- Polymer architecture talent scarcity:Formulation chemistry expertise for oil-resistant grades and aerospace seal specifications concentrates among retiring specialists, constraining R&D throughput at mid-tier compounders.
- Vulcanization line reconfiguration:Transitioning from aromatic oil-dependent compounds to bio-based or low-PAH alternatives requires capital-intensive mixer and curing press modifications with extended validation timelines.
- REACH SVHC notification complexity:The European Chemicals Agency's expanding candidate list of substances of very high concern demands continuous reformulation vigilance, stretching regulatory affairs bandwidth across product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rubber Market |
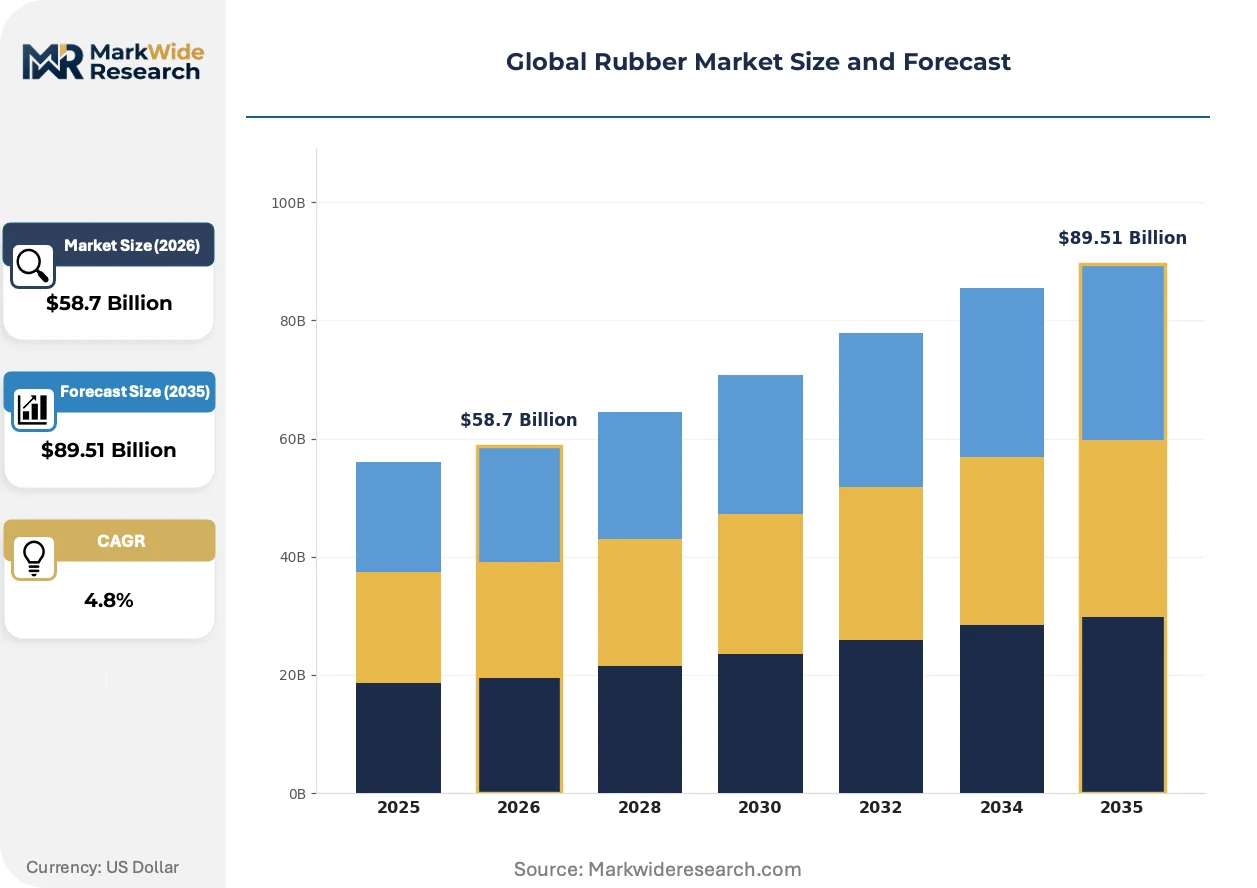
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $89.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Rubber, Synthetic Rubber, Recycled Rubber, Thermoplastic Elastomers End User: Automotive, Construction, Consumer Goods, Healthcare Application: Tires, Footwear, Seals, Hoses Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Bridgestone Corporation, Michelin, Goodyear Tire & Rubber Company, Continental AG, Sinopec, Sumitomo Rubber Industries, Yokohama Rubber Co., Ltd., ARLANXEO, JSR Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rubber Market Strategic Shifts
Material science convergence with sustainability mandates is redefining competitive advantage away from scale economies toward formulation lock-in and certification mastery. Three developments merit particular attention.
Guayule-derived natural rubber is hybridizing desert agriculture with elastomer supply chains, offering domestic production potential for US and Mexican tire manufacturers seeking to reduce Southeast Asian import dependence. Bridgestone and Cooper Tire have established pilot plantations in Arizona and Texas, with commercial volumes projected by 2027. The technology is hybridizing agronomic risk with polymer performance specifications, creating new supplier qualification frameworks that favor vertically integrated compounders.
REACH restrictions on polycyclic aromatic hydrocarbons in extender oils have forced reformulation of tire compounds across all categories sold in European markets. The industrial consequence is accelerated R&D spend on alternative plasticizers including treated distillate aromatic extracts and bio-based processing aids. Tire manufacturers serving EU markets are responding by consolidating supplier relationships around compounders with demonstrated SVHC compliance histories and rapid reformulation capabilities.
Fleet procurement departments are consolidating tire spend around integrated service contracts that bundle mounting, rotation, pressure monitoring, and end-of-life retreading into per-kilometer pricing. This unbundling of traditional aftermarket replacement sales concentrates buying power among large logistics operators and compresses margins for standalone distributors. The shift is most visible in German and Dutch long-haul trucking fleets, where total cost of ownership modeling now dominates supplier selection criteria over unit price comparisons.
Global Rubber Market Segmentation
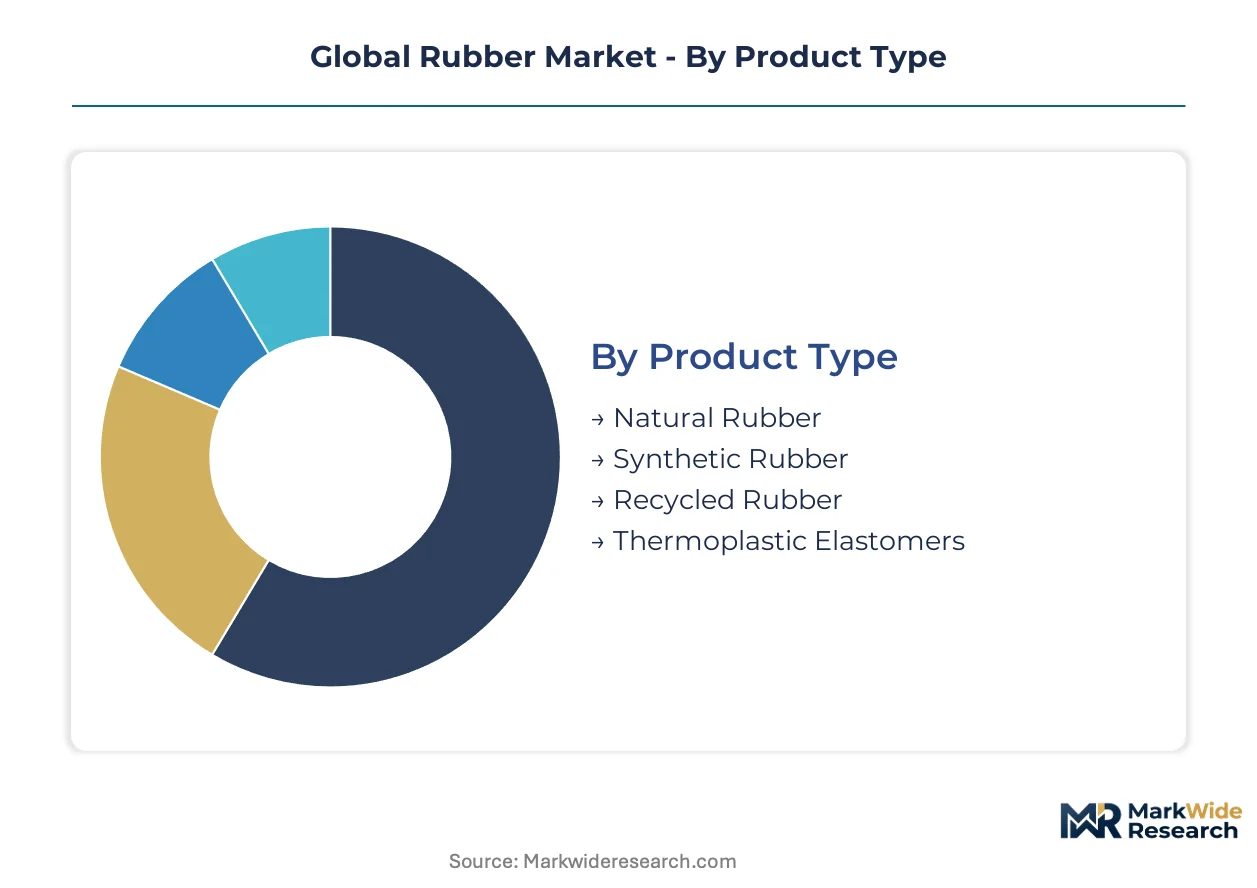
Rubber market segmentation reveals divergent replacement cycles across product categories, with tire applications demanding continuous replenishment while industrial seals operate on decade-long service intervals. Understanding these temporal patterns enables suppliers to calibrate inventory positioning and customer engagement strategies.
Product Type:
Natural rubber and synthetic grades exhibit starkly different inventory velocities, with plantation-harvested material moving through supply chains in seasonal waves while petrochemical-derived polymers flow on continuous production schedules.
- Natural Rubber:Cis-1,4-polyisoprene harvested from Hevea brasiliensis plantations dominates tire tread formulations requiring high resilience and heat dissipation. Demand concentrates in Southeast Asian processing hubs as Thai and Indonesian producers invest in traceability systems to satisfy EUDR compliance deadlines.
- Synthetic Rubber:Styrene-butadiene and polybutadiene polymers manufactured from naphtha feedstocks enable precise molecular weight control for specialized applications. German and South Korean automakers pull high-performance grades for low-rolling-resistance tire platforms on battery electric vehicles.
- Recycled Rubber:Devulcanized crumb from end-of-life tires re-enters supply chains for asphalt modification and playground surfacing. Municipal procurement in US states with extended producer responsibility mandates drives volume.
- Thermoplastic Elastomers:Block copolymer structures combining rubber elasticity with thermoplastic processability displace conventional vulcanizates in medical seals and consumer goods where design flexibility outweighs fatigue performance.
Natural rubber anchors the volume base while thermoplastic elastomers gain share at the steepest rate.
End User:
Customer procurement sophistication varies dramatically, with automotive OEMs demanding formulation lock-in through multi-year supply agreements while construction distributors operate on spot purchasing.
- Automotive:Tire manufacturers and original equipment suppliers consume the majority of high-performance compounds, with fleet operators now consolidating spend around integrated lifecycle contracts. Battery electric vehicle platforms require specialized formulations that compounders with material science R&D capabilities can premium-price.
- Construction:Waterproofing membranes, bridge bearings, and vibration isolation pads utilize bulk natural rubber and reclaimed grades. Infrastructure stimulus programs in India and Brazil drive regional demand concentration.
- Consumer Goods:Footwear, sporting equipment, and household products employ lower-specification compounds where processing efficiency dominates supplier selection. Asian contract manufacturers source primarily on landed cost metrics.
- Healthcare:Medical seals, gloves, and tubing require ISO 10993 biocompatibility certification and extractables testing. Regulatory compliance histories with FDA and EMA create formulation lock-in with qualified compounders.
Automotive procurement absorbs the highest compound volumes while healthcare applications command the steepest price premiums.
Application:
Functional performance requirements dictate formulation complexity, with dynamic mechanical loading in tires demanding sophisticated reinforcement systems versus static compression in seals.
- Tires:Tread, sidewall, and inner liner compounds each require distinct polymer blends, reinforcement architectures, and curing systems. REACH restrictions on polycyclic aromatic hydrocarbons in extender oils force continuous reformulation across European-market production.
- Footwear:Soling compounds balance abrasion resistance with comfort properties through controlled foam cell structures. Vietnamese and Indonesian contract manufacturers dominate global supply for athletic and fashion brands.
- Seals:Oil-resistant grades for aerospace and automotive powertrains require nitrile or fluoroelastomer architectures. Polymer architecture expertise concentrates among retiring specialists, constraining R&D throughput.
- Hoses:Pressure-rated constructions for hydraulic and pneumatic systems combine reinforcement layers with specialized cover compounds. Agricultural and mining equipment OEMs in Australia and Canada specify extreme-temperature performance.
Tire applications anchor the volume base while aerospace seals expand most quickly on specification-grade pricing.
Distribution Channel:
Channel economics reflect customer scale and technical service requirements, with bulk compound shipments to tire factories operating on entirely different margin structures than packaged goods through wholesale distributors.
- Wholesale:Industrial distributors stock standard grades for construction and manufacturing customers with predictable consumption patterns. Regional warehouses in Germany and Texas serve as consolidation points for North American and European demand.
- Retail:Specialty rubber shops and hardware chains cater to small-scale users requiring cut lengths and technical guidance. Staff expertise on compound selection creates differentiation against commoditized online alternatives.
- Online:E-commerce platforms aggregate long-tail demand for specialty grades and custom formulations. Certificate of analysis documentation and lot traceability remain friction points versus established distributor relationships.
- Direct Sales:Major tire manufacturers and automotive OEMs negotiate direct supply agreements with compounders, bypassing distribution markups in exchange for volume commitments and collaborative R&D access.
Direct sales channels capture the highest volume concentration while online distribution climbs the fastest on procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai plantation operators demonstrate the highest price elasticity as smallholders respond immediately to spot price swings, while German automotive compounders exhibit inelastic demand locked into multi-year formulation contracts regardless of feedstock volatility.
Thailand
Smallholder cooperatives in Songkhla and Surat Thani provinces supply two-thirds of global natural rubber exports, with processing clusters modernizing traceability systems to satisfy EUDR plantation-to-port documentation requirements. The Thai Industrial Standards Institute is tightening quality certification protocols for export-grade ribbed smoked sheets. Rayong's eastern seaboard processing corridor attracts Japanese tire manufacturers seeking backward integration into latex supply.
Indonesia
Sumatran and Kalimantan plantations recover from fungal disease outbreaks through clonal replanting programs, with state-owned processors consolidating smallholder output for European compliance. Indonesia's National Quality Agency mandates blockchain-enabled traceability documentation for EU-bound shipments. Medan's Belawan port district hosts expanding crumb rubber processing capacity serving Continental AG and Michelin compounders.
Germany
Automotive OEMs in Stuttgart and Munich pull specialized styrene-butadiene formulations for battery electric vehicle low-rolling-resistance tire platforms. ECHA's expanding REACH SVHC candidate list forces continuous reformulation of carbon black and aromatic oil extenders. The Cologne-Düsseldorf chemical corridor concentrates synthetic rubber R&D facilities serving premium tire specifications.
United States
Guayule pilot plantations in Arizona and Texas offer domestic natural rubber alternatives as Bridgestone and Cooper Tire advance commercialization timelines toward 2027 production targets. EPA emissions rules on tire manufacturing particulates raise compliance costs for imported compound shipments. The Gulf Coast petrochemical corridor maintains butadiene and styrene monomer capacity for synthetic rubber feedstocks.
China
Sinopec's integrated refining-petrochemical complexes in Zhejiang and Shandong provinces supply expanding domestic tire manufacturing serving both local automotive growth and export markets. MIIT's GB standards for tire labeling and energy efficiency align with EU regulatory trajectories. The Yangtze River Delta tire manufacturing belt concentrates capacity for electric vehicle platform suppliers.
Global Rubber Market Competitive Environment
Integrated petrochemical conglomerates and specialized tire manufacturers split the market between feedstock security and formulation mastery. The vendor base concentrates among Asian plantation processors, European automotive compounders, and integrated petrochemical producers with captive synthetic rubber capacity. Three archetypes dominate: vertically integrated tire manufacturers controlling upstream latex sourcing, petrochemical majors with backward integration into butadiene and styrene monomers, and specialized compounders with formulation lock-in on specification-grade applications. Competitive intensity centers on EUDR traceability certification acquisition and REACH-compliant reformulation speed.
Within the integrated tire manufacturer tier, Bridgestone Corporation and Michelin exemplify archetypes pursuing plantation-to-retail control. Sinopec occupies a position among petrochemical majors leveraging refining integration for synthetic rubber feedstock security. These three anchors illustrate how competitive positioning diverges between natural rubber traceability mastery and petrochemical process optimization.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Michelin |
| Goodyear Tire & Rubber Company |
| Continental AG |
| Sinopec |
| Sumitomo Rubber Industries |
| Yokohama Rubber Co., Ltd. |
| ARLANXEO |
| JSR Corporation |
| Others |
Value Chain & Pricing Dynamics
Singapore-Jakarta freight corridors absorb bunker fuel volatility that cascades through Southeast Asian natural rubber export pricing, compressing margins for European compounders while amplifying price differentiation between EUDR-certified and conventional plantation grades. Thai smallholders respond immediately to spot price swings, whereas German automotive compounders lock into multi-year formulation contracts regardless of feedstock turbulence.
Pricing Analysis
Integrated lifecycle service contracts now drive lifetime value capture as fleet operators consolidate procurement around tire-as-a-service models. Pricing stratifies across premium, standard, and economy tiers based on EUDR traceability certification and silica-reinforced compound performance grades. Cost compression in conventional vulcanizates is intensifying because thermoplastic elastomers capture medical seal and consumer goods applications. Asian contract manufacturers exhibit highest price sensitivity on landed cost metrics, while German automotive OEMs prioritize formulation lock-in over unit price.
Supply Chain Analysis
Tariff exposure between Southeast Asian plantation processors and European compounders dominates supply chain risk planning as EUDR documentation requirements extend lead times. Natural rubber supply concentrates in Thailand, Indonesia, and Vietnam, while synthetic rubber feedstocks draw from German and South Korean petrochemical complexes. Raw material dependencies rest on butadiene and styrene monomer from naphtha cracking, plus precipitated silica from specialty chemical producers. Distribution runs through direct sales agreements between major tire manufacturers and compounders, bypassing wholesale markups for volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global Rubber Market dynamics favor service-attach strategies as integrated lifecycle contracts expand faster than standalone replacement tire sales. Fleet procurement consolidation around per-kilometer pricing models rewards compounders with predictive maintenance capabilities and retreading infrastructure.
For Market Incumbents: Insulate formulation margins by accelerating REACH-compliant reformulation capabilities before SVHC candidate list expansions force reactive product withdrawals. Secure EUDR traceability certification through backward integration into Thai and Indonesian processing infrastructure. Defensive consolidation around silica dispersion technology R&D creates lock-in with battery electric vehicle platform suppliers. For New Entrants and Emerging Players: Indian tire manufacturing expansion offers the most penetrable geographic entry point as domestic capacity scales to serve local automotive growth and export markets. Target bio-based feedstock certification partnerships with guayule pilot plantations in Arizona and Texas. Pursue compound formulation collaborations with mid-tier fleet operators seeking alternatives to integrated incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical majors seeking to divest non-core synthetic rubber units amid energy transition pressures. Five-to-ten-year viability hinges on regulatory compliance speed rather than scale economies. Watch for EUDR enforcement actions against non-compliant Southeast Asian processors as inflection indicators for certification-premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EUDR Traceability Certification | Blockchain-enabled plantation-to-port documentation secures European market access for Thai processors. |
| Silica-Reinforced Compound R&D | Precipitated silica loadings above 20% by weight unlock premium positioning with German automakers. |
| Guayule Commercialization Partnership | Desert agriculture hybridization reduces Southeast Asian import dependence for US tire manufacturers. |
| Integrated Lifecycle Contract Expansion | Per-kilometer pricing models shift revenue from transactional sales to recurring maintenance partnerships. |
| REACH-Compliant Reformulation | Alternative plasticizer development avoids SVHC notification complexity across European product portfolios. |
Study Parameters
Initial hypotheses were tested against primary input from plantation operations managers, tire manufacturer procurement directors, compounder R&D leads, and freight logistics coordinators, then refined through secondary validation against customs trade data, ECHA REACH registration databases, Thai Industrial Standards Institute protocols, and SEC filings from listed tire manufacturers. Bottom-up volume modeling triangulated with top-down macroeconomic indicators across natural and synthetic rubber supply chains.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions including polymer type, end-use industry, application function, and regional regulatory cluster. CAGRs were derived from historical elasticity patterns and forward-looking capacity expansion announcements, incorporating battery electric vehicle platform penetration rates and EUDR compliance timeline assumptions as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by petrochemical majors or rapid guayule commercialization by tire manufacturers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Global Thermoplastic Vulcanizate (TPV) Market
Rubber
Global Medical Rubber Stopper Market
Rubber
Rubber Bulbs Market
Rubber
Liquid Polybutadiene Market
Rubber
Chloroprene Rubber Tape Market
Rubber
Rubber Coatings Market
Rubber
Polyisoprene Rubber Market
Rubber
Sterile Rubber Stopper Market
Rubber
Corrosion Protection Rubber Linings and Coatings Market
Rubber
Performance Elastomers Market
Rubber
Conductive Silicone Rubber Market
Rubber
Neoprene Rubber Market
Rubber
Global Hydraulic Rubber Hose Market
Rubber
Isoprene Rubber Market
Rubber
Rubber Molding Market
Rubber
Rubber Carbon Black Market