
 Egyptian Protective Coatings Market | 2026-2036
Egyptian Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Egyptian Protective Coatings Market Foresight
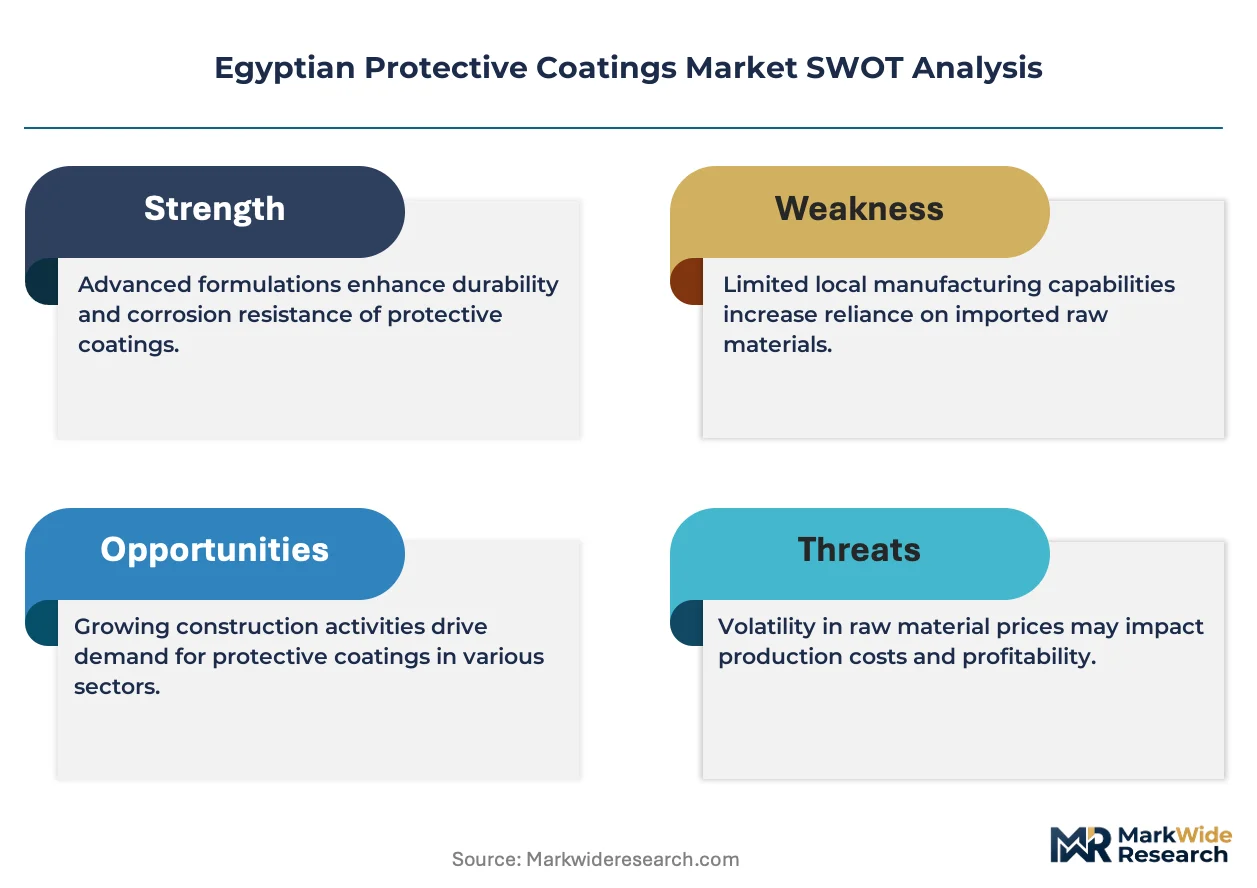
Egypt's updated environmental compliance protocols for industrial facilities is hardening specification standards across the coatings value chain. Hempel A/S anchors its position through marine specialization serving Red Sea and Mediterranean fleets. Akzo Nobel N.V. competes via broad portfolio coverage spanning solvent-based and water-based platforms. Sigma Paints Egypt Ltd leverages domestic manufacturing scale to control distribution across Greater Cairo and Alexandria industrial corridors.
Egyptian protective coatings comprise resin-based formulations engineered to prevent substrate degradation from corrosion, chemical attack, and ultraviolet exposure, typically applied at dry film thicknesses of 150–500 microns depending on service environment. Epoxy systems dominate petrochemical and marine applications where chemical resistance and substrate adhesion are paramount. Water-based technologies are gaining specification share in manufacturing plants and warehouses as environmental compliance tightens. Powder coatings occupy premium industrial equipment segments where zero-VOC performance justifies capital-intensive application infrastructure.
The Egyptian Environmental Affairs Agency enforces air quality standards that constrain solvent-based coating formulations in populated governorates, while the Egyptian Organization for Standardization and Quality mandates product certification for infrastructure projects. Compliance with these frameworks shapes procurement eligibility for state-funded developments including New Administrative Capital construction and Sinai infrastructure renewal. Stakeholders must monitor regulatory alignment between Egyptian standards and evolving IMO marine coating guidelines to anticipate specification shifts in Suez Canal transit vessel maintenance.
Market Dynamics
Egypt's protective coatings sector is being restructured by the collision of IMO 2020 marine fuel regulations and accelerated port infrastructure spending, forcing formulation upgrades across Suez Canal servicing yards and Red Sea dry-dock facilities.
Growth Catalysts
- Suez Canal Economic Zone expansion:Petrochemical investments at Ain Sokhna and East Port Said are generating concentrated demand for high-performance epoxy systems in tank farm construction and pipeline networks.
- Egypt Vision 2030 infrastructure mandates:Bridge rehabilitation protocols and New Administrative Capital construction specifications are mandating certified coating systems for concrete and steel substrates.
- EGPC corrosion management protocols:Updated inspection standards for upstream and downstream assets are accelerating specification upgrades across refinery maintenance cycles.
Market Restraints
- Solvent-based formulation constraints:Egyptian Environmental Affairs Agency air quality enforcement in Greater Cairo and Alexandria is restricting high-VOC product distribution and application windows.
- Epoxy resin import dependency:Feedstock concentration in Asian and European supply chains exposes formulators to currency volatility and shipping cost fluctuations.
- Specialized applicator scarcity:Certified surface preparation and coating inspection technicians remain concentrated in Alexandria and Cairo industrial corridors, limiting project scaling.
Strategic Opportunities
- Sinai infrastructure renewal:Road, pipeline, and military facility construction in North and South Sinai governorates offers first-mover positioning for coating contractors with desert-environment expertise.
- Water-based technology convergence:Hybrid acrylic-epoxy formulations are opening specification pathways in manufacturing plants and warehouse construction where indoor air quality compliance is tightening.
- Egyptian Organization for Standardization certification:Early alignment with evolving EQS product certification requirements creates procurement eligibility advantages for state-funded developments.
Industry Challenges
- Surface preparation standardization:Inconsistent Sa 2.5 blast cleaning execution across subcontractor tiers compromises coating adhesion performance and warranty claims.
- Dual regulatory alignment:Formulators must simultaneously satisfy Egyptian Environmental Affairs Agency domestic standards and IMO marine coating guidelines for Suez Canal transit vessel maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egyptian Protective Coatings Market |
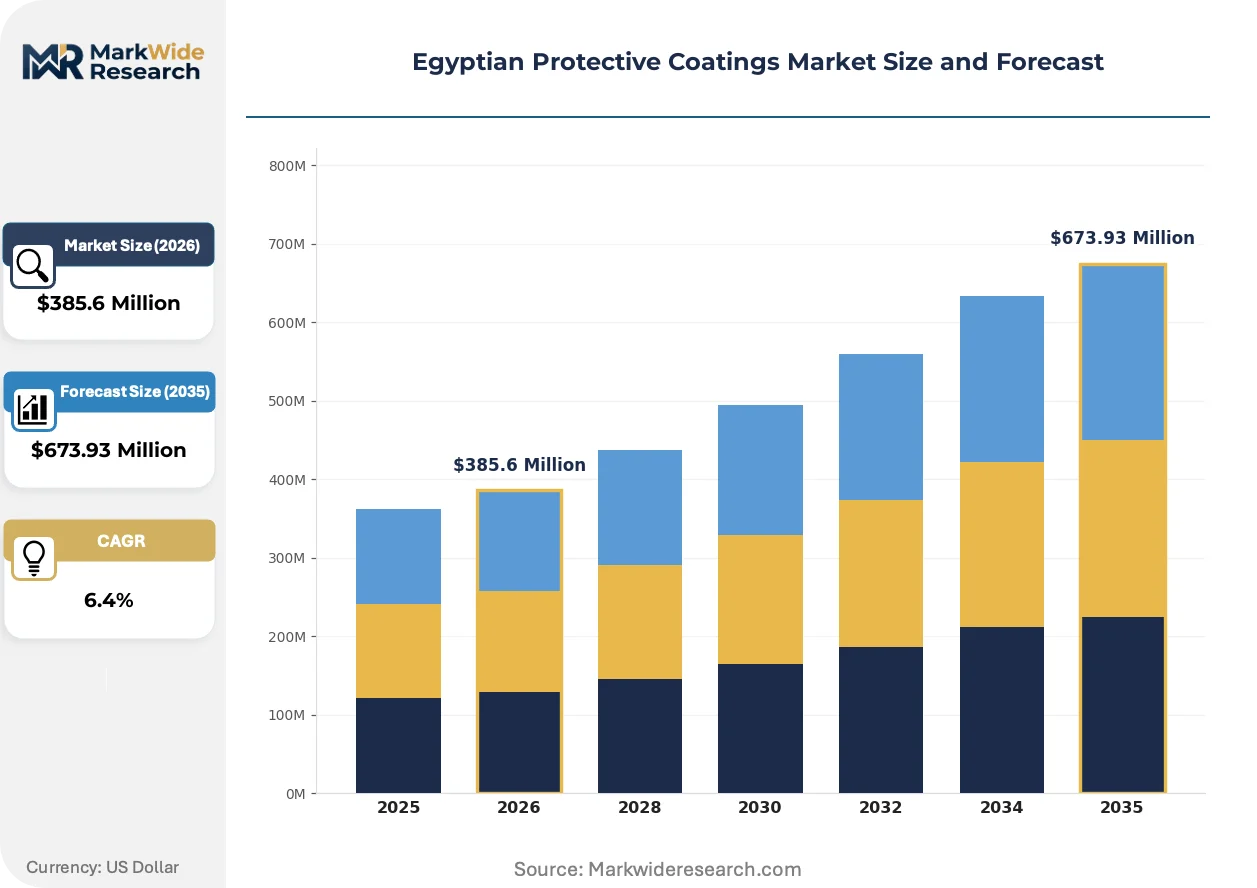
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Alkyd, Silicone, Fluoropolymer Application: Marine Vessels, Oil & Gas Infrastructure, Bridges, Industrial Equipment, Warehouses, Pipelines End User Industry: Oilfield Services, Power Generation, Construction, Manufacturing Plants, Transportation, Chemical Processing Coating Technology: Solvent-Based, Water-Based, Powder Coatings, UV-Cured, High-Solids, Zinc-Rich |
| Companies Covered | Hempel A/S, Sika AG, Akzo Nobel N.V., Nippon Paint Holdings Co., Ltd., Axalta Coating Systems Ltd., Jotun, Sigma Paints Egypt Ltd, CORROCOAT EGYPT, PPG Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egyptian Protective Coatings Market Shifts & Advancements
Formulation chemistry and application protocols across Egypt's protective coatings market are being recast by environmental compliance pressure, vessel efficiency mandates, and shifting procurement authority toward engineering-procurement-construction contractors.
High-solid and solvent-free epoxy systems are rewriting specification standards for ballast tanks and cargo holds serving Red Sea and Mediterranean fleets. Shipyards at Damietta and Alexandria are adopting these technologies to compress dry-dock turnaround times and extend coating lifecycle performance. The shift is compressing demand for conventional solvent-based marine formulations.
Egyptian Environmental Affairs Agency enforcement of ambient air quality standards is hardening formulation requirements in populated governorates. Industrial facilities in Greater Cairo now face mandatory emissions reporting that constrains solvent-based coating application seasons. Water-borne and high-solid alternatives are capturing specification share in manufacturing plant and warehouse maintenance cycles.
Engineering-procurement-construction contractors are consolidating coating specification authority across New Administrative Capital and Suez Canal Economic Zone developments. Single-source accountability for substrate preparation, coating selection, and warranty performance is displacing fragmented subcontractor procurement. This concentration is most visible in petrochemical and infrastructure megaprojects where long-term corrosion guarantees are mandatory.
Egyptian Protective Coatings Market Segmentation
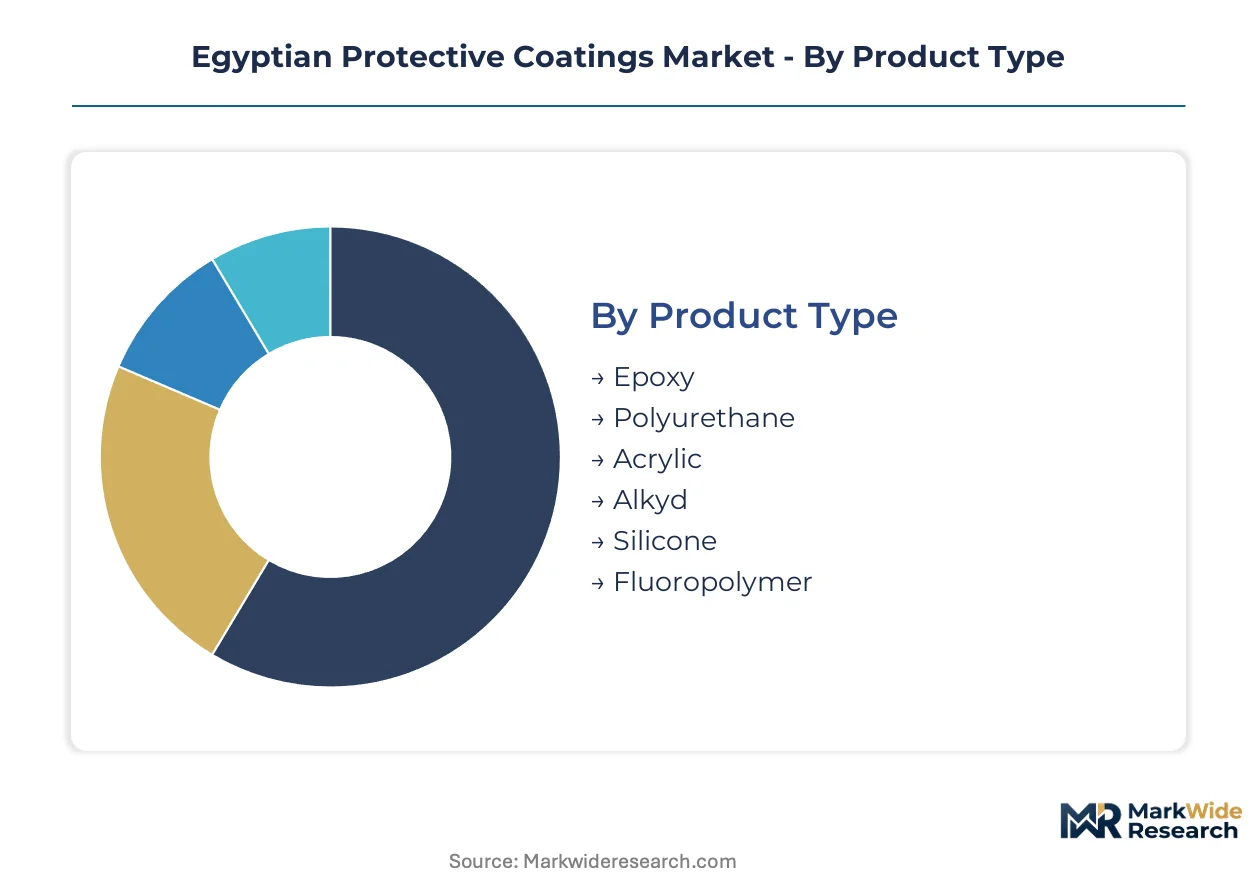
Protective coatings procurement in Egypt diverges sharply by substrate demands, regulatory exposure, and application infrastructure. Specification authority concentrates with engineering-procurement-construction contractors who bundle coating selection into long-term corrosion guarantees. Understanding segment boundaries reveals where formulation investments align with procurement decision power.
Product Type:
Capital intensity varies dramatically across resin chemistries, with solvent-free and high-solid systems demanding specialized plural-component spray equipment and climate-controlled storage.
- Epoxy:Two-part thermoset formulations deliver chemical resistance and substrate adhesion for petrochemical tankage and marine ballast tanks. Suez Canal Economic Zone tank farm construction specifies these systems for 15-year corrosion protection cycles.
- Polyurethane:Aliphatic topcoats provide ultraviolet stability and gloss retention for exterior steel exposed to desert thermal cycling. Bridge rehabilitation contracts across the Nile Delta specify polyurethane finishes over epoxy primers.
- Acrylic:Water-borne acrylics serve manufacturing plant maintenance where Egyptian Environmental Affairs Agency air quality enforcement restricts solvent-based application windows.
- Alkyd:Conventional oil-modified polyesters persist in light industrial equipment where cost constraints outweigh performance specifications.
- Silicone:Heat-resistant formulations protect power generation exhaust stacks and high-temperature process equipment.
- Fluoropolymer:Premium resin systems command specification in coastal infrastructure where salt spray degradation accelerates conventional coating failure.
Epoxy absorbs the bulk of installed capacity; water-borne acrylic is expanding most quickly as environmental compliance tightens across Greater Cairo industrial corridors.
Application:
Application environments dictate surface preparation standards, inspection protocols, and warranty structures that segment procurement behavior.
- Marine Vessels:Ballast tank and cargo hold coatings must satisfy IMO marine guidelines for vessels transiting the Suez Canal. Damietta and Alexandria dry-docks specify high-solid epoxies to compress turnaround schedules.
- Oil & Gas Infrastructure:Egyptian General Petroleum Corporation inspection protocols mandate certified coating systems for refinery vessels and pipeline exteriors. EGPC maintenance cycles drive specification upgrades.
- Bridges:Egypt Vision 2030 rehabilitation contracts require certified systems for concrete and steel substrates across Nile crossings.
- Industrial Equipment:Manufacturing plant maintenance cycles favor water-borne technologies where indoor air quality compliance constrains solvent use.
- Warehouses:Floor and structural steel coatings prioritize rapid return-to-service in logistics facilities around Alexandria and Port Said.
- Pipelines:Desert burial environments and coastal exposure segments demand divergent corrosion protection strategies.
Oil and gas infrastructure commands the largest specification volume; marine vessel applications are climbing the fastest as Red Sea fleet renewal accelerates.
End User Industry:
Industry-specific procurement maturity separates integrated owner-operators from fragmented subcontractor networks.
- Oilfield Services:Upstream operators under EGPC corrosion management protocols specify high-performance systems for wellhead equipment and gathering lines.
- Power Generation:Thermal plant operators balance heat resistance requirements against Egyptian Environmental Affairs Agency emissions constraints.
- Construction:New Administrative Capital megaprojects consolidate coating specification with EPC contractors holding long-term substrate warranties.
- Manufacturing Plants:Factory maintenance departments favor water-borne alternatives where worker exposure regulations tighten.
- Transportation:Bridge authorities and port operators specify certified systems for steel and concrete infrastructure.
- Chemical Processing:Aggressive service environments in Ain Sokhna petrochemical complexes demand specialized chemical-resistant formulations.
Construction absorbs the bulk of specification authority; chemical processing is gaining share fastest as Suez Canal Economic Zone investments mature.
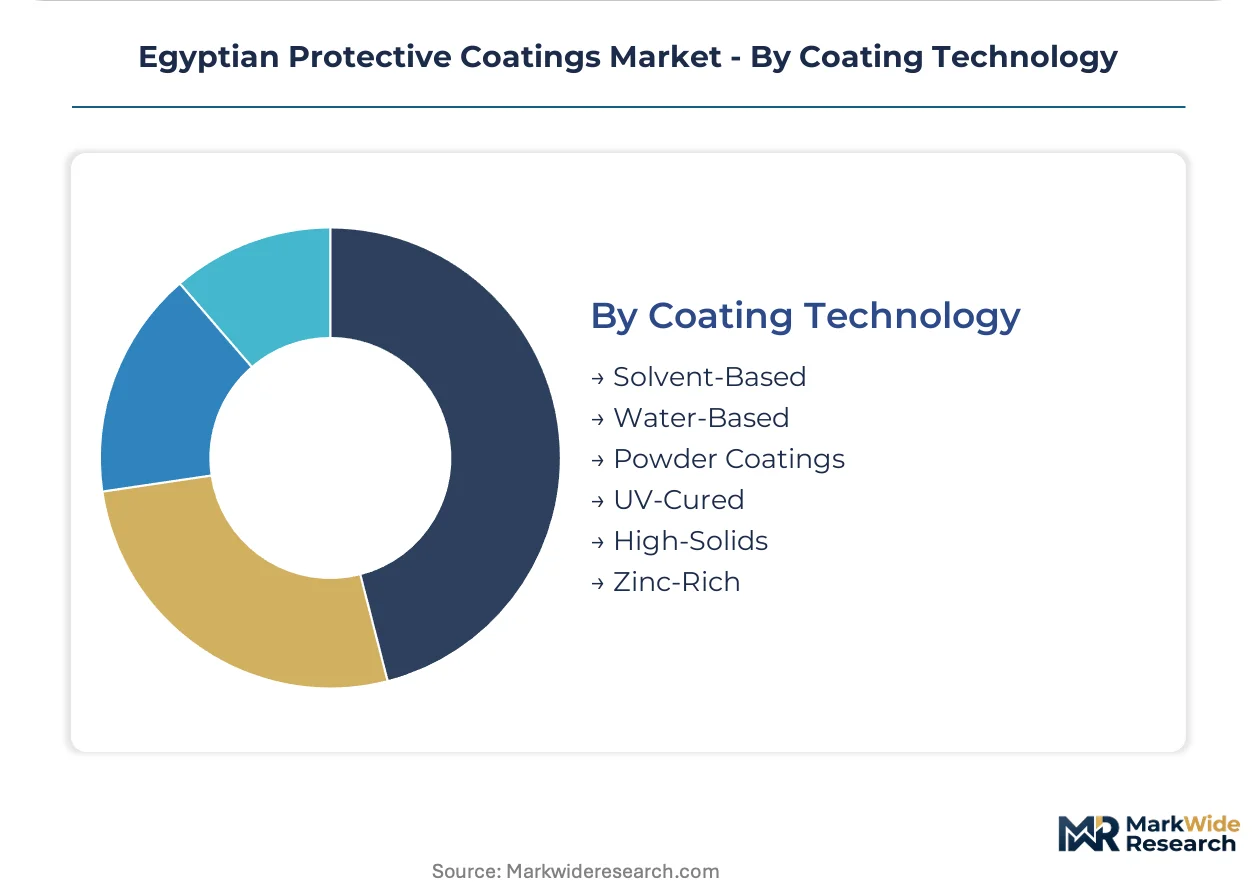
Coating Technology:
Technology selection locks in application infrastructure, skilled labor requirements, and compliance exposure for the coating lifecycle.
- Solvent-Based:Conventional low-solid formulations face distribution restrictions in Greater Cairo and Alexandria as air quality enforcement hardens.
- Water-Based:Hybrid acrylic-epoxy systems penetrate manufacturing and warehouse segments where indoor application dominates.
- Powder Coatings:Zero-VOC performance justifies capital-intensive electrostatic application for premium industrial equipment.
- UV-Cured:Rapid cure chemistry serves specialized factory-applied coatings where production line speed outweighs field flexibility.
- High-Solids:Reduced solvent content satisfies Egyptian Environmental Affairs Agency thresholds while maintaining application productivity.
- Zinc-Rich:Sacrificial primers protect steel substrates in marine and industrial environments where cathodic protection integrates with coating systems.
Solvent-based technology retains the largest installed base; water-based systems are expanding most quickly as environmental compliance reshapes specification standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Cairo and Alexandria industrial corridors concentrate Egypt's protective coatings demand, with the Suez Canal Economic Zone generating specialized marine and petrochemical specification volume.
Greater Cairo
New Administrative Capital construction and manufacturing plant maintenance drive specification authority. Egyptian Environmental Affairs Agency air quality enforcement restricts solvent-based coating application windows in populated governorates. Industrial facilities in 10th of Ramadan City and Obour City adopt water-borne alternatives to comply with emissions reporting mandates.
Alexandria
Port modernization and refinery maintenance cycles anchor demand for high-performance epoxy systems. Egyptian Organization for Standardization certification requirements shape procurement eligibility for state-funded infrastructure. Dry-dock facilities at Dekheila port specify high-solid marine formulations to service Mediterranean fleet renewal.
Suez Canal Economic Zone
Petrochemical investments at Ain Sokhna and East Port Said generate concentrated demand for chemical-resistant tank farm coatings. Egyptian General Petroleum Corporation corrosion management protocols mandate certified systems for pipeline networks. Engineering-procurement-construction contractors consolidate specification authority across megaproject developments.
Red Sea Coastal Governorates
Marine vessel maintenance at Safaga and Hurghada yards accelerates adoption of IMO-compliant coating systems. Egyptian Environmental Affairs Agency coastal zone regulations intersect with international marine guidelines. Ship repair clusters service Red Sea fleet operators seeking extended coating lifecycle performance.
North and South Sinai
Road, pipeline, and military facility construction drives specification for desert-environment coating systems. Egypt Vision 2030 infrastructure mandates prioritize certified contractors with specialized surface preparation capabilities. Limited applicator availability concentrates project execution with established industrial corridor operators.
Egyptian Protective Coatings Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and warranty duration. The Egyptian protective coatings sector exhibits tiered concentration, with international specialists commanding marine and petrochemical specifications while domestic manufacturers compete on distribution reach. Three archetypes dominate: marine-certified specialists, broad-portfolio multinationals, and locally integrated formulators. Competitive moves center on Egyptian Organization for Standardization certification alignment and Suez Canal Economic Zone project positioning.
Among marine-certified specialists, Hempel A/S and Jotun occupy positions defined by Red Sea and Mediterranean fleet service relationships. Akzo Nobel N.V. exemplifies the broad-portfolio multinational archetype spanning solvent-based and water-based platforms. Sigma Paints Egypt Ltd anchors the locally integrated tier through domestic manufacturing scale and Greater Cairo distribution control.
| Leading Market Players |
|---|
| Hempel A/S |
| Sika AG |
| Akzo Nobel N.V. |
| Nippon Paint Holdings Co., Ltd. |
| Axalta Coating Systems Ltd. |
| Jotun |
| Sigma Paints Egypt Ltd |
| CORROCOAT EGYPT |
| PPG Industries |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap formulators across Greater Cairo and Alexandria exercise tight cost discipline through captive distribution networks, translating raw material volatility into formula-specific pricing premiums rather than blanket surcharges. Their ownership structure insulates pricing decisions from quarterly earnings pressure, allowing sustained investment in Egyptian Organization for Standardization certification as a price-anchoring mechanism against multinational competitors.
Pricing Analysis
Outcome-based pricing tied to corrosion-protection warranties anchors premium tiers in Suez Canal Economic Zone petrochemical contracts. Three-tier pricing structure across certified marine systems, industrial-grade epoxies, and commodity alkyd formulations separates procurement tiers by inspection protocol intensity. Price compression runs through solvent-based segments as Egyptian Environmental Affairs Agency enforcement narrows application windows. State-funded infrastructure buyers exhibit lowest price sensitivity due to mandatory certification requirements, while light industrial equipment purchasers drive volume negotiations.
Supply Chain Analysis
Freight cost volatility from Asia-Europe shipping corridors directly feeds into epoxy resin landed costs at Alexandria port terminals. Feedstock concentration in Germany, China, and South Korea exposes Egyptian formulators to currency fluctuation and container availability constraints. Bisphenol-A and epoxy hardener dependencies rest on quarterly contract structures with limited spot market alternatives. Single-source vulnerability concentrates in specialized marine-grade additive packages. Distribution runs through authorized applicator networks clustered in industrial corridors, with direct EPC contractor relationships displacing traditional distributor tiers in megaproject procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized applicator scarcity across North and South Sinai governorates props pricing power for certified contractors, constraining rapid project scaling and sustaining margin premiums for qualified execution capacity.
For Market Incumbents: To counter water-based technology convergence by domestic competitors, deepen backward integration into epoxy resin blending at 10th of Ramadan City facilities while securing exclusive distribution agreements with Suez Canal Economic Zone EPC contractors holding long-term substrate warranties. For New Entrants and Emerging Players: Egyptian Environmental Affairs Agency air quality enforcement in Greater Cairo opens a window for water-borne acrylic-epoxy hybrid formulations in manufacturing plant maintenance cycles. Target warehouse and logistics facility segments with rapid return-to-service requirements, leveraging indoor application advantages to bypass solvent-based seasonal restrictions. For Investors and Strategic Acquirers: Egyptian Organization for Standardization certification backlog expansion is the leading indicator that specification authority is concentrating with EPC contractors, signaling durable margin capture for certified formulators. Prioritize acquisition targets with established EPC relationships and existing certification portfolios rather than pure manufacturing capacity. Watch for EGPC inspection protocol updates as inflection signals for upstream specification upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin Production | Reduces import dependency on German and Chinese feedstock suppliers while hedging currency exposure. |
| Egyptian Organization for Standardization Certification Investment | Creates procurement eligibility for New Administrative Capital and Sinai infrastructure state-funded developments. |
| Water-Based Technology Manufacturing Scale-Up | Aligns formulation capacity with Egyptian Environmental Affairs Agency enforcement tightening in populated governorates. |
| Suez Canal Economic Zone Project Positioning | Captures concentrated demand from Ain Sokhna petrochemical tank farm and pipeline network construction cycles. |
| Certified Applicator Network Expansion | Addresses specialized technician scarcity limiting project execution scaling in desert-environment infrastructure segments. |
Research Methodology
Document review covered Egyptian General Petroleum Corporation inspection protocols, Egyptian Environmental Affairs Agency emissions enforcement records, and Suez Canal Economic Zone investment disclosures, complemented by interviews with plant managers at Alexandria and Cairo industrial facilities, procurement leads at downstream petrochemical operators, distribution channel partners serving Greater Cairo manufacturing corridors, and technical R&D directors at marine coating specialists. Secondary validation drew from customs and trade data, Egyptian Organization for Standardization certification registries, and engineering-procurement-construction contractor project announcements. Bottom-up volume estimates from segment-level coating consumption were cross-referenced against top-down macroeconomic indicators to establish analytical coherence.
Historical consumption patterns across resin chemistries and application segments were cross-referenced against panel input from industry stakeholders to construct projection scenarios. The analytical framework modeled coating technology transitions, substrate-specific specification requirements, and regional industrial development patterns throughout the forecast period. CAGRs were derived from weighted average growth trajectories across marine vessel maintenance cycles, petrochemical infrastructure investment waves, and construction sector coating intensity trends. Forecast inputs incorporated Egyptian Vision 2030 project pipeline visibility and IMO marine guideline compliance deadlines.
The model assumes a particular technology adoption path toward water-borne and high-solid formulations; alternative pathways for solvent-free epoxy systems would alter the outlook if application infrastructure investment accelerates beyond baseline assumptions. Forecasts reflect assumptions about regulatory enforcement consistency, currency stability, and Suez Canal transit volume maintenance. Stakeholders should weight assumptions against their own operating context and project pipeline visibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Heat Resistant Coatings Market
Coatings
Germany Industrial Coatings Market
Coatings
Clear Coatings Market
Coatings
South Africa Protective Coatings Market
Coatings
France Automotive OEM Coatings Market
Coatings
Silicone Coating Market
Coatings
Pure Epoxy Powder Coatings Market
Coatings
Global Hydrophobic Coating Market
Coatings
Dispersion Coating Market
Coatings
Russia Protective Coatings Market
Coatings
Phosphate Conversion Coatings Market
Coatings
Concrete Floor Coatings Market
Coatings
Acrylic Coating Market
Coatings
Global Metal Coatings Market
Coatings
Noise and Vibration Coatings Market
Coatings
Mold Release Coatings Market