
 Pre-Dispersed Rubber Chemicals Market | 2026-2036
Pre-Dispersed Rubber Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Dispersed Rubber Chemicals Market Analytics
Multi-source procurement among tire compounders is shifting toward preferred-supplier agreements with pre-dispersed chemical specialists. LANXESS AG leverages its polymer-bound additive portfolio to anchor long-term contracts with European tire OEMs. Evonik Industries sustains technology leadership through high-dispersion silica-silane masterbatch systems. BASF SE competes on manufacturing scale, operating integrated production networks across Germany and Belgium.
Pre-dispersed rubber chemicals are polymer-bound or liquid-dispersed additive concentrates, typically containing 50-80% active ingredient content, engineered to eliminate dust generation and improve distribution uniformity in rubber mixing. Their primary purpose is to reduce batch-to-batch variability, shorten mixing cycles, and lower workplace exposure to hazardous chemical dusts in tire and industrial rubber production. Antioxidants occupy the largest product segment due to their universal requirement across all durable rubber applications, while accelerators represent the fastest-growing category as tire makers adopt increasingly complex cure systems for high-performance compounds. The tires application segment dominates volume consumption, though industrial goods applications are gaining traction as conveyor belt and hose manufacturers upgrade mixing operations for consistency.
REACH registration requirements and the EU F-Gas Regulation are tightening chemical handling standards across European rubber processing facilities, while OSHA permissible exposure limits and EPA Toxic Substances Control Act provisions govern workplace and environmental compliance in the United States. These frameworks compel compounders to substitute conventional powder chemicals with dust-free pre-dispersed alternatives to maintain operational licenses and avoid penalty exposure. Stakeholders must monitor evolving regulatory thresholds for nitrosamine precursors and respirable particulate limits, as these will determine product reformulation priorities and supplier qualification criteria across major tire-producing jurisdictions.
Market Dynamics
Tire manufacturers are consolidating additive procurement around pre-dispersed formats to compress mixing cycles and eliminate dust exposure liabilities. REACH nitrosamine limits and EPA workplace standards are accelerating this substitution away from conventional powder chemicals.
Growth Catalysts
- REACH compliance deadlines:European compounders face mandatory reduction of residual nitrosamines in rubber chemicals, forcing adoption of polymer-bound additive concentrates that eliminate hazardous dust generation during handling.
- High-performance tire cure systems:Complex multi-stage vulcanization protocols require precisely dispersed accelerator packages to achieve uniform cross-link density across tread, sidewall, and belt compound layers.
- China tire capacity expansion:Domestic producers are building captive pre-dispersed additive facilities to secure supply chain control and reduce import dependency for critical mixing chemicals.
Market Restraints
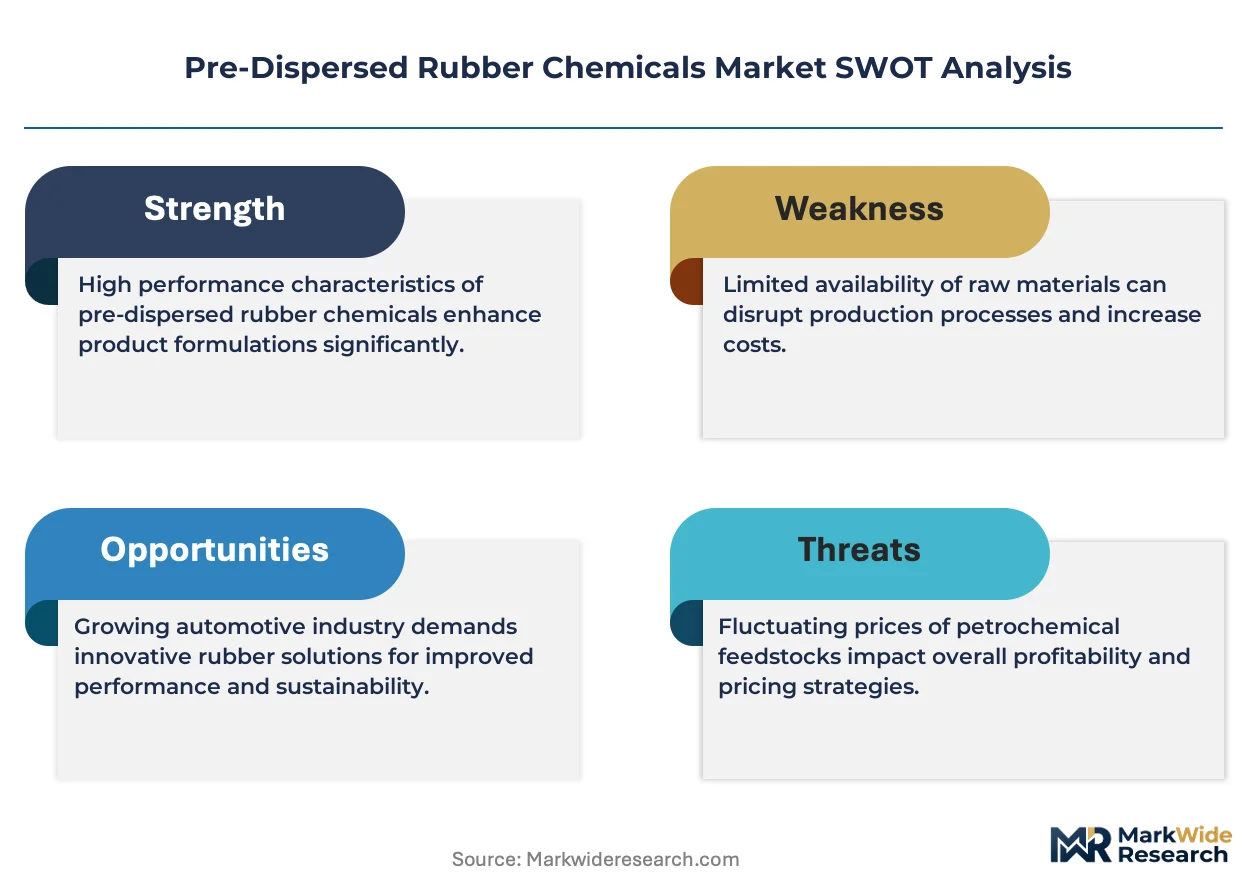
- Petrochemical feedstock volatility:Synthetic rubber polymer carriers and processing oils fluctuate with crude oil indices, compressing margins on polymer-bound masterbatch formulations.
- Specialized equipment requirements:Liquid-dispersed chemical systems demand heated storage tanks and precision metering pumps that many legacy mixing plants lack.
- Conventional powder substitution:Cost-sensitive industrial rubber goods producers in Southeast Asia continue purchasing bulk powder antioxidants despite dust exposure risks.
Strategic Opportunities
- Indian tire manufacturing:Underpenetrated pre-dispersed additive usage among domestic compounders presents expansion potential as BIS standards align with European dust exposure protocols.
- Conveyor belt segment upgrade:Mining equipment manufacturers are retrofitting mixing operations for compound consistency to reduce field failure rates in high-tensile belting.
- Silica-silane integration:Convergence of high-dispersion silica masterbatches with pre-dispersed coupling agents enables single-stage addition for fuel-efficient tire compounds.
Industry Challenges
- Formulation chemistry expertise:Compounders lack technical staff capable of optimizing active ingredient loading rates across varying polymer carrier systems without performance degradation.
- REACH registration timelines:New pre-dispersed chemical variants require 18-24 month ECHA dossier preparation before commercial introduction in European tire plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Dispersed Rubber Chemicals Market |
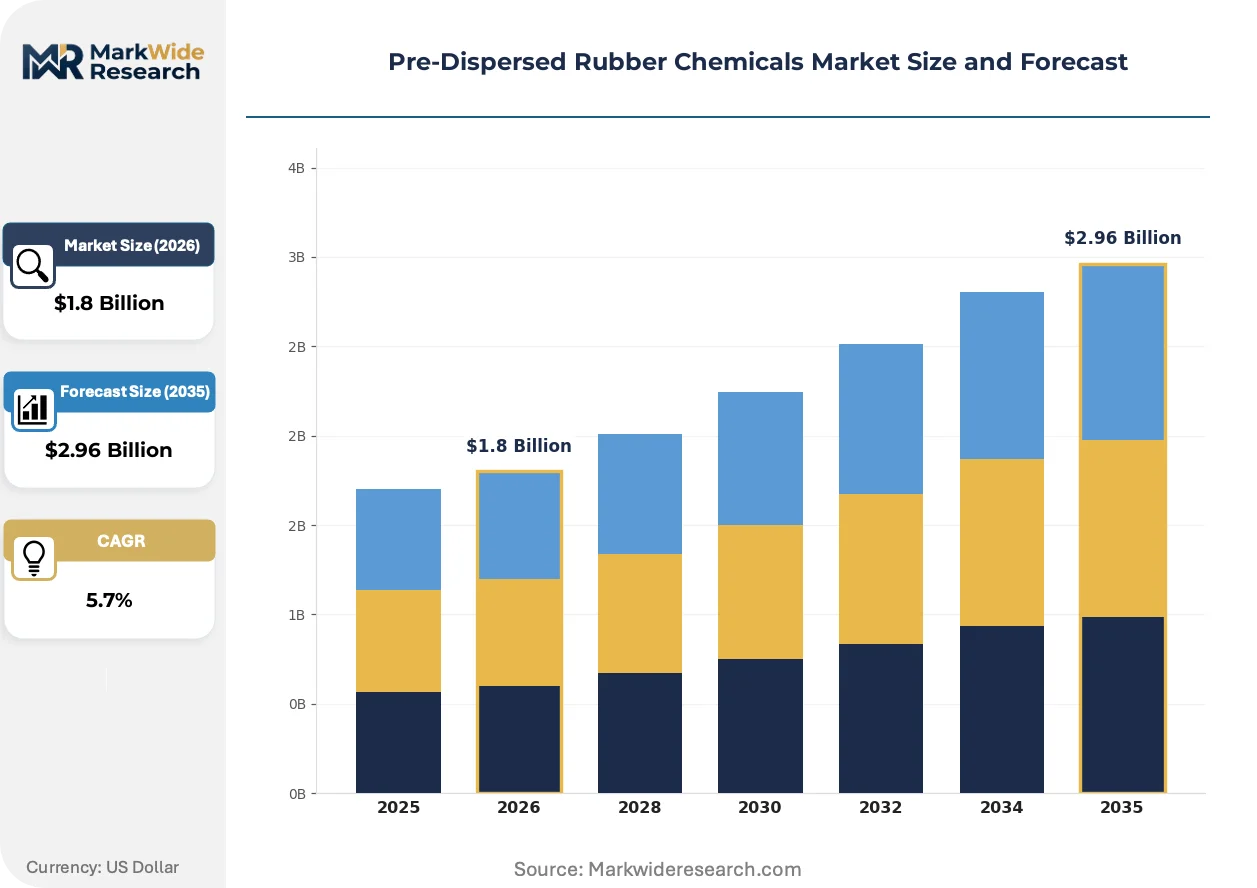
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antioxidants, Accelerators, Fillers, Plasticizers Application: Tires, Automotive Components, Footwear, Industrial Goods End User: Manufacturers, Distributors, Retailers, OEMs Packaging Type: Bags, Drums, Bulk Containers, Retail Packs |
| Companies Covered | LANXESS AG, Evonik Industries, BASF SE, Arkema Group, SI Group, Sinopec Corp., Nocil Limited, Eastman Chemical Company, Kumho Petrochemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Dispersed Rubber Chemicals Market Evolving Landscape
Pre-dispersed rubber chemical formats are converging with digital process control systems to enable real-time dosing adjustments. This integration is compressing development cycles for next-generation tire compounds.
Polymer-bound antioxidant masterbatches are unifying active ingredient protection with carrier polymer compatibility. Tire OEMs in Germany and Japan are specifying these formats for all new compound approvals. The technology is unifying quality assurance protocols across multi-site manufacturing networks by eliminating batch-to-batch powder dispersion variance.
EPA TSCA Section 5 notification requirements for new chemical substances are tightening pre-market approval timelines for innovative additive formulations. Industrial rubber processors in the United States face extended qualification periods before substituting legacy powder chemicals. Accelerators containing alternative nitrosamine-free chemistries are experiencing accelerated regulatory review to meet 2025 workplace exposure targets.
Preferred-supplier contracting is displacing spot purchasing for pre-dispersed additives among volume tire compounders. Long-term offtake agreements now bundle technical service support with volume commitments. This restructuring concentrates procurement decision authority at headquarters technical teams rather than regional plant managers, with the shift most visible among top-five tire manufacturers operating integrated European mixing facilities.
Pre-Dispersed Rubber Chemicals Market Segmentation
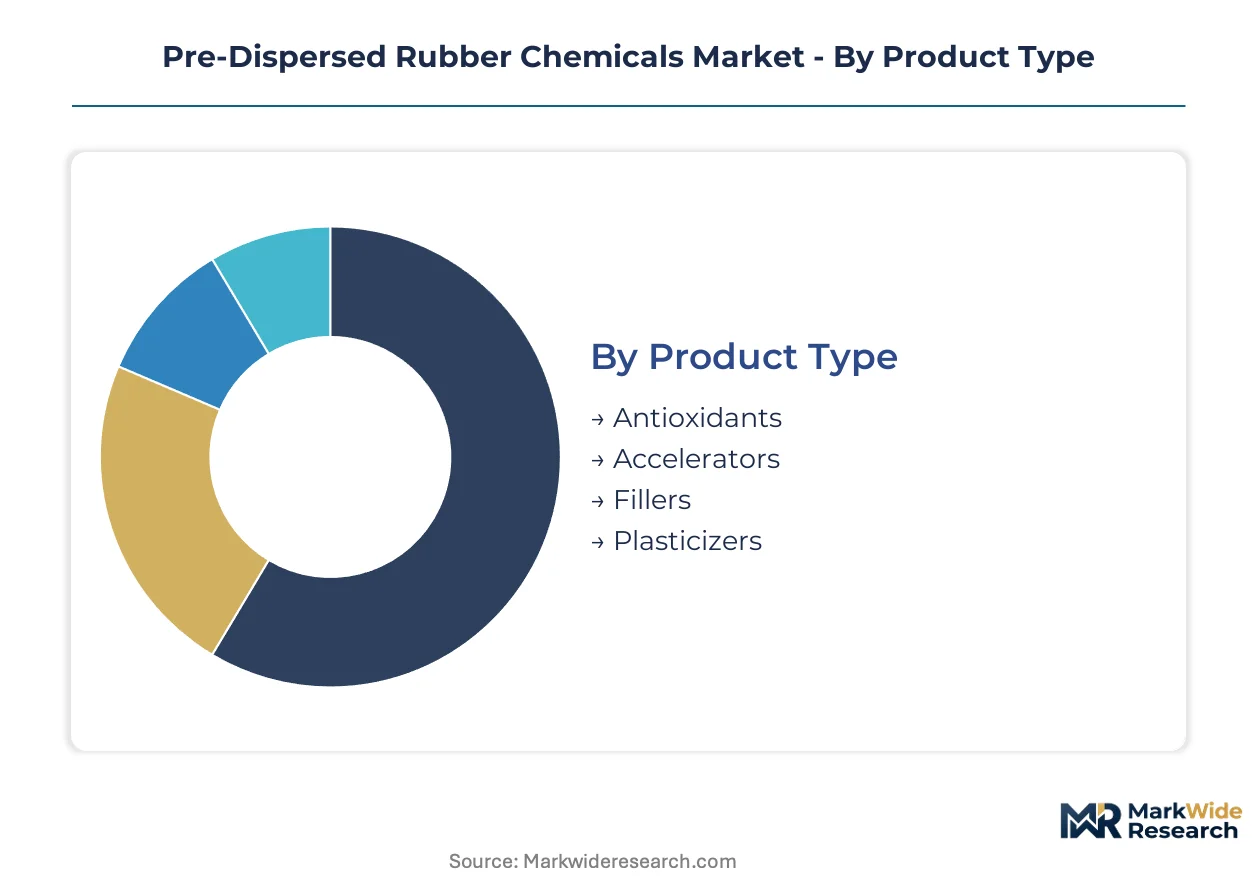
Pre-dispersed rubber chemicals require differentiated certification pathways across product categories, with polymer-bound masterbatches facing REACH dossier requirements while liquid-dispersed formats trigger EPA TSCA notifications. Segmentation reveals how regulatory burden concentrates in specific additive types and end-use applications.
Product Type:
REACH registration obligations vary sharply across product categories, with polymer-bound concentrates requiring full ECHA dossiers while liquid dispersions face lighter notification thresholds in Europe.
- Antioxidants:Polymer-bound concentrates containing phenolic or amine-based active ingredients at 50-70% loading, universally required across all durable rubber applications. Tire manufacturers in Germany and Japan specify these formats for all new compound approvals to eliminate batch-to-batch powder dispersion variance. Antioxidants sit at the top of the volume ranking, with accelerators climbing the fastest.
- Accelerators:Complex multi-stage vulcanization protocols demand precisely dispersed thiazole, sulfenamide, and guanidine packages to achieve uniform cross-link density. Nitrosamine-free chemistries are experiencing accelerated regulatory review to meet workplace exposure targets. Demand concentrates among high-performance tire producers adopting sophisticated cure systems for tread, sidewall, and belt compound layers.
- Fillers:High-dispersion silica-silane masterbatch systems enable single-stage addition for fuel-efficient tire compounds, reducing mixing complexity.
- Plasticizers:Liquid-dispersed processing oils and ester-based softeners improve low-temperature flexibility in automotive sealing applications.
Antioxidants command the largest revenue share due to universal application requirements, while accelerators are expanding most quickly as cure system complexity increases.
Application:
Cost tier differentiation separates premium tire compounds from standard industrial formulations, with mixing cycle reduction justifying higher additive pricing in volume-sensitive segments.
- Tires:Tread, sidewall, and belt compounds require precisely matched pre-dispersed additive packages to achieve fuel efficiency and durability targets. Major tire OEMs operate integrated European mixing facilities where preferred-supplier agreements now bundle technical service with volume commitments. Tires dominate consumption volumes across all geographies.
- Automotive Components:Engine mounts, seals, and hoses demand consistent compound properties for vibration damping and fluid resistance. OEM qualification protocols in Germany and Japan mandate polymer-bound formats for all new compound approvals.
- Footwear:Soling compounds prioritize cost efficiency over mixing sophistication, with many producers in Southeast Asia continuing bulk powder purchases despite dust exposure risks.
- Industrial Goods:Mining equipment manufacturers are retrofitting mixing operations for compound consistency to reduce field failure rates in high-tensile conveyor belting.
Tires anchor the volume ranking, with industrial goods gaining share fastest as mining and material handling upgrade mixing infrastructure.
End User:
Customer type determines procurement authority concentration, with headquarters technical teams displacing regional plant managers in additive sourcing decisions.
- Manufacturers:Integrated tire compounders building captive pre-dispersed additive facilities to secure supply chain control and reduce import dependency for critical mixing chemicals.
- Distributors:Regional chemical distributors serving mid-size industrial rubber processors lacking formulation chemistry expertise to optimize active ingredient loading rates.
- Retailers:Small-volume packaging for maintenance and repair operations in downstream rubber fabrication.
- OEMs:Automotive and tire original equipment manufacturers specifying pre-dispersed formats through direct preferred-supplier contracts with additive specialists.
Manufacturers represent the dominant procurement channel, with OEMs expanding fastest as direct contracting displaces spot purchasing.
Packaging Type:
Handling infrastructure requirements create segmentation by facility scale, with heated storage and precision metering systems favoring bulk formats in greenfield plants.
- Bags:Polymer-bound masterbatches in moisture-barrier packaging for conventional mixing operations without liquid handling infrastructure.
- Drums:Liquid-dispersed chemicals requiring heated storage tanks and precision metering pumps that many legacy mixing plants lack.
- Bulk Containers:Tank truck and ISO-tank deliveries for high-volume tire plants with integrated unloading and storage systems.
- Retail Packs:Small-quantity containers for specialty compounders and research and development laboratories.
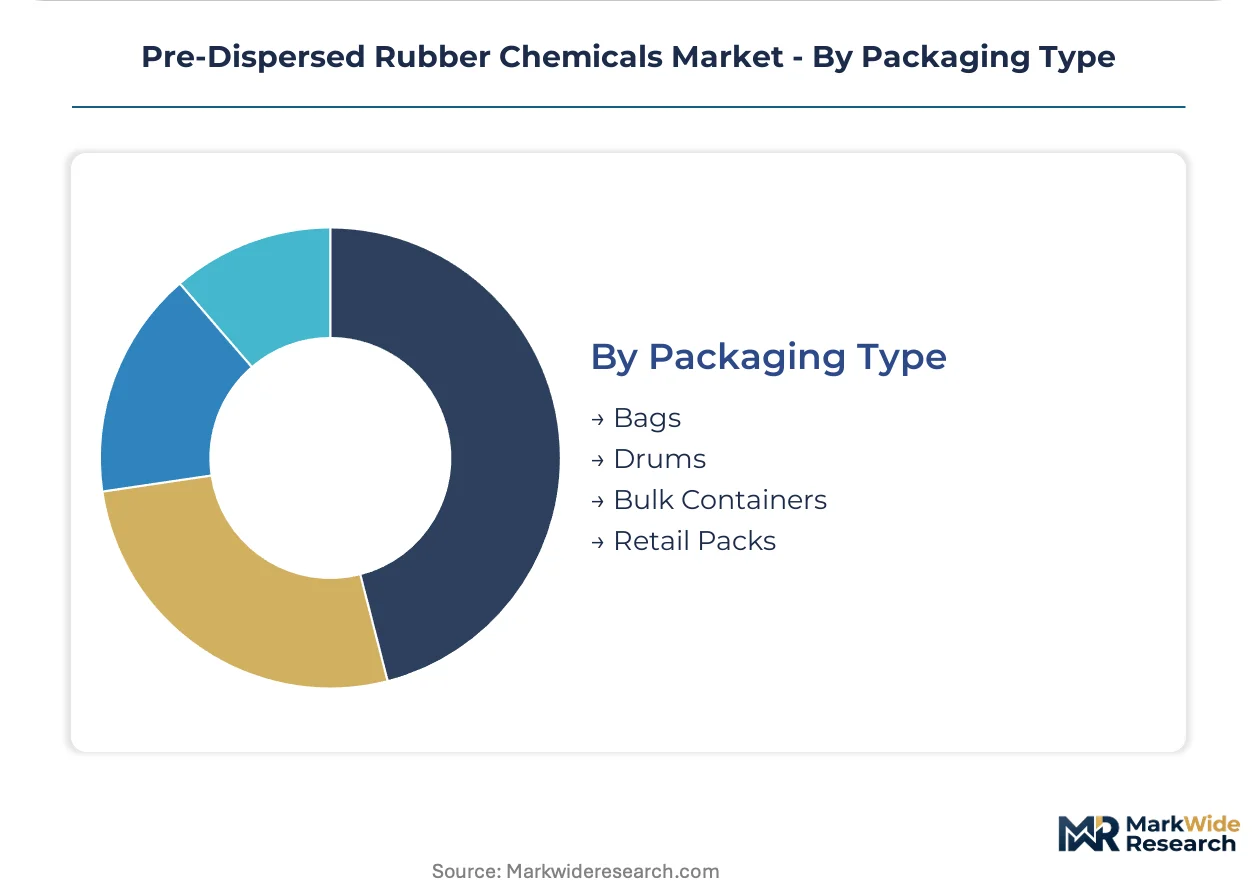
Bulk containers lead the volume ranking, with drums expanding most quickly as liquid-dispersed formats penetrate upgraded mixing facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shandong Peninsula anchors global pre-dispersed rubber chemical manufacturing, with Qingdao and Yantai hosting integrated tire and additive production corridors that supply domestic and export markets.
China
Domestic tire producers in Shandong and Jiangsu provinces are constructing captive pre-dispersed additive facilities to reduce import dependency. MIIT's GB standards for workplace dust exposure are tightening faster than regional enforcement capacity allows. The Yangtze River Delta mixing cluster around Shanghai is upgrading liquid-dispersed handling infrastructure to meet multinational OEM qualification protocols.
Germany
Continental and Michelin mixing operations in Lower Saxony and North Rhine-Westphalia specify polymer-bound formats for all new compound approvals. REACH nitrosamine limits enforced by ECHA are eliminating conventional powder accelerator purchases. The KBA maintains strict material certification requirements that pre-qualify only established pre-dispersed suppliers for OE tire contracts.
United States
EPA TSCA Section 5 notifications are extending qualification timelines for innovative additive formulations at tire plants in South Carolina and Ohio. OSHA permissible exposure limits for respirable particulates are accelerating substitution away from powder chemicals. The Southeast mixing corridor around Greenville, South Carolina is retrofitting heated storage systems for liquid-dispersed accelerator packages.
India
Apollo Tyres and MRF compounders in Tamil Nadu and Haryana are expanding pre-dispersed additive trials as BIS standards align with European dust exposure protocols. CDSCO chemical handling guidelines are tightening faster than domestic supplier capacity expands. The Gujarat chemical belt around Vadodara is attracting foreign masterbatch producers seeking tariff-advantaged production for Asian markets.
Japan
Bridgestone and Yokohama Rubber mixing facilities in Kansai and Chubu regions mandate polymer-bound antioxidants for fuel-efficient tire development. METI's JIS standards for workplace chemical handling exceed baseline ILO conventions. The Kyushu industrial corridor is consolidating specialty rubber chemical production to serve automotive OEMs with just-in-time additive delivery.
Pre-Dispersed Rubber Chemicals Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue silica-silane integration and liquid-dispersion technologies. The vendor base concentrates around polymer-bound masterbatch specialists and petrochemical-integrated chemical divisions. Three archetypes dominate: integrated petrochemical conglomerates, tire-captive additive producers, and independent dispersion technology specialists. Capacity expansion and preferred-supplier contracting constitute the primary competitive vectors, with backward integration into polymer carrier supply chains accelerating among volume compounders.
Among German chemical conglomerates, LANXESS AG and BASF SE exemplify the integrated petrochemical archetype, anchoring polymer-bound additive portfolios through manufacturing networks across Germany and Belgium. Evonik Industries occupies a position within the specialty dispersion tier, representing technology leadership in high-dispersion silica-silane masterbatch systems. These three entities collectively illustrate how European producers leverage REACH compliance expertise to secure long-term contracts with tire OEMs operating integrated mixing facilities.
| Leading Market Players |
|---|
| LANXESS AG |
| Evonik Industries |
| BASF SE |
| Arkema Group |
| SI Group |
| Sinopec Corp. |
| Nocil Limited |
| Eastman Chemical Company |
| Kumho Petrochemical |
| Others |
Value Network & Pricing Analysis
Liquid-dispersed accelerator systems are displacing conventional powder formats across European and North American tire plants, simultaneously compressing per-unit production economics and concentrating procurement leverage among integrated compounders with heated storage infrastructure. This technology transition rewards scale players while squeezing margin buffers for mid-tier suppliers lacking metering pump networks.
Pricing Analysis
Petrochemical feedstock pass-through mechanics dominate polymer-bound masterbatch economics, with synthetic rubber carrier costs and processing oil indices tracking crude oil benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered polymer concentrates from unregistered liquid dispersions and commodity powder alternatives. Cost compression in economy-tier antioxidants is intensifying because Southeast Asian industrial rubber goods producers resist format upgrades. Volume tire manufacturers operating integrated mixing facilities exhibit lowest price sensitivity, while footwear compounders in Vietnam and Indonesia remain most responsive to unit cost differentials.
Supply Chain Analysis
Domestic content mandates in China's tire sector are reshaping sourcing patterns, with Shandong and Jiangsu provincial governments incentivizing captive pre-dispersed additive production. Manufacturing gravity centers on China, Germany, and the United States, with the Shandong Peninsula hosting the densest corridor of integrated tire-additive production. Raw material flows draw from synthetic rubber polymer carriers, amine-based active ingredients, and silica-silane coupling agents. Single-source vulnerability concentrates in specialized dispersion equipment supply, where German and Japanese precision pump manufacturers command essential technology. Distribution runs through preferred-supplier agreements bundling technical service with volume commitments, displacing spot purchasing at major tire OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-dispersed rubber chemicals function as a stable compounder, with regulatory mandates for dust-free handling and nitrosamine reduction providing durable demand tailwinds across tire and industrial rubber end-uses.
For Market Incumbents: Hedge against petrochemical margin volatility through backward integration into synthetic rubber carrier supply chains, particularly in Belgium and Germany where LANXESS and BASF already operate integrated networks. Lock in preferred-supplier status with top-five tire manufacturers by embedding technical service teams at their European mixing facilities, defending against emerging silica-silane specialists eroding technology differentiation. For New Entrants and Emerging Players: The price-point gap between premium REACH-registered polymer concentrates and economy-tier liquid dispersions offers entry space for mid-grade accelerators targeting Indian tire compounders. Focus initial penetration on conveyor belt manufacturers retrofitting mixing operations for compound consistency, where technical support requirements remain modest and qualification timelines compress versus automotive OEM protocols. For Investors and Strategic Acquirers: Valuations sit cheapest among independent dispersion technology specialists lacking captive polymer carrier supply. Five-to-ten-year viability rests on regulatory tightening trajectory rather than cyclical demand swings. Acquisition targets should display established ECHA dossier preparation capabilities and existing technical service relationships with at least two tier-one tire OEMs. Monitor CDSCO enforcement pace in India as the critical inflection signal for geographic expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Carriers | Secures margin control against crude oil index volatility at integrated German and Belgian facilities. |
| REACH Dossier Pre-Registration | Accelerates ECHA approval timelines for nitrosamine-free accelerator variants before compliance deadlines tighten. |
| Liquid-Dispersion Infrastructure Retrofit | Enables heated storage and precision metering capabilities at legacy mixing plants in South Carolina and Ohio. |
| Preferred-Supplier Agreement Expansion | Concentrates procurement authority at headquarters technical teams of Continental and Michelin operations. |
| Silica-Silane Masterbatch Convergence | Supports single-stage addition protocols for fuel-efficient tire compounds demanded by German and Japanese OEMs. |
Research Methodology
Bottom-up tire and industrial rubber compounding modeling reconciled against top-down chemical additive production tracking forms the analytical core of this study. Primary interviews with plant managers at integrated tire facilities, procurement leads at downstream OEMs, distribution channel partners serving mid-size compounders, and technical R&D directors at additive specialists were validated against secondary sources including customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical conglomerates, and ECHA registration databases. This dual approach enables cross-verification of volume assumptions across polymer-bound masterbatch and liquid-dispersed format categories.
Historical trendline analysis of antioxidant and accelerator consumption patterns across the projection horizon informs the forecast framework. Segmentation dimensions modeled include product type tier, end-use application, packaging format scale, and regional production hub concentration. CAGRs were derived through slope analysis of normalized consumption trajectories, incorporating tire industry production forecasts and regulatory compliance timeline assumptions as key inputs. Silica-silane integration rates and liquid-dispersion penetration curves serve as industry-specific demand modifiers.
The model assumes a particular technology adoption path; alternative pathways for liquid-dispersed accelerator systems would alter the outlook if heated storage infrastructure deployment stalls at legacy mixing plants. Forecasts reflect assumptions regarding REACH enforcement consistency, MIIT GB standard implementation pace in China, and sustained tire OEM preference for polymer-bound formats in Germany and Japan. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Choppers Market
Rubber
Rubber Coatings Market
Rubber
Global Liquid Synthetic Rubber Market
Rubber
Europe Silicone Rubber Market
Rubber
Sterile Rubber Stopper Market
Rubber
EMEA and Asia Pacific Electrical Insulating Rubber Gloves Market
Rubber
Global Hydraulic Rubber Hose Market
Rubber
Rubber Wear Liners Market
Rubber
Polybutadiene Market
Rubber
Rubber Gloves Market
Rubber
US Nitrile Gloves Market
Rubber
Liquid Polybutadiene Market
Rubber
Rubber Color Masterbatch Market
Rubber
Polyisoprene Rubber Market
Rubber
Rubber Carbon Black Market
Rubber
Styrene Butadiene Rubber (E-SBR and S-SBR) Market