
 Snap on Rubber Stopper Market | 2026-2036
Snap on Rubber Stopper Market Size, Share, and Industry Trends Forecast 2026-2036
Snap on Rubber Stopper Market Analytics
Silicone is broadening its share against natural rubber in premium closure systems due to superior thermal stability and reduced extractables risk. West Pharmaceutical Services leverages its vertically integrated elastomer compounding operations to sustain supply security for biologic drug manufacturers. Datwyler Holding anchors its position through Swissmedic-certified cleanroom production in Switzerland, while Gerresheimer AG differentiates via specialized coating technologies that minimize protein adsorption on stoppers.
A snap on rubber stopper is an elastomeric closure device, typically 13mm to 32mm in diameter, manufactured through compression or injection molding of halobutyl or bromobutyl rubber compounds to achieve gas-barrier integrity and needle-resealability; it seals vials, bottles, and infusion containers against contamination while permitting multiple syringe punctures. The Pharmaceutical application segment leads value generation due to stringent EMA and FDA sterilization validation requirements, while the Biodegradable product type represents the fastest-growing niche as sustainability mandates from the EU Green Deal reshape material selection criteria across European supply chains. Silicone material grades command premium positioning in high-value biologics packaging where extractables profiles directly influence regulatory submission timelines.
FDA container closure guidance and EMA Annex 1 revision on sterile manufacturing both elevate elastomer qualification burdens, compelling manufacturers to maintain comprehensive extractables and leachables documentation. The EU F-Gas Regulation and REACH chemical restrictions further constrain formulation options for European suppliers, pushing investment toward halogen-free curing systems. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP standards to anticipate testing protocol changes that could obsolete existing product qualifications.
Market Dynamics
EMA Annex 1 revision on sterile manufacturing is compressing qualification timelines for elastomer suppliers while simultaneously fragmenting procurement across multiple certification tiers as biologics manufacturers dual-source to mitigate supply risk.
Growth Catalysts
- Biologics expansion:Cell and gene therapy pipelines in Germany and Switzerland are multiplying vial closure demand per treatment course. Injectable drug producers require halobutyl stoppers with validated extractables profiles for regulatory submissions.
- REACH chemical restrictions:EU chemical policy is accelerating formulation shifts toward halogen-free curing systems. European suppliers are qualifying alternative elastomer compounds to maintain market access.
- Sterilization protocol convergence:Steam and gamma sterilization standards are harmonizing across USP, EP, and JP pharmacopeias. Multi-region drug manufacturers are consolidating stopper specifications to reduce SKU complexity.
Market Restraints
- Raw material concentration:Bromobutyl rubber feedstock depends on concentrated petrochemical supply from select Middle Eastern and Southeast Asian producers. Geopolitical disruption or shipping constraints transmit directly to compound pricing.
- Regulatory friction:FDA container closure guidance demands extensive extractables and leachables documentation. Smaller compounders lack analytical infrastructure to complete qualification packages independently.
- Silicone substitution pressure:Premium biologics packaging is migrating toward platinum-cured silicone alternatives with lower protein adsorption. Natural and halobutyl rubber face share erosion in high-value therapeutic categories.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO-aligned import protocols and domestic production incentives under the PLI scheme are expanding local stopper demand. Contract manufacturers serving export markets require EMA-quality closures.
- Biodegradable elastomer development:EU Green Deal sustainability mandates are creating procurement preference for compostable or bio-based closure materials. Early movers in polymer chemistry capture specification influence with European pharma buyers.
- Coating technology convergence:Fluoropolymer and plasma coating methods are merging with conventional molding to reduce surface extractables. Integrated process offerings differentiate compounders from commodity stopper suppliers.
Industry Challenges
- Cleanroom certification backlog:Swissmedic and EMA GMP inspections face scheduling delays of 12-18 months. Unqualified production lines cannot supply regulated drug markets regardless of technical capability.
- Analytical talent scarcity:Extractables and leachables study design requires specialized chromatography and mass spectrometry expertise. Competition for qualified scientists from contract research organizations inflates compensation costs.
- Legacy equipment integration:Automated vision inspection systems for stopper dimensional verification must interface with decades-old compression molding infrastructure. Retrofit complexity extends validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snap on Rubber Stopper Market |
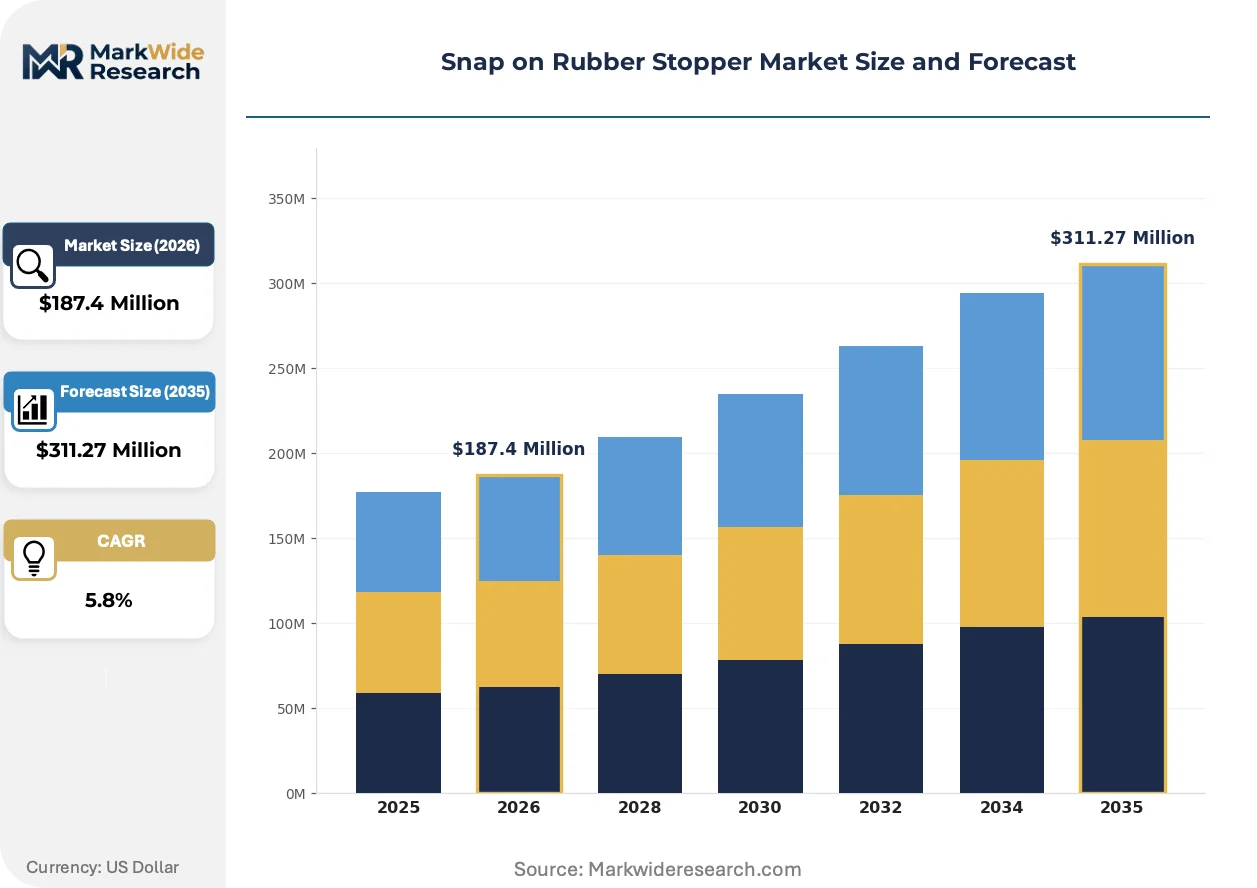
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Custom, Biodegradable, High-Temperature Application: Pharmaceuticals, Beverages, Chemicals, Laboratories Material: Natural Rubber, Silicone, EPDM, PVC Packaging Type: Bulk, Shrink Wrap, Blister Pack, Cartons |
| Companies Covered | West Pharmaceutical Services, Datwyler Holding, AptarGroup, DWK Life Sciences, SGD Pharma, Daikyo Seiko, Gerresheimer AG, Schott AG, Nipro Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snap on Rubber Stopper Market Evolving Landscape
Material science advances and regulatory harmonization pressures are converging to reshape how elastomer closures are formulated, tested, and procured across pharmaceutical supply chains.
Platinum-cured silicone is electrifying premium closure specifications through its superior thermal stability and reduced extractables risk compared with conventional rubber compounds. Biologics manufacturers in Germany and Switzerland are specifying silicone grades for monoclonal antibody and cell therapy packaging. This material transition is compressing margins for compounders without silicone compounding capabilities while rewarding integrated suppliers with captive polymer production.
EMA Annex 1 revision on sterile manufacturing is mandating enhanced container closure integrity testing for all aseptically filled products. Drug manufacturers must now demonstrate quantitative seal performance under accelerated aging conditions. Parenteral packaging lines in Ireland, Belgium, and the Netherlands are retrofitting helium leak detection systems to meet the new validation requirements.
Dual-sourcing contracts are displacing single-source procurement arrangements as pharmaceutical buyers mitigate supply concentration risk. Large molecule drug producers are qualifying secondary stopper suppliers across multiple geographies simultaneously. This pattern is most visible among German and Swiss biotech firms with FDA submission timelines that cannot tolerate raw material delays.
Snap on Rubber Stopper Market Segmentation
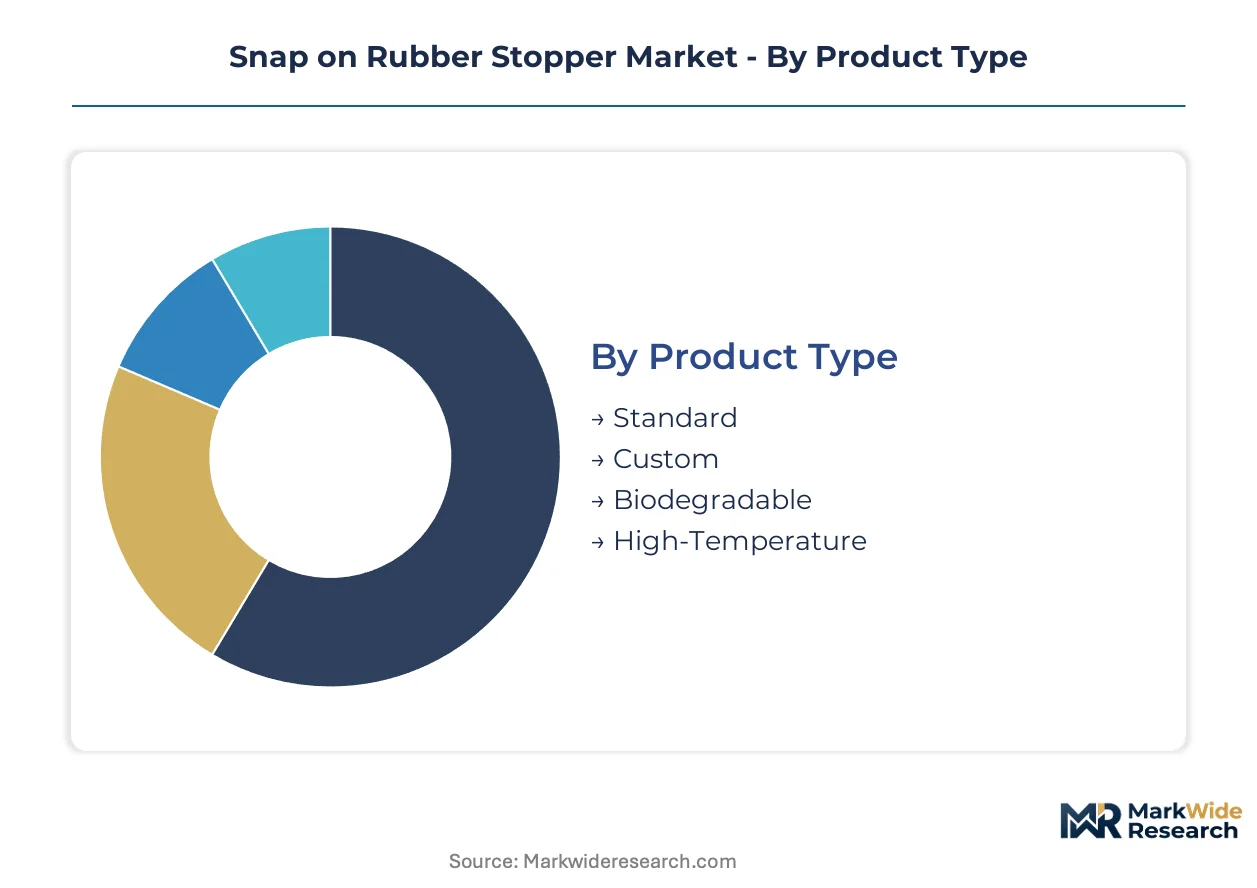
Elastomer closure procurement in pharmaceutical and industrial packaging hinges on material certification tiers, sterilization compatibility, and supply chain traceability requirements. Segmentation reveals how formulation chemistry and packaging format choices cascade into regulatory qualification burdens and sourcing economics.
Product Type:
Standalone molded closures dominate high-volume pharmaceutical lines, while custom-engineered variants embed into specialized drug-device combination products.
- Standard:Compression-molded halobutyl stoppers in 13mm to 32mm diameters serve generic injectable vials across European contract manufacturing organizations. German and Swiss fill-finish facilities specify these for multi-source drug products with established regulatory dossiers.
- Custom:Application-specific geometries with modified reseal surfaces accommodate novel delivery systems such as pre-filled syringes and cartridge-based autoinjectors. Biologics manufacturers in Germany commission these for monoclonal antibody presentations requiring validated container closure integrity under accelerated aging protocols.
- Biodegradable:Compostable elastomer compounds derived from bio-based feedstocks address EU Green Deal procurement mandates.
- High-Temperature:Peroxide-cured formulations withstand steam sterilization cycles above 121°C for parenteral applications.
Volume placements concentrate in Standard configurations; the faster expansion belongs to Biodegradable alternatives as sustainability criteria reshape European tender specifications.
Application:
Regulatory intensity varies sharply across end-use sectors, with pharmaceutical demand commanding premium pricing and exhaustive documentation.
- Pharmaceuticals:Aseptic vial closures for injectable drugs face EMA Annex 1 and FDA container closure guidance compliance. Irish and Belgian fill-finish operations drive specification authority for halobutyl and silicone grades with validated extractables profiles.
- Beverages:Wine and spirits producers specify natural rubber or synthetic closures for oxygen transmission control. French and Italian bottling operations prioritize cost efficiency over pharmaceutical-grade certification.
- Chemicals:Laboratory reagent containers and industrial solvent packaging employ EPDM or PVC stoppers for chemical resistance.
- Laboratories:Research-grade closures for cell culture and analytical applications require gamma-sterilizable materials with low cytotoxicity profiles.
Revenue margins peak in Pharmaceuticals; Beverages deliver volume scale through less stringent qualification pathways.
Material:
Polymer selection determines thermal stability, extractables risk, and protein adsorption characteristics that directly influence therapeutic compatibility.
- Natural Rubber:Isoprene-based compounds offer elastic recovery and needle resealability at moderate cost. Traditional vaccine vial applications in India retain this material where platinum-cured silicone remains economically prohibitive.
- Silicone:Platinum-cured grades with sub-ppm extractables dominate biologics packaging for cell and gene therapies. Swiss and German biotech firms specify these for regulatory submissions where leachables documentation determines approval timelines.
- EPDM:Ethylene-propylene-diene monomer compounds resist ozone and steam sterilization for industrial chemical containment.
- PVC:Plasticized polyvinyl chloride serves cost-sensitive beverage and laboratory segments with limited thermal exposure requirements.
Silicone commands the steepest price premium; EPDM and PVC compete on raw material cost in non-regulated applications.
Packaging Type:
Downstream presentation format influences contamination risk, warehouse handling efficiency, and automated line integration requirements.
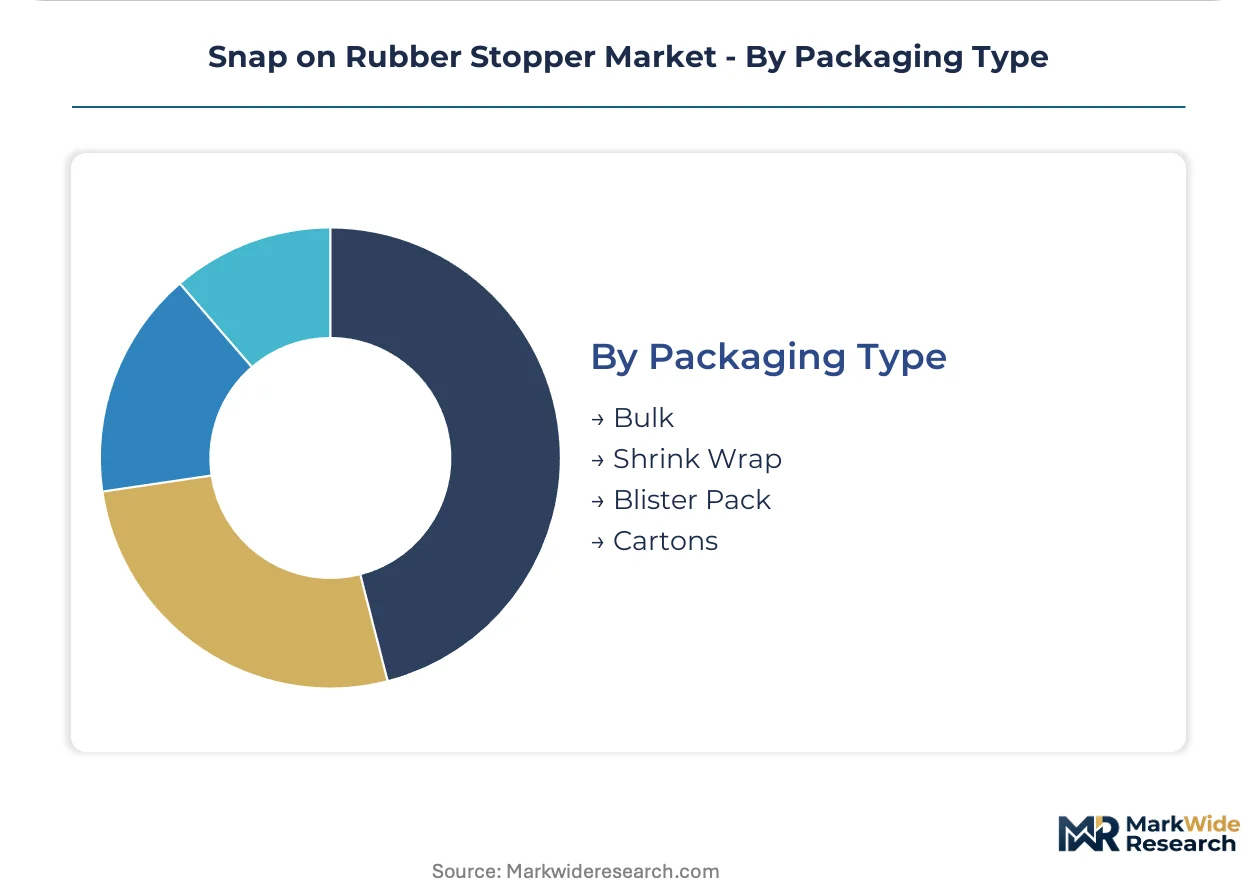
- Bulk:Unwrapped stoppers in fiber drums or polyethylene liners suit high-throughput pharmaceutical lines with in-house washing and siliconization. German contract manufacturers prefer this format for direct feed into isolator-based filling systems.
- Shrink Wrap:Individual or small-batch polymer film wrapping protects against particulate contamination during transport. Swiss cleanroom operations specify this for secondary supplier qualification batches.
- Blister Pack:Thermoformed tray presentations with Tyvek or foil lidding deliver pre-sterilized, ready-to-use closures.
- Cartons:Paperboard secondary packaging supports retail-oriented beverage and laboratory distribution channels.
Bulk shipments dominate pharmaceutical procurement tonnage; Blister Pack formats gain share in single-use bioprocessing applications requiring immediate sterility assurance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German biologics manufacturers and Swiss pharmaceutical packaging specialists concentrate procurement authority for premium elastomer closures, with regulatory validation requirements cascading to supplier qualifications across European fill-finish networks.
Germany
Cell and gene therapy pipelines in Bavaria and Baden-Württemberg multiply vial closure demand per treatment course. EMA Annex 1 revision on sterile manufacturing compresses qualification timelines for elastomer suppliers serving Frankfurt and Munich-based fill-finish operations.
Switzerland
Swissmedic-certified cleanroom production anchors supply security for biologic drug manufacturers in Basel and Zurich. The country's pharmaceutical regulator enforces GMP inspection standards that shape procurement patterns across European monoclonal antibody packaging.
United States
FDA container closure guidance drives extensive extractables and leachables documentation requirements for injectable drug producers. Boston and San Francisco biotech clusters specify platinum-cured silicone grades where leachables profiles determine regulatory submission timelines.
India
CDSCO-aligned import protocols and domestic production incentives under the PLI scheme expand local stopper demand. Contract manufacturers in Maharashtra and Gujarat serving export markets require EMA-quality closures for regulated drug markets.
Japan
PMDA pharmacopeial standards influence elastomer qualification protocols for parenteral packaging. Osaka and Tokyo pharmaceutical clusters maintain strict material certification tiers that fragment procurement across multiple supplier relationships.
Snap on Rubber Stopper Market Competitive Landscape
Capacity expansion dominates the current landscape as compounders invest in cleanroom infrastructure to meet compressed EMA qualification timelines. The vendor base stratifies across three tiers: integrated polymer producers with captive compounding, specialized elastomer fabricators with coating capabilities, and regional molders serving non-regulated applications. Strategic archetypes include vertically integrated pharmaceutical packaging conglomerates, Swiss and German precision compounders with regulatory certification depth, and Asian suppliers leveraging cost-position for generic drug markets. M&A activity and geographic expansion represent the dominant competitive moves as firms acquire analytical capabilities and establish multi-region production footprints.
Among integrated packaging specialists, West Pharmaceutical Services and Gerresheimer AG exemplify the vertically integrated archetype with captive elastomer compounding operations. Datwyler Holding occupies a position within the Swiss precision compounder tier, where Swissmedic-certified production anchors supply relationships with biologics manufacturers. These three firms represent distinct strategic positions: one emphasizing polymer integration, another specialized coating technologies, and the third regulatory-certified cleanroom manufacturing.
| Leading Market Players |
|---|
| West Pharmaceutical Services |
| Datwyler Holding |
| AptarGroup |
| DWK Life Sciences |
| SGD Pharma |
| Daikyo Seiko |
| Gerresheimer AG |
| Schott AG |
| Nipro Corporation |
| Others |
Value Network & Pricing Analysis
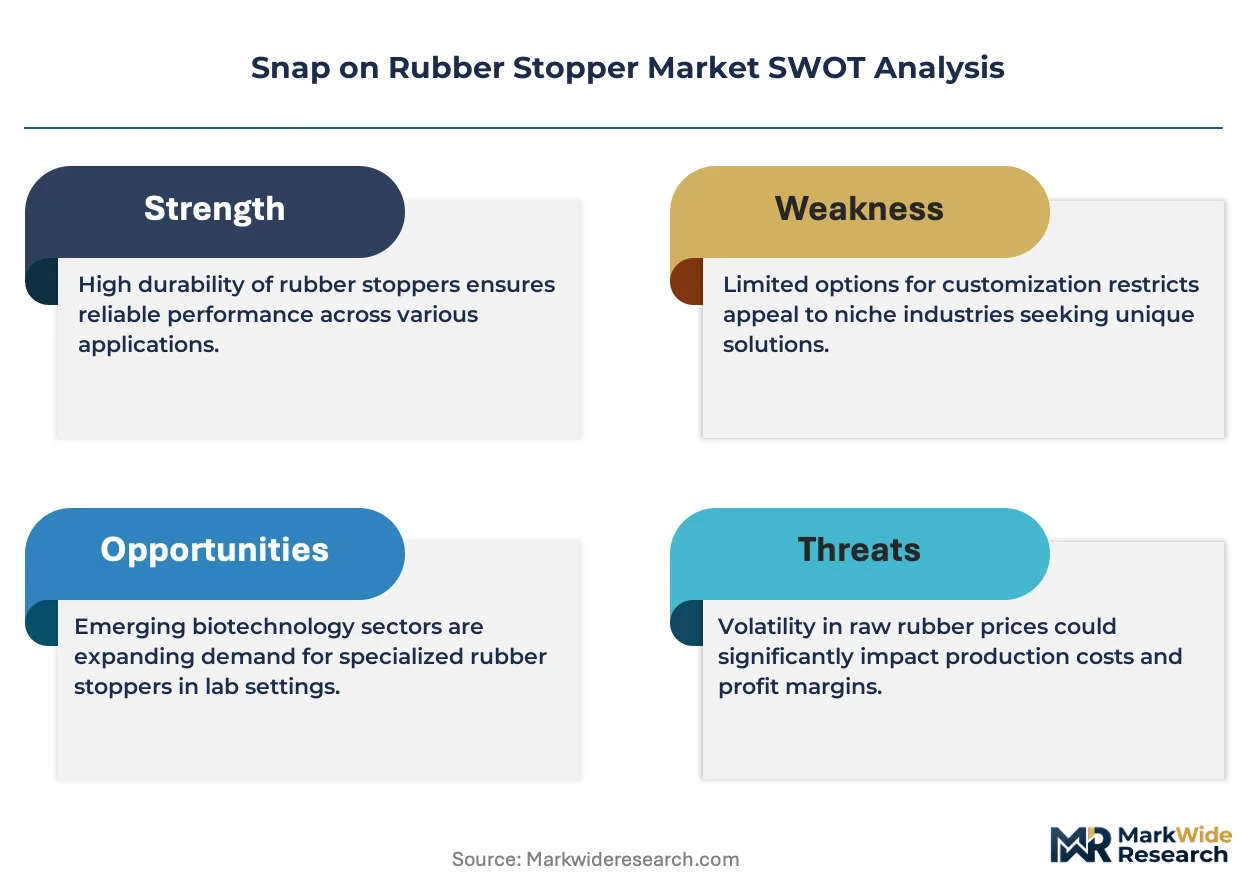
Family-owned mid-cap compounders in Germany and Switzerland anchor supply security through captive cleanroom assets, translating regulatory certification depth into pricing power that commodity molders in Asia cannot replicate. Their ownership structure prioritizes long-dated customer relationships over quarterly margin extraction, stabilizing contract terms even as raw material volatility transmits through bromobutyl rubber feedstock markets.
Pricing Analysis
Volume placements concentrate in standard halobutyl configurations where contract manufacturers prioritize cost efficiency, while platinum-cured silicone grades command substantial premiums in biologics packaging where extractables documentation determines regulatory submission timelines. Pricing stratifies across premium, standard, and economy tiers based on certification grade and sterilization validation burden. Cost compression in the standard tier is intensifying because Indian contract manufacturers serving export markets are consolidating procurement specifications to reduce SKU complexity. Generic drug producers exhibit the highest price sensitivity, whereas cell and gene therapy developers accept premium positioning to secure supply security.
Supply Chain Analysis
Returns and refurbishment flows remain minimal in pharmaceutical-grade closure manufacturing because single-use sterility requirements preclude material recirculation, though industrial chemical packaging permits limited reprocessing of EPDM and PVC stoppers. Bromobutyl rubber feedstock draws from concentrated petrochemical supply in Saudi Arabia, Singapore, and Japan, while silicone monomer production centers on Germany, the United States, and China. Single-source vulnerability in Swissmedic-certified cleanroom capacity creates qualification bottlenecks that extend lead times regardless of compound availability. Distribution runs through direct supplier relationships with fill-finish operations rather than distributor intermediaries, reflecting the technical specification intensity of pharmaceutical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over elastomer compounding determines qualification timelines and margin capture. Players without captive polymer production face persistent share erosion as EMA Annex 1 revisions compress supplier validation windows.
For Market Incumbents: Extend coating technology capabilities to differentiate from commodity molders, integrating fluoropolymer and plasma surface treatments that reduce protein adsorption. Add Swissmedic-certified cleanroom capacity in Basel-adjacent locations to capture dual-sourcing contracts from biologics manufacturers mitigating supply concentration risk. Silicone substitution pressure in premium therapeutic categories threatens halobutyl-dependent revenue streams. For New Entrants and Emerging Players: The mid-tier pricing gap between platinum-cured silicone and standard halobutyl stoppers offers entry space for hybrid elastomer formulations with intermediate extractables profiles. Target biodegradable closure development for European pharmaceutical tenders where EU Green Deal sustainability mandates reshape material selection criteria. Pursue specification influence through early collaboration with polymer chemistry research institutes rather than competing on cost against established compounders. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with EMA quality agreements but constrained analytical infrastructure in Germany and Switzerland, where extractables study capabilities determine competitive viability. Five-to-ten-year viability hinges on successful navigation of REACH chemical restrictions and pharmacopeial harmonization between USP, EP, and JP standards. Monitor CDSCO import protocol alignment and PLI scheme domestic production incentives in India as inflection indicators for geographic demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Certification Investment | Swissmedic and EMA GMP inspections unlock supply relationships with regulated biologics manufacturers. |
| Silicone Compounding Capacity Addition | Platinum-cured grades capture premium positioning in cell and gene therapy packaging segments. |
| Biodegradable Elastomer Development | EU Green Deal procurement mandates create specification influence with sustainability-focused pharmaceutical buyers. |
| Coating Technology Integration | Fluoropolymer surface treatments reduce protein adsorption for monoclonal antibody presentations. |
| Indian Manufacturing Footprint | CDSCO-aligned production serves domestic contract manufacturers and export markets requiring EMA-quality closures. |
Research Methodology
Independent corroboration across regulatory submission databases, cleanroom certification records, and polymer trade flow data underwrites the qualitative findings in this study. Primary interviews with fill-finish operations managers, regulatory affairs directors at biologics manufacturers, elastomer compounding technical leads, and pharmaceutical procurement specialists were combined with secondary validation from EMA inspection reports, FDA container closure guidance documents, USP and EP pharmacopeial standards, and REACH chemical restriction filings. Bottom-up segment sizing and top-down market triangulation were applied across material grades, packaging formats, and application segments.
Comparable historical reference periods anchored the projection horizon, with growth trajectories calibrated against sterilization protocol convergence timelines and biologics pipeline expansion rates. Segmentation dimensions modeled include product type, application sector, material chemistry, and packaging presentation format, alongside regional regulatory cluster differentiation. CAGRs were derived from elasticity-adjusted demand curves and supply-side capacity constraints. Forecast inputs incorporated EMA Annex 1 revision implementation pace and CDSCO import protocol evolution.
Inputs from EMA inspection scheduling databases and Swissmedic certification registries were available through the study window; gaps in real-time bromobutyl rubber inventory data introduce uncertainty bands around near-term pricing assumptions. Forecasts reflect documented assumptions regarding sterilization standard harmonization and sustainability mandate enforcement intensity. Practitioners should monitor REACH restriction list updates and pharmacopeial testing protocol revisions for early signals of qualification burden shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Recycled Elastomers Market
Rubber
Polyisoprene Rubber Market
Rubber
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Rubber
Chloro-Sulfonated Polyethylene Market
Rubber
Plastomers Market
Rubber
Nitrile Butadiene Rubber (NBR) Powder Market
Rubber
Pre-Dispersed Rubber Chemicals Market
Rubber
Silicone Rubber Market
Rubber
Global Medical Rubber Stopper Market
Rubber
Rubber Wear Liners Market
Rubber
Chloroprene Rubber Modified Asphalt Emulsion Market
Rubber
Rubber Foam Market
Rubber
Butyl Reclaimed Rubber Market
Rubber
Global Rubber Vulcanization Market
Rubber
Polybutadiene Elastomers Market
Rubber
Rubber Bulb Seals Market