
 Chloroprene Rubber Tape Market | 2026-2036
Chloroprene Rubber Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Chloroprene Rubber Tape Market Insights
Automotive OEMs is bifurcating from general industrial buyers as the dominant demand archetype for chloroprene rubber tape. Denka Company Limited anchors its position through captive chloroprene monomer supply and precision calendering capabilities for thin-gauge automotive grades. ARLANXEO competes on backward integration into butadiene feedstock and European REACH compliance documentation. Mitsui Chemicals Inc. specializes in halogen-free formulations targeting EV battery pack sealing applications in Japan and Southeast Asia.
Chloroprene rubber tape consists of polychloroprene elastomer coated onto woven or non-woven substrates, typically calendered to thicknesses between 0.1 mm and 3.0 mm with pressure-sensitive or heat-activated adhesive layers. The material delivers oil resistance, flame retardancy, and dimensional stability across temperatures from minus 35 degrees Celsius to 130 degrees Celsius, serving primarily as sealing, cushioning, and insulation interfaces in industrial assemblies. Specialty tape formats command margin premiums due to custom die-cutting requirements and cleanroom-grade surface specifications for electronics cleanrooms. Single-sided tape dominates volume shipments into automotive weatherstripping and construction membrane sealing, while double-sided tape is expanding fastest in electronics display lamination where optical clarity and outgassing control matter.
China's SAMR enforces GB standards limiting volatile organic compound emissions from adhesive tapes used in indoor construction and automotive interiors. Japan's METI maintains JIS standards for chloroprene product labeling and fire safety classification in building applications. The EU REACH regulation and RoHS directive restrict specific phthalate plasticizers and heavy metal stabilizers in tapes entering European electronics and medical device supply chains. Stakeholders must monitor regulatory divergence between Asian and European chemical compliance regimes when configuring regional product formulations and certification portfolios.
Market Dynamics
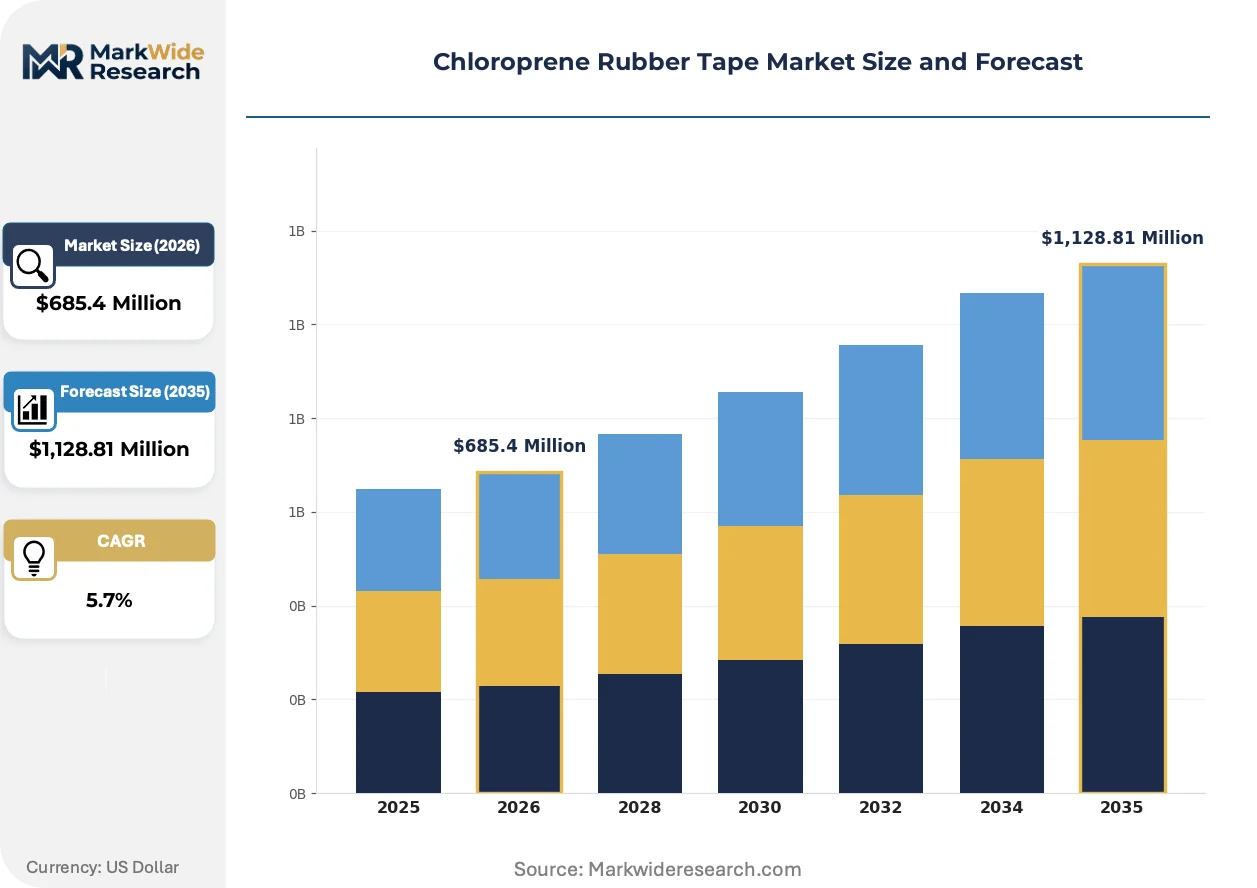
Automotive electrification is restructuring chloroprene rubber tape demand toward battery-grade specifications, while China's tightening GB standards on volatile organic compounds force simultaneous reformulation across construction and electronics supply chains.
Growth Catalysts
- EV Battery Sealing Mandates:Automakers specify chloroprene tape for thermal interface management and pack sealing as lithium-ion energy density rises. This pulls specialty thin-gauge grades into OEM qualification pipelines faster than general industrial applications.
- China's Dual Carbon Goals:MEE enforcement of carbon intensity benchmarks accelerates domestic substitution of solvent-based acrylic tapes with waterborne chloroprene systems in Shanghai manufacturing clusters.
- REACH Documentation Requirements:European electronics assemblers demand full material disclosure for RoHS compliance, privileging suppliers with certified supply chain traceability over commodity competitors.
Market Restraints
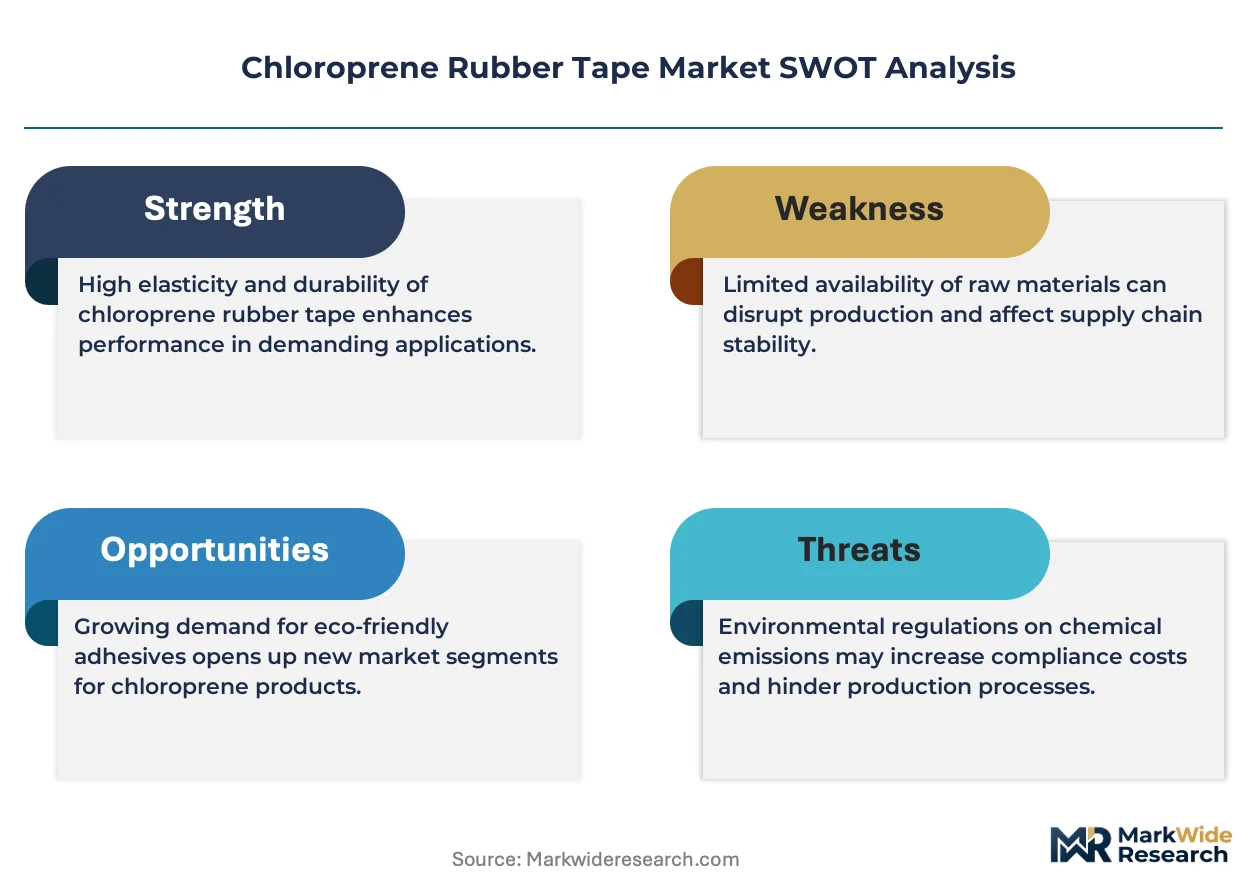
- Chloroprene Monomer Supply Concentration:Three Japanese and Chinese producers control over 80% of global monomer output, exposing tape manufacturers to force majeure pricing volatility.
- Phthalate Plasticizer Restrictions:EU REACH Annex XVII and evolving GB standards ban specific plasticizers still embedded in legacy adhesive formulations, requiring costly reformulation.
- Silicone Substitution in High-Temperature Zones:Automotive underhood applications above 130 degrees Celsius increasingly specify silicone foam tapes, capping chloroprene's addressable thermal range.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme subsidies for mobile phone and component assembly create first-mover advantage for tape suppliers establishing local slitting and die-cutting operations.
- Halogen-Free Formulation Premiums:METI guidance on flame-retardant material disclosure in Japanese building applications rewards suppliers with pre-certified low-smoke formulations.
- Direct OEM Contracting:Bypassing traditional distribution, tape specialists secure multi-year supply agreements with EV battery pack integrators in Jiangsu province, locking in volume commitments.
Industry Challenges
- Cleanroom Certification Timelines:Electronics customers require ISO 14644-1 Class 7 or better manufacturing validation, extending qualification cycles by 12-18 months for new entrants.
- Adhesive Polymer Synthesis Expertise Gap:Formulation chemistry talent concentrates at legacy Japanese and German producers, constraining independent tape manufacturers' R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chloroprene Rubber Tape Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,128.81 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided Tape, Double-Sided Tape, Specialty Tape, Foam Tape End User: Automotive, Electronics, Construction, Medical Thickness: Thin, Medium, Thick, Extra Thick Adhesive Type: Pressure Sensitive, Heat Activated, Water Activated, Others |
| Companies Covered | ARLANXEO, Sinopec Group, Denka Company Limited, Mitsui Chemicals Inc., SABIC, Lanxess AG, Asahi Kasei Chemicals Corporation, Avery Dennison Corporation, Showa Denko K.K., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chloroprene Rubber Tape Market Trends and Innovations
Waterborne adhesive systems and precision calendering automation are compressing cost structures for thin-gauge automotive grades, while regulatory disclosure mandates transform supplier qualification from transactional to audit-intensive.
Waterborne polychloroprene dispersions are displacing solvent-based coating lines in East Asian tape manufacturing. Automotive OEMs in Japan and South Korea now specify aqueous systems for interior applications to meet cabin air quality targets. This shift compresses capital requirements for new coating capacity while raising energy costs for drying operations.
EU REACH substance of very high concern listings now cover additional chlorinated flame retardants used in tape backings. Electronics exporters to Europe must resubmit technical files with updated safety data sheets. German automotive suppliers have responded by consolidating purchase orders with REACH-registered manufacturers possessing in-house regulatory affairs teams.
Consolidated vendor lists are concentrating procurement leverage among tier-one automotive and electronics assemblers. Tape buyers now require quarterly carbon footprint disclosures alongside price quotes. This behavioral shift is most visible in Jiangsu and Zhejiang province supply chains, where battery pack integrators maintain approved supplier lists below ten qualified sources per material category.
Chloroprene Rubber Tape Market Segmentation
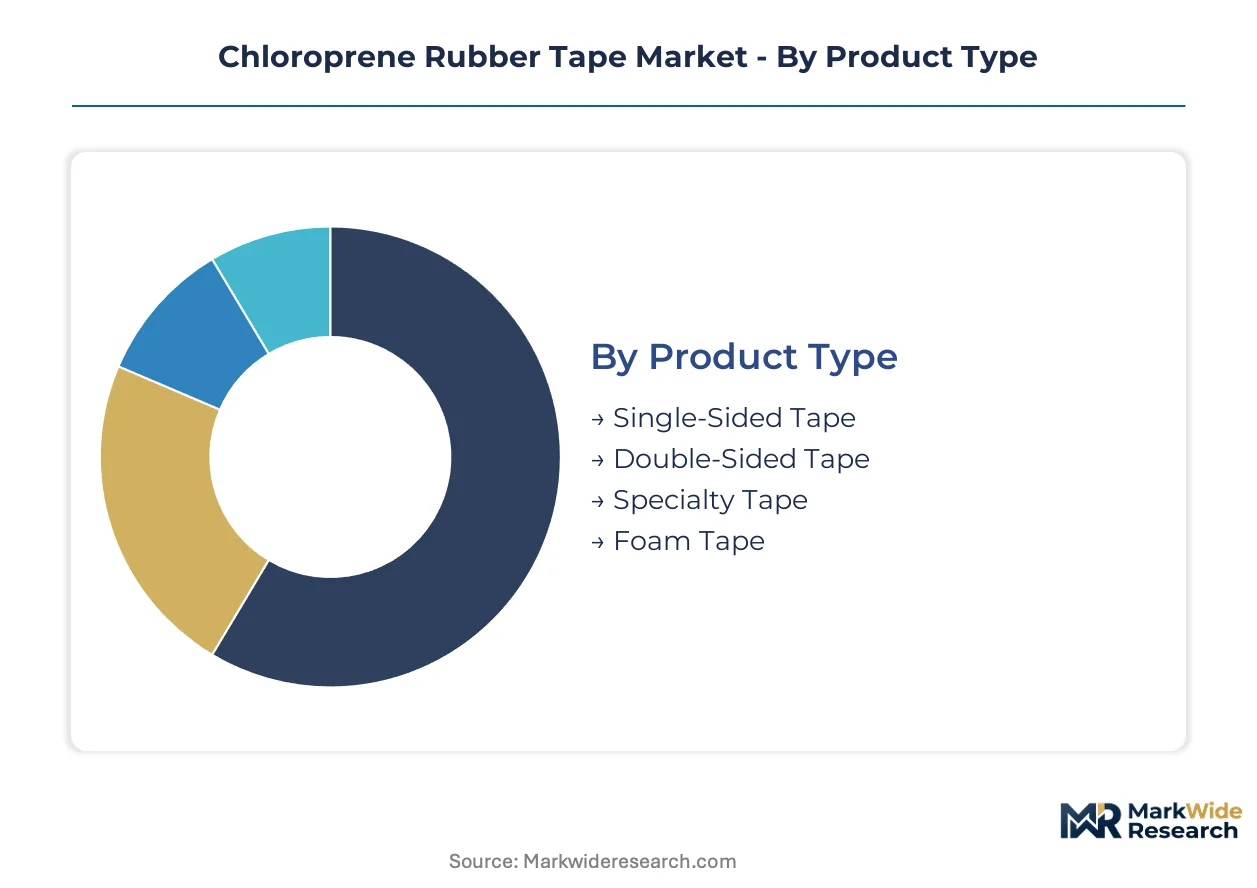
Segmentation in chloroprene rubber tape reveals how margin pools concentrate in specialty grades serving EV battery sealing and electronics cleanroom applications. Manufacturers configure coating lines and adhesive synthesis capacity around these high-specification niches while commoditized construction grades compete on throughput scale.
Product Type:
Margin concentration sits in specialty and double-sided formats where custom die-cutting and cleanroom certification create defendable pricing power.
- Single-Sided Tape:Polychloroprene elastomer coated on one substrate face, typically calendered to 0.5-2.0 mm for automotive weatherstripping and construction membrane sealing. Demand concentrates in East China manufacturing clusters where petrochemical feedstock access supports high-volume coating operations serving domestic construction growth.
- Double-Sided Tape:Adhesive layers on both faces with carrier substrates, engineered for optical clarity and outgassing control in electronics display lamination. Japanese and South Korean electronics assemblers specify aqueous chloroprene systems for interior cabin air quality compliance, pulling thin-gauge grades into OEM qualification pipelines faster than general industrial applications.
- Specialty Tape:Custom die-cut formats with cleanroom-grade surface specifications for semiconductor and medical device assembly.
- Foam Tape:Cellular chloroprene structures providing compression sealing and vibration damping in HVAC and appliance gasketing.
Single-sided tape holds installed capacity. Double-sided tape is rotating up the share rankings.
End User:
Application concentration determines adhesive formulation chemistry and certification burden across customer segments.
- Automotive:OEM specifications for battery pack thermal interface management and sealing as lithium-ion energy density rises. China's NMPA and evolving GB standards on chemical emissions force simultaneous reformulation across interior and underhood applications.
- Electronics:Display lamination, semiconductor packaging, and cleanroom assembly requiring ISO 14644-1 Class 7 or better manufacturing validation. EU REACH documentation requirements privilege suppliers with certified supply chain traceability over commodity competitors in European electronics export supply chains.
- Construction:Membrane sealing and weatherproofing applications governed by China's SAMR enforcement of GB standards limiting volatile organic compound emissions from adhesive tapes.
- Medical:Device assembly and wound care applications requiring biocompatibility testing and sterilization stability.
Automotive commands qualification timelines. Electronics is climbing the fastest on specification premiums.
Thickness:
Calendering precision and substrate handling economics stratify manufacturing investment across gauge categories.
- Thin:Below 0.3 mm for electronics flex circuit bonding and battery cell stacking. Precision calendering automation compresses cost structures for these grades in Japanese and German producer facilities.
- Medium:0.3-1.0 mm general industrial grades serving appliance and HVAC gasketing with balanced material efficiency and handling characteristics.
- Thick:1.0-2.5 mm for construction membrane sealing and heavy-duty cushioning where compression set resistance matters.
- Extra Thick:Above 2.5 mm for specialized vibration isolation and gap-filling in industrial machinery mounts.
Medium gauge dominates volume throughput. Thin grades are expanding most quickly on EV battery demand.
Adhesive Type:
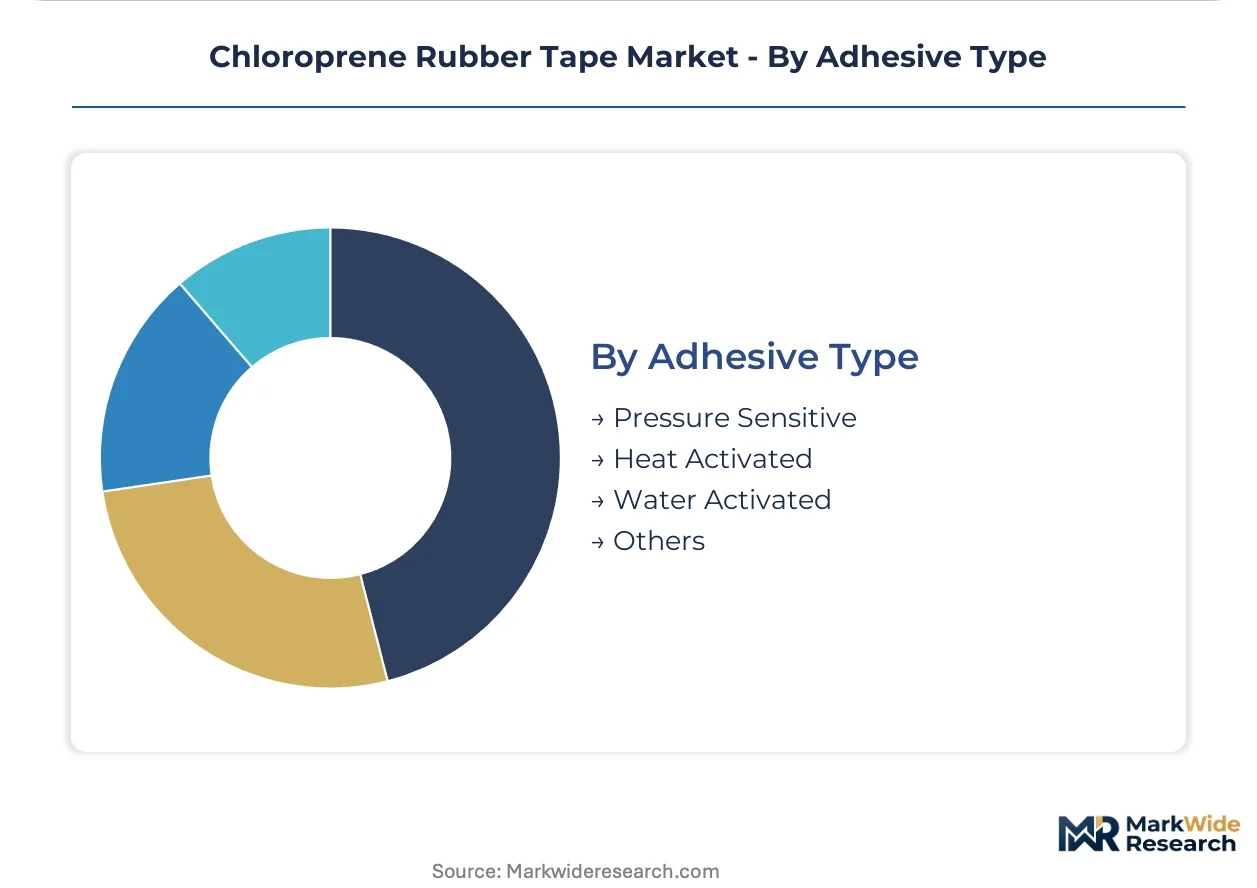
Coating chemistry selection determines capital intensity, environmental compliance, and end-use qualification pathways.
- Pressure Sensitive:Tackified polychloroprene formulations enabling immediate bond formation without activation energy. Automotive OEMs in Japan specify these systems for interior trim attachment to meet cabin air quality targets under METI guidance.
- Heat Activated:Latent adhesive requiring thermal energy to develop full bond strength, specified for structural applications where repositioning window and permanent load-bearing capacity are required.
- Water Activated:Repulpable or moisture-curing systems for paperboard and temporary holding applications in packaging and printing.
- Others:Solvent-activated and dual-cure formulations for specialized industrial bonding scenarios.
Pressure sensitive maintains formulation diversity. Heat activated is gaining share fastest on automotive structural bonding specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese chloroprene monomer producers supply tape manufacturers across South Korea and China, creating a tightly integrated East Asian supply corridor that dominates global trade flows in specialty adhesive grades.
China
EV battery pack integrators in Jiangsu province drive specialty thin-gauge tape demand as lithium-ion energy density rises. SAMR enforces GB standards limiting volatile organic compound emissions from adhesive tapes in automotive interiors and construction applications. Shanghai manufacturing clusters concentrate waterborne chloroprene coating capacity serving domestic electronics assemblers.
Japan
Automotive OEMs specify aqueous chloroprene systems for interior trim attachment to meet cabin air quality targets. METI maintains JIS standards for chloroprene product labeling and fire safety classification in building applications. Nagoya industrial corridor hosts precision calendering facilities supplying halogen-free formulations to Southeast Asian battery manufacturers.
Germany
REACH documentation requirements privilege suppliers with certified supply chain traceability in European electronics export supply chains. ECHA substance of very high concern listings cover additional chlorinated flame retardants used in tape backings. Bavarian automotive suppliers consolidate purchase orders with REACH-registered manufacturers possessing in-house regulatory affairs teams.
United States
NHTSA safety standards and EPA emission regulations shape adhesive tape specifications for automotive and industrial applications. Midwest manufacturing centers import specialty chloroprene grades for HVAC and appliance gasketing. California's air quality mandates accelerate solvent-to-waterborne system transitions among West Coast tape converters.
South Korea
Electronics display manufacturers specify double-sided chloroprene tape for optical clarity and outgassing control in panel lamination. MFDS chemical safety guidelines influence adhesive formulation disclosure requirements. Gyeonggi-do province clusters semiconductor packaging operations demanding ISO 14644-1 Class 7 cleanroom-certified tape supply.
Chloroprene Rubber Tape Market Competitive Landscape
Player mix skews toward integrated petrochemical conglomerates with captive monomer supply and specialized adhesive compounders serving qualification-intensive end-use segments. Japanese and German producers dominate thin-gauge automotive and electronics grades through precision calendering expertise. Two strategic archetypes prevail: backward-integrated monomer producers leveraging feedstock control, and formulation specialists competing on regulatory certification speed. Competitive moves center on REACH registration completion for European market access and direct OEM contracting to bypass distribution layers.
Within the integrated chemical conglomerate tier, Denka Company Limited and Mitsui Chemicals Inc. exemplify producers with in-house chloroprene monomer capabilities. Denka anchors Japanese supply chains through precision calendering operations. Mitsui occupies a position in halogen-free formulation development for battery applications. ARLANXEO represents European-based competition with butadiene feedstock integration and REACH compliance documentation strength. These three companies illustrate how geographic and supply-chain positioning stratify competitive access to premium-grade market segments.
| Leading Market Players |
|---|
| ARLANXEO |
| Sinopec Group |
| Denka Company Limited |
| Mitsui Chemicals Inc. |
| SABIC |
| Lanxess AG |
| Asahi Kasei Chemicals Corporation |
| Avery Dennison Corporation |
| Showa Denko K.K. |
| Others |
Pricing and Supply Chain Analysis
Calendering capacity utilization above eighty percent in Japanese and German producer facilities creates asymmetric pricing power for thin-gauge automotive and electronics grades. This scale concentration elevates price floors for specialty formats while commoditized construction tapes compete on throughput margins in East China clusters.
Pricing Analysis
Solvent-based legacy formulations trade at discount to waterborne next-generation systems specified by Japanese and South Korean automotive OEMs. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered specialty grades from general industrial commodities. Cost compression in standard grades is intensifying because Chinese domestic producers expand waterborne coating capacity. Construction membrane buyers exhibit highest price sensitivity; EV battery pack integrators accept premium positioning for halogen-free certified supply.
Supply Chain Analysis
Chloroprene monomer production chokepoint at three Japanese and Chinese producers exposes tape manufacturers to force majeure disruption. Manufacturing draws from Japan, China, and Germany for calendering and coating operations. Feedstock rests on butadiene and chlorine derivatives subject to energy price volatility. Distribution runs through approved supplier lists maintained by tier-one automotive and electronics assemblers with consolidated vendor bases below ten qualified sources per material category.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise concentrates at legacy Japanese and German producers, constraining independent tape manufacturers' R&D velocity and creating defendable moats for incumbents with in-house adhesive synthesis capabilities.
For Market Incumbents: Shield margin position in specialty thin-gauge grades by completing REACH registration for European electronics export access before competitors. Accelerate backward integration into waterborne polychloroprene dispersions to offset solvent-based system phase-out under China's GB standards. Denka and Mitsui's captive monomer supply demonstrates how feedstock control defends pricing power against commodity entrants. For New Entrants and Emerging Players: Regulatory certification speed gaps in Indian electronics manufacturing present white-space opportunity for tape suppliers establishing local slitting and die-cutting operations under PLI scheme subsidies. Target semiconductor packaging applications in Gyeonggi-do province where ISO 14644-1 Class 7 cleanroom validation requirements extend qualification cycles for established competitors. Lead with direct OEM contracting to bypass distribution layers and secure multi-year volume commitments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation specialists with pre-certified halogen-free portfolios over commodity coating operations. Five-to-ten year viability hinges on waterborne system transition completion and EV battery pack sealing specification capture. Watch for consolidation signals when REACH documentation burdens force smaller European compounders toward strategic exit.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chloroprene Monomer | Captive supply from Denka and Chinese producers insulates margin from feedstock volatility. |
| REACH Registration Completion | ECHA compliance documentation opens European electronics and medical device supply chains. |
| Waterborne Coating Capacity Expansion | Shanghai manufacturing clusters pivot from solvent systems under SAMR GB standard enforcement. |
| Direct OEM Contracting | Jiangsu battery pack integrators consolidate procurement leverage through approved supplier lists. |
| Cleanroom Certification Investment | ISO 14644-1 Class 7 validation qualifies supply for South Korean semiconductor packaging demand. |
Research Methodology
A standing panel of tape manufacturing plant managers, automotive OEM procurement leads, electronics assembly engineers, and distribution channel partners provided ongoing calibration against secondary validation. Primary fieldwork combined with customs trade data, SEC 10-K filings from listed chemical conglomerates, ACC and Cefic industry reports, and GB standard documentation from SAMR enabled bottom-up and top-down triangulation across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, end-use industry, thickness gauge, and adhesive chemistry segmentation. CAGRs were derived from modeled annual progression rates applied to base-year sizing. Forecast inputs incorporated EV battery pack production trajectories, waterborne system adoption curves, and regulatory phase-in schedules for REACH and GB standard compliance.
Forecasts assume regulatory continuity in EU REACH, China GB standards, and Japan METI guidance; material policy shifts would require re-modeling. Chloroprene monomer supply disruption, silicone substitution acceleration, or cleanroom certification timeline compression represent specific risk factors. Practitioners should keep alternative scenarios live as automotive electrification specifications and dual carbon enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Flooring Market
Rubber
Rubber Ropes Market
Rubber
Rubber Carbon Black Market
Rubber
Global Cast Elastomers Market
Rubber
Synthetic Polyisoprene Rubber Market
Rubber
Tire Reinforcement Materials Market
Rubber
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Rubber
Rubber Plated Hose Market
Rubber
Polybutadiene Elastomers Market
Rubber
Polyisoprene Market
Rubber
Conductive Silicone Rubber Market
Rubber
Rubber Splicing Tape Market
Rubber
Polybutadiene Market
Rubber
Tire Chemicals Market
Rubber
Nitrile Butadiene Rubber (NBR) Latex Market
Rubber
Silicone Rubber Market