
 Liquid Polybutadiene Market | 2026-2036
Liquid Polybutadiene Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Polybutadiene Market Analysis
High-vinyl grade specifications is rotating toward center stage as compounders seek enhanced abrasion resistance and wet-grip performance in tire treads. Kraton Corporation leverages its integrated hydrogenation technology to sustain premium positioning in specialty elastomer grades. LG Chem anchors Asian supply through large-scale solution polymerization capacity at its Yeosu complex. Evonik Industries AG differentiates via functionalized liquid rubber variants targeting adhesives and sealant formulators.
Liquid polybutadiene denotes low-molecular-weight polybutadiene oligomers, typically manufactured through anionic or free-radical polymerization of 1,3-butadiene monomer to yield viscous fluids with molecular weights ranging from 1,000 to 10,000 g/mol and vinyl contents between 10% and 90%; these materials function primarily as reactive plasticizers, toughening agents, and crosslinkable modifiers in thermoset and thermoplastic formulations. The liquid rubber segment occupies mature volume pools in tire manufacturing and industrial belting, while styrenic block copolymers command margin concentration in medical packaging and consumer goods applications. Thermoplastic elastomers represent the fastest-growing product category as footwear producers substitute conventional vulcanized rubber with injection-moldable alternatives.
The EPA regulates hazardous air pollutant emissions from synthetic rubber production under Maximum Achievable Control Technology standards, compelling U.S. manufacturers to invest in closed-loop reactor systems and solvent recovery infrastructure. REACH registration requirements in Europe mandate full toxicological dossiers for liquid polybutadiene imports above one tonne annually, creating compliance barriers for non-EU suppliers. China's MEE enforces increasingly stringent volatile organic compound limits on coatings and adhesives containing petroleum-derived additives. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation tailoring or unified product platforms offer superior returns.
Market Dynamics
REACH compliance deadlines and EPA Maximum Achievable Control Technology standards are compressing formulation windows for liquid polybutadiene suppliers, forcing simultaneous retooling of hydrogenation infrastructure and solvent recovery systems across multiple continents.
Growth Catalysts
- Low-rolling-resistance tire mandates:China's MIIT fuel-efficiency standards and the EU's CO2 emission limits for vehicles are compelling tire manufacturers to reformulate tread compounds with high-vinyl liquid polybutadiene binders.
- MEE volatile organic compound enforcement:China's Ministry of Ecology and Environment is tightening limits on petroleum-derived additives in coatings and adhesives, accelerating substitution toward reactive liquid rubber modifiers.
- Thermoplastic elastomer substitution:Footwear producers in Vietnam and Indonesia are displacing conventional vulcanized rubber with injection-moldable liquid polybutadiene-modified compounds to reduce cycle times.
Market Restraints
- Butadiene feedstock volatility:Crude oil price swings and naphtha cracking economics create margin compression for anionic polymerization producers dependent on spot monomer purchases.
- Solution polymerization concentration:Large-scale capacity clusters in South Korea and eastern China create geographic supply vulnerability to regional logistics disruptions or trade policy shifts.
- Functionalization complexity:Graft chemistry limitations for maleic anhydride and silane modifications restrict adhesion performance in high-temperature sealant applications.
Strategic Opportunities
- India automotive compounding:Domestic tire production expansion under the PLI scheme creates unmet demand for high-vinyl liquid rubber grades currently imported from Southeast Asia.
- EV battery thermal management:Liquid polybutadiene-modified potting compounds are penetrating electric vehicle battery module assemblies as flame-retardant encapsulants.
- ISO 14001-driven supplier qualification:Environmental management system certification is becoming a gatekeeping requirement for European automotive Tier-1 procurement, favoring integrated hydrogenation capabilities.
Industry Challenges
- Anionic polymerization expertise scarcity:The specialized knowledge required for living polymerization control and molecular weight targeting is concentrated among retiring technical workforces in Japan and Germany.
- REACH dossier compilation timelines:Full toxicological registration for liquid polybutadiene imports above one tonne annually requires 18-24 month preparation cycles, delaying market entry for new suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Polybutadiene Market |
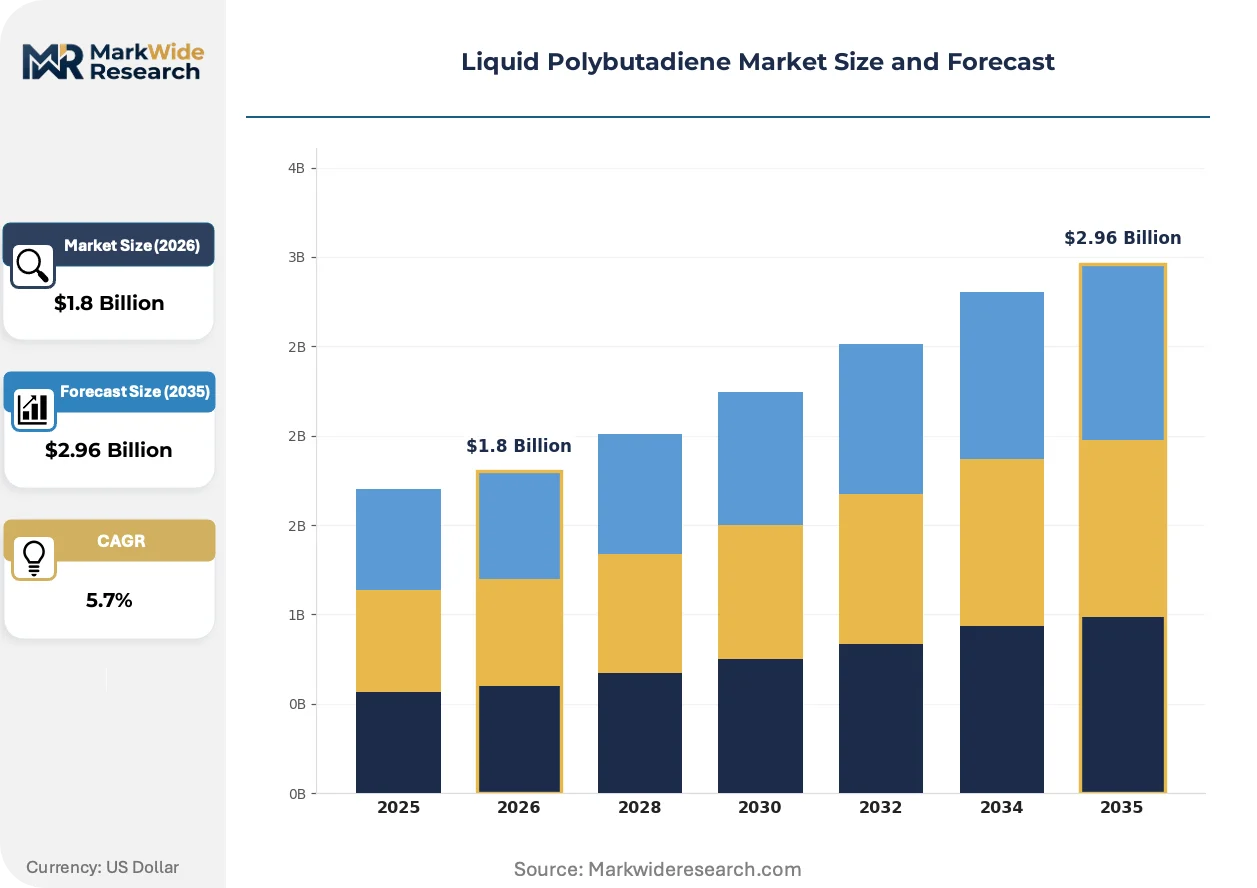
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Styrenic Block Copolymers, Liquid Rubber, Thermoplastic Elastomers, Additives End Use Industry: Automotive, Coatings, Adhesives, Construction Application: Sealants, Tires, Footwear, Paints Distribution Channel: Direct Sales, Online Retailers, Distributors, Dealers |
| Companies Covered | Kraton Corporation, LG Chem, Asahi Kasei Corporation, SABIC, Mitsui Chemicals, Evonik Industries AG, TSRC Corporation, Synthomer plc, Idemitsu Kosan Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Polybutadiene Market Emerging Trajectories
Reactive plasticizer technology is converging with advanced hydrogenation methods to create differentiated performance tiers, while regulatory fragmentation across major economies is forcing parallel formulation development tracks.
Continuous flow reactor designs for anionic polymerization are miniaturizing production footprints and enabling distributed manufacturing closer to tire compounding clusters. Korean petrochemical groups are piloting these systems at Yeosu and Ulsan to reduce logistics costs for just-in-time rubber deliveries. The technology is compressing capital requirements for mid-scale entrants while maintaining molecular weight distribution control.
REACH authorization requirements for Substances of Very High Concern are extending to residual solvent traces in liquid rubber imports, compelling non-EU suppliers to invest in supercritical CO2 stripping or membrane separation. German automotive OEMs are now requiring SVHC-free certifications for all rubber additives in underhood applications. Suppliers without closed-loop solvent recovery are exiting the European medical packaging segment entirely.
Compounders are consolidating supplier relationships around integrated hydrogenation capabilities rather than sourcing commodity grades for downstream modification. Korean tire manufacturers are qualifying single-source partnerships for both high-vinyl liquid polybutadiene and the hydrogenated derivatives used in dynamic vulcanizates. This behavior concentrates procurement volumes with producers possessing captive catalytic hydrogenation assets, marginalizing toll-modification intermediaries in the supply chain.
Liquid Polybutadiene Market Segmentation
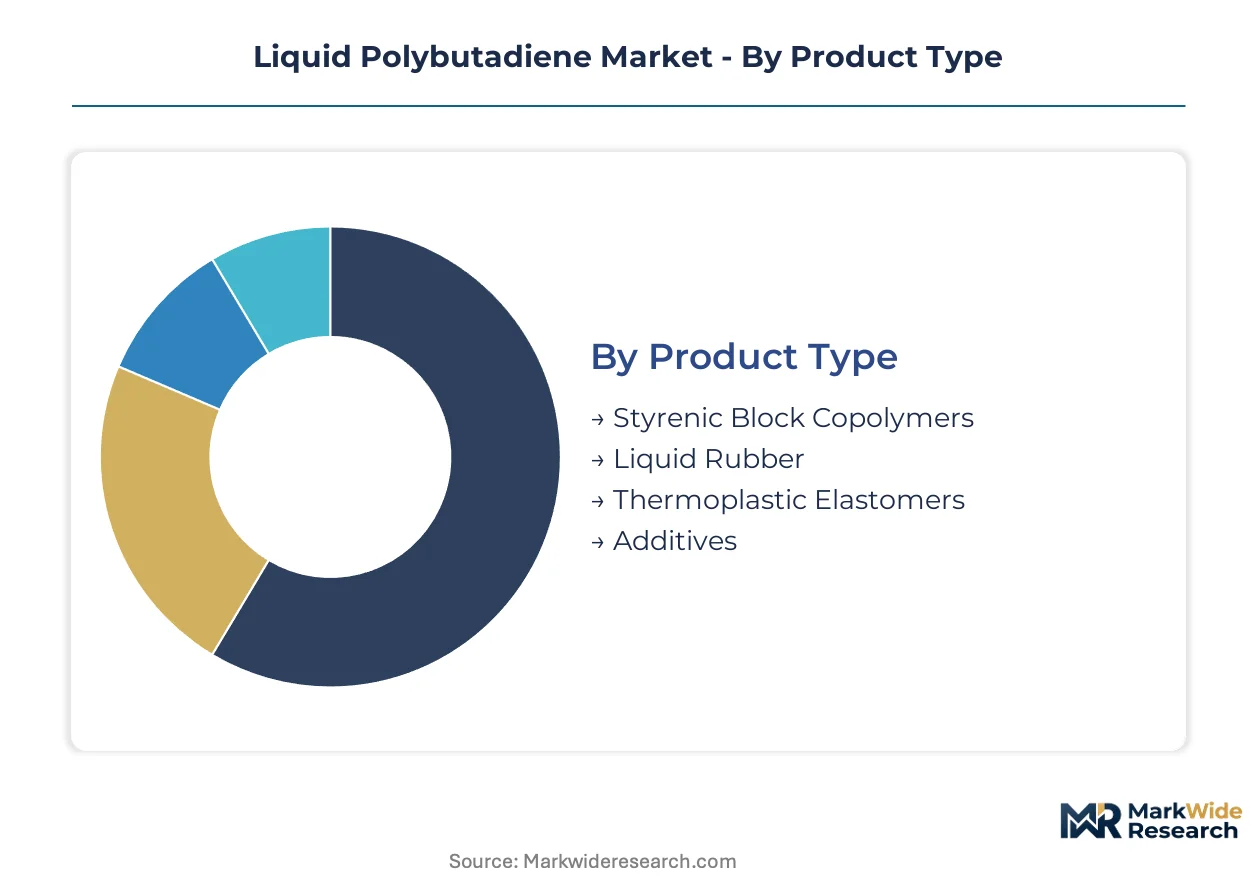
Segmentation in liquid polybutadiene markets reflects divergent technical specifications across tire compounding, adhesive formulation, and thermoplastic modification. Each category carries distinct regulatory footprints and margin structures that shape supplier positioning.
Product Type:
REACH authorization timelines and EPA Maximum Achievable Control Technology standards create divergent compliance burdens across hydrogenation grades and molecular weight specifications.
- Liquid Rubber:Low-molecular-weight oligomers with 1,000-10,000 g/mol specifications serve as reactive plasticizers in tire tread compounds. Demand concentrates in Chinese tire manufacturing clusters where MIIT fuel-efficiency standards mandate low-rolling-resistance formulations.
- Thermoplastic Elastomers:Injection-moldable compounds displace conventional vulcanized rubber in Vietnamese and Indonesian footwear production, compressing cycle times while meeting MEE volatile organic compound limits.
- Styrenic Block Copolymers:Medical packaging applications require SVHC-free certifications under REACH Substances of Very High Concern protocols.
- Additives:Functionalized variants for adhesives and sealants face graft chemistry limitations in high-temperature applications.
Liquid rubber handles the majority of throughput; thermoplastic elastomers are expanding most quickly on share.
End Use Industry:
Cost tier differentiation separates commodity volume plays from specialty margin capture across automotive and industrial applications.
- Automotive:Tire manufacturers in China and South Korea consume high-vinyl grades for tread compounds while EV battery producers adopt liquid polybutadiene-modified potting compounds for thermal management.
- Coatings:Infrastructure consumption in China anchors regional offtake under tightening MEE volatile organic compound enforcement.
- Adhesives:Formulators seek functionalized variants for improved adhesion performance in construction and industrial assembly.
- Construction:Sealant applications require maleic anhydride and silane modifications constrained by graft chemistry complexity.
Automotive absorbs the dominant share of volume; coatings is climbing the fastest as infrastructure investment accelerates.
Application:
Volume concentration in tire manufacturing contrasts with emerging penetration in battery encapsulation and specialty footwear.
- Tires:Low-rolling-resistance mandates from China's MIIT and EU CO2 emission limits compel reformulation with high-vinyl liquid polybutadiene binders. Korean manufacturers qualify single-source partnerships for both base grades and hydrogenated derivatives.
- Footwear:Vietnamese and Indonesian producers substitute vulcanized rubber with injection-moldable compounds to reduce cycle times and meet export market specifications.
- Sealants:High-temperature applications face performance constraints from functionalization complexity in maleic anhydride grafting.
- Paints:Coatings formulators respond to MEE volatile organic compound limits by shifting toward reactive liquid rubber modifiers.
Tires command the largest volume position; footwear is gaining share fastest on substitution dynamics.
Distribution Channel:
Customer type stratification separates just-in-time tire compounders from batch-oriented adhesive formulators with divergent logistics requirements.
- Direct Sales:Korean tire manufacturers establish single-source partnerships with integrated hydrogenation producers for captive supply security.
- Distributors:Regional chemical distributors serve mid-scale adhesive and sealant formulators requiring technical support and smaller lot sizes.
- Dealers:Local dealers handle construction segment deliveries with varying specification requirements across project sites.
- Online Retailers:Digital channels penetrate small-batch specialty applications with standardized grade offerings.
Direct sales manages the bulk of contract volume; distributors are expanding most rapidly as mid-tier compounders proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale solution polymerization capacity clusters in South Korea and eastern China dominate liquid polybutadiene supply, while regulatory divergence between EPA, REACH, and MEE standards forces parallel formulation development across manufacturing locations.
China
Domestic automotive production and infrastructure coatings consumption anchor regional offtake, with tire manufacturers in Shandong and Jiangsu provinces expanding low-rolling-resistance formulations. MEE volatile organic compound enforcement tightens limits on petroleum-derived additives in coatings and adhesives, accelerating substitution toward reactive liquid rubber modifiers. The Yangtze River Delta chemical corridor hosts concentrated compounding capacity serving both domestic OEMs and export markets.
South Korea
Korean tire manufacturers qualify single-source partnerships for high-vinyl liquid polybutadiene and hydrogenated derivatives used in dynamic vulcanizates. The Yeosu and Ulsan industrial complexes anchor Asian supply through integrated solution polymerization and hydrogenation infrastructure. Continuous flow reactor pilots at these locations compress capital requirements while maintaining molecular weight distribution control for just-in-time rubber deliveries.
United States
EPA Maximum Achievable Control Technology standards compel investment in closed-loop reactor systems and solvent recovery infrastructure for synthetic rubber production. Domestic tire producers reformulate tread compounds to balance abrasion resistance with fuel-efficiency targets set by NHTSA. The Gulf Coast petrochemical corridor provides butadiene feedstock access, though spot monomer purchase economics create margin compression for anionic polymerization producers.
Germany
REACH registration requirements mandate full toxicological dossiers for liquid polybutadiene imports above one tonne annually, creating compliance barriers for non-EU suppliers. German automotive OEMs now require SVHC-free certifications for all rubber additives in underhood applications. The Ruhr industrial region hosts specialty elastomer modification facilities serving medical packaging and consumer goods segments with stringent purity specifications.
India
Domestic tire production expansion under the PLI scheme creates unmet demand for high-vinyl liquid rubber grades currently imported from Southeast Asia. BIS standards for automotive rubber components are converging with global fuel-efficiency benchmarks, requiring reformulation expertise concentrated among technical workforces in Maharashtra and Gujarat. The Chennai-Bangalore industrial corridor attracts compounders seeking to localize supply chains for export-oriented footwear and automotive Tier-1 customers.
Liquid Polybutadiene Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated hydrogenation capabilities separating premium-grade suppliers from commodity volume producers. The market structure concentrates procurement volumes with producers possessing captive catalytic assets, marginalizing toll-modification intermediaries. Three archetypes dominate: Korean petrochemical groups with scale polymerization, European specialty chemical houses with functionalization expertise, and Japanese technical rubber specialists with legacy anionic polymerization knowledge. Competitive moves center on single-source partnership qualification for automotive Tier-1 procurement and supercritical CO2 stripping investments for REACH SVHC compliance.
Among the named suppliers, Kraton Corporation and LG Chem exemplify divergent scale-versus-specialization positioning, while Evonik Industries AG represents the functionalized variant archetype targeting adhesives and sealant formulators. Kraton occupies a position within the integrated hydrogenation tier, LG Chem anchors large-scale solution polymerization capacity, and Evonik sits within the specialty chemicals segment emphasizing technical service and application development. These three illustrate how supplier consolidation around environmental management system certification and closed-loop solvent recovery is reshaping viable competitive positions in European and North American procurement channels.
| Leading Market Players |
|---|
| Kraton Corporation |
| LG Chem |
| Asahi Kasei Corporation |
| SABIC |
| Mitsui Chemicals |
| Evonik Industries AG |
| TSRC Corporation |
| Synthomer plc |
| Idemitsu Kosan Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
ISO 14001 environmental management system certification gates both supplier qualification and price differentiation in liquid polybutadiene procurement, concentrating pricing power with integrated hydrogenation producers while marginalizing toll-modification intermediaries unable to absorb compliance costs.
Pricing Analysis
REACH Substances of Very High Concern authorization dictates the pricing tier structure across the European procurement channel. Three-tier pricing stratifies across premium hydrogenated grades, standard high-vinyl formulations, and economy liquid rubber variants. Price differentiation hinges on certification grade and captive hydrogenation capability. Cost compression in standard grades intensifies as Korean producers expand Yeosu and Ulsan capacity. Mid-scale adhesive formulators exhibit highest price sensitivity; automotive Tier-1 tire manufacturers demonstrate lowest sensitivity due to single-source partnership premiums.
Supply Chain Analysis
Port congestion along the Busan-Shanghai container corridor elevates inbound logistics costs for non-integrated compounders sourcing from Korean petrochemical groups. Supply concentrates in South Korea, China, and the United States Gulf Coast. Raw material flows draw from naphtha cracking economics and spot butadiene monomer markets. Single-source vulnerability permeates the hydrogenated derivatives segment where Korean tire manufacturers have consolidated procurement. Distribution runs through direct sales contracts for automotive volumes and regional chemical distributors for mid-tier adhesive formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid polybutadiene incumbents face substitution pressure from bio-based reactive plasticizers and thermoplastic polyurethane alternatives in footwear and sealant applications, requiring defensive positioning around integrated hydrogenation assets and REACH-compliant supply chains.
For Market Incumbents: Compound defensive advantages through backward integration into captive catalytic hydrogenation capacity at Yeosu or Ulsan scale. Secure single-source partnership qualification with Korean and Chinese automotive Tier-1 suppliers before REACH authorization timelines harden procurement gates. Neutralize bio-based substitute threats by accelerating supercritical CO2 stripping investments for SVHC-free certification. For New Entrants and Emerging Players: Lead with continuous flow reactor technology to compress capital requirements for distributed manufacturing near Indian tire compounding clusters under the PLI scheme. Target the unmet high-vinyl grade demand in Maharashtra and Gujarat where BIS standards convergence creates specification windows. Pursue technical service partnerships with mid-scale adhesive formulators seeking functionalized variant development support. For Investors and Strategic Acquirers: REACH authorization milestone reshapes the acquisition landscape toward integrated hydrogenation capabilities and closed-loop solvent recovery infrastructure. Long-term viability centers on producers with captive catalytic assets serving automotive and medical packaging segments. Monitor MEE enforcement intensity in the Yangtze River Delta as the signal for regional supply chain restructuring and import substitution opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogenation | Captive catalytic capacity secures premium-grade positioning under REACH SVHC protocols. |
| Continuous Flow Reactor Deployment | Miniaturized production footprints enable just-in-time delivery to tire compounding clusters. |
| Supercritical CO2 Stripping Investment | Eliminates residual solvent traces for German automotive OEM underhood certifications. |
| Single-Source Partnership Qualification | Korean tire manufacturers consolidate procurement with integrated hydrogenation suppliers. |
| India PLI Scheme Localization | Domestic capacity addresses unmet high-vinyl demand from Shandong and Jiangsu tire producers. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with plant managers at solution polymerization facilities, procurement leads at tire OEMs, technical R&D directors at adhesive formulators, and distribution channel partners; and secondary validation through customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed petrochemical groups, and EPA MACT compliance disclosures. Bottom-up volume triangulation across molecular weight specifications and end-use segments intersected with top-down market sizing from regional production capacity and apparent consumption estimates.
Across the projection horizon, the analytical framework modeled segmentation across hydrogenation grade tier, end-use industry concentration, vinyl content specification, and regional production hub. CAGRs derived from elasticity-adjusted demand projections incorporating MIIT fuel-efficiency mandate compliance timelines and MEE volatile organic compound enforcement trajectories. Forecast inputs included butadiene-naphtha spread dynamics and automotive tire production forecasts from vehicle registration databases.
The analysis sits within stated boundaries; outcomes outside sustained naphtha cracking economics, stable REACH authorization timelines, or intact Korea-China logistics corridors would require recalibration. Forecasts reflect documented assumptions around regulatory enforcement intensity and substitution elasticity in footwear and sealant segments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Polybutadiene Market
Rubber
Rubber Splicing Tape Market
Rubber
Rubber Foam Materials Market
Rubber
Silica for S-SBR Market
Rubber
Oil Saver Rubber Market
Rubber
Co-Extruded Rubber Profiles Market
Rubber
Rubber Rollers Market
Rubber
Rubber Extruder Market
Rubber
Plastomers Market
Rubber
Rubber Wear Liners Market
Rubber
Acrylic Rubber Market
Rubber
Rubber Roller Cleaner Market
Rubber
US Nitrile Gloves Market
Rubber
Liquid Silicone Rubber Market
Rubber
EPDM Rubber Market
Rubber
Rubber Gloves Market