
 Global Styrene Butadiene Styrene Market | 2026-2036
Global Styrene Butadiene Styrene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Styrene Butadiene Styrene Market Foresight
The divergence between premium solution-polymerized grades and commodity emulsion-based SBS is realigning procurement patterns across downstream tiers. LG Chem leverages its integrated butadiene feedstock position to sustain margin resilience in high-impact automotive specifications. Kumho Petrochemical anchors Korean supply for footwear and adhesive compounds, while Kraton Corporation differentiates through hydrogenated SBS technology leadership in medical and consumer electronics overmolding.
Styrene butadiene styrene is a thermoplastic elastomer synthesized from styrene and butadiene monomers in block copolymer architecture, typically containing 15–40% styrene content by mass, combining rubber-like elasticity at service temperatures with thermoplastic processability for injection molding and extrusion. Its primary commercial purpose centers on replacing vulcanized rubber in applications requiring recyclability and colorability without crosslinking. Solution polymerized grades command superior clarity and mechanical consistency for appliance manufacturing and consumer electronics housings, whereas emulsion polymerized variants occupy cost-sensitive construction adhesive and packaging segments where performance tolerances are wider. General purpose formulations dominate volume throughput, though high impact grades are capturing margin pools in automotive underhood components exposed to thermal cycling and fluid contact.
REACH registration requirements under ECHA govern styrene monomer residual limits in European compound formulations, while China's SAMR enforces GB standards for construction material flammability and VOC emissions that directly constrain adhesive-grade SBS specifications. The US EPA and OSHA jointly regulate butadiene workplace exposure thresholds, elevating capital requirements for domestic production retrofits and favoring producers with advanced process controls. Stakeholders must monitor regulatory divergence between EU chemical sustainability targets and Asia-Pacific industrial growth mandates to anticipate formulation reformulation cycles and regional supply reallocations.
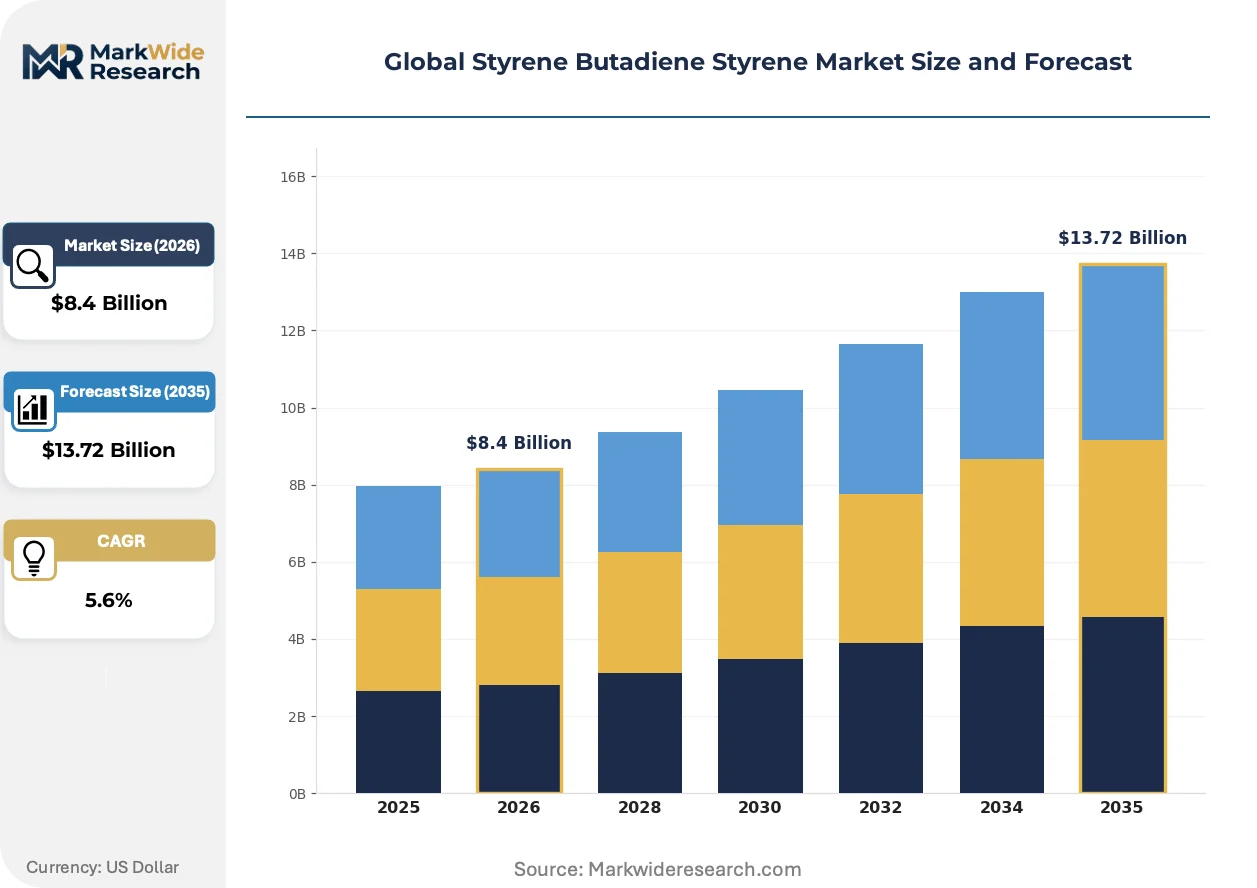
Market Dynamics
The divergence between solution-polymerized and emulsion-polymerized SBS grades is restructuring procurement hierarchies across automotive, construction, and consumer goods verticals, compressing margin pools for undifferentiated producers while rewarding specification expertise.
Growth Catalysts
- Automotive lightweighting mandates:China's MIIT fuel efficiency standards and the EU's CO2 fleet targets are accelerating SBS substitution for heavier rubber and metal sealing components in underhood and chassis systems.
- REACH chemical registration:ECHA's tightened styrene monomer residual limits in European compound formulations are disqualifying non-compliant Asian exporters and consolidating procurement toward certified producers.
- Polymer compounding cluster expansion:Eastern China's Yangtze River Delta manufacturing corridor is absorbing capacity investments to serve domestic appliance and infrastructure buildouts with localized SBS supply.
Market Restraints
- Butadiene feedstock volatility:Crude-linked naphtha cracking economics and steam cracker operating rates in Korea and Thailand transmit cost instability directly to SBS margin structures.
- Emulsion-grade oversupply:Commodity SBS capacity concentration in Shandong and Zhejiang provinces is compressing pricing power for construction adhesive applications with limited performance differentiation.
- Thermoplastic polyurethane substitution:TPU advances in medical tubing and wearable electronics overmolding are capturing specification wins previously held by hydrogenated SBS grades.
Strategic Opportunities
- India construction material standards:BIS enforcement of GB-comparable VOC and flammability norms for adhesives and waterproofing membranes is creating compliance-driven demand for specification-grade SBS.
- Medical device overmolding convergence:Hydrogenated SBS integration with silicone and liquid crystal polymer substrates is opening biocompatible housing applications for diagnostic equipment and drug delivery systems.
- Direct compounder distribution:Bypassing traditional distributor networks to supply polymer compounders in Vietnam and Indonesia is capturing margin previously absorbed by multi-tier channel structures.
Industry Challenges
- Process control engineering scarcity:Advanced reactor temperature and molecular weight distribution management for solution-polymerized grades requires specialized talent concentrated at Korean and Japanese producers.
- REACH registration timeline compression:ECHA's substance evaluation deadlines for butadiene derivatives are forcing reformulation investments with limited advance notice for smaller compounders.
- Legacy extrusion equipment incompatibility:High-styrene content SBS grades with modified rheology profiles demand screw design and cooling system retrofits that strain capital allocation at mid-tier processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Styrene Butadiene Styrene Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.72 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Purpose, High Impact, Emulsion Polymerized, Solution Polymerized Application: Automotive Components, Electrical Equipment Housing, Footwear Soles, Adhesives, Toys & Sporting Goods End User Industry: Consumer Electronics, Construction Materials, Packaging, Appliance Manufacturing Distribution Channel: Direct Sales, Distributors, Online Platforms, Industrial Suppliers |
| Companies Covered | LG Chem, Kumho Petrochemical, Kraton Corporation, China National Petroleum Corporation, LCY Group, Dynasol Group, Sinopec, Versalis, TSRC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Styrene Butadiene Styrene Market Shifts & Advancements
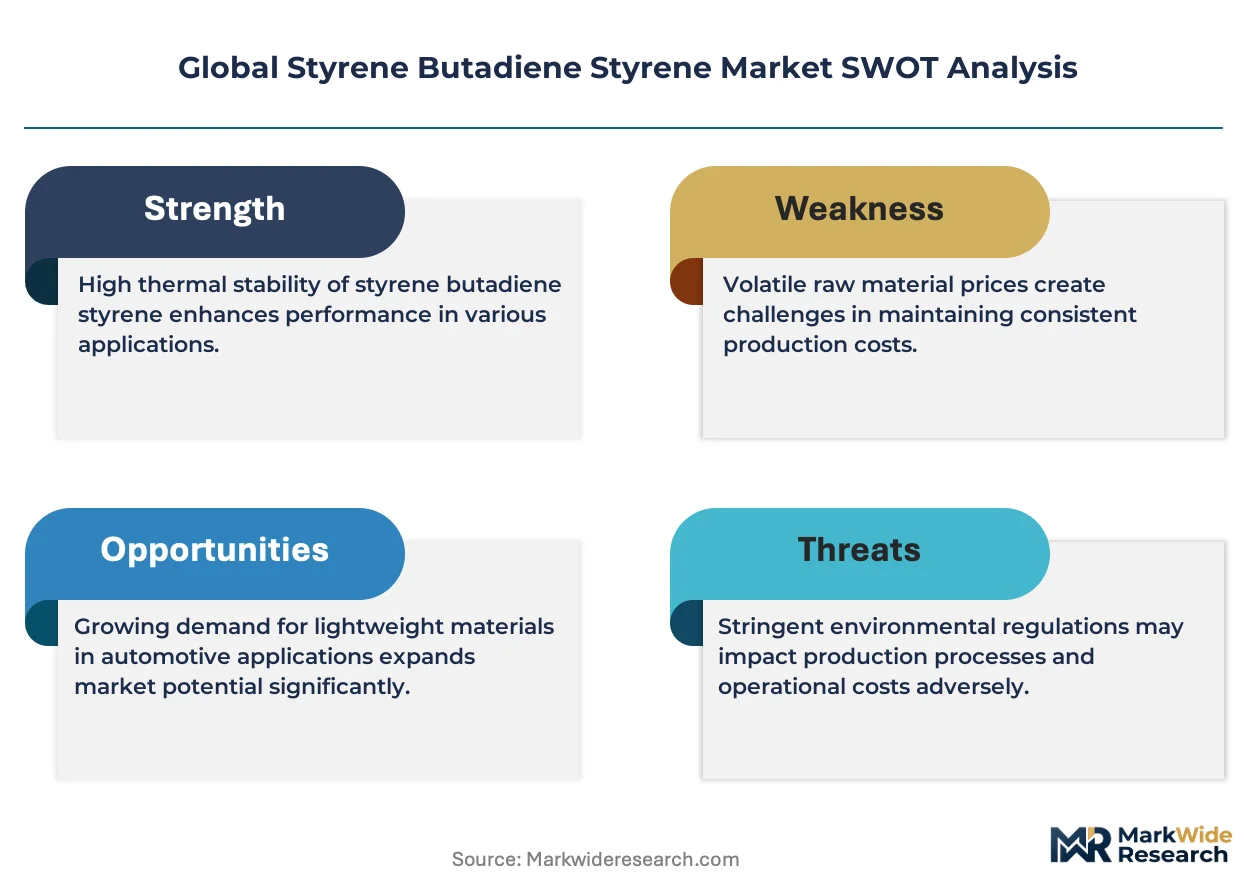
Active hydrogenation technology deployment, regulatory chemistry constraints, and procurement centralization are compressing traditional supply hierarchies while opening specification-driven margin pools for technical differentiation.
Advanced partial hydrogenation of SBS mid-blocks is electrifying performance thresholds for medical device and consumer electronics applications requiring thermal stability above 100°C combined with thermoplastic processability. Korean compounders are adopting these grades for smartphone hinge seals and wearable sensor housings at triple-digit annual volume growth. This capability expansion is electrifying competitive segmentation between hydrogenation-equipped producers and commodity emulsion specialists.
China's SAMR enforcement of GB 18583 and GB 30982 standards for construction adhesive VOC emissions and flammability is disqualifying legacy emulsion formulations from state-funded infrastructure projects. Compounders serving railway and tunnel waterproofing segments are reformulating toward solution-polymerized SBS with certified styrene residual profiles. The construction adhesive tier is absorbing compliance costs through specification upgrades rather than volume sacrifice.
Automotive Tier 1 suppliers are consolidating SBS procurement through central technical buying centers in Stuttgart, Shanghai, and Detroit, displacing regional plant-level purchasing autonomy. Specification engineers now dictate grade selection based on thermal cycling and fluid resistance protocols, compressing price negotiation leverage for traditional sales relationships. This concentration is most visible in German and Chinese automotive sealing system supply chains where platform standardization dominates.
Global Styrene Butadiene Styrene Market Segmentation
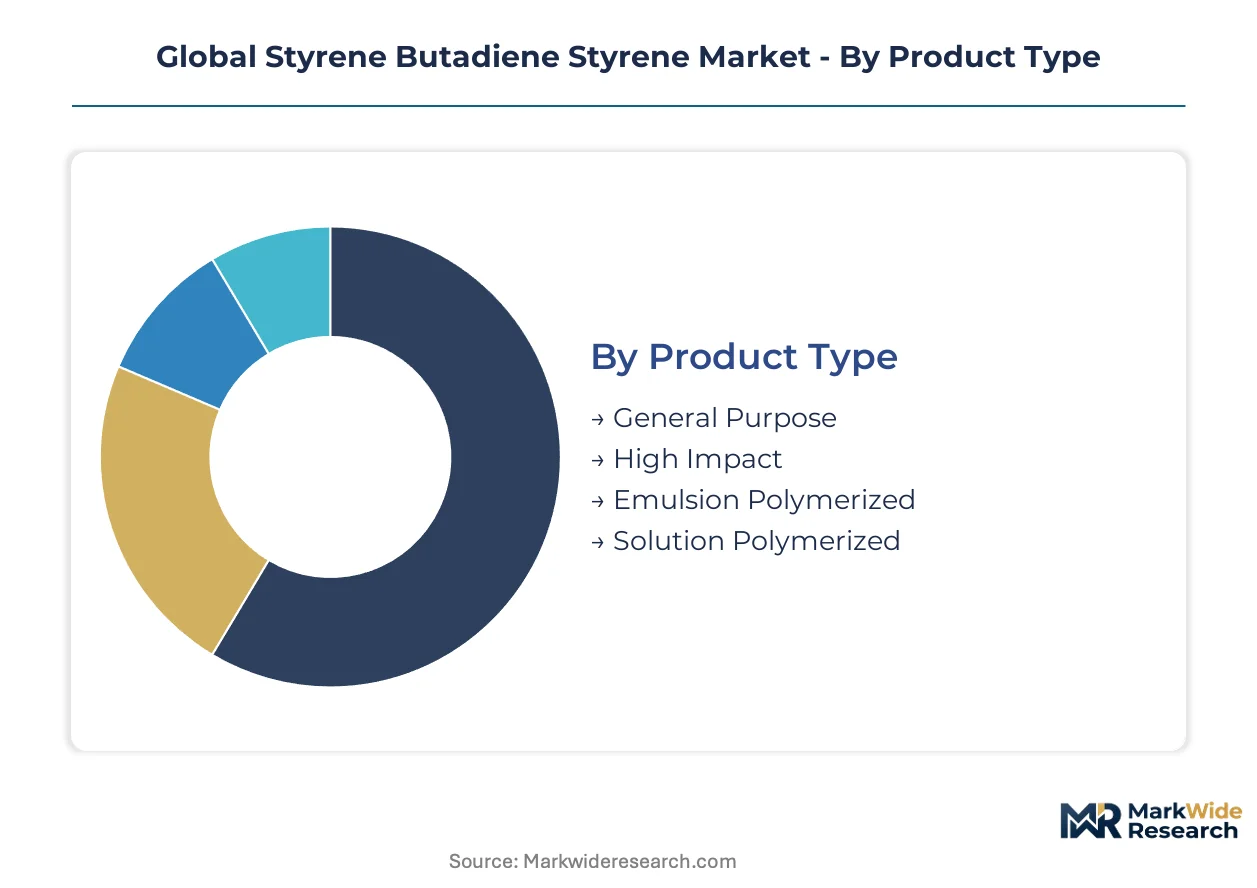
SBS market segmentation reveals how polymer architecture and certification requirements stratify procurement decisions across automotive, construction, and consumer goods verticals. Specification-grade differentiation commands pricing premiums while commodity grades compete on feedstock integration and regional logistics.
Product Type:
REACH registration under ECHA and China's GB construction standards impose divergent compliance burdens across polymerization routes, with solution-polymerized grades facing stricter styrene residual documentation than emulsion variants.
- Solution Polymerized:Manufactured via anionic polymerization in hydrocarbon solvent systems, yielding narrow molecular weight distribution and superior optical clarity. Demand concentrates in German automotive sealing systems and Korean consumer electronics housings where MIIT and ECHA compliance documentation is mandatory for Tier 1 supplier qualification.
- High Impact:Engineered with elevated butadiene mid-block content and controlled styrene end-block architecture to absorb mechanical shock and thermal cycling stress. Procurement is accelerating in Chinese underhood components as domestic OEMs adopt fuel efficiency standards requiring lightweight rubber replacements.
- General Purpose:Balanced styrene-butadiene block ratios optimized for cost-sensitive extrusion and molding operations across packaging and toy applications.
- Emulsion Polymerized:Produced via free-radical aqueous emulsion systems with broader polydispersity, serving construction adhesive formulators in Shandong and Zhejiang provinces where GB 18583 VOC compliance is emerging.
Leading the category by volume: General Purpose. Growing fastest: High Impact.
Application:
End-use concentration patterns reflect diverging margin structures between specification-driven automotive procurement and price-sensitive construction segments.
- Automotive Components:Sealing gaskets, vibration dampeners, and fluid-resistant underhood housings requiring thermal stability above 100°C. Specification engineers at Stuttgart and Shanghai technical buying centers dictate grade selection based on fluid resistance protocols.
- Adhesives:Pressure-sensitive and hot-melt formulations for construction waterproofing membranes. Demand is concentrating in Chinese railway and tunnel projects where SAMR enforces GB 30982 flammability standards.
- Electrical Equipment Housing:Overmolding and cable jacketing applications requiring dielectric stability.
- Footwear Soles:Thermoplastic injection molding for athletic and casual shoe midsoles.
- Toys & Sporting Goods:Colorable, recyclable elastomer substitutes for traditional vulcanized rubber.
Automotive Components captures the largest revenue pool. Adhesives is expanding most quickly on infrastructure compliance mandates.
End User Industry:
Customer sophistication tiers separate specification-grade compounders from volume buyers prioritizing feedstock security.
- Construction Materials:Waterproofing membranes, sealants, and insulation boards for commercial and infrastructure buildouts. Procurement clusters in China's Yangtze River Delta where polymer compounding facilities serve state-funded projects.
- Consumer Electronics:Smartphone hinge seals, wearable sensor housings, and laptop overmolding requiring hydrogenated SBS grades for thermal stability above 100°C.
- Appliance Manufacturing:Refrigerator gaskets, washing machine dampeners, and small appliance housings.
- Packaging:Flexible film layers and container seals where clarity and resealability compete with TPU alternatives.
Construction Materials dominates tonnage throughput. Consumer Electronics delivers the steepest expansion trajectory on medical and diagnostic device convergence.
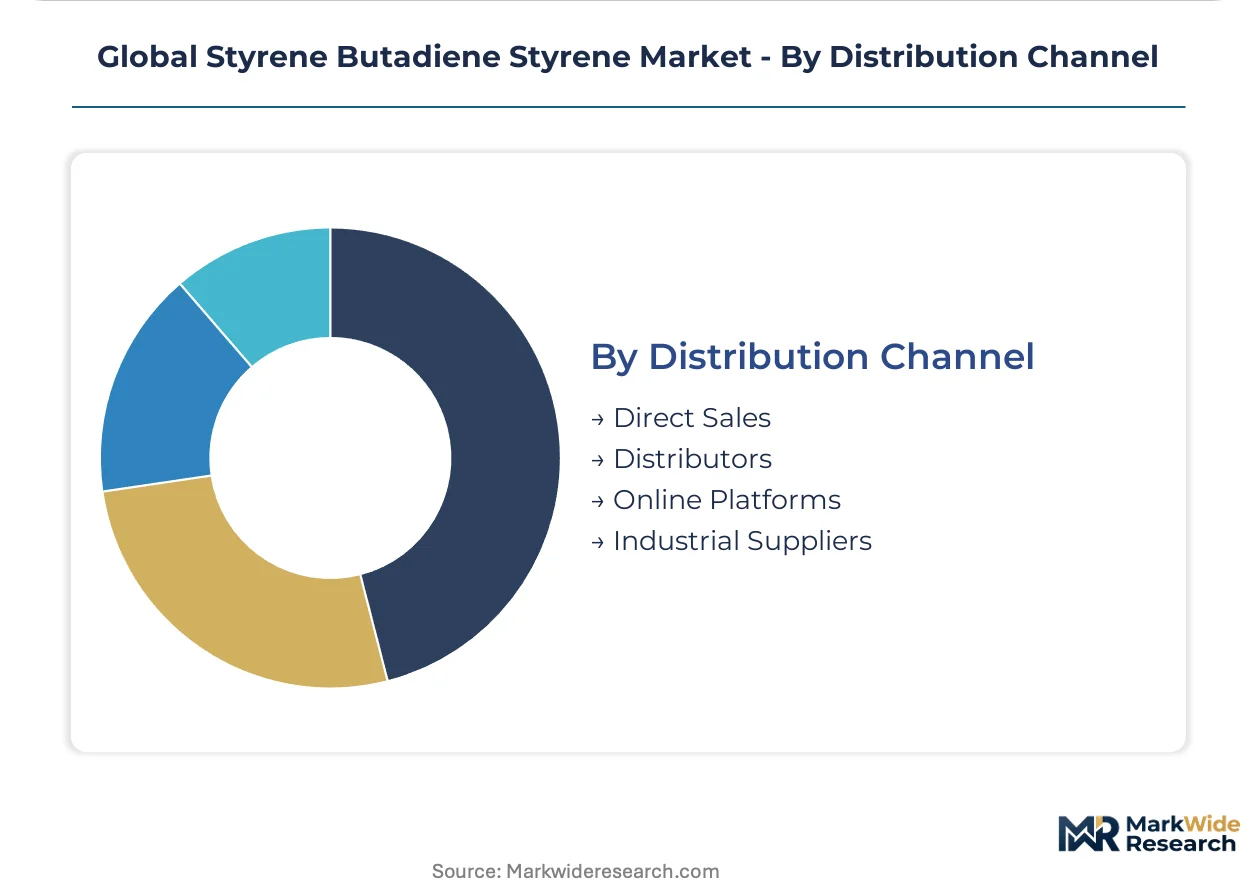
Distribution Channel:
Channel selection reflects customer scale and formulation complexity, with compounders bypassing traditional tiers to capture margin.
- Direct Sales:Technical service relationships between polymer producers and Tier 1 automotive suppliers, electronics OEMs, and large construction chemical formulators. Contracts specify certified styrene residual profiles and lot traceability.
- Distributors:Regional inventory positioning for mid-tier processors lacking volume to justify direct producer relationships.
- Industrial Suppliers:Consolidated procurement for maintenance, repair, and small-batch operations.
- Online Platforms:Emerging for standardized grades and technical documentation access.
Direct Sales leads by value contribution. Distributors retain volume dominance in fragmented construction adhesive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta manufacturing corridor anchors global SBS procurement intensity, with polymer compounding clusters in Ningbo and Shanghai serving domestic appliance and infrastructure buildouts at unmatched scale.
China
Automotive lightweighting mandates from MIIT and state-funded railway waterproofing projects drive specification-grade demand. SAMR enforces GB 18583 and GB 30982 standards for construction adhesive VOC emissions and flammability. Shandong and Zhejiang provinces concentrate commodity emulsion capacity, while solution-polymerized grades concentrate in eastern coastal facilities serving export automotive tiers.
United States
Underhood sealing system procurement from Detroit-based Tier 1 suppliers accelerates high-impact grade absorption. EPA and OSHA jointly regulate butadiene workplace exposure thresholds, elevating capital requirements for domestic production retrofits. Gulf Coast petrochemical corridors sustain feedstock-integrated SBS output for automotive and packaging applications.
Germany
Stuttgart-centered automotive technical buying centers dictate grade selection for thermal cycling and fluid resistance protocols. ECHA's REACH registration requirements govern styrene monomer residual limits in compound formulations. BASF-Ludwigshafen and surrounding Rhineland chemical clusters anchor specification-grade hydrogenated SBS demand for medical and electronics overmolding.
South Korea
Consumer electronics housing and wearable sensor applications propel triple-digit annual volume growth for hydrogenated grades. MFDS and METI-aligned standards shape biocompatibility documentation requirements for medical device integration. Yeosu and Ulsan petrochemical complexes leverage integrated butadiene positions to serve Korean compounding facilities and export automotive specifications.
India
BIS enforcement of GB-comparable VOC and flammability norms for construction adhesives creates compliance-driven demand for specification-grade material. Infrastructure waterproofing mandates for railway and tunnel projects accelerate SBS membrane procurement. Gujarat and Maharashtra polymer processing corridors absorb imported solution-polymerized grades for localized compounding operations.
Global Styrene Butadiene Styrene Market Competitive Landscape
Premium-margin players sit above commodity-margin players across hydrogenation capability and certified residual documentation. The vendor base stratifies between integrated petrochemical majors with captive butadiene supply, specialized elastomer compounders with reactor technology licensing, and regional emulsion-grade producers competing on logistics proximity. Three archetypes dominate: feedstock-integrated Asian majors, hydrogenation-technology specialists, and construction-focused commodity compounders. Capacity expansion and direct compounder distribution bypassing traditional tiers represent the dominant competitive vectors.
Within the integrated petrochemical tier, LG Chem and Kumho Petrochemical exemplify feedstock-anchored positioning, while Kraton Corporation occupies the hydrogenation-technology specialist archetype. These three entities represent divergent margin strategies—integrated feedstock security versus specification-grade technical differentiation—across automotive, medical, and consumer electronics end-uses.
| Leading Market Players |
|---|
| LG Chem |
| Kumho Petrochemical |
| Kraton Corporation |
| China National Petroleum Corporation |
| LCY Group |
| Dynasol Group |
| Sinopec |
| Versalis |
| TSRC Corporation |
| Others |
Supply & Pricing Matrix
Automotive Tier 1 technical buying centers in Stuttgart, Shanghai, and Detroit command specification-grade SBS procurement through centralized contracts, anchoring a value-based pricing model tied to certified residual profiles and thermal cycling performance outcomes rather than commodity spot benchmarks.
Pricing Analysis
Value-based pricing anchors on thermal stability certification and REACH-compliant styrene residual documentation, with solution-polymerized grades commanding premiums over emulsion variants. Price differentiation separates hydrogenated medical-grade specifications from construction adhesive commodities, with the latter absorbing cost compression from Shandong and Zhejiang oversupply. Tier 1 automotive buyers exhibit lowest price sensitivity due to platform standardization mandates, while mid-tier construction compounders face acute margin pressure from feedstock volatility.
Supply Chain Analysis
REACH and GB standard qualification gates restrict European and Chinese construction procurement to certified producers, concentrating solution-polymerized supply in Korean coastal complexes and eastern Chinese facilities. Butadiene feedstock draws from naphtha cracking economics in Korea, Thailand, and US Gulf Coast corridors. Single-source vulnerability persists for hydrogenation reactor technology licensed from Japanese and Korean engineering specialists. Distribution runs through direct technical service relationships with Tier 1 automotive and electronics OEMs, bypassing traditional distributor tiers for specification-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into captive butadiene supply and downstream compounding capabilities defines the current vertical-integration race, with feedstock security and certification infrastructure representing the decisive levers for margin defense.
For Market Incumbents: Cement hydrogenation technology leadership through reactor licensing consolidation and medical-grade certification expansion at Korean and German facilities. Threats from thermoplastic polyurethane substitution in wearable electronics demand accelerated R&D in silicone-SBS hybrid substrates. Prioritize direct distribution bypasses in Vietnam and Indonesia to capture margin from fragmented construction adhesive channels. For New Entrants and Emerging Players: Mid-tier Indian construction compounders present the most penetrable buyer archetype, with BIS compliance mandates creating specification-grade demand that imported solution-polymerized grades can satisfy. White-space opportunities concentrate in Gujarat and Maharashtra polymer processing corridors lacking localized hydrogenation capabilities. A technical service partnership model with European certification documentation offers the strongest go-to-market angle against established Asian majors. For Investors and Strategic Acquirers: Distressed-cycle entries favor emulsion-grade producers in Shandong province facing GB 18583 compliance retrofit costs, where specification-grade conversion investments could reposition assets for railway waterproofing membrane supply. Long-term viability hinges on hydrogenation capability access or captive butadiene integration. Watch for MIIT fuel efficiency standard acceleration in China as the inflection signal for high-impact grade demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butadiene Feedstock | Captive naphtha cracking in Korean Yeosu and Ulsan complexes secures margin resilience against crude-linked volatility. |
| Hydrogenation Reactor Technology Licensing | Partial hydrogenation capabilities unlock medical device and consumer electronics specifications above 100°C thermal thresholds. |
| Direct Compounder Distribution Expansion | Bypassing multi-tier channels in Vietnam and Indonesia captures margin previously absorbed by regional distributors. |
| REACH and GB Certification Investment | Certified styrene residual documentation qualifies producers for European automotive and Chinese state-funded infrastructure procurement. |
| Joint Venture with Polymer Compounding Clusters | Partnerships in Yangtze River Delta facilities localize supply for appliance manufacturing and railway waterproofing demand. |
Research Methodology
Trade databases, ECHA registration filings, and MIIT automotive standard disclosures formed the secondary backbone, cross-referenced with primary interviews involving polymer plant managers, Tier 1 automotive procurement leads, construction chemical formulators, and hydrogenation technology licensors. Bottom-up volume modeling from grade-specific production capacities and top-down demand triangulation from end-use consumption patterns were reconciled across the analysis window.
Historical trendline analysis of solution-polymerized and emulsion-polymerized grade spreads informed the projection framework, with segmentation across polymerization route, styrene content tier, end-use industry, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating automotive lightweighting mandates and construction compliance phase-ins. Butadiene-naphtha price spreads and reactor utilization rates at Korean petrochemical complexes served as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH substance evaluation timelines for butadiene derivatives and MIIT fuel efficiency standard acceleration. Forecasts reflect assumptions about regulatory enforcement consistency and steam cracker operating rate stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Accelerators Market
Rubber
Rubber Plated Hose Market
Rubber
Rubber Bulb Seals Market
Rubber
Rubber Tapes Market
Rubber
Rubber Color Masterbatch Market
Rubber
Polybutadiene Market
Rubber
Nitrile Butadiene Rubber (NBR) Latex Market
Rubber
Global Chloroprene Rubber Market
Rubber
Polyacrylate Rubber Market
Rubber
Global Latex Allergy Market
Rubber
Polybutadiene Elastomers Market
Rubber
Global Rubber Coated Fabrics Market
Rubber
Rubber Reinforcing Chemicals Market
Rubber
Rubber Valve Stem Market
Rubber
Rubber Choppers Market
Rubber
Rubber Conveyor Belt Market