
 EPDM Sealing Strip Market | 2026-2036
EPDM Sealing Strip Market Size, Share, and Industry Trends Forecast 2026-2036
EPDM Sealing Strip Market Analysis
Advanced extrusion coextrusion and automated profile welding is tilting production economics toward precision-tolerance sealing systems. Hutchinson leverages backward integration into rubber compounding to secure compound consistency for automotive glazing channels. Trelleborg AB anchors its position through marine and infrastructure sealing specialization alongside automotive supply. Continental AG competes on manufacturing scale, operating multi-continent extrusion networks that service both OEM direct and tier-one distributor channels.
EPDM sealing strip denotes an ethylene-propylene-diene monomer rubber extrusion, typically formulated with carbon black reinforcement and paraffinic oil plasticizers, cured through sulfur or peroxide vulcanization to achieve Shore A hardness between 40 and 90 for compression-set resistance in static and dynamic sealing joints. The primary industrial purpose spans weatherproofing, vibration damping, and fluid containment across transportation, building envelope, and mechanical equipment interfaces. Automotive application leads absolute volume, driven by door, hood, and glass-run sealing on passenger and commercial vehicles, while construction application registers faster structural growth as energy-efficient building codes tighten thermal envelope requirements. Self-adhesive product variants command margin premiums through eliminated secondary bonding operations, whereas bulk rolls dominate volume throughput in distributor-led industrial supply chains.
EPA tailpipe and fuel-efficiency standards shape automotive sealing specifications in the United States, while REACH substance restrictions and EU Green Deal decarbonization mandates constrain filler and plasticizer selections across European manufacturing. ECHA classification of certain process oils as substances of very high concern is forcing compound reformulation toward bio-based or naphthenic alternatives. China's GB standards and MIIT automotive regulations govern local content and performance testing protocols for domestic vehicle production. Stakeholders must monitor evolving chemical compliance boundaries across these jurisdictions while calibrating R&D allocation between low-emission mobility platforms and building-efficiency retrofit cycles.
Market Dynamics
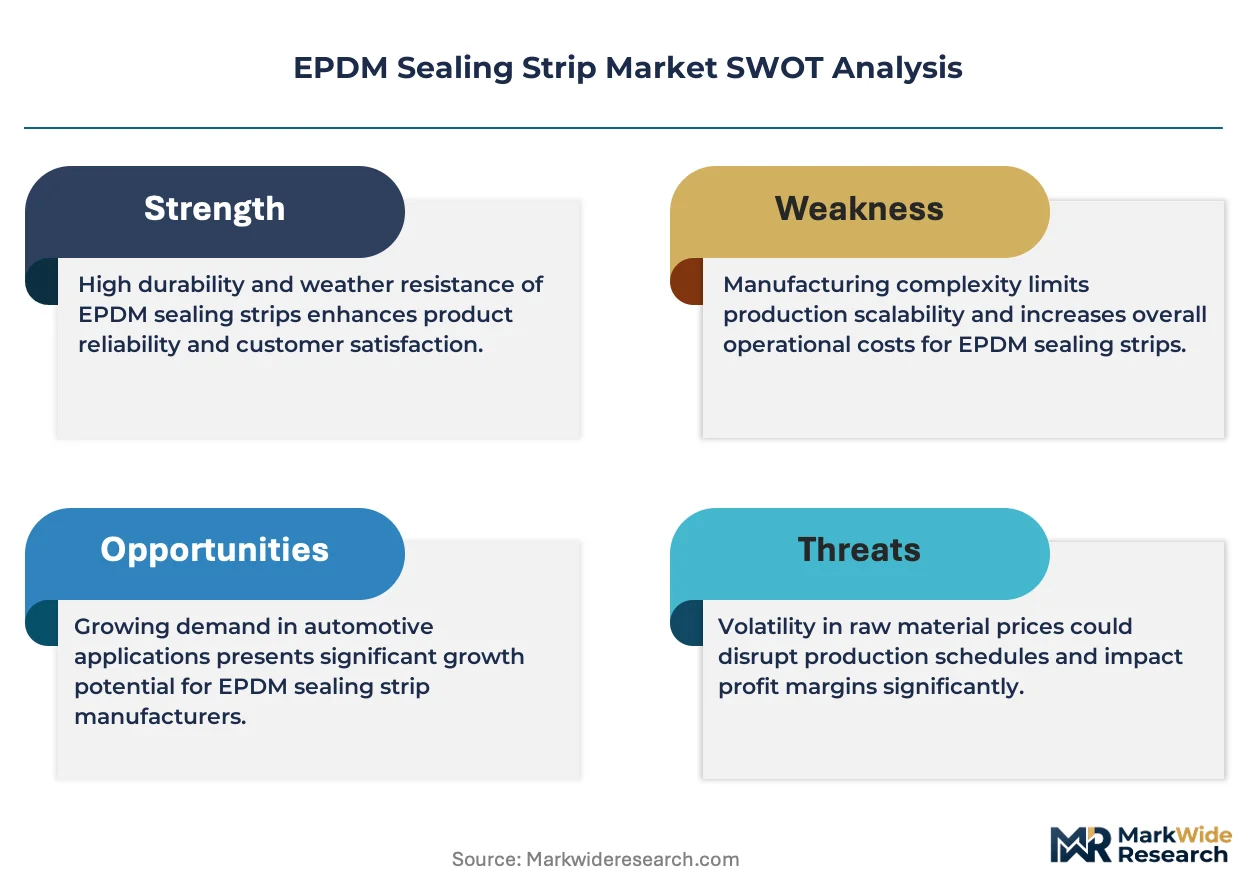
REACH substance restrictions and EU Green Deal mandates are forcing compound reformulation across European manufacturing, while precision extrusion technology upgrades concentrate production capability among capital-intensive operators.
Growth Catalysts
- Automotive electrification platforms:Electric vehicle architectures in Germany and Japan require specialized sealing profiles for battery enclosures and thermal management systems.
- Energy-efficient building codes:Tightened thermal envelope standards across multiple jurisdictions are accelerating specification of high-performance EPDM weatherstripping in commercial construction.
- REACH compliance differentiation:Early reformulation toward bio-based plasticizers and SVHC-free process oils creates competitive separation for compliant suppliers.
Market Restraints
- Carbon black supply concentration:Reinforcement filler procurement depends on concentrated petrochemical feedstock channels vulnerable to price volatility.
- EPDM polymer capacity geography:Ethylene-propylene monomer supply clusters in specific regional production corridors, exposing converters to logistics cost swings.
- Thermoplastic vulcanizate substitution:TPV materials encroach on lower-performance static sealing applications through simplified processing economics.
Strategic Opportunities
- Retrofit building efficiency cycles:Aging commercial building stock in North American and European urban centers creates aftermarket demand for high-performance envelope sealing.
- Marine infrastructure specialization:Port expansion and offshore renewable energy installations require corrosion-resistant sealing systems with extended service life specifications.
- Self-adhesive product formats:Elimination of secondary bonding operations through integrated pressure-sensitive adhesive layers commands margin premiums in distributor channels.
Industry Challenges
- Compound formulation expertise scarcity:Reformulation for SVHC compliance requires specialized rubber chemistry knowledge concentrated among experienced technical staff.
- Multi-jurisdiction certification timelines:Parallel GB standard testing for China MIIT automotive regulations, EPA compliance documentation, and ECHA substance notifications extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EPDM Sealing Strip Market |
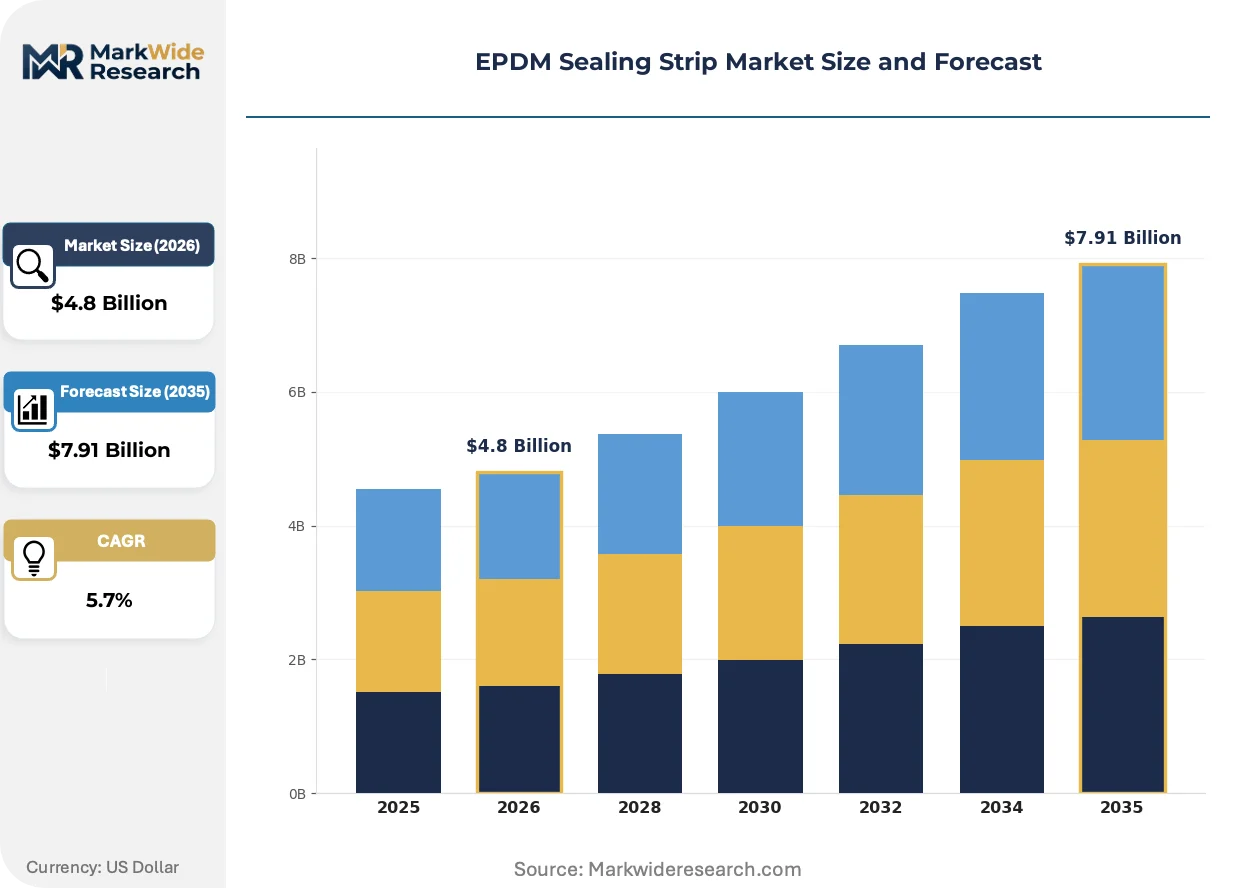
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhesive, Non-Adhesive, Bulk Rolls, Custom Profiles Application: Automotive, Construction, HVAC, Industrial End User: Manufacturers, Distributors, OEMs, Contractors Form: Solid, Sponge, Foam, Gasket |
| Companies Covered | Hutchinson, Trelleborg AB, Cooper, SaarGummi, Nishikawa, Henniges, Continental AG, 3M Company, Toyoda Gosei, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EPDM Sealing Strip Market Emerging Trajectories
Extrusion technology convergence with automated quality systems is compressing tolerance bands and reshaping supplier capability requirements. Material science advances and regulatory chemistry constraints are simultaneously pulling formulation strategies in divergent directions.
Multilayer coextrusion with integrated conductive or thermally active layers is hybridizing traditional EPDM profiles into functional components. Automotive OEMs in Germany and Japan are specifying these hybrid architectures for electric vehicle battery sealing. This convergence is hybridizing the competitive boundary between commodity rubber extruders and precision polymer component specialists.
ECHA classification of certain aromatic process oils as substances of very high concern is forcing systematic compound reformulation across European manufacturing. Compounders are migrating toward naphthenic or bio-based alternatives with modified viscosity profiles. Automotive glazing channel specifications in Germany are experiencing the most intensive reformulation activity as OEMs anticipate downstream regulatory extension.
Integrated auto and construction supply chains in China's eastern manufacturing corridor are consolidating procurement authority among fewer large-scale distributors. Tier-one distributors are displacing fragmented regional suppliers through volume-based pricing and technical service bundling. This concentration is most visible in Shandong and Jiangsu provinces where custom profile volumes anchor distributor margin structures.
EPDM Sealing Strip Market Segmentation
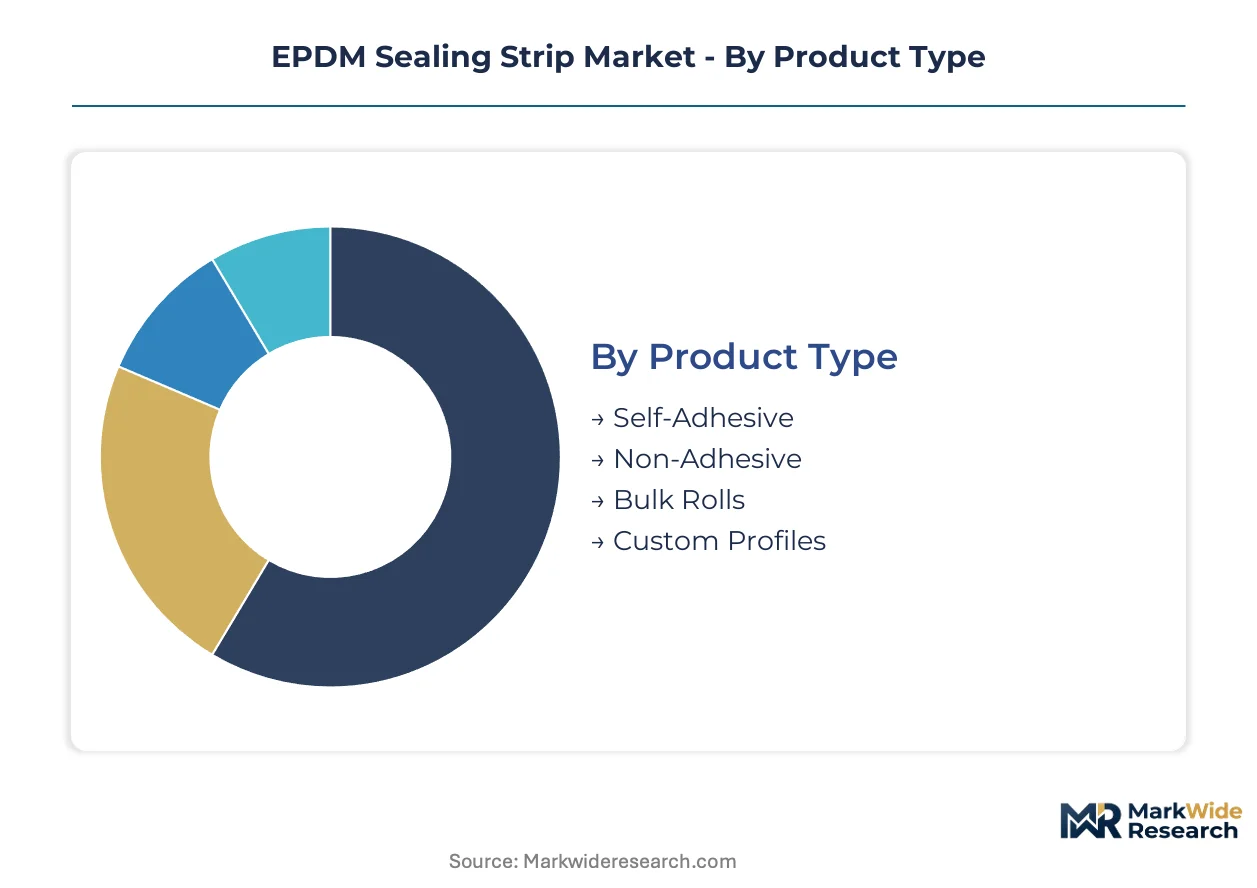
EPDM sealing strip demand fragments across four structural dimensions that determine pricing power, technical requirements, and channel economics. Product format and application specifications create divergent margin profiles, while end-user procurement patterns and physical form factors dictate manufacturing scale and capital intensity.
Product Type:
Mature formats dominate volume throughput, while emerging configurations capture specification premiums through eliminated processing steps.
- Self-Adhesive:Pressure-sensitive adhesive layers integrated during extrusion eliminate secondary bonding operations. German automotive glazing channels and Japanese battery enclosure specifications are driving procurement concentration toward this format for electric vehicle platforms.
- Non-Adhesive:Standard extruded profiles requiring separate mechanical fastening or adhesive application. Construction weatherstripping in China's eastern manufacturing corridor consumes bulk volumes through distributor-led supply chains serving retrofit building efficiency cycles.
- Bulk Rolls:Continuous extrusion wound for industrial processing and distributor cutting operations.
- Custom Profiles:Precision-tolerance geometries engineered to OEM-specific sealing joint dimensions.
Non-adhesive profiles retain volume leadership; self-adhesive formats hold the steepest expansion curve.
Application:
Cost tiers separate commodity weatherproofing from performance-critical dynamic sealing systems.
- Automotive:Door, hood, and glass-run sealing on passenger and commercial vehicles demands Shore A hardness between 40 and 90 for compression-set resistance. German OEMs are expanding procurement for electric vehicle thermal management and battery enclosure applications.
- Construction:Building envelope weatherstripping registers accelerated specification as energy-efficient codes tighten thermal performance requirements across North American and European commercial retrofit cycles.
- HVAC:Vibration damping and air-handling unit sealing for mechanical equipment interfaces.
- Industrial:Fluid containment and equipment sealing across manufacturing and process industries.
Automotive applications anchor revenue concentration; construction specifications are gaining share fastest through regulatory tightening.
End User:
Customer type determines technical service intensity and contract structure across the procurement spectrum.
- Manufacturers:Direct extrusion procurement for captive sealing component integration into finished goods.
- Distributors:Volume-based pricing authority concentrates among tier-one distributors in Shandong and Jiangsu provinces, displacing fragmented regional suppliers through bundled technical service offerings.
- OEMs:Automotive original equipment manufacturers in Germany and Japan specify precision-tolerance profiles with REACH-compliant compound formulations.
- Contractors:Project-based procurement for construction installation and building envelope retrofit operations.
Distributors retain volume leadership; OEM direct procurement holds the steepest expansion curve through electrification platform requirements.
Form:
Physical density and cellular structure create divergent performance envelopes for static versus dynamic sealing joints.
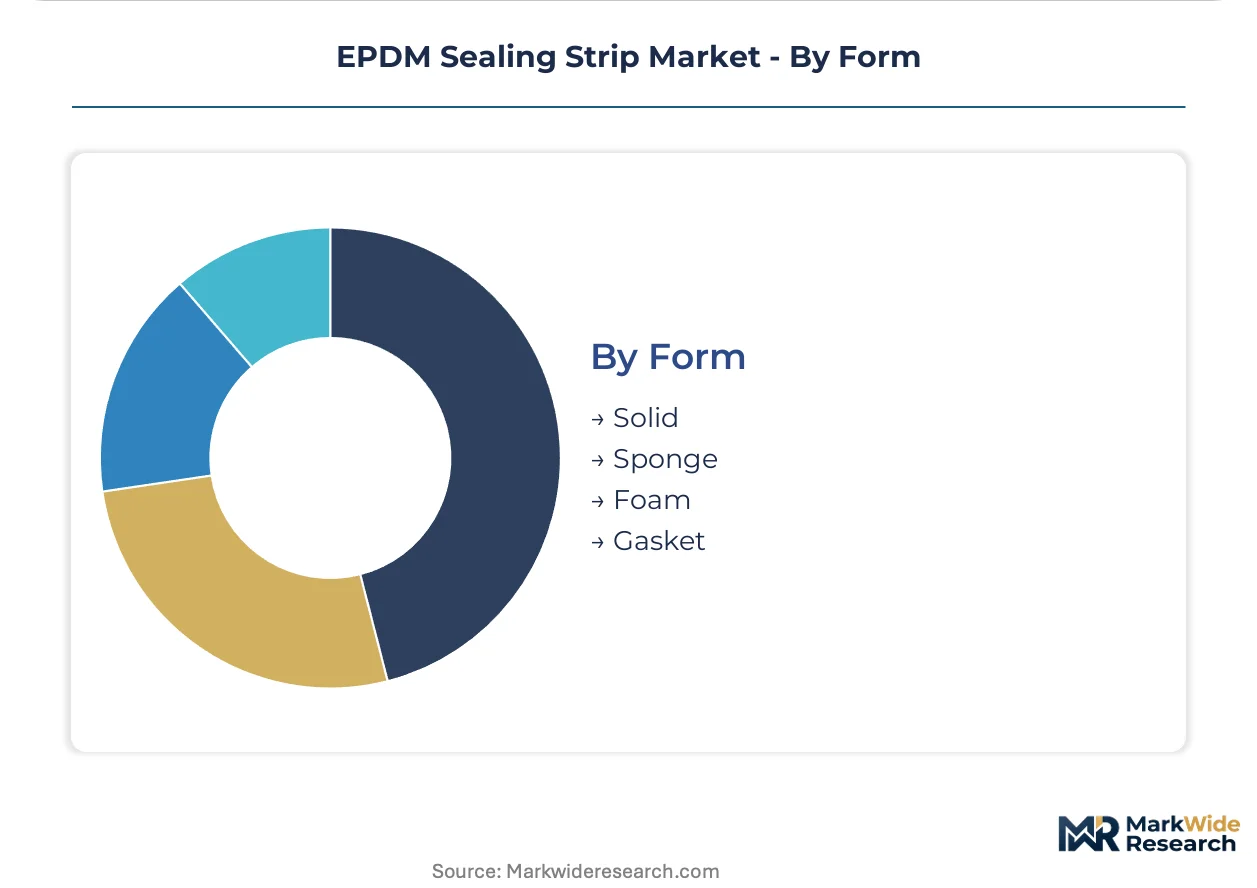
- Solid:Dense vulcanized rubber for high-pressure fluid containment and structural sealing applications.
- Sponge:Closed-cell or open-cell structures providing compressibility for irregular joint surfaces.
- Foam:Lower-density cellular configurations for lightweight vibration damping and acoustic isolation.
- Gasket:Precision-cut or molded shapes for flange sealing and mechanical assembly interfaces.
Solid profiles retain volume leadership; sponge configurations hold the steepest expansion curve through automotive NVH and battery sealing specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-tolerance EPDM profiles to automotive OEMs across Japan and China, while Chinese manufacturers supply bulk construction weatherstripping to Southeast Asian retrofit markets. This trade-flow configuration concentrates technical specification authority in European compound formulation while volume manufacturing scales across East Asian extrusion networks.
Germany
Automotive OEMs in Stuttgart and Munich are expanding procurement for electric vehicle battery enclosure sealing. ECHA substance restrictions under REACH are forcing systematic reformulation away from aromatic process oils toward naphthenic alternatives. The Baden-Württemberg industrial corridor hosts concentrated rubber compounding expertise serving glazing channel specifications.
China
Integrated auto and construction supply chains in Shandong and Jiangsu provinces consume bulk custom profile volumes. MIIT automotive regulations and GB standards govern local content requirements for domestic vehicle production. The Yangtze River Delta manufacturing cluster anchors distributor-led procurement concentration displacing fragmented regional suppliers.
Japan
Automotive electrification platforms require specialized sealing profiles for thermal management systems. METI industrial standards shape performance testing protocols for domestic OEM supply relationships. The Kanto region around Tokyo concentrates precision extrusion capability serving Toyota and Nissan procurement networks.
United States
Commercial building retrofit cycles in Chicago and New York Metro are accelerating specification of high-performance weatherstripping. EPA tailpipe and fuel-efficiency standards influence automotive sealing specifications for domestic production. The Midwest automotive belt maintains extrusion networks servicing OEM direct and tier-one distributor channels.
India
Construction sector expansion in Maharashtra and Gujarat is driving demand for building envelope sealing solutions. BIS standards govern rubber product quality certification for domestic infrastructure projects. The Delhi-NCR corridor is emerging as a distribution hub for construction-grade EPDM profiles serving northern state markets.
EPDM Sealing Strip Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where capital-intensive extrusion networks face pressure from precision-tolerance specialists. The vendor base separates into three strategic archetypes: automotive OEM-direct suppliers with captive compounding capability, construction-focused distributors with volume-based pricing authority, and hybrid operators spanning marine and infrastructure specializations. Dominant competitive moves include backward integration into rubber compounding to secure formulation consistency, and geographic expansion through multi-continent extrusion networks to service both direct OEM and distributor channels.
Within the automotive-direct tier, Hutchinson and Continental AG exemplify capital-intensive operators with integrated compounding and extrusion capabilities. Trelleborg AB occupies a position bridging automotive supply with marine and infrastructure specializations. These three entities represent distinct strategic postures: compound-consistency through backward integration, manufacturing scale across continental networks, and application diversification beyond transportation into corrosion-resistant infrastructure systems.
| Leading Market Players |
|---|
| Hutchinson |
| Trelleborg AB |
| Cooper |
| SaarGummi |
| Nishikawa |
| Henniges |
| Continental AG |
| 3M Company |
| Toyoda Gosei |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta freight corridor's container cost dynamics amplify supply concentration effects among Shandong and Jiangsu extrusion networks while compressing margin structures for non-adhesive bulk roll distributors serving construction retrofit cycles. REACH compliance differentiation creates downstream price stratification between SVHC-compliant compounders and legacy formulation suppliers.
Pricing Analysis
Precision-extrusion next-generation profiles command substantial premiums over standard sulfur-cured prior-generation formulations and emerging peroxide-cured alternatives. Three-tier pricing structure across premium REACH-compliant automotive specifications, standard construction weatherstripping, and economy-grade industrial bulk rolls reflects certification grade and volume scale differentiation. Pricing pressure stems from thermoplastic vulcanizate substitution in static sealing applications. Tier-one distributors exhibit lowest price sensitivity due to bundled technical service contracts, while fragmented regional suppliers face acute margin compression.
Supply Chain Analysis
Export-control restrictions on advanced extrusion monitoring systems limit technology transfer to precision-tolerance operators in Germany and Japan. EPDM polymer supply concentrates in China, South Korea, and Saudi Arabia, drawing from ethylene-propylene monomer feedstock anchored in regional petrochemical corridors. Carbon black reinforcement and naphthenic process oil dependencies create single-source vulnerability for European compound reformulation. Distribution runs through tier-one distributors displacing fragmented regional suppliers in China's eastern manufacturing corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory chemistry fragmentation across REACH, EPA, and MIIT jurisdictions creates specialized formulation niches for compound-consistency specialists serving electric vehicle platform procurement.
For Market Incumbents: Build formulation-consistency moats through backward integration into captive rubber compounding serving German automotive glazing channels. Secure multi-jurisdiction certification pipelines ahead of ECHA substance restriction extensions. Counter thermoplastic vulcanizate substitution threat by emphasizing compression-set performance in dynamic sealing joints. Prioritize R&D allocation toward bio-based plasticizer integration for SVHC-compliant product lines. For New Entrants and Emerging Players: Establish a beachhead in marine infrastructure specialization serving port expansion and offshore renewable energy installations. Target India's construction sector expansion in Maharashtra and Gujarat for building envelope retrofit specifications. Leverage self-adhesive format premiums through pressure-sensitive adhesive layer integration eliminating secondary bonding operations. Pursue technical service bundling to displace fragmented regional distributors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming rubber extrusion divisions lacking electrification platform focus. Long-term viability hinges on compound reformulation expertise scarcity and electric vehicle thermal management specification growth. Monitor ECHA substance notification timelines as inflection indicator for compliant supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Compounding | Hutchinson secures formulation consistency for automotive glazing channels through captive compound production. |
| Multi-Jurisdiction Certification Investment | Parallel REACH, EPA, and MIIT compliance documentation compresses product launch cycles for OEM-direct suppliers. |
| Self-Adhesive Product Format Expansion | Eliminated secondary bonding operations command margin premiums in distributor-led construction supply chains. |
| Marine Infrastructure Specialization | Port expansion and offshore wind installations require corrosion-resistant sealing with extended service life specifications. |
| Precision Extrusion Technology Upgrade | Automated quality systems compress tolerance bands for electric vehicle battery enclosure specifications. |
Methodological Framework
Initial hypotheses were tested against primary input from automotive OEM procurement directors, rubber compound technical directors, tier-one distributor category managers, and construction contractor specification leads and refined through secondary validation against customs trade data, SEC 10-K filings, ECHA substance notifications, and MIIT automotive regulation updates. Bottom-up volume triangulation across product format segments converged with top-down value estimates derived from extrusion capacity utilization rates.
Demand-supply balance modeling across the projection horizon incorporated vehicle production databases, building permit flows for commercial retrofit cycles, and EPDM polymer capacity announcements. Segmentation dimensions included product format, application specification, end-user procurement pattern, and cellular structure form. CAGRs were derived from elasticity-adjusted volume projections and price trajectory assumptions for SVHC-compliant versus legacy formulations.
Stress conditions across carbon black price volatility, ECHA substance restriction acceleration, and thermoplastic vulcanizate substitution penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding electric vehicle platform rollout timing and energy-efficient building code adoption trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Asia-Pacific Chromatography Resins Market
Specialty Compounds
Silk Protein Market
Specialty Compounds
Specialty Sorbents Market
Specialty Compounds
Lentein Market
Specialty Compounds
Fluoropolymer Masterbatch Market
Specialty Compounds
Phenylacetyl Chloride Market
Specialty Compounds
Global Molding Compounds Market
Specialty Compounds
Filler Masterbatch Market
Specialty Compounds
Gypsum-Free Plaster Market
Specialty Compounds
Opacifiers Market
Specialty Compounds
Middle East and Africa Specialty Chemicals Market
Specialty Compounds
Thionyl Chloride Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Global Polymer Clay Market
Specialty Compounds
Thioglycolate Market
Specialty Compounds
Hypalon Market