
 Hydroxyl Terminated Polybutadiene Market | 2026-2036
Hydroxyl Terminated Polybutadiene Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroxyl Terminated Polybutadiene Market Outlook
ISO 9001 and AS9100 certification cycles for aerospace chemical suppliers is unwinding the competitive landscape for smaller HTPB producers. Evonik Industries leverages its backward integration into butadiene feedstock to sustain cost advantages across European defense contracts. Idemitsu Kosan anchors its position through captive supply of high-purity grades to Japan's space launch programs. Cray Valley competes on specialized liquid HTPB formulations for European coatings customers seeking low-viscosity alternatives.
Hydroxyl terminated polybutadiene is a telechelic oligomer with terminal hydroxyl functionality typically ranging from 0.5 to 2.5 meq/g, manufactured through anionic polymerization of butadiene followed by termination with hydrogen peroxide or epoxide reagents. Its primary industrial purpose centers on serving as a curable binder and flexibilizing agent in solid rocket propellants, polyurethane elastomers, and high-performance adhesives requiring hydrolytic stability and low-temperature ductility. Liquid HTPB dominates volume flows into aerospace and defense applications where cast-cure processing of propellant grains demands controlled viscosity and hydroxyl equivalent weight. The coatings application segment captures widening interest as formulators seek HTPB-based binders for corrosion-resistant maritime and infrastructure protective films.
Defense procurement regulations from the US Department of Defense, REACH chemical registration requirements administered by ECHA, and India's BIS certification for strategic materials collectively shape product specifications and market access corridors for HTPB suppliers. These frameworks mandate lot-to-lot consistency in hydroxyl value and moisture content, effectively filtering out producers lacking analytical and quality management infrastructure. Stakeholders must monitor how evolving munitions export controls and domestic sourcing mandates in key defense markets redirect supply chain configurations and qualification pathways.
Market Dynamics
Defense procurement agencies across NATO member states are consolidating solid rocket motor specifications around HTPB-based binders, compressing supplier qualification timelines and favoring producers with existing aerospace certifications.
Growth Catalysts
- REACH compliance thresholds:ECHA's tightening purity standards for hydroxyl-terminated intermediates are filtering out non-compliant suppliers, concentrating aerospace-qualified production among certified chemical manufacturers.
- India's defense modernization:The Defence Research and Development Organisation is scaling domestic propellant manufacturing, creating localized demand for high-grade HTPB with traceable supply chains.
- Anionic polymerization advances:Improved termination techniques using hydrogen peroxide and epoxide reagents are yielding more consistent hydroxyl equivalent weights for precision cast-cure processing.
Market Restraints
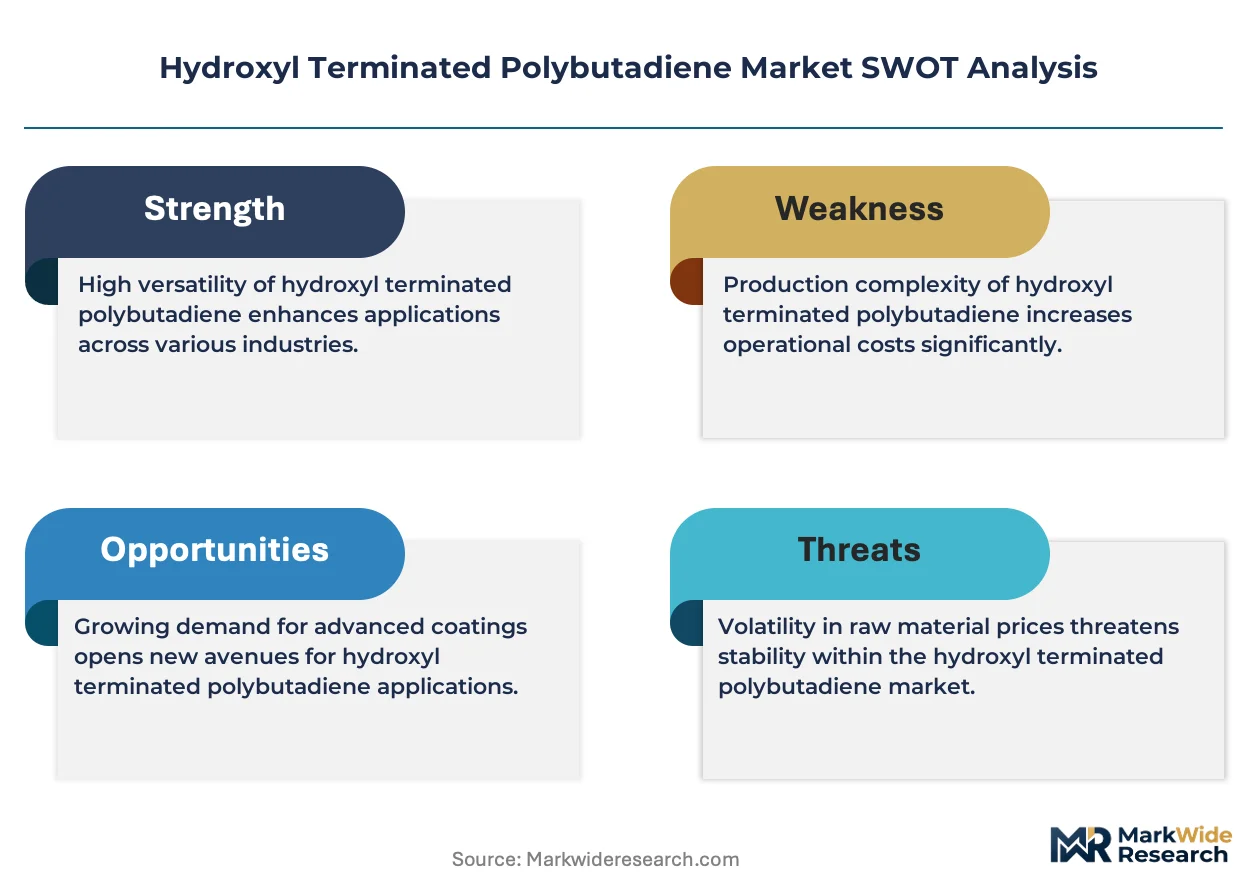
- Butadiene feedstock volatility:Crude oil price swings directly compress margins for non-integrated producers lacking captive butadiene supply.
- European supply concentration:REACH-registered HTPB production clusters among a handful of German and French chemical complexes, creating geographic vulnerability to regional energy disruptions.
- Epoxy-amine substitution:High-performance adhesive formulators in commercial aerospace are testing alternative binder chemistries for certain non-propulsive applications.
Strategic Opportunities
- Maritime coatings expansion:Formulators in South Korea are specifying HTPB-based binders for corrosion-resistant hull protection films in commercial shipping fleets.
- Japan's space launch pipeline:METI-backed programs are expanding domestic demand for liquid HTPB grades with ultra-low moisture specifications.
- AS9100 certification arbitrage:Mid-sized chemical producers in Eastern Europe can capture NATO subcontractor work by achieving aerospace quality management credentials.
Industry Challenges
- Analytical infrastructure gaps:Lot-to-lot hydroxyl value consistency requires investment in titration and spectroscopic equipment that smaller producers struggle to finance.
- Dual-use export licensing:Munitions control frameworks in the US and EU are extending qualification timelines for cross-border propellant ingredient shipments.
- Moisture specification compliance:Aerospace customers now demand sub-500 ppm moisture content, requiring nitrogen-blanketed handling systems that demand seven-figure capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroxyl Terminated Polybutadiene Market |
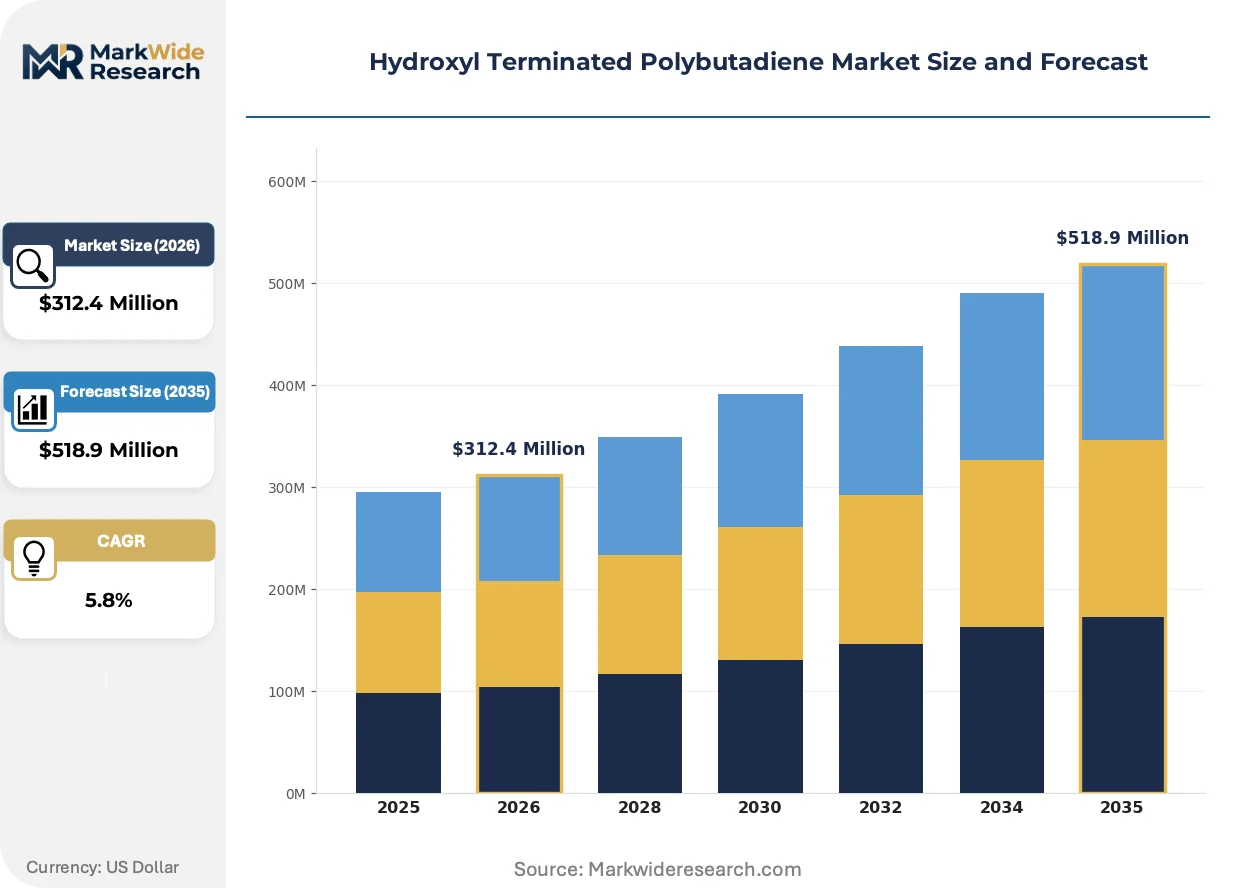
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HTPB, Liquid HTPB, Solid HTPB, HTPB Blends Application: Aerospace, Automotive, Coatings, Adhesives End User: Defense, Construction, Electronics, Pharmaceuticals Packaging Type: Drums, Containers, Bags, Bulk |
| Companies Covered | Evonik Industries, Idemitsu Kosan Co., Ltd., Cray Valley, Island Pyrochemical Industries, CRS Chemicals, BASF SE, Huntsman Corporation, LANXESS, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroxyl Terminated Polybutadiene Market Strategic Shifts
Telechelic oligomer chemistry is advancing along three distinct vectors: manufacturing precision, regulatory compliance automation, and application-specific formulation tailoring.
Low-viscosity liquid HTPB grades are decomposing the traditional tradeoff between processability and mechanical performance in solid rocket propellant binders. Indian Space Research Organisation specifications now favor these formulations for large-diameter motor casting. The technology is decomposing incumbent high-viscosity product lines in defense procurement catalogs.
REACH registration requirements administered by ECHA are mandating granular substance identity documentation for hydroxyl-terminated polybutadiene intermediates. Chemical suppliers must now submit analytical datasets covering molecular weight distribution and terminal functionality. European coatings customers are responding by consolidating purchases among registrants with complete dossiers.
Certificate-driven supplier selection is compressing procurement cycles for aerospace-qualified HTPB. Defense contractors in the United States are bypassing traditional distributor networks to contract directly with ISO 9001 and AS9100 certified manufacturers. This pattern is most visible in solid rocket motor programs where lot traceability requirements have intensified.
Hydroxyl Terminated Polybutadiene Market Segmentation
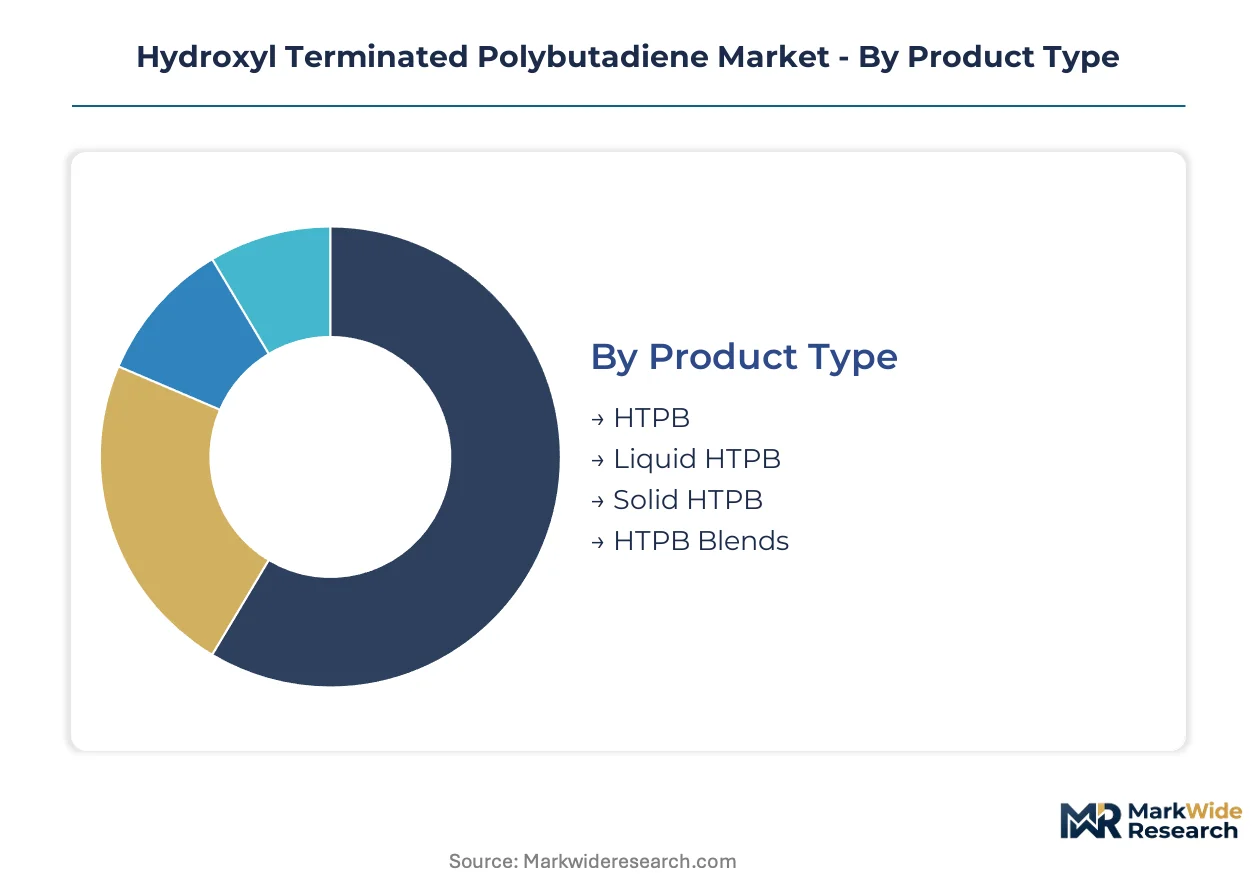
HTPB procurement decisions hinge on specification-grade requirements that vary sharply across defense, aerospace, and industrial channels. Each segment category carries distinct certification burdens and handling protocols that reshape supplier economics.
Product Type:
REACH registration thresholds and AS9100 certification cycles create divergent compliance pathways across physical forms of hydroxyl-terminated polybutadiene.
- Liquid HTPB:Low-viscosity formulations with hydroxyl equivalent weights between 40-60 meq/g enable precision cast-cure processing for solid rocket motor grains. India's Defence Research and Development Organisation has standardized liquid grades for domestic propellant manufacturing, tightening moisture specifications below 500 ppm.
- HTPB:Standard-grade telechelic oligomer serves as the baseline binder for polyurethane elastomers and general-purpose adhesives requiring hydrolytic stability. Construction sealant formulators in South Korea specify this grade for infrastructure waterproofing membranes.
- Solid HTPB:Higher molecular weight variants with controlled crystallinity provide structural integrity for molded components. Japan's METI-backed space programs source solid grades for satellite bushing applications demanding low-temperature ductility.
- HTPB Blends:Pre-formulated mixtures with plasticizers and curatives reduce processing complexity for smaller coatings manufacturers. European maritime coatings producers favor blends for corrosion-resistant hull protection films.
Liquid HTPB handles the majority of throughput; HTPB Blends are expanding most quickly on share as formulators seek simplified handling protocols.
Application:
End-use specifications cascade from defense procurement regulations through commercial aerospace and into industrial coatings channels.
- Aerospace:Solid rocket propellant binders and fuel tank sealants require lot-to-lot consistency in hydroxyl value and sub-500 ppm moisture content. NATO member defense agencies consolidate specifications around HTPB-based binders, compressing supplier qualification timelines.
- Coatings:Corrosion-resistant maritime and infrastructure protective films exploit HTPB's hydrolytic stability and UV resistance. South Korean commercial shipping fleets specify these binders for hull protection in saltwater environments.
- Automotive:Underbody sealants and vibration-damping compounds utilize HTPB's low-temperature flexibility. German automotive suppliers source REACH-registered grades for electric vehicle battery enclosure gaskets.
- Adhesives:High-performance structural bonding applications leverage the oligomer's compatibility with isocyanate curing systems. Japanese electronics manufacturers specify ultra-low moisture grades for semiconductor packaging adhesives.
Aerospace commands premium pricing tiers; Coatings demonstrates the steepest expansion trajectory as infrastructure investment accelerates.
End User:
Customer archetypes impose distinct handling, documentation, and security requirements that filter supplier participation.
- Defense:Munitions control frameworks in the US and EU extend qualification timelines for cross-border propellant ingredient shipments. India's BIS certification for strategic materials mandates traceable supply chains for domestic missile programs.
- Construction:Infrastructure waterproofing and expansion joint sealants drive volume demand for standard-grade HTPB. German civil engineering contractors specify REACH-registered products for tunnel lining applications.
- Electronics:Semiconductor packaging and flexible circuit board adhesives require ultra-high purity grades with controlled ionic content. Japanese manufacturers source through METI-qualified distributors.
- Pharmaceuticals:Limited adoption in medical device coatings and drug delivery matrix materials. US FDA scrutiny of polymer biocompatibility constrains penetration in this channel.
Defense concentrates procurement among certified suppliers; Electronics is climbing the fastest as miniaturization demands advanced adhesive binders.
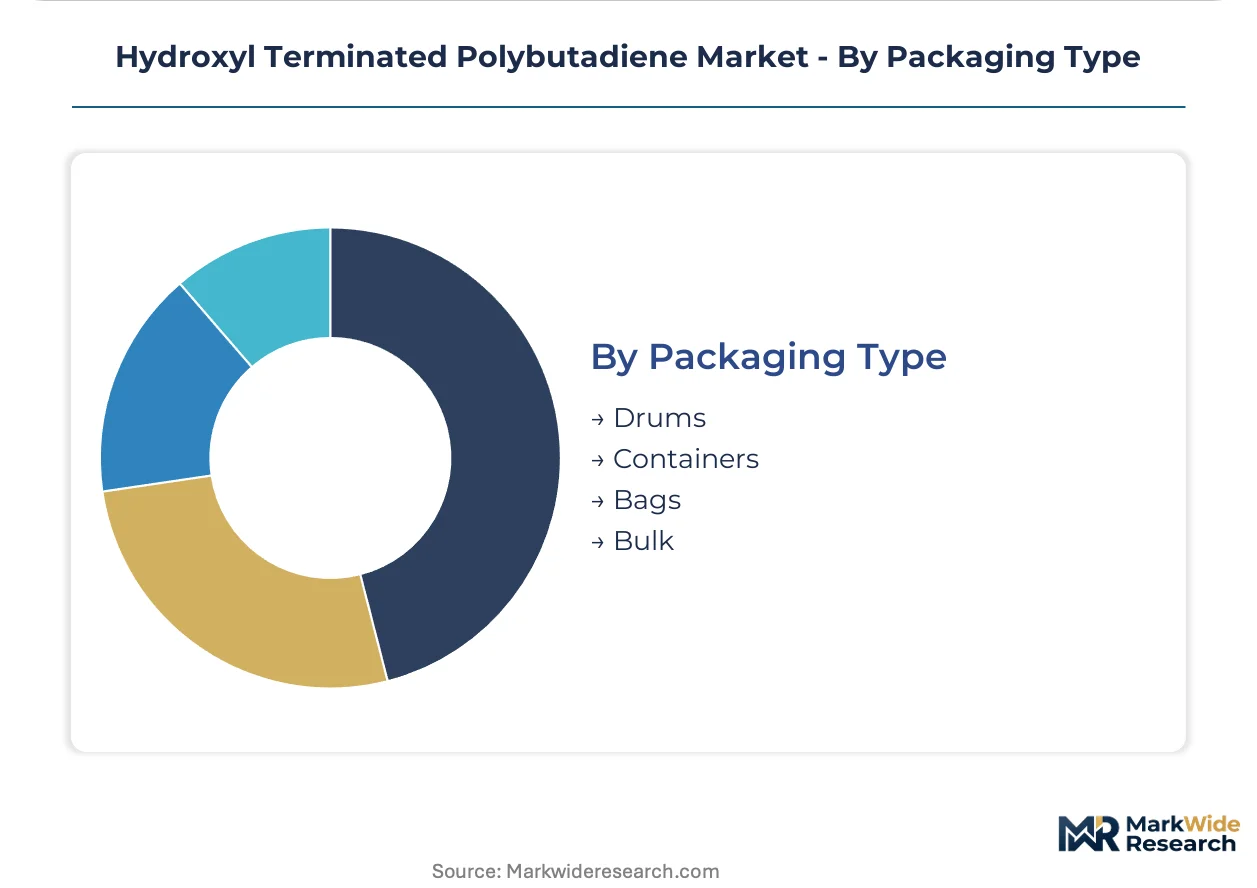
Packaging Type:
Handling infrastructure and nitrogen-blanketed storage requirements segment suppliers by capital deployment capability.
- Drums:Standard 200-liter steel drums with nitrogen padding serve aerospace and defense customers requiring lot traceability. ECHA REACH documentation accompanies each drum for European coatings formulators.
- Bulk:Tanker truck and ISO container deliveries reduce per-unit handling costs for large-scale propellant manufacturers. India's Defence Research and Development Organisation contracts specify bulk delivery for domestic blending facilities.
- Containers:Intermediate bulk containers bridge drum and bulk economics for mid-volume adhesive producers. German chemical distributors stock these for just-in-time delivery to automotive tier suppliers.
- Bags:Moisture-barrier foil bags with desiccant inserts protect solid HTPB grades during extended storage. Japanese space launch contractors require bagged formats for cleanroom handling protocols.
Bulk captures the largest volume flows; Bags gain share fastest as cleanroom handling requirements proliferate in electronics applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel petrochemical corridor underwrites North American HTPB supply security, while Rotterdam's liquid bulk terminals anchor European feedstock flows to defense contractors.
United States
Pentagon solid rocket motor programs and NASA launch vehicle procurement drive specification-grade demand. FAA and DoD munitions export controls extend qualification timelines for cross-border propellant ingredient shipments. The Gulf Coast petrochemical corridor from Houston to Lake Charles concentrates backward-integrated butadiene production serving aerospace-qualified HTPB manufacturers.
Germany
Automotive underbody sealant specifications and electric vehicle battery enclosure gaskets create industrial demand alongside defense applications. ECHA REACH registration requirements mandate granular substance identity documentation for hydroxyl-terminated intermediates. The Rhine-Ruhr chemical complex around Leverkusen and Dormagen clusters aerospace-certified production with ISO 9001 and AS9100 quality management infrastructure.
Japan
METI-backed space launch programs and satellite bushing applications expand domestic demand for ultra-low moisture HTPB grades. JIS standards and METI qualification protocols filter supplier participation in government-funded aerospace projects. The Keihin industrial corridor between Tokyo and Yokohama concentrates precision chemical manufacturing serving JAXA and private launch contractors.
India
DRDO missile program expansion and ISRO large-diameter motor casting specifications drive domestic propellant manufacturing scale-up. BIS certification for strategic materials mandates traceable supply chains with lot-to-lot hydroxyl value consistency. The Gujarat chemical belt from Vadodara to Dahej anchors new blending facilities serving India's defense modernization pipeline.
South Korea
Commercial shipping fleet hull protection specifications and infrastructure waterproofing membranes widen coatings applications. MFDS and national defense procurement frameworks impose dual-use chemical handling protocols. The Ulsan petrochemical complex integrates butadiene feedstock with specialty polymer production for maritime and aerospace customers.
Hydroxyl Terminated Polybutadiene Market Competitive Environment
Listed leaders compete with private specialists across certification infrastructure and feedstock integration. The vendor base fragments across three tiers: petrochemical majors with captive butadiene supply, mid-sized aerospace-certified specialists, and regional distributors serving industrial coatings channels. Strategic archetypes include backward-integrated polymer producers, formulation-centric compounders, and quality-management-heavy qualification specialists. Competitive moves center on AS9100 certification arbitrage for NATO subcontractor access and capacity expansion near Indian defense manufacturing clusters.
Among German chemical conglomerates, Evonik Industries and BASF SE exemplify petrochemical majors leveraging upstream butadiene control. Japanese specialists Idemitsu Kosan Co., Ltd. occupy a position within the premium-grade tier serving space launch programs with ultra-low moisture specifications. These three anchors represent distinct competitive vectors: feedstock integration, geographic proximity to defense demand, and aerospace quality management depth.
| Leading Market Players |
|---|
| Evonik Industries |
| Idemitsu Kosan Co., Ltd. |
| Cray Valley |
| Island Pyrochemical Industries |
| CRS Chemicals |
| BASF SE |
| Huntsman Corporation |
| LANXESS |
| Arkema |
| Others |
Value Chain & Pricing Dynamics
Ninety-day qualification timelines for AS9100-certified HTPB lots concentrate pricing power among German and Japanese producers with nitrogen-blanketed handling infrastructure, while spot buyers in South Korean coatings channels absorb volatility through shorter contract tenors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale. Premium tiers command spreads for REACH-registered, ultra-low-moisture grades serving JAXA and DRDO programs; standard tiers serve automotive sealant formulators with ISO 9001 documentation; economy tiers supply construction waterproofing without aerospace pedigree. Cost compression in the standard tier is intensifying because Indian domestic blending facilities are scaling captive production. Defense contractors exhibit the least price sensitivity due to lot-traceability mandates; coatings distributors in commercial shipping show highest elasticity, switching to epoxy-amine alternatives when HTPB spreads widen.
Supply Chain Analysis
Strategic stockpile preferences dominate defense procurement, with NATO agencies mandating six-month forward coverage of specification-grade HTPB, while commercial coatings buyers run just-in-time drum deliveries from Rotterdam liquid bulk terminals. Geographic concentration clusters in Germany, Japan, and the United States, with the Rhine-Ruhr and Keihin corridors anchoring aerospace-qualified output. Feedstock dependency rests on butadiene from Gulf Coast steam crackers and Ulsan naphtha crackers. Single-source vulnerability concentrates in European REACH-registered production, where energy disruptions threaten lot-to-lot consistency. Distribution runs through certified chemical distributors for drum quantities and direct tanker offtake for bulk propellant manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for propellant formulation support are expanding faster than base chemical offtake, creating recurring revenue pools for suppliers with casting-process expertise.
For Market Incumbents: Secure backward integration into butadiene feedstock or lock in long-term offtake with Gulf Coast crackers to blunt margin pressure from crude volatility. Expand AS9100-certified capacity near India's Gujarat chemical belt before BIS qualification windows narrow. Epoxy-amine substitution in commercial aerospace adhesives threatens non-defense revenue streams. For New Entrants and Emerging Players: Lead with maritime coatings formulations in South Korea, where hull protection specifications are widening faster than qualified supplier counts. Target Eastern European NATO subcontractor channels by achieving aerospace quality credentials ahead of incumbent certification cycles. Offer pre-formulated HTPB blends with plasticizers to capture smaller coatings manufacturers seeking simplified handling. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized HTPB lines lacking dedicated aerospace sales infrastructure. Five-to-ten-year viability hinges on defense procurement persistence and space launch cadence expansion. Monitor India's domestic propellant manufacturing scale-up as the inflection signal for regional supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butadiene | Captive feedstock supply from Houston Ship Channel crackers insulates margin from crude volatility. |
| AS9100 Certification Expansion | Aerospace quality credentials unlock NATO solid rocket motor subcontractor procurement channels. |
| Maritime Coatings Formulation Partnership | Collaboration with South Korean shipbuilders anchors HTPB-based hull protection film adoption. |
| Nitrogen-Blanketed Handling Infrastructure | Sub-500 ppm moisture compliance requires seven-figure capital deployment that filters out smaller competitors. |
| Long-Term Defense Supply Agreement | Multi-year offtake contracts with DRDO or Pentagon programs de-risk capacity utilization. |
Study Parameters
A standing panel of solid rocket motor program managers, aerospace procurement officers, coatings formulators, and chemical plant operations directors provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA REACH registration databases, U.S. Defense Logistics Agency procurement records, ISRO technical specifications, and customs trade data for butadiene derivative flows. Bottom-up triangulation against top-down petrochemical capacity models ensured segment-level consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled grade tier, end-use industry, packaging format, and regional production hub as segmentation dimensions. CAGRs were derived from propellant program pipeline assessments and coatings demand elasticity estimates, with cross-reference to space launch cadence projections and defense budget appropriation trajectories.
The analysis sits within stated boundaries; outcomes outside sustained defense procurement growth or REACH regulatory stability would require recalibration. Forecasts reflect assumptions regarding butadiene feedstock availability and aerospace certification cycle durations. Revision becomes warranted when epoxy-amine substitution rates in commercial adhesives cross materiality thresholds or when Indian domestic HTPB capacity achieves import substitution scale.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Pre-Dispersed Rubber Chemicals Market
Rubber
Tire Softener Market
Rubber
Rubber Foam Materials Market
Rubber
Co-Extruded Rubber Profiles Market
Rubber
Solution Styrene Butadiene Rubber (S-SBR) Market
Rubber
Rubber Accelerators Market
Rubber
Rubber Extruder Market
Rubber
Rubber Masterbatch Market
Rubber
Nitrile Butadiene Rubber Market
Rubber
Rubber Sand Market
Rubber
Europe Rubber Derived Unrefined Pyrolysis Oil Market
Rubber
Global Cast Elastomers Market
Rubber
Metallurgical Rubber Roller Market
Rubber
Isoprene Rubber (IR) Latex Market
Rubber
Rubber Gloves Market
Rubber
Polyisoprene Market