
 Europe Rubber Derived Unrefined Pyrolysis Oil Market | 2026-2036
Europe Rubber Derived Unrefined Pyrolysis Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Rubber Derived Unrefined Pyrolysis Oil Market Foresight
Asset-light leasing models for pyrolysis reactor modules is narrowing the capital barrier for mid-scale entrants. Pyrum leverages its proprietary continuous pyrolysis technology to sustain engineering margins on turnkey plant deliveries. Quantafuel AS anchors its competitive position through backward integration into feedstock preprocessing and refining know-how. Fortum Oyj differentiates by dominating utility-scale offtake contracting with Nordic cement and lime producers.
Europe rubber derived unrefined pyrolysis oil is a dark, viscous liquid produced through thermal decomposition of end-of-life tires in oxygen-starved conditions, typically containing 30-40% aromatic hydrocarbons, sulfur levels above 1.5 wt%, and heating values comparable to heavy fuel oil; its primary commercial purpose is serving as a drop-in burner fuel for cement kilns, lime calciners, and industrial boilers that tolerate higher sulfur and ash content than refined distillates. Crude pyrolysis oil occupies the largest volume share given minimal downstream processing requirements, while chemical feedstock applications are expanding fastest as refiners test hydrotreating pathways to extract benzene, toluene, and xylene fractions. Vacuum distilled oil commands premium pricing where sulfur reduction enables compliance with tighter emissions standards.
REACH registration requirements and the EU Green Deal's waste hierarchy enforcement through the Waste Framework Directive are tightening feedstock traceability and end-product classification rules for pyrolysis operators. ECHA's evolving guidance on recovered substance status directly determines whether outputs qualify as products or remain regulated as waste, shaping market access economics across member states. Stakeholders must monitor how the F-Gas Regulation's indirect pressure on synthetic rubber disposal costs interacts with national transpositions of the revised Industrial Emissions Directive to anticipate feedstock availability and plant siting constraints.
Market Dynamics
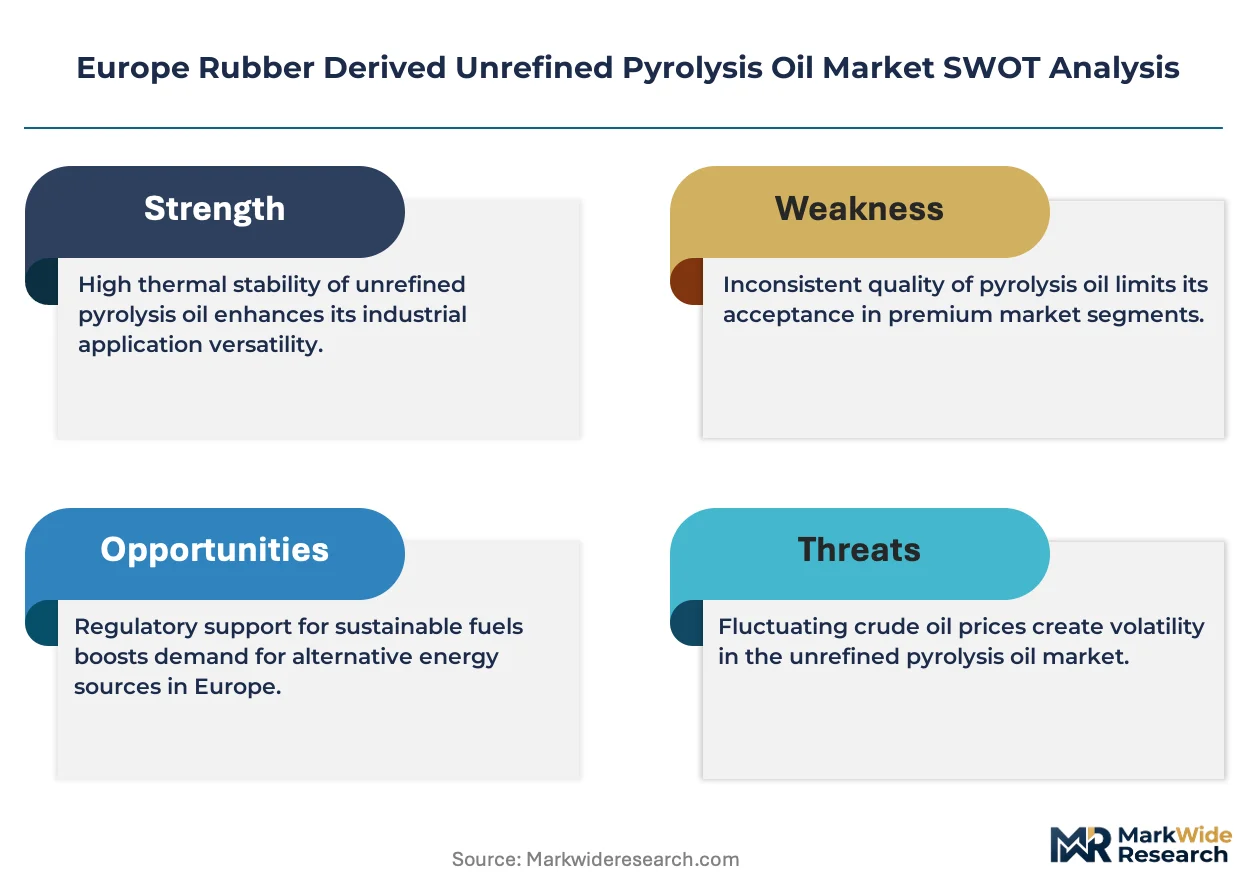
The EU Green Deal's waste-to-energy mandates are compressing permitting timelines for pyrolysis installations while cement kilns absorb larger fuel volumes as natural gas cost volatility persists.
Growth Catalysts
- Waste Framework Directive enforcement:The EU Green Deal's waste hierarchy mandates are accelerating feedstock traceability systems and end-product classification clarity for pyrolysis operators.
- Cement kiln fuel substitution:German lime calciners and clinker producers are absorbing rising volumes of unrefined pyrolysis oil as heavy fuel oil alternatives face carbon pricing pressure.
- Continuous reactor engineering:Proprietary continuous pyrolysis systems are narrowing capital barriers for mid-scale entrants through modular, asset-light deployment models.
Market Restraints
- Sulfur content ceiling:Unrefined pyrolysis oil's 1.5 wt% sulfur levels restrict offtake to industrial burners with flue gas desulfurization, excluding marine and transport fuel markets.
- Feedstock concentration risk:End-of-life tire collection infrastructure clusters in Germany, Poland, and the Netherlands, creating geographic supply vulnerability for peripheral plant locations.
- REACH registration friction:ECHA's evolving recovered substance guidance creates classification uncertainty that shapes market access economics across member states.
Strategic Opportunities
- Hydrotreating pathway development:Refiners testing benzene, toluene, and xylene extraction from crude pyrolysis oil are opening chemical feedstock applications with premium pricing potential.
- Nordic utility-scale contracting:Fortum Oyj's dominance in cement and lime offtake agreements demonstrates replicable contract structures for Baltic and Scandinavian market entry.
- F-Gas Regulation tailwinds:Synthetic rubber disposal cost pressure from fluorinated gas restrictions is expanding feedstock availability for integrated tire pyrolysis operators.
Industry Challenges
- Process engineering talent scarcity:Continuous pyrolysis reactor optimization requires specialized thermal decomposition expertise that competes with broader chemical engineering labor markets.
- ECHA compliance timeline compression:Recovered substance status determinations under REACH create permitting delays that extend project financing windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Rubber Derived Unrefined Pyrolysis Oil Market |
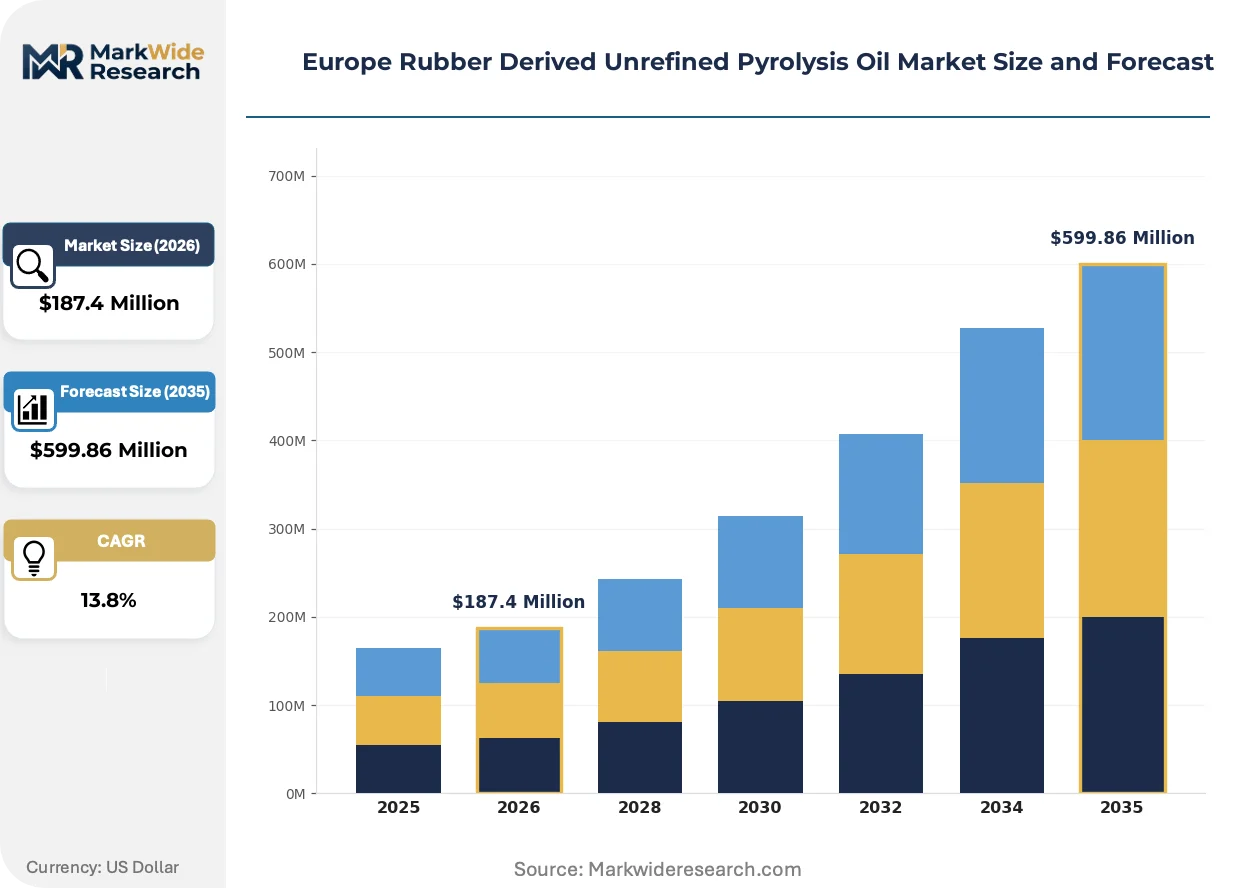
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $599.86 Million |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Distilled Oil, Crude Pyrolysis Oil, Char, Water End Use Industry: Fuel Oil, Chemical Manufacturing, Road Construction, Power Generation Application: Industrial Heating, Energy Generation, Material Recovery, Chemical Feedstock Collection Method: Batch Collection, Continuous Collection, Automated Collection, Manual Collection |
| Companies Covered | Biogreen (ETIA Group), No-Waste-Technology GmbH, Green Fuel Nordic Oy, Nexus Circular, Plastic Energy, Fortum Oyj, Twence B.V., Quantafuel AS, Pyrum, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Rubber Derived Unrefined Pyrolysis Oil Market Shifts & Advancements
Modular reactor deployment and hydrotreating R&D are compressing the gap between waste-derived fuel and refined chemical feedstock markets.
Continuous pyrolysis reactor systems with real-time temperature control and automated char removal are rendering obsolete batch-mode tire decomposition units that suffer from energy inefficiency and inconsistent oil quality. Cement producers in the Rhine-Ruhr industrial cluster are adopting these systems at pilot scale, with full commercial deployment expected within two permitting cycles. The technology shift is compressing payback periods for plant operators and squeezing margins for engineering firms without proprietary continuous designs.
REACH registration requirements and the EU Green Deal's waste hierarchy enforcement through the Waste Framework Directive are tightening feedstock traceability mandates across member states. ECHA's evolving guidance on recovered substance status directly determines whether pyrolysis outputs qualify as products or remain regulated as waste, reshaping market access economics. Operators in Germany and the Netherlands are responding by investing in blockchain-based tire provenance tracking and third-party certification systems.
Long-term offtake contracting with utility-scale cement and lime producers is displacing spot-market fuel oil sales as the dominant commercial model. Nordic industrial heat users are consolidating procurement through multi-year supply agreements that bundle feedstock preprocessing, logistics, and emissions compliance documentation. This pattern is most visible in Sweden and Finland, where Fortum Oyj's contracting template has standardized risk allocation between pyrolysis operators and fuel buyers.
Europe Rubber Derived Unrefined Pyrolysis Oil Market Segmentation
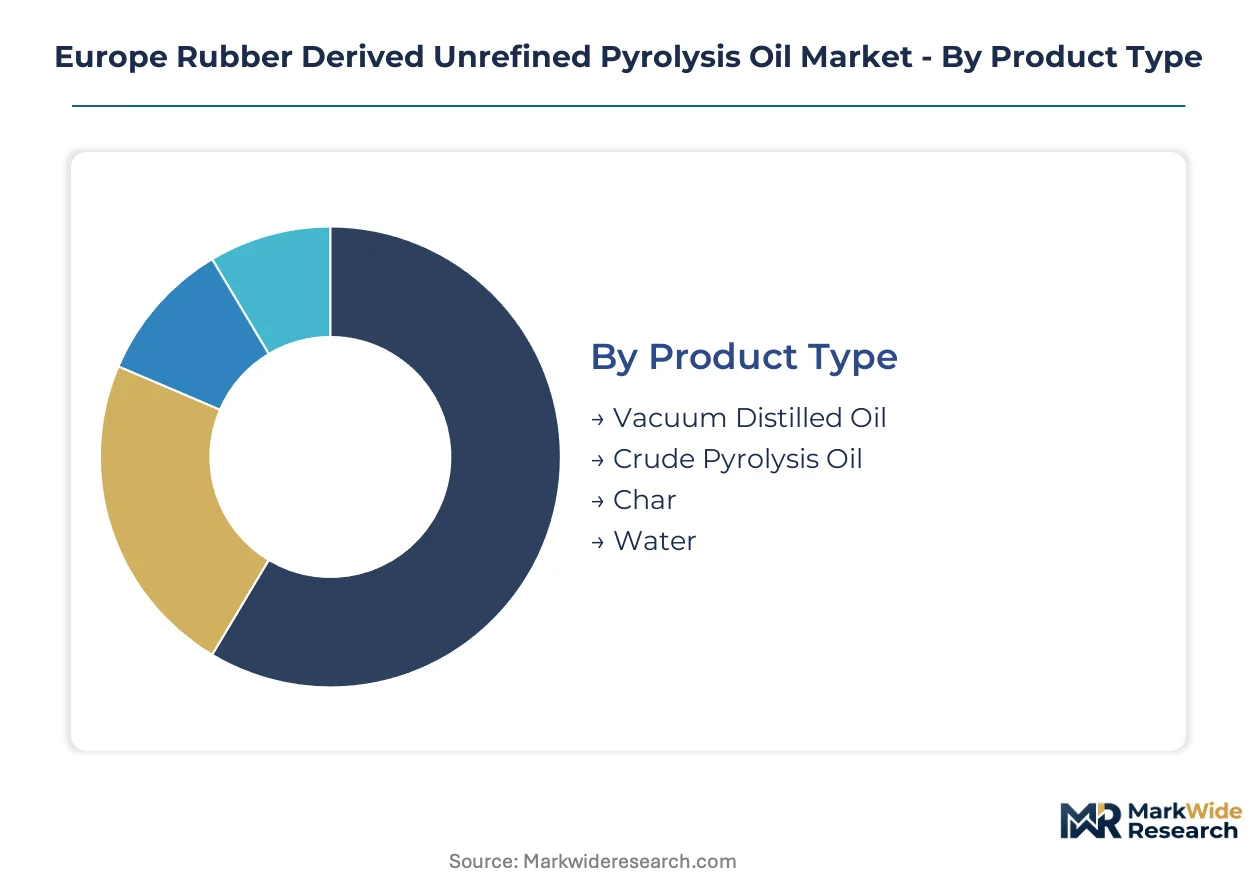
Segmentation reveals how pyrolysis operators balance processing complexity against market access. Product differentiation and collection technology choices directly determine which end-use sectors remain reachable under tightening EU emissions rules.
Product Type:
Mature refining pathways dominate revenue capture, while emerging purification technologies unlock premium market tiers.
- Crude Pyrolysis Oil:A dark viscous liquid containing 30-40% aromatic hydrocarbons and sulfur above 1.5 wt%, requiring no downstream processing. Cement kilns in Germany's Rhine-Ruhr cluster absorb the largest volumes as carbon pricing erodes heavy fuel oil competitiveness.
- Vacuum Distilled Oil:Partially refined through fractional distillation to reduce sulfur and ash content, enabling compliance with stricter industrial emissions standards. Dutch lime calciners and Nordic cement producers pay premium pricing for this grade where flue gas desulfurization capacity is limited.
- Char:Solid carbon residue from tire decomposition, used as reinforcement filler or fuel supplement. Polish rubber recyclers are developing char upgrading pathways for carbon black replacement in tire manufacturing.
- Water:Condensed aqueous phase containing dissolved organics and inorganics, typically requiring wastewater treatment before discharge. Some operators in the Netherlands are testing water fraction recycling for process heat recovery.
Crude pyrolysis oil retains volume leadership; vacuum distilled oil holds the steepest expansion curve.
End Use Industry:
Cost tier differentiation separates commodity fuel applications from higher-margin chemical valorization pathways.
- Fuel Oil:Direct combustion in cement kilns, lime calciners, and industrial boilers tolerating elevated sulfur content. German clinker producers have established the deepest offtake infrastructure, with multi-year supply contracts now standard.
- Chemical Manufacturing:Hydrotreated fractions yielding benzene, toluene, and xylene for petrochemical feedstock. Refiners in Belgium and the Netherlands are piloting this pathway as REACH registration clarity improves recovered substance classification.
- Road Construction:Binder modification and asphalt rejuvenation using selected pyrolysis fractions. Polish infrastructure contractors are testing rubber-derived binders for noise-reduction surfacing layers.
- Power Generation:Boiler fuel for district heating and industrial cogeneration. Finnish utility Fortum Oyj has anchored this segment through integrated waste-to-energy contracting.
Fuel oil applications retain volume leadership; chemical manufacturing holds the steepest expansion curve.
Application:
Customer type stratification mirrors the sulfur tolerance and emissions compliance requirements of distinct thermal energy users.
- Industrial Heating:Direct burner fuel for process heat in energy-intensive manufacturing. Cement and lime producers across Germany, Poland, and the Netherlands constitute the primary demand concentration.
- Energy Generation:Combustion for electricity and district heat production. Nordic utilities are consolidating procurement through standardized long-term offtake templates.
- Material Recovery:Extraction of carbon black, steel wire, and inorganics from tire decomposition. Belgian operators are optimizing char upgrading for tire industry circularity mandates.
- Chemical Feedstock:Refined aromatic streams for downstream petrochemical synthesis. Hydrotreating investments by Dutch refiners are accelerating this application's commercial viability.
Industrial heating retains volume leadership; chemical feedstock holds the steepest expansion curve.
Collection Method:
Volume throughput and labor intensity trade-offs determine facility economics across different operational scales.
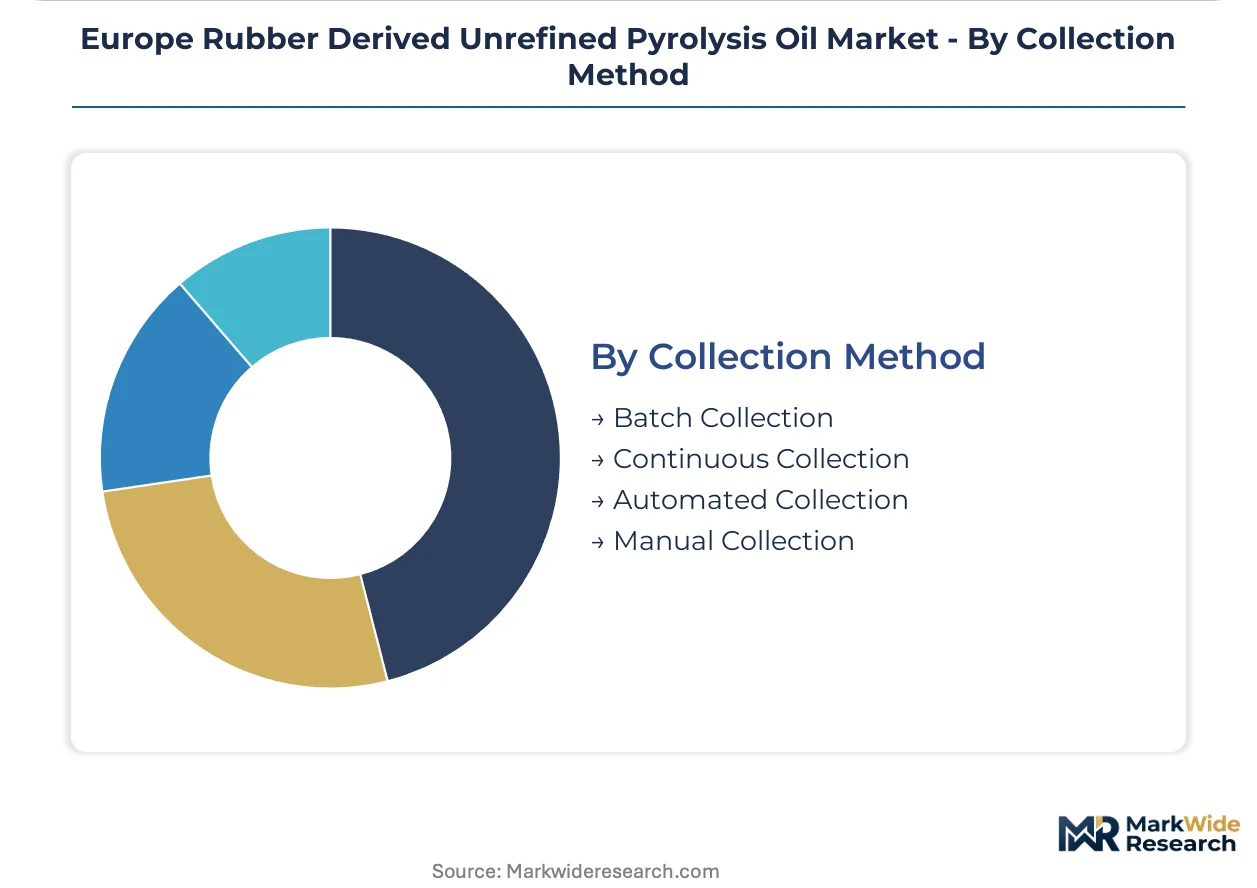
- Continuous Collection:Automated real-time oil and char extraction with temperature-controlled decomposition. Pyrum's proprietary reactor systems have established engineering leadership in this category, compressing payback periods for mid-scale entrants.
- Batch Collection:Intermittent processing cycles with manual intervention between runs. Smaller Polish and Baltic operators still deploy this mode where capital constraints limit technology upgrading.
- Automated Collection:Sensor-driven separation with minimal labor input, typically integrated with continuous reactor designs. German pilot installations are validating this approach for scale-up replication.
- Manual Collection:Labor-intensive handling of decomposition products, predominant in legacy facilities and developing regulatory environments. ECHA compliance timelines are accelerating phase-out of this mode.
Continuous collection retains volume leadership; automated collection holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows within the region reflect a net importer dynamic, with Nordic and Baltic markets sourcing processed volumes from German and Dutch pyrolysis clusters while exporting shredded tire feedstock westward.
Germany
Cement kilns in the Rhine-Ruhr industrial corridor absorb the largest regional volumes of unrefined pyrolysis oil as carbon pricing erodes heavy fuel oil competitiveness. The country's federal emissions trading authority enforces strict flue gas monitoring standards that favor continuous reactor systems with consistent output quality. Pyrum operates multiple installations across the Saarland and Rhineland-Palatinate regions, supplying long-term offtake contracts with Heidelberg Materials and other clinker producers.
Netherlands
Rotterdam's petrochemical complex hosts pilot hydrotreating facilities testing benzene, toluene, and xylene extraction from crude pyrolysis fractions. Dutch regulators under the National Institute for Public Health and the Environment enforce stringent REACH compliance timelines that accelerate operator investment in feedstock traceability systems. Limburg province harbors the densest concentration of tire shredding and preprocessing capacity, feeding both domestic pyrolysis units and export flows to German industrial consumers.
Poland
Lower Silesia and the Upper Silesian Industrial Region concentrate tire collection infrastructure serving both domestic pyrolysis operators and cross-border feedstock shipments. Polish waste management regulations under the Chief Inspectorate of Environmental Protection mandate extended producer responsibility schemes that expand end-of-life tire availability. Katowice-based recyclers are developing char upgrading pathways for carbon black replacement, targeting circularity mandates from domestic tire manufacturers.
Sweden
Nordic cement and lime producers consolidate procurement through standardized multi-year supply agreements that bundle logistics and emissions compliance documentation. Swedish environmental courts under the Land and Environment Court system enforce the EU Industrial Emissions Directive with stringent permitting reviews that favor established operators with proven continuous reactor technology. The Stora Enso industrial cluster in Varkaus anchors utility-scale offtake contracting replicated across Finnish and Norwegian markets.
Belgium
Antwerp's refining hub hosts experimental hydrotreating investments testing chemical feedstock applications for pyrolysis-derived aromatic streams. Belgian federal regulators coordinate with ECHA on recovered substance classification determinations that shape market access economics for cross-border operators. The Port of Antwerp-Bruges logistics zone concentrates feedstock preprocessing and intermediate storage capacity serving both domestic consumers and export markets into northern France and western Germany.
Europe Rubber Derived Unrefined Pyrolysis Oil Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: engineering-led technology licensors, integrated waste-to-energy utilities, and specialized feedstock processors. Proprietary continuous reactor designs differentiate the top tier, while mid-scale entrants compete on modular deployment speed and asset-light leasing structures. Dominant competitive moves include backward integration into tire shredding and preprocessing, plus long-term offtake contracting with cement and lime producers that locks in volume commitments.
Within the technology-licensor tier, Pyrum and Quantafuel AS exemplify divergent strategic positions—Pyrum anchors engineering margins on turnkey plant deliveries, while Quantafuel AS occupies a position emphasizing feedstock preprocessing integration. Fortum Oyj represents the utility-scale contracting archetype, demonstrating replicable contract structures across Nordic markets. These three entities collectively illustrate how competitive positioning in this market depends on choosing between technology monetization, feedstock control, or offtake consolidation as the primary value capture mechanism.
| Leading Market Players |
|---|
| Biogreen (ETIA Group) |
| No-Waste-Technology GmbH |
| Green Fuel Nordic Oy |
| Nexus Circular |
| Plastic Energy |
| Fortum Oyj |
| Twence B.V. |
| Quantafuel AS |
| Pyrum |
| Others |
Supply & Pricing Matrix
The Rhine-Ruhr industrial cluster anchors European pyrolysis oil capacity, with its concentration of continuous reactor installations granting German operators pricing leverage over Nordic cement buyers facing natural gas cost volatility. Limburg province's preprocessing infrastructure feeds cross-border arbitrage opportunities that compress margins for peripheral Baltic operators lacking feedstock integration.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing, with cement and lime producers locking in multi-year supply agreements that bundle logistics and emissions compliance documentation. Price differentiation rests on sulfur content grade and REACH registration certification tier, with vacuum distilled oil commanding premium positioning over crude pyrolysis fractions. Cost compression in the crude oil tier is intensifying as modular reactor deployment expands feedstock processing capacity. Small-scale lime calciners in Poland exhibit the highest price sensitivity, while Heidelberg Materials and other Rhine-Ruhr clinker producers demonstrate lowest sensitivity due to carbon pricing exposure on conventional fuel alternatives.
Supply Chain Analysis
Tariff exposure between Germany and Poland dominates supply chain risk assessment, as cross-border feedstock shipments face evolving waste classification scrutiny under national transpositions of the Waste Framework Directive. Geographic supply concentration centers on Germany, the Netherlands, and Poland, where tire shredding infrastructure intersects with industrial heat demand clusters. Raw material dependencies draw from end-of-life tire collection networks, steel wire recovery streams, and synthetic rubber disposal volumes from F-Gas Regulation compliance. Single-source vulnerability characterizes the feedstock tier, with Limburg and Katowice preprocessing hubs creating chokepoint exposure. Distribution runs through barge and rail networks serving cement kiln clusters, with Rotterdam-Antwerp-Bruges logistics zones consolidating intermediate storage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe rubber derived unrefined pyrolysis oil represents an early-cycle expansion story, with EU Green Deal waste-to-energy mandates accelerating permitting velocity and cement kiln fuel substitution creating durable demand anchoring.
For Market Incumbents: Build regulatory moats through REACH registration completion and recovered substance status determinations ahead of ECHA timeline compression. Cement kiln offtake contracting with Nordic utilities locks in volume commitments that emerging modular entrants cannot replicate. Threat vectors include hydrotreating R&D by Dutch refiners that could bypass unrefined oil tiers entirely. Capacity addition in the Baltic states extends geographic coverage while feedstock preprocessing integration defends margin position against Polish collection infrastructure expansion. For New Entrants and Emerging Players: Pursue automated collection technology deployment in Sweden and Finland, where Fortum Oyj's contracting template has standardized procurement but supplier concentration remains limited. The chemical feedstock application segment offers the most penetrable white space, with Belgian and Dutch refiners piloting benzene-toluene-xylene extraction pathways that lack established pyrolysis oil suppliers. Go-to-market positioning should emphasize blockchain-based tire provenance tracking to preempt ECHA compliance requirements that disadvantage legacy batch-mode operators. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among engineering-led technology licensors with proprietary continuous reactor designs and long-term offtake backlogs. The five-to-ten year viability window favors operators with demonstrated ECHA engagement and utility-scale contracting templates replicable across Nordic markets. Acquisition target archetypes include mid-scale Polish and Baltic operators with feedstock collection infrastructure but lacking refining technology integration. Watch for hydrotreating investment announcements by Rotterdam-Antwerp refining complexes as the signal indicating chemical feedstock pathway commercialization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Preprocessing | Limburg tire shredding capacity secures supply control for German pyrolysis operators facing collection infrastructure competition. |
| Long-term Supply Agreement with Cement Producers | Heidelberg Materials multi-year offtake contracts in Rhine-Ruhr anchor volume visibility against spot market volatility. |
| Green Certification Program for Recovered Substances | ECHA-compliant blockchain traceability unlocks product classification advantages under REACH registration pathways. |
| Capacity Expansion in Nordic Markets | Swedish and Finnish utility-scale contracting templates replicate Fortum Oyj's procurement consolidation model. |
| Technology Licensing for Continuous Reactor Systems | Pyrum's proprietary designs compress payback periods for mid-scale entrants through modular deployment. |
Research Methodology
Initial hypotheses were tested against primary input from pyrolysis plant managers, cement procurement leads, tire collection infrastructure operators, and ECHA regulatory affairs specialists, then refined through secondary validation. Bottom-up triangulation combined customs and trade data on tire-derived fuel flows, Cefic chemical industry reports, SEC filings from listed waste-to-energy utilities, and national waste framework transposition documents. Top-down cross-checks anchored market sizing against EU Green Deal implementation timelines and Industrial Emissions Directive enforcement patterns.
Demand-supply balance framing structured the analytical approach across the analysis window, with segmentation dimensions spanning product type tiers, end-use industry verticals, application categories, and collection method technologies. CAGRs were derived from installed capacity buildout trajectories, offtake contract velocity, and feedstock availability projections. Industry-specific forecast inputs incorporated carbon pricing trajectory assumptions for German clinker producers and F-Gas Regulation disposal cost pressures on synthetic rubber waste streams.
Sensitivities concentrate around ECHA recovered substance guidance revisions, hydrotreating R&D commercialization timelines, and cement sector carbon border adjustment mechanism implementation. Forecasts reflect modeling assumptions on permitting velocity under EU Green Deal mandates and tire collection infrastructure expansion rates. Material shifts in REACH registration classification outcomes or Nordic utility procurement consolidation patterns would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
EPDM Rubber Market
Rubber
Industrial Rubber Market
Rubber
Hospital Rubber Sheet Market
Rubber
Rubber Accelerators Market
Rubber
Industrial Rubber Products Market
Rubber
Global Tire Material Market
Rubber
Polyisoprene Market
Rubber
Rubber Carbon Black Market
Rubber
Global Automotive Elastomers Market
Rubber
Rubber Plated Hose Market
Rubber
Conductive Silicone Rubber Market
Rubber
Rubber Extruder Market
Rubber
Global Chloroprene Rubber Market
Rubber
Specialty Nitrile Butadiene Rubber (NBR) Market
Rubber
Rubber Seal Plugs Market
Rubber
Acrylic Rubber Market