
 Rubber Bulbs Market | 2026-2036
Rubber Bulbs Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Bulbs Market Intelligence
The EU Green Deal is decoupling European medical device procurement from virgin latex dependency, creating pull-through demand for certified sustainable rubber formulations. Walter Stern, Inc. anchors North American laboratory supply chains through backward integration into custom-molded bulb production. SciLab Korea Co., Ltd. leverages domestic synthetic rubber capacity to serve Asia-Pacific diagnostic instrument makers with ISO-compliant components.
Rubber bulbs are elastomeric vessels—typically natural latex, neoprene, or silicone—manufactured via dip molding or compression molding to create airtight, flexible chambers that generate negative pressure for fluid transfer or vacuum applications. Medical-grade bulbs require biocompatibility testing under ISO 10993 and tensile strength specifications exceeding 15 MPa to withstand repeated sterilization cycles. Pneumatic and mechanical product types dominate current volume, with specialty bulbs capturing expanding margin pools in surgical robotics and point-of-care diagnostics. The automotive application segment sustains steady offtake for brake bleeding and fluid extraction tools, while medical applications lead growth trajectory amid ambulatory care expansion.
The US FDA enforces Quality System Regulation 21 CFR Part 820 for medical device component suppliers, compelling rubber bulb manufacturers to maintain validated sterilization processes and batch traceability. EMA's Medical Device Regulation (MDR) and REACH chemical restrictions jointly elevate compliance costs for European market access, favoring producers with in-house testing laboratories. China's NMPA and GB standards for rubber medical products add a third compliance layer for exporters serving hospital procurement tenders. Stakeholders must monitor evolving biocompatibility testing protocols and regional substitution incentives for petroleum-derived synthetic elastomers.
Market Dynamics
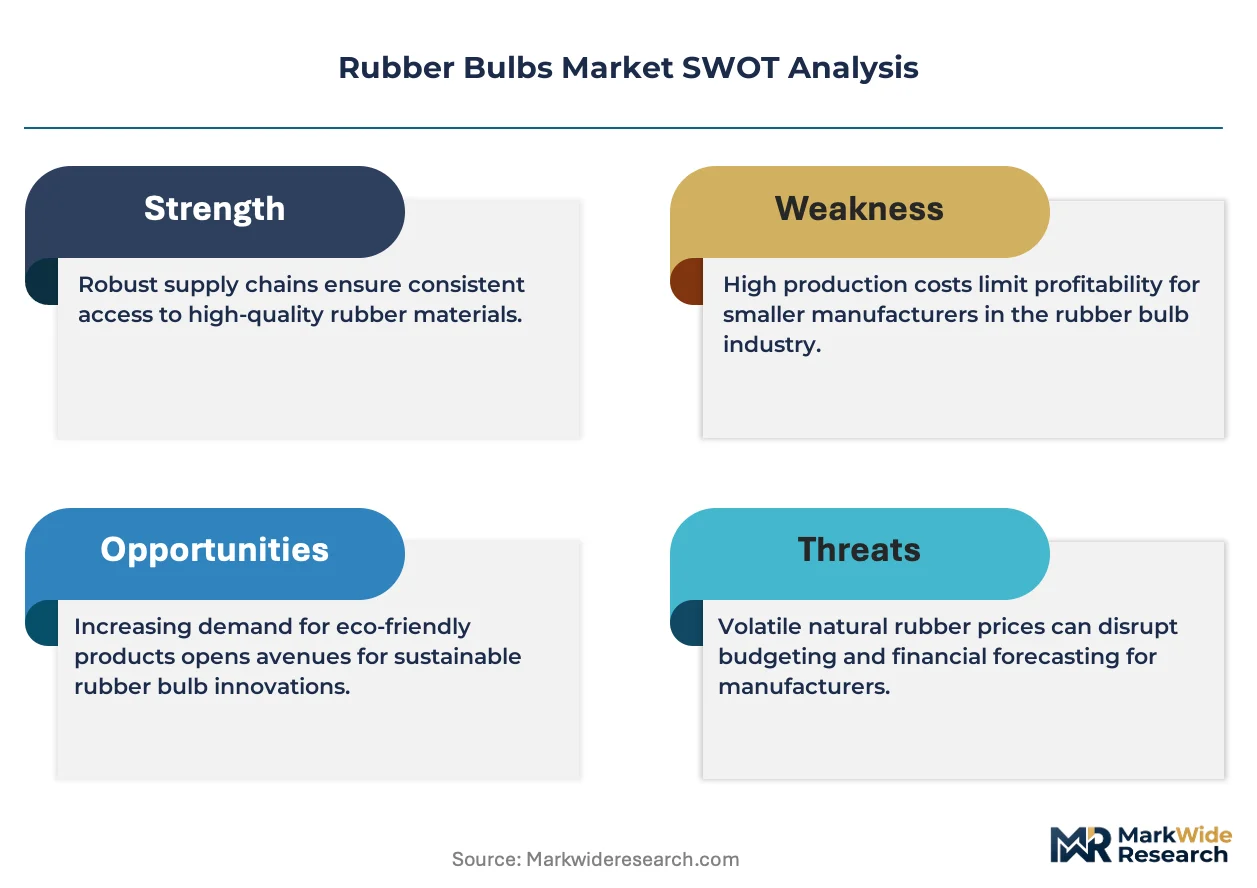
Medical device procurement is tightening material compliance standards across elastomeric components, with biocompatibility testing protocols and chemical substance restrictions now filtering supplier qualification at the component level rather than finished-device level.
Growth Catalysts
- Ambulatory care expansion:Surgical robotics manufacturers and point-of-care diagnostic instrument makers are scaling orders for precision-molded bulbs capable of withstanding repeated sterilization cycles.
- EU Green Deal substitution mandates:Certified sustainable rubber formulations are displacing virgin latex in European hospital procurement tenders, creating pull-through demand for compliant component suppliers.
- ISO 10993 testing standardization:Harmonized biocompatibility protocols are reducing regulatory friction for cross-border medical device component trade.
Market Restraints
- Petroleum-derived synthetic elastomer input costs:Neoprene and silicone feedstock prices track crude oil volatility, compressing margin stability for compounders without long-term supply contracts.
- German precision equipment supply concentration:Specialized rubber component fabrication clusters in Baden-Württemberg and Bavaria create geographic single-point-of-failure risk for just-in-time medical device assembly.
- REACH chemical restriction scope expansion:ECHA's evolving substance of very high concern list forces iterative reformulation of existing bulb compounds, extending product development timelines.
Strategic Opportunities
- Surgical robotics integration:Miniaturized pneumatic bulb architectures for robotic suction instruments represent uncontracted white space in OEM component portfolios.
- India PLI scheme medical device incentives:Domestic synthetic rubber capacity expansion near Mumbai and Chennai offers tariff-advantaged sourcing for export-oriented diagnostic instrument assembly.
- Direct-to-laboratory e-procurement channels:Research institutions and clinical laboratories are bypassing traditional distribution tiers for standardized bulb SKUs, compressing channel margin capture.
Industry Challenges
- Compound formulation chemist scarcity:Specialized expertise in medical-grade elastomer curing and sterilization validation commands premium compensation, constraining R&D throughput at mid-tier manufacturers.
- EMA MDR technical documentation assembly:Extended conformity assessment timelines for notified body review of component-level biological safety data delay market access for new bulb specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Bulbs Market |
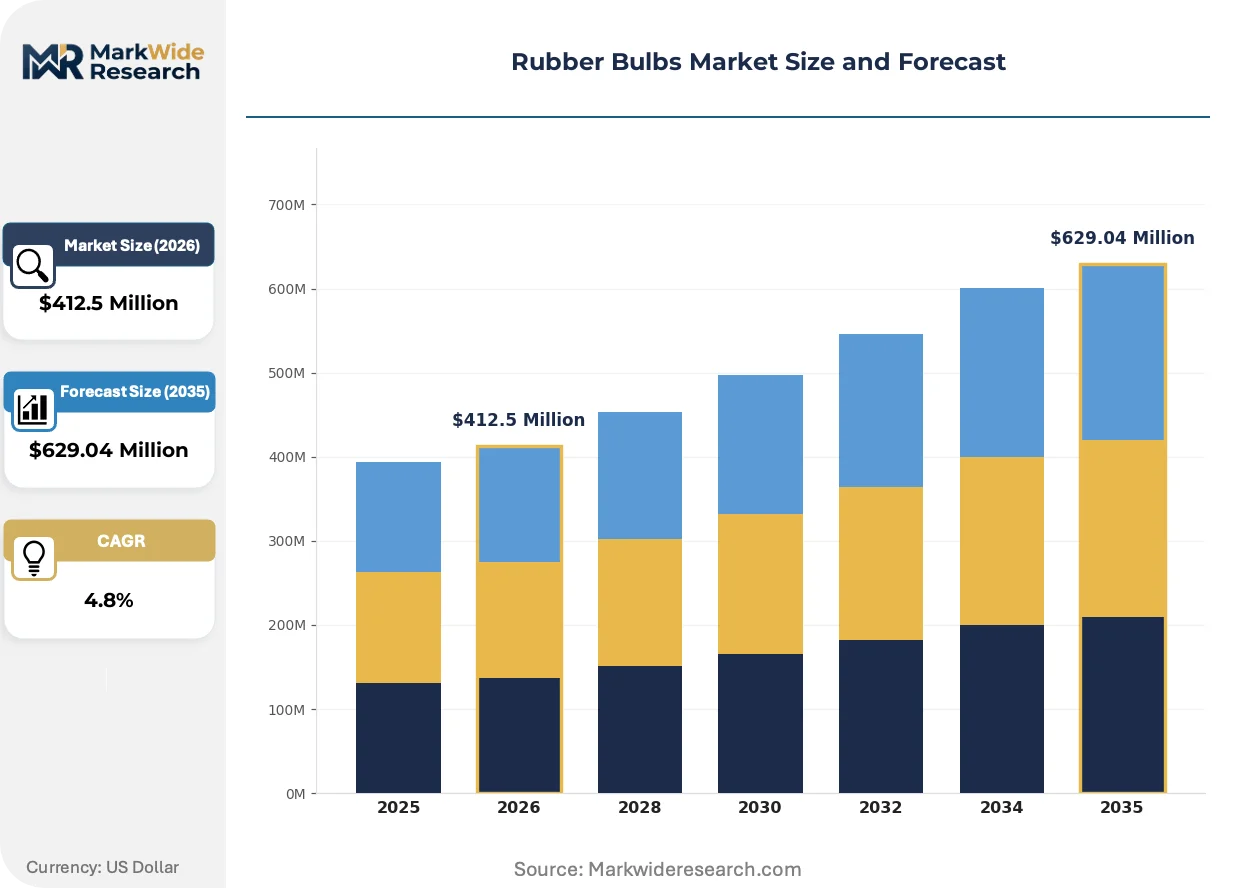
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic, Mechanical, Industrial, Specialty End User: Manufacturers, Retailers, Distributors, Importers Application: Automotive, Medical, Agriculture, Consumer Goods Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesalers |
| Companies Covered | Walter Stern, Inc., SciLab Korea Co., Ltd., North American Latex Corporation, BPL Medical Technologies, Rubbertron Industries, GSC International, Inc., United Scientific Supplies, Abbott Rubber Company, Aero Rubber Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Bulbs Market Strategic Shifts & Innovations
Material science advances and regulatory harmonization efforts are compressing product development cycles while elevating performance thresholds for elastomeric components in critical-care applications.
Silicone-overmolded hybrid bulb architectures are converging with thermoplastic elastomer substrates to create multi-durometer suction instruments capable of withstanding gamma sterilization without compression set degradation. Cardiovascular device OEMs in Switzerland and the United States are piloting these compounds for catheter aspiration functions. This convergence is compressing the traditional latex-silicone-neoprene material segmentation into unified performance-tier sourcing categories.
EMA's Medical Device Regulation (MDR) Article 10 general safety and performance requirements are compelling rubber bulb suppliers to maintain validated sterilization processes and batch traceability systems equivalent to finished-device manufacturers. Industrial consequence includes mandatory quality management system certification for component-only vendors previously exempt from 21 CFR Part 820 scope. German and French notified bodies are experiencing 14-18 month backlog for initial manufacturer audits, forcing early-stage suppliers toward MDSAP pathway alignment.
Hospital procurement consortia are consolidating component sourcing decisions at integrated delivery network level rather than individual facility purchasing, compressing supplier qualification to pre-approved vendor list status. Group purchasing organizations in the United States and National Health Service supply chain hubs in England are displacing independent distributor relationships with direct manufacturer contracts. This concentration is most visible in academic medical center networks where standardization incentives override legacy supplier preferences for suction and aspiration instrument consumables.
Rubber Bulbs Market Segmentation
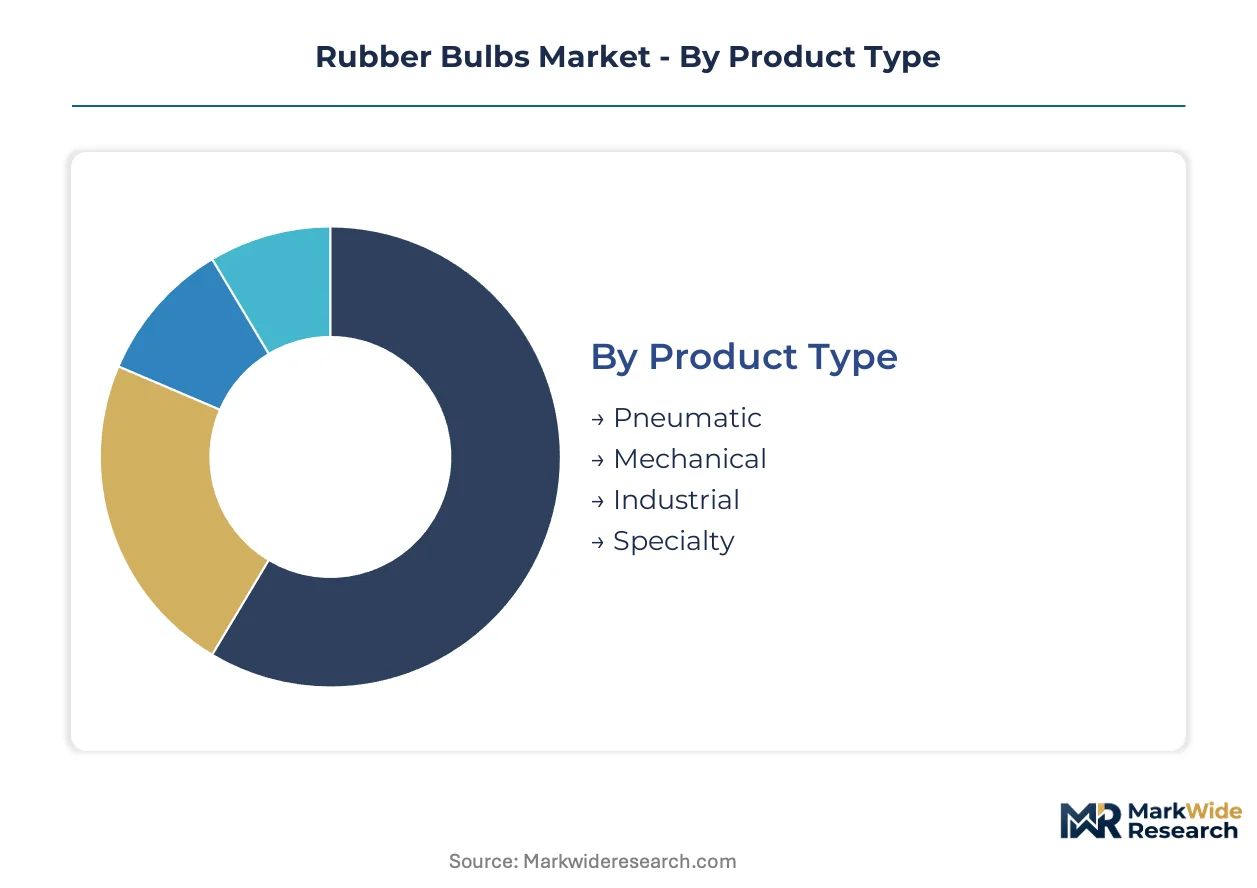
Segmentation in the rubber bulbs market reveals how upgrade cycles and compliance requirements reshape procurement across product tiers. Component specifications now diverge sharply between legacy equipment maintenance and next-generation device integration.
Product Type:
Replacement-cycle intensity varies dramatically by bulb architecture, with sterilization-tolerant designs commanding extended service intervals and premium positioning.
- Pneumatic:These bulbs generate negative pressure through manual compression of elastomeric chambers, typically molded from natural latex or silicone compounds rated for 500+ compression cycles. Demand clusters in German precision medical equipment manufacturing, where ISO 10993 biocompatibility certification filters supplier qualification for suction instrument OEMs.
- Mechanical:Spring-assisted or lever-actuated bulb mechanisms reduce operator fatigue in high-frequency clinical settings, incorporating thermoplastic elastomer seals alongside traditional rubber bodies. Swiss cardiovascular device manufacturers specify these architectures for catheter aspiration functions requiring consistent vacuum pressure across repeated sterilization protocols.
- Industrial:Neoprene and EPDM formulations dominate fluid extraction tools for automotive brake bleeding and agricultural chemical handling, prioritizing chemical resistance over medical-grade certification.
- Specialty:Miniaturized pneumatic architectures for surgical robotics integrate multi-durometer silicone-overmolded hybrids capable of gamma sterilization without compression set degradation.
Volume placements concentrate in Pneumatic; the faster expansion belongs to Specialty.
End User:
Customer-type economics stratify sharply between specification owners and fulfillment intermediaries, with backward integration pressure reshaping margin capture.
- Manufacturers:Medical device OEMs and laboratory instrument makers source certified rubber components directly, maintaining validated sterilization processes and batch traceability under FDA Quality System Regulation. These buyers consolidate procurement at integrated delivery network level, compressing supplier qualification to pre-approved vendor lists.
- Retailers:Scientific supply chains and clinical laboratory distributors stock standardized bulb SKUs for research institutions, facing disintermediation pressure from direct-to-laboratory e-procurement channels.
- Distributors:Regional medical device distributors maintain inventory buffers for just-in-time assembly operations, absorbing working capital requirements that manufacturers increasingly internalize.
- Importers:Trading companies facilitate cross-border component flows, navigating EMA MDR technical documentation requirements and REACH chemical restriction compliance for European market access.
Margin capture tilts toward Manufacturers; Distributors face the steepest compression from channel consolidation.
Application:
End-use performance requirements create distinct material specification tiers, with sterilization tolerance and chemical resistance driving formulation selection.
- Medical:Suction and aspiration instruments for surgical robotics, point-of-care diagnostics, and ambulatory care settings demand tensile strength exceeding 15 MPa and validated biocompatibility under ISO 10993. EU Green Deal substitution mandates are displacing virgin latex with certified sustainable rubber formulations in hospital procurement tenders.
- Automotive:Brake bleeding kits and fluid extraction tools sustain steady offtake for neoprene bulbs, with petroleum-derived synthetic elastomer input costs tracking crude oil volatility.
- Agriculture:Chemical-resistant bulbs for pesticide handling and irrigation systems prioritize EPDM compounds over medical-grade specifications.
- Consumer Goods:Household cleaning appliances and personal care devices utilize lower-specification natural latex formulations with minimal regulatory compliance overhead.
Revenue concentration sits with Medical; Automotive maintains the most stable replacement-cycle predictability.
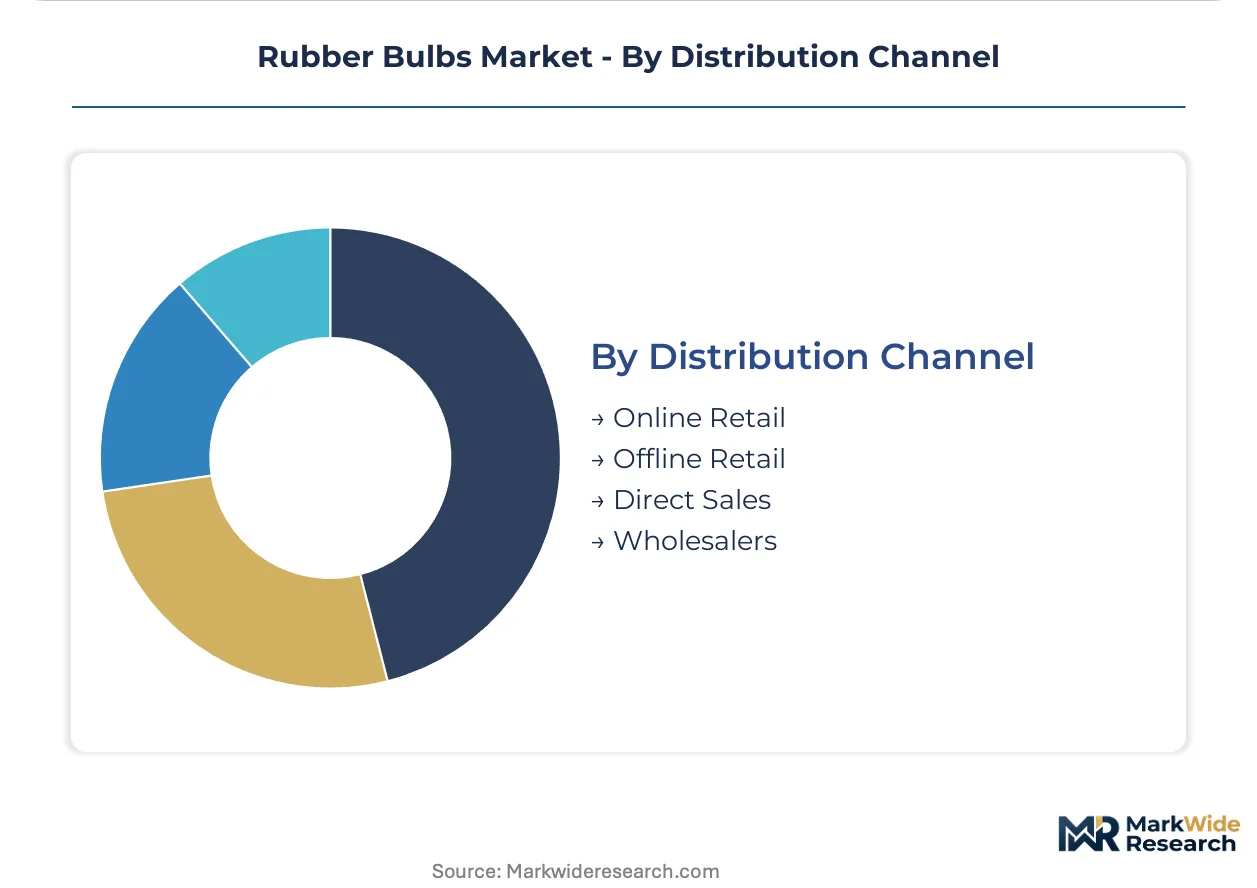
Distribution Channel:
Channel economics reflect the tension between specification complexity and procurement efficiency, with digital intermediaries gaining share in standardized segments.
- Online Retail:E-procurement platforms serving research institutions and clinical laboratories bypass traditional distribution tiers, compressing channel margin capture for standardized bulb SKUs.
- Offline Retail:Brick-and-mortar scientific supply stores maintain local inventory for emergency replacement needs, though footprint consolidation accelerates.
- Direct Sales:Medical device OEMs contract directly with rubber bulb manufacturers for custom-molded components, mandating validated sterilization processes and batch traceability equivalent to finished-device requirements.
- Wholesalers:Industrial distributors aggregate demand from automotive and agricultural equipment makers, offering chemical-resistant bulb assortments without medical-grade certification premiums.
Direct Sales commands the highest value per transaction; Online Retail is gaining share fastest in standardized laboratory supply categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg and Bavaria anchor European rubber bulb fabrication, with precision medical equipment clusters in Stuttgart and Munich driving specialized component demand for surgical robotics OEMs.
United States
Surgical robotics manufacturers in Massachusetts and Minnesota scale orders for precision-molded bulbs capable of gamma sterilization. FDA Quality System Regulation 21 CFR Part 820 compels component suppliers to maintain validated batch traceability. Walter Stern, Inc. anchors North American laboratory supply chains through backward integration into custom-molded production.
Germany
Precision medical equipment producers source specialized rubber components for suction and aspiration instruments. EU REACH chemical substance restrictions and EMA Medical Device Regulation elevate compliance costs for market access. Stuttgart's medical technology corridor concentrates fabrication of ISO 10993-certified elastomer components for export-oriented device assembly.
Switzerland
Cardiovascular device OEMs pilot silicone-overmolded hybrid bulb architectures for catheter aspiration functions. Swissmedic biocompatibility requirements align with EMA MDR technical documentation standards. Basel and Zurich host precision molding operations serving robotic surgery instrument makers with multi-durometer compound expertise.
China
Domestic synthetic rubber capacity expansion supports diagnostic instrument assembly for export markets. NMPA and GB standards for rubber medical products add compliance layers for hospital procurement tenders. Yangtze River Delta manufacturing hubs near Shanghai supply standardized bulb SKUs to Asia-Pacific laboratory distributors.
South Korea
Domestic synthetic rubber producers serve Asia-Pacific diagnostic instrument makers with ISO-compliant components. MFDS medical device regulations harmonize with international biocompatibility testing protocols. SciLab Korea Co., Ltd. leverages regional polymer capacity to supply precision-molded bulbs for point-of-care diagnostic platforms.
Rubber Bulbs Market Key Industry Players
The competitive structure tilts toward mid-tier specialists with validated sterilization capabilities and batch traceability systems. Fragmentation persists among regional compounders lacking medical-grade certification, while consolidation pressure mounts from OEM direct-sourcing mandates. Three archetypes dominate: integrated laboratory suppliers with captive molding capacity, synthetic rubber compounders serving diagnostic instrument makers, and precision medical component specialists. Capacity expansion and M&A activity concentrate among firms securing notified body certification for EMA MDR compliance.
Among North American fabricators, Walter Stern, Inc. and North American Latex Corporation occupy positions within the integrated supply tier, exemplifying backward integration strategies that compress channel margins. SciLab Korea Co., Ltd. represents the Asia-Pacific synthetic rubber compounder archetype, anchoring regional diagnostic instrument supply chains.
| Leading Market Players |
|---|
| Walter Stern, Inc. |
| SciLab Korea Co., Ltd. |
| North American Latex Corporation |
| BPL Medical Technologies |
| Rubbertron Industries |
| GSC International, Inc. |
| United Scientific Supplies |
| Abbott Rubber Company |
| Aero Rubber Company, Inc. |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between ISO 10993-certified medical bulbs and commodity-grade industrial formulations splits both pricing power and supply chain configurations across the rubber bulbs market. Premium medical-grade suppliers in Germany and Switzerland command validated sterilization premiums, while automotive and agricultural buyers in China and India source uncertified neoprene through spot-market channels with minimal compliance overhead.
Pricing Analysis
Gamma sterilization tolerance anchors value-based pricing for surgical robotics integration, with multi-durometer silicone-overmolded hybrids capturing sustained premiums over natural latex alternatives. Price differentiation rests on ISO 10993 certification tier and batch traceability depth, with FDA-registered suppliers extracting margin premiums from OEM direct contracts. Cost compression in commodity pneumatic bulbs intensifies because petroleum-derived synthetic elastomer feedstock volatility compresses compounder margins. Research institutions and clinical laboratories exhibit highest price sensitivity through e-procurement platforms, while cardiovascular device OEMs in Switzerland demonstrate lowest sensitivity given sterilization validation requirements.
Supply Chain Analysis
India's PLI scheme medical device incentives are reshaping sourcing patterns for export-oriented diagnostic instrument assembly near Mumbai and Chennai. Geographic supply concentration centers on Germany, China, and South Korea, with Baden-Württemberg precision clusters, Yangtze River Delta manufacturing hubs, and domestic synthetic rubber capacity near Seoul serving distinct tier requirements. Raw material dependencies draw from natural latex plantations in Southeast Asia, petroleum-derived neoprene from South Korean petrochemical complexes, and medical-grade silicone from German specialty chemical producers. Single-source vulnerability concentrates in German precision equipment supply clusters, where just-in-time medical device assembly creates geographic concentration risk. Distribution runs through direct manufacturer contracts for medical OEMs and e-procurement platforms for standardized laboratory SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone-overmolded hybrid architectures are displacing legacy latex-neoprene material segmentation, compressing procurement categories into unified performance-tier sourcing frameworks. This technology transition rewards suppliers with multi-durometer compound expertise and gamma sterilization validation capabilities.
For Market Incumbents: Cement sterilization validation leadership by securing MDSAP pathway alignment ahead of German and French notified body audit backlogs. Deepen backward integration into custom-molded production to capture channel margin compression from direct-to-laboratory e-procurement growth. Defend against synthetic rubber compounder entrants by locking long-term supply contracts with petroleum feedstock producers.
For New Entrants and Emerging Players: Begin with surgical robotics miniaturized pneumatic bulb architectures, where uncontracted white space exists in OEM component portfolios. Target India PLI scheme zones near Chennai for tariff-advantaged synthetic rubber sourcing serving export diagnostic instrument assembly. Pursue hospital procurement consortia qualification at integrated delivery network level rather than individual facility penetration.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier specialists possessing in-house ISO 10993 testing laboratories given EMA MDR technical documentation assembly delays. Long-term viability favors compounders with validated gamma sterilization processes and batch traceability equivalent to finished-device manufacturers. Watch ECHA substance of very high concern list expansions as inflection indicators forcing iterative reformulation and consolidation among undercapitalized regional players.
| Strategic Initiative | Industry Significance |
|---|---|
| MDSAP Pathway Alignment | Accelerates FDA, Health Canada, and TGA market access for component suppliers facing notified body backlogs. |
| Backward Integration into Custom Molding | Walter Stern's captive production model compresses distributor margins and secures laboratory supply chain anchoring. |
| India PLI Zone Capacity Addition | Tariff-advantaged synthetic rubber sourcing serves export-oriented diagnostic instrument assembly from Mumbai-Chennai corridor. |
| Silicone-Overmolded Hybrid Development | Swiss cardiovascular OEM pilots converge multi-durometer architectures with gamma sterilization tolerance for catheter aspiration. |
| Direct-to-Laboratory E-Procurement Channel | SciLab Korea leverages regional polymer capacity to bypass traditional distribution tiers for standardized bulb SKUs. |
Research Approach
Document review covered FDA 510(k) filings, EMA MDR technical documentation, and REACH substance restriction updates, complemented by interviews with medical device OEM procurement directors, rubber compounder R&D leads, hospital GPO contract managers, and notified body auditors. Secondary validation drew from ISO 10993 biocompatibility testing protocols, customs trade data for elastomer imports, and SEC filings from integrated laboratory suppliers. Bottom-up segment sizing triangulated against top-down medical device production forecasts across the analysis window.
Segment-level outputs for pneumatic, mechanical, industrial, and specialty bulb architectures combined with medical, automotive, agricultural, and consumer goods application splits. Manufacturer, retailer, distributor, and importer end-user economics modeled separately. CAGRs derived from sterilization cycle intensity trends, ambulatory care expansion rates, and EU Green Deal substitution mandate implementation pacing. Surgical robotics integration timelines and point-of-care diagnostic platform rollouts informed specialty segment trajectory.
Underlying measurement precision varies by segment; medical-grade certified bulbs carry tighter precision than commodity industrial formulations due to regulatory documentation depth. Forecasts reflect assumptions on REACH chemical restriction scope expansion, petroleum feedstock volatility, and notified body audit clearance rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Chloroprene Rubber Modified Asphalt Emulsion Market
Rubber
EPDM Market
Rubber
Rubber Carbon Black Market
Rubber
Rubber Accelerators Market
Rubber
Conductive Silicone Rubber Market
Rubber
Rubber Rollers Market
Rubber
Chloro-Sulfonated Polyethylene Market
Rubber
Silicone Rubber Market
Rubber
Rubber Foam Market
Rubber
Carboxylated Nitrile Rubber Market
Rubber
Rubber Wear Liners Market
Rubber
Global Rubber Coated Fabrics Market
Rubber
Rubber Seal Plugs Market
Rubber
Rubber Roller Cleaner Market
Rubber
Global Hydraulic Rubber Hose Market
Rubber
Hospital Rubber Sheet Market