
 Turkey Marine Lubricants Market | 2026-2036
Turkey Marine Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Marine Lubricants Market Analytics
ISO 8217 marine fuel quality certification is redrawing supplier eligibility in Turkey's marine lubricants sector. Petrol Ofisi A.S. leverages its coastal terminal network to dominate bulk deliveries through Izmir and Mersin. Shell & Turcas Petrol A.S. anchors its position via technical service partnerships with Turkish shipyards along the Sea of Marmara. Fuchs Lubricants Turkey differentiates through specialized stern tube and hydraulic system formulations for the local fishing fleet.
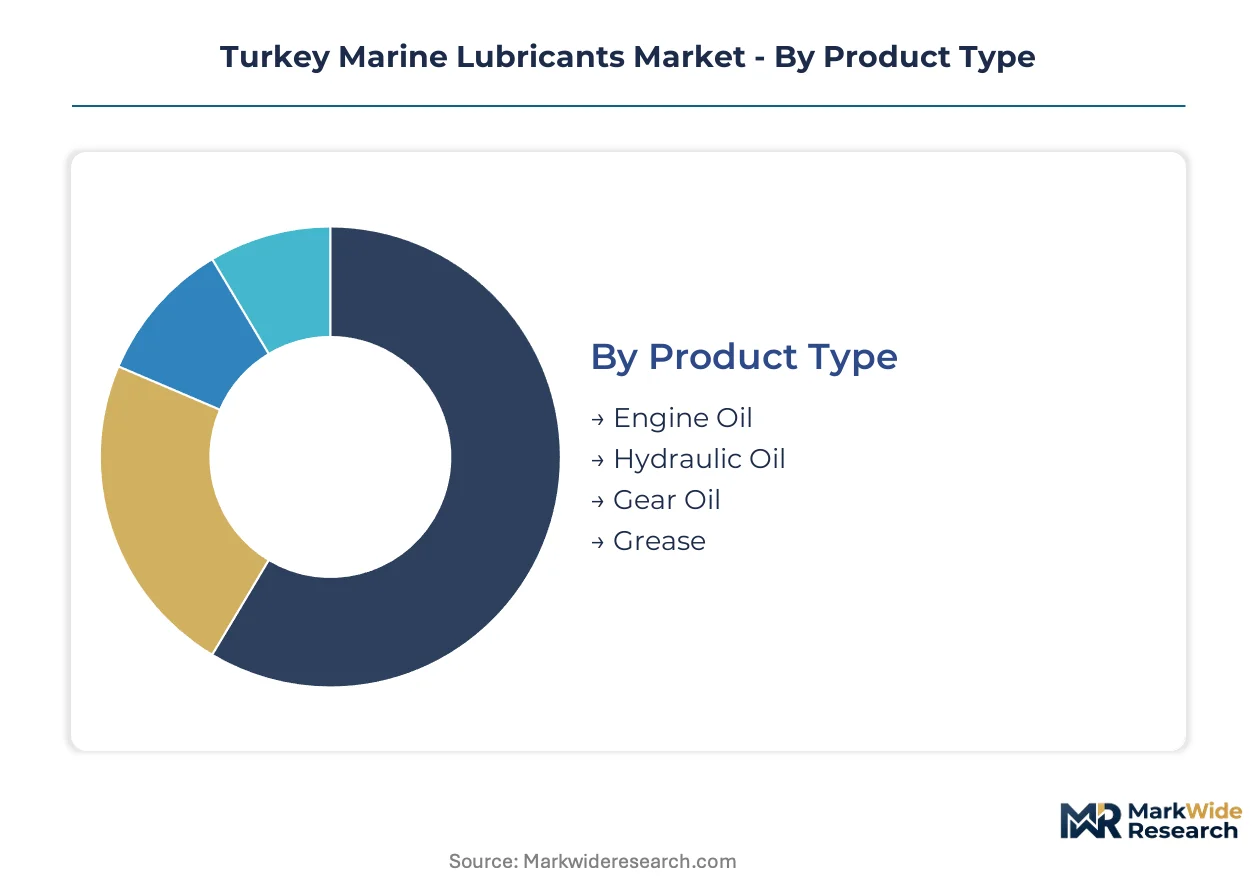
Marine lubricants are formulated base oil and additive packages engineered to withstand high-salinity corrosion, extreme pressure loading, and extended drain intervals in propulsion and auxiliary systems. These products typically incorporate detergents, dispersants, anti-wear agents, and alkaline reserve components measured by total base number (TBN) to neutralize acidic combustion byproducts from residual fuel operation. Engine oil commands the largest volume share among product types, reflecting the installed base of two-stroke crosshead and four-stroke trunk piston engines serving Turkish commercial shipping. Hydraulic oil represents the fastest-expanding category, driven by dynamic positioning systems and deck machinery upgrades on vessels calling at Ceyhan and Aliaga. Gear oil and grease maintain stable demand tied to winch, crane, and steering gear maintenance cycles.
Turkish Ministry of Transport and Infrastructure port state control directives align with MARPOL Annex VI emission standards, compelling lubricant reformulation for vessels operating under the Turkish flag. The country's national environmental regulator enforces waste oil handling protocols that shape collection and re-refining economics at major bunkering points. Stakeholders must monitor how sulfur cap enforcement and EU carbon border adjustment mechanisms redirect vessel routing through Turkish straits, altering lubricant consumption patterns at Istanbul and Canakkale transit hubs.
Market Dynamics
IMO 2020 low-sulfur fuel compliance is forcing cylinder oil reformulation across Turkish-flagged fleets, as residual fuel sulfur content limits tighten engine oil alkalinity requirements and drain interval specifications.
Growth Catalysts
- Turkish Ministry of Transport port state control directives:MARPOL Annex VI alignment compels lubricant specification upgrades for vessels under national flag, pulling volume through Istanbul bunkering terminals.
- Dynamic positioning systems:Hydraulic oil demand accelerates as offshore support vessels and tankers upgrade deck machinery at Ceyhan and Aliaga.
- Marmara and Aegean port clusters:Bunker fuel switching activity concentrates procurement decisions among fleet operators maintaining Turkish registry.
Market Restraints
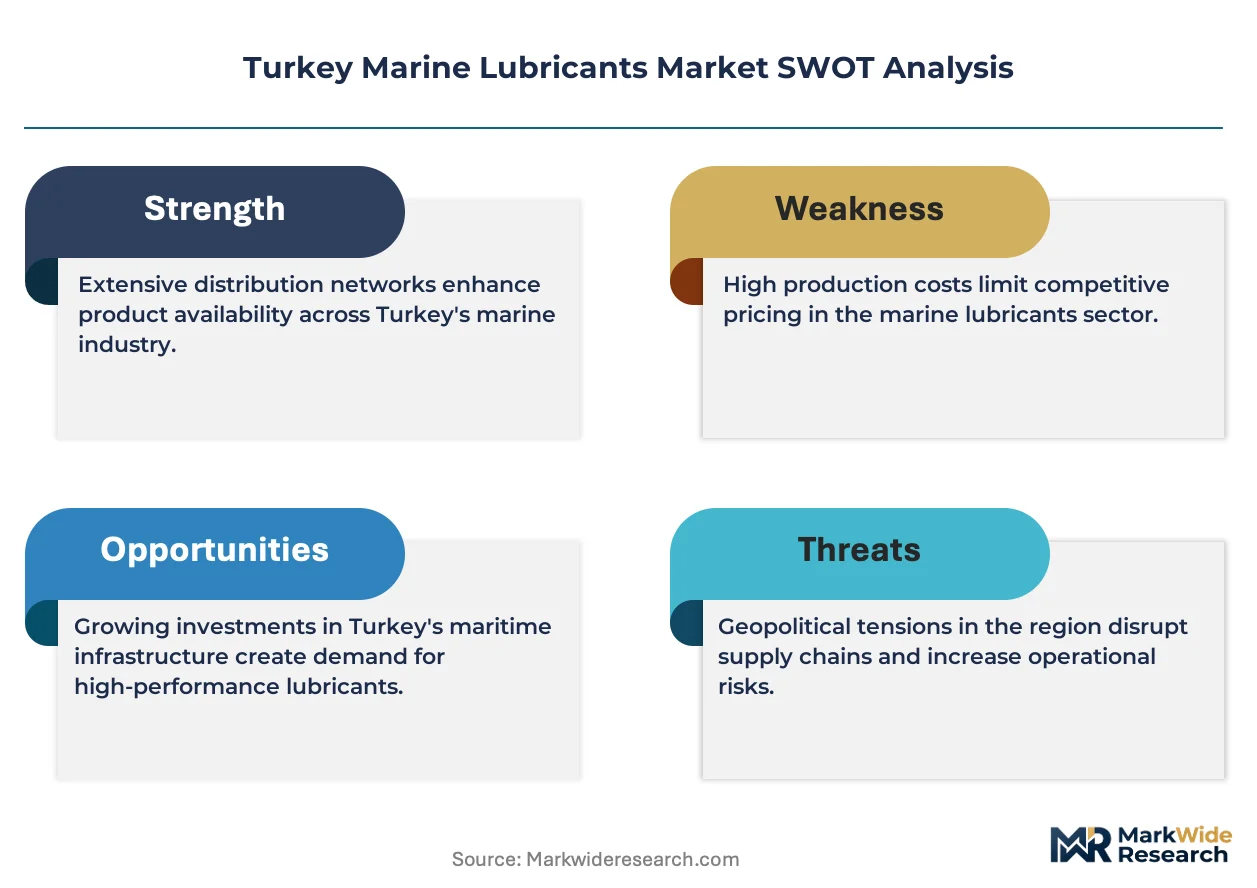
- Group II/III base oil import dependency:Turkey lacks domestic API Group II/III production, exposing blenders to freight and feedstock volatility from Middle Eastern and European suppliers.
- Collection infrastructure gaps:Waste oil handling protocols enforced by the national environmental regulator create uneven re-refining economics outside Mersin and Izmir.
- Residual fuel acidity:High-sulfur residual fuel combustion produces corrosive byproducts that accelerate TBN depletion, shortening drain intervals and raising consumption costs.
Strategic Opportunities
- Black Sea coastal terminals:Samsun and Trabzon remain underpenetrated for specialized stern tube formulations serving regional fishing and short-sea fleets.
- EU carbon border adjustment mechanisms:Vessel routing through Turkish straits may intensify as carbon pricing redirects traffic, elevating lubricant throughput at Canakkale transit points.
- Re-refining technology convergence:Vacuum distillation and hydrotreating advances enable circular base oil recovery from collected marine waste streams.
Industry Challenges
- Lubricant engineer certification timelines:OEM approval processes for new cylinder oil formulations extend 18-24 months, delaying product launches for MAN Energy Solutions and Wärtsilä engine platforms.
- Legacy two-stroke engine compatibility:Low-sulfur cylinder oils require seal and liner material upgrades on older crosshead engines, complicating fleet-wide specification harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Marine Lubricants Market |
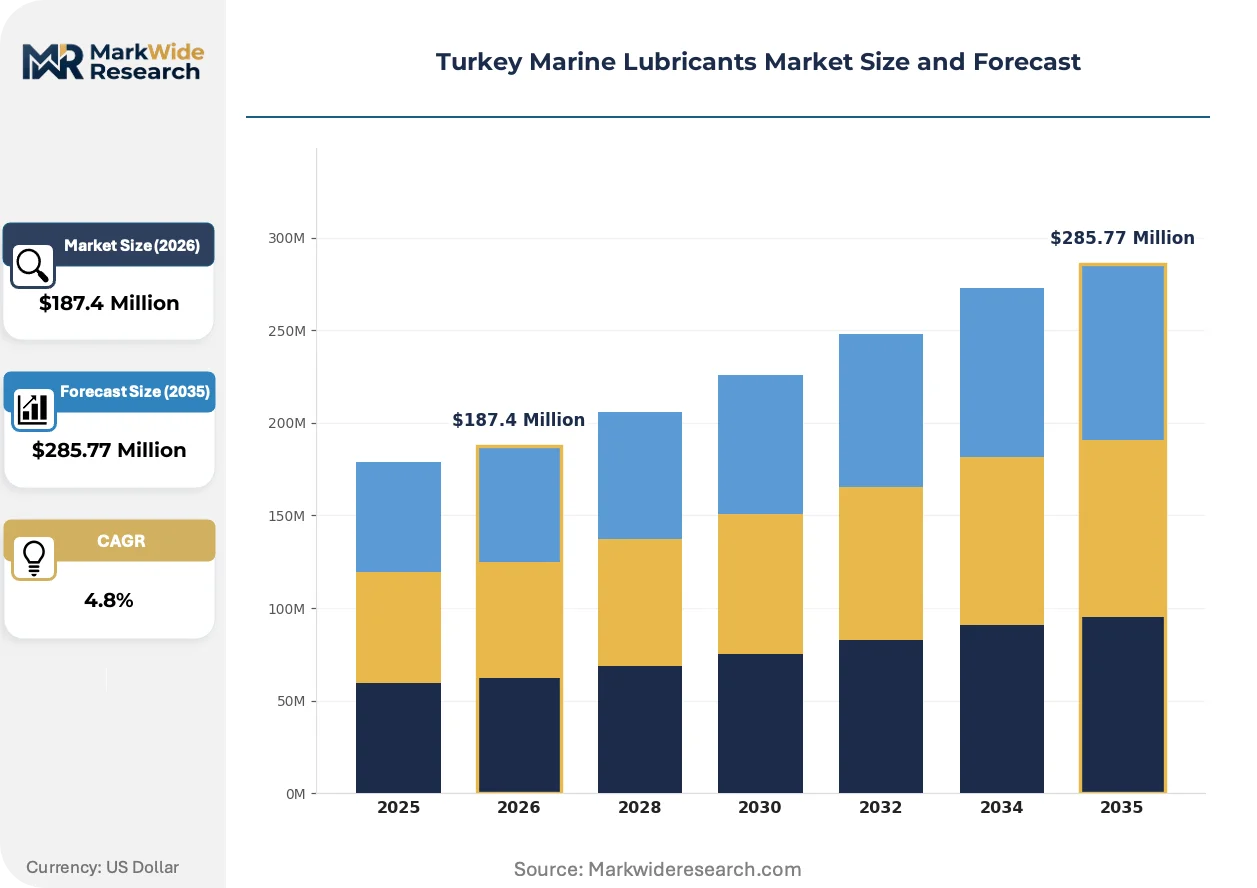
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Hydraulic Oil, Gear Oil, Grease Application: Commercial Shipping, Fishing Vessels, Navy Operations, Recreational Boats Viscosity Grade: Low Viscosity, Medium Viscosity, High Viscosity, Variable Viscosity Packaging Type: Buckets, Drums, Cases, Totes |
| Companies Covered | Petrol Ofisi A.S., Shell & Turcas Petrol A.S., BP Petrolleri A.S. (Castrol Turkey), TotalEnergies Turkey Pazarlama A.S., Mobil Oil Türk A.S., Fuchs Lubricants Turkey, Lukoil Eurasia Petrol A.S., Prista Oil, Lubrico, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Marine Lubricants Market Evolving Landscape
Synthetic and bio-based lubricant technologies are fragmenting traditional mineral oil dominance, while regulatory pressure on emissions and waste streams accelerates formulation complexity across Turkish maritime corridors.
Electrohydraulic control fluids for dynamic positioning systems are bifurcating the hydraulic oil category. Offshore supply vessels and cruise ships operating from Istanbul and Izmir are adopting these shear-stable, fire-resistant formulations at accelerating rates. The technology is compressing demand for conventional mineral hydraulic oils in high-load deck machinery applications.
Turkish national environmental regulator waste oil handling protocols now mandate cradle-to-grave tracking for marine lubricants discharged in territorial waters. This enforcement is restructuring collection logistics, requiring licensed transporters and registered re-refiners at Mersin, Izmir, and Istanbul. Cylinder oil and engine oil categories face the steepest compliance cost adjustments.
Fleet procurement consolidation is altering distributor relationships. Large Turkish shipowners are negotiating direct supply agreements with blenders, bypassing traditional ship chandler intermediaries. This channel compression is most visible among container and bulk carriers operating scheduled services through the Sea of Marmara.
Turkey Marine Lubricants Market Segmentation
Marine lubricant procurement in Turkey fragments across technical specifications, vessel categories, and logistics formats. Each segmentation axis reveals distinct margin structures and competitive intensity patterns across the Marmara and Aegean port clusters.
Product Type:
Margin pools concentrate in high-alkalinity cylinder oils and synthetic hydraulic formulations where specification complexity limits supplier substitution.
- Engine Oil:Formulated with detergent-dispersant packages and alkaline reserve measured by total base number to neutralize acidic combustion byproducts from residual fuel operation. Demand concentrates in Istanbul's bunkering terminals where Turkish-flagged container and bulk carriers procure for two-stroke crosshead and four-stroke trunk piston engines under MARPOL Annex VI compliance pressure.
- Hydraulic Oil:Shear-stable formulations engineered for dynamic positioning systems and high-load deck machinery. Procurement is accelerating at Ceyhan and Aliaga as offshore support vessels and tankers upgrade electrohydraulic control systems, displacing conventional mineral grades in premium applications.
- Gear Oil:Extreme-pressure lubricants for winch, crane, and steering gear reduction systems.
- Grease:Calcium sulfonate and lithium complex thickeners for bearing and cable maintenance cycles.
Engine oil holds installed capacity across the Turkish commercial fleet. Hydraulic oil is rotating up the share rankings on offshore vessel specification upgrades.
Application:
Cost tier stratification separates scheduled service operators from seasonal and state-procurement channels.
- Commercial Shipping:Container, bulk, and tanker fleets operating under Turkish flag registry drive volume procurement through direct blender agreements, bypassing traditional ship chandler intermediaries. Fleet consolidation among Marmara-based owners concentrates purchasing power at Istanbul bunkering hubs.
- Fishing Vessels:Regional Black Sea and Aegean fleets require specialized stern tube formulations with biodegradable base stocks to satisfy territorial water discharge protocols enforced by the national environmental regulator.
- Navy Operations:Turkish Ministry of National Defense procurement specifications prioritize domestic blending capacity and strategic stockpile requirements.
- Recreational Boats:Marina-based retail distribution through Izmir and Bodrum service centers, with seasonal demand peaks concentrated in Aegean coastal tourism corridors.
Commercial shipping commands procurement scale. Fishing vessels are climbing the fastest on regulatory-driven specification upgrades.
Viscosity Grade:
Volume distribution tracks ambient operating temperature ranges across Turkey's maritime zones, from Black Sea cold-start conditions to Mediterranean thermal loading.
- Medium Viscosity:SAE 30-40 grade lubricants dominate trunk piston engine applications across the Turkish commercial fleet, balancing cold-flow properties with high-temperature film strength for vessels transiting Istanbul and Canakkale straits.
- High Viscosity:SAE 50+ formulations serve crosshead engines burning high-sulfur residual fuels, with demand concentrating at Mersin and Izmir terminals where older tonnage maintains operational registry.
- Low Viscosity:SAE 20 and below grades for modern four-stroke engines optimized for low-sulfur distillate operation.
- Variable Viscosity:Multi-grade SAE 15W-40 and 10W-30 formulations for auxiliary engines and seasonal temperature variation.
Medium viscosity retains the largest installed base. High viscosity is gaining share fastest as legacy fleet retention extends drain interval economics.
Packaging Type:
Supply concentration shapes logistics economics, with bulk infrastructure favoring drum and tote formats at major terminals versus distributed bucket sales.
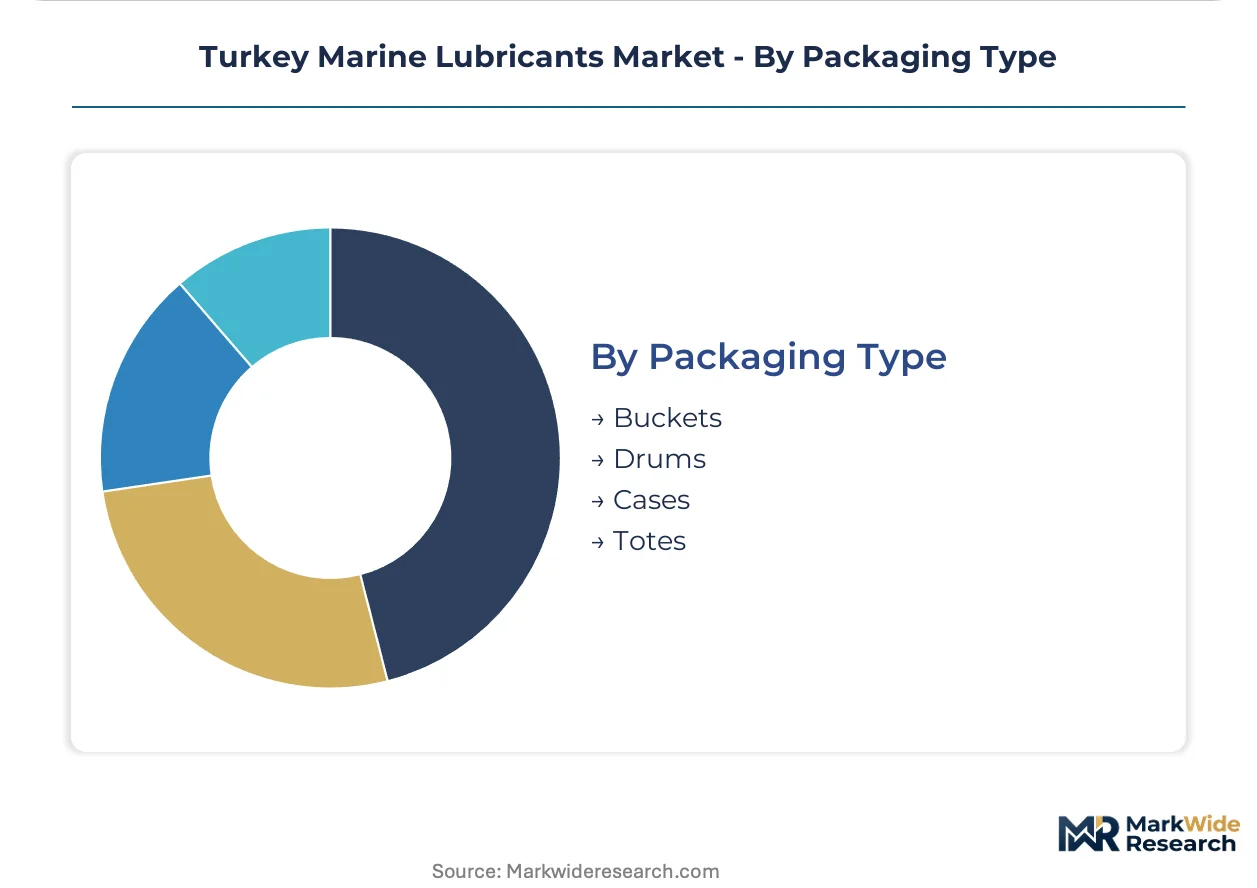
- Drums:200-liter steel containers dominate Istanbul bunkering terminal throughput, serving scheduled service vessels with predictable consumption patterns and established waste oil collection return logistics.
- Totes:Intermediate bulk containers penetrate Aliaga and Ceyhan offshore vessel segments where deck machinery volumes justify bulk dispensing systems and reduced packaging waste handling costs.
- Buckets:20-liter pails for fishing vessel retail and recreational marina maintenance.
- Cases:Multi-pack configurations for ship chandler inventory and emergency spare stock.
Drums anchor terminal throughput volume. Totes are expanding most quickly on offshore vessel specification convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and ship service providers concentrate procurement decisions across Turkey's maritime corridors. Buyer archetypes span Turkish-flagged commercial carriers, Black Sea fishing cooperatives, and offshore vessel operators at specialized terminals.
Marmara Region
Istanbul bunkering terminals and ship service hubs drive cylinder oil and engine oil volume for container and bulk carriers. Turkish Ministry of Transport port state control directives enforce MARPOL Annex VI compliance, tightening lubricant specifications. The Sea of Marmara shipping lanes and Tuzla shipyard cluster anchor procurement concentration for scheduled service operators.
Aegean Region
Izmir coastal terminals and Aliaga port facilities process hydraulic oil demand from offshore support vessels upgrading dynamic positioning systems. National environmental regulator waste oil handling protocols mandate cradle-to-grave tracking for lubricants discharged in territorial waters. The Izmir-Aliağa industrial corridor concentrates re-refining infrastructure and licensed collection logistics.
Mediterranean Region
Mersin terminals serve as the southern gateway for high-viscosity formulations targeting legacy crosshead engines on residual fuel. The national environmental regulator enforces waste oil collection protocols that shape re-refining economics at this hub. Mersin port infrastructure supports both commercial shipping procurement and regional distribution to smaller harbors.
Black Sea Region
Samsun and Trabzon coastal terminals remain underpenetrated for specialized stern tube formulations serving regional fishing and short-sea fleets. Turkish-flagged fishing cooperatives face biodegradable lubricant mandates for territorial water discharge compliance. The Black Sea port cluster is climbing the procurement rankings on regulatory-driven specification upgrades.
Turkey Marine Lubricants Market Competitive Landscape
Player mix skews toward integrated energy majors with coastal terminal networks and specialized lubricant blenders with technical service capabilities. Market structure concentrates around three to four dominant suppliers controlling bulk delivery infrastructure at Istanbul, Izmir, and Mersin. Strategic archetypes include terminal-anchored majors, shipyard-integrated technical service providers, and regional specialists in fishing fleet formulations. Competitive moves center on direct supply agreement negotiations with large Turkish shipowners and certification investments for OEM-approved cylinder oil formulations.
Among Turkey-based integrated suppliers, Petrol Ofisi A.S. and Shell & Turcas Petrol A.S. represent the terminal-anchored major archetype, while Fuchs Lubricants Turkey occupies a position exemplifying the specialized blender tier focused on technical formulations. These three companies anchor the competitive structure across Marmara and Aegean procurement corridors.
| Leading Market Players |
|---|
| Petrol Ofisi A.S. |
| Shell & Turcas Petrol A.S. |
| BP Petrolleri A.S. (Castrol Turkey) |
| TotalEnergies Turkey Pazarlama A.S. |
| Mobil Oil Türk A.S. |
| Fuchs Lubricants Turkey |
| Lukoil Eurasia Petrol A.S. |
| Prista Oil |
| Lubrico |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Izmir and Mersin coastal terminals shapes both supply concentration and price floors for Turkish marine lubricant blenders. Scale economies in bulk base oil handling compress per-unit logistics costs for terminal-anchored majors while elevating breakeven thresholds for smaller distributors serving fishing and recreational segments.
Pricing Analysis
Cost-plus contracts indexed to Platts Singapore fuel oil assessments dominate procurement agreements between Turkish shipowners and lubricant suppliers. Three-tier pricing structure across premium synthetic, standard mineral, and economy re-refined grades tracks base oil Group II/III certification tiers and OEM approval status. Pricing pressure stems from fleet procurement consolidation as Marmara-based container carriers negotiate direct blender agreements, bypassing traditional ship chandler markups. Commercial shipping operators exhibit lowest price sensitivity due to MARPOL compliance mandates, while Black Sea fishing cooperatives face acute cost pressure from biodegradable lubricant mandates.
Supply Chain Analysis
Bosporus Strait transit constraints concentrate base oil feedstock flows through Mediterranean and Black Sea port alternatives. Turkish blenders draw from Middle Eastern Group II/III producers, European additive compounders, and domestic re-refining capacity at Izmir-Aliağa. Single-source vulnerability persists for high-alkalinity cylinder oil additive packages sourced from specialized European chemical manufacturers. Distribution runs through coastal terminal bulk facilities for commercial fleets, with drum repackaging networks extending to Black Sea fishing harbors and Aegean marina service centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and waste oil collection logistics represent faster-expanding margin pools than base lubricant volume, as Turkish environmental enforcement deepens cradle-to-grave compliance requirements. Recurring revenue from re-refining partnerships and OEM-approved formulation support now outpaces hardware growth in procurement decisions.
For Market Incumbents: Compound terminal network advantages by integrating backward into licensed waste oil collection at Samsun and Trabzon, preempting regulatory-driven specification upgrades in underpenetrated Black Sea fishing segments. Deepen technical service partnerships with Tuzla shipyards to anchor OEM certification timelines for MAN Energy Solutions and Wärtsilä engine platforms, defending against direct supply agreement erosion from fleet procurement consolidation. For New Entrants and Emerging Players: OEM certification fast-tracks through partnership with established European additive suppliers offer the most penetrable entry vector for specialized cylinder oil formulations targeting legacy two-stroke crosshead engines. Black Sea coastal terminals remain white-space territory for biodegradable stern tube formulations serving Turkish-flagged fishing cooperatives. Position through shipyard-integrated technical service rather than terminal bulk infrastructure competition. For Investors and Strategic Acquirers: Regional re-refining specialists with licensed collection logistics and vacuum distillation capabilities present the most defensible acquisition archetype as circular base oil recovery economics improve. Long-term viability hinges on regulatory enforcement trajectory rather than fleet expansion cycles. Monitor Turkish Ministry of Transport port state control inspection frequency as inflection indicator for compliance-driven specification upgrade intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Re-Refining | Captures circular base oil value from MARPOL-mandated waste collection at Mersin and Izmir terminals. |
| OEM Certification Investment | Accelerates approval timelines for MAN Energy Solutions and Wärtsilä cylinder oil formulations. |
| Black Sea Terminal Expansion | Addresses underpenetrated Samsun and Trabzon demand for fishing fleet biodegradable lubricants. |
| Direct Supply Agreement Negotiation | Bypasses ship chandler intermediaries as Marmara container carriers consolidate procurement. |
| Technical Service Partnership | Anchors blender relationships with Tuzla shipyards through embedded lubricant engineering support. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with Turkish shipowners, port terminal operators, and lubricant blending executives, alongside secondary validation through customs trade records, Turkish Ministry of Transport port state control disclosure filings, and MARPOL Annex VI implementation reports. Primary fieldwork encompassed technical directors at Istanbul bunkering terminals, procurement leads at Marmara-based fleet operators, and environmental compliance officers at Izmir-Aliağa re-refining facilities. Bottom-up volume estimates from vessel registry data and top-down market sizing from import-export flows were triangulated against blender capacity disclosures.
Across the analysis window, projections integrate product type segmentation by alkalinity grade and synthetic content, application segmentation across commercial shipping and fishing vessel archetypes, and packaging format segmentation reflecting bulk terminal versus distributed retail logistics. CAGRs were derived from fleet expansion trajectories under Turkish flag registry and regulatory compliance cost pass-through assumptions. Forecast inputs include IMO sulfur cap enforcement intensity and EU carbon border adjustment mechanism routing effects through Turkish straits.
Decision-makers should treat outputs as directional under sustained MARPOL Annex VI enforcement and stable Middle Eastern base oil supply assumptions; material deviation in regulatory stringency or feedstock trade flows would warrant model refresh. Practitioners should keep alternative scenarios live as Turkish Ministry of Transport inspection protocols and EU carbon pricing implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Firearm Lubricants Market
Lubricants
Malaysia Automotive Engine Oils Market
Lubricants
France Lubricants Market
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
Global Refrigeration Lubricants Market
Lubricants
Technical Fluids Market
Lubricants
Jordan Lubricants Market
Lubricants
Russia Lubricants Market
Lubricants
South America Commercial Vehicles Lubricants Market
Lubricants
Heavy Equipment Lubricants Market
Lubricants
Spain Automotive Engine Oils Market
Lubricants
Specialty Lubricants Market
Lubricants
Global Group IV and V Lubricants Market
Lubricants
Bulgaria Lubricants Market
Lubricants
Hydropower Lubricants Market
Lubricants
Europe Grease Market