
 Tire and Rubber Lubricants Market | 2026-2036
Tire and Rubber Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Tire and Rubber Lubricants Market Analytics
Asian petrochemical producers is consolidating capacity around integrated rubber processing corridors. Lanxess leverages its specialty chemicals portfolio to dominate European tire lubricant formulations. ExxonMobil Chemical anchors North American supply through backward integration into base oil refining. Shell Chemicals competes on low-viscosity process oils tailored for high-performance tire compounds.
Tire and rubber lubricants are formulated mixtures of mineral oils, synthetic polymers, and fatty acid esters designed to reduce friction during rubber mixing, extrusion, and curing, typically operating at temperatures between 120°C and 180°C to prevent scorch and improve filler dispersion. Process oils constitute the largest volume segment due to their essential role in tire manufacturing compounding stages. Synthetic polymers represent the fastest-expanding material category as tire producers substitute mineral oils to meet stricter volatility standards. Wax additives command premium positioning in footwear production applications where surface finish requirements exceed automotive specifications.
REACH restrictions on polycyclic aromatic hydrocarbons in process oils compel European formulators toward hydrotreated alternatives, while China's GB standards and the EU Green Deal carbon border adjustments reshape import competitiveness for mineral oil suppliers. EPA regulations in the United States govern volatile organic compound emissions from rubber processing facilities, driving water-based emulsion adoption. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with diverging compliance thresholds.
Market Dynamics
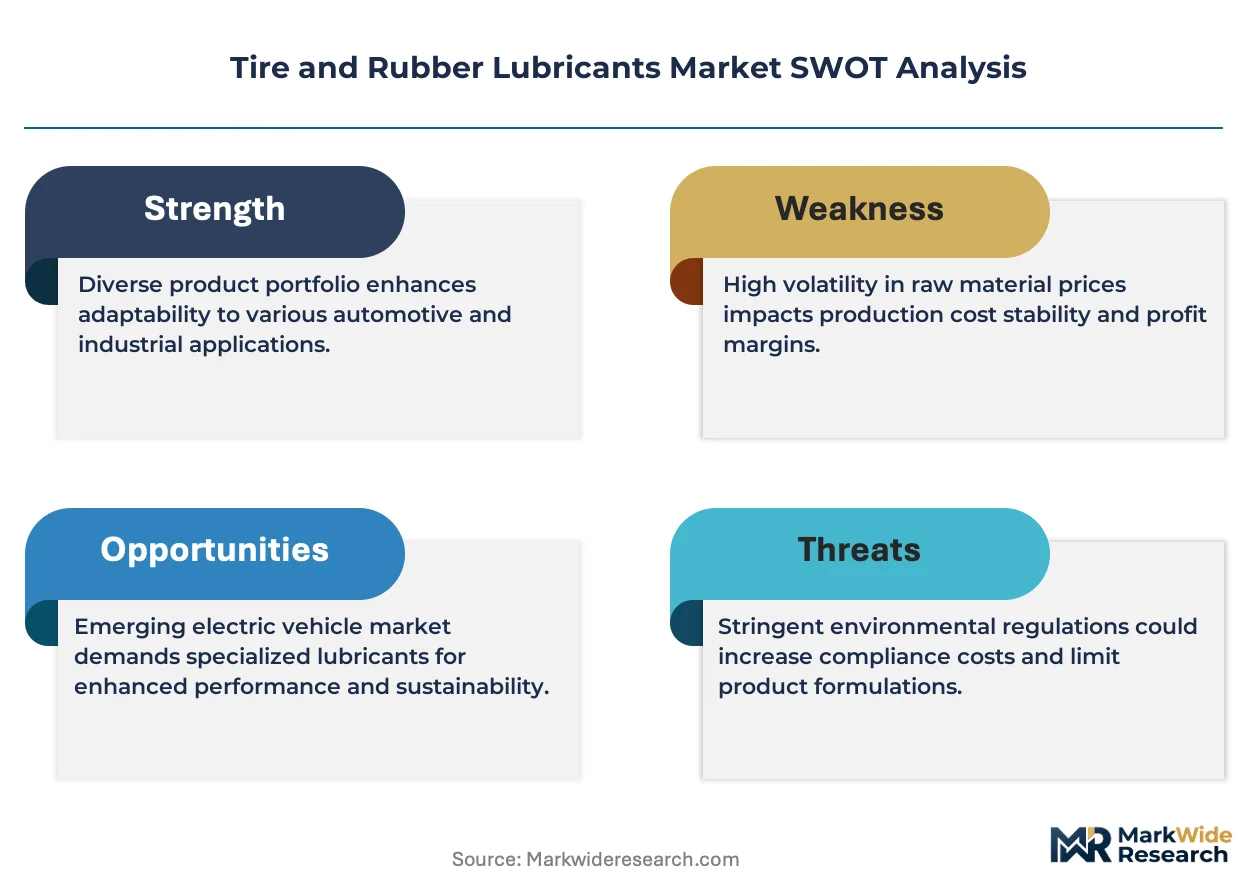
REACH polycyclic aromatic hydrocarbon restrictions on process oils are forcing European formulators toward hydrotreated alternatives, while China's dual carbon goals concentrate synthetic rubber production in Shandong province and reshape mineral oil demand patterns.
Growth Catalysts
- EU tire labeling mandates:German manufacturers expand process oil consumption to meet rolling resistance grade thresholds, pulling hydrotreated naphthenic volumes across European compounding facilities.
- Shandong synthetic rubber clustering:China's petrochemical corridor consolidation concentrates mineral oil-based lubricant demand in a single province, creating procurement scale effects for integrated suppliers.
- High-performance tire compounds:Low-viscosity process oils enable silica-silane coupling in green tire formulations, substituting carbon black and reducing heat buildup during vulcanization.
Market Restraints
- Base oil supply concentration:Group II/III refinery capacity concentrates in US Gulf Coast and Middle Eastern hubs, exposing Asian formulators to freight cost volatility and currency mismatch.
- REACH compliance friction:Hydrotreated alternative oils carry 15-25% cost premiums over solvent-extracted equivalents, compressing margin structures for mid-tier European compounders.
- Water-based emulsion performance gaps:Reduced scorch protection and inferior filler dispersion limit substitution rates in high-shear extrusion applications despite EPA volatile organic compound pressure.
Strategic Opportunities
- India tire manufacturing expansion:PLI scheme incentives for domestic rubber product output create first-mover positioning for process oil suppliers establishing technical service presence in Tamil Nadu and Gujarat.
- Wax additive footwear premiumization:Surface finish specifications exceeding automotive tiers command 40-60% price multiples in Italian and Portuguese leather substitute manufacturing.
- Bio-based ester convergence:Fatty acid ester and synthetic polymer blending technologies mature simultaneously, enabling volatility-compliant formulations without full petroleum displacement.
Industry Challenges
- Rubber processing chemist scarcity:Formulation expertise bridging mineral oil rheology and polymer science concentrates among retiring specialists in Akron and Leverkusen industrial clusters.
- Dual certification timelines:Separate GB standard testing in China and EPA Method 24 validation in the United States extend product launch cycles for multi-jurisdictional suppliers.
- Legacy mixing equipment retrofit costs:Water-based emulsion adoption requires steam jacket modifications and seal material replacements in 1970s-vintage Banbury installations still operating across Southeast Asian tire plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire and Rubber Lubricants Market |
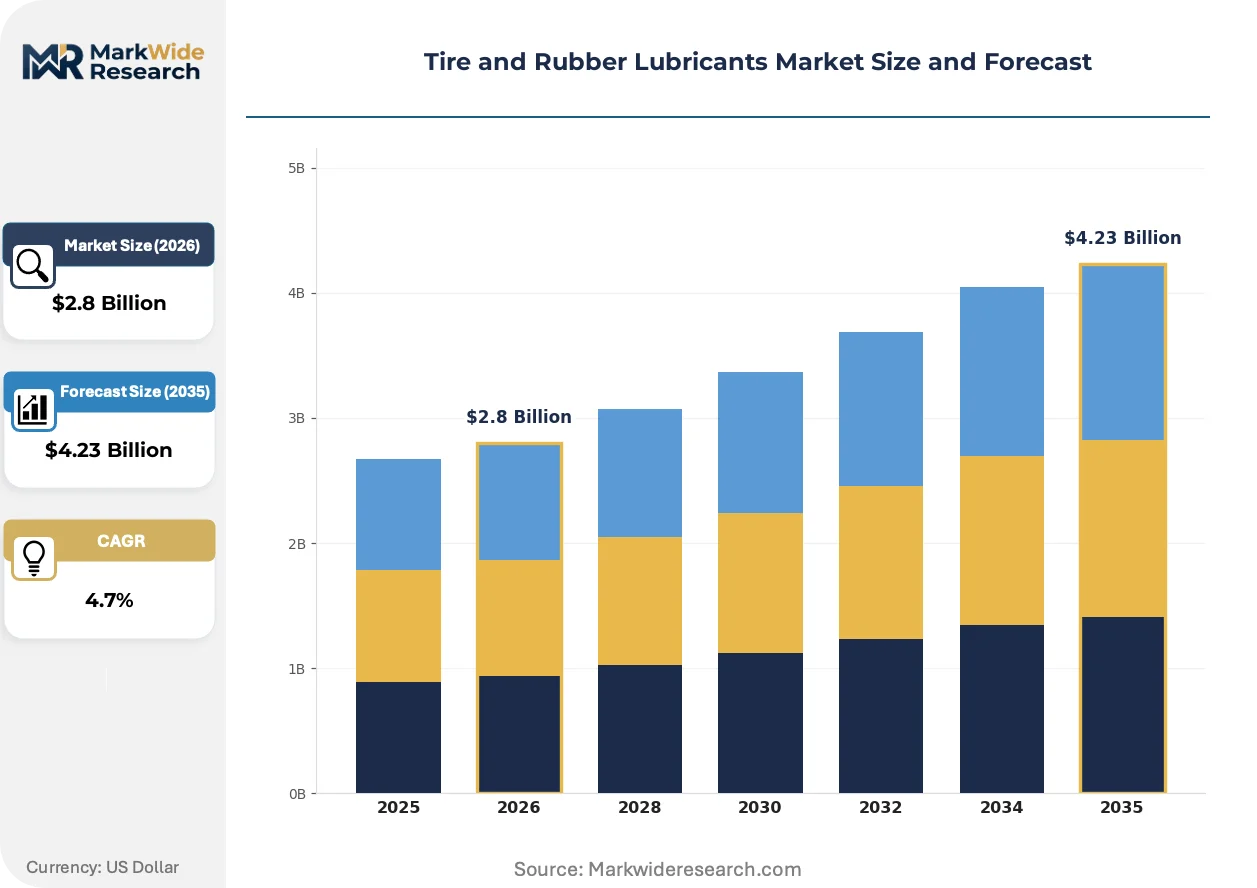
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Process Oils, Emulsions, Additives, Wax Material Type: Silicone, Mineral Oil, Fatty Acid Esters, Synthetic Polymers Application: Tire Manufacturing, Rubber Processing, Automotive Parts, Footwear Production End User: Tire Manufacturers, Automotive OEMs, Industrial Users, Footwear Manufacturers |
| Companies Covered | JSR Corporation, Lanxess, Sinopec, Shell Chemicals, ExxonMobil Chemical, Arlanxeo, LG Chem, Synthos, Kumho Petrochemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire and Rubber Lubricants Market Evolving Landscape
Digital process control systems, regulatory chemistry pivots, and procurement centralization are restructuring how tire and rubber lubricants are specified, formulated, and delivered to compounders.
Closed-loop viscosity monitoring is automating real-time process oil dosing adjustments during Banbury mixing cycles. Major tire manufacturers in Germany and Japan deploy these systems to maintain batch-to-batch consistency within 3% variance bands. The technology is automating away manual sampling protocols and reducing off-spec rubber scrap rates.
REACH restrictions on polycyclic aromatic hydrocarbons in extender oils have triggered wholesale formulation revisions across European tire production. Hydrotreated naphthenic and paraffinic base stocks now dominate new product development pipelines, displacing traditional aromatic extracts. German compounders face the steepest transition costs due to legacy supply contracts with solvent extraction refineries.
Centralized procurement desks at multinational tire manufacturers now specify lubricants against compound performance outcomes rather than individual material properties. Technical service agreements bundle process oil supply with mixing optimization consulting, displacing spot purchasing through distributors. This pattern is most visible in South Korean and Japanese tire makers consolidating supplier panels from twelve vendors to three approved partners.
Tire and Rubber Lubricants Market Segmentation
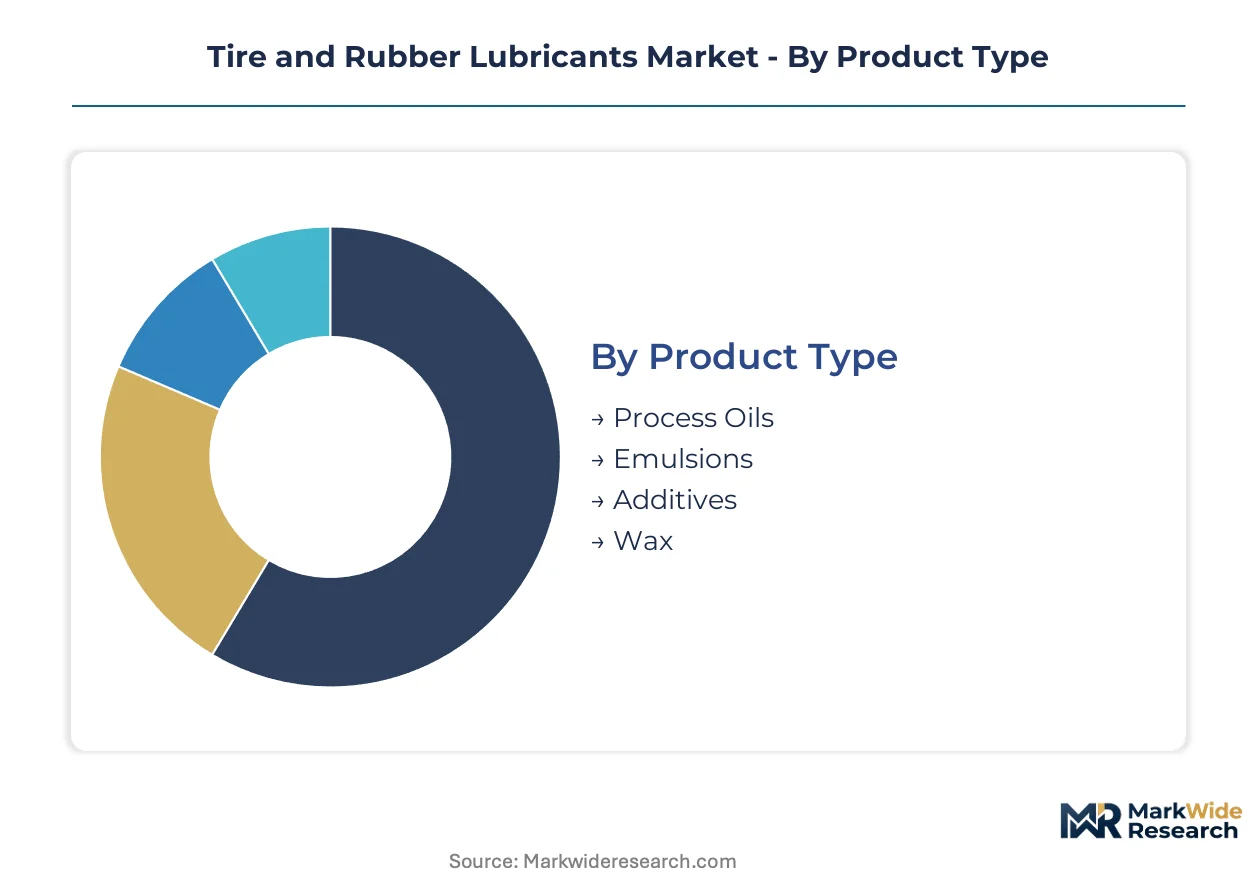
Segmentation in tire and rubber lubricants reveals how capital deployment, formulation chemistry, and end-use specifications fragment procurement patterns. Distinct technical requirements across tire compounding, footwear finishing, and automotive extrusion create specialized supply relationships that resist commoditization.
Product Type:
Capital intensity varies sharply across product categories, with continuous-process refining assets for base oil production demanding the heaviest upfront investment compared to batch blending operations for emulsions and additives.
- Process Oils:Hydrotreated naphthenic and paraffinic base stocks formulated for rubber extender and plasticizer functions, typically occupying 60-70% of lubricant volume in tire compounds. German tire manufacturers anchor European demand for low-viscosity grades that meet EU tire labeling rolling resistance thresholds. REACH polycyclic aromatic hydrocarbon restrictions are accelerating substitution of solvent-extracted aromatic oils, compressing margins for refiners without hydroprocessing capability.
- Emulsions:Water-based dispersions of mineral oils or synthetic esters stabilized with surfactant systems, designed for reduced volatile organic compound emissions during rubber processing. EPA Method 24 compliance requirements in United States rubber extrusion facilities are pulling adoption despite performance gaps in high-shear applications. Capital requirements concentrate in emulsion polymerization and stability testing infrastructure rather than hydrocarbon refining.
- Additives:Functional chemicals including anti-scorch agents, peptizers, and dispersion aids dosed at 1-5% of compound weight. Formulation expertise rather than fixed asset intensity determines competitive positioning in this segment.
- Wax:Microcrystalline and synthetic waxes providing surface finish and release properties, commanding premium positioning in Portuguese and Italian footwear manufacturing where aesthetic specifications exceed automotive tiers.
Process oils absorb the bulk of installed capacity; emulsions are expanding most quickly.
Material Type:
Raw material cost structures stratify sharply, with silicone feedstocks tied to silicon metal and methyl chloride pricing while mineral oils track crude differentials and refinery utilization.
- Mineral Oil:Group I, II, and III base stocks refined from crude petroleum, dominating volume in tire manufacturing due to cost position and established supply infrastructure. Shandong province synthetic rubber clustering concentrates Chinese demand for naphthenic grades. Dual carbon goals under China's GB standards are pressuring carbon intensity disclosures from mineral oil suppliers.
- Synthetic Polymers:Polyalphaolefins, polyisobutylenes, and other petroleum-derived polymers engineered for precise viscosity and volatility specifications. Japanese tire manufacturers specify these materials for high-performance silica-silane coupling formulations. Premium pricing over mineral oils reflects polymerization asset intensity and technical service requirements.
- Silicone:Polydimethylsiloxane fluids and modified siloxanes delivering thermal stability across extreme temperature ranges. Automotive underhood applications in electric vehicle battery sealing systems anchor niche demand.
- Fatty Acid Esters:Bio-based or petrochemical esters from oleic, stearic, and adipic acid feedstocks, bridging volatility compliance and renewable content requirements without full petroleum displacement.
Mineral oil commands current volume leadership; synthetic polymers are climbing the fastest.
Application:
Specification intensity diverges across applications, with tire manufacturing demanding batch-to-batch viscosity control while footwear production prioritizes surface aesthetic outcomes.
- Tire Manufacturing:Compounding, extrusion, and curing operations consuming process oils as extenders, plasticizers, and processing aids. German and Japanese tire makers deploy closed-loop viscosity monitoring to maintain 3% batch variance bands. EU tire labeling mandates for rolling resistance and wet grip grades are tightening lubricant specification windows.
- Footwear Production:Mold release, surface finishing, and leather substitute manufacturing applications where wax additive premiums reach 40-60% over automotive specifications. Portuguese and Italian manufacturers drive demand for aesthetic-grade formulations.
- Automotive Parts:Hose, belt, and seal manufacturing requiring scorch protection during high-temperature vulcanization.
- Rubber Processing:General industrial compounding for conveyor belts, gaskets, and molded goods with less stringent performance specifications than tire or automotive tiers.
Tire manufacturing absorbs dominant capacity share; footwear production commands steepest price multiples.
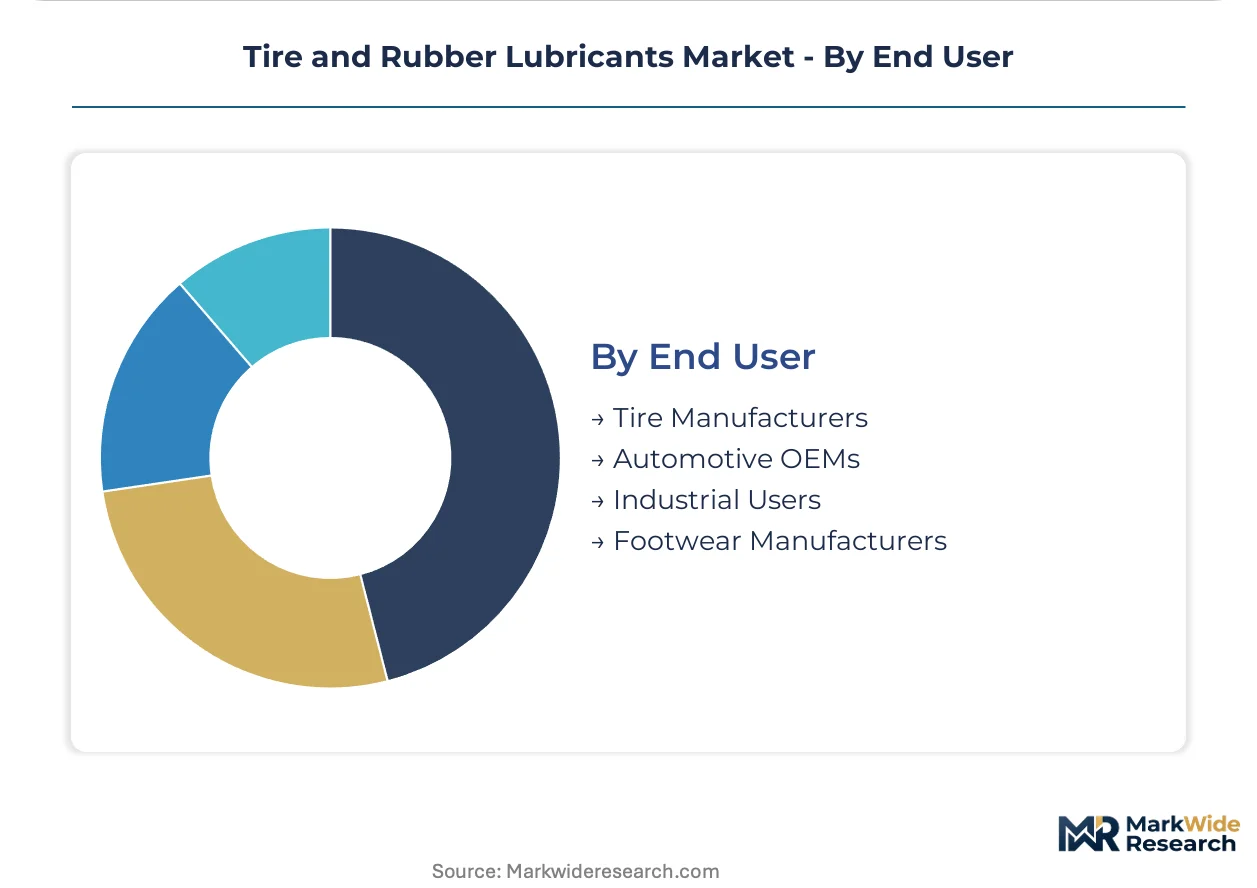
End User:
Procurement sophistication tiers separate multinational tire makers with centralized technical service agreements from fragmented industrial compounders purchasing through distributors.
- Tire Manufacturers:Multinational producers consolidating supplier panels from twelve vendors to three approved partners, bundling process oil supply with mixing optimization consulting. South Korean and Japanese tire makers anchor this procurement centralization trend.
- Automotive OEMs:Direct specification of lubricants for captive rubber parts production, with vertical integration into compounding operations at major German and United States vehicle manufacturers.
- Footwear Manufacturers:Italian and Portuguese leather substitute producers with formulation specifications exceeding automotive tiers, often purchasing wax additives through specialized chemical distributors rather than base oil suppliers.
- Industrial Users:Fragmented conveyor belt, gasket, and molded goods producers with spot purchasing patterns and limited technical service requirements.
Tire manufacturers concentrate procurement volume; footwear manufacturers generate highest margin per ton.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crude oil refining corridors in the US Gulf Coast and Middle Eastern hubs anchor base oil supply for tire lubricant formulators worldwide. Germany's Ruhr industrial cluster and China's Shandong petrochemical corridor concentrate downstream rubber processing demand. Regional regulatory divergence around polycyclic aromatic hydrocarbons and carbon intensity disclosures is fragmenting procurement patterns.
United States
Gulf Coast Group II/III refinery capacity supplies domestic tire manufacturers with hydrotreated base stocks. EPA Method 24 governs volatile organic compound emissions from rubber extrusion facilities, pulling water-based emulsion adoption despite performance gaps. Akron, Ohio retains formulation expertise bridging mineral oil rheology and polymer science.
Germany
Tire manufacturers in Baden-Württemberg and Lower Saxony expand process oil consumption to meet EU tire labeling rolling resistance grade thresholds. REACH restrictions on polycyclic aromatic hydrocarbons compel formulators toward hydrotreated naphthenic alternatives, compressing margins for solvent extraction refineries. Leverkusen's specialty chemicals cluster anchors European lubricant formulation leadership.
China
Shandong province's synthetic rubber output concentrates mineral oil-based lubricant demand in a single procurement corridor. Dual carbon goals under GB standards pressure carbon intensity disclosures from base oil suppliers. Yangtze River Delta tire makers deploy closed-loop viscosity monitoring to maintain batch consistency.
Japan
Kansai and Chubu tire manufacturers specify synthetic polymers for high-performance silica-silane coupling formulations. METI industrial standards shape lubricant volatility specifications for domestic rubber processing. Nagoya automotive suppliers consolidate supplier panels from twelve vendors to three approved partners.
India
PLI scheme incentives for domestic rubber product output create first-mover positioning for process oil suppliers. Tamil Nadu and Gujarat tire manufacturing expansion concentrates technical service requirements in southern and western industrial corridors. BIS standards on rubber processing chemicals are tightening formulation compliance windows.
Tire and Rubber Lubricants Market Competitive Landscape
Global majors compete with regional champions across base oil refining and specialty formulation capabilities. The vendor base stratifies between integrated petrochemical conglomerates with captive supply and independent compounders purchasing through distributors. Three archetypes dominate: Gulf Coast and Middle Eastern refiners with hydroprocessing assets, European specialty chemicals houses with REACH-compliant portfolios, and Asian petrochemical groups serving clustered rubber demand. Competitive moves concentrate on backward integration into base oil production and technical service bundling with process oil supply.
Among integrated petrochemical conglomerates, ExxonMobil Chemical and Shell Chemicals occupy positions anchored in North American and European refining infrastructure respectively. Lanxess exemplifies the specialty chemicals archetype with European REACH-compliant formulation capabilities. Sinopec represents state-backed vertical integration serving Shandong corridor demand concentration. These three patterns illustrate how geographic proximity to refining assets, regulatory compliance specialization, and downstream clustering shape competitive positioning without requiring identical strategic postures.
| Leading Market Players |
|---|
| JSR Corporation |
| Lanxess |
| Sinopec |
| Shell Chemicals |
| ExxonMobil Chemical |
| Arlanxeo |
| LG Chem |
| Synthos |
| Kumho Petrochemical |
| Others |
Value Network & Pricing Analysis
Multinational tire manufacturers consolidating supplier panels from twelve vendors to three approved partners command pricing power through bundled technical service agreements rather than spot purchasing. This procurement centralization anchors contract structures around compound performance outcomes, displacing transactional spot markets for process oils and additives.
Pricing Analysis
Technical service bundling separates premium formulations from unbundled commodity supply, with mixing optimization consulting included in annual contracts for top-tier tire makers. Price differentiation rests on REACH compliance certification and hydrotreatment asset access, with hydrotreated alternatives commanding 15-25% premiums over solvent-extracted grades. Cost compression in mid-tier European compounder margins is intensifying because legacy solvent extraction refineries face stranded asset risk. Spot purchasing through distributors remains most price-sensitive, while centralized procurement at South Korean and Japanese tire makers shows lowest sensitivity due to performance-outcome contracting.
Supply Chain Analysis
Single-source vulnerability sits with Group II/III refinery capacity concentrated in the US Gulf Coast and Middle Eastern hubs, exposing Asian formulators to freight cost volatility. Raw material flows draw from crude petroleum, silicon metal for silicone feedstocks, and oleic acid for fatty acid ester production. Tariff exposure runs through carbon border adjustment mechanisms under the EU Green Deal reshaping import competitiveness for mineral oil suppliers. Distribution feeds from integrated petrochemical conglomerates with captive base oil production to centralized procurement desks at multinational tire manufacturers, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydroprocessing capacity scarcity props pricing power for REACH-compliant formulators, constraining supply elasticity as European tire manufacturers face mandatory formulation transitions.
For Market Incumbents: Anchor defensive positioning through backward integration into base oil refining and technical service bundling with process oil supply. Hydrotreatment asset scarcity threatens mid-tier European compounders unable to secure compliant feedstock. Certification investment in dual GB standard and EPA Method 24 validation preserves multi-jurisdictional access. For New Entrants and Emerging Players: Digital technical service platforms offer low-capital entry routes to penetrate India's PLI scheme-funded tire manufacturing expansion in Tamil Nadu and Gujarat. Wax additive supply for Portuguese and Italian footwear production presents penetrable white-space with 40-60% price multiples over automotive tiers. Direct technical consulting relationships with emerging tire compounders bypass entrenched distributor networks. For Investors and Strategic Acquirers: The window for entry favors specialty chemicals houses with REACH-compliant hydrotreated portfolios and established rubber processing chemist expertise. Long-term viability centers on regulatory chemistry pivot capabilities as volatility standards tighten across jurisdictions. Watch for consolidation signals when solvent extraction refineries announce hydroprocessing retrofit investments or asset retirement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Refining | Captive hydroprocessing capacity secures REACH-compliant feedstock supply for European formulators facing solvent extraction obsolescence. |
| Technical Service Bundling | Mixing optimization consulting contracts lock in multi-year supply relationships with centralized procurement desks at Japanese tire manufacturers. |
| Dual Certification Investment | Simultaneous GB standard and EPA Method 24 validation accelerates product launch cycles for multi-jurisdictional suppliers. |
| Digital Process Control Integration | Closed-loop viscosity monitoring partnerships with German tire makers automate real-time dosing adjustments and reduce off-spec scrap. |
| Bio-based Ester Formulation Development | Fatty acid ester and synthetic polymer blending bridges volatility compliance and renewable content without full petroleum displacement. |
Research Methodology
Independent corroboration across rubber processing chemists at Akron and Leverkusen industrial clusters, procurement directors at multinational tire manufacturers, and technical service managers at base oil suppliers underwrites the qualitative findings. Primary interviews with plant engineers at Shandong synthetic rubber facilities, distribution channel partners in European specialty chemicals, and R&D directors at emulsion formulators combined with secondary validation from customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings. Bottom-up demand modeling across tire manufacturing, footwear production, and automotive parts applications triangulates with top-down supply-side capacity assessments.
Rate-of-change decomposition across the projection horizon segments volume and value by product type, material category, application intensity, and end-user procurement sophistication. Modeled dimensions include process oil grade tier, rubber compounding end-use, formulation chemistry pathway, and regional production hub clustering. CAGRs derive from elasticity-adjusted demand projections and capacity utilization trajectories. Industry-specific forecast inputs incorporate EU tire labeling mandate compliance timelines and China's dual carbon goal implementation pace affecting synthetic rubber corridor concentration.
The model holds under stable regulatory enforcement intensity and continued petrochemical feedstock availability; deviation in REACH amendment scope or crude supply disruption would shift trajectory bounds. Forecasts reflect documented assumptions about hydrotreatment capacity expansion schedules and emulsion performance gap closure rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Recycled Elastomers Market
Rubber
Global Chloroprene Rubber Market
Rubber
Global Rubber Coated Fabrics Market
Rubber
Ethylene Propylene Rubber Cable Market
Rubber
Global Automotive Elastomers Market
Rubber
Sterile Rubber Stopper Market
Rubber
EPDM Market
Rubber
Rubber Color Masterbatch Market
Rubber
Global Rubber Vulcanization Market
Rubber
Liquid Silicone Rubber Market
Rubber
Nitrile Elastomers Market
Rubber
Fluorosilicone (FVMQ) Rubber Market
Rubber
Europe Neoprene Market
Rubber
Rubber Rollers Market
Rubber
Snap on Rubber Stopper Market
Rubber
Global Medical Rubber Stopper Market