
 Oil Saver Rubber Market | 2026-2036
Oil Saver Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Saver Rubber Market Analytics
Market Context
Southeast Asia is tilting toward expanded nitrile and hydrogenated nitrile rubber compounding capacity to serve regional oilfield service demand. Oil States Industries leverages integrated manufacturing from raw polymer through finished seals to sustain pricing power in deepwater BOP stacks. Datwyler Sealing Solutions anchors European supply through precision-molded fluoroelastomer packings for high-pressure wellhead assemblies. Titan BOP Rubber Products dominates niche replacement schedules for legacy ram and annular preventer configurations in the Gulf of Mexico.
Technical Definition and Segments
Oil saver rubber denotes specialized elastomeric compounds engineered to resist hydrocarbon swelling, thermal degradation, and mechanical extrusion in dynamic sealing environments, typically formulated with acrylonitrile content between 18 and 50 percent for fluid compatibility grading. These materials function primarily as pressure-retaining barriers in blowout preventers, wellheads, and flow control equipment where seal failure risks catastrophic fluid release. Synthetic rubber grades, particularly hydrogenated nitrile and fluoroelastomer variants, command premium positioning due to sour gas resistance and extended service intervals in HPHT reservoirs. The oil & gas end user segment concentrates the highest value per unit, while automotive seals represent a volume-stable parallel channel with shorter replacement cycles and lower compound complexity.
Regulatory Frame
The EPA enforces emissions control standards that mandate leak detection and repair protocols, directly stimulating demand for low-permeability elastomer seals in production infrastructure. REACH registration requirements and RoHS substance restrictions in Europe constrain phthalate plasticizer formulations, pushing compounders toward bio-based process oils and peroxide cure systems. OSHA workplace exposure limits for hydrogen sulfide further reinforce specification rigor for sour service packings. Stakeholders must monitor evolving methane performance standards and material passport traceability rules to align product development with procurement gatekeeping.
Market Dynamics
HPHT reservoir expansion is compressing seal replacement cycles as operators demand elastomer formulations that withstand 400°F bottom-hole temperatures and 15,000 psi differential pressures without plasticizer bleed-out.
Growth Catalysts
- REACH RoHS substitution mandates:ECHA registration deadlines are phasing out phthalate-plasticized nitrile compounds across European refining infrastructure, forcing compounders toward peroxide-cured hydrogenated nitrile systems.
- Shale fracturing intensity:Permian Basin operators are running blowout preventers at higher cycle frequencies, accelerating annular packing replacement schedules beyond historical 18-month intervals.
- Fluoroelastomer thermal ceiling extension:Advanced FKM terpolymer grades now tolerate 600°F sour gas exposure, opening deep gas well applications previously closed to nitrile-based formulations.
Market Restraints
- Acrylonitrile feedstock volatility:Butadiene-acrylonitrile contract pricing swings 30-40 percent quarterly, eroding compounder margins on fixed-price seal contracts to oilfield service majors.
- Japanese fluoroelastomer concentration:Daikin and AGC control 60 percent of global FKM polymer supply, creating single-source vulnerability for premium wellhead seal manufacturers.
- Hydrogen sulfide compatibility ceiling:Standard HNBR formulations suffer rapid embrittlement above 50 ppm H2S partial pressure, limiting applicability in sour gas corridors.
Strategic Opportunities
- Brazil pre-salt development:Petrobras deepwater rig deployments off Santos Basin are specifying API 16A compliant packings with 25-year service life guarantees, creating premium tier demand.
- Carbon capture injection seals:Supercritical CO2 compression infrastructure requires elastomers resistant to explosive decompression, an emerging specification channel adjacent to hydrocarbon extraction.
- API 6A Appendix F testing protocols:New validation requirements for PR2 performance qualification are filtering out non-specialized compounders, consolidating share among certified suppliers.
Industry Challenges
- Compounding chemist scarcity:Formulation expertise bridging polymer science and oilfield tribology has contracted as senior technologists retire without pipeline replacement.
- API certification timeline compression:PR2 qualification cycles now stretch 14-18 months, delaying new product commercialization and locking out agile entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Saver Rubber Market |
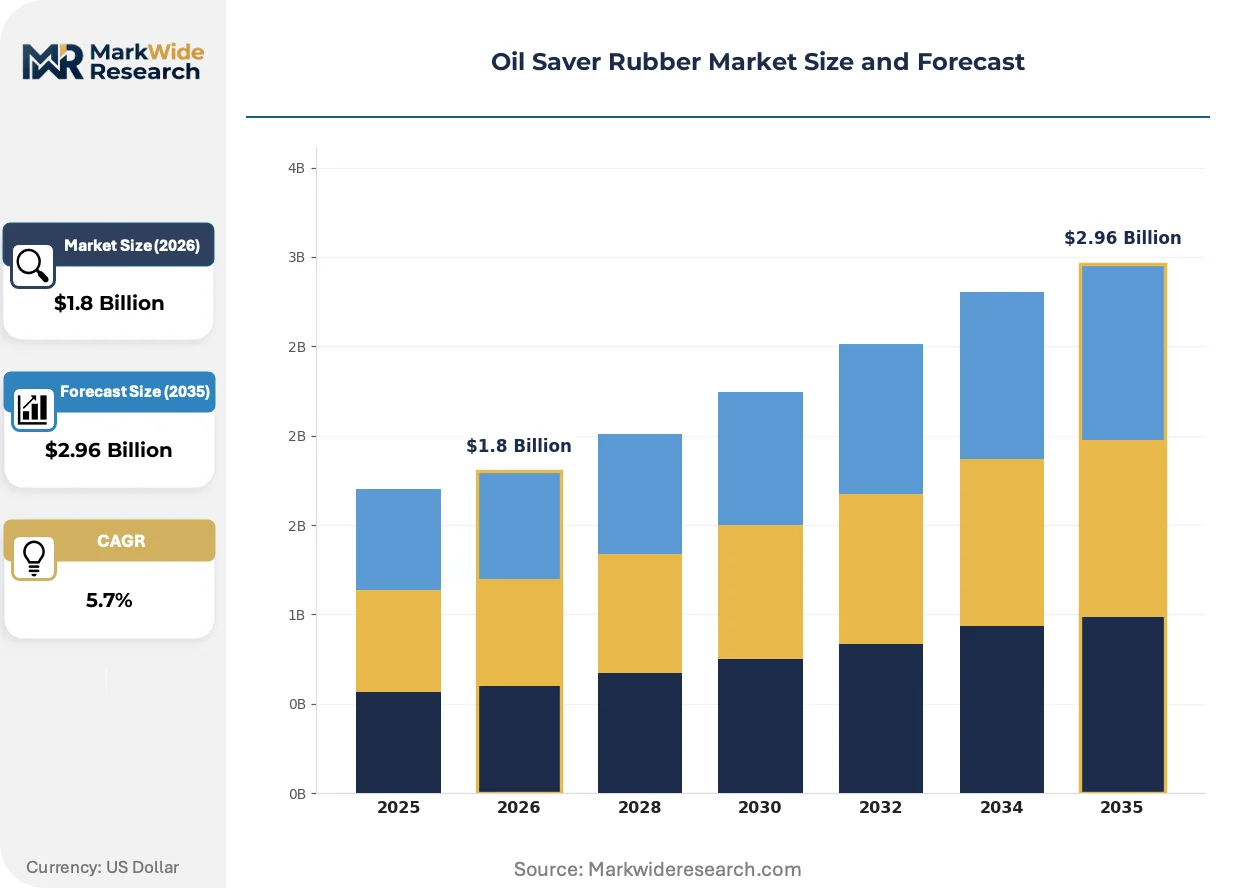
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Rubber, Synthetic Rubber, Reclaimed Rubber, Thermoplastic Elastomers Application: Automotive Seals, Oil Filters, Gaskets, Industrial Hoses Grade: High Performance, Standard Grade, Low Permeability, Economical End User: Automotive Industry, Machinery Manufacturers, Oil & Gas Sector, Chemical Processing |
| Companies Covered | Oil States Industries, Titan BOP Rubber Products, Datwyler Sealing Solutions, Houston Specialty Products Co., Revata Engineering, Global Elastomeric Products, Titan Oil Tools, PE Energy, Double E, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Saver Rubber Market Evolving Landscape
Material science convergence with predictive maintenance systems is redefining how seal performance gets specified, validated, and monetized across the oilfield service value chain.
Peroxide-cure hydrogenated nitrile with saturated backbone architecture is rendering obsolete sulfur-cure nitrile in dynamic BOP applications. Major independent operators in the Gulf of Mexico have adopted HNBR ram packings as standard since 2022. The technology is rendering obsolete legacy compound inventories held by regional distributors.
EPA methane performance standards under the Inflation Reduction Act impose leak-rate thresholds on production equipment. Facility operators must demonstrate sub-0.05 percent volumetric leakage through certified low-permeability seals. Onshore shale producers in Texas and New Mexico are retrofitting wellhead assemblies with FKM primary seals to secure compliance credits.
Integrated service contracts now bundle seal supply with predictive replacement scheduling based on real-time pressure-cycle telemetry. Operators purchase guaranteed uptime rather than discrete components. This model concentrates procurement authority with integrated oilfield service companies and marginalizes independent seal distributors in North American land markets.
Oil Saver Rubber Market Segmentation
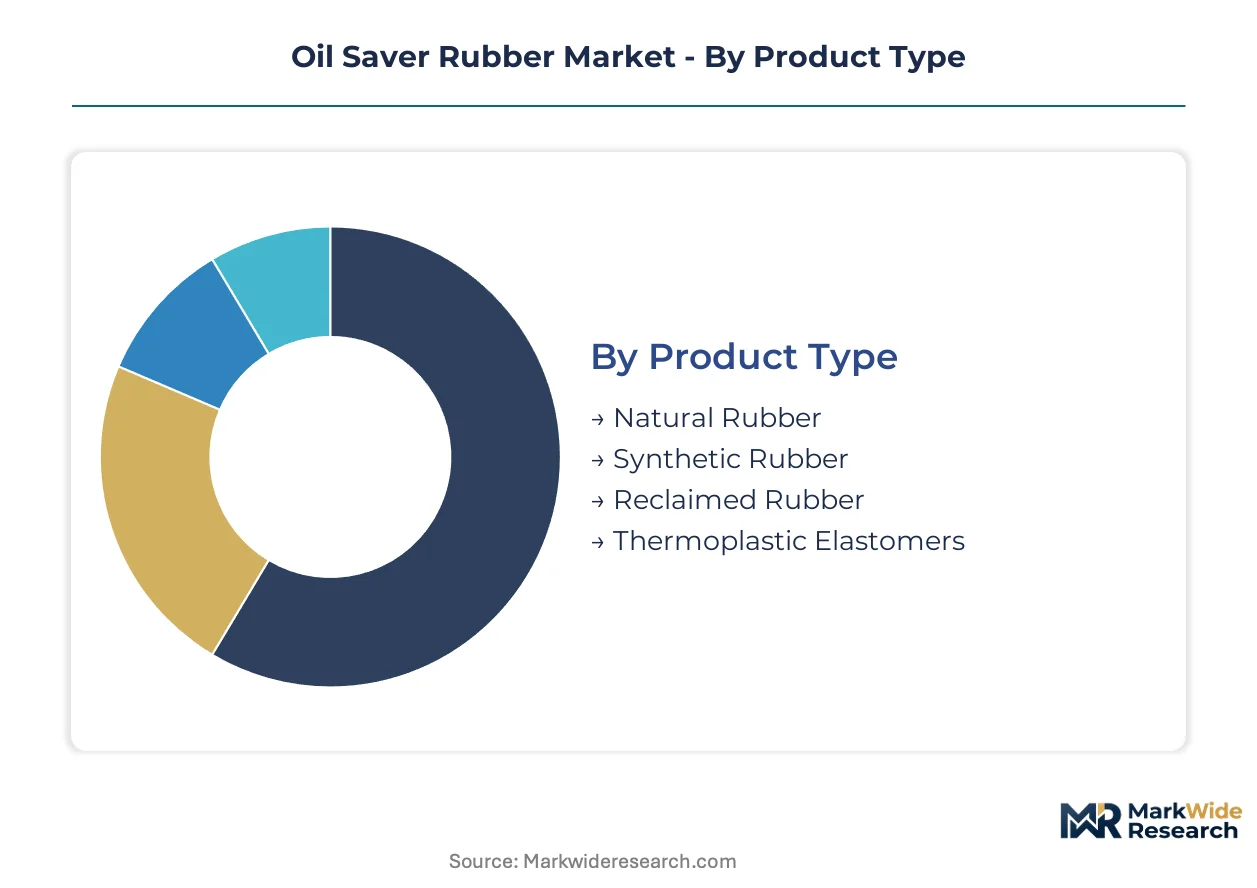
Segmentation in oil saver rubber markets reveals divergent service intensity profiles across end-use environments. Replacement cycle frequency, certification burden, and specification rigor vary dramatically between dynamic BOP packings and static automotive gaskets. Procurement patterns cluster around performance tiers rather than price alone.
Product Type:
After-sales-service intensity escalates with compound complexity, as hydrogenated nitrile and fluoroelastomer formulations demand specialized installation protocols and predictive replacement scheduling.
- Synthetic Rubber:Hydrogenated nitrile and fluoroelastomer formulations dominate high-pressure wellhead applications. Permian Basin operators specify HNBR ram packings for sour service environments where sulfur-cure nitrile fails within months. FKM terpolymers tolerate 600°F bottom-hole temperatures in deep gas wells.
- Natural Rubber:Limited to low-pressure auxiliary seals and temporary containment barriers. Gulf of Mexico distributors maintain minimal inventory as operators migrate toward synthetic alternatives.
- Reclaimed Rubber:Restricted to non-critical gasketing and economy-grade industrial hose reinforcement. Compounders blend reclaimed content into static seal applications with minimal hydrocarbon exposure.
- Thermoplastic Elastomers:Emerging in carbon capture injection seals where supercritical CO2 resistance proves critical. Pilot deployments in Texas CCS clusters validate explosive decompression performance.
Synthetic rubber holds the largest share; momentum sits with thermoplastic elastomers.
Application:
Volume concentration diverges sharply from value concentration, with automotive seals generating unit scale but wellhead packings capturing margin premiums.
- Oil Filters:High-volume replacement category with standardized nitrile gasket specifications. Refinery maintenance schedules drive predictable demand cycles along the US Gulf Coast.
- Automotive Seals:Short replacement intervals and commodity pricing characterize this segment. Tier-1 suppliers specify hydrogenated nitrile for transmission seals in heavy-duty commercial vehicles.
- Gaskets:Static sealing applications span flange connections and valve bonnets. API 6A Appendix F testing protocols filter out non-specialized compounders in wellhead gasket supply.
- Industrial Hoses:Flexible containment for transfer operations in downstream refining. REACH phthalate restrictions accelerate substitution toward peroxide-cured formulations in European petrochemical corridors.
Oil filters dominate unit volume; wellhead packings command the steepest expansion trajectory in value terms.
Grade:
Certification tier directly determines supplier qualification and pricing power, with API validation creating defensible moats around premium compounders.
- High Performance:FKM and advanced HNBR grades specified for HPHT reservoirs. Brazil pre-salt developments require 25-year service life guarantees in deepwater BOP stacks.
- Low Permeability:EPA methane performance standards mandate sub-0.05 percent volumetric leakage rates. Texas shale producers retrofit wellheads with FKM primary seals to secure compliance credits.
- Standard Grade:Sulfur-cure nitrile for moderate pressure and temperature applications. Inventory obsolescence accelerates as operators standardize on peroxide-cure alternatives.
- Economical:Reclaimed and filler-heavy compounds for non-critical containment. Price-sensitive procurement in secondary machinery manufacturing tolerates shorter service intervals.
High performance grade anchors revenue concentration; low permeability specifications are climbing the fastest amid regulatory tightening.
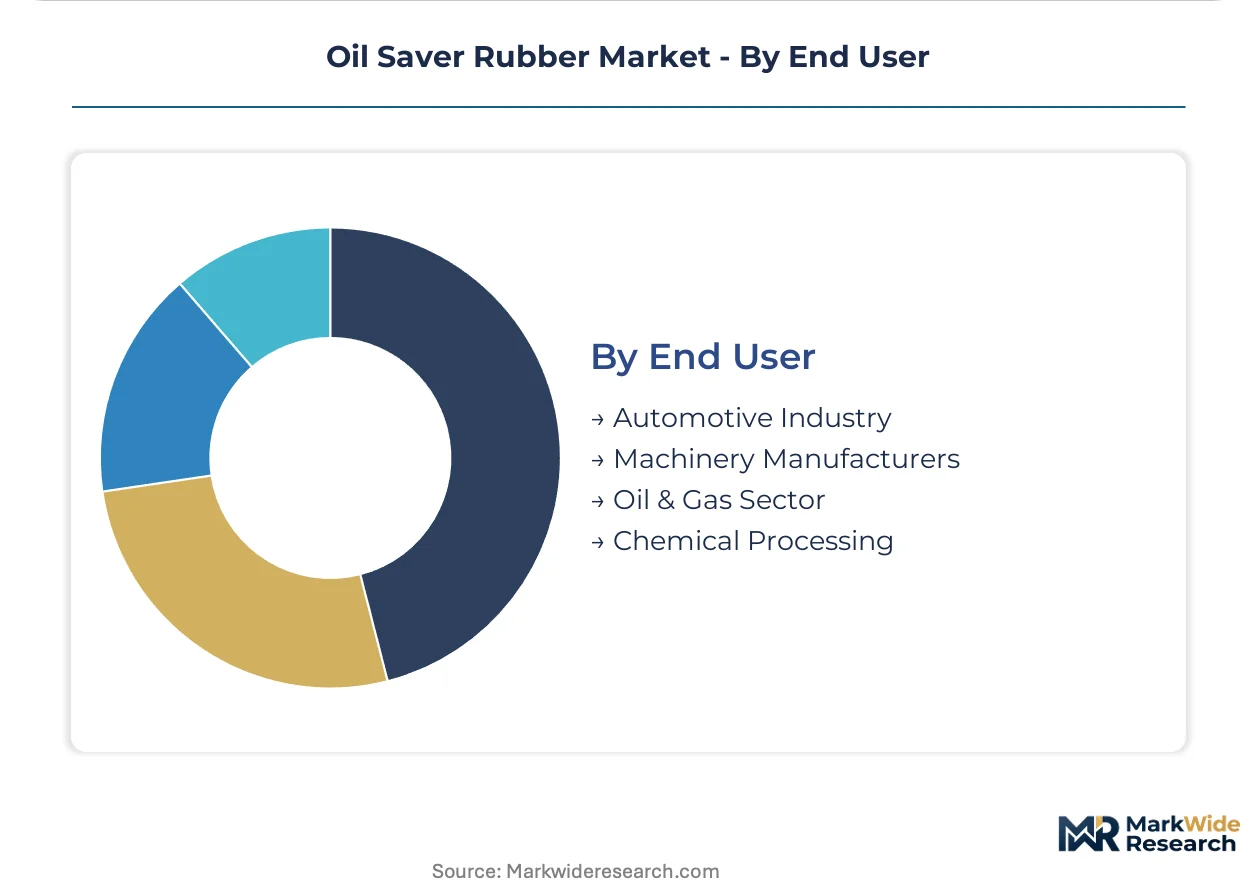
End User:
Customer concentration patterns split between integrated oilfield service companies bundling seal supply with predictive maintenance, and fragmented machinery OEMs purchasing on specification sheets.
- Oil & Gas Sector:Blowout preventer packings and wellhead seals concentrate the highest value per unit. Integrated service contracts now bundle component supply with real-time pressure-cycle telemetry.
- Automotive Industry:Transmission and powertrain seals represent stable volume with compressed margins. Tier-1 suppliers enforce stringent IATF certification requirements on compounders.
- Machinery Manufacturers:Hydraulic cylinder seals and pump packings for general industrial equipment. Procurement authority fragments across regional equipment builders.
- Chemical Processing:Reactor vessel gaskets and valve seals resistant to aggressive process media. ECHA registration deadlines phase out legacy phthalate-plasticized compounds.
Oil and gas sector holds the largest share; carbon capture infrastructure is gaining share fastest as an adjacent specification channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer compounding capacity clusters along the US Gulf Coast and in Western Europe, with emerging fabrication sites in Southeast Asia serving regional oilfield demand. Raw material supply chains for acrylonitrile and fluoroelastomer feedstocks concentrate in East Asian chemical corridors. Procurement patterns split between integrated service contracts in North American shale plays and specification-driven spot purchasing in European refining.
United States
Permian Basin operators drive replacement volume for blowout preventer packings as fracturing intensity compresses service intervals. EPA methane performance standards under the Inflation Reduction Act mandate sub-0.05 percent leak rates, forcing wellhead seal retrofits across Texas and New Mexico. Houston anchors domestic compounding capacity, with specialty fabricators clustered along the Ship Channel refining corridor supplying Gulf of Mexico deepwater rig fleets.
Germany
REACH registration deadlines and RoHS substance restrictions are phasing out phthalate-plasticized nitrile compounds across the Ruhr industrial belt. ECHA enforcement has accelerated adoption of peroxide-cured hydrogenated nitrile systems in chemical processing infrastructure. The Cologne-Düsseldorf corridor hosts precision molders serving high-pressure valve manufacturers with certified API 6A Appendix F packings.
Brazil
Petrobras pre-salt development off the Santos Basin is specifying API 16A compliant seals with 25-year service life guarantees for deepwater BOP stacks. ANVISA and environmental licensing requirements impose material traceability standards on subsea equipment suppliers. The Rio de Janeiro industrial zone concentrates domestic fabrication capacity for offshore service companies operating in the Campos and Santos basins.
China
State-owned oil majors are expanding HPHT drilling in Sichuan shale gas and Tarim Basin sour gas fields, stimulating demand for fluoroelastomer formulations. MEE emissions regulations and dual carbon goals are tightening material specifications for production infrastructure. The Yangtze River Delta chemical corridor supplies acrylonitrile feedstock to regional compounders serving domestic oilfield service demand.
United Arab Emirates
ADNOC downstream expansion and sour gas development at Shah and Bab fields are driving specification-grade seal procurement. MOHAP and federal environmental standards are aligning with European REACH frameworks for chemical substance restrictions. The Jebel Ali industrial zone hosts distributors and service centers supplying packings to rig fleets operating across the Arabian Gulf.
Oil Saver Rubber Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on compound formulation and precision molding. The vendor base splits between integrated oilfield service companies bundling seal supply with predictive maintenance contracts, and independent compounders competing on API certification tiers. Three archetypes dominate: vertically integrated polymer-to-seal manufacturers, specialized BOP packing fabricators, and diversified industrial seal houses with oilfield divisions. Consolidation pressure is mounting through strategic partnerships between compounders and telemetry providers, while capacity expansion concentrates in Southeast Asian nitrile rubber compounding.
Among North American integrated manufacturers, Oil States Industries exemplifies the polymer-to-finished-seal archetype with captive compounding capacity. Houston Specialty Products Co. and Titan BOP Rubber Products occupy positions within the specialized BOP packing tier, with geographic naming anchoring their Gulf Coast supply relationships. Datwyler Sealing Solutions represents the European precision-molding archetype, with Swiss-origin signaling fluoroelastomer formulation expertise for high-pressure wellhead applications.
| Leading Market Players |
|---|
| Oil States Industries |
| Titan BOP Rubber Products |
| Datwyler Sealing Solutions |
| Houston Specialty Products Co. |
| Revata Engineering |
| Global Elastomeric Products |
| Titan Oil Tools |
| PE Energy |
| Double E |
| Others |
Value Network & Pricing Analysis
Houston Ship Channel freight corridors transmit butadiene-acrylonitrile cost volatility directly into compounder margins, compressing pricing power for non-integrated seal fabricators while rewarding polymer-to-finished-seal manufacturers with captive feedstock control.
Pricing Analysis
API 6A Appendix F certification dictates the pricing tier structure across oil saver rubber procurement, separating PR2-qualified compounders from uncertified competitors. Three-tier pricing structure across premium, standard, and economy levels stratifies by hydrogenated nitrile versus sulfur-cure nitrile versus reclaimed compound grades. Cost compression in standard-grade nitrile intensifies because Permian Basin operators are consolidating procurement through integrated service contracts. Machinery manufacturers exhibit highest price sensitivity, while deepwater BOP stack specifiers prioritize 25-year service life guarantees over unit cost.
Supply Chain Analysis
Tariff exposure between Japan and the United States dominates supply chain risk planning for fluoroelastomer-dependent seal manufacturers. Daikin and AGC in Japan, alongside Lanxess in Germany and Zeon in Japan, anchor global FKM polymer supply. Raw material dependencies center on acrylonitrile monomer, peroxide cure activators, and bio-based process oils substituting for REACH-restricted phthalates. Single-source vulnerability concentrates in terpolymer grades for 600°F sour gas applications. Distribution runs through oilfield service company warehousing networks rather than independent distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oil saver rubber markets sit in early-cycle expansion as HPHT reservoir development and carbon capture infrastructure create specification-grade demand channels previously absent from compounder portfolios.
For Market Incumbents: Entrench API certification moats through accelerated PR2 qualification timelines for next-generation thermoplastic elastomer formulations. Expand captive hydrogenated nitrile compounding capacity along the US Gulf Coast to offset butadiene-acrylonitrile contract volatility. Threat substitution from predictive maintenance telemetry bundling demands channel control through integrated service contracts rather than component spot sales. For New Entrants and Emerging Players: Establish a beachhead in carbon capture injection seal applications where supercritical CO2 resistance requirements filter out legacy nitrile compounders. Target thermoplastic elastomer pilot deployments in Texas CCS clusters as the most penetrable specification channel. Go-to-market leverage rests on explosive decompression testing partnerships with research universities rather than API certification timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with backward integration into hydrogenated nitrile polymer production and validated FKM formulation libraries. Long-term viability hinges on 5-10 year service contract visibility with integrated oilfield service companies. Acquisition archetype: mid-cap specialists with API 6A Appendix F certification and telemetry integration partnerships. Signal to watch: Petrobras pre-salt procurement volume acceleration as inflection indicator for premium-tier demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HNBR Polymer Production | Captive acrylonitrile supply insulates margins from butadiene contract volatility. |
| API 6A Appendix F Certification Acceleration | PR2 qualification filters non-specialized compounders from wellhead packing supply. |
| Telemetry Partnership with Oilfield Service Companies | Predictive maintenance bundling marginalizes independent seal distributors. |
| Carbon Capture Seal Development Program | Supercritical CO2 resistance opens adjacent specification channel beyond hydrocarbons. |
| Southeast Asian Compounding Capacity Expansion | Regional nitrile rubber fabrication serves growing oilfield service demand. |
Research Methodology
A standing panel of blowout preventer maintenance engineers, wellhead procurement managers at integrated operators, compounder R&D directors, and API certification auditors provided ongoing calibration against operating reality. Primary interviews with these stakeholders combined with secondary validation from EPA methane performance filings, ECHA REACH registration databases, SEC 10-K disclosures from oilfield service companies, and customs trade data on acrylonitrile imports. Bottom-up segmentation modeling and top-down macroeconomic anchoring triangulated volume and value estimates.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated regulatory enforcement pathways throughout the forecast period. Segmentation dimensions modeled include compound grade tier, end-use application intensity, certification level, and regional production infrastructure maturity. CAGRs derived from replacement cycle compression rates in Permian Basin fracturing operations and pre-salt deepwater rig deployment schedules in Brazil. Industry-specific inputs incorporated HPHT reservoir count expansion and carbon capture injection well permitting velocity.
Sensitivities concentrate around acrylonitrile feedstock price volatility, Japanese fluoroelastomer supply disruption, and EPA methane standard enforcement intensity. Forecasts reflect assumptions on shale fracturing cycle frequency and deepwater rig utilization rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Plated Hose Market
Rubber
Polybutadiene Elastomers Market
Rubber
Polyisoprene Rubber Market
Rubber
Isoprene Rubber (IR) Latex Market
Rubber
FKM Elastomers Market
Rubber
Acrylic Based Elastomers Market
Rubber
Industrial Rubber Products Market
Rubber
Rubber Compound Market
Rubber
Silicone Rubber Market
Rubber
US Nitrile Gloves Market
Rubber
Global Thermoplastic Vulcanizate (TPV) Market
Rubber
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Rubber
Global Tire Material Market
Rubber
Rubber Foam Market
Rubber
Synthetic Rubber Market
Rubber
Rubber Carbon Black Market